
 Europe HVAC Field Device Market | 2026-2036
Europe HVAC Field Device Market Size, Share, and Industry Trends Forecast 2026-2036
Europe HVAC Field Device Market Insights
Multi-sourcing of sensor assemblies is realigning procurement patterns across European HVAC supply chains. Siemens AG leverages its automation heritage to anchor positions in building management integration. Danfoss A/S specializes in thermal controls for district energy networks across Nordic markets. Bosch Thermotechnik competes through manufacturing scale in residential heating peripherals.
HVAC field devices encompass electromechanical sensors, transmitters, and actuators that measure and regulate temperature, pressure, humidity, and fluid flow within climate control systems, typically operating across ranges such as minus 40 to plus 150 degrees Celsius for thermal sensing elements. These instruments feed data to building automation controllers to optimize energy consumption and indoor environmental quality in commercial and industrial installations. Temperature sensors occupy the largest product category due to universal deployment in every heating and cooling loop. Wireless technology segments are expanding fastest as BACnet and LoRaWAN protocols gain traction in retrofit applications where cabling costs prove prohibitive. Smart technology integrations command premium positioning where edge computing enables predictive maintenance algorithms.
The EU Green Deal and F-Gas Regulation are reshaping equipment specifications by mandating lower-global-warming-potential refrigerants and tighter leakage monitoring, which drives demand for next-generation pressure and flow instrumentation. Ecodesign directives from the European Commission set minimum efficiency thresholds that force replacement cycles in existing building stock. REACH compliance adds material traceability requirements for sensor housings and electronic components. Stakeholders must monitor how the EU AI Act's risk classification framework applies to autonomous building control algorithms that increasingly govern field device networks.
Market Dynamics
EU Green Deal renovation mandates are compressing replacement cycles for installed HVAC field devices across European building stock. The convergence of F-Gas Regulation leakage monitoring requirements and Ecodesign efficiency thresholds is forcing simultaneous upgrades of sensors, actuators, and control interfaces in commercial and residential systems.
Growth Catalysts
- District heating network modernization:Nordic and German utilities are retrofitting centralized heat distribution with smart thermal metering and remote valve actuation to optimize load balancing and reduce distribution losses.
- EU F-Gas Regulation Phase-Down:Refrigerant transition protocols mandate continuous pressure and temperature monitoring for lower-GWP alternatives, expanding sensor deployment in commercial refrigeration and heat pump circuits.
- LoRaWAN protocol adoption:Wireless field devices eliminate cabling costs in historic building retrofits across France and Italy, accelerating deployment where structural constraints prohibit wired infrastructure.
Market Restraints
- Semiconductor supply concentration:MEMS sensor fabrication depends on foundry capacity concentrated in East Asia, exposing European HVAC OEMs to lead time volatility for critical transducer elements.
- Copper and rare earth price volatility:Electromechanical actuators and sensor housings face input cost pressure from commodity fluctuations, compressing margin buffers for mid-tier device manufacturers.
- Legacy BACnet integration friction:Interoperability gaps between proprietary wireless protocols and existing building automation networks slow retrofit adoption in institutional buildings with sunk infrastructure investments.
Strategic Opportunities
- Polish and Romanian building stock penetration:EU cohesion fund allocations for energy efficiency are unlocking public sector procurement of connected HVAC controls in markets with underpenetrated smart building infrastructure.
- Edge computing convergence with field devices:On-sensor predictive maintenance algorithms reduce downtime for critical healthcare and data center climate systems, creating premium positioning for intelligent actuator-sensor hybrids.
- EU AI Act risk classification alignment:Autonomous building control systems fall under specific compliance tiers, creating advisory and certification service opportunities for control algorithm vendors serving high-risk installation categories.
Industry Challenges
- Cyber-physical systems engineering talent scarcity:Integration of IT security protocols with OT field device firmware requires specialized skill sets that European HVAC suppliers struggle to source at scale.
- Multi-protocol certification timelines:Simultaneous CE marking, BACnet compliance, and wireless radio equipment directive testing extends product launch cycles, delaying revenue recognition for new device introductions.
- Interoperability testing fragmentation:Inconsistent implementation of open standards across BMS platforms forces redundant engineering effort for device vendors seeking broad compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe HVAC Field Device Market |
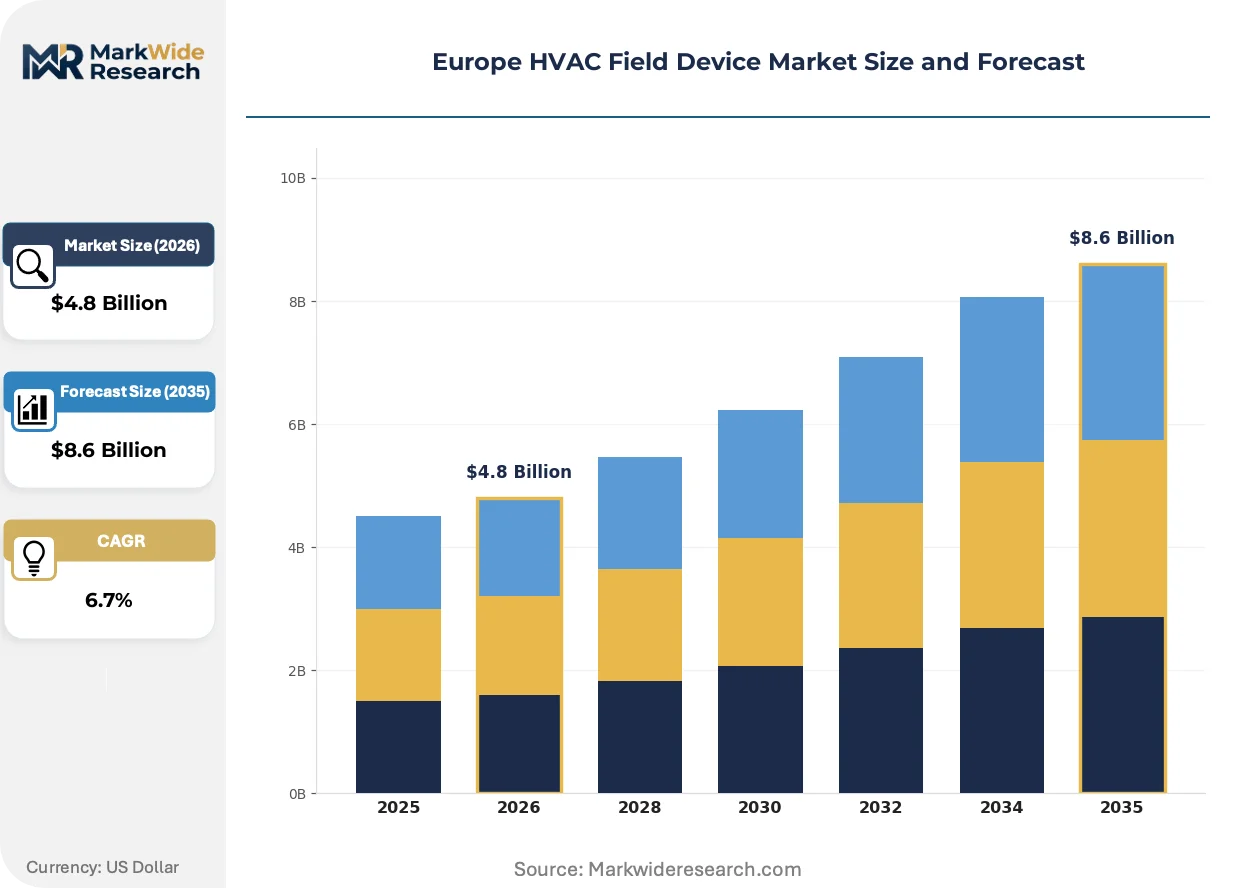
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Transmitters, Humidity Sensors, Flow Meters Application: Commercial Buildings, Residential Units, Industrial Facilities, Agriculture Technology: Wired, Wireless, Hybrid, Smart Technology End User: Facility Management, HVAC Contractors, System Integrators, Engineers |
| Companies Covered | Honeywell International, Johnson Controls International, Schneider Electric, Siemens AG, Carrier Global Corporation, Daikin Industries, Danfoss A/S, Bosch Thermotechnik, Mitsubishi Electric Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe HVAC Field Device Market Trends and Innovations
Wireless connectivity architectures and on-device intelligence are redefining how HVAC field devices communicate, process data, and deliver value beyond basic measurement functions. The transition from passive sensors to autonomous edge nodes is compressing the traditional separation between field instrumentation and control logic.
MEMS-based thermal mass flow sensors are electrifying refrigerant monitoring in commercial heat pump systems. German and French HVAC OEMs are integrating these solid-state alternatives to mechanical flow meters in next-generation equipment platforms. The technology is electrifying service model economics by enabling continuous leakage detection that triggers predictive maintenance dispatch before regulatory thresholds are breached.
The EU AI Act's risk-based classification framework is imposing algorithmic transparency requirements on autonomous building control systems. HVAC field devices with embedded decision logic now face documentation and conformity assessment obligations previously reserved for safety-critical industrial equipment. High-risk installations including healthcare and transport infrastructure are experiencing extended procurement cycles as vendors adapt quality management systems to the new compliance architecture.
Building operators in the Netherlands and Denmark are consolidating vendor relationships around full-stack climate system providers rather than procuring discrete sensors and actuators separately. This concentration is displacing component specialists who lack integration capabilities or long-term service infrastructure. The shift is most visible in commercial office retrofits where facilities managers prioritize single-accountability contracts over fragmented equipment sourcing.
Europe HVAC Field Device Market Segmentation
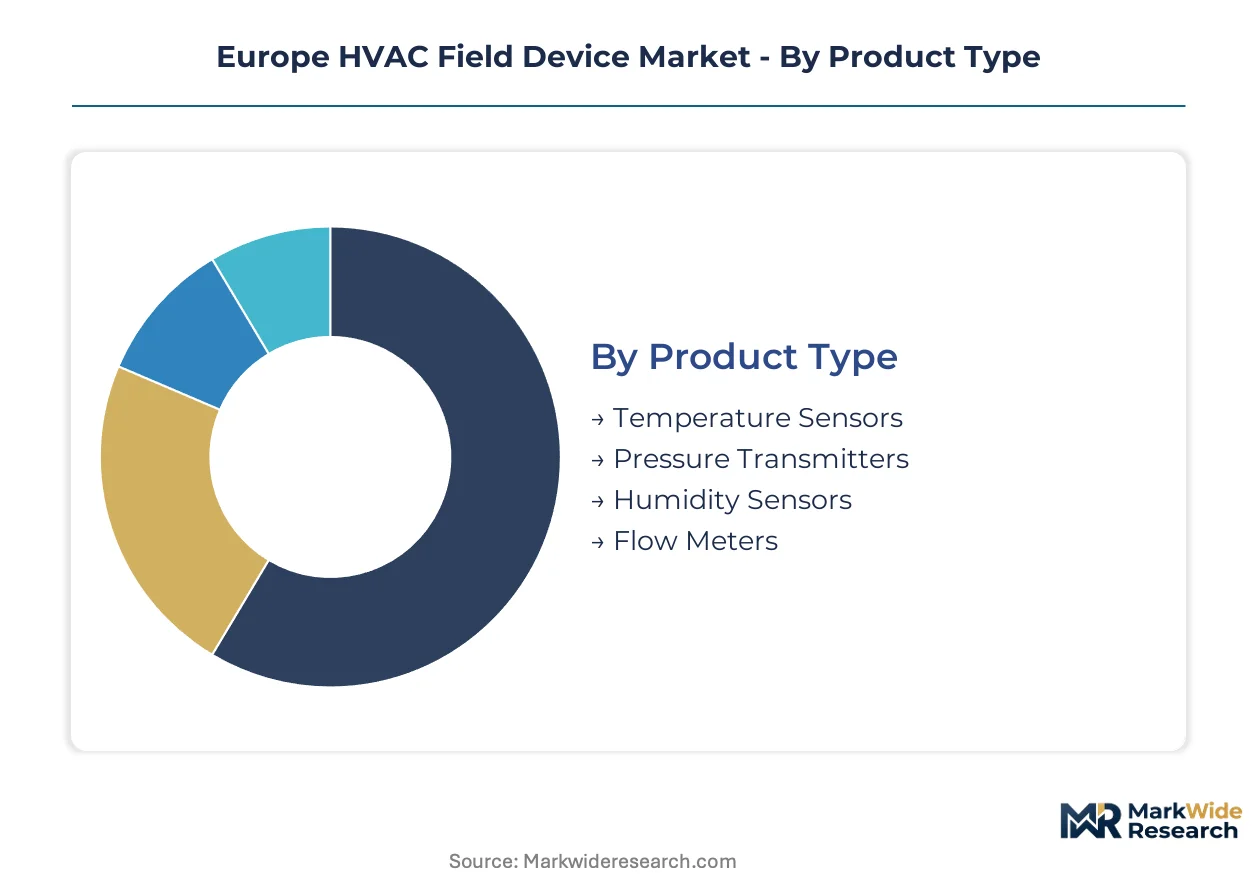
Field device segmentation in European HVAC markets reflects divergent procurement economics across retrofit versus new construction cycles. Component specification varies sharply between district heating utilities and commercial facility managers, with wireless architectures gaining traction where installation labor costs dominate project economics.
Product Type:
Supply concentration in MEMS fabrication and electromechanical assembly favors manufacturers with captive semiconductor sourcing or long-term foundry partnerships.
- Temperature Sensors:Thermistor, RTD, and thermocouple elements span minus 40 to plus 150 degrees Celsius operating ranges. German district heating operators deploy these universally across distribution loops, driven by EU Green Deal metering mandates for heat cost allocation in multi-tenant buildings.
- Pressure Transmitters:Piezoresistive and capacitive transducers monitor refrigerant circuits and hydronic distribution networks. F-Gas Regulation leakage detection requirements in France and Italy are accelerating replacement of mechanical gauges with continuous electronic monitoring.
- Humidity Sensors:Capacitive polymer and resistive thin-film elements regulate indoor air quality in healthcare and data center applications.
- Flow Meters:Thermal mass, ultrasonic, and electromagnetic technologies measure hydronic and refrigerant mass flow.
Temperature sensors absorb the bulk of installed capacity; smart pressure transmitters are expanding most quickly.
Application:
End-use economics separate projects where devices are specified by engineering consultants from those where contractors drive component selection based on availability.
- Commercial Buildings:Office, retail, and hospitality installations require BACnet-compatible field devices with standardized object models. Dutch and Danish facilities managers are consolidating procurement around full-stack climate providers, reducing discrete component sourcing.
- Residential Units:Single-family and multi-family heating systems prioritize cost-optimized sensors with minimal calibration requirements. Polish and Romanian public housing retrofits funded by EU cohesion allocations are unlocking volume demand for connected thermostats and zone valves.
- Industrial Facilities:Manufacturing plants and process industries specify ruggedized transmitters with extended temperature and vibration tolerance.
- Agriculture:Greenhouse climate control and livestock ventilation deploy corrosion-resistant humidity and temperature instrumentation.
Commercial buildings command the highest device density per square meter; residential retrofits in Eastern Europe are gaining share fastest.
Technology:
Protocol adoption curves determine which connectivity architectures can access project funding tied to smart building certification schemes.
- Wired:BACnet MS/TP and Modbus RTU dominate new construction where cabling costs are amortized across building lifecycles.
- Wireless:LoRaWAN and Zigbee eliminate infrastructure constraints in historic building retrofits across France and Italy, with French regulators accelerating radio equipment directive approvals for sub-gigahertz building automation.
- Hybrid:Architectures combine wired backbone networks with wireless edge devices to bridge legacy and modern infrastructure.
- Smart Technology:Edge computing-enabled sensors with embedded predictive maintenance algorithms command premium positioning in healthcare and data center applications where downtime costs justify higher unit economics.
Wired installations retain the largest installed base; wireless protocols are climbing the fastest as retrofit activity intensifies.
End User:
Procurement authority fragmentation creates divergent sales cycles between owner-operated assets and third-party managed facilities.
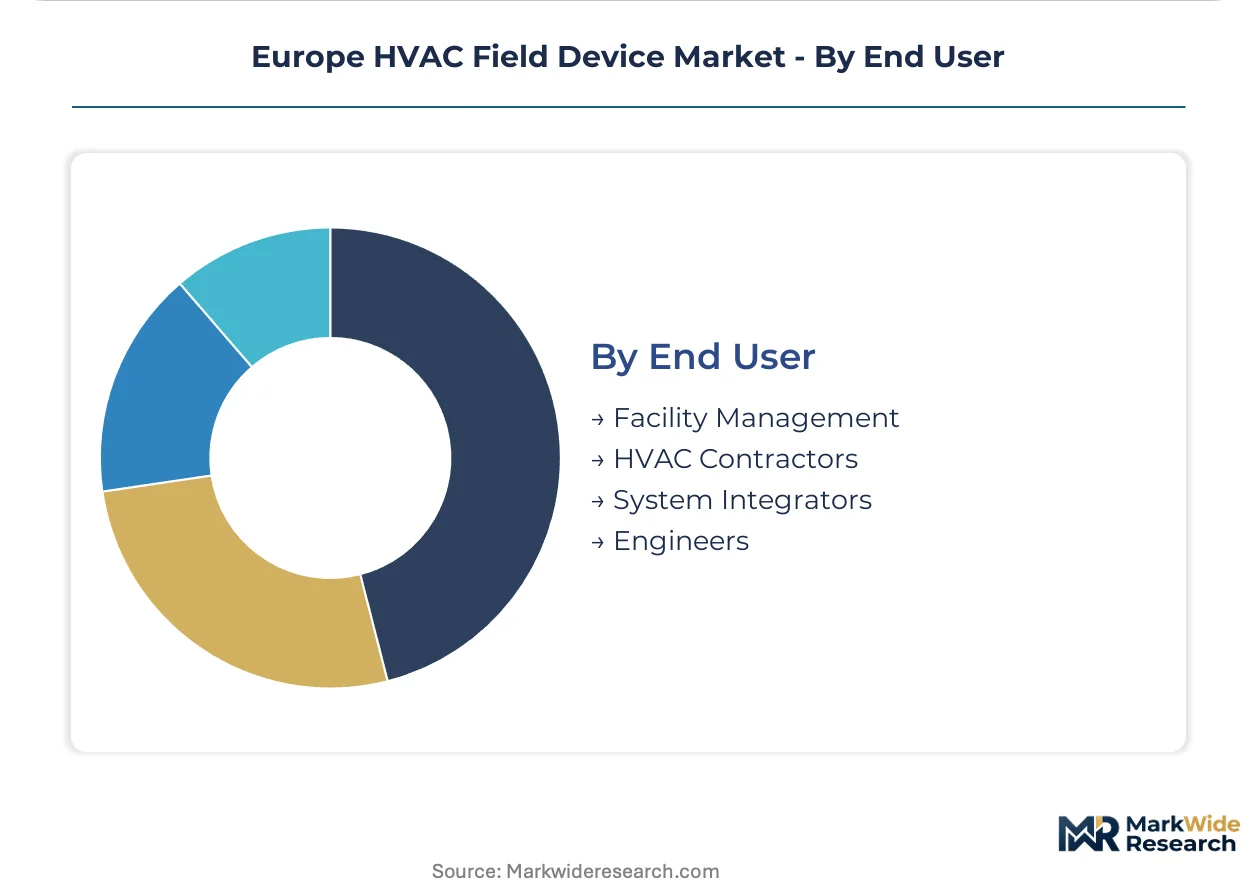
- Facility Management:Corporate and institutional real estate teams prioritize lifecycle cost optimization and remote monitoring capabilities.
- HVAC Contractors:Installation firms drive component selection in residential and light commercial markets based on distributor availability and warranty terms.
- System Integrators:Building automation specialists specify interoperable devices that reduce commissioning labor and protocol translation complexity.
- Engineers:Consulting firms performing design-build and design-bid-build projects mandate certified devices that satisfy Ecodesign and CE marking requirements for public sector procurement.
Facility management directs the largest procurement volume; system integrators are expanding their specification influence fastest as building complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germanium and rare earth deposits in the Nordic region anchor sensor element supply chains serving European HVAC manufacturers. Raw material proximity to MEMS foundries in Germany and France reduces lead times for thermal transducer components. District heating infrastructure density across Northern Europe concentrates demand for smart metering devices.
Germany
District heating network operators in Berlin and Hamburg are deploying smart thermal meters for multi-tenant heat cost allocation. The EU Green Deal building renovation targets mandate connected controls in existing commercial stock. Bavaria's industrial corridor hosts Siemens AG automation facilities supplying BACnet-integrated field devices to Central European retrofit projects.
France
Historic building retrofits in Paris and Lyon are accelerating LoRaWAN protocol adoption where cabling installation faces structural constraints. ANSM radio equipment directive approvals for sub-gigahertz building automation are streamlining wireless device certification. The F-Gas Regulation Phase-Down is forcing continuous refrigerant monitoring upgrades in commercial refrigeration circuits.
Netherlands
Facilities managers in Amsterdam and Rotterdam are consolidating procurement around full-stack climate providers rather than discrete component sourcing. Ecodesign directive compliance deadlines are compressing replacement cycles for installed building automation infrastructure. Dutch greenhouse operators deploy corrosion-resistant humidity instrumentation for precision agriculture climate control.
Poland
EU cohesion fund allocations for energy efficiency are unlocking public sector procurement of connected HVAC controls in Warsaw and Kraków residential districts. REACH compliance requirements are adding material traceability obligations for sensor housing suppliers. Polish HVAC contractors are specifying cost-optimized wireless thermostats for multi-family housing retrofits.
Italy
F-Gas Regulation leakage detection mandates are accelerating replacement of mechanical pressure gauges with electronic transmitters in Milan and Rome commercial installations. Historic center building constraints in Florence and Venice favor wireless field devices eliminating invasive cabling. Italian system integrators prioritize BACnet-compatible devices reducing commissioning labor complexity.
Europe HVAC Field Device Market Competitive Landscape
Strategic partnerships dominate the current landscape as device vendors seek protocol certification alignment and BMS platform interoperability. The vendor base clusters around three tiers: full-stack building automation conglomerates, thermal control specialists, and component-scale manufacturers. Two archetypes anchor competitive positioning: automation heritage players leveraging software integration capabilities, and thermal engineering specialists with district energy network expertise. M&A activity and technology licensing agreements represent the primary competitive vectors as firms address multi-protocol certification complexity.
Among diversified European industrial conglomerates, Siemens AG and Schneider Electric exemplify the automation-heritage archetype with building management integration capabilities. Danfoss A/S occupies a specialist position in thermal controls for district energy applications. These three entities represent distinct strategic postures: full-stack system provision, thermal-centric component specialization, and electromechanical scale manufacturing respectively.
| Leading Market Players |
|---|
| Honeywell International |
| Johnson Controls International |
| Schneider Electric |
| Siemens AG |
| Carrier Global Corporation |
| Daikin Industries |
| Danfoss A/S |
| Bosch Thermotechnik |
| Mitsubishi Electric Corporation |
| Others |
Pricing and Supply Chain Analysis
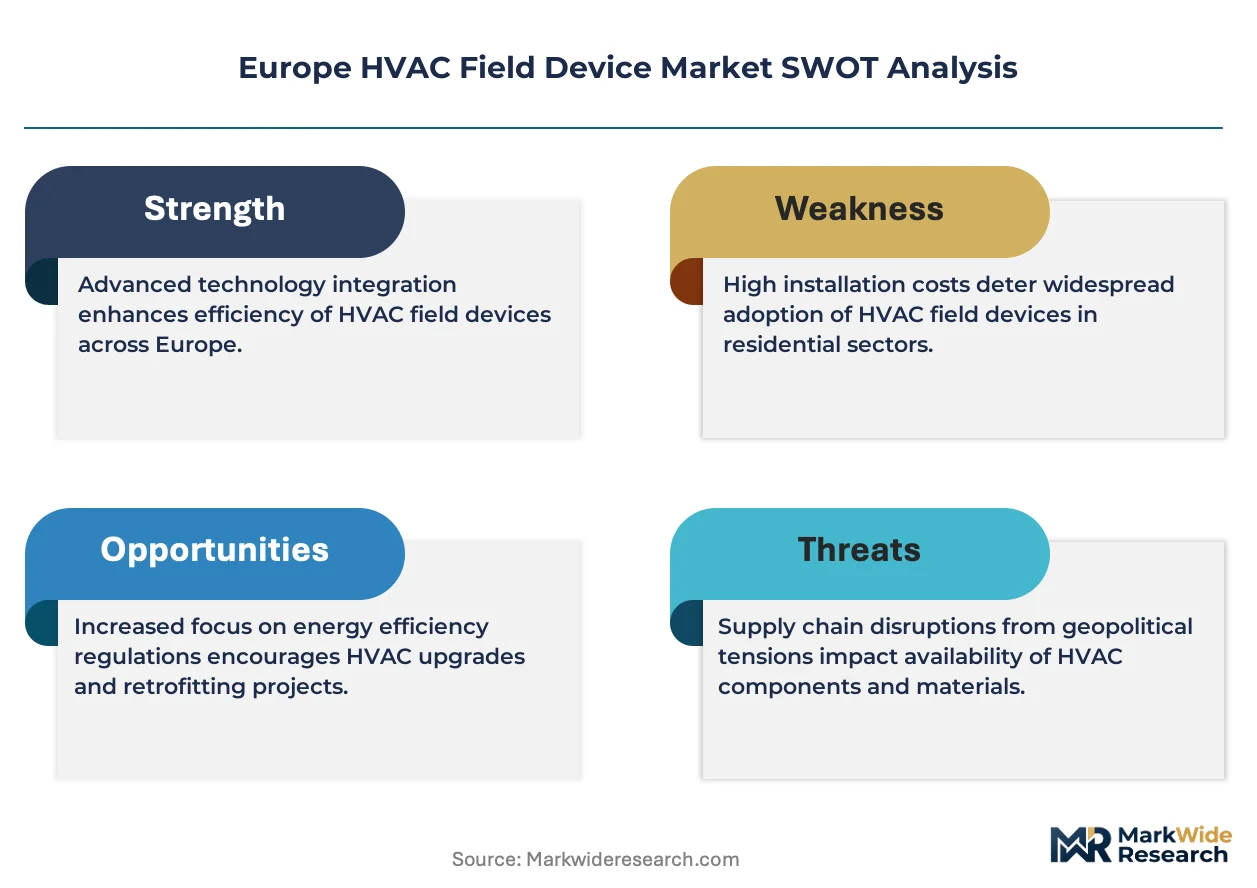
The EU Green Deal building renovation targets gate qualified supply for HVAC field devices, restricting premium-tier pricing access to vendors with CE marking, BACnet certification, and REACH-compliant material traceability. German and French facilities managers pay 15-25% premiums for connected devices bundled with predictive maintenance algorithms, while Polish and Romanian contractors select unbundled hardware to minimize upfront capital outlay.
Pricing Analysis
Warranty and service bundling separates premium positioning from commodity competition in European HVAC field devices. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—CE-marked smart sensors with edge computing command top tier, basic BACnet-compatible devices occupy mid-tier, and unbranded electromechanical components serve price-sensitive Eastern European retrofits. Cost compression in the economy tier is intensifying because Polish and Romanian public housing contractors prioritize lowest first-cost procurement over lifecycle optimization. Residential retrofit contractors exhibit highest price sensitivity; Dutch data center operators demonstrate lowest sensitivity due to downtime cost justification.
Supply Chain Analysis
Freight cost volatility from East Asia to European distribution hubs is reshaping inventory strategies for MEMS sensor-dependent manufacturers. MEMS fabrication concentrates in Taiwan, South Korea, and China, while electromechanical assembly clusters in Germany, Poland, and Czechia. European HVAC OEMs draw from rare earth deposits in Nordic regions for thermal transducer elements, with copper and semiconductor feedstocks anchoring cost structures. Single-source vulnerability in 300mm MEMS foundry capacity exposes lead time volatility for critical pressure and flow sensor elements. Distribution runs through authorized distributor networks serving HVAC contractors, with direct OEM relationships dominating large-scale district heating utility procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS foundry capacity constraints prop pricing power for vendors with captive semiconductor supply or long-term foundry partnerships. Supply bottlenecks in thermal transducer fabrication reward early capacity commitments.
For Market Incumbents: Cement protocol certification leadership by accelerating BACnet/LoRaWAN multi-standard compliance investments ahead of EU AI Act enforcement timelines. Defend against Polish and Romanian emerging players by establishing regional service depots that reduce response times for critical healthcare and data center installations. Prioritize backward integration into MEMS sensor design to secure transducer supply against East Asian foundry volatility. For New Entrants and Emerging Players: Polish municipal housing authorities represent an underserved buyer archetype with EU cohesion fund allocations unlocking volume procurement of cost-optimized wireless thermostats. Romanian district heating utilities offer secondary entry point for smart thermal metering devices where incumbent presence remains thin. Pursue white-label manufacturing partnerships with established German automation conglomerates to bypass multi-protocol certification barriers. For Investors and Strategic Acquirers: Accelerated ANSM radio equipment directive approvals for sub-gigahertz building automation is the leading indicator that French wireless retrofit demand is entering sustained expansion phase. Long-term viability centers on vendors with software-defined service architectures converting hardware sales to recurring revenue streams. Target acquisition candidates with district heating network expertise and established Nordic utility relationships. Monitor F-Gas Regulation Phase-Down enforcement intensity as inflection signal for refrigerant monitoring sensor demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Protocol Certification Investment | Simultaneous CE marking and BACnet compliance reduces product launch delays for German OEMs. |
| Edge Computing Integration | On-sensor predictive maintenance algorithms capture premium positioning in Dutch data center climate systems. |
| Foundry Partnership Securement | Long-term MEMS capacity agreements insulate against Taiwan semiconductor supply volatility. |
| District Heating Service Infrastructure | Regional maintenance depots defend incumbent positions in Nordic utility retrofit cycles. |
| EU AI Act Compliance Architecture | Algorithmic documentation capabilities unlock high-risk healthcare and transport infrastructure procurement. |
Research Methodology
Document review covered EU regulatory filings including ECHA REACH registrations, European Commission Ecodesign implementing measures, and ANSM radio equipment directive approvals, complemented by interviews with building automation engineering directors, HVAC contractor procurement leads, district heating utility planning officers, and facilities management executives across Germany, France, Netherlands, Poland, and Italy. Secondary validation drew from customs trade data for HVAC component imports, SEC filings of listed building automation conglomerates, and national energy agency building stock statistics. Bottom-up device shipment estimates triangulated against top-down construction and retrofit expenditure projections.
Historical installation rates for connected versus conventional field devices were cross-referenced against panel input from system integrators regarding protocol adoption curves. Segmentation modeling incorporated product type, application, technology architecture, and end-user procurement authority across the analysis window. CAGR derivation weighted replacement cycle compression from EU Green Deal mandates against wireless technology penetration elasticity in historic building retrofits. Forecast inputs included MEMS foundry capacity expansion announcements and EU cohesion fund allocation schedules for Eastern European energy efficiency programs.
Revisions become necessary when MEMS semiconductor supply disruptions exceed six-month duration, F-Gas Regulation enforcement intensity diverges from baseline assumptions, or EU AI Act implementation timelines shift risk classification boundaries for autonomous building controls. Forecasts reflect documented assumptions regarding retrofit activity rates and wireless protocol standardization progress. Stakeholders should weight assumptions against their own operating context and regional regulatory engagement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Global Air Duct Market
HVAC Equipment
Compressor Market
HVAC Equipment
North America Air Conditioning Equipment Market
HVAC Equipment
Helical Screw Blowers Market
HVAC Equipment
North America, Europe, and Asia Pacific Air Compressor Market
HVAC Equipment
Refrigerant Compressors Market
HVAC Equipment
Ceiling Cassettes Market
HVAC Equipment
Water Chiller Market
HVAC Equipment
Underfloor Air Distribution Systems Market
HVAC Equipment
HVAC Airflow and Blend Door Actuator Systems Market
HVAC Equipment
Asia Pacific Commercial HVAC Market
HVAC Equipment
GCC Water Heater Market
HVAC Equipment
Warm Air Furnaces Market
HVAC Equipment
Utility and Industrial Boilers Market
HVAC Equipment
North America HVAC Equipment Market
HVAC Equipment
Global Split Systems Market