
 Screw Compressor Market | 2026-2036
Screw Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Screw Compressor Market Intelligence
Direct distribution through OEM service networks is rewriting how end users procure compressed air systems in heavy manufacturing. Atlas Copco leverages its captive aftermarket channel to sustain recurring revenue from parts and monitoring contracts. Kaeser Kompressoren anchors its position through a dense authorized dealer footprint across Central European industrial belts. ELGi Equipments Limited competes aggressively on export pricing from its Indian manufacturing base while building regional service hubs.
A screw compressor is a positive-displacement rotary machine that traps air between two helical rotors and reduces its volume to achieve pressures typically ranging from 100 to 250 psi for industrial service. Its primary purpose is to deliver continuous, pulsation-free compressed air for pneumatic tools, process automation, and instrument air systems. Oil-free screw compressors command premium positioning in food processing and pharmaceutical applications where ISO 8573 Class 0 certification eliminates contamination risk. Variable frequency drive technology represents the fastest-expanding segment as facilities pursue load-matched energy consumption rather than fixed-speed unload cycles. Portable screw compressors occupy a mature, price-sensitive niche tied to construction and mining site mobility requirements.
The US EPA and OSHA enforce permissible exposure limits and energy-performance benchmarks that shape compressor selection in American manufacturing plants. The EU F-Gas Regulation and CE marking requirements under the Machinery Directive restrict refrigerant choices and mandate safety interlocks for European-deployed units. India's BIS energy-labeling standards and the Bureau of Energy Efficiency's compulsory norms are tightening eligibility for industrial procurement tenders. Stakeholders must monitor how regional efficiency standards diverge and whether local content rules in India and Southeast Asia reshape supplier qualification criteria for large infrastructure contracts.
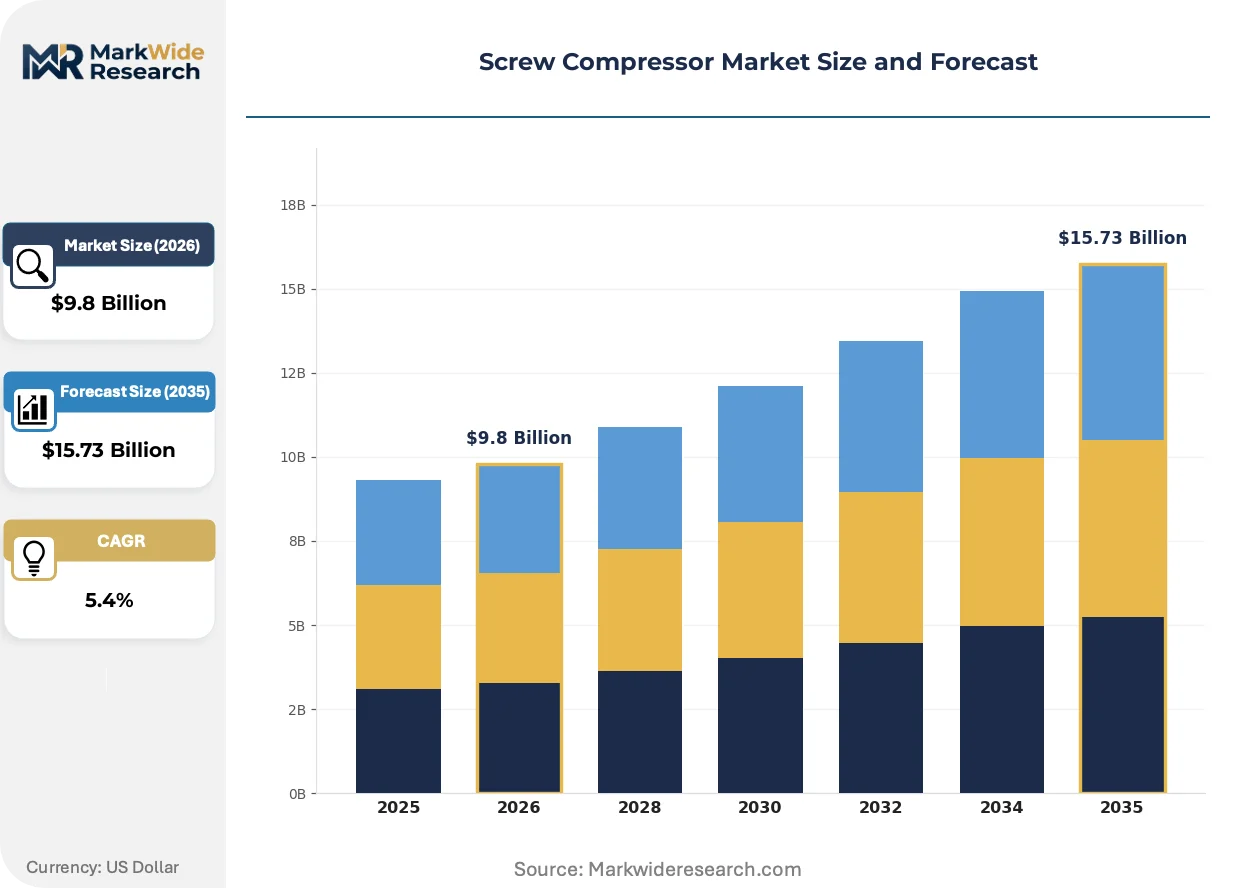
Market Dynamics
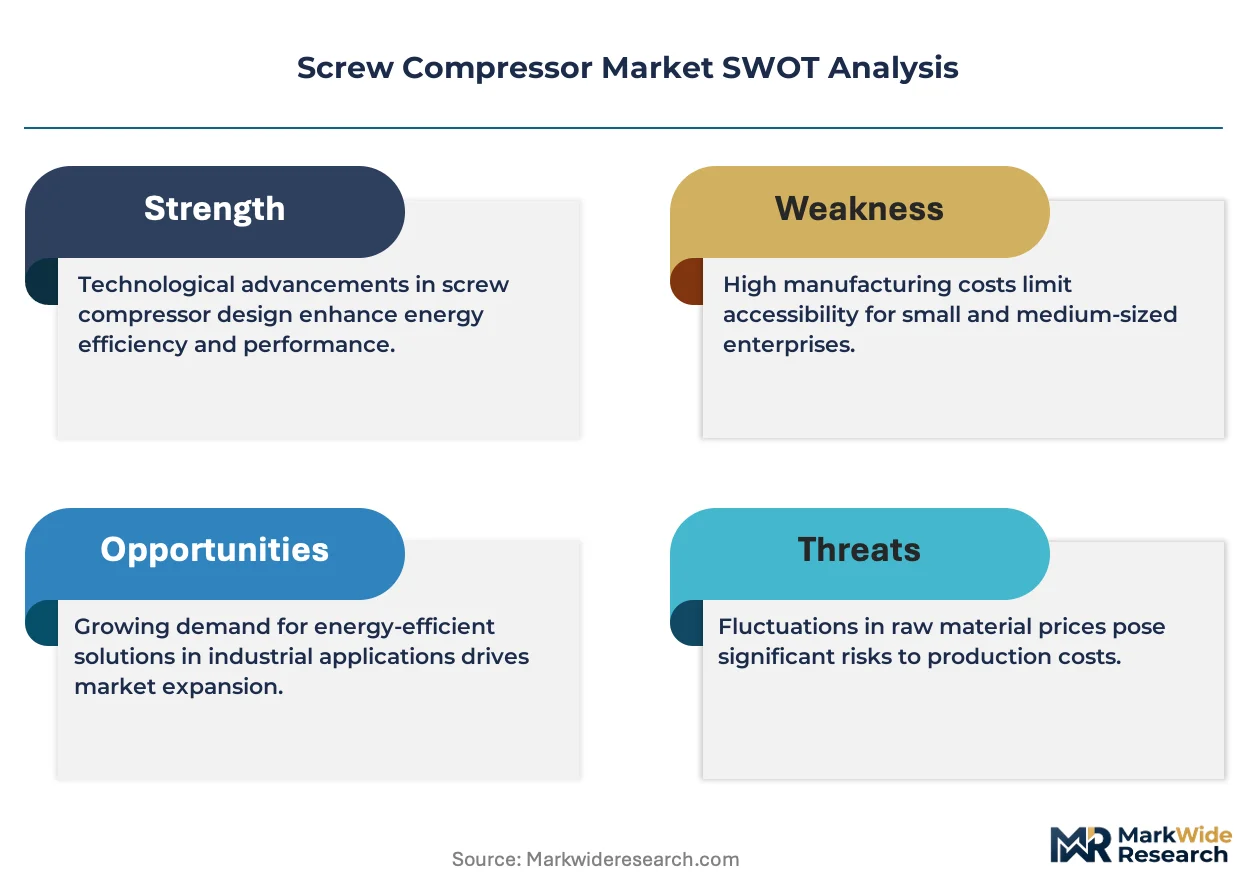
Variable frequency drive technology is compressing fixed-speed compressor margins as energy-efficiency mandates tighten across industrial geographies. Facilities now demand load-matched consumption rather than legacy unload cycles.
Growth Catalysts
- China's dual carbon goals:National energy-efficiency mandates accelerate displacement of piston compressors with variable-speed screw systems in heavy manufacturing corridors.
- ISO 8573 Class 0 certification:Food processing and pharmaceutical facilities pursue oil-free compressor fleets to eliminate contamination risk in sensitive production environments.
- Hyderabad-Ahmedabad pharmaceutical clusters:Clean air certification requirements drive accelerated equipment refresh cycles in India's concentrated drug manufacturing belt.
Market Restraints
- Rare earth magnet supply concentration:Permanent magnet motor production depends on Chinese raw material processing, creating input vulnerability for high-efficiency variable-speed units.
- EU F-Gas Regulation:Refrigerant restrictions on compressor cooling systems add compliance friction and limit retrofit options for installed European base.
- Centrifugal compressor substitution:Large-scale continuous-process facilities above 500 kW increasingly specify oil-free centrifugal alternatives for peak efficiency.
Strategic Opportunities
- Southeast Asian food processing expansion:Stricter contamination standards in Vietnam, Thailand, and Indonesia create white space for oil-free compressor deployment.
- India's PLI scheme for manufacturing:Production-linked incentives attract domestic compressor assembly investment to serve regional infrastructure tenders.
- Predictive maintenance convergence:IoT sensor integration with compressor control systems enables remote monitoring contracts as a recurring revenue channel.
Industry Challenges
- Rotor profile grinding expertise:Precision machining of asymmetric helical rotors requires specialized toolpath programming skills concentrated in Central European supplier networks.
- Legacy control system integration:Variable-speed drives must interface with existing plant SCADA architectures, extending commissioning timelines and requiring custom protocol gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Screw Compressor Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil-injected, Oil-free, Variable speed, Portable Application: Manufacturing, Food processing, Oil & gas, Chemical production End User: Industrial, Construction, Mining, Automotive Technology: Single stage, Multi-stage, Direct drive, Variable frequency drive |
| Companies Covered | Atlas Copco, Ingersoll Rand, Hitachi Industrial Equipment Systems, Kaeser Kompressoren, ELGi Equipments Limited, Gardner Denver, Sullair, Daikin Industries, Emerson Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Screw Compressor Market Strategic Shifts & Innovations
Compressed air system architecture is fragmenting into modular, digitally orchestrated subsystems. Component-level intelligence now competes with traditional centralized control paradigms.
Permanent magnet synchronous motor technology is hybridizing with traditional induction motor compressor designs. The technology eliminates rotor slip losses and enables wider turndown ratios for partial-load operation. Automotive and electronics manufacturers with fluctuating shift patterns adopt these configurations fastest. This convergence is hybridizing the boundary between premium and standard equipment tiers, compressing mid-market positioning.
REACH chemical restrictions and EU F-Gas Regulation are tightening refrigerant and lubricant specifications for compressor cooling circuits. Industrial users face retrofit limitations or complete system replacement to maintain compliance. Oil-free screw configurations in pharmaceutical and food-grade applications face the steepest compliance cost escalation, accelerating migration to air-cooled alternatives.
Service contract unbundling is fragmenting traditional bundled aftermarket relationships. End users now separate predictive monitoring, parts supply, and labor into discrete procurement decisions. Heavy manufacturing facilities in Germany and the US lead this disaggregation. Channel intermediaries face margin compression as OEMs build direct digital service interfaces to capture recurring monitoring revenue.
Screw Compressor Market Segmentation
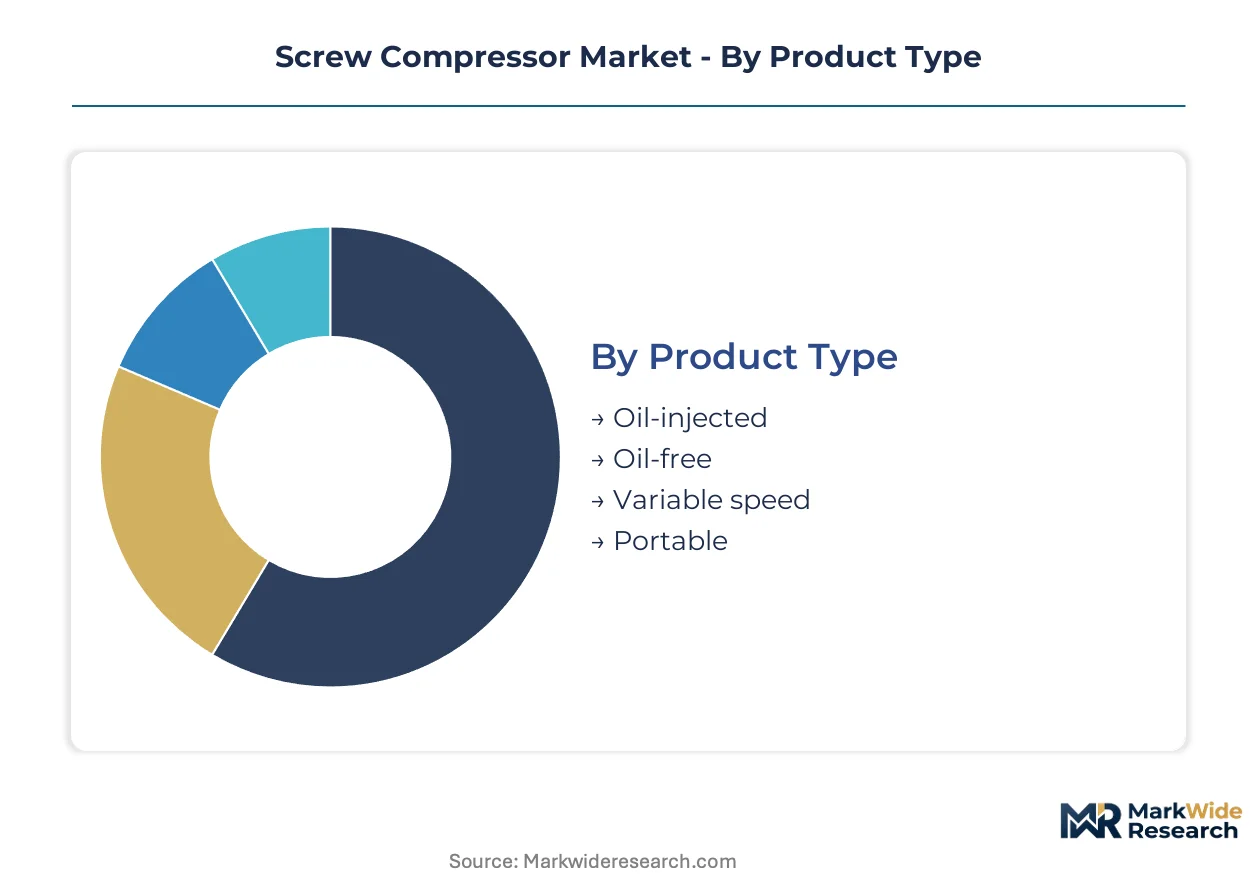
Screw compressor segmentation reveals divergent service intensity and lifecycle economics across product tiers. Oil-free and variable-speed configurations demand specialized aftermarket protocols that reshape distributor profitability and end-user total cost calculations.
Product Type:
Aftermarket service intensity varies dramatically across lubrication architectures, with oil-free systems requiring precision rotor reconditioning and sealed bearing replacement at compressed intervals.
- Oil-injected:These systems utilize lubricant-flooded compression chambers to seal rotor clearances and dissipate heat, achieving pressure ratios up to 13 bar in continuous-duty manufacturing environments. Demand concentrates in China's heavy industrial corridors where energy-efficiency mandates are displacing legacy piston equipment, though water separation and oil filtration maintenance impose recurring service costs.
- Oil-free:Dry compression chambers eliminate hydrocarbon contamination through precision-timed rotor profiles and specialized coatings, achieving ISO 8573 Class 0 certification required by pharmaceutical manufacturers near Hyderabad and Ahmedabad. The absence of lubricant cooling demands more frequent bearing inspection and tighter rotor clearance monitoring, elevating service contract value per installed unit.
- Variable speed:Integrated permanent magnet motors with wide turndown ratios match output to fluctuating demand patterns in automotive assembly plants.
- Portable:Skid-mounted or trailer configurations serve construction and mining site mobility requirements with simplified maintenance protocols.
By volume, oil-injected systems lead. By growth pace, variable speed configurations are expanding most quickly.
Application:
Process criticality determines specification tier and spare parts stocking depth, with food and pharmaceutical applications mandating redundant backup capacity and expedited service response.
- Manufacturing:General industrial pneumatic power and automation systems constitute the baseline volume segment across automotive and electronics assembly operations.
- Food processing:Oil-free screw compressors eliminate product contamination risk in Southeast Asian facilities expanding to meet export certification requirements, with compressed air contacting packaging and processing equipment directly.
- Oil & gas:Explosion-proof enclosures and sour gas compatibility specifications dominate upstream and midstream deployment in hydrocarbon extraction corridors.
- Chemical production:Corrosion-resistant materials and specialized sealing systems address aggressive process environments in continuous-flow reactor operations.
Manufacturing commands the largest installed base. Food processing demonstrates the steepest expansion trajectory as contamination standards tighten across export markets.
End User:
Operational continuity requirements separate capital expenditure approaches, with mining and automotive sectors diverging on redundancy investment and predictive maintenance adoption.
- Industrial:Diverse manufacturing and process facilities with scheduled maintenance windows and moderate uptime penalties for unplanned outages.
- Construction:Project-based demand with high equipment utilization rates and rapid depreciation schedules favoring rental and lease procurement models.
- Mining:Remote site operations with extreme dust loading and limited service access drive specification toward heavy-duty filtration and extended maintenance intervals.
- Automotive:Fluctuating shift patterns and just-in-time production dependencies create demand for load-matched variable-speed configurations with minimal unload energy losses.
Industrial end users represent the deepest installed base. Automotive sector demand is gaining share fastest as electrification transitions reshape component manufacturing footprints.
Technology:
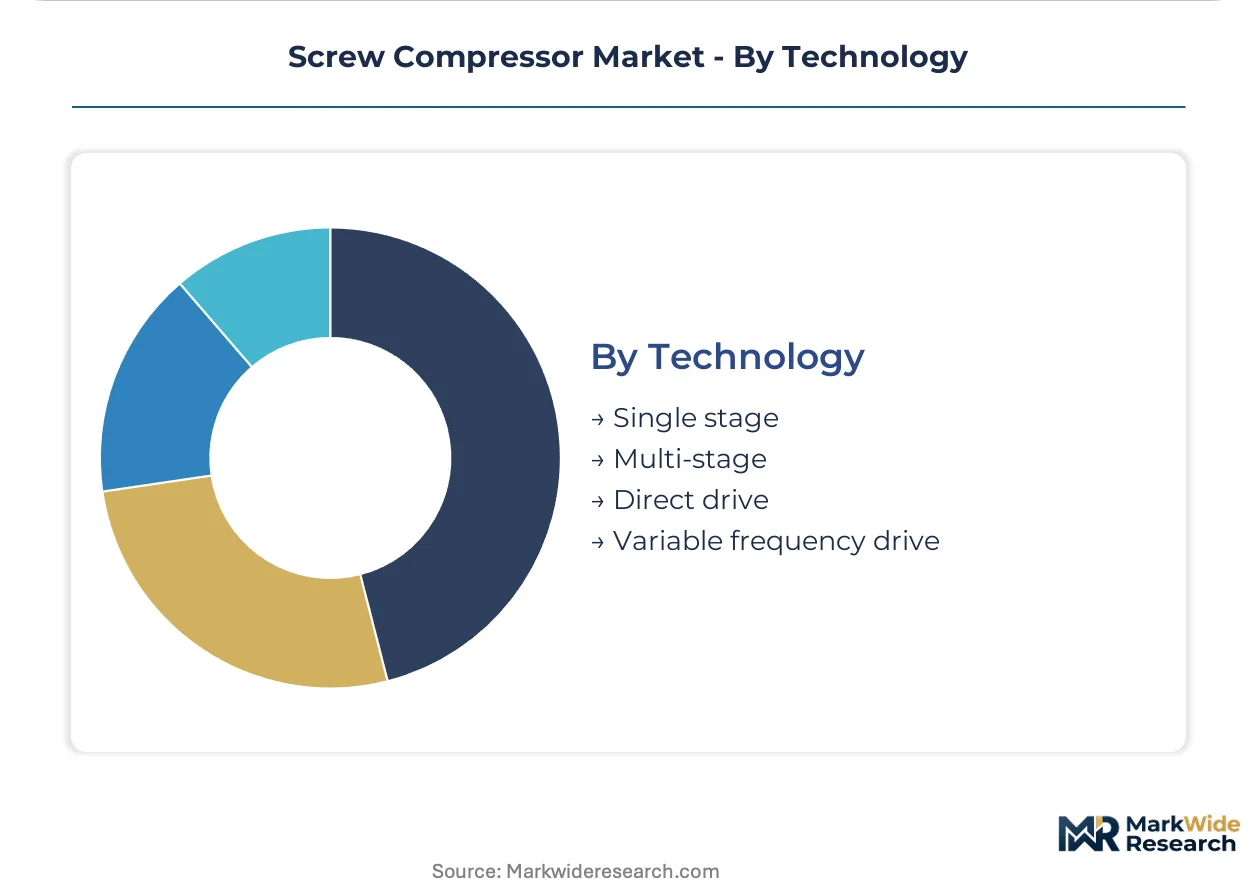
Drive architecture and staging configuration determine energy recovery potential and integration complexity with existing plant control systems.
- Single stage:One compression chamber achieves discharge pressures up to 10 bar for general industrial service with simplified rotor geometry and reduced manufacturing cost.
- Multi-stage:Intercooled compression sequences improve thermodynamic efficiency for high-pressure applications above 13 bar in petrochemical process duty.
- Direct drive:Coupled motor-compressor arrangements eliminate belt maintenance and alignment drift in continuous-operation environments.
- Variable frequency drive:Inverter-controlled motor speed matches airflow to real-time demand, eliminating unload cycles and reducing energy consumption in fluctuating load profiles.
Single stage systems dominate unit shipments. Variable frequency drive technology is climbing the fastest as efficiency mandates harden across industrial geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European screw compressor installations command 15-20% pricing premiums over comparable Indian deployments, reflecting tighter efficiency certification costs and specialized service density. This asymmetry shapes how multinational suppliers configure regional product portfolios and aftermarket contract structures.
China
MIIT energy-efficiency mandates and the dual carbon goals are accelerating displacement of piston compressors with variable-speed screw systems across heavy manufacturing corridors. GB standards for compressor performance are tightening eligibility for government procurement tenders. The Yangtze River Delta industrial belt near Shanghai is seeing concentrated fleet upgrades as export-oriented manufacturers face buyer-imposed carbon accounting requirements.
Germany
REACH chemical restrictions and EU F-Gas Regulation are forcing refrigerant and lubricant specification changes in compressor cooling circuits. CE marking requirements under the Machinery Directive mandate safety interlocks and documentation protocols that elevate compliance costs. The Baden-Württemberg automotive manufacturing cluster around Stuttgart is driving demand for load-matched variable-speed configurations with minimal unload energy losses.
United States
OSHA permissible exposure limits and EPA energy-performance benchmarks shape compressor selection in American manufacturing plants. The IRA manufacturing incentives are stimulating domestic production facility expansions with modern compressed air infrastructure. The Gulf Coast petrochemical corridor spanning Texas and Louisiana is specifying explosion-proof screw compressor systems for continuous-process hydrogen and syngas applications.
India
BIS energy-labeling standards and the Bureau of Energy Efficiency's compulsory norms are tightening eligibility for industrial procurement tenders. The PLI scheme for manufacturing is attracting domestic compressor assembly investment to serve regional infrastructure contracts. Pharmaceutical manufacturing corridors near Hyderabad and Ahmedabad are driving accelerated equipment refresh cycles as clean air certification requirements harden.
Japan
METI industrial efficiency targets and JIS standards for compressed air quality are elevating specification tiers in precision manufacturing sectors. The country's national carbon neutrality commitments are pressuring facility managers to retire aging piston equipment. The Chubu industrial region around Nagoya is seeing concentrated adoption of oil-free screw systems in automotive electronics and semiconductor component fabrication.
Screw Compressor Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in rotor machining and control module supply. The vendor base separates into three strategic archetypes: diversified industrial conglomerates with captive compressor divisions, dedicated compressed air specialists with dense service networks, and emerging Asian fabricators competing on export pricing. Competitive positioning hardens through backward integration into permanent magnet motor production and forward integration into predictive maintenance software platforms.
Within the diversified industrial tier, Atlas Copco and Ingersoll Rand exemplify platform integrators with captive aftermarket channels sustaining recurring revenue from parts and monitoring contracts. Kaeser Kompressoren represents the dedicated specialist archetype, anchoring position through authorized dealer density across Central European industrial belts. ELGi Equipments Limited occupies the emerging fabricator position, competing aggressively on export pricing from its Indian manufacturing base while building regional service hubs.
| Leading Market Players |
|---|
| Atlas Copco |
| Ingersoll Rand |
| Hitachi Industrial Equipment Systems |
| Kaeser Kompressoren |
| ELGi Equipments Limited |
| Gardner Denver |
| Sullair |
| Daikin Industries |
| Emerson Electric |
| Others |
Cost & Logistics Intelligence
Rare earth magnet processing concentration in China anchors cost structures for permanent magnet motor production, concentrating margin capture upstream while downstream OEMs compete on service contract bundling and predictive maintenance software integration. This asymmetry shapes how European and Indian manufacturers configure regional pricing strategies against Chinese domestic suppliers.
Pricing Analysis
Configured-to-order pricing for oil-free and variable-speed screw compressors commands 25-40% premiums over standard oil-injected units, with ISO 8573 Class 0 certification and permanent magnet motor integration as primary differentiation drivers. Pricing pressure stems from Asian fabricators competing aggressively on export pricing from Indian manufacturing bases, compressing mid-market positioning. Heavy manufacturing facilities in Germany and the United States demonstrate lowest price sensitivity due to uptime penalty costs, while construction and mining procurement in Southeast Asia shows highest sensitivity favoring rental and lease models.
Supply Chain Analysis
Export-control restrictions on permanent magnet motor technology limit flows of high-efficiency variable-speed drive components from Chinese suppliers to European and North American OEMs, creating input vulnerability for premium compressor tiers. Manufacturing concentration centers on China, Germany, and India for rotor machining and final assembly, with specialized toolpath programming skills for asymmetric helical profiles concentrated in Central European supplier networks. Distribution runs through OEM captive service networks and authorized dealer footprints, with direct digital interfaces increasingly capturing recurring monitoring revenue and disaggregating traditional bundled aftermarket relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Screw compressor markets are approaching a platform-economics inflection where IoT-enabled predictive maintenance ecosystems and remote monitoring software interoperability determine supplier stickiness beyond hardware specifications.
For Market Incumbents: Harden rotor profile grinding expertise retention through captive training programs and specialized toolpath programming partnerships in Central European supplier networks to defend against emerging Asian fabricators. Anchor position through backward integration into permanent magnet motor production and forward integration into predictive maintenance software platforms, countering centrifugal compressor substitution above 500 kW and rare earth magnet supply concentration risks. For New Entrants and Emerging Players: Southeast Asian food processing corridors in Vietnam, Thailand, and Indonesia present underpenetrated white space as stricter contamination standards create demand for oil-free compressor deployment without entrenched incumbent service density. Target pharmaceutical manufacturing clusters near Hyderabad and Ahmedabad where clean air certification requirements drive accelerated equipment refresh cycles, entering through aggressive export pricing from Indian manufacturing bases paired with regional service hub buildouts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed compressed air specialists holding dense authorized dealer footprints across Central European industrial belts but lacking predictive maintenance software capabilities. Five-to-ten year viability hinges on digital service platform integration and recurring revenue capture from parts and monitoring contracts; watch for centrifugal compressor substitution acceleration in large-scale continuous-process facilities above 500 kW as an inflection signal for screw compressor addressable market compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Motors | Eliminates rare earth supply vulnerability for variable-speed compressor tiers serving automotive electrification transitions. |
| Predictive Maintenance Software Platform Launch | Captures recurring monitoring revenue from German and US heavy manufacturing facilities disaggregating service procurement. |
| Regional Service Hub Expansion in Southeast Asia | Supports oil-free compressor deployment in Vietnam and Thailand food processing facilities facing export certification requirements. |
| ISO 8573 Class 0 Certification Investment | Unlocks pharmaceutical procurement corridors near Hyderabad and Ahmedabad with mandatory clean air specifications. |
| Joint Venture for Rotor Machining Capability | Secures asymmetric helical profile grinding expertise concentrated in Central European supplier networks against capability scarcity. |
Research Approach
A spread of perspectives from plant engineers, maintenance directors, OEM procurement teams, aftermarket service heads, and compressed air system integrators converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against customs and trade data, SEC 10-K filings, Bureau of Energy Efficiency compulsory norm disclosures, and MIIT energy-efficiency mandate documentation. Bottom-up unit shipment modeling and top-down industrial capital expenditure triangulation anchored volume and value estimates.
Demand-supply-balance framing structured the analytical approach across the projection horizon, with segmentation modeling across lubrication architecture, drive technology, end-use industry, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating efficiency mandate acceleration timelines, pharmaceutical manufacturing corridor expansion patterns, and rare earth magnet supply elasticity assumptions. Industry-specific inputs included plant-level compressed air audit data and OEM service contract pricing disclosures.
Practitioners should monitor MIIT mandate enforcement intensity, EU F-Gas Regulation refrigerant restriction expansion, and permanent magnet motor export-control tightening for early signals requiring forecast revision. Cross-checking against Bureau of Energy Efficiency tender eligibility databases and industrial procurement tracker data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
China HVAC Market
HVAC Equipment
Ventilation Fan Market
HVAC Equipment
Industrial Blowers Market
HVAC Equipment
Chilled Beams Market
HVAC Equipment
Europe Ventilation Equipment Market
HVAC Equipment
HVAC Pumps Market
HVAC Equipment
France Commercial HVAC Market
HVAC Equipment
Equipment Fan Filter Unit (EFU) Market
HVAC Equipment
Louver Dampers Market
HVAC Equipment
Heating Equipment Market
HVAC Equipment
Fabric Air Ducts Market
HVAC Equipment
Commercial Refrigeration Equipment Market
HVAC Equipment
Global Industrial Air Chiller Market
HVAC Equipment
Europe Industrial Heat Pump Market
HVAC Equipment
Compressor Market
HVAC Equipment
US Residential Heat Pump Market