
 Refrigeration and Air Conditioning Compressors Market | 2026-2036
Refrigeration and Air Conditioning Compressors Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigeration and Air Conditioning Compressors Market Analytics
Variable-speed digital inverter technology is reconfiguring compressor architectures across residential and commercial systems. Panasonic Corporation leverages its semiconductor expertise to integrate intelligent power modules directly into compressor motor drives. Daikin Industries anchors premium positioning through proprietary swing-compressor designs optimized for R-32 refrigerant compatibility. Carrier Global Corporation sustains project-engineering dominance in large-tonnage centrifugal installations for data center cooling.
Refrigeration and air conditioning compressors are mechanical devices that raise refrigerant pressure and temperature through volumetric displacement or dynamic compression, typically achieving discharge pressures between 150 and 450 psig depending on application and refrigerant type. Their primary purpose is to circulate refrigerant through vapor-compression cycles that extract heat from conditioned spaces or processes and reject it to ambient sinks. Scroll compressors now lead the residential air conditioning segment due to superior efficiency and quieter operation, while screw configurations dominate industrial process cooling where part-load performance determines operating economics. Digital inverter technology represents the fastest-growing technology category as building codes tighten minimum efficiency requirements and utilities expand demand-response programs.
The US Environmental Protection Agency enforces SNAP program restrictions on high-global-warming-potential refrigerants under Clean Air Act authority, directly affecting compressor sealing materials and lubricant specifications. The European Union F-Gas Regulation mandates stepped reductions in fluorinated gas consumption, compelling OEMs to certify compressors for CO2, propane, and hydrofluoroolefin refrigerants. India's Bureau of Energy Efficiency implements mandatory labeling and performance standards for room air conditioners that cascade into compressor efficiency tiers. Stakeholders must monitor refrigerant-phaseout schedules, efficiency standard convergence across jurisdictions, and inverter-control intellectual property positions to anticipate procurement and product-development priorities.
Market Dynamics
The Kigali Amendment's hydrofluorocarbon phasedown mandates are forcing compressor architecture redesigns for lower-global-warming-potential refrigerants, while variable-speed digital inverter technology simultaneously reconfigures efficiency benchmarks across residential and commercial installations.
Growth Catalysts
- Cold Chain Logistics Expansion:Pharmaceutical and perishable food distribution requirements in developing economies are accelerating fleet capacity investments, directly lifting demand for commercial-grade compressor systems.
- F-Gas Regulation:The European Union's stepped fluorinated gas consumption reductions are compelling OEMs to certify compressors for CO2, propane, and hydrofluoroolefin alternatives, creating replacement cycles.
- Residential AC Penetration:India's accelerating air conditioning adoption, combined with Bureau of Energy Efficiency mandatory labeling standards, is cascading into tiered compressor efficiency demand.
Market Restraints
- Refrigerant Transition Costs:Redesigning compressor sealing materials and lubricant specifications for lower-GWP alternatives imposes R&D burden and retooling capex on manufacturers.
- Supply Concentration Risk:Rare earth magnet dependencies for high-efficiency permanent magnet motors concentrate in limited geographic sources, exposing inverter compressor production to input volatility.
- Technical Limitation:CO2 transcritical systems operate at substantially higher pressures than conventional refrigerants, limiting compressor design portability and requiring specialized manufacturing competencies.
Strategic Opportunities
- Data Center Cooling:Hyperscale computing load growth is creating dedicated demand for large-tonnage centrifugal compressor installations with precise temperature control requirements.
- Demand-Response Integration:Utility-sponsored grid stabilization programs are creating premium positioning for inverter-controlled compressors with embedded communication protocols for automated load modulation.
- Swing-Compressor Architectures:Proprietary designs optimized for R-32 refrigerant compatibility offer differentiation pathways as single-component refrigerants displace blends requiring glide management.
Industry Challenges
- Refrigerant-Certification Timeline:Multi-jurisdictional safety standard approvals for flammable A2L and A3 refrigerants compress product launch windows and fragment regional product portfolios.
- Power Electronics Integration:Intelligent power module incorporation into compressor motor drives requires semiconductor expertise foreign to traditional mechanical component suppliers, forcing partnership or acquisition decisions.
- Retrofit Compatibility:Existing installed base mineral oil incompatibility with new synthetic lubricants necessary for lower-GWP refrigerants complicates field conversion economics and contractor training requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigeration and Air Conditioning Compressors Market |
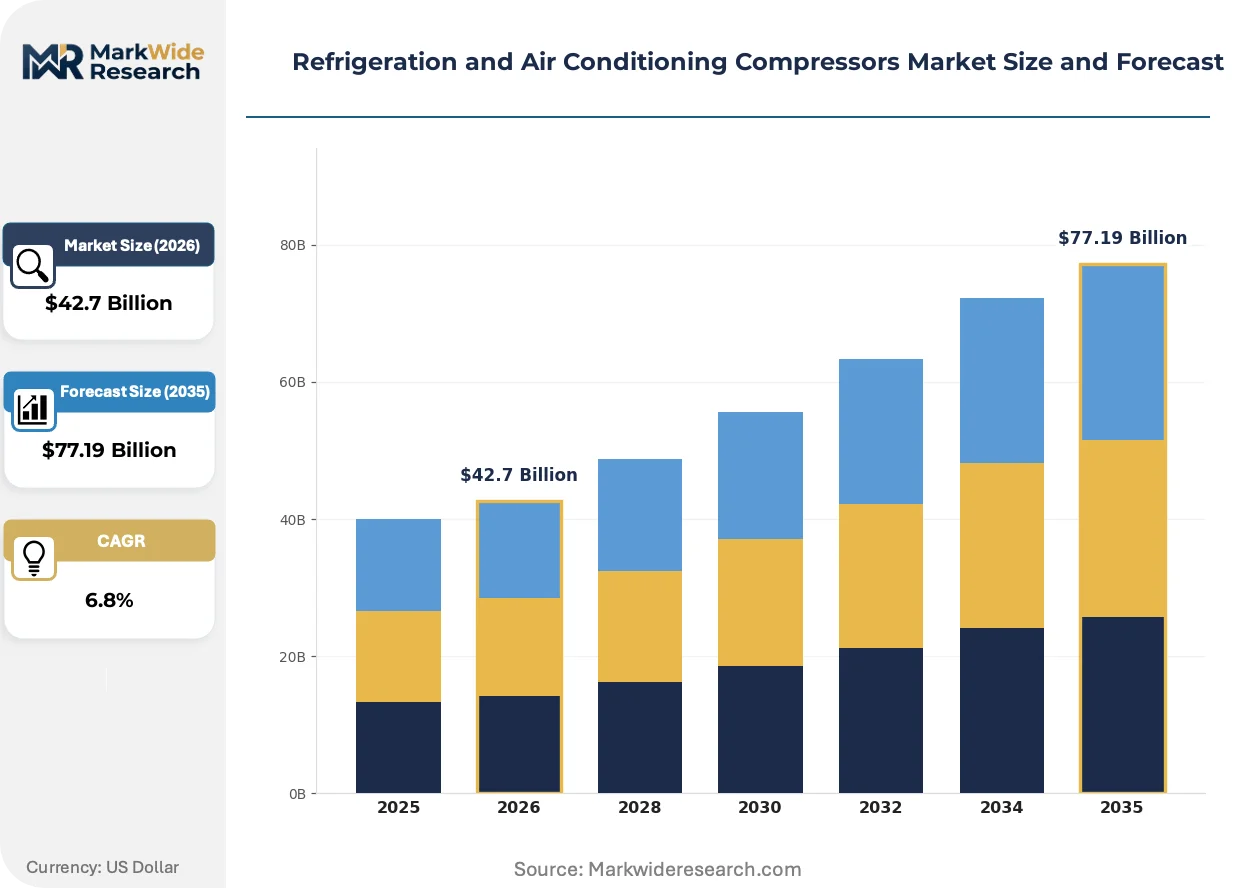
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $77.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scroll, Reciprocating, Centrifugal, Screw End User: Residential, Commercial, Industrial, Automotive Technology: Variable Speed, Fixed Speed, Digital Inverter, Hybrid Application: Food Preservation, HVAC, Transportation, Process Cooling |
| Companies Covered | Midea Group, Panasonic Corporation, Mitsubishi Electric Corporation, Johnson Controls–Hitachi Air Conditioning, Daikin Industries, Carrier Global Corporation, LG Electronics, Bitzer SE, Emerson Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigeration and Air Conditioning Compressors Market Evolving Landscape
Digital control architectures and refrigerant chemistry transitions are converging to redefine compressor performance baselines, with efficiency mandates and grid-interactive capabilities becoming inseparable design requirements rather than optional features.
Variable-speed digital inverter technology is virtualizing traditional fixed-capacity compressor operation by enabling continuous modulation rather than discrete cycling. Data center operators and commercial building managers are specifying these systems for part-load optimization. The technology is virtualizing aftermarket service models by embedding predictive diagnostics that compress unplanned downtime windows.
The US Environmental Protection Agency's SNAP program restrictions on high-global-warming-potential refrigerants are reshaping compressor material specifications under Clean Air Act enforcement. Sealing elastomer selections and lubricant viscosities must now accommodate hydrofluoroolefin and natural refrigerant chemistries. Residential and light commercial original equipment manufacturers are responding with accelerated R-32 and R-454B certification timelines.
After-sales service unbundling is fragmenting traditional compressor procurement relationships as end-users separate hardware acquisition from maintenance contracts. Industrial process cooling operators in North America and Europe are negotiating performance-guarantee arrangements distinct from capital equipment purchases. This bifurcation is most visible in pharmaceutical manufacturing clusters where validated cold chain uptime requirements dominate vendor selection criteria.
Refrigeration and Air Conditioning Compressors Market Segmentation
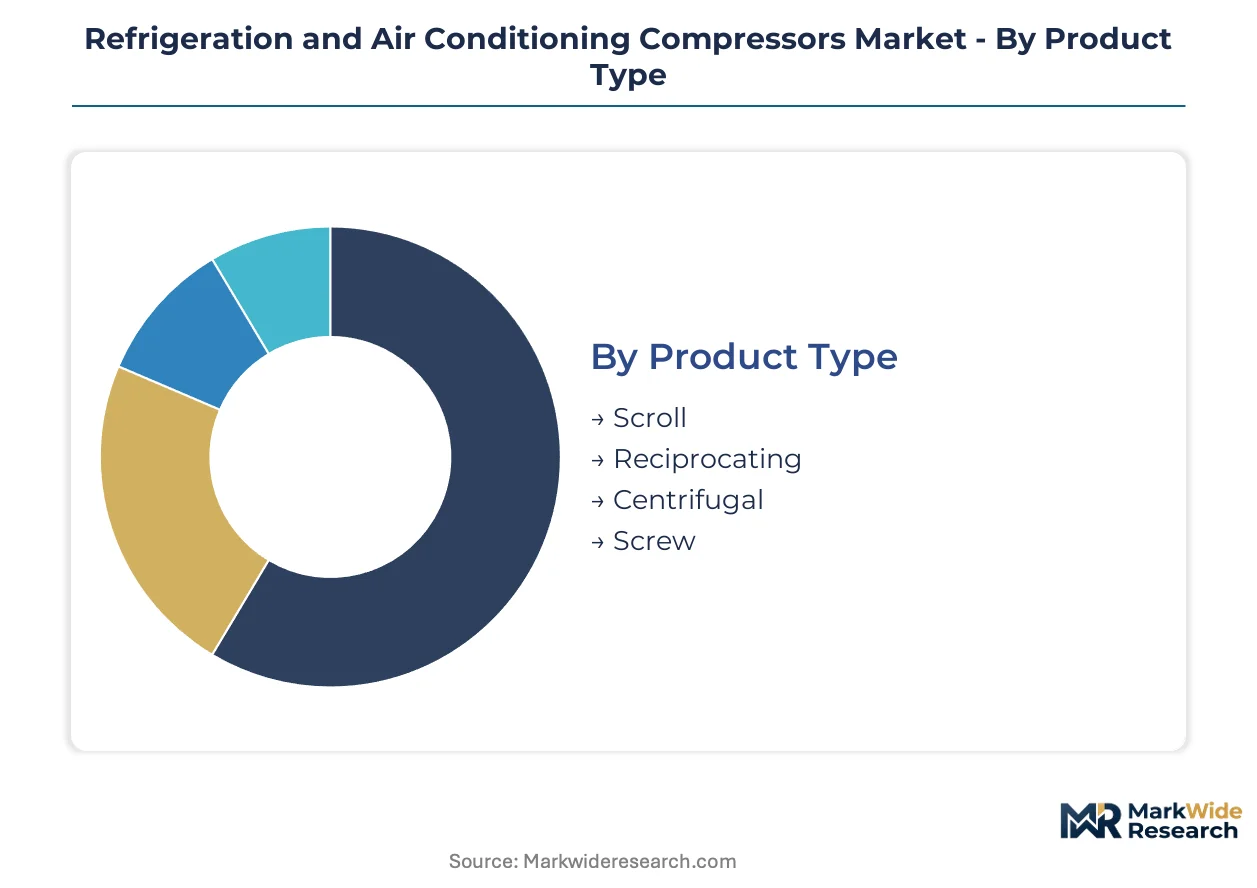
Compressor segmentation reveals divergent replacement cycles across product architectures, with residential scroll units turning over every 10-15 years while industrial screw installations persist 20-25 years. Technology transitions and refrigerant phaseouts are compressing these cycles unevenly, forcing suppliers to maintain parallel production lines for legacy and next-generation specifications.
Product Type:
Scroll compressors rotate through replacement fastest in residential service, while centrifugal units anchor the slowest-turnover tier in infrastructure-scale installations.
- Scroll:Orbiting and fixed scrolls compress refrigerant through intermeshing spiral geometry, eliminating reciprocating valve losses. Residential air conditioning penetration in India and Southeast Asia concentrates demand here, with Bureau of Energy Efficiency labeling tiers filtering procurement toward higher-efficiency variants.
- Reciprocating:Piston-driven volumetric compression operates through crankshaft-actuated cylinders with suction and discharge reed valves. Cold chain logistics fleet expansion across Brazil and Mexico sustains commercial refrigeration demand for this cost-optimized architecture.
- Centrifugal:Dynamic compression via high-speed impellers achieves large tonnage with minimal moving parts. Data center cooling clusters in Virginia, Frankfurt, and Singapore specify these for hyperscale load management.
- Screw:Twin helical rotors mesh to deliver continuous compression with superior part-load performance. Industrial process cooling in German chemical manufacturing and Japanese automotive painting lines depends on screw configurations.
Scroll dominates installed base. Centrifugal is where expansion concentrates for mission-critical thermal management.
End User:
Customer-type segmentation maps directly to margin architecture, with industrial buyers negotiating performance guarantees while residential procurement fragments across price-sensitive retail channels.
- Residential:Unitary and split-system compressors serve single-family and multi-family dwellings. India's accelerating air conditioning adoption, combined with mandatory efficiency labeling, cascades into tiered compressor procurement.
- Commercial:Rooftop units, chillers, and display case systems serve retail, hospitality, and office verticals. European F-Gas Regulation compliance is compelling retrofit cycles across supermarket chains in France, Germany, and Italy.
- Industrial:Process cooling, cold storage, and manufacturing climate control require continuous-duty architectures. Pharmaceutical manufacturing clusters in Switzerland and Massachusetts validate uptime through performance-based maintenance contracts.
- Automotive:Electric vehicle thermal management and cabin comfort systems integrate compact variable-speed compressors. Battery thermal conditioning demands are expanding compressor duty cycles beyond traditional HVAC loads.
Commercial captures replacement volume. Industrial commands premium positioning through performance guarantees.
Technology:
Control sophistication stratifies pricing power, with digital inverter architectures commanding 40-60% premiums over fixed-speed equivalents in efficiency-regulated markets.
- Variable Speed:Motor frequency modulation matches capacity to thermal load rather than cycling on-off. Japanese and South Korean utilities sponsor demand-response programs that specify these for grid stabilization credits.
- Fixed Speed:Single-speed operation at rated capacity provides baseline cost positioning. Price-sensitive residential markets in Indonesia and Vietnam retain this architecture for entry-tier room air conditioners.
- Digital Inverter:Intelligent power modules enable precise speed control with embedded diagnostics. US EPA SNAP program restrictions on high-GWP refrigerants are accelerating certification timelines for inverter-optimized R-32 and R-454B systems.
- Hybrid:Dual-mode operation combines fixed and variable capacity stages for transitional efficiency. Commercial building retrofits in California and New York specify hybrids where full inverter conversion economics prove prohibitive.
Fixed speed anchors volume. Digital inverter is climbing the fastest as efficiency codes tighten.
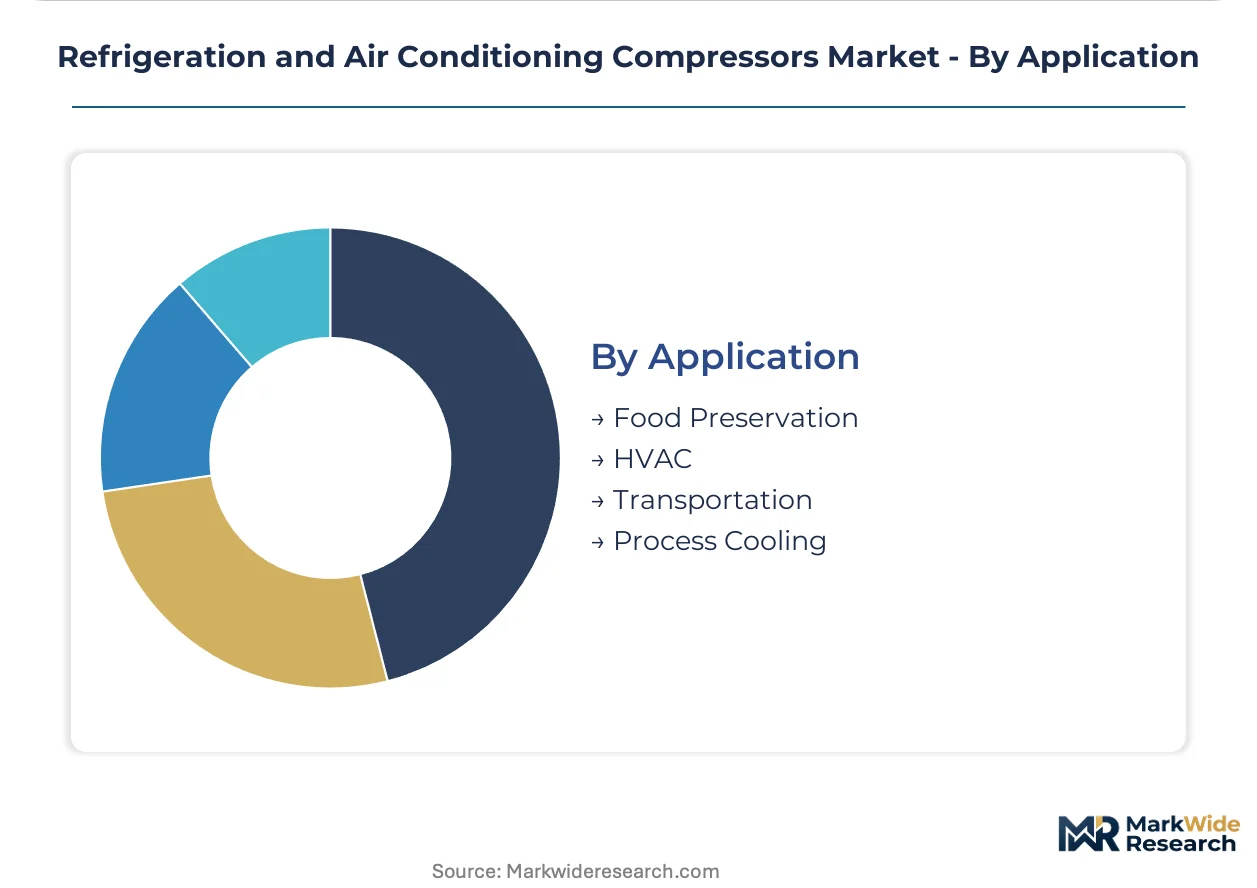
Application:
End-use thermal requirements dictate compressor specification divergence, with food preservation demanding precise humidity control and data center cooling prioritizing continuous operation.
- Food Preservation:Cold storage, refrigerated transport, and retail display cases maintain precise temperature bands. Indian cold chain logistics operators are expanding fleet capacity to meet pharmaceutical and perishable food distribution requirements.
- HVAC:Space conditioning for human comfort spans residential through commercial scale. Kigali Amendment hydrofluorocarbon phasedown mandates are forcing compressor redesigns for lower-GWP alternatives across this application.
- Transportation:Reefer containers, truck refrigeration, and railcar cooling enable temperature-controlled logistics. Port infrastructure investments in Rotterdam and Singapore are lifting demand for containerized compressor systems.
- Process Cooling:Manufacturing, chemical, and pharmaceutical production requires precise temperature control. CO2 transcritical systems for this application operate at substantially higher pressures, limiting compressor design portability.
HVAC dominates installed base. Food preservation is where expansion concentrates for cold chain infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports compressor systems to India and Southeast Asian markets through established manufacturing corridors. Cold chain infrastructure buildouts and residential air conditioning penetration across developing economies drive cross-border procurement flows. Regulatory divergence on refrigerant phaseout timelines fragments regional product specifications.
United States
Data center cooling clusters in Virginia and Texas anchor demand for large-tonnage centrifugal installations. The EPA enforces SNAP program restrictions on high-GWP refrigerants under Clean Air Act authority. Pharmaceutical manufacturing validated cold chain requirements in Massachusetts and North Carolina sustain premium compressor procurement.
China
Domestic residential air conditioning replacement cycles and commercial refrigeration retrofits concentrate demand in coastal manufacturing zones. The Ministry of Ecology and Environment implements dual carbon goals that cascade into compressor efficiency mandates. Yangtze River Delta industrial clusters supply inverter-controlled systems for Southeast Asian export markets.
India
Commercial refrigeration retrofits and residential air conditioning penetration accelerate simultaneously across urban centers. The Bureau of Energy Efficiency mandates labeling and performance standards for room air conditioners that filter procurement toward higher-efficiency compressor tiers. Cold chain logistics operators in Maharashtra and Gujarat expand fleet capacity for pharmaceutical distribution.
Germany
Industrial process cooling in chemical manufacturing and automotive painting lines sustains screw compressor demand. The EU F-Gas Regulation mandates stepped fluorinated gas consumption reductions that compel OEM certification for CO2 and propane alternatives. Bavarian and North Rhine-Westphalian industrial clusters validate uptime through performance-based maintenance contracts.
Japan
Semiconductor-integrated compressor motor drives and proprietary swing-compressor designs anchor technology leadership. METI sponsors demand-response programs that specify inverter-controlled systems for grid stabilization credits. Kanto and Kansai manufacturing bases export digital inverter architectures to Southeast Asian markets.
Refrigeration and Air Conditioning Compressors Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidation pressure concentrates among full-system integrators while component specialists retain niche positioning. Three archetypes dominate: diversified industrial conglomerates with captive demand, dedicated HVAC-R pure-plays with refrigerant-transition expertise, and electronics-origin entrants with power electronics capabilities. Capacity expansion in inverter motor production and strategic partnerships for semiconductor sourcing represent the dominant competitive moves.
Among Japanese-origin diversified manufacturers, Panasonic Corporation and Daikin Industries exemplify the electronics-to-HVAC integration archetype. Carrier Global Corporation anchors the American full-system engineering tradition. Midea Group represents the scale-driven Chinese manufacturing model. Each occupies distinct positioning vectors: semiconductor-integrated drives, proprietary refrigerant-optimized architectures, project-engineering dominance, and cost-optimized volume production respectively.
| Leading Market Players |
|---|
| Midea Group |
| Panasonic Corporation |
| Mitsubishi Electric Corporation |
| Johnson Controls–Hitachi Air Conditioning |
| Daikin Industries |
| Carrier Global Corporation |
| LG Electronics |
| Bitzer SE |
| Emerson Electric Co. |
| Others |
Value Network & Pricing Analysis
Rare earth magnet concentration in Chinese and Burmese mining corridors feeds directly into permanent magnet motor cost structures, concentrating margin capture among inverter compressor specialists with secured upstream offtake. This input geography locks pricing power with Japanese and South Korean manufacturers while forcing others into volatile spot-market exposure.
Pricing Analysis
Fixed-speed scroll compressors anchor economy-tier positioning at entry price points, while digital inverter architectures command 40-60% premiums in efficiency-regulated markets like Japan and the EU. Three-tier pricing structure across premium, standard, and economy levels separates certified R-32 systems from legacy R-410A inventory and transitional R-454B hybrids. Cost compression in fixed-speed tiers is intensifying because Indian and Indonesian OEMs are expanding domestic assembly capacity. Residential retrofit buyers in Southeast Asia exhibit highest price sensitivity, while data center operators in Virginia and Frankfurt prioritize performance guarantees over unit cost.
Supply Chain Analysis
Contract manufacturing for power electronics modules concentrates among Taiwan-based EMS providers and select Japanese semiconductor foundries with automotive-grade certification. Finished compressor assembly draws from China, Thailand, and Mexico, with rare earth magnet sourcing resting on Chinese separation facilities and Burmese heavy rare earth mines. Single-source vulnerability in neodymium-dysprosium supply chains exposes inverter motor production to export quota disruptions. Distribution runs through HVAC-R wholesale distributors in North America, integrated OEM captive channels in Japan, and project-engineering firms for large-tonnage centrifugal installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Performance-based maintenance contracts and predictive diagnostics subscriptions are expanding faster than hardware shipments, creating service-attach economics that favor incumbents with installed base visibility. Recurring revenue layers now determine enterprise valuation multiples in compressor manufacturing.
For Market Incumbents: Harden inverter motor supply chains through backward integration into rare earth magnet procurement or binding long-term offtake with Australian and Canadian mining projects. Deepen semiconductor partnerships to secure intelligent power module allocation amid automotive and industrial demand competition. Defensive consolidation of regional service networks protects against emerging pure-play diagnostics entrants unbundling aftermarket relationships. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, where F-Gas Regulation spillover from European OEMs has not yet saturated local certification. CO2 transcritical system specialization for Nordic and German supermarket chains offers technical differentiation against scroll-dominant incumbents. Go-to-market through regional cold chain logistics operators bypasses established HVAC-R distribution gatekeepers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European refrigeration specialists facing refrigerant-transition capex burdens and fragmented national service footprints. Five-to-ten year viability hinges on successful R-32 and CO2 certification completion before 2030 regulatory deadlines. Monitor Bureau of Energy Efficiency labeling tier migrations in India as inflection indicator for efficiency-premium compressor demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Rare Earth Magnet Supply Agreement | Binding offtake with Australian or Canadian mining projects secures inverter motor input cost predictability against Chinese quota volatility. |
| Semiconductor Partnership Expansion | Collaboration with Taiwan-based EMS providers ensures automotive-grade power module allocation for digital inverter compressor production. |
| CO2 Transcritical Certification Investment | Specialized engineering competence for high-pressure systems opens German and Nordic supermarket retrofit cycles under F-Gas Regulation. |
| Predictive Diagnostics Platform Launch | Embedded sensor networks and cloud-based uptime monitoring transform hardware margins into recurring service revenue streams. |
| Southeast Asian Manufacturing Footprint | Thailand or Vietnam assembly capacity captures Indian and ASEAN residential air conditioning penetration with tariff-advantaged supply. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with compressor OEM procurement directors, cold chain logistics fleet managers, data center cooling engineers, and HVAC-R wholesale distribution executives. Secondary validation drew from EPA SNAP program filings, EU F-Gas Regulation compliance databases, Indian Bureau of Energy Efficiency labeling records, and customs trade data for compressor and component flows. Bottom-up unit shipment estimates by product type and technology tier were triangulated against top-down market value reconstruction from disclosed OEM revenue segments.
Calibration against historical efficiency standard adoption curves and refrigerant-phaseout implementation timelines anchored growth projections across the analysis window. Segmentation modeling incorporated product architecture, control technology, end-use application, and regional regulatory cluster dimensions. CAGRs were derived from slope analysis of replacement cycle compression and penetration rate saturation curves, with specific inputs including Kigali Amendment phasedown schedules and utility demand-response program expansion trajectories.
Stress conditions across rare earth supply disruption, refrigerant-certification timeline slippage, and inverter control intellectual property litigation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding efficiency standard convergence and cold chain infrastructure investment continuity. Quarterly review of Indian BEE labeling tier migrations, EU F-Gas quota auction prices, and hyperscale data center capex announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
US Commercial Water Heater Market
HVAC Equipment
Global Tubular Heating Elements Market
HVAC Equipment
Asia-Pacific Industrial Heat Pump Market
HVAC Equipment
India Chillers Market
HVAC Equipment
Commercial RAC PD Compressor Market
HVAC Equipment
Middle East and Africa Commercial HVAC Market
HVAC Equipment
Global Split Systems Market
HVAC Equipment
Water Softener Equipment Market
HVAC Equipment
Linear Slot Diffuser Market
HVAC Equipment
Commercial Refrigeration Compressor Market
HVAC Equipment
Global Smart Vent Market
HVAC Equipment
Canada Outdoor Air Source Heat Pump Market
HVAC Equipment
Industrial Heating Equipment Market
HVAC Equipment
Europe Hydronic Radiators Market
HVAC Equipment
Europe Air to Water Heat Pump Market
HVAC Equipment
Steam Operated Condensate Pump Market