
 Combustion Controls, Equipments and Systems Market | 2026-2036
Combustion Controls, Equipments and Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Combustion Controls, Equipments and Systems Market Intelligence
The scarcity of technicians with dual expertise in process automation and data analytics is reorganizing service models for industrial combustion systems. This skills gap creates opportunities for vendors offering comprehensive lifecycle support and remote monitoring services. Siemens AG leverages its extensive digital twin and simulation software to support complex installations. Honeywell International Inc. specializes in integrated burner management systems for critical safety applications. ABB Ltd. competes on the strength of its advanced process automation platforms for large-scale industrial clients.
Combustion controls, equipment, and systems encompass a suite of hardware and software designed to manage fuel-burning processes. These systems precisely regulate the air-to-fuel ratio, ensuring complete combustion to maximize thermal efficiency and minimize pollutant formation. Their primary purpose is to enable safe, reliable, and compliant operation of boilers, furnaces, and turbines. Burner management systems represent a critical, high-margin product category due to their safety-centric function. The adoption of Programmable Logic Controllers (PLCs) is displacing older analog controls, particularly within the chemical processing application.
Regulatory frameworks established by the US Environmental Protection Agency (EPA) and the European Union's Industrial Emissions Directive mandate stringent limits on NOx and SOx emissions. In parallel, China's Ministry of Ecology and Environment (MEE) enforces efficiency standards as part of its national energy conservation policies. These rules directly shape product design and investment cycles for end-users. System integrators and asset owners must now decide between upgrading existing infrastructure with new controls or investing in entirely new, digitally native combustion platforms.
Market Dynamics
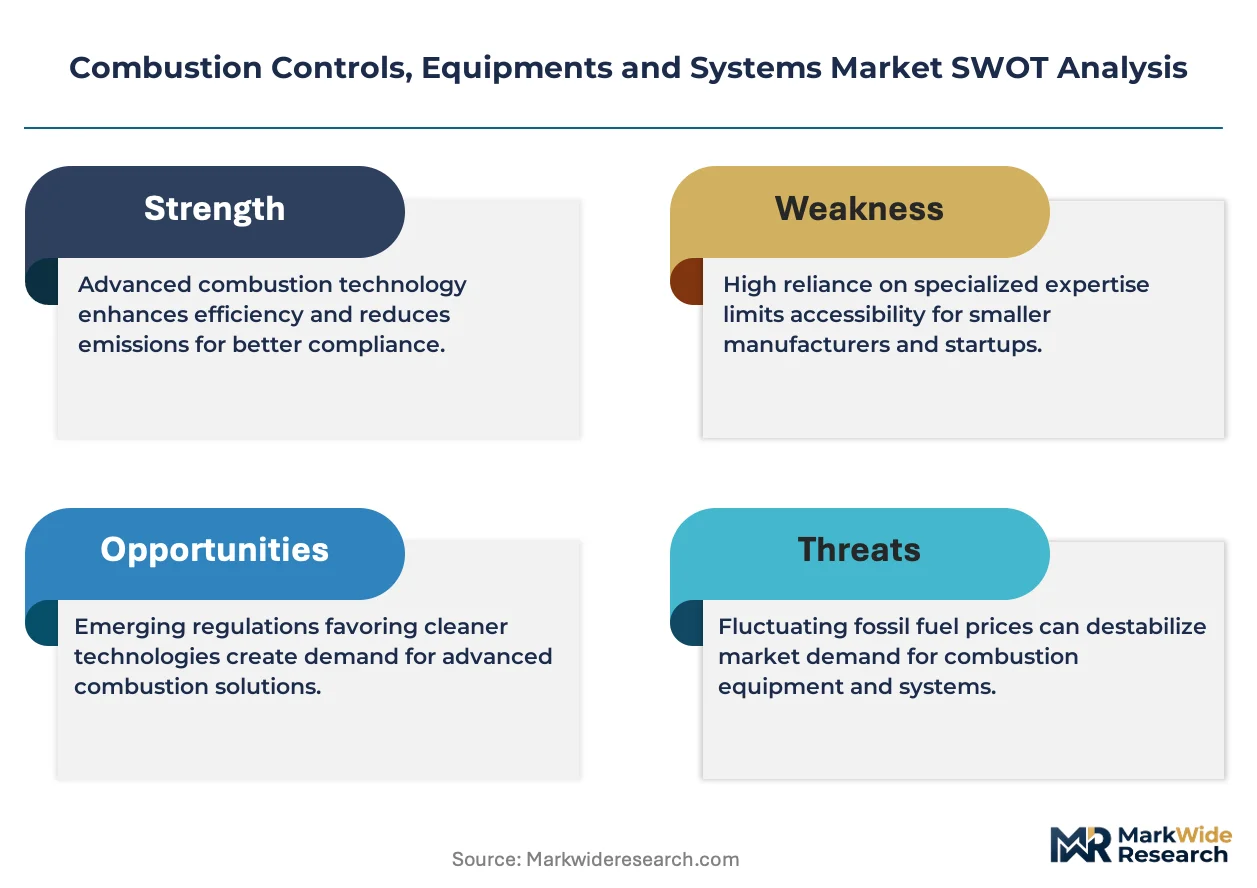
The imperative to reduce industrial emissions while maximizing thermal efficiency is the central force shaping the combustion controls market. This pressure stems from a global convergence of stringent environmental regulations, including mandates from the EPA and China's MEE, which directly influence technology investment decisions.
Growth Catalysts
- Emissions Regulations:The EU Green Deal and similar frameworks are compelling operators in power generation and chemical processing to upgrade or replace legacy systems to meet stricter NOx and SOx limits.
- Industrial Modernization:National programs, particularly China's dual carbon goals for heavy industry, are driving large-scale investment in modern, efficient combustion equipment to reduce energy intensity and environmental impact.
- Safety Mandates:The critical function of burner management systems in preventing industrial accidents sustains high-margin demand, especially in applications requiring certified safety integrity levels (SIL).
Market Restraints
- High Capital Costs:The significant upfront investment required for new, digitally native combustion platforms or comprehensive retrofits of existing furnaces and boilers can be prohibitive for some asset owners.
- Integration Complexity:Integrating modern PLC-based controls with older, proprietary plant infrastructure presents substantial technical hurdles and can lead to extended downtime during installation.
- Skills Gap:A structural scarcity of technicians with combined expertise in traditional combustion engineering, process automation, and modern data analytics limits the speed of deployment and support.
Strategic Opportunities
- Digital Twin Services:Offering simulation and digital twin software allows vendors to support complex installations remotely, model performance improvements, and train operators before commissioning.
- Predictive Maintenance:The convergence of IoT sensors with control systems creates an opportunity to provide data-driven, subscription-based services for predictive maintenance and remote troubleshooting.
- Modular Systems for SMEs:Developing scalable, pre-engineered combustion control packages can address the needs of smaller industrial operators in sectors like food processing and textiles who lack extensive in-house engineering teams.
Industry Challenges
- Legacy System Interoperability:A primary operational challenge is ensuring new digital controls can communicate effectively with a diverse array of existing legacy equipment from multiple manufacturers within a single plant.
- Talent Acquisition and Training:The industry faces persistent difficulty in recruiting and retaining personnel who possess the dual skill set of process control and data analytics required for modern service models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combustion Controls, Equipments and Systems Market |
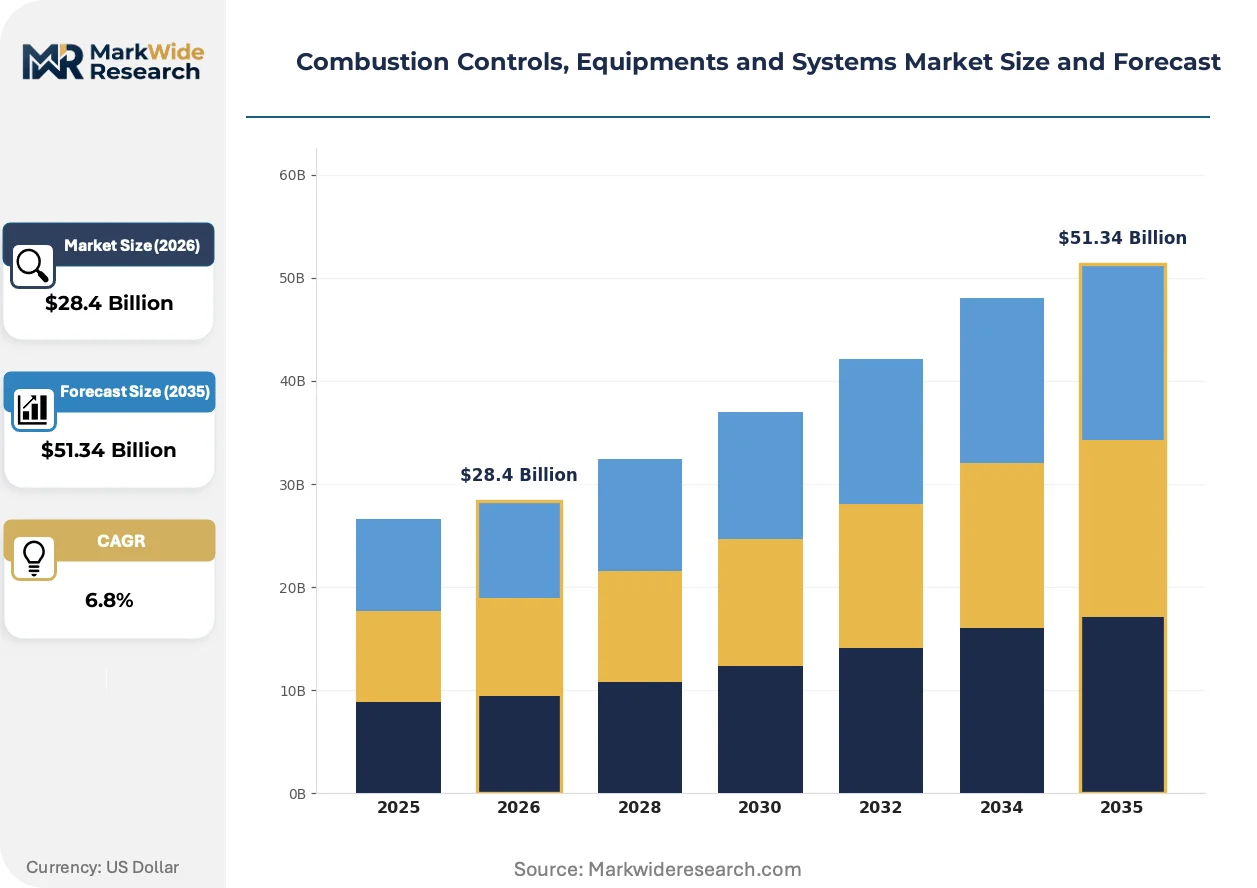
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $51.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Combustion Controllers, Flame Detectors, Gas Analyzers, Burner Management Systems, Oxygen Sensors Technology: PID Control, Feedback Control, Programmable Logic Controllers, Digital Control Systems, Zone Control Application: Power Generation, Metal Processing, Chemical Processing, Food & Beverage, Waste Management End User: Energy Producers, Metallurgical Firms, Chemical Manufacturers, Food Processing Plants, Environmental Services |
| Companies Covered | Siemens AG, Honeywell International Inc., ABB Ltd., Schneider Electric SE, General Electric, Emerson Electric Co., Alfa Laval AB, Yokogawa Electric Corporation, Rockwell Automation Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combustion Controls, Equipments and Systems Market Strategic Shifts & Innovations
A shift from discrete hardware sales toward integrated, software-defined systems is redefining value in the combustion controls market. This evolution prioritizes data-driven optimization, remote management capabilities, and full lifecycle support, responding directly to both regulatory pressures and operational demands for greater efficiency.
Programmable Logic Controllers (PLCs) provide modular, software-configurable automation for managing fuel-burning processes. End-users in the chemical processing and power generation sectors are rapidly adopting these systems to replace outdated equipment. The superior flexibility, diagnostics, and data-logging capabilities of PLCs are displacing older, inflexible analog and relay-based control panels across industrial applications.
The European Union's Industrial Emissions Directive establishes strict pollutant limits for large combustion plants. This regulation compels facility operators to invest in advanced burner controls and continuous emissions monitoring systems to prove compliance. The power generation and heavy industrial sectors are most affected, facing accelerated investment cycles for either retrofitting existing assets or undertaking complete system replacements.
End-users are increasingly procuring comprehensive lifecycle support services bundled with equipment, rather than purchasing standalone hardware. This model shifts the focus to outcome-based contracts that include remote monitoring, predictive analytics, and performance guarantees, often fulfilled by the original equipment vendor. This service-centric approach is most visible in North America and Europe, where it helps asset owners mitigate the impact of skilled technician shortages.
Combustion Controls, Equipments and Systems Market Segmentation
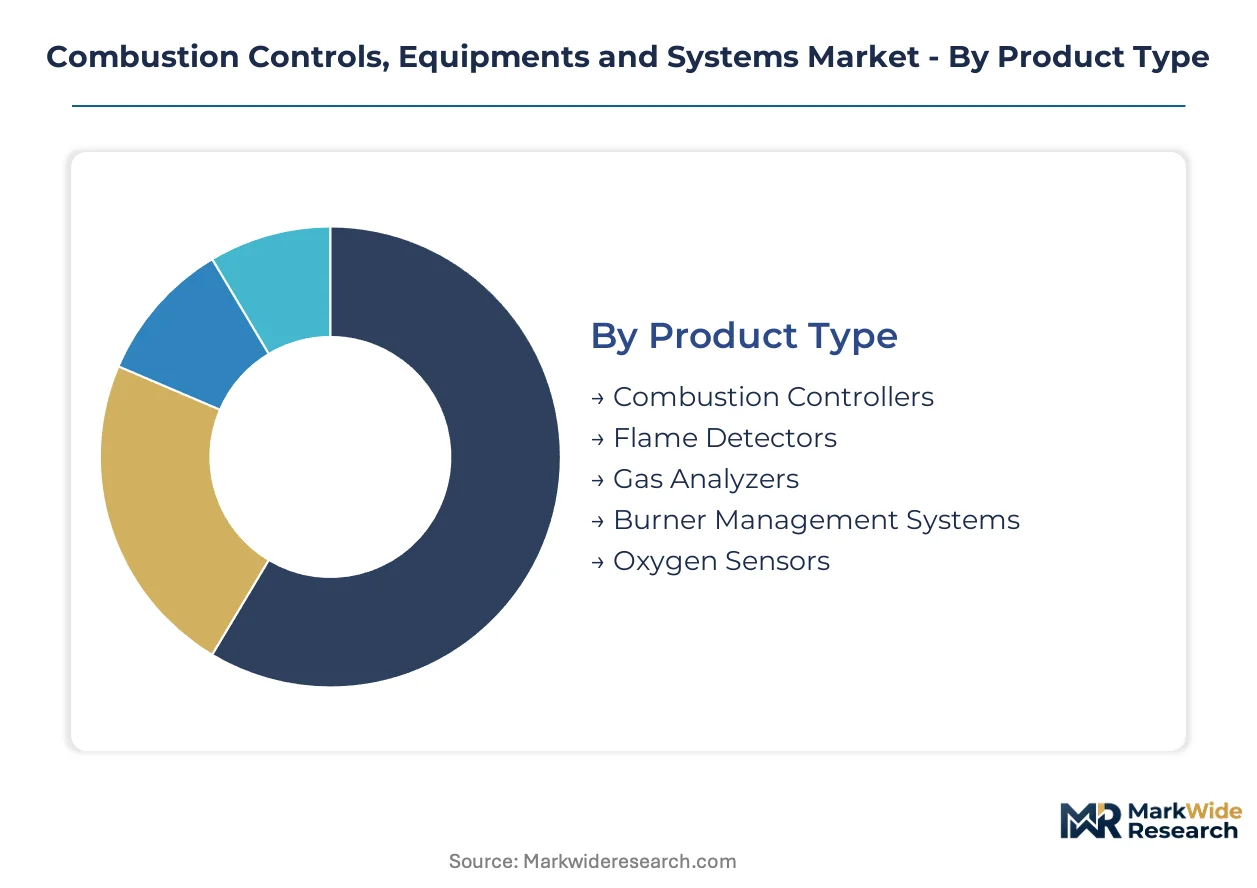
Understanding the Combustion Controls, Equipments and Systems Market through segmentation reveals distinct product functionalities and technological advancements. This analysis identifies critical applications and end-user demands influencing market dynamics. Segmenting the market provides clarity on where innovation and investment are most concentrated.
Product Type:
Product type segmentation often reveals regional preferences, with certain controls seeing higher adoption in mature markets while others gain traction in industrializing economies.
- Burner Management Systems:Critical for safety, preventing explosions and ensuring reliable operation in industrial furnaces and boilers. Demand concentrates in the power generation sector due to stringent safety mandates and high-value assets.
- Combustion Controllers:These systems precisely regulate air-to-fuel ratios, optimizing thermal efficiency and minimizing pollutant emissions. European industrial facilities prioritize these controllers for compliance with strict environmental regulations.
- Flame Detectors:Essential safety devices verifying the presence of a flame in burners, crucial across diverse industrial applications.
- Gas Analyzers:These instruments monitor exhaust gases to measure emissions and combustion efficiency, supporting environmental compliance.
- Oxygen Sensors:Used to measure oxygen levels in flue gases, enabling precise air-fuel ratio adjustments for optimal combustion.
Burner Management Systems commands the established base. The steepest expansion runs through Combustion Controllers.
Technology:
Technological advancements drive both cost efficiencies and performance gains, with newer digital solutions often offering superior capabilities over traditional analog methods.
- Programmable Logic Controllers:PLCs offer modular, software-configurable automation for complex fuel-burning processes, displacing older analog controls. Chemical processing applications in China are rapidly adopting these systems for modernization.
- Digital Control Systems:These integrated platforms provide advanced diagnostics, data logging, and remote management features for combustion processes. North American power plants increasingly deploy these systems for enhanced operational visibility and efficiency.
- Feedback Control:This method continuously adjusts combustion parameters based on real-time sensor data, maintaining optimal conditions.
- PID Control:Proportional-Integral-Derivative controllers provide precise and stable regulation of combustion variables like temperature and pressure.
- Zone Control:This technology manages combustion parameters independently across different sections of a large furnace or boiler.
Traditional PID Control maintains a significant installed base. Programmable Logic Controllers are gaining share fastest due to their flexibility.
Application:
Market applications vary widely, reflecting diverse operational requirements and regulatory pressures across different industrial sectors.
- Power Generation:This sector utilizes combustion controls for boilers and turbines to maximize efficiency and meet stringent emissions regulations. Demand in India and Southeast Asia is driven by new plant constructions and upgrades.
- Chemical Processing:Combustion systems are critical for heating and reaction processes, requiring precise control for safety and product quality. European chemical manufacturers prioritize advanced controls for emissions compliance and operational stability.
- Metal Processing:Furnaces and kilns in this industry rely on combustion controls for temperature accuracy and energy efficiency.
- Food & Beverage:This sector uses combustion equipment for heating, drying, and sterilization processes, demanding hygienic and reliable controls.
- Waste Management:Incinerators and waste-to-energy plants employ combustion controls to manage thermal processes and minimize harmful emissions.
Power Generation applications continue to drive substantial market volume. Chemical Processing is seeing the most rapid expansion in advanced control adoption.
End User:
End-user segments exhibit distinct purchasing behaviors and service requirements, influencing vendor strategies for product development and support.
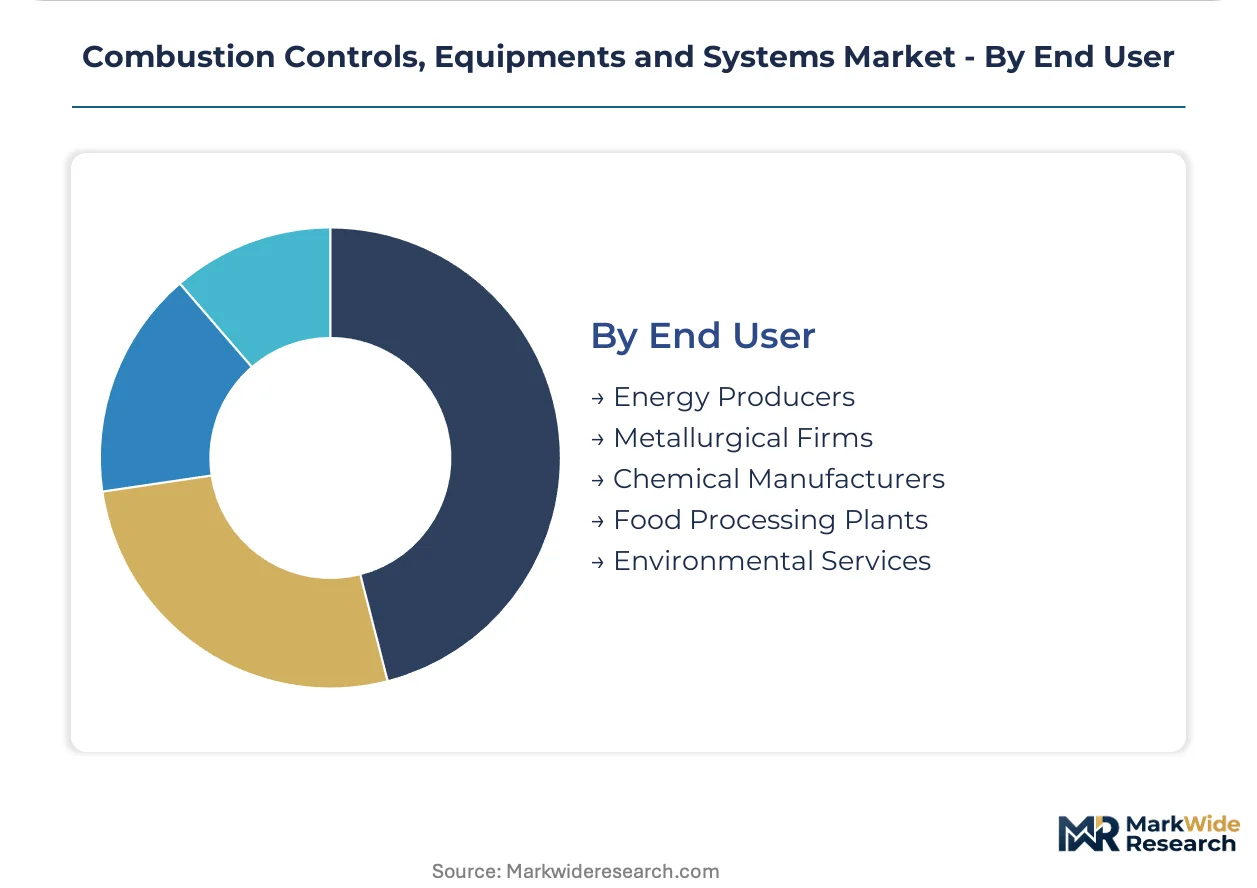
- Energy Producers:These companies, including utilities and independent power producers, invest in combustion controls for operational reliability, efficiency, and environmental compliance. US energy producers are upgrading to digital platforms for grid stability and emissions reduction.
- Chemical Manufacturers:Chemical plants require highly precise and safe combustion control systems for their complex processes. German chemical firms prioritize integrated solutions to meet both production quality and environmental standards.
- Metallurgical Firms:Steel mills and foundries utilize robust combustion controls for high-temperature processes like smelting and heat treatment.
- Food Processing Plants:These facilities use combustion equipment for various heating applications, demanding hygienic and energy-efficient control solutions.
- Environmental Services:Companies involved in waste-to-energy and emissions control deploy specialized combustion systems for their operations.
Energy Producers represent the largest customer base for combustion controls. Chemical Manufacturers are exhibiting the most dynamic growth in advanced system integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for combustion controls, equipment, and systems varies significantly by geography, reflecting differing industrial maturity and regulatory priorities. China's market is driven by large-scale industrial modernization, contrasting with European demand centered on stringent environmental compliance upgrades.
China
Industrial modernization programs and national dual carbon goals drive robust demand for advanced combustion controls. Heavy industries require efficient systems to reduce energy intensity and meet MEE efficiency standards. The Yangtze River Delta region, a major manufacturing hub, sees significant investment in digitally native combustion platforms.
Germany
European chemical manufacturers and power generation facilities prioritize advanced controls for emissions compliance and operational stability. The EU Green Deal and Industrial Emissions Directive compel operators to invest in sophisticated burner controls. The Ruhr industrial area is a focal point for retrofitting existing plants with advanced process automation.
United States
Energy producers and chemical processing plants are upgrading to digital platforms for enhanced operational visibility and efficiency. US EPA regulations mandate stringent limits on NOx and SOx emissions, influencing technology investment decisions. The Gulf Coast industrial corridor experiences high demand for integrated burner management systems in critical safety applications.
India
New power plant constructions and industrial expansion projects are driving substantial market volume in India. The Central Electricity Authority (CEA) enforces efficiency standards for thermal power plants. Gujarat's rapidly industrializing zones are adopting modern combustion equipment to meet growing energy demand and improve process control.
Combustion Controls, Equipments and Systems Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the combustion controls, equipment, and systems market. This tiered structure reflects the capital intensity of developing comprehensive platforms versus niche component manufacturing. Strategic archetypes include full-suite automation providers, specialized safety system manufacturers, and regional system integrators. Competitive moves often involve strategic partnerships to bridge technology gaps or targeted acquisitions to expand geographic reach.
Within the integrated solutions archetype, Siemens AG and Honeywell International Inc. represent established global players offering extensive digital twin and simulation software capabilities. These companies provide comprehensive lifecycle support and integrated burner management systems for critical safety applications. ABB Ltd. also occupies a strong position, specializing in advanced process automation platforms for large-scale industrial clients, anchoring the premium segment for complex installations.
| Leading Market Players |
|---|
| Siemens AG |
| Honeywell International Inc. |
| ABB Ltd. |
| Schneider Electric SE |
| General Electric |
| Emerson Electric Co. |
| Alfa Laval AB |
| Yokogawa Electric Corporation |
| Rockwell Automation Inc. |
| Others |
Cost & Logistics Intelligence
Extended lead times for specialized PLC components directly influence procurement strategies and vendor pricing power, particularly for integrated systems. This dynamic shapes how asset owners approach upgrades and new installations, often balancing immediate cost against long-term operational reliability.
Pricing Analysis
Project-based pricing models dominate for complex integrated combustion control systems, reflecting the high customization and engineering effort involved. Price differentiation stems from the level of safety certification (e.g., SIL levels) and the breadth of after-sales service bundles offered by vendors. Pricing softness is observed in standard component sales due to increasing competition from regional manufacturers, particularly in Asia. Smaller industrial operators in sectors like food processing exhibit higher price sensitivity compared to power generation clients who prioritize performance and reliability.
Supply Chain Analysis
Strategic stockpiling of critical components, such as microcontrollers and specialized sensors, helps mitigate supply chain disruptions in this market. Geographic supply concentration for basic PLC manufacturing centers in China, while Germany and the United States lead in advanced control systems. The market draws from specialized sensors and high-temperature alloys as essential inputs. Single-source vulnerability for highly specialized safety-certified components presents a structural risk. Distribution runs through specialized system integrators and direct sales channels from major original equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents an early-cycle expansion story, driven by the rapid penetration of PLC-based systems in chemical processing and power generation applications.
For Market Incumbents:Consolidate market share by acquiring smaller, specialized software firms offering data analytics or digital twin capabilities. This strategy addresses the emerging threat of commoditized hardware from Asian manufacturers. Invest heavily in R&D for AI-driven predictive maintenance platforms to maintain technological leadership. Deepen vertical integration into proprietary sensor technology to uphold performance differentiation and intellectual property.
For New Entrants and Emerging Players:UL and CE certification fast-track programs offer a pathway for new entrants to validate safety-critical burner management systems. Smaller industrial operators in food processing and textiles represent a penetrable segment, lacking extensive in-house engineering teams. Focus on modular, pre-engineered combustion control packages with subscription-based remote monitoring services. Address the skills gap by offering comprehensive installation and ongoing support as a go-to-market angle.
For Investors and Strategic Acquirers:Carve-out targets emerge from large industrial conglomerates divesting non-core combustion control divisions. The market demonstrates long-term viability over a 5-10 year window, driven by continuous regulatory updates and industrial modernization. Seek out mid-sized firms specializing in advanced process automation or integrated software platforms as acquisition archetypes. Increased merger and acquisition activity among system integrators signals market consolidation and maturation, serving as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates disparate control systems into unified, efficient operational frameworks. |
| Digital Twin Development | Enables remote performance optimization and reduces commissioning time for complex installations. |
| Service Model Expansion | Captures recurring revenue streams and addresses the industry's pervasive skills gap. |
| Geographic Expansion into China | Accesses a rapidly modernizing industrial base driven by national dual carbon goals. |
| Advanced Sensor R&D | Improves measurement precision for air-to-fuel ratios, directly enhancing efficiency and compliance. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation from public and proprietary sources. Primary insights were gathered from plant managers, process engineers, procurement leads, and regulatory compliance officers across key geographies. Secondary data included EPA emissions data, China's MEE policy documents, and corporate financial reports, with bottom-up data collection cross-referenced with top-down market sizing estimates.
The forecasting boundary spans the projection horizon, utilizing a robust analytical framework to model market dynamics. Segmentation dimensions modeled included product type, technology, application, end-user, and regional regulatory frameworks. Compound annual growth rates were derived from historical trends and projected future demand, incorporating key industry-specific forecast inputs such as industrial output indices and environmental regulatory updates.
Underlying assumptions cover stable energy prices and consistent regulatory enforcement, with deviation risk concentrated in geopolitical disruptions affecting supply chains or sudden shifts in environmental policy. Revision becomes warranted when major industrial output changes or new emissions mandates cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Screw Compressor Market
HVAC Equipment
Centrifugal Blower Market
HVAC Equipment
China Residential Heat Pump Market
HVAC Equipment
HVAC Airflow and Blend Door Actuator Systems Market
HVAC Equipment
United States HVAC Equipment and Services Market
HVAC Equipment
Air-Conditioning Natural Convection Refrigerator Market
HVAC Equipment
Commercial Refrigeration Compressor Market
HVAC Equipment
Commercial RAC PD Compressor Market
HVAC Equipment
Global Air Curtain Market
HVAC Equipment
Wall Hung Boilers Market
HVAC Equipment
Industrial Condensing Units Market
HVAC Equipment
Warm Air Heater Market
HVAC Equipment
Europe HVAC Market
HVAC Equipment
Recirculating Chillers Market
HVAC Equipment
Residential Furnaces Market
HVAC Equipment
Air Conditioner Quilt Market