
 United States Heat Exchanger Market | 2026-2036
United States Heat Exchanger Market Size, Share, and Industry Trends Forecast 2026-2036
United States Heat Exchanger Market Intelligence
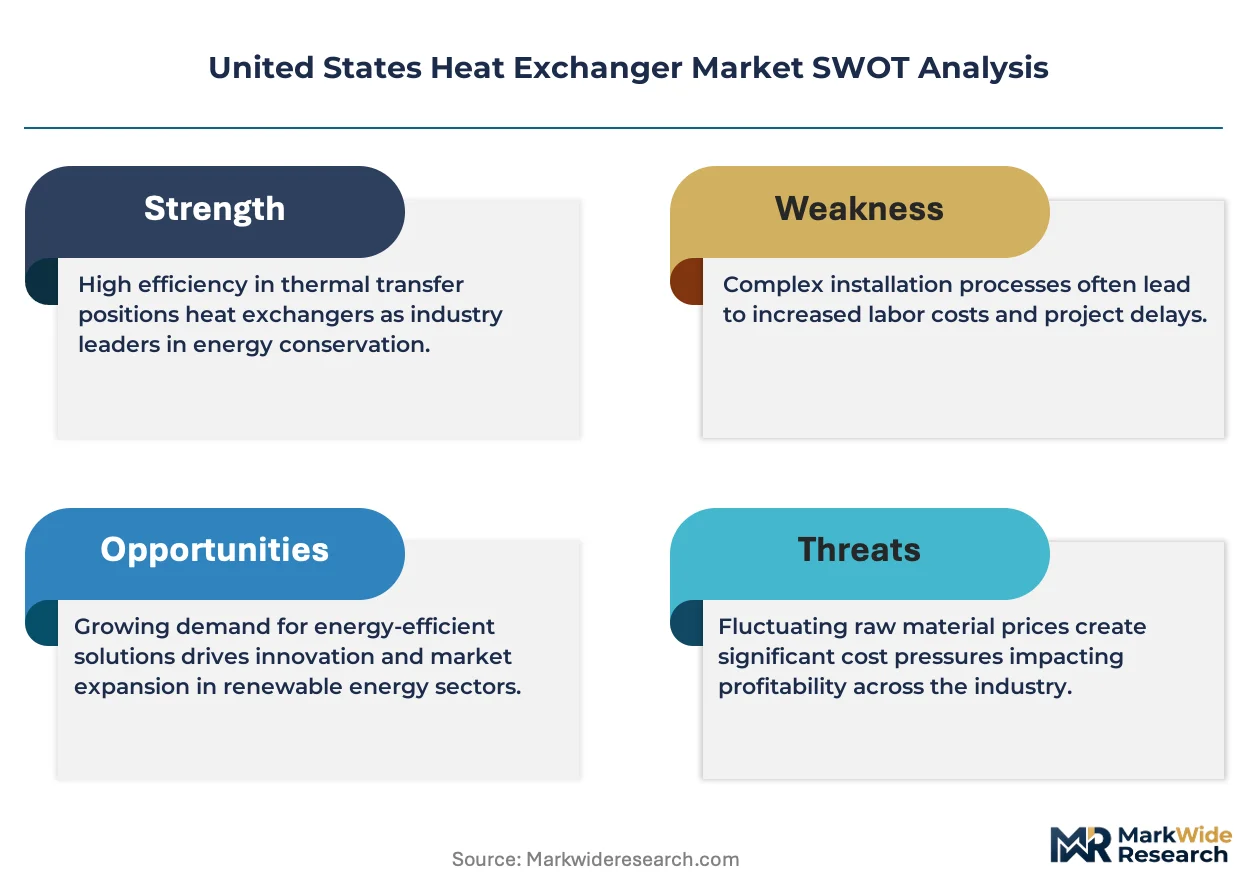
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is repositioning the cost-of-entry calculus for heat exchanger manufacturers serving the US market. Alfa Laval leverages its global plate heat exchanger portfolio to navigate tighter refrigerant compliance requirements. Koch Heat Transfer Company anchors its position through specialized shell-and-tube designs for high-pressure hydrocarbon service. Chart Industries differentiates via cryogenic heat exchanger expertise tied to booming LNG infrastructure.
A heat exchanger is a thermal transfer device that moves heat between two or more fluid streams at different temperatures, typically constructed from stainless steel, titanium, or nickel alloys with design pressures ranging from vacuum to over 1,000 bar and temperature spans from cryogenic to above 1,000 degrees Celsius. Its primary industrial purpose is energy recovery, process temperature control, and utility optimization across continuous-flow operations. Shell and tube configurations dominate heavy industrial applications where fouling tolerance and mechanical reliability outweigh capital cost, while plate designs capture expanding share in HVAC and data center cooling where footprint efficiency and close temperature approaches command premium positioning. Air cooled variants face structural headwinds in water-stressed regions but sustain niche dominance in remote oil and gas production.
FERC interstate pipeline safety standards, ASME Boiler and Pressure Vessel Code Section VIII, and state-level building efficiency codes collectively shape product certification burdens and procurement specifications across US end-use sectors. OSHA process safety management requirements for high-hazard facilities further tighten material traceability and welding qualification protocols. Stakeholders must monitor how the Department of Energy's evolving appliance efficiency standards and emerging carbon border adjustments reshape competitive positioning between domestic fabrication and imported equipment.
Market Dynamics
The EPA's phasedown of hydrofluorocarbon refrigerants under the AIM Act is forcing heat exchanger manufacturers to redesign equipment around lower-global-warming-potential working fluids, compressing development timelines and repositioning competitive advantage toward thermal engineering expertise.
Growth Catalysts
- LNG Export Terminal Buildouts:Texas Gulf Coast petrochemical cluster expansions require massive cryogenic heat transfer infrastructure for liquefaction trains and regasification facilities.
- AIM Act Compliance Pressure:The EPA's hydrofluorocarbon phasedown mandates equipment redesigns that favor compact plate heat exchangers with optimized refrigerant charge volumes.
- Data Center Cooling Density:Hyperscale computing deployments in Northern Virginia and Phoenix are procuring close-approach plate designs for liquid cooling loops.
Market Restraints
- Nickel Alloy Price Volatility:Hastelloy and Inconel input costs for high-temperature service swing with mining supply disruptions and trade policy uncertainty.
- Domestic Fabrication Concentration:ASME-certified pressure vessel shops cluster in Texas, Louisiana, and Oklahoma, creating geographic supply bottlenecks during project surges.
- Refrigerant Transition Friction:The AIM Act's stepped reduction schedule forces parallel inventory management for legacy HFC and emerging A2L mildly flammable alternatives.
Strategic Opportunities
- Hydrogen Economy Infrastructure:Gulf Coast hydrogen hub investments require specialized heat exchangers for electrolysis thermal management and high-pressure gas conditioning.
- Carbon Capture Integration:Post-combustion amine scrubbing installations at Texas and Louisiana refineries create demand for corrosion-resistant compact designs.
- State Efficiency Mandates:California Title 24 building energy standards and New York Local Law 97 carbon caps accelerate replacement cycles in commercial HVAC.
Industry Challenges
- ASME Section IX Welder Qualification:Specialized orbital welding for titanium and zirconium tubes faces certification backlogs at third-party inspection agencies.
- Legacy System Integration:Brownfield petrochemical sites require custom spool piece fabrication to interface plate heat exchangers with existing shell-and-tube footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Heat Exchanger Market |
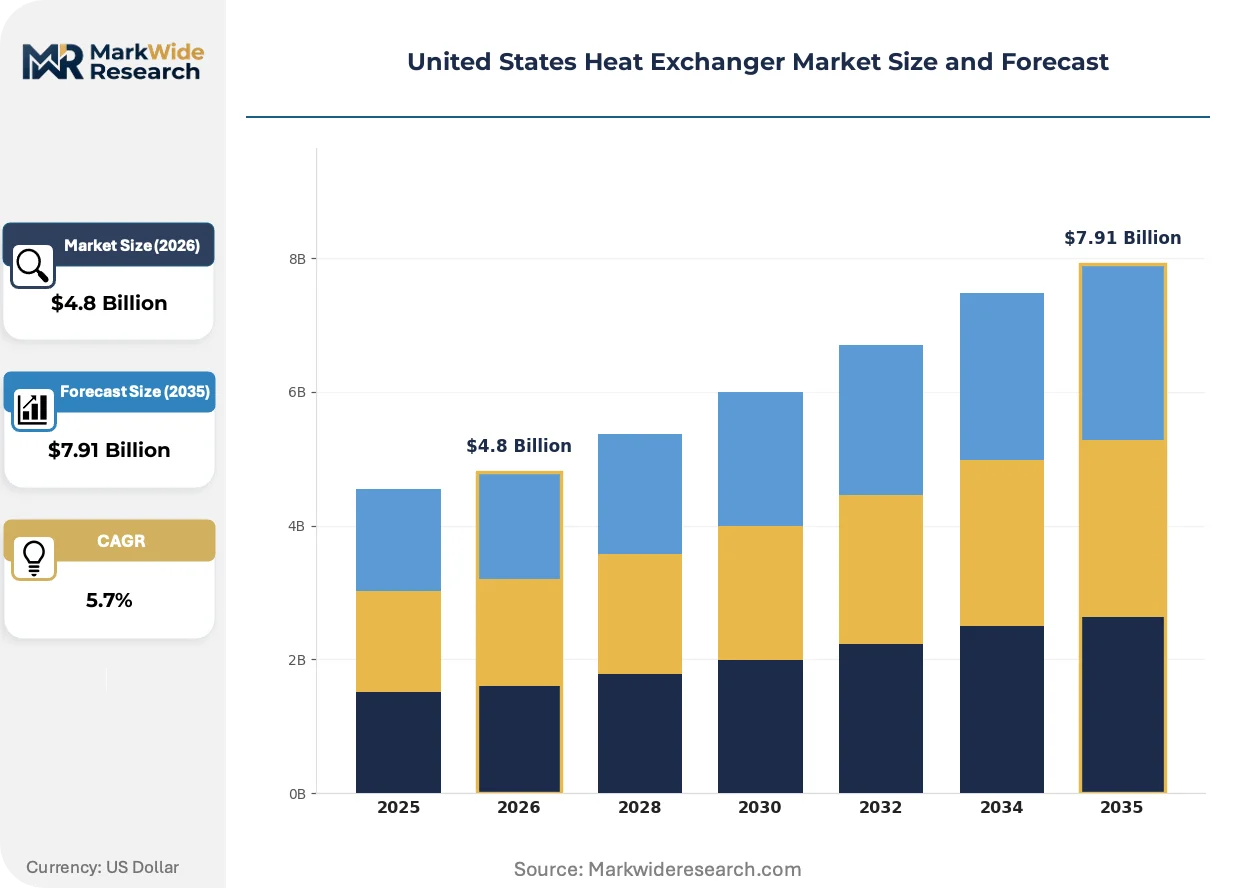
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shell and Tube, Plate, Air Cooled, Double Pipe Application: Power Generation, HVAC Systems, Chemical Processing, Oil & Gas End User: Industrial, Commercial, Residential, Institutional Technology: Direct Contact, Electrical, Thermal, Spiral |
| Companies Covered | Alfa Laval, Chart Industries, Koch Heat Transfer Company, API Heat Transfer, Kelvion Holding GmbH, Xylem, Mersen, SHECO Industries, Johnson Controls International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Heat Exchanger Market Strategic Shifts & Innovations
Additive manufacturing of heat exchanger cores is compressing prototyping cycles and enabling geometries impossible with conventional stamping or welding, particularly for aerospace and satellite thermal management applications.
Printed circuit heat exchanger technology is electrifying deployment in supercritical CO2 power cycles and concentrated solar thermal plants. Southwest Research Institute and Oak Ridge National Laboratory are validating diffusion-bonded microchannel designs for 700°C service. The technology is electrifying market entry for equipment suppliers previously excluded from high-temperature energy recovery.
The EPA's Significant New Alternatives Policy program is accelerating refrigerant approvals for hydrofluoroolefins and hydrocarbon blends. Equipment manufacturers must recertify pressure ratings and material compatibility for each new fluid chemistry. The commercial HVAC and supermarket refrigeration segments are responding fastest, with Texas and Florida utilities offering efficiency rebates for early A2L adoption.
Equipment-as-a-service contracting is displacing capital purchase in data center and district cooling applications. Trane and Carrier are unbundling hardware from performance guarantees, absorbing operational risk for temperature reliability and energy efficiency. The model is most visible in Northern Virginia's Ashburn-Loudoun corridor, where hyperscalers prefer opex treatment for mechanical infrastructure.
United States Heat Exchanger Market Segmentation
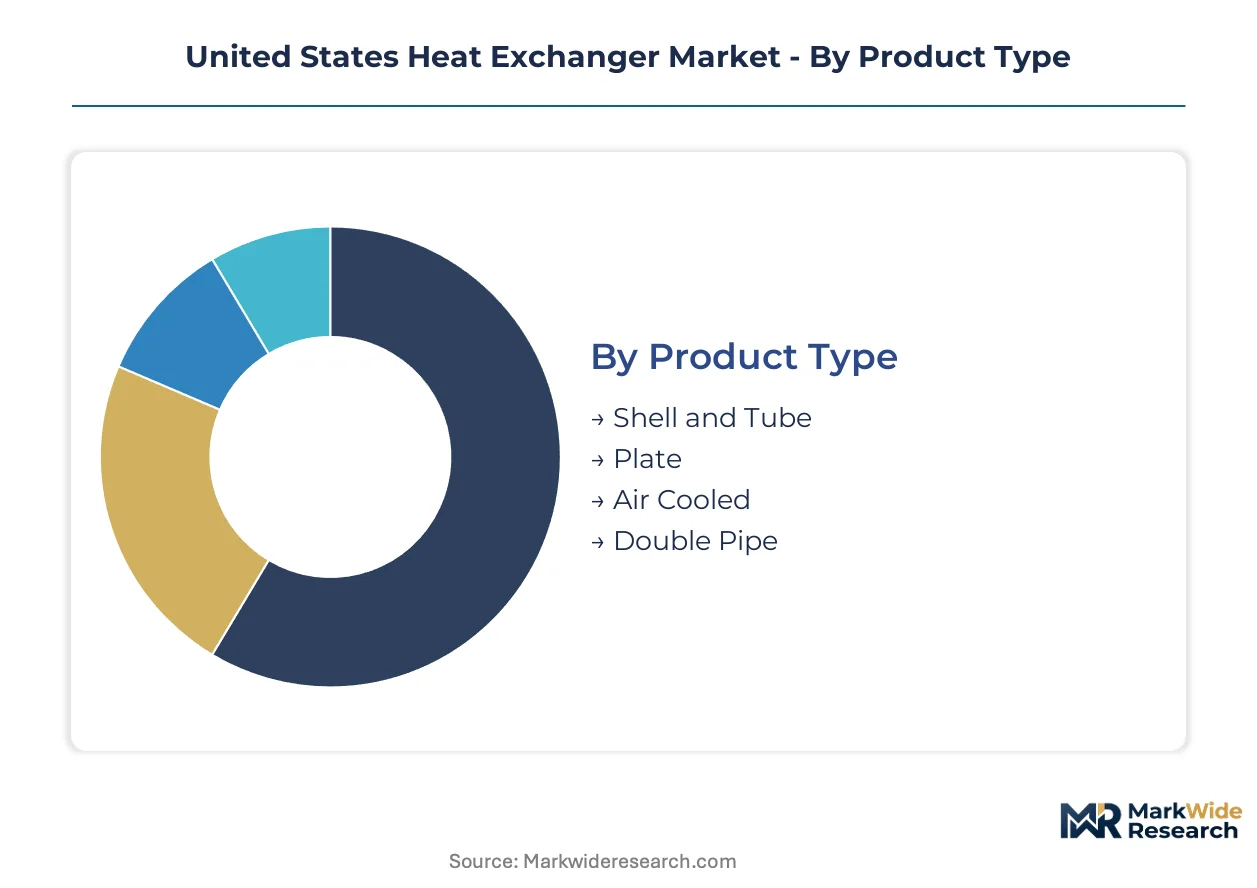
Heat exchanger procurement specifications diverge sharply across pressure ratings, temperature envelopes, and fouling tolerance requirements. Equipment selection cascades through material grade, configuration geometry, and certification tier, creating distinct commercial lanes with minimal cross-shopping.
Product Type:
Standardization dominates at the commodity end, while engineered-to-order configurations command premium positioning for severe service conditions.
- Shell and Tube:Cylindrical pressure vessels containing tube bundles welded to tube sheets, rated for 1,000+ bar and 600°C service. Petrochemical clusters along the Texas Gulf Coast specify these for high-pressure hydrocarbon processing where mechanical reliability outweighs footprint penalties. ASME Section VIII certification requirements extend lead times but lock in incumbent fabricators.
- Plate:Corrugated metal plates stacked and sealed with gaskets or brazed joints, enabling 1°C approach temperatures in compact footprints. Data center liquid cooling loops in Northern Virginia and Phoenix are standardizing on brazed aluminum variants for hyperscale deployments. The AIM Act refrigerant phasedown accelerates adoption by minimizing working fluid charge volumes.
- Air Cooled:Finned-tube bundles forced-air cooled, eliminating water consumption. Remote Permian Basin oil production facilities specify these where water access is constrained. Thermal efficiency penalties limit penetration in humid Gulf Coast climates.
- Double Pipe:Concentric tube-in-tube construction for low-flow, high-temperature differential service. Small-scale chemical processors in Ohio and Pennsylvania deploy these for pilot plant operations where capital constraints preclude shell-and-tube investment.
Most installed capacity flows through Shell and Tube. Expansion is steepest in Plate.
Application:
End-use intensity maps directly to regional industrial base concentration and infrastructure replacement cycles.
- Power Generation:Feedwater heaters, condensers, and cooling tower interfaces for combined-cycle gas turbines and legacy coal plants. Texas ERCOT grid operators are retrofitting air-cooled condensers to reduce water withdrawal permits. Efficiency mandates from FERC and state PUCs drive replacement demand.
- HVAC Systems:Chiller evaporators and condensers, district heating substations, and building heat recovery. California Title 24 and New York Local Law 97 are accelerating commercial building retrofit cycles. A2L refrigerant transition is forcing equipment replacement ahead of mechanical failure.
- Chemical Processing:Reactor temperature control, distillation overhead condensers, and solvent recovery systems. Louisiana and Texas Gulf Coast petrochemical expansions require corrosion-resistant alloys for acid gas service.
- Oil & Gas:Wellhead heaters, gas processing dew point control, and LNG liquefaction trains. Corpus Christi and Sabine Pass LNG export terminals are procuring cryogenic aluminum heat exchangers in multi-year supply agreements.
Power Generation retains the largest installed base. HVAC Systems are climbing the fastest as building efficiency mandates tighten.
End User:
Procurement sophistication scales with technical staff depth and maintenance infrastructure availability.
- Industrial:Continuous-process manufacturers with in-house reliability engineering and predictive maintenance programs. Refineries and chemical plants specify API 660 and API 661 compliance as baseline procurement filters.
- Commercial:Property managers and facility operators prioritizing energy cost reduction over capital efficiency. Equipment-as-a-service contracting is displacing purchase in district cooling and large-format retail.
- Residential:Single-family and multifamily building stock served through HVAC contractor distribution. Product selection is brand-driven with minimal technical differentiation visible to end purchasers.
- Institutional:Universities, hospitals, and government facilities with extended hold periods and sustainability procurement mandates. Federal GSA schedules and state cooperative purchasing agreements concentrate vendor selection.
Industrial users command the highest specification density. Commercial is gaining share fastest through performance contracting models.
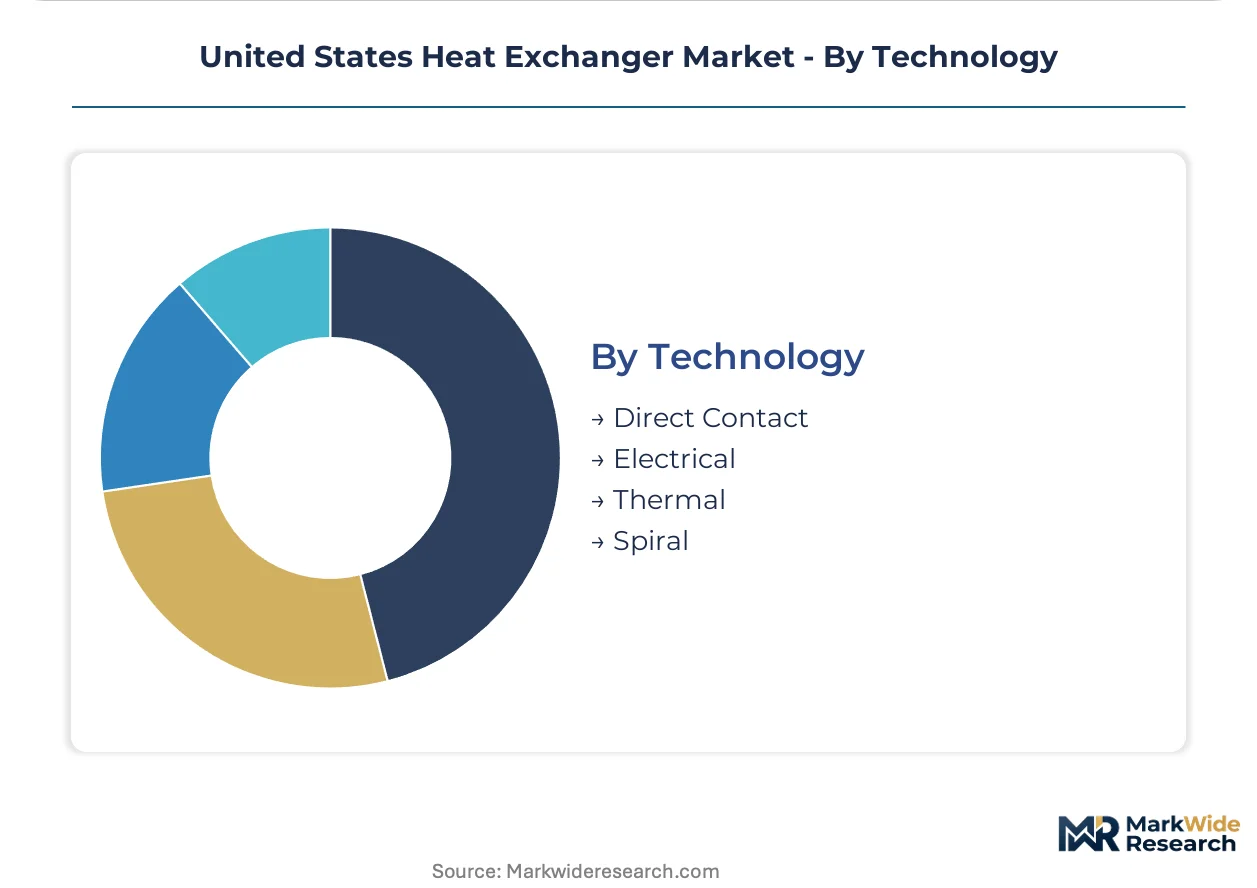
Technology:
Technology selection trades thermal efficiency against pressure containment complexity and maintenance accessibility.
- Direct Contact:Fluids mix directly without intervening heat transfer surface, achieving theoretical maximum efficiency. Geothermal power plants in Nevada and California deploy these for brine preheating where fluid compatibility permits commingling.
- Electrical:Thermoelectric and electrohydrodynamic enhancement for specialized aerospace and satellite thermal management. NASA and defense contractors fund development through SBIR pathways.
- Thermal:Conventional conduction-convection designs comprising the commercial mainstream. Regenerative and recuperative variants capture waste heat in steel mills and cement kilns.
- Spiral:Welded spiral channel construction for slurry and high-fouling service. Pulp and paper mills in the Pacific Northwest and Southeast specify these for black liquor recovery where conventional plate designs would clog.
Thermal technology carries the largest installed footprint. Spiral designs are expanding most quickly in high-fouling process applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Welding-certified fabricators and pressure vessel engineers concentrate along the Gulf Coast, anchoring domestic production capacity for high-specification thermal equipment.
Texas Gulf Coast
Petrochemical cluster expansions in Corpus Christi and Baytown drive procurement of shell-and-tube designs for high-pressure hydrocarbon service. EPA AIM Act refrigerant regulations accelerate plate heat exchanger adoption to minimize working fluid volumes. LNG export terminals at Sabine Pass and Freeport execute multi-year supply agreements for cryogenic aluminum heat exchangers.
Louisiana Industrial Corridor
Refinery and chemical plant retrofits demand corrosion-resistant alloys for acid gas and sour water service. OSHA process safety management requirements tighten material traceability protocols for ASME Section VIII certification. Baton Rouge and Lake Charles fabrication shops face capacity constraints during turnaround seasons.
California
Data center liquid cooling deployments in Silicon Valley and Central Valley hyperscale facilities standardize on compact plate designs. Title 24 building energy standards mandate heat recovery equipment in commercial HVAC retrofits. Sacramento and Los Angeles municipal utilities administer rebate programs for A2L refrigerant system conversions.
Northern Virginia
Ashburn-Loudoun corridor hyperscalers procure close-approach plate heat exchangers for direct liquid cooling loops. FERC interstate pipeline safety standards govern thermal management for auxiliary power systems. Equipment-as-a-service contracting displaces capital purchase for mechanical infrastructure.
Ohio River Valley
Pilot plant operations and specialty chemical processors deploy double-pipe configurations for low-flow, high-temperature differential service. State building efficiency codes in Ohio and Pennsylvania accelerate replacement cycles in institutional facilities. Cleveland and Pittsburgh fabrication shops serve brownfield integration projects.
United States Heat Exchanger Market Key Industry Players
The competitive structure tilts toward diversified industrial conglomerates with integrated thermal engineering capabilities. Three archetypes dominate: global heat transfer specialists with refrigerant-transition expertise, cryogenic equipment providers tethered to LNG infrastructure cycles, and diversified industrial conglomerates leveraging HVAC distribution networks. Capacity expansion and strategic partnerships represent the dominant competitive vectors as fabricators seek ASME certification coverage across multiple pressure vessel shops.
Among the named participants, Alfa Laval represents the global specialist archetype with plate heat exchanger portfolio breadth. Chart Industries exemplifies cryogenic-focused positioning tied to liquefaction train demand. Koch Heat Transfer Company occupies a position within the specialized fabricator tier serving high-pressure hydrocarbon applications. These three anchors illustrate how regulatory pressure on refrigerant chemistry and LNG export terminal buildouts reshape competitive positioning across distinct capability clusters.
| Leading Market Players |
|---|
| Alfa Laval |
| Chart Industries |
| Koch Heat Transfer Company |
| API Heat Transfer |
| Kelvion Holding GmbH |
| Xylem |
| Mersen |
| SHECO Industries |
| Johnson Controls International |
| Others |
Cost & Logistics Intelligence
ASME certification tiers split the market into divergent commercial lanes where Section VIII-stamped fabricators command project premiums while non-certified shops compete on speed for low-pressure service. This bifurcation concentrates supply in Texas, Louisiana, and Oklahoma fabrication corridors while pricing power accumulates with incumbent holders of pressure vessel qualifications.
Pricing Analysis
Equipment-as-a-service contracting unbundles hardware from performance guarantees in data center and district cooling applications. Pricing stratifies across premium, standard, and economy tiers based on ASME certification grade and alloy specification. Cost compression in commodity plate designs intensifies due to Chinese import competition. Commercial facility operators exhibit highest price sensitivity while Gulf Coast petrochemical buyers prioritize mechanical reliability over capital cost.
Supply Chain Analysis
Refurbishment flows for shell-and-tube bundles create secondary supply channels that compete with new equipment in turnaround seasons. Domestic production draws from nickel alloy feedstock anchored in Canada and Australia, with titanium sheet sourced from Japan and Russia. Tariff exposure on Chinese brazed aluminum plate assemblies creates single-source vulnerability for data center cooling deployments. Distribution runs through OEM-direct project contracting for industrial accounts and HVAC wholesaler networks for commercial replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where refrigerant transition mandates and LNG infrastructure cycles favor premium thermal engineering capabilities over commodity fabrication.
For Market Incumbents: Extend ASME certification coverage across multiple pressure vessel shops to capture turnaround surge demand. Deepen backward integration into nickel alloy distribution to buffer Hastelloy and Inconel price volatility. Consolidate regional fabrication capacity before emerging entrants acquire distressed Gulf Coast assets. For New Entrants and Emerging Players: Begin with hydrogen economy infrastructure applications where specification standards remain unsettled and incumbent certification advantages matter less. Target carbon capture integration projects at Texas and Louisiana refineries for first commercial reference. Pursue joint development agreements with electrolyzer OEMs to embed heat exchanger designs early in project specifications. For Investors and Strategic Acquirers: Consolidation pressure builds where ASME Section IX welder qualification backlogs constrain expansion capacity for mid-tier fabricators. Five-to-ten year viability favors specialists with refrigerant-transition engineering depth over commodity plate assemblers. Watch EPA Significant New Alternatives Policy refrigerant approval velocity as inflection indicator for equipment replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| ASME Certification Expansion | Section VIII coverage unlocks Gulf Coast petrochemical procurement specifications. |
| Refrigerant-Compatible Design Investment | A2L and hydrofluoroolefin readiness secures EPA AIM Act compliance positioning. |
| LNG Cryogenic Partnership | Multi-year supply agreements with liquefaction train developers anchor revenue visibility. |
| Equipment-as-a-Service Launch | Performance contracting absorbs operational risk for hyperscale data center operators. |
| Additive Manufacturing Pilot | Diffusion-bonded microchannel prototypes validate 700°C service for concentrated solar applications. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork captured perspectives from plant engineers at Gulf Coast petrochemical facilities, procurement leads at LNG terminal developers, HVAC contractor distributors, aftermarket service heads, and thermal engineering directors at hyperscale data center operators. Secondary validation drew from FERC interstate pipeline filings, EPA refrigerant phasedown schedules, ASME Boiler and Pressure Vessel Code documentation, and EIA industrial energy consumption surveys. Bottom-up equipment shipment tallies and top-down end-use demand estimates were cross-referenced for triangulation.
Comparable historical periods anchored the projection framework across the analysis window. Segmentation modeling tracked product type, application intensity, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for technology substitution effects and policy implementation timelines. Forecast inputs incorporated nickel alloy price volatility indices and EPA refrigerant approval velocity assumptions.
Several conditions sit outside the modeled scope, including geopolitical disruption to titanium supply routes and unanticipated acceleration of AIM Act phasedown schedules. Forecasts reflect assumptions about LNG export terminal construction timelines and data center power density trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Canada Commercial HVAC Market
HVAC Equipment
Recirculating Chillers Market
HVAC Equipment
HVAC Chillers Market
HVAC Equipment
HVAC Air Duct Market
HVAC Equipment
Global HVAC Packaged Unit Market
HVAC Equipment
Global Industrial Air Chiller Market
HVAC Equipment
Italy Commercial HVAC Market
HVAC Equipment
Global Submerged Coil Heat Exchanger Market
HVAC Equipment
Compact Fan Coils Market
HVAC Equipment
Japan Commercial HVAC Market
HVAC Equipment
Desert Air Cooler Market
HVAC Equipment
Global Split Systems Market
HVAC Equipment
HVAC Air Quality Monitoring Market
HVAC Equipment
Europe Residential Fan Coil Convectors Market
HVAC Equipment
Germany HVAC Market
HVAC Equipment
Global Variable Refrigerant Flow (VRF) Market