
 India Residential Heat Pump Market | 2026-2036
India Residential Heat Pump Market Size, Share, and Industry Trends Forecast 2026-2036
India Residential Heat Pump Market Insights
BIS certification under IS 2082 for electrical storage water heaters is collapsing the vendor landscape, eliminating uncertified imports and sub-scale fabricators. Daikin Airconditioning India Pvt. Ltd. leverages its inverter compressor technology from commercial HVAC to dominate premium residential heat pump segments. Ariston Thermo India Pvt. Ltd. sustains a dedicated heat pump manufacturing footprint near Pune, anchoring its position in the western India market. Havells competes through its extensive electrician and plumber distribution network, controlling last-mile installation capacity that rivals struggle to replicate.
India residential heat pumps transfer thermal energy from ambient air, ground, or water sources to heat domestic water or interior spaces using vapor-compression refrigeration cycles with coefficient of performance ratings typically between 2.5 and 4.0. These systems displace direct electric resistance heating and reduce household energy consumption for thermal comfort applications. Air source products lead volume due to lower installation complexity and minimal site preparation, though ground source installations command premium pricing where bore drilling feasibility permits. Variable speed technology is gaining fastest among technology segments because inverter-driven compressors match output to partial-load conditions prevalent in Indian climates with narrow diurnal temperature swings.
BIS mandates product safety and efficiency testing, while the Bureau of Energy Efficiency (BEE) star labeling program shapes consumer purchase decisions through operating cost transparency. State nodal agencies under the Ministry of New and Renewable Energy administer residential solar-thermal and heat pump subsidies that vary by implementation capacity. The Central Electricity Authority (CEA) grid integration standards for distributed heating loads will determine whether utilities treat residential heat pump clusters as manageable demand or as peak-shaving challenges requiring tariff redesign. Stakeholders must monitor how BEE tightens minimum energy performance standards and whether state renewable purchase obligations expand to cover residential thermal electrification.
Market Dynamics
Variable speed compressor technology is bifurcating the India residential heat pump market, compressing fixed-speed margins while inverter-equipped systems capture premium installation contracts in Maharashtra and Gujarat apartment developments.
Growth Catalysts
- Maharashtra renewable energy mandates:State nodal agencies under the Ministry of New and Renewable Energy administer subsidies that accelerate air-source heat pump adoption in multi-unit residential buildings across Mumbai and Pune.
- IS 2082 BIS certification:The Bureau of Indian Standards mandate for electrical storage water heaters eliminates uncertified imports and consolidates demand around tested domestic suppliers.
- Variable speed technology:Inverter-driven compressors match output to partial-load conditions prevalent in Indian climates with narrow diurnal temperature swings, reducing operating costs for end-users.
Market Restraints
- Copper coil input volatility:Heat pump manufacturing depends on copper pricing that fluctuates with global commodity markets, compressing fabrication margins during supply tightness.
- Western India supplier concentration:Manufacturing clusters near Pune and Ahmedabad create geographic vulnerability to regional logistics disruptions or state-level policy variations.
- Ground source technical limitation:Bore drilling feasibility constraints restrict geothermal installations to peri-urban plots with sufficient land availability, limiting addressable market expansion.
Strategic Opportunities
- Tamil Nadu and Karnataka underpenetration:Southern states lack equivalent renewable purchase obligations for residential thermal electrification, creating first-mover expansion territory for certified suppliers.
- Solar-thermal convergence:Hybrid systems combining photovoltaic generation with heat pump water heating reduce grid dependency and align with Ministry of New and Renewable Energy distributed energy goals.
- Electrician-plumber channel innovation:Last-mile installation capacity controlled through dedicated technician networks creates defensible distribution moats beyond traditional appliance retail.
Industry Challenges
- Refrigerant handling certification gap:Technician training for vapor-compression system installation and maintenance lags behind equipment deployment rates, creating service backlogs in Delhi and Mumbai.
- BIS testing timeline compression:Certification backlog at Bureau of Indian Standards laboratories extends product launch cycles, disadvantaging smaller fabricators against established testing relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Residential Heat Pump Market |
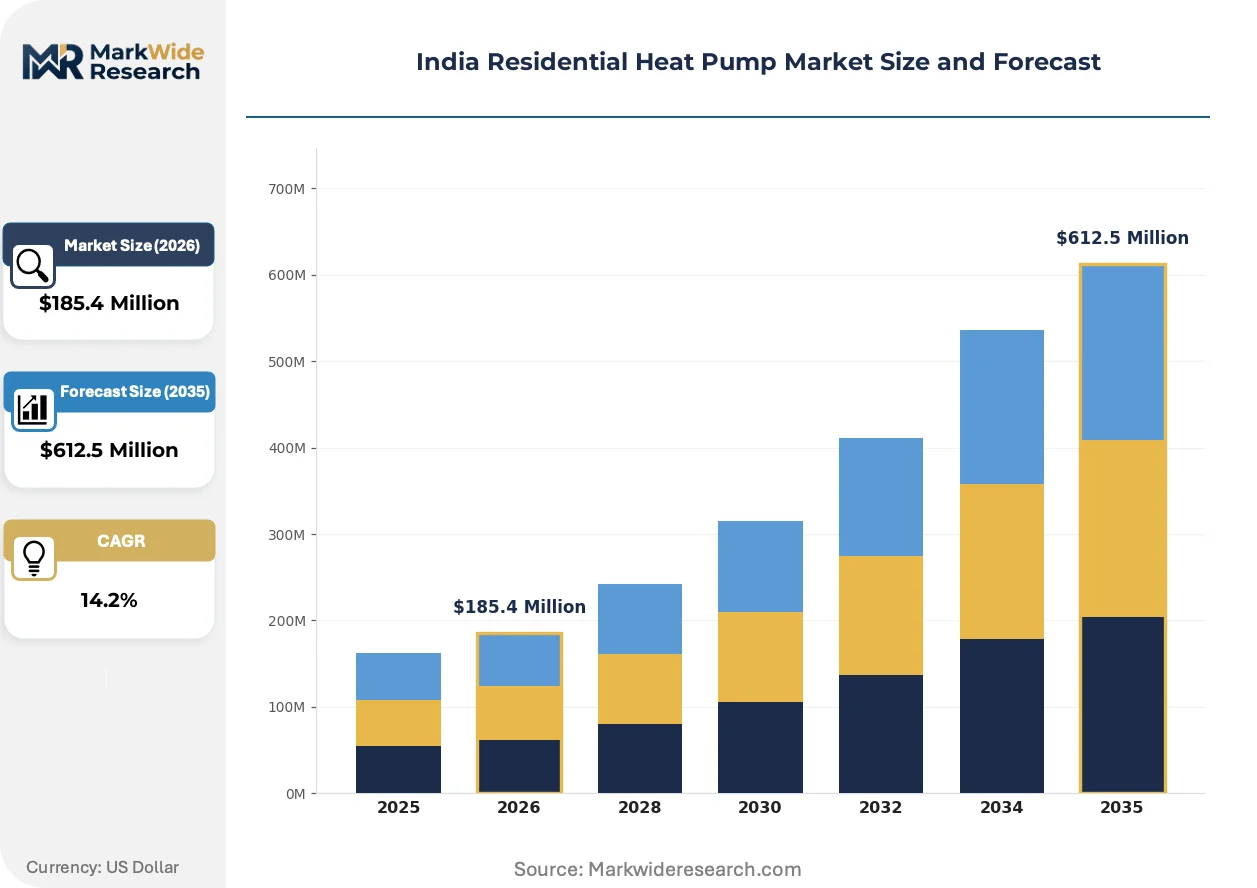
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $612.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Source, Ground Source, Hybrid, Water Source Technology: Reverse Cycle, Thermoelectric, Variable Speed, Direct Expansion Installation Type: New Construction, Retrofit, Commercial Standards, Residential Standards Application: Space Heating, Water Heating, Pool Heating, Cooling |
| Companies Covered | Ariston Thermo India Pvt. Ltd., Racold, Daikin Airconditioning India Pvt. Ltd., LG Electronics India, Havells, V-Guard, Stiebel Eltron, Flamingo Heat Pumps, A. O. Smith India Water Products Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Residential Heat Pump Market Trends and Innovations
Technological specialization and regulatory tightening are actively restructuring competitive advantage in India residential heat pumps, favoring suppliers with integrated manufacturing and certification capabilities.
Variable speed compressor technology is bifurcating the product landscape. Inverter-driven systems modulate thermal output to match partial-load demand patterns common in Indian residential climates. Premium apartment developers in Mumbai and Delhi specify these units for centralized water heating installations. Fixed-speed equipment is compressing into price-sensitive replacement markets and rural single-family applications.
Bureau of Energy Efficiency star labeling revisions are tightening minimum energy performance standards for electrical heating appliances. The program shapes consumer purchase decisions through operating cost transparency displayed at point-of-sale. Tier-1 suppliers with established testing relationships at BEE-recognized laboratories accelerate compliance ahead of smaller competitors.
Certification-driven preference formation is altering channel dynamics. Electricians and plumbers increasingly specify BIS-certified equipment to avoid liability exposure from substandard installations. This behavior concentrates procurement authority with trade contractors rather than end consumers, particularly in Gujarat and Maharashtra where state renewable mandates elevate compliance scrutiny.
India Residential Heat Pump Market Segmentation
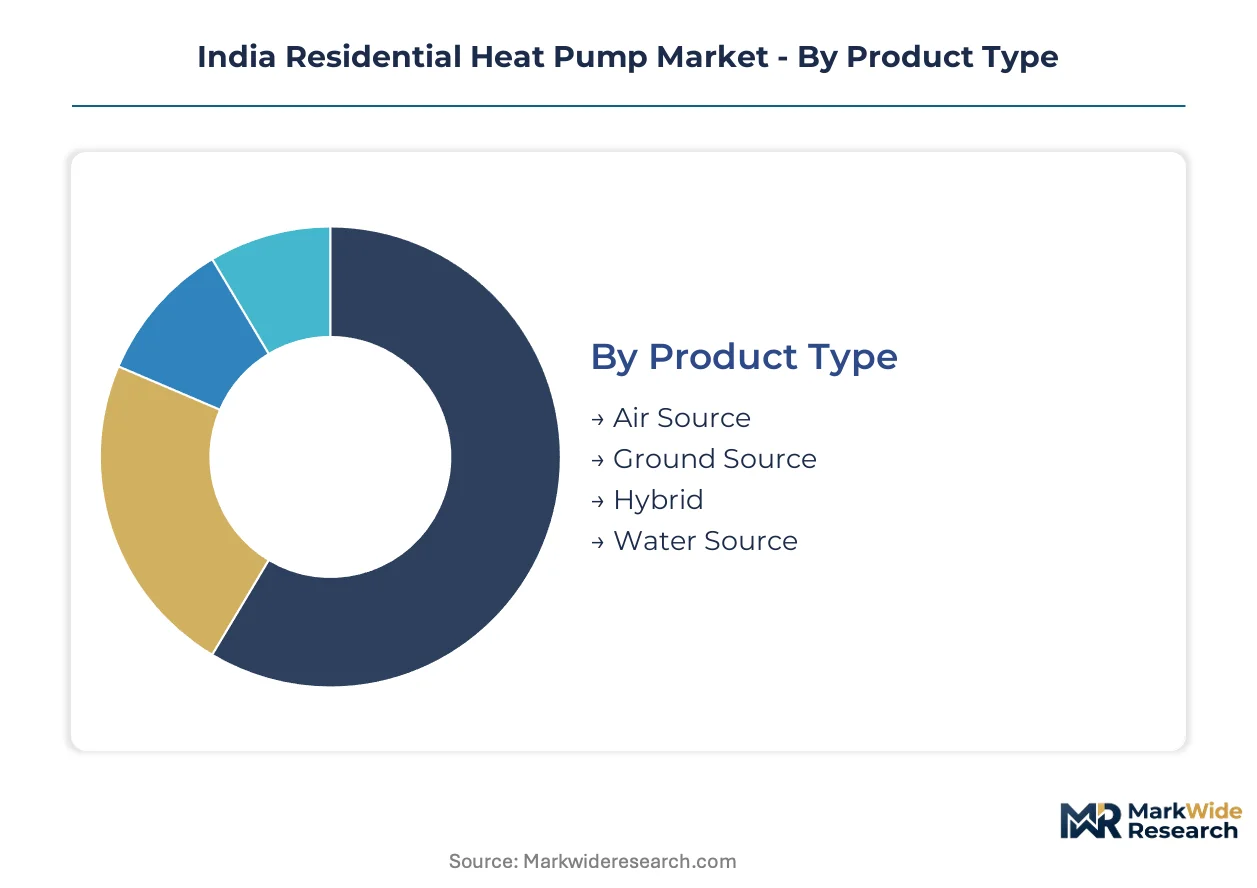
Segmentation in the India residential heat pump market reveals how technology choices and installation contexts reshape procurement patterns across Maharashtra, Gujarat, and emerging southern states. Understanding these divides exposes where BIS certification requirements and state renewable mandates concentrate commercial activity.
Product Type:
Domestic demand concentrates in air-source systems, while ground-source and hybrid categories serve niche peri-urban developments with specific site conditions.
- Air Source:These systems extract thermal energy from ambient air using vapor-compression cycles with coefficient of performance ratings between 2.5 and 4.0. Apartment complexes in Mumbai and Delhi specify centralized air-source installations for domestic water heating, driven by lower capital costs and minimal site preparation requirements compared to alternatives.
- Ground Source:Bore drilling-dependent geothermal systems command premium pricing where peri-urban land availability permits vertical loop field installation. Gujarat and Maharashtra peri-urban developments with sufficient plot sizes represent the primary addressable base, constrained by geological feasibility and upfront capital intensity.
- Hybrid:Solar-thermal convergence systems combine photovoltaic generation with heat pump water heating to reduce grid dependency. These configurations align with Ministry of New and Renewable Energy distributed energy goals but require higher technical integration at installation.
- Water Source:Surface water or well-dependent systems serve lakeside and coastal residential clusters where ambient water temperature stability improves efficiency. Limited deployment concentrates in Kerala and coastal Karnataka where water access permits.
Air Source holds the largest share; momentum sits with Hybrid configurations as solar-thermal convergence gains policy support.
Technology:
Cost tiers separate mature fixed-output systems from inverter-equipped premium offerings that capture Maharashtra and Gujarat apartment contracts.
- Variable Speed:Inverter-driven compressors modulate thermal output to match partial-load demand patterns prevalent in Indian climates with narrow diurnal temperature swings. Premium developers in Mumbai and Pune specify these units for centralized installations, accepting higher capital costs for operating cost reduction.
- Reverse Cycle:Standard vapor-compression systems provide both heating and cooling through refrigerant flow reversal. These dominate replacement markets and price-sensitive rural single-family applications where installation simplicity outweighs efficiency optimization.
- Thermoelectric:Solid-state heat pumping using Peltier effects serves small-capacity point-of-use applications. Limited scale restricts deployment to auxiliary heating roles in high-end residential renovations.
- Direct Expansion:Refrigerant-to-air or refrigerant-to-water heat exchange systems eliminate secondary fluid loops. Simplified architecture reduces installation labor but limits capacity modulation flexibility compared to inverter alternatives.
Reverse Cycle dominates volume; Variable Speed is climbing the fastest as BEE star labeling tightens minimum performance standards.
Installation Type:
Application context splits between greenfield construction with integrated mechanical design and retrofit projects constrained by existing building infrastructure.
- New Construction:Greenfield residential developments incorporate heat pump sizing and distribution infrastructure during architectural design. Maharashtra and Gujarat multi-unit projects increasingly specify centralized systems to meet state renewable energy mandates for residential buildings.
- Retrofit:Existing building replacements of electric resistance or gas-fired heating systems face space constraints and electrical capacity limitations. Electrician-plumber channel relationships determine specification authority in this fragmented segment.
- Commercial Standards:Multi-unit residential buildings with centralized plant rooms require engineered systems meeting CEA grid integration standards for distributed heating loads. Compliance complexity favors established suppliers with testing relationships.
- Residential Standards:Single-family and small multi-family installations follow simplified BIS certification pathways. IS 2082 compliance requirements compress the supplier base toward certified domestic fabricators.
New Construction commands premium pricing; Retrofit represents the deepest volume pool as replacement cycles accelerate.
Application:
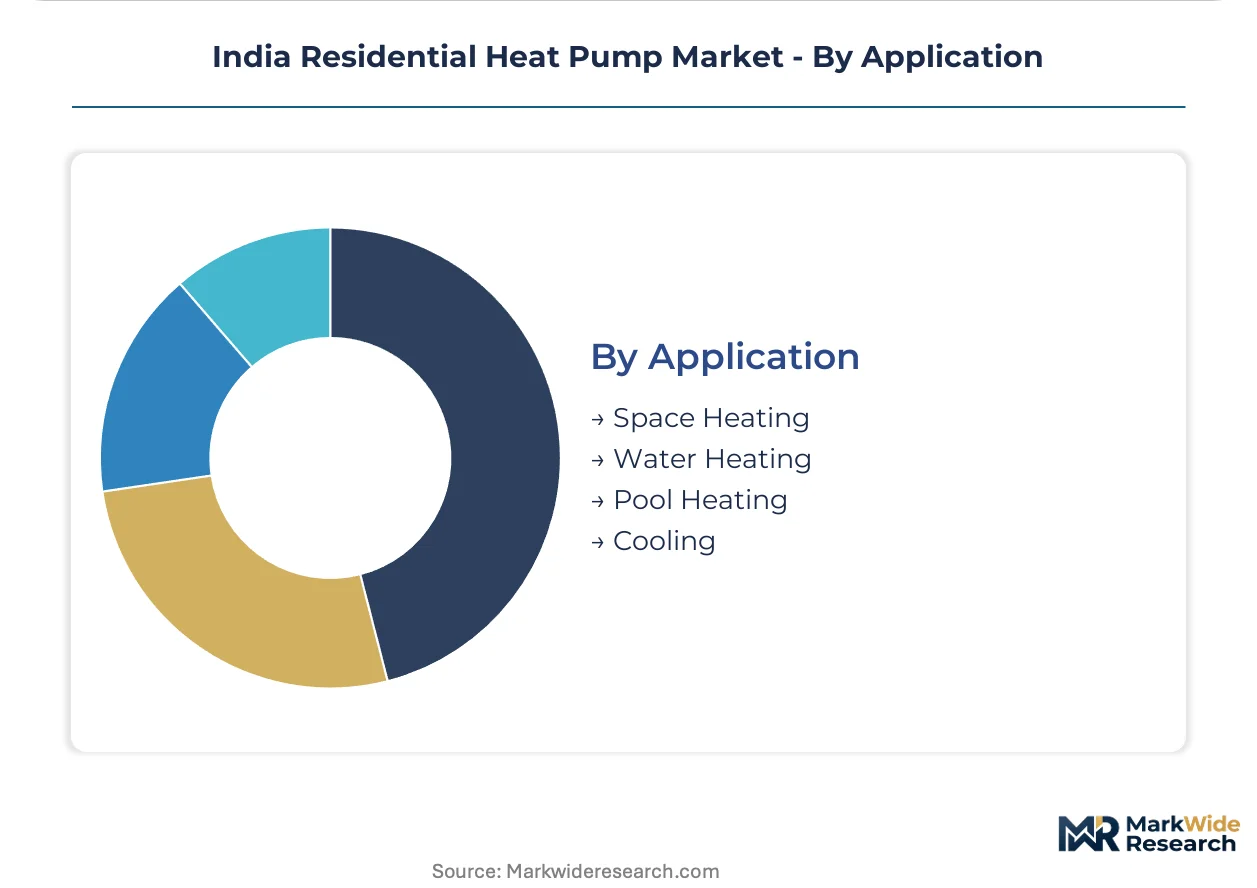
End-use concentration varies by climate zone, with water heating dominating tropical and subtropical regions while space heating gains traction in northern hill states.
- Water Heating:Domestic hot water production constitutes the primary residential heat pump application across Indian climates. Centralized systems in Mumbai and Delhi apartment complexes displace electric resistance storage heaters, driven by operating cost advantages and state-level renewable purchase obligations.
- Space Heating:Interior thermal comfort applications concentrate in northern states with winter heating requirements. Himachal Pradesh and Uttarakhand hill stations represent emerging demand pockets as electrification displaces fuelwood and kerosene heating.
- Cooling:Reverse-cycle operation provides air conditioning during cooling seasons. This dual-function capability improves capital efficiency justification in markets with both heating and cooling requirements.
- Pool Heating:Residential swimming pool thermal maintenance serves high-end villa developments in Goa, Kerala, and Hyderabad. Limited market depth restricts supplier attention to niche premium positioning.
Water Heating anchors revenue; Space Heating is expanding most quickly as northern hill states electrify thermal comfort.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level renewable energy mandates and BIS certification requirements are concentrating demand in western India while creating expansion corridors in underpenetrated southern markets.
Maharashtra
Mumbai and Pune apartment complexes specify centralized air-source systems for domestic water heating under state nodal agency subsidies. The Maharashtra Energy Development Agency administers residential thermal electrification incentives that compress procurement timelines. Manufacturing clusters near Pune anchor supplier presence for western India distribution.
Gujarat
Ahmedabad and Surat peri-urban developments with sufficient plot sizes represent the primary addressable base for ground-source installations constrained by geological feasibility. State renewable purchase obligations for residential buildings elevate compliance scrutiny among trade contractors. Fabrication capacity concentrates in manufacturing zones supplying both local projects and export markets.
Delhi-NCR
Centralized water heating installations in multi-unit residential buildings displace electric resistance storage heaters driven by operating cost advantages. Bureau of Energy Efficiency star labeling shapes consumer purchase decisions through operating cost transparency at point-of-sale. Refrigerant handling certification gaps create service backlogs that lag behind equipment deployment rates.
Karnataka
Bangalore residential developments lack equivalent renewable purchase obligations for thermal electrification, creating first-mover expansion territory for certified suppliers. State nodal agencies under the Ministry of New and Renewable Energy administer distributed energy programs with variable implementation capacity. Solar-thermal convergence systems align with distributed energy goals but require higher technical integration.
Tamil Nadu
Chennai and Coimbatore markets remain underpenetrated relative to western states, offering territory acquisition potential for suppliers with established BIS testing relationships. Coastal water temperature stability improves efficiency for surface water-dependent configurations in lakeside residential clusters. Electrician-plumber channel relationships determine specification authority in this fragmented retrofit segment.
India Residential Heat Pump Market Competitive Landscape
Player mix skews toward diversified HVAC conglomerates and dedicated water heating specialists with manufacturing footprints in western India. Market structure exhibits tiered consolidation around certification-compliant suppliers versus fragmented sub-scale fabricators facing BIS testing timeline compression. Strategic archetypes include inverter technology licensors, distribution network controllers, and integrated component manufacturers. Dominant competitive moves encompass backward integration into compressor sourcing and captive technician training networks.
Among diversified HVAC conglomerates, Daikin Airconditioning India Pvt. Ltd. and LG Electronics India exemplify technology transfer strategies from commercial refrigeration into residential heat pump segments. Ariston Thermo India Pvt. Ltd. occupies a position within the dedicated water heating specialist tier, anchoring western India manufacturing presence. Havells represents the distribution network control archetype through extensive electrician and plumber channel relationships that rivals struggle to replicate.
| Leading Market Players |
|---|
| Ariston Thermo India Pvt. Ltd. |
| Racold |
| Daikin Airconditioning India Pvt. Ltd. |
| LG Electronics India |
| Havells |
| V-Guard |
| Stiebel Eltron |
| Flamingo Heat Pumps |
| A. O. Smith India Water Products Pvt. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day copper coil inventory cycles at Pune fabrication clusters compress margin buffers when global commodity markets spike, concentrating pricing power with inverter-technology suppliers who command premium positioning in Maharashtra and Gujarat apartment developments.
Pricing Analysis
Certification level under BIS IS 2082 creates the primary spread between tier-1 and sub-scale suppliers. Three-tier pricing structure separates BEE 5-star inverter systems from fixed-speed standard offerings and uncertified economy imports. Cost compression in fixed-speed tiers is intensifying because copper volatility and BIS testing backlogs squeeze fabricator margins. Price-sensitive rural single-family replacement buyers drive volume at the economy tier, while premium developers in Mumbai and Delhi show least sensitivity to capital cost for centralized installations.
Supply Chain Analysis
China and Japan anchor compressor component sourcing for Indian heat pump assembly, with domestic coil winding and refrigerant charging operations concentrated near Pune and Ahmedabad. Manufacturing draws from copper cathode imports, inverter drive electronics, and synthetic refrigerant supplies. Single-source vulnerability in semiconductor-based compressor controllers creates exposure to Asia-Pacific logistics chokepoints. Distribution runs through dedicated electrician-plumber technician networks rather than traditional appliance retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across state-level renewable mandate implementation creates niche acquisition opportunities for suppliers with BIS certification relationships and western India manufacturing footprints.
For Market Incumbents: Secure captive technician training capacity to close the refrigerant handling certification gap that lags equipment deployment in Delhi and Mumbai. Deepen backward integration into inverter compressor sourcing to defend margins against copper volatility and component import dependency. BEE star labeling revisions represent the priority regulatory lever requiring accelerated testing relationships. For New Entrants and Emerging Players: Anchor in Tamil Nadu and Karnataka where renewable purchase obligations for residential thermal electrification remain underdeveloped relative to Maharashtra and Gujarat. Solar-thermal convergence configurations offer the most penetrable technology angle for first-mover positioning. Electrician-plumber channel partnerships provide the essential go-to-market structure in fragmented southern retrofit markets. For Investors and Strategic Acquirers: Long-term, this sits as a policy-elasticity play because state nodal agency subsidy administration and BEE standard tightening will determine competitive consolidation speed. Acquisition targets should display integrated BIS testing relationships and western India manufacturing presence. The signal to watch is CEA grid integration standard finalization for distributed heating load treatment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Sourcing | Reduces exposure to China-Japan component volatility and secures margin control. |
| Captive Technician Training Network | Closes refrigerant handling certification gaps that create service backlogs in Delhi. |
| BIS Testing Relationship Investment | Accelerates product launch cycles against competitors facing laboratory backlog. |
| Solar-Thermal Convergence Development | Aligns with Ministry of New and Renewable Energy distributed energy goals. |
| Southern State Geographic Expansion | Captures underpenetrated Tamil Nadu and Karnataka markets before mandate harmonization. |
Research Methodology
Initial hypotheses were tested against primary input from HVAC equipment procurement managers, state nodal agency program officers, BIS certification laboratory directors, and electrician-plumber trade contractors and refined through secondary validation against Bureau of Energy Efficiency star labeling databases, Ministry of New and Renewable Energy subsidy disbursement records, Central Electricity Authority grid integration filings, and customs import data for compressor components. Bottom-up installation volume estimates and top-down energy consumption projections were triangulated to establish market sizing.
Variance decomposition across the projection horizon isolates drivers by product type, technology tier, installation context, and application end-use. CAGRs were derived from segment-level growth trajectory modeling incorporating state mandate implementation pace, BEE standard revision schedules, and copper price sensitivity elasticity. Forecast inputs include Maharashtra Energy Development Agency subsidy administration capacity and Delhi-Mumbai apartment construction permit pipelines.
Decision-makers should treat outputs as directional under assumptions of continued BIS enforcement tightening and state renewable mandate expansion; material deviation would warrant model refresh. Specific risk factors include refrigerant phase-down regulations, grid tariff redesign for distributed heating loads, and commodity supply disruptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Global HVAC Filter Market
HVAC Equipment
Global Air-To-Air Heat Pumps Market
HVAC Equipment
France Commercial HVAC Market
HVAC Equipment
Asia-Pacific Heat Exchanger Market
HVAC Equipment
Ceiling Cassettes Market
HVAC Equipment
Global Air Handling Units (AHU) Market
HVAC Equipment
Commercial Refrigeration Compressor Market
HVAC Equipment
United States HVAC Equipment and Services Market
HVAC Equipment
US Heating Equipment Market
HVAC Equipment
GCC Water Heater Market
HVAC Equipment
Europe Hydronic Radiators Market
HVAC Equipment
Heavy Duty Heat Pump Market
HVAC Equipment
Japan HVAC Market
HVAC Equipment
Industrial Ventilation Equipment Market
HVAC Equipment
North America HVAC Equipment Market
HVAC Equipment
HVAC System Analyzer Market