
 Water Chiller Market | 2026-2036
Water Chiller Market Size, Share, and Industry Trends Forecast 2026-2036
Water Chiller Market Analysis
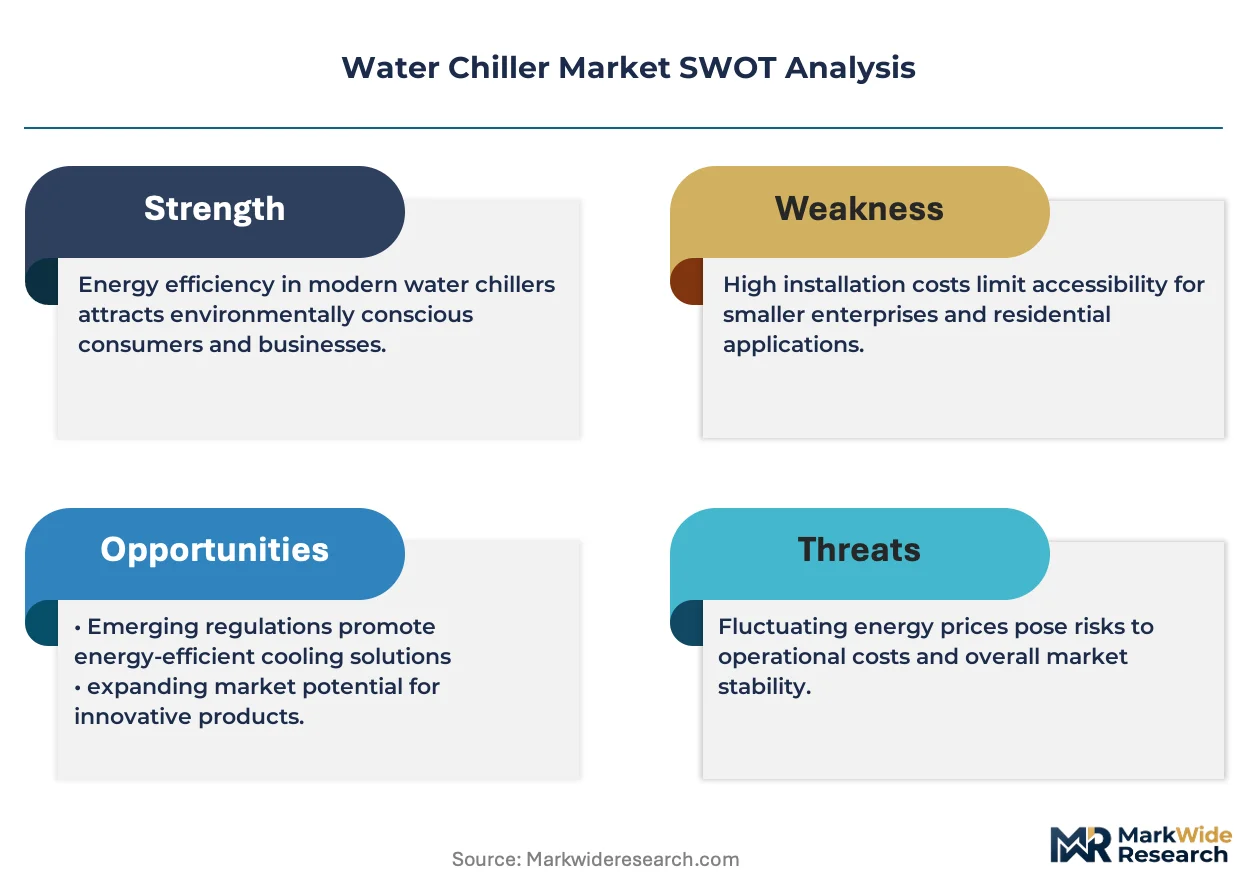
Natural refrigerant adoption is decoupling water chiller product economics from legacy fluorinated gas dependency. Carrier Corporation leverages its global service network to sustain aftermarket revenue streams. Trane Technologies anchors its portfolio in high-efficiency centrifugal systems for large commercial installations.
A water chiller is a mechanical refrigeration system that removes heat from a liquid coolant, typically water or a water-glycol mixture, through a vapor-compression or absorption cycle, then circulates the chilled fluid to air-handling units or process equipment. The device maintains temperatures ranging from approximately 2°C to 7°C at the evaporator outlet for HVAC comfort cooling, or sub-zero setpoints for industrial process applications. Air-cooled units dominate commercial retrofit markets where cooling tower infrastructure is unavailable, while water-cooled centrifugal systems capture margin pools in district cooling and large healthcare complexes. Absorption chillers, though slower-growing, retain strategic positions in facilities with waste heat recovery or combined heat and power integration.
The US Department of Energy and the EPA regulate chiller efficiency through minimum energy performance standards and refrigerant phase-down mandates under the AIM Act. China's MIIT enforces GB standards for industrial cooling equipment while promoting dual carbon goals that accelerate low-GWP refrigerant transitions. Stakeholders must monitor evolving refrigerant regulations and efficiency tier thresholds to align R&D pipelines with compliance timelines across major manufacturing and installation geographies.
Market Dynamics
Refrigerant phase-down mandates under the US AIM Act and EU F-Gas Regulation are compressing product development cycles while forcing manufacturers to redesign thermal architectures around low-GWP alternatives.
Growth Catalysts
- Data center expansion:Hyperscale facilities in Northern Virginia and Frankfurt are specifying magnetic-bearing centrifugal chillers for part-load efficiency. Operators prioritize units with integrated free-cooling economizers.
- Heat reuse integration:District heating networks in Copenhagen and Stockholm are retrofitting absorption chillers to capture waste heat from combined heat and power plants. Municipal utilities are expanding district cooling coverage.
- GB standard alignment:China's MIIT enforcement of stricter efficiency tiers for industrial cooling equipment is accelerating replacement cycles in Jiangsu and Guangdong manufacturing clusters.
Market Restraints
- Copper and aluminum input volatility:Heat exchanger fabrication depends on non-ferrous metal prices that fluctuate with commodity cycles. Chinese smelter output disruptions transmit directly to chiller bill-of-material costs.
- Refrigerant supply concentration:Production of R-1234ze and R-513A concentrates among three chemical manufacturers. Patent-protected blends command premium pricing that erodes margins on mid-range equipment.
- Water-cooled system infrastructure requirements:Cooling tower installation demands civil works and water treatment chemistry that extend project timelines. Air-cooled alternatives capture retrofit opportunities where space constraints prohibit tower placement.
Strategic Opportunities
- India's pharmaceutical cold chain:Vaccine storage and active pharmaceutical ingredient manufacturing are expanding process cooling demand in Hyderabad and Mumbai. CDSCO temperature compliance mandates create specification pull for precision chillers.
- Electrification of heating networks:Large heat pumps with chiller-reversible operation are displacing gas boilers in Scandinavian district energy. Vapor-compression equipment suppliers are retooling for simultaneous heating and cooling duty.
- Service revenue unbundling:Predictive maintenance contracts using refrigerant leak detection and vibration monitoring are creating recurring revenue streams independent of equipment sales cycles.
Industry Challenges
- Refrigerant handling certification:Technician licensing for A2L mildly flammable refrigerants requires retraining field service networks. OEMs are absorbing certification costs to maintain installation quality.
- Legacy control system integration:BACnet and Modbus protocol mismatches between new variable-speed drives and existing building management systems extend commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Chiller Market |
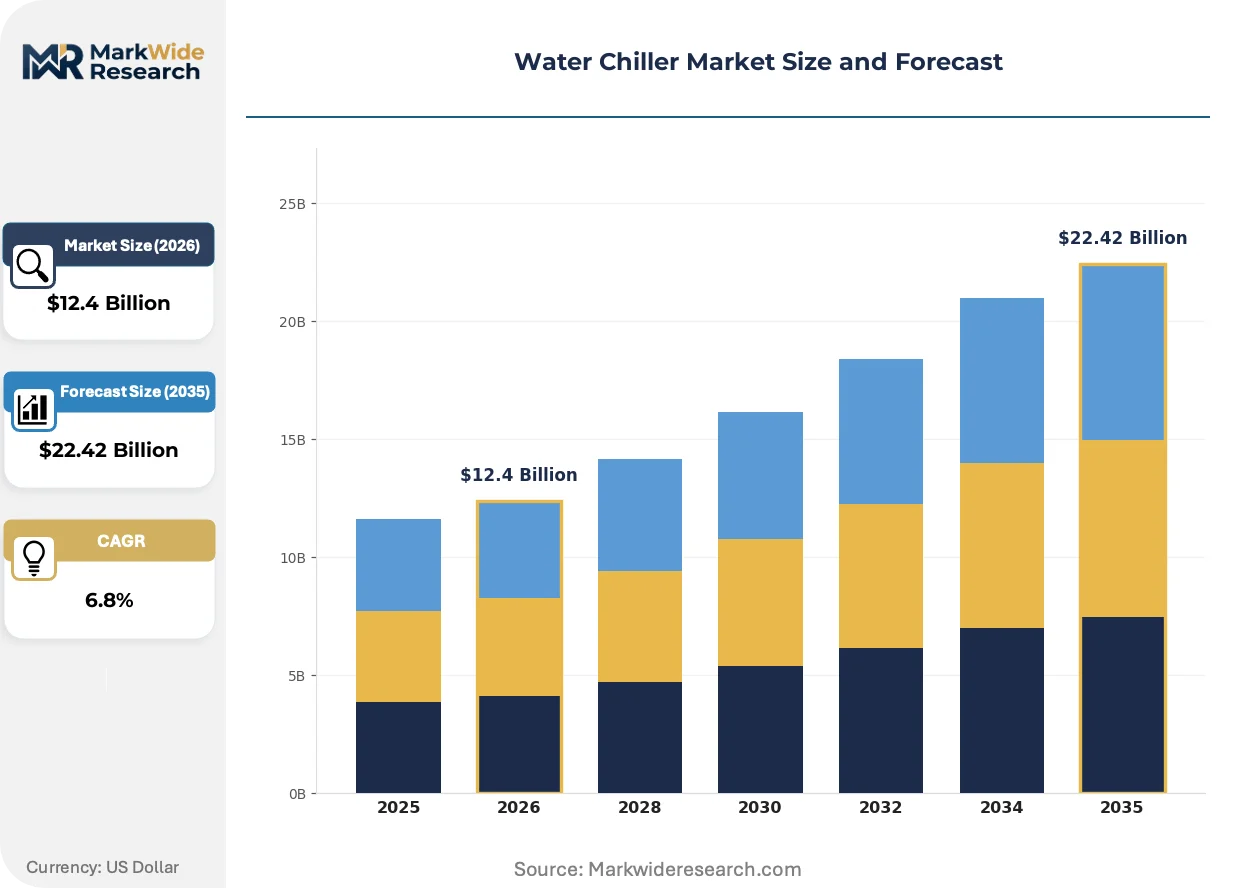
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Absorption, Centrifugal End User: Commercial, Industrial, Residential, Healthcare Application: Food Processing, HVAC, Process Cooling, Chemical Production Technology: Modular, Variable Speed, Scroll, Screw |
| Companies Covered | Carrier Corporation, Trane Technologies, Daikin Industries, Johnson Controls, Mitsubishi Electric Corporation, Panasonic Corporation, LG Electronics, Thermax Limited, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Chiller Market Emerging Trajectories
Digital twin deployment and machine learning-based fault detection are compressing maintenance intervals while enabling remote optimization of chiller plant efficiency.
Variable-speed magnetic bearing technology is automating part-load performance optimization in large-tonnage centrifugal systems. Data center operators in Singapore and Dublin are specifying these units for their 10:1 turndown capability and elimination of oil management systems. The technology is automating energy consumption reductions that previously required manual operator intervention.
The EU F-Gas Regulation's stepped GWP reduction schedule is forcing refrigerant transitions ahead of equipment replacement cycles. Chiller manufacturers are engineering drop-in alternatives and redesigning compressors for flammable A2L blends. Healthcare facilities in Germany and France face the tightest compliance timelines due to early phase-out dates for R-134a in new equipment.
Energy-as-a-service contracting is displacing capital purchase models in commercial real estate. Building owners in London and New York are transferring performance risk to chiller operators through guaranteed efficiency clauses. This model concentrates in Class A office portfolios where sustainability certifications drive tenant premiums.
Water Chiller Market Segmentation
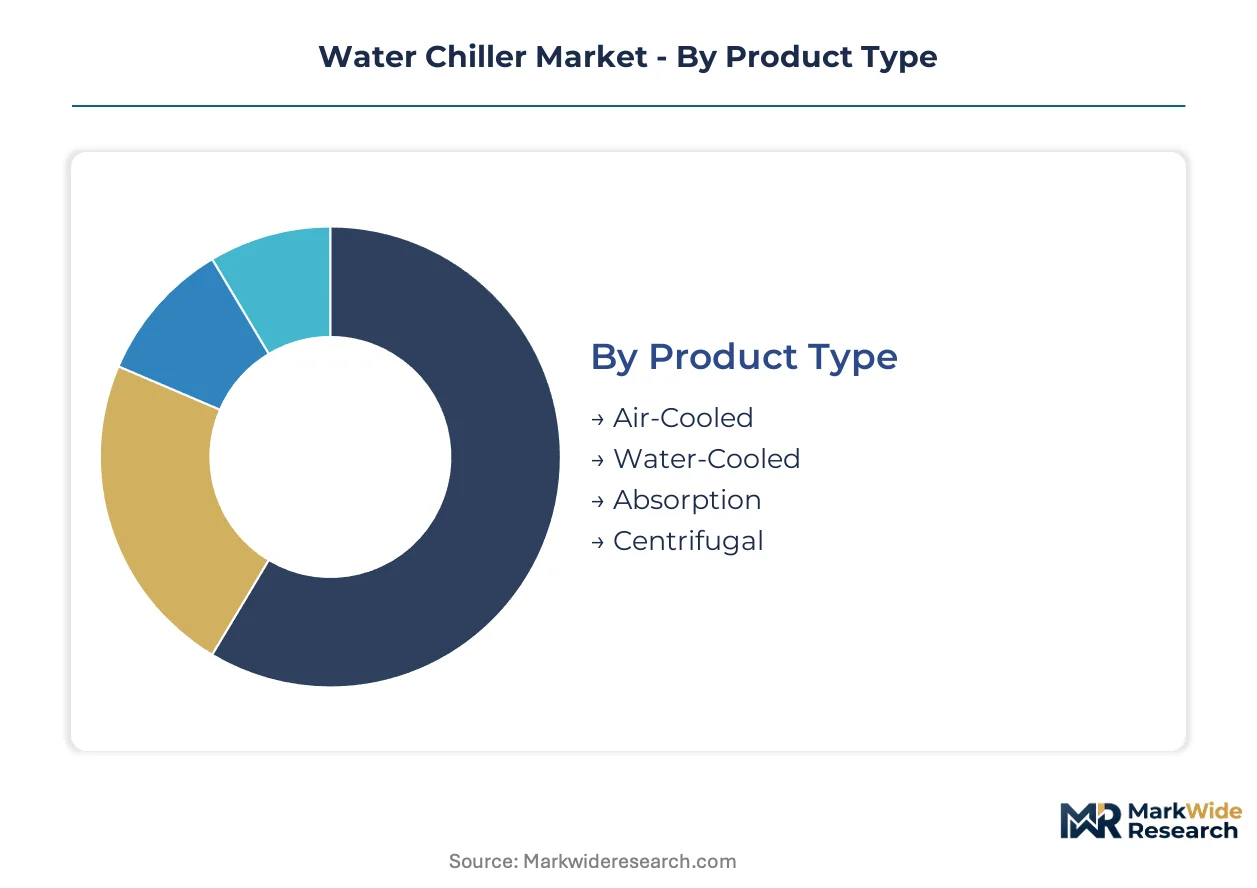
Water chiller procurement decisions hinge on thermal load profiles, infrastructure constraints, and refrigerant compliance timelines. Segment boundaries increasingly blur as manufacturers engineer hybrid systems spanning multiple categories. Understanding these divisions clarifies specification pathways for distinct cooling duties.
Product Type:
Volume concentrates in standardized air-cooled units, while premium engineering margins attach to specialized absorption and centrifugal architectures.
- Air-Cooled:Condenser coils reject heat directly to ambient air through forced convection, eliminating cooling tower infrastructure. Demand clusters in US commercial retrofits where municipal water restrictions and rooftop space constraints prohibit evaporative systems. Facility managers prioritize these units for speed of installation in Class B office renovations.
- Water-Cooled:Shell-and-tube condensers transfer heat to a secondary water loop feeding cooling towers or dry coolers. Large healthcare complexes in Germany and district cooling networks in Singapore specify these systems for peak efficiency at design load. The technology commands specification in facilities with 24/7 baseload profiles where energy recovery justifies civil infrastructure investment.
- Absorption:Thermal compressors using lithium bromide or ammonia cycles operate from waste heat sources. Cogeneration plants in Copenhagen integrate these units for district cooling supply.
- Centrifugal:Dynamic compression via impeller arrays achieves highest capacity-to-footprint ratios. Magnetic-bearing variants dominate data center specifications above 500 tons.
Today's leader: Water-Cooled. Tomorrow's challenger: Air-Cooled.
End User:
Application maturity separates established commercial installations from emerging residential micro-chiller demand.
- Commercial:Office towers, retail complexes, and hospitality properties drive replacement cycles for R-22 and R-134a legacy equipment. Building automation integration requirements dominate specification criteria in US Class A portfolios seeking LEED certification.
- Industrial:Manufacturing facilities require precise temperature control for metalworking fluids, plastic injection molding, and semiconductor fabrication. Jiangsu and Guangdong provinces in China anchor demand as MIIT efficiency standards accelerate equipment turnover in export-oriented factories.
- Residential:Distributed chiller-heaters for luxury multifamily and single-family estates represent nascent category growth. European heat pump regulations are stimulating product development for combined heating and cooling duty.
- Healthcare:Hospitals and pharmaceutical manufacturing demand redundant capacity with N+1 configurations. CDSCO temperature compliance in India creates specification pull for precision control in vaccine storage applications.
Commercial installations currently dominate unit volume. Industrial process cooling offers the steepest expansion trajectory as manufacturing reshoring accelerates.
Application:
Comfort cooling versus process precision defines divergent engineering requirements and margin structures.
- HVAC:Space conditioning for human occupancy operates at 5°C to 7°C supply temperatures with seasonal load variation. Northern Virginia data centers are driving magnetic-bearing centrifugal specifications for part-load efficiency optimization.
- Process Cooling:Industrial manufacturing demands sub-zero setpoints with ±0.5°C stability for chemical reactions and material forming. Hyderabad pharmaceutical clusters specify these systems for active pharmaceutical ingredient crystallization control.
- Food Processing:Blast chilling and cold storage applications require hygienic design with stainless steel wetted surfaces. EU hygiene regulations shape evaporator and pump specifications.
- Chemical Production:Exothermic reaction cooling and solvent recovery systems operate in hazardous area classifications. Explosion-proof electrical enclosures and corrosion-resistant metallurgy dominate engineering priorities.
HVAC remains the volume anchor. Process cooling is gaining share fastest as precision manufacturing expands in Asia-Pacific.
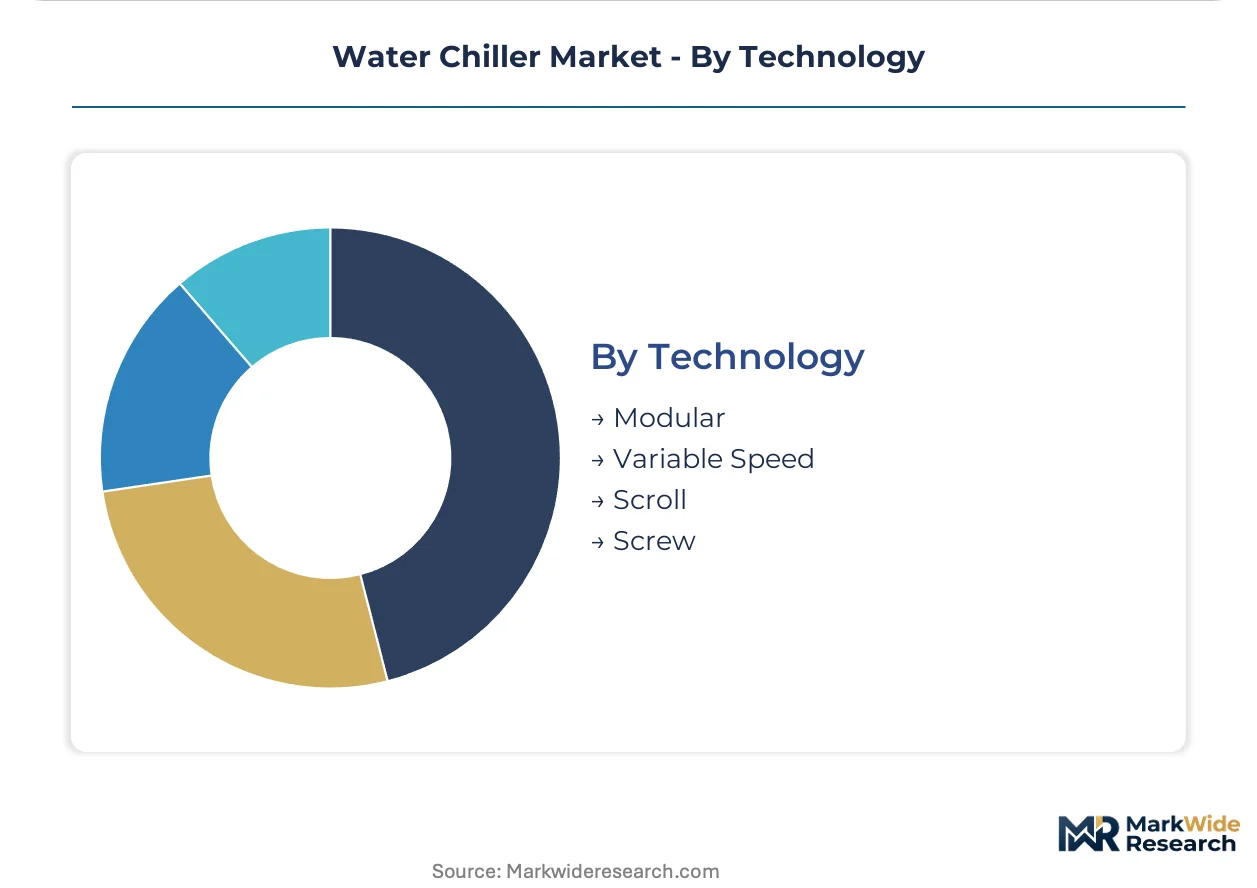
Technology:
Modularity and speed control are displacing fixed-speed legacy architectures across capacity ranges.
- Variable Speed:Inverter-driven compressors modulate capacity to match real-time thermal load, cutting energy consumption at part-load conditions. Singapore data centers mandate this technology for tropical climate efficiency.
- Modular:Factory-assembled skid packages enable phased capacity expansion and redundant N+1 configurations. London commercial real estate energy-as-a-service contracts favor these units for operational flexibility.
- Screw:Positive displacement compression delivers stable performance across wide ambient temperature ranges. Mid-range commercial and light industrial applications in the US Midwest specify these for reliability in variable climates.
- Scroll:Orbiting compression mechanisms dominate small-tonnage residential and light commercial segments. Japanese manufacturers anchor global supply for this technology category.
Variable speed holds current technology leadership. Modular architectures are climbing fastest as distributed energy systems proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Guangdong manufacturing clusters anchor Asia-Pacific water chiller demand as export-oriented factories accelerate equipment turnover under efficiency mandates. The US Department of Energy and China's MIIT are tightening compliance timelines that compress replacement cycles across major installation geographies.
United States
Hyperscale data centers in Northern Virginia and Texas are specifying magnetic-bearing centrifugal systems for part-load efficiency optimization. The US Department of Energy's minimum efficiency standards for commercial equipment are tightening product requirements and accelerating R-134a phase-out timelines. Dallas-Fort Worth healthcare complexes are retrofitting water-cooled systems for district cooling integration.
China
Urbanization and manufacturing cluster expansion in Jiangsu and Guangdong provinces are driving process cooling and HVAC installations. China's MIIT enforces stricter GB standards for industrial cooling equipment while promoting dual carbon goals that accelerate low-GWP refrigerant transitions. Shanghai and Beijing district cooling networks are expanding coverage to commercial real estate portfolios.
Germany
Healthcare facilities in Frankfurt and Munich face the EU F-Gas Regulation's tightest compliance timelines for R-134a phase-out in new equipment. The country's national energy regulator enforces building efficiency codes that prioritize heat recovery integration. Stuttgart automotive manufacturing clusters are retrofitting absorption chillers for waste heat capture from combined heat and power plants.
India
Pharmaceutical cold chain expansion in Hyderabad and Mumbai is creating specification pull for precision chillers under CDSCO temperature compliance mandates. The country's national pharmaceutical regulator enforces strict storage protocols for vaccine distribution networks. Gujarat chemical production corridors are installing explosion-proof process cooling systems for hazardous area classifications.
Singapore
Tropical climate data centers are mandating variable-speed technology for efficiency optimization in high-ambient conditions. The city-state's building authority enforces green mark certification standards that prioritize energy performance in commercial developments. Marina Bay financial district cooling plants are integrating free-cooling economizers to reduce compressor runtime.
Water Chiller Market Vendor Landscape
Global majors compete with regional champions across refrigerant technology and service network coverage. The vendor base spans consolidated multinational conglomerates with full HVAC portfolios alongside specialized regional fabricators focused on specific capacity ranges or cooling applications. Three strategic archetypes dominate: full-system integrators leveraging global service networks, technology specialists concentrating on magnetic-bearing or absorption architectures, and regional cost-optimized manufacturers serving price-sensitive retrofit markets. Competitive moves center on M&A activity to secure refrigerant technology IP and strategic partnerships for district cooling project development.
Within the full-system integrator tier, Carrier Corporation and Trane Technologies exemplify archetypes built on global aftermarket service infrastructure and high-efficiency centrifugal system engineering. Daikin Industries occupies a position representing Japanese manufacturing precision in variable-speed compressor technology. These three companies anchor the premium specification segment where building automation integration and predictive maintenance contracts determine procurement decisions.
| Leading Market Players |
|---|
| Carrier Corporation |
| Trane Technologies |
| Daikin Industries |
| Johnson Controls |
| Mitsubishi Electric Corporation |
| Panasonic Corporation |
| LG Electronics |
| Thermax Limited |
| Hitachi |
| Others |
Supply Flow & Price Mechanics
The US EPA's refrigerant phase-down mandates under the AIM Act gate qualified supply and premium-tier pricing access. Only manufacturers with certified A2L handling infrastructure and low-GWP compressor redesigns capture specification in regulated markets. This environmental compliance tiering concentrates pricing power among full-system integrators while marginalizing regional fabricators lacking refrigerant technology IP.
Pricing Analysis
Copper and aluminum input-cost pass-through dominates chiller pricing dynamics. Heat exchanger fabrication draws from Chinese smelter output and LME spot markets, transmitting commodity volatility directly to bill-of-material costs. Pricing stratifies across magnetic-bearing centrifugal, standard screw, and fixed-speed scroll tiers. Data center operators show least price sensitivity for part-load efficiency specifications. Mid-range commercial retrofits face acute cost compression where air-cooled alternatives compete on speed of installation.
Supply Chain Analysis
Refrigerant supply rests on Japanese and US specialty chemical producers holding patents on R-1234ze and R-513A blends. Compressor manufacturing anchors in China, Japan, and Germany. Copper tube and aluminum fin stock feed from Chinese rolling mills. Single-source vulnerability concentrates in flammable refrigerant handling certification networks. Distribution runs through OEM-direct project channels for large-tonnage units and HVAC wholesale distributors for commercial retrofit volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The water chiller market functions as a stable compounder. Data center thermal load expansion drives steady replacement and upgrade cycles regardless of macroeconomic cyclicality.
For Market Incumbents: Hedge refrigerant transition risk by securing backward integration into low-GWP compressor technology. Carrier Corporation and Trane Technologies must defend service network density against emerging energy-as-a-service operators absorbing performance risk through guaranteed efficiency clauses. Prioritize certification investment for A2L mildly flammable refrigerant handling to maintain installation quality. For New Entrants and Emerging Players: Magnetic-bearing technology miniaturization offers a technology-first wedge into sub-200-ton commercial segments underserved by incumbent centrifugal portfolios. Target India's pharmaceutical cold chain in Hyderabad and Mumbai where CDSCO temperature compliance mandates create specification pull for precision process cooling. Pursue OEM partnership routes rather than direct distribution to bypass entrenched service network barriers. For Investors and Strategic Acquirers: Roll-up economics work for regional service specialists with dense technician networks because predictive maintenance contracts generate recurring revenue independent of equipment sales cycles. Target acquisition archetype: mid-cap fabricators with district cooling project development capabilities in Asia-Pacific manufacturing clusters. Watch for inflection when energy-as-a-service contract penetration in Class A commercial real estate crosses threshold density.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Technology Licensing | Secures low-GWP compressor IP from Japanese chemical manufacturers for A2L compliance. |
| Predictive Maintenance Platform | Captures recurring revenue through vibration monitoring and refrigerant leak detection contracts. |
| District Cooling Joint Venture | Positions for Singapore and Shanghai municipal utility expansion with heat recovery integration. |
| Magnetic-Bearing Capacity Addition | Serves Northern Virginia hyperscale data center specifications for part-load efficiency. |
| Pharmaceutical Cold Chain Certification | Meets CDSCO mandates for vaccine storage precision control in Mumbai and Hyderabad. |
Methodological Framework
Coverage spans the United States, China, Germany, India, and Singapore, with primary inputs from each. The research combines interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads with secondary validation. Sources include US Department of Energy efficiency filings, China's MIIT GB standard publications, EU F-Gas Regulation compliance databases, and customs trade records. Bottom-up equipment shipment data triangulates against top-down energy consumption models.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, end user, application, and technology tier. CAGRs derive from equipment replacement cycle analysis and regulatory compliance timeline alignment. Forecast inputs incorporate data center capex disclosures and district cooling network expansion announcements.
The model holds under steady refrigerant phase-down schedules and stable copper price regimes; deviation in Chinese smelter output or accelerated A2L mandates would shift replacement timing. Forecasts reflect these base-case assumptions. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Utility and Industrial Boilers Market
HVAC Equipment
Industrial Chiller Market
HVAC Equipment
China HVAC Field Device Market
HVAC Equipment
Scrubber Dryer Market
HVAC Equipment
Cooling Tower Market
HVAC Equipment
Fabric Air Ducts Market
HVAC Equipment
Japan HVAC Market
HVAC Equipment
HVAC Actuators Market
HVAC Equipment
HVAC Systems Market
HVAC Equipment
GCC Kitchen Hood Market
HVAC Equipment
France Commercial HVAC Market
HVAC Equipment
Global Industrial Fans and Blowers Market
HVAC Equipment
North America Gas Water Heater Market
HVAC Equipment
Steam Heat Exchanger Market
HVAC Equipment
Asia-Pacific Heat Exchanger Market
HVAC Equipment
Brazed Plate Heat Exchangers Market