
 Heating Radiator Market | 2026-2036
Heating Radiator Market Size, Share, and Industry Trends Forecast 2026-2036
Heating Radiator Market Intelligence
The European Union's Green Deal, with its mandate for building decarbonization, is decoupling radiator selection from traditional fossil fuel systems and toward compatibility with heat pumps. Rheem Manufacturing Company leverages its extensive HVAC portfolio to offer integrated solutions for new construction and retrofits. Trane Technologies Company competes on system-level efficiency, positioning its products within broader building energy management platforms. Meanwhile, Mestek Inc. anchors its position in the commercial sector with specialized baseboard hydronic systems.
A heating radiator is a heat exchanger transferring thermal energy from a medium like hot water or steam into a space via convection and radiation. Material choices, such as cast iron or aluminum, directly influence the unit's thermal inertia and heat output characteristics. Hydronic technology holds the largest share, with panel radiators being a standard choice for residential buildings. Towel warmers and custom cast iron radiators represent high-value niches, particularly in hospitality and premium residential projects.
Product design and efficiency are governed by a matrix of regional regulations, including the US EPA's ENERGY STAR program and the EU's Energy Performance of Buildings Directive (EPBD). In China, national GB standards for energy efficiency in buildings mandate specific performance levels for heating components. Future profitability for manufacturers will hinge on developing radiators optimized for low-temperature inputs from renewable sources like heat pumps.
Market Dynamics
The fundamental market dynamic is the decoupling of heating systems from fossil fuels, driven by global decarbonization mandates. This shift forces the redesign of radiators to operate efficiently with low-temperature water from renewable sources like heat pumps, altering material and design priorities.
Growth Catalysts
- Building Energy Mandates:The EU's Energy Performance of Buildings Directive (EPBD) compels member states to upgrade older building stock, stimulating demand for high-efficiency radiators in residential retrofits.
- Modernization Programs:National housing modernization initiatives, particularly in Germany and the United Kingdom, prioritize energy efficiency upgrades, creating a direct stimulus for advanced hydronic heating components.
- Low-Temperature Optimization:The development of radiators with larger surface areas and improved convective designs enhances performance with heat pumps, accelerating their adoption in new builds and renovations.
Market Restraints
- Raw Material Volatility:Fluctuations in the price of key inputs like aluminum and steel directly impact manufacturing costs and product pricing, creating margin pressure for producers.
- Substitute System Competition:In new construction, alternative heating technologies such as radiant underfloor heating systems compete directly with traditional radiators, especially in markets prioritizing minimalist aesthetics.
- Legacy System Inertia:The large installed base of high-temperature boiler systems in older residential properties slows the adoption of radiators optimized for low-temperature inputs, creating a replacement cycle lag.
Strategic Opportunities
- Smart Radiator Integration:Embedding IoT sensors and smart thermostatic valves into radiators creates opportunities for granular, zone-based heating control, appealing to the smart home and energy management markets.
- Hospitality and Premium Residential:Demand for custom-designed and high-finish radiators, such as designer towel warmers and bespoke cast iron units, represents a high-margin niche in luxury hotel and residential projects.
- Emerging Market Infrastructure:Urbanization and new residential construction in Eastern European and select Asian countries provide opportunities for establishing modern, centralized hydronic heating infrastructure.
Industry Challenges
- Retrofit Integration Complexity:Ensuring new low-temperature radiators are compatible with the existing pipework and system pressure of older buildings during retrofits poses a significant technical challenge for installers.
- Installer Skill Gaps:A shortage of HVAC technicians trained in designing and installing integrated systems that pair modern radiators with renewable heat sources limits the market's growth potential.
- Regulatory Compliance Burden:Adhering to a diverse and evolving set of regional energy efficiency standards, from the EU's EPBD to China's GB standards, requires continuous investment in product testing and certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heating Radiator Market |
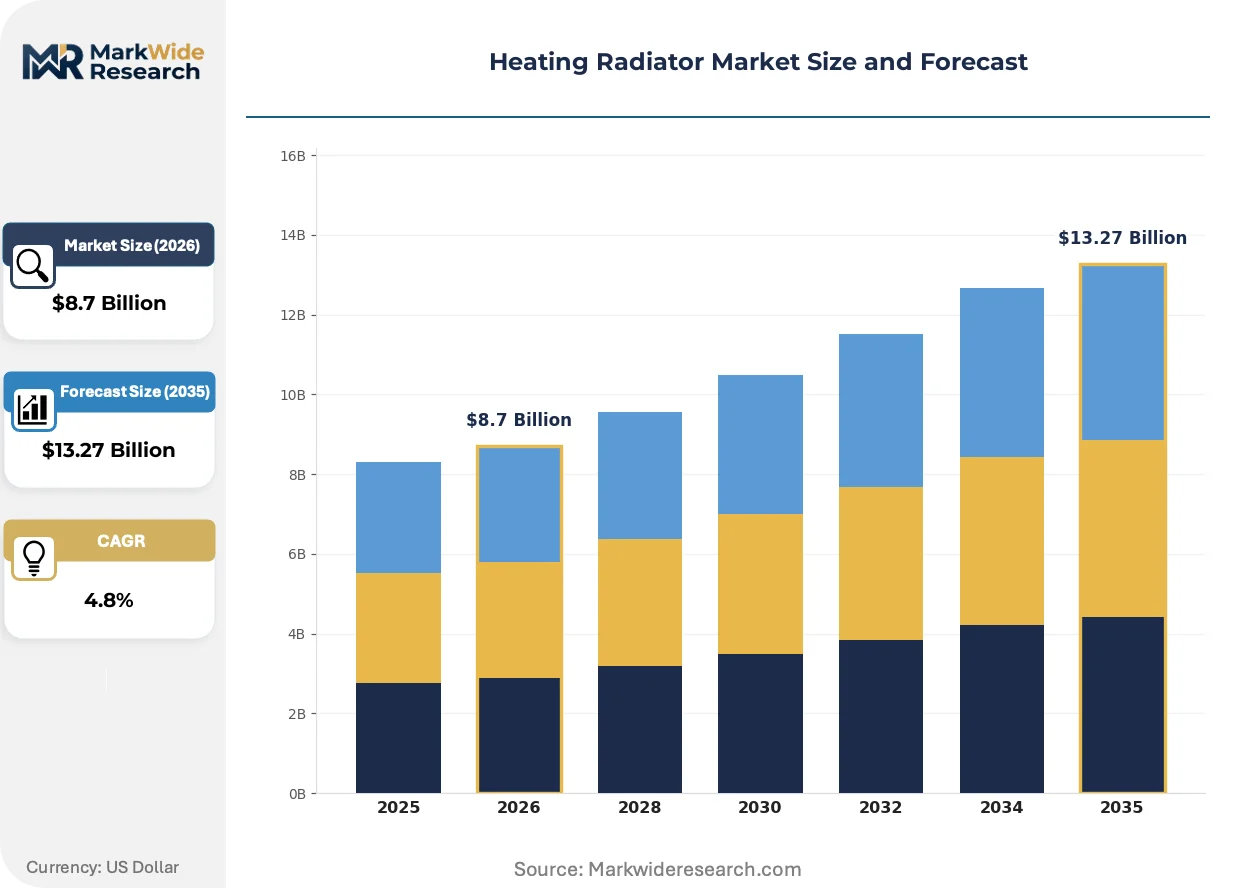
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panel Radiators, Column Radiators, Towel Warmers, Baseboard Radiators, Cast Iron Radiators Technology: Convection, Radiant, Fan-Forced, Electric, Hydronic Application: Residential Buildings, Commercial Establishments, Educational Facilities, Government Institutions, Hospitality Venues End User: Property Developers, HVAC Contractors, Facility Managers, Real Estate Investors, Maintenance Firms |
| Companies Covered | OCS Industries, Runtal North America, Rheem Manufacturing Company, Mestek Inc., Sterling Hydronics, Trane Technologies Company, Cast Iron Radiators, U.S. Boiler Company, Johnson Controls International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heating Radiator Market Strategic Shifts & Innovations
The radiator's role is evolving from a standalone heat emitter to a critical component within integrated, low-carbon building energy systems. This transition prioritizes system compatibility, smart controls, and material science to maximize efficiency with renewable heat sources.
Bimetallic radiators, which combine a corrosion-resistant steel core with a highly conductive aluminum exterior, offer rapid heat transfer and robust longevity. The residential retrofit sector is adopting these units for their dual compatibility with both legacy high-temperature boilers and modern low-temperature heat pumps. This hybrid material construction is absorbing the performance trade-offs between pure aluminum and cast iron, providing a balanced solution for system upgrades.
Implementation of the European Union's F-Gas Regulation, which phases down certain refrigerants, indirectly promotes the use of heat pumps that utilize alternatives. This policy accelerates the shift away from fossil fuel boilers, creating demand for radiators designed for the lower operating temperatures of these systems. Panel and column radiator manufacturers are responding by engineering products with larger surface areas to deliver adequate heat output.
A notable behavioral shift involves building specifiers and architects prioritizing whole-system performance over the cost of individual components. This trend moves purchasing decisions away from simple like-for-like radiator replacements and toward integrated HVAC packages from a single supplier. The shift is most visible in the commercial new construction sector in North America and Europe, where building energy management platforms are standard.
Heating Radiator Market Segmentation
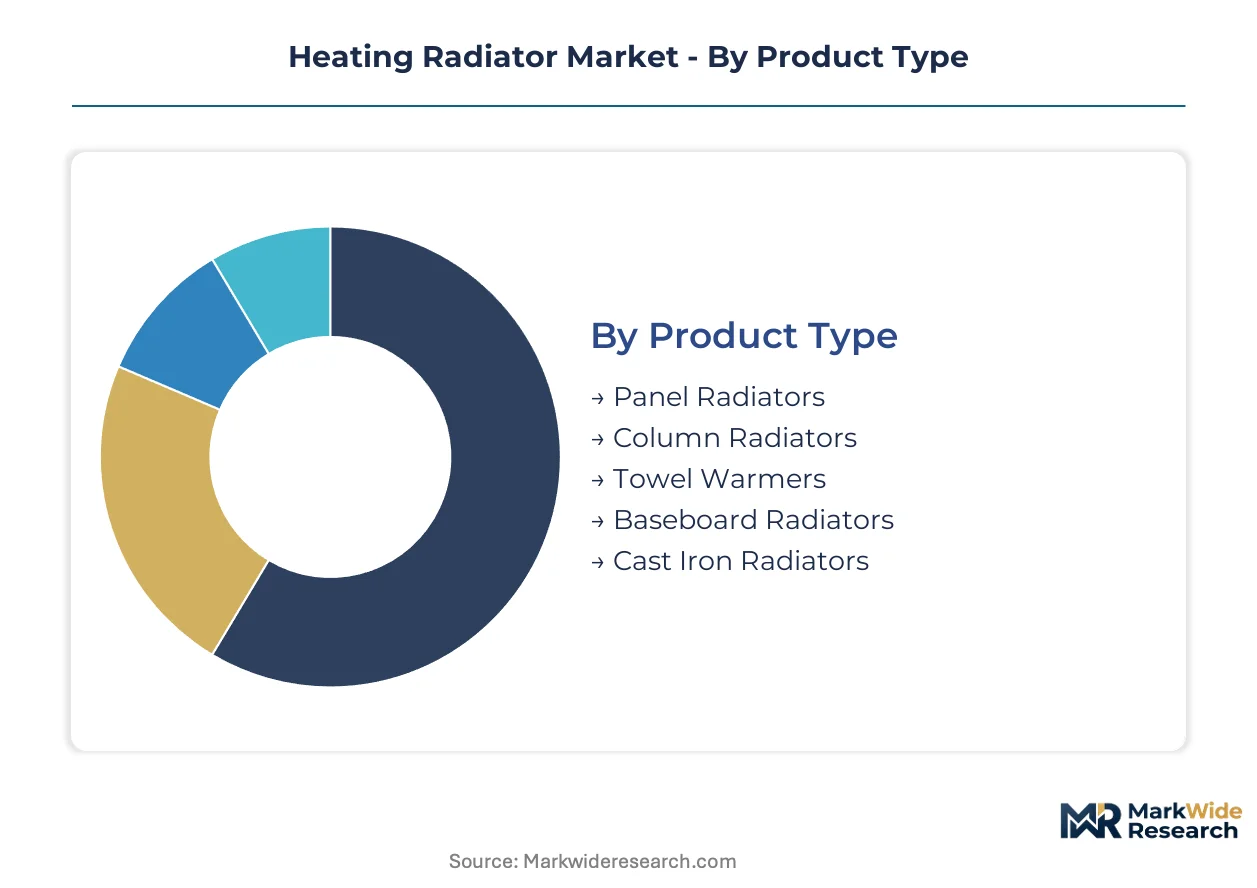
The Heating Radiator Market segmentation reveals distinct demand patterns and regulatory influences shaping product development and end-user adoption. Understanding these segments is critical for manufacturers to align product offerings with evolving energy efficiency standards and architectural preferences across different building types.
Product Type:
Compliance with regional energy efficiency directives, such as the EU's Energy Performance of Buildings Directive and China's national GB standards, dictates specific design and performance certifications across radiator product types.
- Panel Radiators:These units feature flat steel panels with internal fins, offering a large surface area for efficient heat transfer. Demand concentrates in residential retrofits across Germany and the United Kingdom, driven by government mandates for improved energy efficiency in older housing stock.
- Column Radiators:Constructed from vertical or horizontal tubes, these radiators provide high heat output and a distinct aesthetic, often in steel or aluminum. New construction projects in Eastern European countries prioritize column radiators for their modern design and compatibility with contemporary hydronic systems.
- Towel Warmers:Designed for bathrooms and kitchens, these radiators offer both heating and a functional drying rack. Hospitality venues and premium residential projects in Europe frequently specify designer towel warmers.
- Baseboard Radiators:Typically low-profile, these hydronic units are installed along walls, delivering consistent, even heat. Commercial sector applications, particularly in North America, utilize baseboard systems for discreet heating.
- Cast Iron Radiators:Known for their high thermal inertia and decorative designs, these heavy units retain heat for extended periods. Luxury residential properties and historic building renovations in the United Kingdom favor custom cast iron radiators.
Panel Radiators sit at the top of the volume ranking, with Column Radiators climbing the fastest.
Technology:
The choice of heating radiator technology directly influences installation complexity and suitability for specific building types and energy sources.
- Hydronic:This technology circulates hot water or steam from a central boiler or heat pump through the radiator panels or columns. Residential retrofits across the European Union widely adopt hydronic systems due to established infrastructure and efficient integration with low-temperature heat sources.
- Electric:Electric radiators convert electricity directly into heat using resistive elements, providing standalone heating without plumbing. Supplementary heating in North American commercial spaces frequently employs electric radiators for their ease of installation and precise zonal control.
- Convection:These radiators primarily warm air, which then circulates throughout the room, providing rapid heat distribution. Many standard panel radiators utilize convection as their primary heat transfer mechanism.
- Radiant:Radiant technology transfers heat directly to objects and surfaces in a room, creating a sense of warmth at lower air temperatures. Custom cast iron radiators often provide a significant radiant heat component.
- Fan-Forced:Incorporating an integrated fan, these units actively push heated air into the space, offering a quick heating response. Compact fan-forced radiators serve well in smaller, intermittently used areas.
Hydronic technology maintains a dominant market share, while Electric technology shows significant growth in niche applications.
Application:
Radiator application segments differentiate based on the specific heating demands and aesthetic requirements of varied building occupants.
- Residential Buildings:This segment encompasses heating solutions for homes, driven by energy efficiency, comfort, and aesthetic integration. Retrofitting older housing stock in the United Kingdom drives demand for new high-efficiency radiators, supported by government modernization programs.
- Hospitality Venues:Hotels, resorts, and guesthouses require custom-designed units that blend aesthetic appeal with high performance and energy efficiency. Premium hotels in Germany seek bespoke radiator solutions that integrate seamlessly with luxury interiors and advanced climate control systems.
- Commercial Establishments:This segment includes office spaces, retail outlets, and other business premises, often requiring zone-based heating solutions. Modern office buildings in Europe increasingly specify panel radiators compatible with central building energy management platforms.
- Educational Facilities:Schools and universities prioritize robust construction, consistent heating, and long-term durability in their heating systems. Public sector procurement in Germany often focuses on energy-efficient radiator solutions for educational infrastructure.
- Government Institutions:Public administration buildings require heating systems that meet stringent regulatory compliance and offer long operational lifespans. National government initiatives in China promote energy-efficient heating components for new public buildings.
Residential Buildings represent the largest volume segment, with Hospitality Venues commanding premium pricing.
End User:
End-user segments exhibit distinct procurement patterns and decision-making criteria for heating radiator systems.
- Property Developers:These entities specify heating systems for new construction and major renovation projects, focusing on initial cost, long-term efficiency, and market appeal. New residential projects in China, driven by rapid urbanization, rely heavily on Property Developers for system selection.
- HVAC Contractors:Responsible for the installation and integration of heating systems, these professionals prioritize ease of installation, system compatibility, and reliable performance. Retrofit projects across the EU depend on HVAC Contractors to adapt new low-temperature radiators to existing hydronic infrastructure.
- Facility Managers:Overseeing the operation and maintenance of large buildings, Facility Managers focus on system reliability, operational efficiency, and energy management. Commercial building managers in North America seek radiators offering smart control integration for optimal energy performance.
- Real Estate Investors:These stakeholders consider heating system efficiency and modernization as factors influencing property value and energy performance ratings. Investors in the United Kingdom prioritize energy-efficient heating upgrades to enhance asset value and meet sustainability targets.
- Maintenance Firms:Providing repair services and component replacement, these firms focus on the availability of spare parts and ease of servicing. Older building stock in Germany often relies on Maintenance Firms for servicing and upgrading legacy heating radiator systems.
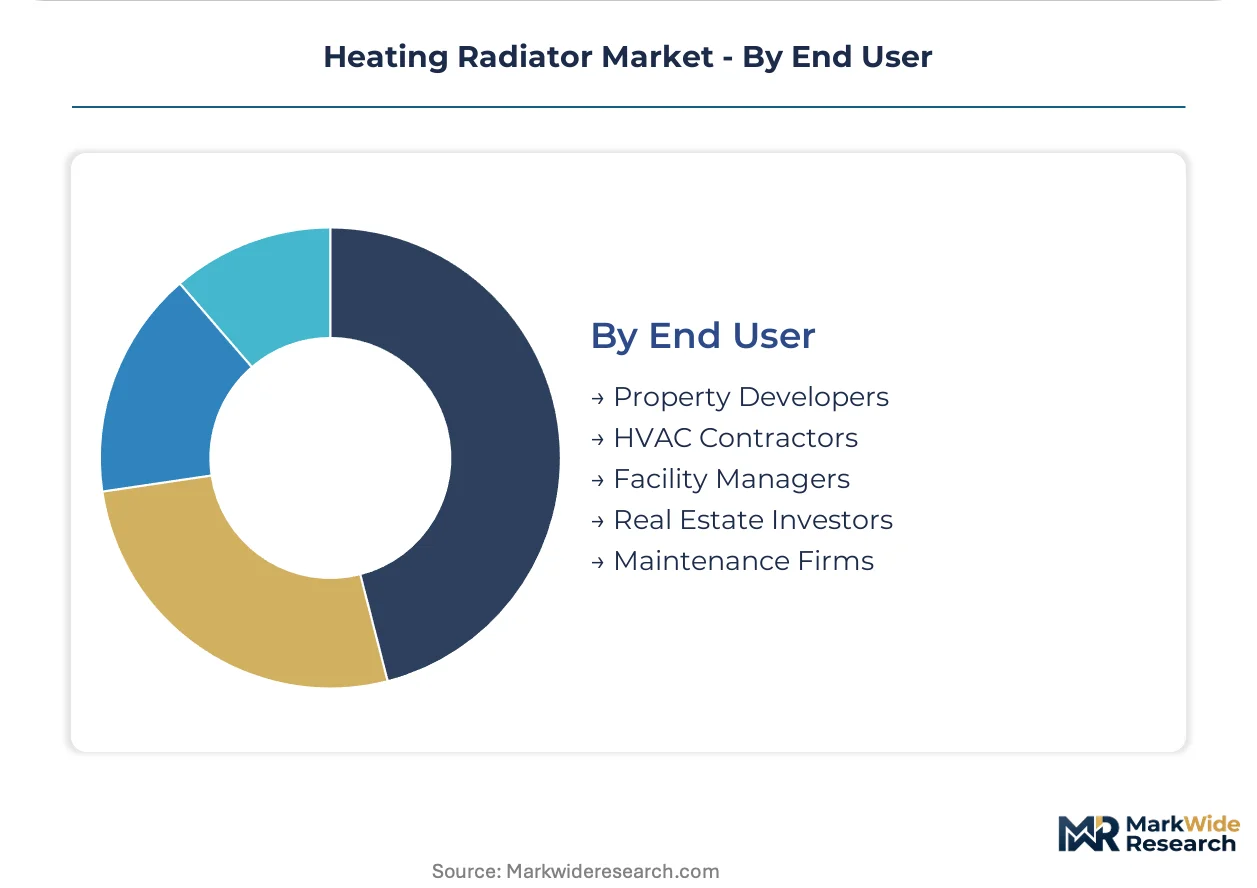
Property Developers and HVAC Contractors hold significant influence over initial system selection, while Facility Managers drive ongoing maintenance and upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The heating radiator industry originated and scaled significantly within European markets, driven by early advancements in hydronic systems for residential and commercial applications. This historical foundation continues to influence market dynamics, particularly with ongoing decarbonization efforts. Global demand patterns now reflect a blend of legacy infrastructure upgrades and new construction requirements across diverse geographies.
Germany
High demand for energy-efficient radiator upgrades stems from a mature housing stock and robust environmental policies. The Energy Performance of Buildings Directive (EPBD) mandates significant improvements in building thermal efficiency. Manufacturers in Bavaria and North Rhine-Westphalia focus on developing low-temperature compatible radiators.
United Kingdom
Modernization programs for residential properties drive substantial demand for advanced hydronic heating components. The UK government's push for energy efficiency in housing stock directly stimulates radiator retrofits. London and other urban centers prioritize smart radiator integration for enhanced energy management.
China
Rapid urbanization and new residential construction projects generate significant volume demand for heating radiators. National GB standards for energy efficiency in buildings establish performance benchmarks for heating components. Manufacturers in the Yangtze River Delta region scale production of panel and column radiators.
United States
Commercial sector applications and residential retrofits contribute to a steady demand for diverse radiator solutions. The US EPA's ENERGY STAR program influences product design towards higher efficiency. HVAC contractors in the Northeast and Midwest manage complex installations of hydronic and electric systems.
France
Energy transition policies and a focus on renewable heating sources are reshaping radiator selection in French buildings. The French government promotes heat pump adoption, increasing demand for low-temperature radiators. Manufacturers near Lyon and Paris innovate in bimetallic radiator designs for optimal performance.
Heating Radiator Market Key Industry Players
Premium-margin players sit above commodity-margin players across product complexity and customization within the heating radiator market. The market structure exhibits a tiered consolidation, with established global HVAC players dominating the high-efficiency and integrated solutions segments. Mid-sized specialists carve out niches in custom designs and specific applications. Key strategic archetypes include integrated system providers, specialized component manufacturers, and regional market leaders. Portfolio diversification and strategic partnerships represent dominant competitive moves among larger entities.
Among integrated system providers, Rheem Manufacturing Company leverages its extensive HVAC portfolio to offer comprehensive solutions for both new construction and retrofits. Trane Technologies Company occupies a position focused on system-level efficiency, positioning its products within broader building energy management platforms. Mestek Inc. anchors its presence in the commercial sector, specializing in baseboard hydronic systems. These companies exemplify strategies ranging from broad portfolio integration to focused segment leadership.
| Leading Market Players |
|---|
| OCS Industries |
| Runtal North America |
| Rheem Manufacturing Company |
| Mestek Inc. |
| Sterling Hydronics |
| Trane Technologies Company |
| Cast Iron Radiators |
| U.S. Boiler Company |
| Johnson Controls International |
| Others |
Cost & Logistics Intelligence
Premium-tier radiators, such as custom cast iron and designer towel warmers, exhibit significantly higher pricing and involve specialized, often localized, artisanal supply chains. Conversely, high-volume panel radiators operate on commodity pricing, leveraging globalized material sourcing and efficient mass production.
Pricing Analysis
Project-based pricing dominates the premium segment, reflecting bespoke designs and specialized installation services for hospitality and luxury residential projects. Price differentiation stems from material choices like bimetallic construction and aesthetic customization, alongside brand premium for established manufacturers. Pricing softness runs through the standard panel radiator segment due to intense competition and raw material volatility. Residential retrofit buyers in Germany are highly price-sensitive, while premium hospitality venues prioritize value-based solutions.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks facilitate efficient delivery of radiators to installers and retailers across Europe and North America. Production concentrates in China for high-volume panel radiators, while specialized units are often manufactured in Germany and Italy. The industry draws from steel and aluminum for core components, with copper used in hydronic systems. Commodity price volatility for these metals represents a significant structural risk. Distribution runs through a multi-channel model, engaging HVAC contractors and specialized building material suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The heating radiator market functions as a regulatory compounder, with the European Union's Energy Performance of Buildings Directive (EPBD) driving substantial demand for high-efficiency upgrades. This mandate accelerates the shift towards low-temperature compatible radiators across member states.
For Market Incumbents: Deploy R&D investments into bimetallic and larger surface area radiator designs optimized for low-temperature heat pump systems. Incumbents should also forge strategic partnerships with heat pump manufacturers to offer integrated HVAC packages, countering competition from substitute underfloor heating systems. Investing in installer training programs addresses skill gaps and reinforces market position against new entrants. Continuous certification under evolving standards like the EU's EPBD ensures regulatory compliance.
For New Entrants and Emerging Players: Capture market share by focusing on smart radiator integration, embedding IoT sensors and smart thermostatic valves for zone-based heating control. New entrants should target the underpenetrated Eastern European new construction segment with modern column radiators, emphasizing design and energy efficiency. A go-to-market angle centered on design-led differentiation and compatibility with emerging heat pump technologies offers a distinct competitive advantage. Premium residential projects also present a high-margin entry point.
For Investors and Strategic Acquirers: Consolidation pressure builds where regional market leadership and specialized manufacturing capabilities align with decarbonization mandates. The market offers long-term viability as radiators remain an essential component in energy-efficient buildings over the next 5-10 years. Acquire mid-sized specialists with strong bimetallic radiator expertise or robust regional distribution networks. A critical signal to watch is the accelerating adoption rate of heat pumps in Germany and the United Kingdom, indicating future radiator demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Low-Temperature Radiator R&D | Optimizes radiator performance with heat pumps, aligning with EU decarbonization goals. |
| Integrated HVAC System Partnerships | Offers comprehensive solutions for residential retrofits, leveraging existing HVAC portfolios. |
| Smart Thermostatic Valve Development | Enables granular zone-based heating control, appealing to smart home markets. |
| Bespoke Design & Customization | Addresses high-margin demand from hospitality venues and luxury residential projects. |
| Installer Training Programs | Mitigates skill gaps for complex low-temperature system integrations in older buildings. |
Research Approach
Coverage spans Europe, North America, and Asia-Pacific, with primary inputs from each region informing the analysis. The study combines in-depth interviews with HVAC contractors, property developers, and R&D directors from leading manufacturers. Secondary validation draws from EU building directives, national energy agency reports, and manufacturers' technical specifications. This approach ensures robust bottom-up and top-down triangulation of market data.
Rate-of-change decomposition analyzes historical market evolution and projects future trajectories across the analysis window. The analytical framework segments the market by product type, technology, application, end-user, and regional regulatory compliance. Compound Annual Growth Rates (CAGRs) derive from historical trends, projected building renovation rates, and anticipated heat pump installation volumes. This robust model accounts for both established market dynamics and emerging influences.
Raw material price volatility, evolving regulatory policy shifts, and installer skill availability are the dominant revision risks for market forecasts. All projections reflect assumptions about future economic conditions and technological advancements. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
HVAC Airflow and Blend Door Actuator Systems Market
HVAC Equipment
Europe HVAC Market
HVAC Equipment
Heavy Duty Heat Pump Market
HVAC Equipment
Cooling Tower Market
HVAC Equipment
Screw Compressor Market
HVAC Equipment
Air Humidifier and Dehumidifier Market
HVAC Equipment
Global Air-To-Air Heat Pumps Market
HVAC Equipment
Water Softener Equipment Market
HVAC Equipment
Asia-Pacific Industrial Heat Pump Market
HVAC Equipment
Air Conditioning Compressor Market
HVAC Equipment
GCC Kitchen Hood Market
HVAC Equipment
Industrial Dehumidifiers Market
HVAC Equipment
Europe Bus HVAC Market
HVAC Equipment
Equipment for HVAC Market
HVAC Equipment
Field-Erected Cooling Tower Market
HVAC Equipment
Global Portable Evaporative Air Cooler Market