
 Centrifugal Blower Market | 2026-2036
Centrifugal Blower Market Size, Share, and Industry Trends Forecast 2026-2036
Centrifugal Blower Market Analysis
Power generation utilities are redrawing procurement priorities for centrifugal blowers as baseload plant operators prioritize reliability over first-cost metrics. Atlas Copco leverages its compressor technology heritage to anchor positions in high-pressure process gas applications. Ingersoll Rand competes through integrated air-system architectures that bundle blowers with downstream treatment equipment. Howden Group dominates in heavy-duty mining ventilation, where abrasive duty cycles demand specialized impeller metallurgy and field-service density.
A centrifugal blower accelerates air radially through an impeller housed in a volute casing, typically achieving pressure ratios below 1.2 and discharge pressures ranging from a few inches of water column to 15 psig depending on impeller diameter and rotational speed. These machines serve industrial processes requiring continuous, oil-free air movement for combustion aeration, material transport, and building ventilation systems. HVAC installations command the largest volume footprint, though pneumatic conveying in food and pharmaceutical plants generates premium pricing through stainless-steel construction and contamination-control certifications. High-power ratings above 500 kW represent the fastest-expanding configuration tier, driven by bulk chemical and wastewater aeration projects where single-unit reliability reduces parallel redundancy costs. Medium-power segments remain the most contested margin pool, with Asian manufacturers pressuring European incumbents on delivery lead times.
The EPA's energy efficiency regulations and the EU F-Gas Regulation jointly constrain blower system design, compelling manufacturers to optimize impeller aerodynamics and adopt permanent-magnet motor integrations that reduce input kilowatts per standard cubic foot of air delivered. OSHA ventilation standards for confined industrial spaces further shape product specifications, particularly in mining and chemical processing end uses where explosive atmosphere certifications apply. Buyers must weigh total lifecycle energy expenditure against capital outlay as carbon accounting frameworks tighten operational scrutiny across heavy industry.
Market Dynamics
Permanent-magnet motor integration is compressing energy intensity benchmarks across wastewater and chemical processing installations, forcing incumbent suppliers to reengineer legacy drivetrain architectures or surrender specification control to integrated motor-blower specialists.
Growth Catalysts
- EPA Energy Efficiency Mandates:Tightened industrial equipment standards in the United States are accelerating variable-speed drive adoption in municipal wastewater facilities.
- German Chemical Processing Clusters:Engineering-intensive pneumatic conveying operations in the Ruhr and Bavaria regions sustain premium demand for precision-engineered impeller systems.
- Aging Infrastructure Replacement:Municipalities across the United States and Europe are upgrading aeration blower fleets installed during the 1970s-1980s construction boom.
Market Restraints
- Permanent Magnet Material Concentration:Rare earth supply chains concentrate in Chinese processing facilities, exposing motor manufacturers to price volatility and export restriction risk.
- High-Precision Casting Capacity:Specialized foundry capacity for large-diameter impeller castings remains concentrated in Western European and Japanese suppliers.
- EU F-Gas Regulation Compliance:Sealed bearing and lubrication system redesigns add engineering cycle time and certification cost for European market entry.
Strategic Opportunities
- India Wastewater Infrastructure:National Mission for Clean Ganga funding and urban sewage treatment expansion create first-mover positioning for high-efficiency aeration suppliers.
- Permanent-Magnet Motor Convergence:Integration of silicon carbide inverters with magnet-embedded rotors enables 15-20% efficiency gains over conventional induction systems.
- Digital Twin Deployment:Predictive maintenance platforms bundled with blower packages open recurring revenue streams in critical-uptime chemical processing installations.
Industry Challenges
- Aerodynamic Simulation Expertise:Computational fluid dynamics competency gaps constrain smaller manufacturers from optimizing impeller profiles for specific process gas densities.
- Explosive Atmosphere Certification:ATEX and IECEx compliance timelines for mining and chemical applications extend 12-18 months, delaying project revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Centrifugal Blower Market |
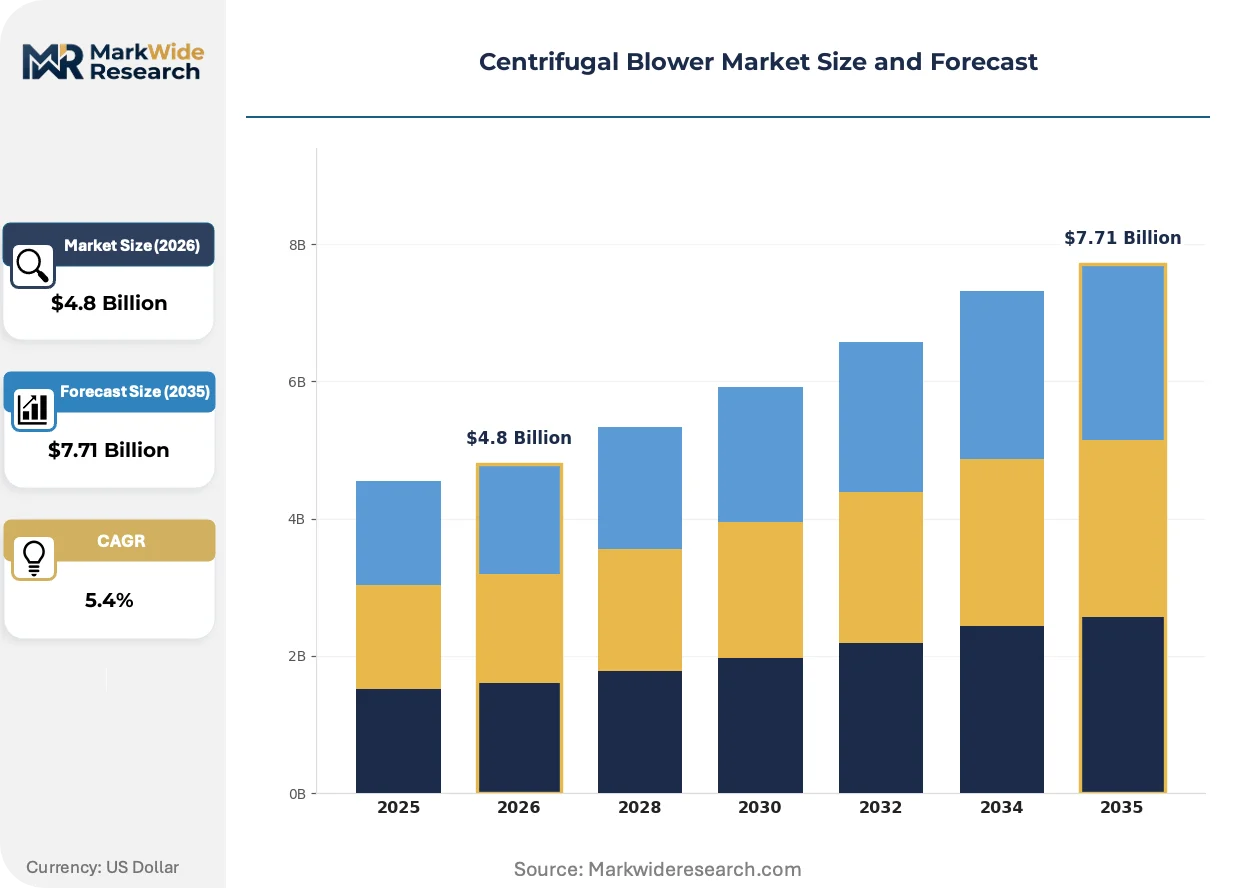
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: HVAC, Dust Collection, Pneumatic Conveying, Wastewater Treatment End User: Manufacturing, Power Generation, Mining, Chemical Processing Installation: Indoor, Outdoor, Wall-mounted, Portable Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Atlas Copco, Ingersoll Rand, Chart Industries, Aerzen, Continental Blower, Atlantic Blowers, Aeromeccanica Stranich, Twin City Fan & Blower, Howden Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Centrifugal Blower Market Emerging Trajectories
Magnetic bearing technology and advanced impeller aerodynamics are converging to eliminate mechanical wear surfaces, extending maintenance intervals from months to years in continuous-duty process applications.
Magnetic bearing systems eliminate oil lubrication and mechanical contact in high-speed centrifugal blowers, enabling direct-coupled motor operation above 20,000 RPM. Wastewater treatment utilities in Germany and the Netherlands are specifying these configurations for critical aeration trains. Oil-free operation is supplanting conventional gearbox-driven architectures in food-grade and pharmaceutical pneumatic conveying where contamination risk carries batch-rejection costs.
The EU F-Gas Regulation is restricting fluorinated greenhouse gas use in industrial equipment, compelling manufacturers to redesign sealed bearing housings and eliminate refrigerant-dependent cooling loops. Blower suppliers serving the European market must now validate alternative thermal management approaches through notified body assessment. Chemical processing clusters in Belgium and the Netherlands face the steepest compliance timelines as their national regulators enforce early adoption schedules.
Power purchase agreement structures are reshaping blower procurement in energy-intensive industries, with chemical processors and mining operators demanding guaranteed kilowatt-per-SCF performance over 10-year contract horizons. Equipment suppliers are responding with energy-performance guarantees backed by remote monitoring infrastructure. This contracting evolution is most advanced in German and US Gulf Coast petrochemical corridors where electricity constitutes 40-60% of aeration operating cost.
Centrifugal Blower Market Segmentation
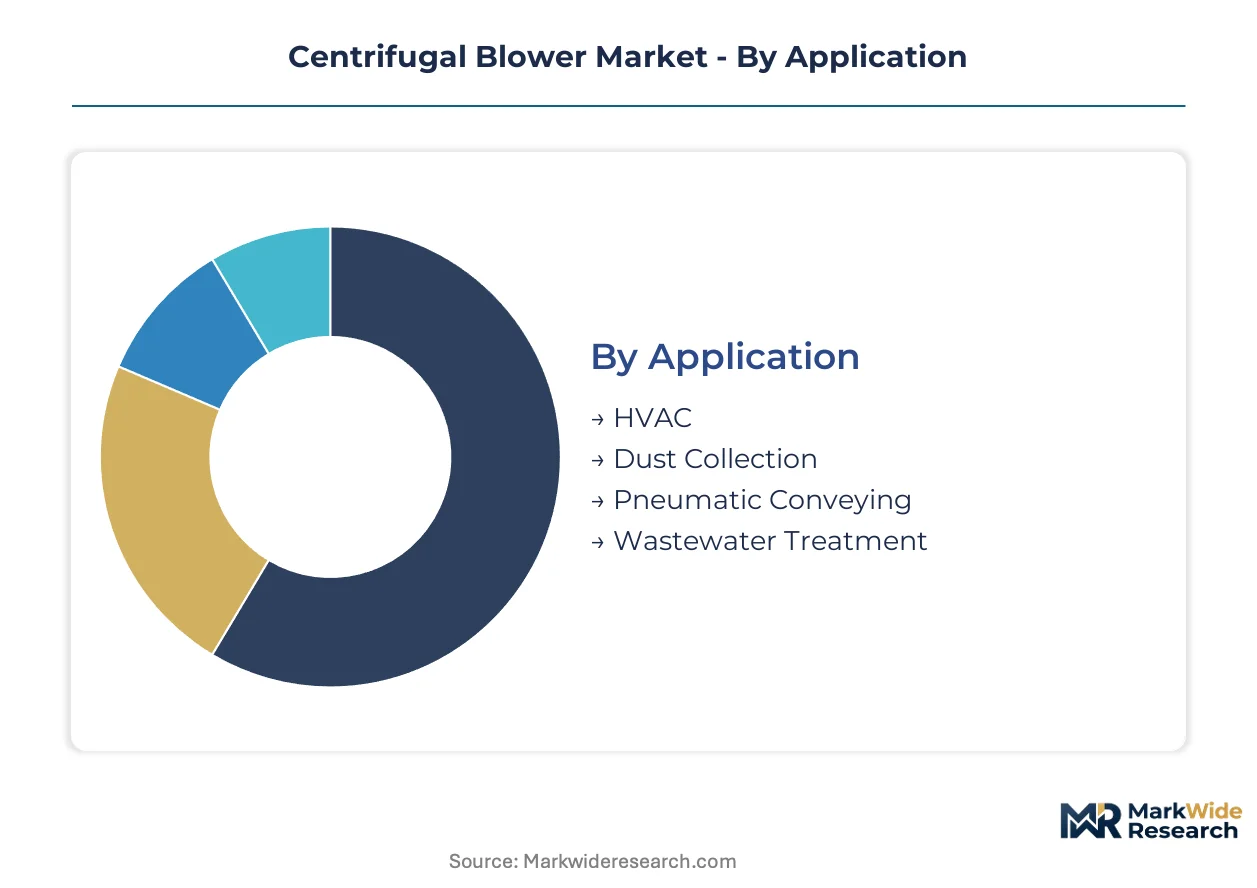
Centrifugal blower procurement channels diverge sharply by application maturity and end-user technical sophistication. Specification control sits with engineering consultants in process industries, while HVAC contractors dominate volume transactions through distributor networks.
Application:
Channel mix splits between specification-driven process sales and price-sensitive volume contracting, with divergent margin profiles across each pathway.
- HVAC:Standardized units move through mechanical contractor bidding channels where distributor stocking agreements determine specification capture. German and US commercial building retrofits sustain replacement demand for belt-drive configurations in the 5-50 kW range.
- Wastewater Treatment:Municipal procurement boards specify high-efficiency aeration blowers through engineer-procure-construct contracts where lifecycle cost analysis overrides first-cost metrics. EPA efficiency mandates accelerate variable-speed drive adoption across US municipal utilities.
- Pneumatic Conveying:Food and pharmaceutical plants require stainless-steel construction with contamination-control certifications.
- Dust Collection:Metalworking and woodworking facilities source through industrial supply distributors with filter-bundled packages.
HVAC dominates installed base. Wastewater treatment is where expansion concentrates.
End User:
Customer technical capability determines whether blowers sell as capital equipment or integrated air-system solutions.
- Chemical Processing:German Ruhr and US Gulf Coast petrochemical clusters demand precision-engineered impeller systems for process gas handling. Site reliability engineers specify magnetic bearing configurations to eliminate oil contamination risk in continuous-duty operations.
- Power Generation:Baseload plant operators prioritize mean-time-between-failures metrics over acquisition cost, creating specification stickiness for established suppliers. Combined cycle gas turbine plants require high-pressure combustion air blowers with 10-year service intervals.
- Mining:Abrasive duty cycles in underground ventilation demand specialized impeller metallurgy and dense field service networks.
- Manufacturing:General industrial users source through compressed air service providers with maintenance-inclusive contracts.
Chemical processing commands premium pricing tiers. Mining represents the steepest expansion trajectory for heavy-duty configurations.
Installation:
Physical mounting constraints dictate motor enclosure ratings, acoustic treatment, and foundation requirements that cascade through bill-of-materials cost structures.
- Indoor:Tight footprint requirements in European process plants drive demand for compact direct-drive architectures with integrated VFD packages. Acoustic enclosures add 15-25% to base equipment cost in occupied building applications.
- Outdoor:Wastewater treatment facilities in the Netherlands and Belgium specify weatherized enclosures with alternative thermal management to satisfy EU F-Gas compliance timelines.
- Wall-mounted:Commercial kitchen and laboratory ventilation applications require vibration-isolated mounting systems.
- Portable:Construction and emergency response use cases demand trailer-mounted packages with quick-connect ducting.
Indoor configurations anchor revenue stability. Outdoor specifications are climbing fastest as infrastructure projects expand.
Power Rating:
Unit scale determines manufacturing complexity, with foundry capacity and precision machining capabilities concentrating in discrete supplier tiers.
- High Power:Configurations above 500 kW serve bulk chemical and wastewater aeration projects where single-unit reliability eliminates parallel redundancy costs. Large-diameter impeller castings require specialized foundry capacity concentrated in Western European and Japanese suppliers.
- Medium Power:The most contested margin pool faces pricing pressure from Asian manufacturers competing on delivery lead times. Standardized 50-200 kW packages dominate food processing and general industrial applications.
- Low Power:HVAC and light commercial applications source through distributor channels with minimal customization.
- Ultra High Power:Custom-engineered systems for steel mill blast furnaces and cement kiln combustion air require project-specific design cycles.
Medium power holds the largest volume position. High power is expanding most quickly as project scale increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor freight rail network underwrites Germany's centrality in precision-engineered blower systems, while the US Gulf Coast petrochemical pipeline grid anchors North American demand for high-pressure process gas equipment.
United States
Municipal wastewater utilities across the Ohio River Valley are replacing aeration blowers installed during the 1970s infrastructure boom. The EPA's tightened energy efficiency standards for industrial equipment accelerate variable-speed drive adoption. Chicago and Houston engineering consultants specify magnetic bearing configurations for critical-uptime chemical processing installations.
Germany
Ruhr and Bavaria chemical processing clusters sustain premium demand for precision-engineered impeller systems in pneumatic conveying operations. The EU F-Gas Regulation compels sealed bearing redesigns and alternative thermal management validation through notified body assessment. Stuttgart-based reliability engineers specify oil-free magnetic bearing blowers to eliminate contamination risk in continuous-duty pharmaceutical production.
Netherlands
Wastewater treatment facilities in the Randstad conurbation specify weatherized outdoor enclosures with EU F-Gas-compliant thermal management. The country's national environmental regulator enforces early adoption schedules for fluorinated greenhouse gas restrictions. Rotterdam chemical processors demand energy-performance guarantees backed by remote monitoring infrastructure under 10-year power purchase agreement structures.
India
National Mission for Clean Ganga funding drives urban sewage treatment expansion across the Ganges basin. The Central Electricity Authority mandates efficiency benchmarks for municipal infrastructure equipment procurement. Maharashtra and Gujarat industrial corridors create first-mover positioning opportunities for high-efficiency aeration suppliers targeting bulk chemical projects.
China
Rare earth processing concentration in Jiangxi and Inner Mongolia exposes permanent-magnet motor supply chains to export restriction risk. The Ministry of Ecology and Environment enforces dual carbon goals that compress energy intensity benchmarks across wastewater installations. Yangtze River Delta chemical clusters drive demand for large-diameter impeller castings requiring specialized foundry capacity.
Centrifugal Blower Market Vendor Landscape
Listed leaders compete with private specialists across engineering-intensive segments where specification control determines margin capture. The vendor base splits between diversified industrial conglomerates with compressor technology heritage and focused blower fabricators with dense field service networks. Three archetypes dominate: integrated air-system architects bundling downstream treatment equipment, precision impeller specialists serving chemical process industries, and heavy-duty mining ventilation providers with abrasive-duty metallurgy expertise. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers secure foundry access and silicon carbide inverter supply.
Among European-based engineering conglomerates, Atlas Copco and Howden Group occupy positions reflecting compressor technology lineage and heavy-duty application specialization respectively. Ingersoll Rand exemplifies the integrated air-system archetype through bundled blower and treatment equipment architectures. These three companies anchor the competitive landscape without exhausting its structural variation, as regional specialists in India and China compete on delivery lead times for medium-power standardized configurations.
| Leading Market Players |
|---|
| Atlas Copco |
| Ingersoll Rand |
| Chart Industries |
| Aerzen |
| Continental Blower |
| Atlantic Blowers |
| Aeromeccanica Stranich |
| Twin City Fan & Blower |
| Howden Group |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation compliance timelines gate both supplier qualification and price differentiation simultaneously, as notified body assessment costs for sealed bearing redesigns concentrate margin capture among European incumbents while Asian manufacturers compete on delivery lead times for medium-power standardized configurations.
Pricing Analysis
Volume-discount tiering structures stratify across premium magnetic bearing configurations, standard variable-speed drive packages, and economy belt-drive units. Price differentiation rests on certification grade—ATEX and IECEx explosive atmosphere ratings command 25-40% premiums—and after-sales service bundling. Cost compression in the medium-power tier intensifies because Asian foundries undercut Western European casting costs. Municipal wastewater utilities exhibit lowest price sensitivity due to lifecycle cost procurement mandates, while HVAC contractors remain most sensitive to first-cost metrics.
Supply Chain Analysis
Rare earth processing concentration in Jiangxi and Inner Mongolia exposes permanent-magnet motor supply chains to export restriction risk. Large-diameter impeller castings draw from specialized foundry capacity concentrated in Germany, Japan, and select Western European suppliers. Silicon carbide inverter components hinge on Taiwanese and Chinese semiconductor fabrication. Single-source vulnerability in neodymium supply creates pricing volatility transmission. Distribution runs through engineer-procure-construct contractors in process industries and mechanical distributor networks in commercial HVAC.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin deployment for predictive maintenance is converting blower systems into platform-enabled assets, with remote monitoring infrastructure creating recurring revenue streams that favor ecosystem orchestrators over component suppliers.
For Market Incumbents: Fortify specification control in chemical processing clusters by deepening backward integration into precision casting capacity and magnetic bearing technology. Magnetic bearing system expertise represents a defendable moat as oil-free operation mandates expand. Incumbent suppliers must secure silicon carbide inverter supply agreements before Asian competitors capture integrated motor-blower architectures.
For New Entrants and Emerging Players: Aftermarket service density gaps in India's wastewater infrastructure expansion present white-space positioning opportunities. National Mission for Clean Ganga funding creates penetrable municipal procurement channels for high-efficiency aeration suppliers. First-mover positioning requires bundling energy-performance guarantees with remote monitoring platforms to match European incumbent contracting structures.
For Investors and Strategic Acquirers: EPA energy efficiency mandate enforcement reshapes the acquisition landscape toward variable-speed drive specialists with municipal utility relationships. Long-term viability centers on suppliers capable of 10-year energy-performance contracting. Acquisition targets should demonstrate foundry access or permanent-magnet motor integration capabilities. Watch for EU F-Gas Regulation acceleration in Belgium and Netherlands as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Permanent-Magnet Motor Integration | Silicon carbide inverter convergence enables 15-20% efficiency gains over induction systems. |
| Foundry Capacity Expansion | Large-diameter impeller casting access secures high-power project participation in chemical processing. |
| Digital Twin Deployment | Predictive maintenance platforms generate recurring revenue in critical-uptime chemical installations. |
| EU F-Gas Compliance Certification | Notified body validation opens sealed bearing redesign opportunities in Netherlands and Belgium. |
| India Market Entry Partnership | Clean Ganga funding channels create first-mover positioning in urban sewage treatment expansion. |
Methodological Framework
A standing panel of plant engineers, municipal procurement officers, aftermarket service directors, and OEM technical specification leads provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with maintenance directors at wastewater treatment facilities, reliability engineers in German chemical processing clusters, and compressed air system distributors. Secondary validation drew from EPA enforcement databases, EU ECHA substance restriction filings, customs trade data on permanent-magnet motor imports, and SEC 10-K disclosures from listed industrial conglomerates. Bottom-up unit shipment estimates triangulated against top-down energy intensity benchmarks for aeration applications.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including power rating tier, installation environment, application type, and end-user industry vertical. CAGRs were derived from unit economics modeling of replacement cycles and efficiency upgrade payback periods. Forecast inputs incorporated EPA mandate implementation timelines, EU F-Gas Regulation phase-out schedules, and India infrastructure funding disbursement patterns.
Forecasts assume regulatory continuity in EPA industrial equipment standards and EU F-Gas enforcement; material policy shifts would require re-modeling. Rare earth export restrictions, foundry capacity constraints, and municipal budget cycles represent specific risk factors that could revise projections. Practitioners should keep alternative scenarios live as dual carbon goal enforcement in China and National Mission for Clean Ganga funding velocity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Welded Spiral Heat Exchangers Market
HVAC Equipment
Hydronic Radiators Market
HVAC Equipment
Utility and Industrial Boilers Market
HVAC Equipment
Europe Heat Exchanger Market
HVAC Equipment
Heating and Cooling Market
HVAC Equipment
Industrial Boiler Market
HVAC Equipment
Refrigeration and Air Conditioning Compressors Market
HVAC Equipment
Europe HVAC Field Device Market
HVAC Equipment
Global Snow Making System Market
HVAC Equipment
North America HVAC Filter Change Service Market
HVAC Equipment
North America Gas Water Heater Market
HVAC Equipment
Germany Commercial HVAC Market
HVAC Equipment
Global Portable Evaporative Air Cooler Market
HVAC Equipment
HVAC Actuators Market
HVAC Equipment
South Korea HVAC Market
HVAC Equipment
Radiant Heating and Cooling Systems Market