
 Hydrogen ICE Ignition System Platforms Market | 2026-2036
Hydrogen ICE Ignition System Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen ICE Ignition System Platforms Market Insights
Germany is reshaping competitive dynamics in hydrogen combustion hardware as MAN Energy Solutions and DEUTZ AG anchor development clusters around Munich and Cologne. Cummins leverages its existing high-horsepower ignition expertise to compete in stationary and marine hydrogen engine contracts. MAHLE GmbH specializes in thermal management components that differentiate its platform offerings from conventional spark architectures.
Hydrogen ICE ignition system platforms are engineered subassemblies that initiate controlled combustion in hydrogen-fueled reciprocating engines, typically operating with modified spark energy profiles and electrode materials resistant to hydrogen embrittlement and pre-ignition. These systems serve industrial and commercial markets seeking lower-carbon alternatives to diesel without full powertrain electrification. Spark ignition platforms currently dominate prototype deployments due to their adaptability from natural gas engine architectures, while laser ignition technology leads R&D intensity for its potential to eliminate electrode degradation in lean-burn hydrogen cycles. Maritime propulsion applications represent the fastest-growing segment as classification societies develop interim safety protocols for hydrogen-fueled vessels.
The EU Green Deal and Euro VII standards are forcing OEMs to validate hydrogen ICE ignition systems against stricter NOx and methane slip thresholds before platform commercialization. Germany's KBA and Japan's METI have both issued preliminary type-approval pathways for hydrogen combustion engines, though final certification protocols remain under development. Stakeholders must monitor which regulator moves first on production-intent homologation standards, as this will determine where initial manufacturing scale concentrates.
Market Dynamics
Maritime classification societies are accelerating interim safety protocols for hydrogen-fueled vessels, compressing development timelines for ignition system validation while OEMs race to secure first-mover platform certifications.
Growth Catalysts
- Euro VII emission thresholds:Tightening CO2 limits for internal combustion alternatives are forcing heavy-duty fleet operators to pilot hydrogen powertrains.
- Japan's METI preliminary type-approval:Early regulatory pathways for hydrogen combustion engines are concentrating marine and on-road test bed investments.
- Laser ignition R&D intensity:Advanced ignition architectures promise elimination of electrode degradation in lean-burn hydrogen cycles.
Market Restraints
- Platinum-group metal electrode costs:Hydrogen-resistant spark plug materials face persistent input price volatility from concentrated South African and Russian supply.
- Final certification protocol delays:Germany's KBA and Japan's METI have not completed production-intent homologation standards.
- Battery-electric substitution:Zero-emission mandates in urban freight corridors favor full electrification over hydrogen combustion retrofits.
Strategic Opportunities
- Maritime propulsion segment:Classification society interim protocols are opening vessel retrofit contracts ahead of permanent codes.
- Thermal management convergence:Integration of ignition platforms with hydrogen-specific cooling architectures creates bundled platform offerings.
- Stationary power applications:Data center backup and grid-balancing installations seek lower-carbon alternatives to diesel gensets.
Industry Challenges
- Pre-ignition suppression engineering:Hydrogen's low ignition energy requires specialized combustion chamber design expertise that remains scarce.
- Legacy natural gas engine retrofit complexity:Existing spark ignition architectures demand extensive modification for hydrogen embrittlement resistance.
- Cross-border certification harmonization:Divergent KBA and METI testing protocols force redundant validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen ICE Ignition System Platforms Market |
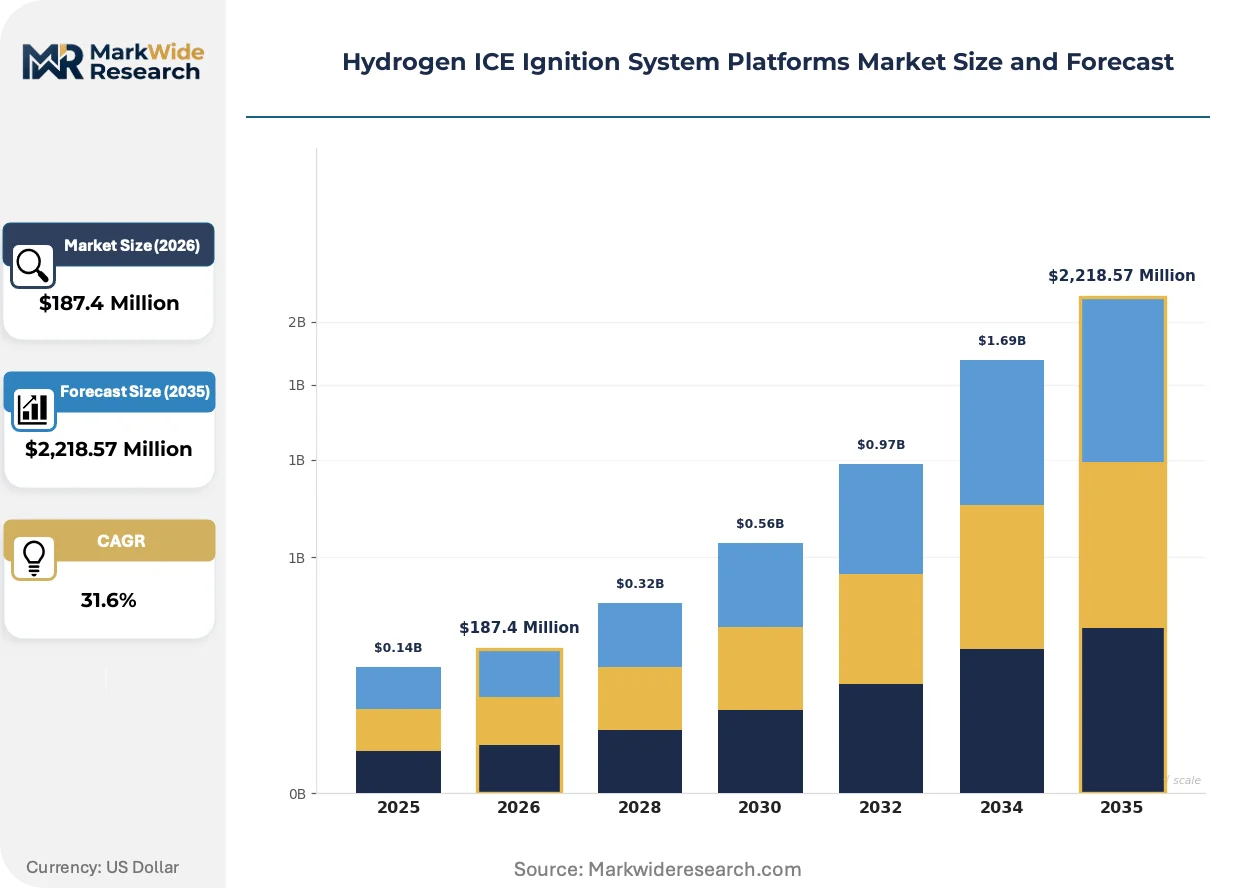
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $2,218.57 Million |
| CAGR (2026 – 2036) | 31.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Spark Ignition, Compression Ignition, Laser Ignition, Plasma Ignition Technology: Piezoelectric, Capacitive Discharge, Inductive, Dielectric Barrier Discharge, Pulse Ignition Application: Passenger Vehicles, Commercial Vehicles, Stationary Engines, Maritime Propulsion End User: OEMs, Aftermarket Suppliers, Fleet Operators, Industrial Equipment Manufacturers |
| Companies Covered | Cummins, DEUTZ AG, JCB, MAN Energy Solutions, Toyota Motor Corporation, Weichai Power, Hyundai Motor Group, Yamaha Motor, MAHLE GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen ICE Ignition System Platforms Market Trends and Innovations
Laser ignition architectures and modified spark energy profiles are collapsing traditional electrode material requirements while regulatory frameworks in Germany and Japan establish competing certification benchmarks.
Plasma-assisted ignition systems are collapsing conventional spark energy thresholds by enabling leaner combustion mixtures without misfire risk. Marine engine builders in Norway and Japan are piloting these architectures for two-stroke hydrogen conversions. The technology is collapsing the historical trade-off between NOx formation and thermal efficiency in hydrogen reciprocating engines.
The EU Green Deal's interim hydrogen combustion provisions are forcing OEMs to validate ignition platforms against evolving NOx and methane slip thresholds before commercial release. Industrial engine manufacturers face compressed timelines to secure type-approval under frameworks that remain under development. Heavy-duty commercial vehicle fleets in Germany are scaling pilot programs specifically to influence final KBA certification criteria.
Maritime operators are unbundling ignition system procurement from complete engine packages, creating direct supplier relationships previously intermediated by OEMs. Classification society pre-approval processes are accelerating this disintermediation in European and East Asian shipbuilding corridors. Specialized ignition platform vendors now contract directly with vessel operators seeking retrofit compatibility assurances.
Hydrogen ICE Ignition System Platforms Market Segmentation
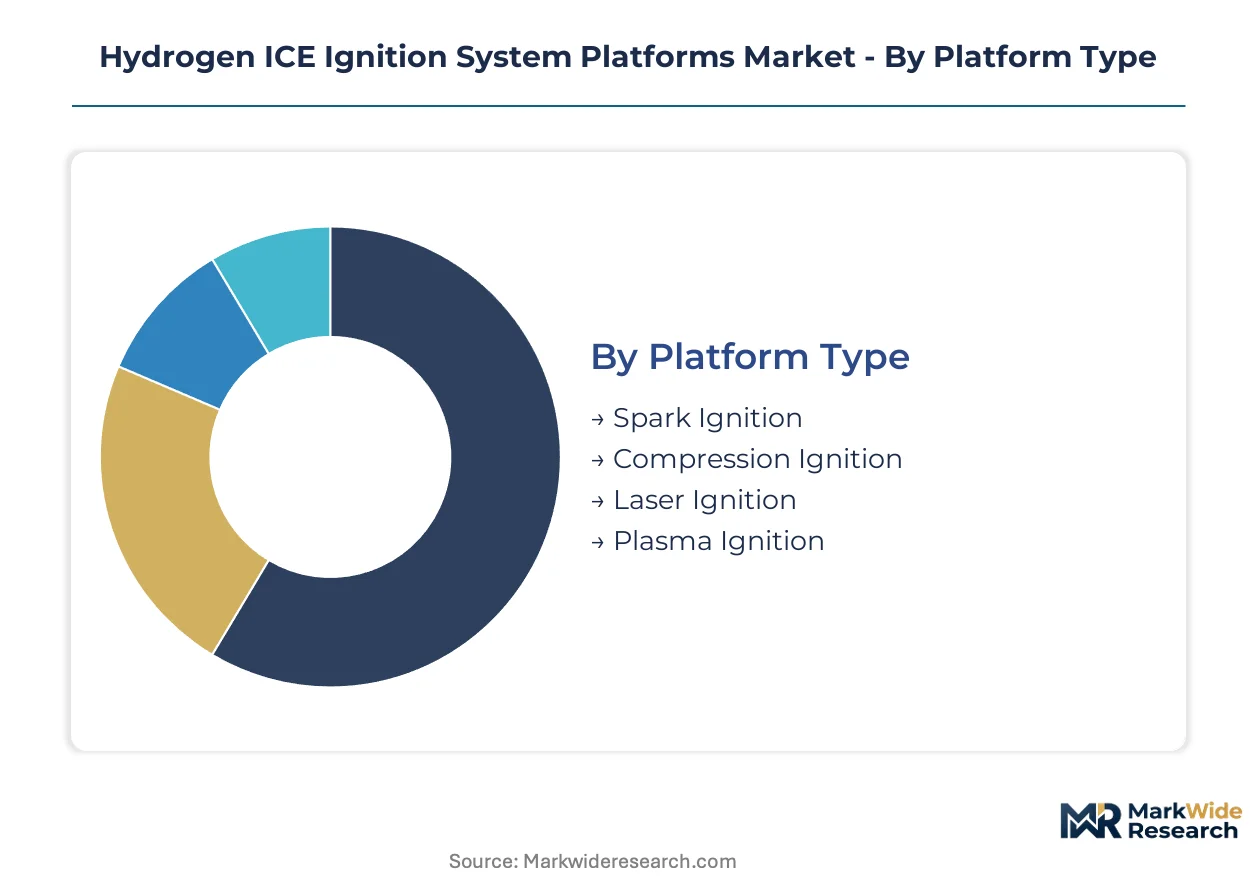
Segmentation in hydrogen ICE ignition systems determines aftermarket service protocols, spare parts inventory strategies, and technical training investments. Platform architecture choices lock in decade-long maintenance commitments for fleet operators and industrial users.
Platform Type:
After-sales service intensity varies sharply across ignition architectures, with electrode replacement cycles and diagnostic complexity driving lifetime cost divergence for operators.
- Spark Ignition:Modified electrode materials resist hydrogen embrittlement while retaining adaptability from natural gas engine foundations. German heavy-duty fleets and Japanese marine test beds concentrate prototype procurement here, though platinum-group metal costs constrain scaling.
- Laser Ignition:Solid-state optical architectures eliminate electrode degradation entirely, enabling lean-burn cycles previously impractical with spark systems. Norwegian and Japanese marine engine builders pilot these configurations for two-stroke conversions, attracted by compressed maintenance intervals.
- Compression Ignition:High-pressure direct injection demands specialized combustion chamber engineering that remains scarce among system integrators.
- Plasma Ignition:Corona discharge systems collapse conventional spark energy thresholds, permitting mixture dilution without misfire penalties.
Spark ignition holds the largest share; momentum sits with laser ignition.
Technology:
Cost tier separation in ignition electronics reflects semiconductor content, thermal packaging requirements, and calibration software sophistication.
- Piezoelectric:Crystal-based energy conversion delivers precise ignition timing with minimal electromagnetic interference. Stationary power applications in data center backup installations favor this architecture for reliability metrics.
- Capacitive Discharge:Rapid energy release profiles suit high-RPM hydrogen engines where dwell time constraints dominate. Marine propulsion retrofits in European shipyards concentrate demand here.
- Inductive:Conventional coil-based systems dominate legacy natural gas engine conversions requiring minimal control system redesign.
- Dielectric Barrier Discharge:Atmospheric plasma generation enables non-equilibrium chemistry for ultra-lean mixtures.
- Pulse Ignition:Multi-strike discharge patterns suppress pre-ignition tendencies in high-compression hydrogen cycles.
Capacitive discharge dominates premium marine contracts; piezoelectric systems are climbing fastest in stationary power.
Application:
Volume concentration tracks regulatory enforcement intensity, with emission threshold timelines determining fleet operator procurement urgency.
- Maritime Propulsion:Classification society interim safety protocols compress validation timelines while opening retrofit contracts ahead of permanent codes. Norwegian and Japanese vessel operators unbundle ignition procurement from complete engine packages.
- Commercial Vehicles:Germany's KBA preliminary type-approval pathway concentrates heavy-duty pilot programs around Munich and Cologne development clusters. Euro VII CO2 thresholds force fleet operators toward hydrogen combustion alternatives.
- Stationary Engines:Grid-balancing and data center backup installations seek lower-carbon diesel alternatives without full electrification infrastructure.
- Passenger Vehicles:Limited OEM investment reflects battery-electric dominance in light-duty zero-emission mandates.
Commercial vehicles hold the largest share; maritime propulsion shows the steepest expansion trajectory.
End User:
Customer type determines procurement authority, with direct operator relationships displacing traditional OEM intermediation in maritime and stationary segments.
- Fleet Operators:Heavy-duty commercial vehicle owners in Germany scale pilot programs specifically to influence KBA certification criteria, securing early-mover platform lock-in.
- Industrial Equipment Manufacturers:Cogeneration and prime power system integrators bundle ignition platforms with hydrogen-specific cooling architectures.
- OEMs:Engine builders retain procurement control in passenger and commercial vehicle segments where type-approval integration demands vertical coordination.
- Aftermarket Suppliers:Independent distributors capture spare electrode and controller replacement demand as installed bases mature.
OEMs hold the largest share; fleet operators are gaining procurement authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Development clusters in Germany and Japan currently anchor prototype manufacturing for hydrogen ICE ignition platforms, though regulatory momentum in Norway and pilot scaling in the United States are redrawing investment maps. Each geography brings distinct certification timelines and end-use priorities that shape platform architecture choices.
Germany
Heavy-duty fleet operators around Munich and Cologne are scaling hydrogen combustion pilot programs to influence KBA certification criteria. The EU Green Deal's interim provisions force OEMs to validate ignition systems against evolving NOx thresholds before commercial release. MAN Energy Solutions and DEUTZ AG anchor development clusters that concentrate engineering talent for stationary and marine applications.
Japan
METI's preliminary type-approval pathway has concentrated marine and on-road test bed investments from Toyota and Yamaha. The regulator's early framework is accelerating laser ignition R&D for two-stroke vessel conversions. Nagoya and Yokohama host the densest concentrations of hydrogen engine prototyping facilities.
Norway
Maritime classification society interim protocols are compressing validation timelines for vessel retrofit contracts. DNV's pre-approval processes are accelerating direct procurement relationships between vessel operators and ignition platform vendors. Bergen and Oslo development corridors specialize in plasma-assisted ignition architectures for lean-burn hydrogen cycles.
United States
Stationary power applications in Texas and California are driving demand for data center backup and grid-balancing hydrogen gensets. EPA emission thresholds for stationary engines are tightening faster than mobile source regulations, favoring early ignition platform deployment. Detroit and Houston clusters focus on capacitive discharge systems adapted from natural gas engine foundations.
China
Weichai Power's hydrogen engine program in Shandong Province is scaling pilot production for heavy-duty commercial vehicles. MIIT standards for hydrogen combustion engines remain under development, creating uncertainty for export-oriented manufacturers. Qingdao and Weifang industrial corridors concentrate thermal management component fabrication for ignition platform integration.
Hydrogen ICE Ignition System Platforms Market Competitive Landscape
Diversified engine builders and specialized ignition component suppliers split the market along vertical integration boundaries. The structure tilts toward tiered competition where full-system providers compete against modular platform vendors. Three archetypes dominate: legacy engine OEMs repurposing natural gas expertise, automotive diversifiers leveraging manufacturing scale, and dedicated hydrogen combustion specialists. M&A activity concentrates on thermal management capability acquisition, while strategic partnerships proliferate around laser ignition commercialization.
Within the legacy engine OEM tier, Cummins and DEUTZ AG exemplify players adapting high-horsepower ignition expertise to hydrogen cycles. Toyota Motor Corporation occupies a distinct position as an automotive-scale diversifier with parallel investments in fuel cell and combustion pathways. Among specialized component suppliers, MAHLE GmbH represents the thermal management integration archetype that differentiates platform offerings from conventional spark architectures.
| Leading Market Players |
|---|
| Cummins |
| DEUTZ AG |
| JCB |
| MAN Energy Solutions |
| Toyota Motor Corporation |
| Weichai Power |
| Hyundai Motor Group |
| Yamaha Motor |
| MAHLE GmbH |
| Others |
Pricing and Supply Chain Analysis
The Rotterdam-Antwerp hydrogen corridor's freight cost volatility feeds directly into ignition platform landed costs, compressing margins for European system integrators while amplifying price differentiation between platinum-group metal electrode tiers and solid-state laser architectures.
Pricing Analysis
Euro VII emission thresholds dictate the pricing tier structure across hydrogen ICE ignition platforms, separating certified pre-production systems from prototype-grade hardware. Three-tier pricing stratifies across OEM-integrated premium bundles, standalone standard platforms for fleet retrofits, and economy-tier aftermarket electrode replacements. Pricing pressure stems from persistent platinum-group metal input volatility concentrated in South African and Russian supply. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership calculations against battery-electric alternatives, while maritime classification societies prioritize certification assurance over unit economics.
Supply Chain Analysis
Platinum-group metal feedstock draws from South African mining concentrations, Russian palladium extraction, and limited North American secondary refining. Optical-grade sapphire substrates for laser ignition systems source from Japanese and Taiwanese crystal growth facilities. German thermal management component fabrication and Chinese high-voltage semiconductor packaging complete the upstream map. Single-source vulnerability concentrates in hydrogen-resistant electrode coatings, where proprietary alloy formulations remain captive to two European specialty metallurgy houses. Distribution runs through engine OEM procurement channels in commercial vehicles, with direct operator relationships displacing intermediaries in maritime and stationary power segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
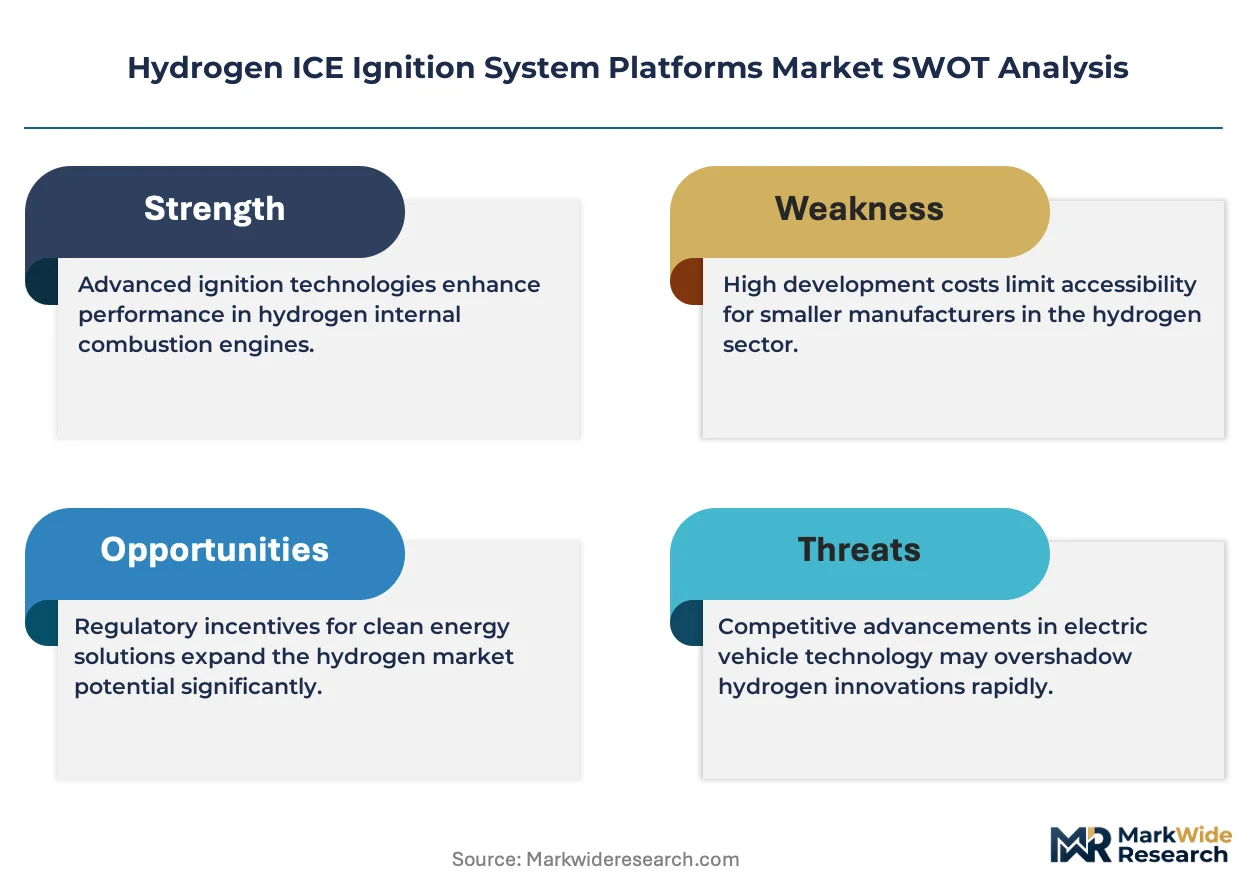
Hydrogen ICE ignition platforms constitute a switching-cost moat: fleet operators face decade-long maintenance lock-in once platform architectures are specified, while regulatory certification entrenchment raises rival entry barriers.
For Market Incumbents: Harden thermal management integration capabilities through captive supply of hydrogen-specific cooling components, defending against modular platform vendors unbundling ignition from engine packages. Deepen backward integration into platinum-group metal electrode alloy formulation to buffer input cost volatility threatening margin sustainability in spark ignition tiers. For New Entrants and Emerging Players: Stationary power applications in Texas and California data center corridors represent the most penetrable entry point, bypassing maritime classification society certification timelines that favor established suppliers. Laser ignition component subassemblies for two-stroke marine retrofits offer a second white-space target, with Norwegian vessel operators unbundling procurement from complete engine packages. A certification-partnership go-to-market angle with DNV or ClassNK accelerates credibility without full type-approval burden. For Investors and Strategic Acquirers: Specialized hydrogen combustion thermal management firms with existing OEM supply relationships anchor acquisition interest, given their irreplaceable position in bundled platform offerings. Long-term viability hinges on regulatory persistence: hydrogen combustion retains relevance only where battery-electric infrastructure gaps persist across heavy-duty and maritime duty cycles. The inflection signal to watch is KBA or METI finalization of production-intent homologation standards, which will determine manufacturing scale concentration and first-mover lock-in permanence.| Strategic Initiative | Industry Significance |
|---|---|
| Laser Ignition Commercialization Partnership | Collaboration with Norwegian marine engine builders accelerates solid-state optical architecture deployment ahead of permanent classification codes. |
| Thermal Management Capability Acquisition | MAHLE GmbH's integration model demonstrates how cooling component control differentiates platform offerings from commodity spark systems. |
| Platinum-Group Metal Alloy Supply Agreement | Long-term offtake contracts with South African refiners hedge electrode input volatility constraining spark ignition scaling economics. |
| Maritime Classification Society Pre-Approval | DNV interim safety protocol validation opens vessel retrofit contracts before permanent hydrogen-fueled vessel codes are ratified. |
| Stationary Power Pilot Deployment | Texas data center backup installations provide commercial reference sites for grid-balancing hydrogen genset ignition platforms. |
Research Methodology
A standing panel of ignition system platform engineers, maritime classification society technical reviewers, heavy-duty fleet procurement directors, and hydrogen engine R&D leads provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with these stakeholders and secondary validation against EU regulatory filings, KBA type-approval draft documents, METI hydrogen combustion engine guidelines, and maritime classification society interim protocol publications. Bottom-up platform shipment estimates triangulated against top-down hydrogen engine production forecasts across the analysis window.
Scenario bracketing framed demand projections across regulatory acceleration, baseline, and battery-electric substitution stress cases throughout the forecast period. Segmentation modeling incorporated platform type, ignition technology, application vertical, and end-user procurement authority dimensions. CAGRs were derived from fitted growth curves anchored to pilot program scaling announcements and preliminary type-approval timeline disclosures. Industry-specific inputs included platinum-group metal price trajectory assumptions and maritime classification society protocol evolution schedules.
Stress conditions across hydrogen infrastructure buildout pace, Euro VII enforcement timing, and battery-electric heavy-duty range extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory persistence and technology cost curves. Cross-checking against IEA hydrogen demand projections and OEM capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
On-Site Hydrogen Generator Market
Hydrogen Energy
Green Hydrogen Dispensing Equipment Market
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
USA Hydrogen Electrolyzer Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
India Hydrogen Market
Hydrogen Energy
Clean Hydrogen Market
Hydrogen Energy
Europe Hydrogen Generation Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Brown Hydrogen Market
Hydrogen Energy
Hydrogen Market
Hydrogen Energy
US Hydrogen Fueling Station Market
Hydrogen Energy
Hydrogen Purifiers Market
Hydrogen Energy
Hydrogen Generation Market
Hydrogen Energy
Partial Oxidation Blue Hydrogen Market
Hydrogen Energy
Hydrogen-Cooled Turbine Generator Market