
 Merchant Hydrogen Market | 2026-2036
Merchant Hydrogen Market Size, Share, and Industry Trends Forecast 2026-2036
Merchant Hydrogen Market Intelligence
The traditional dominance of refineries in merchant hydrogen consumption is rebalancing as demand from steel manufacturing and power generation intensifies. Linde plc leverages its extensive production and distribution network to serve both established and emerging applications. Air Liquide competes on the basis of large-scale project execution for low-carbon hydrogen schemes. Meanwhile, Iwatani Corporation specializes in liquid hydrogen supply chains, particularly within key Asian markets.
Merchant hydrogen is hydrogen gas produced by one entity and sold to another, typically delivered as a compressed gas or cryogenic liquid. Purity levels often exceed 99.99% to meet specifications for applications like semiconductor manufacturing or fuel cells. Grey hydrogen from steam methane reforming constitutes the largest volume, but its position is challenged by low-carbon alternatives. Green hydrogen produced via electrolysis is the fastest-growing product type, gaining traction among chemical producers and refineries.
The US Inflation Reduction Act provides significant tax credits for clean hydrogen production, directly stimulating investment. Similarly, the EU Green Deal and China's dual carbon goals establish firm targets for renewable hydrogen use in industry. The key strategic decision for suppliers and end users now centers on navigating these diverse regional incentive schemes to secure long-term supply agreements.
Market Dynamics
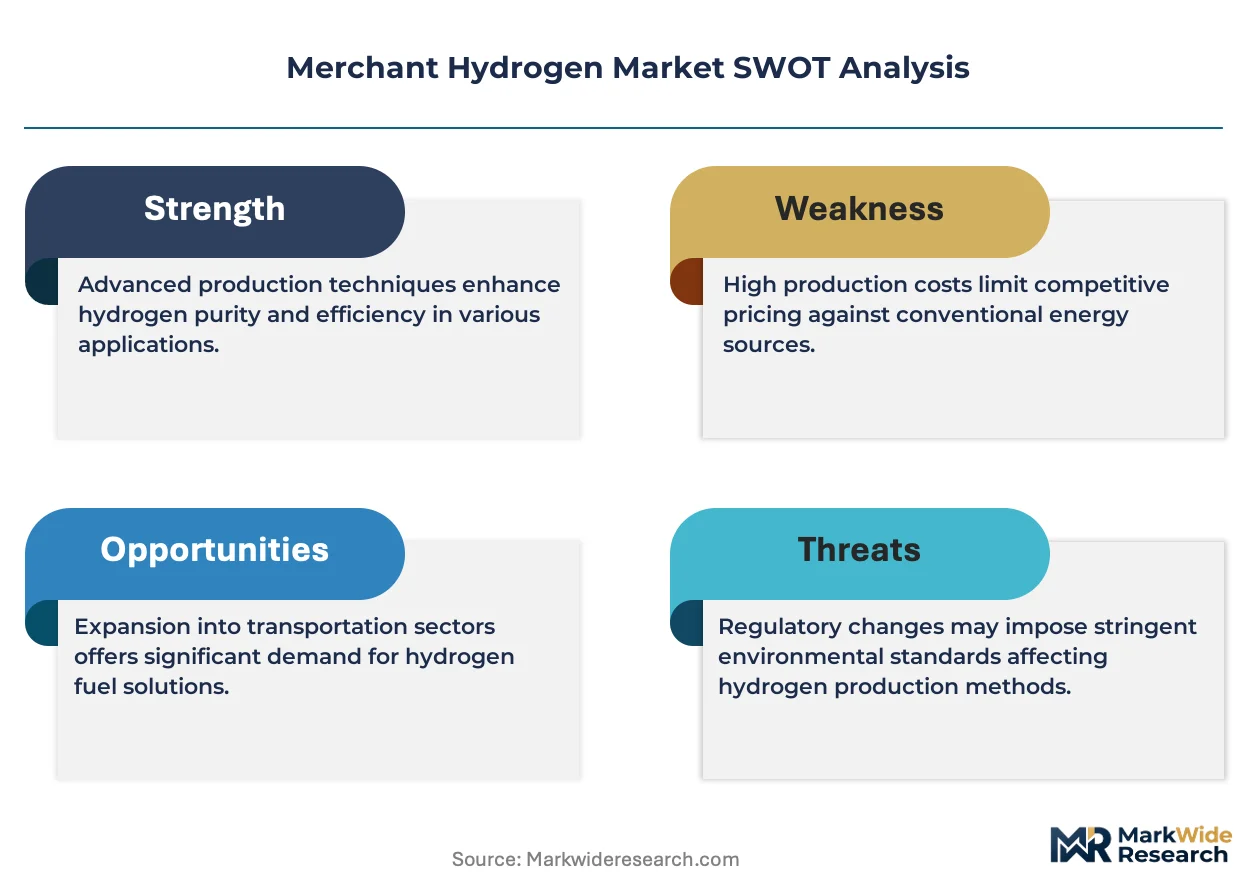
The central force shaping the merchant hydrogen market is the regulatory-driven bifurcation between traditional grey hydrogen and emerging low-carbon alternatives. Government incentives, such as the US Inflation Reduction Act, are not merely supporting green hydrogen but actively creating a distinct, premium-priced market segment.
Growth Catalysts
- Decarbonization Mandates:Demand from hard-to-abate sectors, particularly steel manufacturing and ammonia production, for low-carbon feedstocks provides a foundational catalyst for green and blue hydrogen project development.
- Supportive Regulatory Frameworks:Policies like the EU Green Deal and China's dual carbon goals establish firm targets and provide financial incentives, de-risking large-scale investments in new production capacity.
- Industrial Cluster Strategy:The development of hydrogen hubs in regions like the US Gulf Coast and Germany's North Sea coast enables shared infrastructure for production, storage, and distribution, lowering costs for multiple end-users.
Market Restraints
- High Production Costs:The cost of green hydrogen from electrolysis remains significantly higher than grey hydrogen from natural gas, dependent on volatile renewable electricity prices and electrolyzer capital costs.
- Infrastructure Deficiencies:A lack of dedicated pipelines and large-scale storage solutions for hydrogen creates logistical bottlenecks, limiting transport to compressed gas trucking or costly liquefaction for most new projects.
- Water Resource Constraints:Electrolysis requires substantial quantities of purified water, posing a significant constraint for project development in water-stressed regions suitable for solar or wind power generation.
Strategic Opportunities
- Sustainable Aviation Fuel (SAF):The use of green hydrogen as a critical feedstock for e-kerosene and other power-to-liquid SAF pathways presents a major new demand vector driven by aviation industry decarbonization targets.
- Export-Oriented Production:Geographies with abundant renewable resources, such as Australia and Chile, have the opportunity to become major exporters of green hydrogen or its derivatives like ammonia to demand centers in Asia and Europe.
- Mobility and Fueling Networks:Developing hydrogen refueling station networks for heavy-duty trucking and public transport offers a high-value application, particularly in logistics corridors and urban centers with clean air mandates.
Industry Challenges
- Project Financing Complexity:The high capital expenditure and long payback periods for large-scale low-carbon hydrogen projects require complex financing structures and long-term offtake agreements, which remain challenging to secure.
- Standardization and Certification:The absence of globally harmonized standards for defining and certifying "green" or "low-carbon" hydrogen creates market fragmentation and trade barriers, complicating international supply agreements.
- Skilled Workforce Scarcity:A shortage of engineers, technicians, and safety experts with experience in electrolysis, high-pressure systems, and cryogenic liquids is a growing bottleneck for project execution and plant operation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Merchant Hydrogen Market |
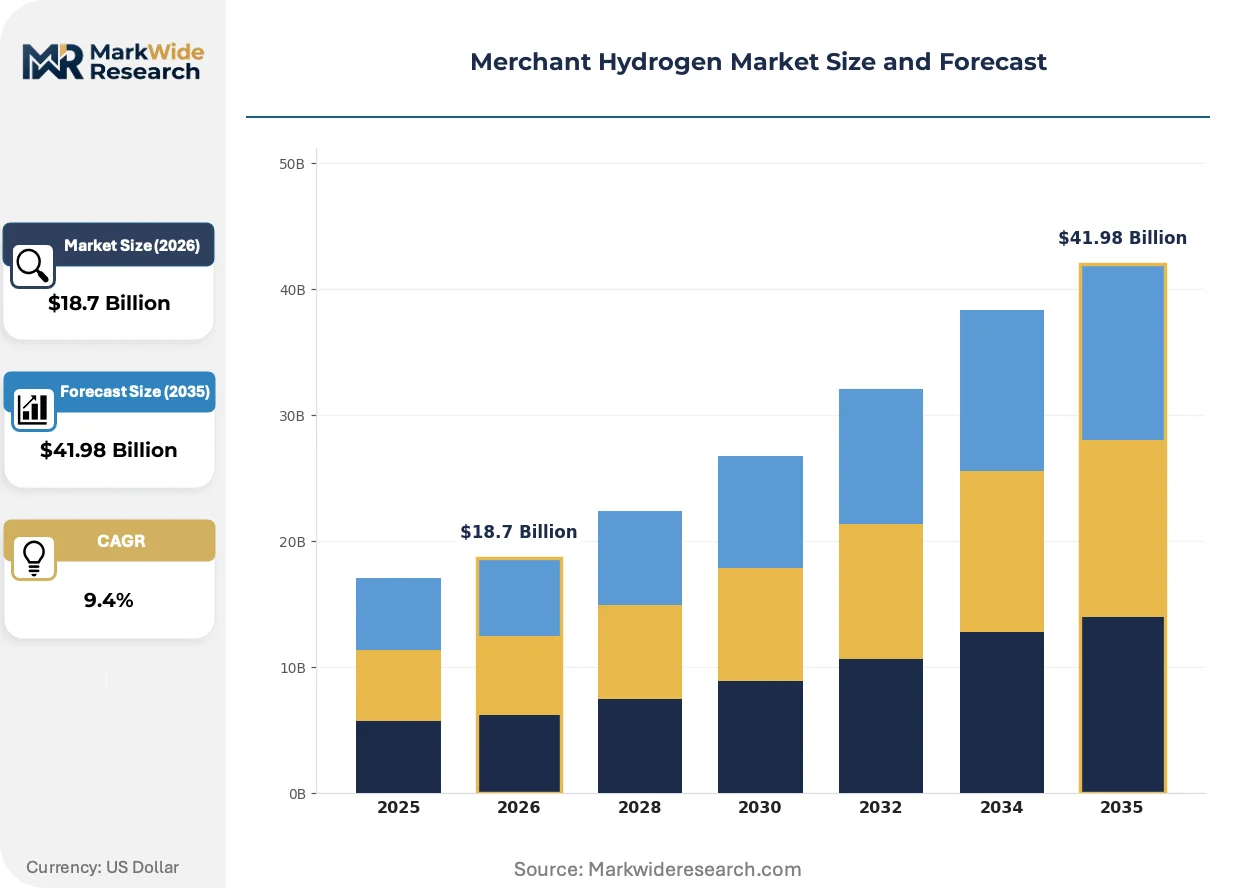
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Hydrogen, Blue Hydrogen, Grey Hydrogen, Turquoise Hydrogen Production Technology: Electrolysis, Steam Methane Reforming, Coal Gasification, Biomass Gasification Application: Refineries, Ammonia Production, Steel Manufacturing, Power Generation End User: Chemical Producers, Energy Companies, Metal Fabricators, Transportation Providers |
| Companies Covered | Linde plc, Air Liquide, Air Products and Chemicals, Inc., Messer Group GmbH, Iwatani Corporation, Plug Power Inc., TotalEnergies, Uniper SE, FuelCell Energy, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Merchant Hydrogen Market Strategic Shifts & Innovations
The convergence of advanced electrolysis technology and firm policy mandates is accelerating the transition of low-carbon hydrogen from a niche concept to a core industrial gas. This shift is creating distinct market pathways for green and blue hydrogen, fundamentally altering supply chain strategies.
Advanced Electrolyzer Deployment
Next-generation electrolysis technologies, including solid oxide and anion exchange membrane (AEM) systems, promise higher efficiency and reduced reliance on critical minerals. Industrial consumers in the chemical and refining sectors are early adopters, integrating these systems to meet both internal sustainability goals and external regulatory pressures. This high-efficiency production technology is expanding into new industrial processes like direct iron reduction for steelmaking, where scale and cost-effectiveness are paramount.
Carbon Intensity-Based Incentives
The US Inflation Reduction Act (IRA) introduces a production tax credit that is tiered based on the carbon intensity of the hydrogen produced, not the production method. This policy directly incentivizes the cleanest possible production pathways, making green hydrogen from renewables and blue hydrogen with high carbon capture rates more economically viable. The chemicals and fertilizer sectors in the US are actively re-evaluating projects to maximize these credits.
Strategic Offtake Agreements
Industrial buyers are increasingly favoring long-term, fixed-volume offtake agreements over traditional spot-market purchasing for low-carbon hydrogen. This model provides the revenue certainty needed for developers to secure financing for new, capital-intensive production facilities. This trend is most visible in Europe, where steelmakers and ammonia producers are forming partnerships with energy firms to guarantee future supply.
Merchant Hydrogen Market Segmentation
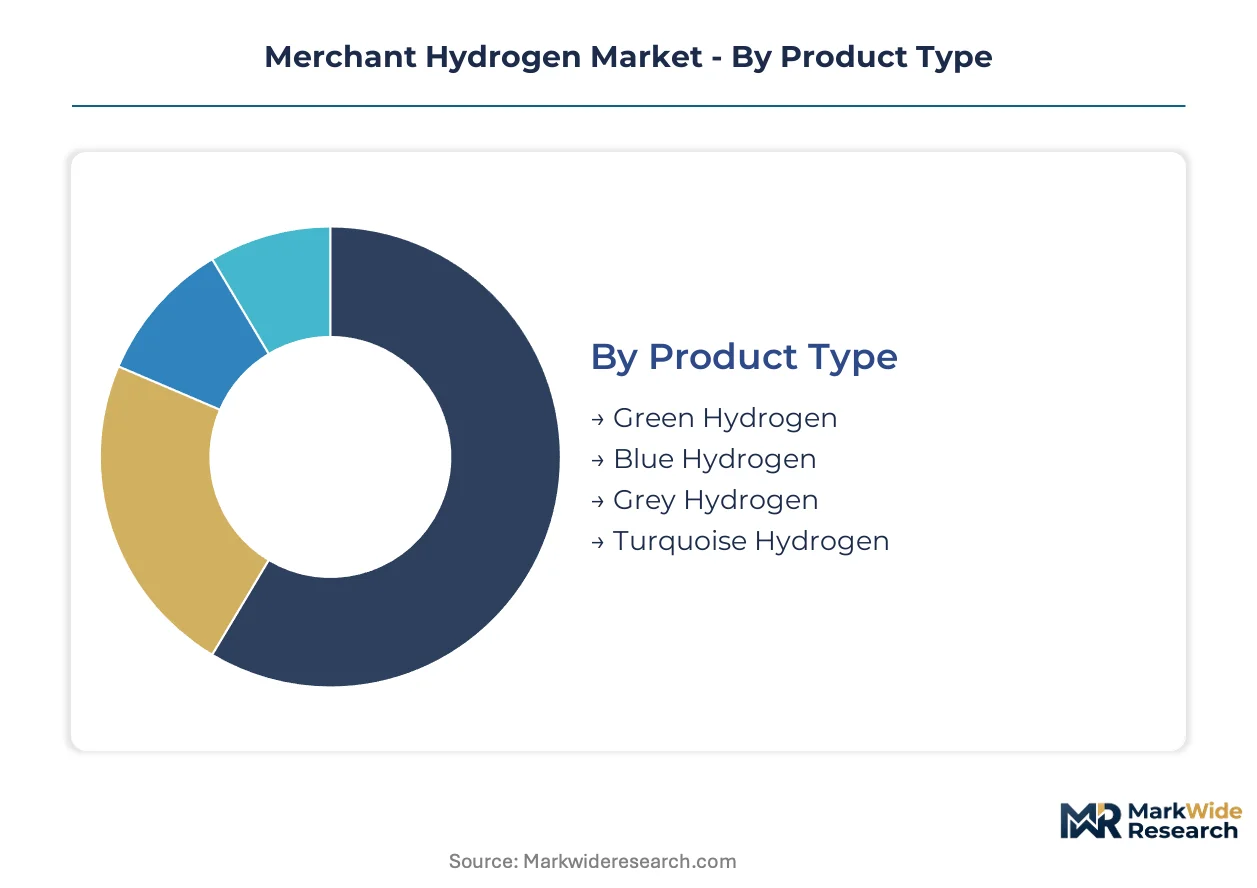
The merchant hydrogen market segments by the specific characteristics of the hydrogen product, its production method, the industrial application, and the end-user profile. Understanding these distinctions clarifies supply chain dynamics and demand patterns across diverse industrial sectors.
Product Type:
Buyers in this category differentiate based on the carbon intensity and purity specifications of the hydrogen they procure.
- Green Hydrogen:This hydrogen is produced via electrolysis, utilizing renewable electricity sources like solar or wind power, resulting in near-zero greenhouse gas emissions. Demand concentrates in European steel manufacturing and US ammonia production, driven by stringent decarbonization mandates and production tax credits.
- Grey Hydrogen:Produced primarily through steam methane reforming of natural gas without carbon capture, grey hydrogen constitutes the largest volume of merchant supply. Refineries in the US Gulf Coast and chemical producers in China rely heavily on this cost-effective feedstock for established processes.
- Blue Hydrogen:Generated from fossil fuels, typically natural gas, with carbon capture and storage technology employed to mitigate CO2 emissions. This product type offers a lower-carbon alternative for industrial clusters lacking sufficient renewable electricity.
- Turquoise Hydrogen:Produced by methane pyrolysis, which yields hydrogen and solid carbon, avoiding CO2 emissions. This emerging pathway is under development for specific industrial applications where carbon byproducts can be utilized.
Grey Hydrogen leads volumes today; Green Hydrogen is gaining share fastest.
Production Technology:
The maturity and capital intensity of hydrogen production technologies significantly influence supply availability and cost structures for purchasers.
- Electrolysis:This technology splits water into hydrogen and oxygen using an electric current, forming the backbone for green hydrogen production. Large-scale projects in Germany and Australia are deploying advanced electrolyzers to meet future industrial demand.
- Steam Methane Reforming:SMR is the most established and cost-effective method for hydrogen production, reacting natural gas with steam at high temperatures. This process supports traditional refining and ammonia production across the globe, particularly in regions with abundant natural gas.
- Coal Gasification:This method converts coal into syngas, from which hydrogen can be extracted, predominantly used in industrial complexes in China. The environmental footprint of this technology is high due to significant carbon emissions.
- Biomass Gasification:This process converts organic matter into hydrogen-rich syngas, offering a renewable pathway for hydrogen production. Smaller-scale projects are exploring this technology for localized energy systems.
Steam Methane Reforming dominates current production volumes; Electrolysis is expanding most quickly.
Application:
Hydrogen demand varies substantially across applications, driven by specific process requirements and the need for low-carbon feedstocks.
- Refineries:Hydrogen is crucial for hydrotreating and hydrocracking processes to remove sulfur and upgrade crude oil into cleaner fuels. Refineries in the US and India represent a foundational demand base for merchant hydrogen.
- Steel Manufacturing:Green hydrogen is increasingly used in direct reduced iron (DRI) processes to replace coal, significantly decarbonizing steel production. European steelmakers are forming partnerships for long-term green hydrogen supply.
- Ammonia Production:Hydrogen is a primary feedstock for the Haber-Bosch process to produce ammonia, a key component in fertilizers and chemicals. Projects in the Middle East and the US are targeting low-carbon ammonia production.
- Power Generation:Hydrogen can be used as a fuel for gas turbines or in fuel cells to generate electricity, offering a flexible energy storage and power solution. Projects in Japan are exploring hydrogen co-firing in power plants.
Refineries represent the largest application volume; Steel Manufacturing demand is climbing the fastest.
End User:
End-user segments are defined by their strategic priorities, ranging from cost optimization to decarbonization targets and regulatory compliance.
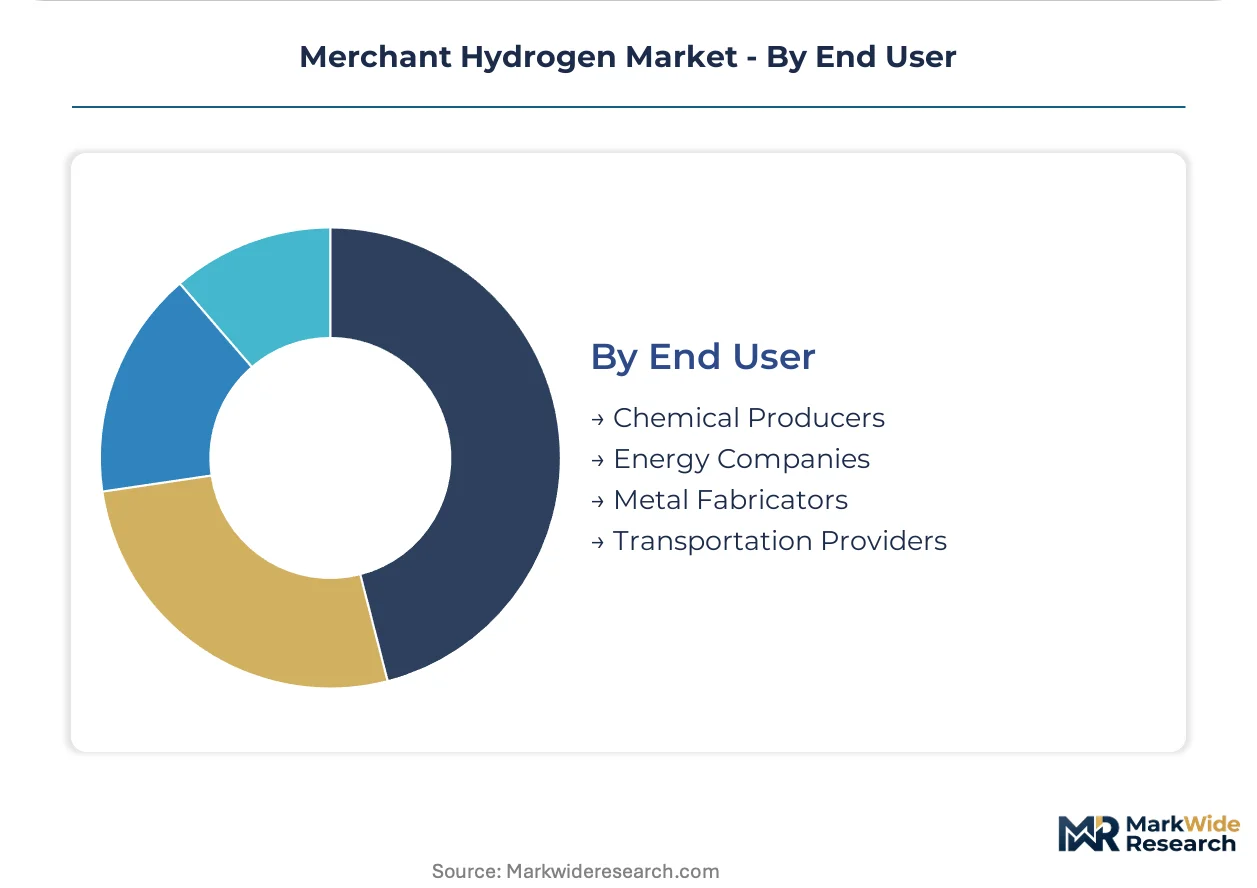
- Chemical Producers:These companies utilize hydrogen as a feedstock for various chemical syntheses, including methanol, plastics, and specialty chemicals. European chemical giants are investing in green hydrogen to meet sustainability goals.
- Energy Companies:This segment includes utilities and oil and gas firms exploring hydrogen for power generation, energy storage, or as a feedstock for synthetic fuels. Major energy firms are developing large-scale hydrogen production hubs in Australia.
- Metal Fabricators:Beyond steel, other metal industries use hydrogen for annealing, protective atmospheres, and specialized welding applications. These users often require high-purity hydrogen for their processes.
- Transportation Providers:This segment includes heavy-duty trucking, public transport, and potentially aviation and shipping, where hydrogen fuel cells offer zero-emission mobility. Hydrogen refueling networks are expanding in California and South Korea.
Chemical Producers account for significant hydrogen consumption; Energy Companies show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-driven incentives are creating a distinct market for low-carbon hydrogen, causing production to gravitate towards regions with favorable policy frameworks and abundant renewable resources. This dynamic is driving a strategic re-evaluation of supply chain locations by major industrial gas producers and end-users. The global merchant hydrogen market reflects a complex interplay of regional decarbonization goals and economic competitiveness.
United States
Demand for low-carbon hydrogen from ammonia production and refining is accelerating across the United States. The US Inflation Reduction Act provides significant production tax credits, making green and blue hydrogen projects more economically viable. The US Gulf Coast, with its existing industrial infrastructure and renewable energy potential, is seeing a concentration of new hydrogen hub developments.
Germany
Steel manufacturing and chemical producers drive Germany's growing interest in green hydrogen. The EU Green Deal and national hydrogen strategies establish firm targets for renewable hydrogen use in industry. Germany's North Sea coast is becoming a focal point for large-scale electrolysis projects, leveraging offshore wind power for hydrogen production.
China
Chemical production and coal gasification currently dominate hydrogen consumption in China. China's dual carbon goals are stimulating investment in low-carbon hydrogen pathways. Industrial complexes in provinces like Inner Mongolia and Shandong are exploring green hydrogen production to meet decarbonization mandates.
Australia
Abundant renewable energy resources position Australia as a potential major exporter of green hydrogen and its derivatives. Government initiatives support large-scale renewable hydrogen projects targeting Asian and European demand centers. Western Australia and Queensland are developing significant hydrogen production hubs for export-oriented schemes.
Japan
Power generation and mobility applications are key demand drivers for hydrogen in Japan. METI policies encourage hydrogen use for energy security and decarbonization. Projects in the Fukushima region are exploring hydrogen production for local energy systems and fuel cell vehicle infrastructure.
Merchant Hydrogen Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting the diverse requirements of the merchant hydrogen market. The competitive structure is characterized by a mix of established industrial gas majors and emerging clean energy developers. Strategic archetypes include integrated producers, technology specialists, and regional pure-plays. Companies are primarily engaging in capacity expansion and strategic partnerships to secure long-term offtake agreements.
Industrial gas giants like Linde plc and Air Liquide exemplify the integrated producer archetype, leveraging extensive production and distribution networks for both grey and low-carbon hydrogen. These firms occupy a position of scale across diverse applications, from refineries to emerging green steel projects. Iwatani Corporation, on the other hand, represents a specialized player, focusing on liquid hydrogen supply chains and mobility solutions, particularly within key Asian markets.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Messer Group GmbH |
| Iwatani Corporation |
| Plug Power Inc. |
| TotalEnergies |
| Uniper SE |
| FuelCell Energy, Inc. |
| Others |
Cost & Logistics Intelligence
Decarbonization mandates from European steelmakers are forcing a supply-side shift towards low-carbon hydrogen, creating a premium pricing segment distinct from traditional grey hydrogen. This reconfigures long-term procurement strategies.
Pricing Analysis
Distributor margins for merchant hydrogen are influenced by regional logistics costs and purity specifications. The dominant pricing structure involves contract-based long-term offtake agreements for low-carbon hydrogen, alongside commodity spot pricing for grey hydrogen. Price differentiation stems from carbon intensity certification levels and geographic delivery costs. Chemical producers buying grey hydrogen are most price-sensitive, while fuel cell manufacturers requiring certified green hydrogen show less sensitivity.
Supply Chain Analysis
Regional distribution centers for compressed hydrogen gas and cryogenic liquid hydrogen are critical, especially around industrial clusters. Production concentrates in the US Gulf Coast, Germany, and China, driven by existing infrastructure and policy. The supply chain relies on natural gas for grey hydrogen and renewable electricity sources for green hydrogen. Infrastructure deficiencies, particularly a lack of dedicated pipelines, pose a significant logistical bottleneck.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The merchant hydrogen market operates as a stable compounder, driven by the foundational and growing demand from hard-to-abate industrial sectors. Decarbonization mandates provide sustained, long-term growth.
For Market Incumbents: Deepen long-term offtake agreements with industrial end-users to secure revenue certainty against emerging low-carbon hydrogen developers. Invest in advanced electrolyzer R&D to lower green hydrogen production costs and maintain competitive positioning. Regulatory shifts favoring low-carbon alternatives pose a threat to grey hydrogen dominance. Leverage existing infrastructure and operational expertise to achieve economies of scale in new production.
For New Entrants and Emerging Players: EPC contractors offer a strategic entry point for new entrants by partnering on large-scale green hydrogen project development. Target the emerging sustainable aviation fuel (SAF) sector and localized mobility fueling networks as high-value applications. Focus on regions with abundant renewable resources like Australia for export-oriented production. Differentiate through superior project execution capabilities and strong sustainability certifications.
For Investors and Strategic Acquirers: Asymmetric upside sits with technology specialists developing highly efficient electrolyzer systems and advanced carbon capture solutions. This market offers long-term viability, driven by global decarbonization targets spanning decades. Seek out mid-cap pure-play green hydrogen developers with secured land rights and early-stage offtake agreements. The signal to watch is the consistent reduction in green hydrogen levelized cost of production (LCOP) relative to grey hydrogen.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Build new large-scale electrolysis plants in renewable-rich regions to meet future demand. |
| Green Manufacturing Transition | Convert existing grey hydrogen production facilities to blue hydrogen with carbon capture technology. |
| Long-term Supply Agreement | Secure multi-year offtake contracts with European steelmakers and US ammonia producers. |
| Joint Venture | Form partnerships with energy companies for integrated renewable power and hydrogen projects. |
| Technology Licensing | Acquire licenses for advanced electrolyzer technologies to improve production efficiency. |
Research Approach
Bottom-up industrial application modeling reconciled against top-down production capacity tracking forms the analytical core for this merchant hydrogen market study. Primary interviews with industrial gas executives, chemical plant managers, energy company strategists, and regulatory affairs specialists provided qualitative insights. Secondary validation drew from IEA reports, national hydrogen strategies, and corporate sustainability disclosures. This approach ensures robust triangulation of market dynamics.
Historical trendline analysis, coupled with future technology adoption curves, underpins the projection framework across the analysis window. Segmentation dimensions modeled include product type, production technology, industrial application, and regional policy environment. Compound annual growth rates were derived from projected production volumes and anticipated shifts in demand by end-user. Key forecast inputs incorporate electrolyzer capital costs and renewable energy prices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to evolving regulatory incentives and technological breakthroughs. Forecasts reflect assumptions documented regarding policy stability and infrastructure development. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Hydrogen Ejector Market
Hydrogen Energy
Green Hydrogen Energy Storage System Market
Hydrogen Energy
Hydrogen Station Market
Hydrogen Energy
Hydrogen Powered Engine Market
Hydrogen Energy
Hydrogen Market
Hydrogen Energy
Hydrogen Energy Electrolyzer Market
Hydrogen Energy
Green Hydrogen Market
Hydrogen Energy
Clean Hydrogen Market
Hydrogen Energy
Hydrogen Tanks Market
Hydrogen Energy
Europe Hydrogen Generation Market
Hydrogen Energy
Europe Clean Hydrogen Market
Hydrogen Energy
Electrolyzer Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Hydrogen Liquefaction Unit Market
Hydrogen Energy
Brown Hydrogen Market
Hydrogen Energy
Solar Hydrogen Panel Market