
 Asia-Pacific Clean Hydrogen Market | 2026-2036
Asia-Pacific Clean Hydrogen Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Clean Hydrogen Market Insights
Project finance structures with long-term offtake agreements and sovereign guarantee backstops is reconfiguring competitive entry in Asia-Pacific clean hydrogen. Linde plc leverages its industrial gas infrastructure to anchor large-scale electrolyzer deployments across Japan and Australia. Siemens Energy AG sustains technology leadership through proprietary proton exchange membrane stacks that dominate utility-scale project tenders. Iwatani Corporation controls Japan's hydrogen refueling network, extending its logistics dominance into ammonia cracking and liquid hydrogen transport.
Clean hydrogen comprises hydrogen gas produced with near-zero carbon intensity, typically via water electrolysis powered by renewable electricity or through steam methane reforming with carbon capture, achieving purity thresholds exceeding 99.97 percent for fuel cell applications. Its primary commercial purpose centers on decarbonizing hard-to-abate sectors where direct electrification proves technically or economically unworkable. Electrolysis capacity leads current investment flows, yet alkaline systems occupy the cost-efficient baseline while proton exchange membrane technology captures premium deployments requiring rapid response and compact footprint. Industrial processes represent the deepest demand pool today, though transportation applications are expanding fastest as heavy-duty fuel cell trucks and maritime ammonia engines achieve technical validation.
Japan's METI hydrogen roadmap, Australia's hydrogen energy supply chain framework, and South Korea's hydrogen economy implementation plan collectively establish certification standards, import infrastructure timelines, and subsidy mechanisms that determine project viability. These regulatory architectures directly shape equipment procurement specifications, cross-border trade protocols, and offtake pricing structures across the region. Stakeholders must monitor which jurisdiction's certification regime achieves regional interoperability first, as this will determine hub dominance and equipment sourcing patterns.
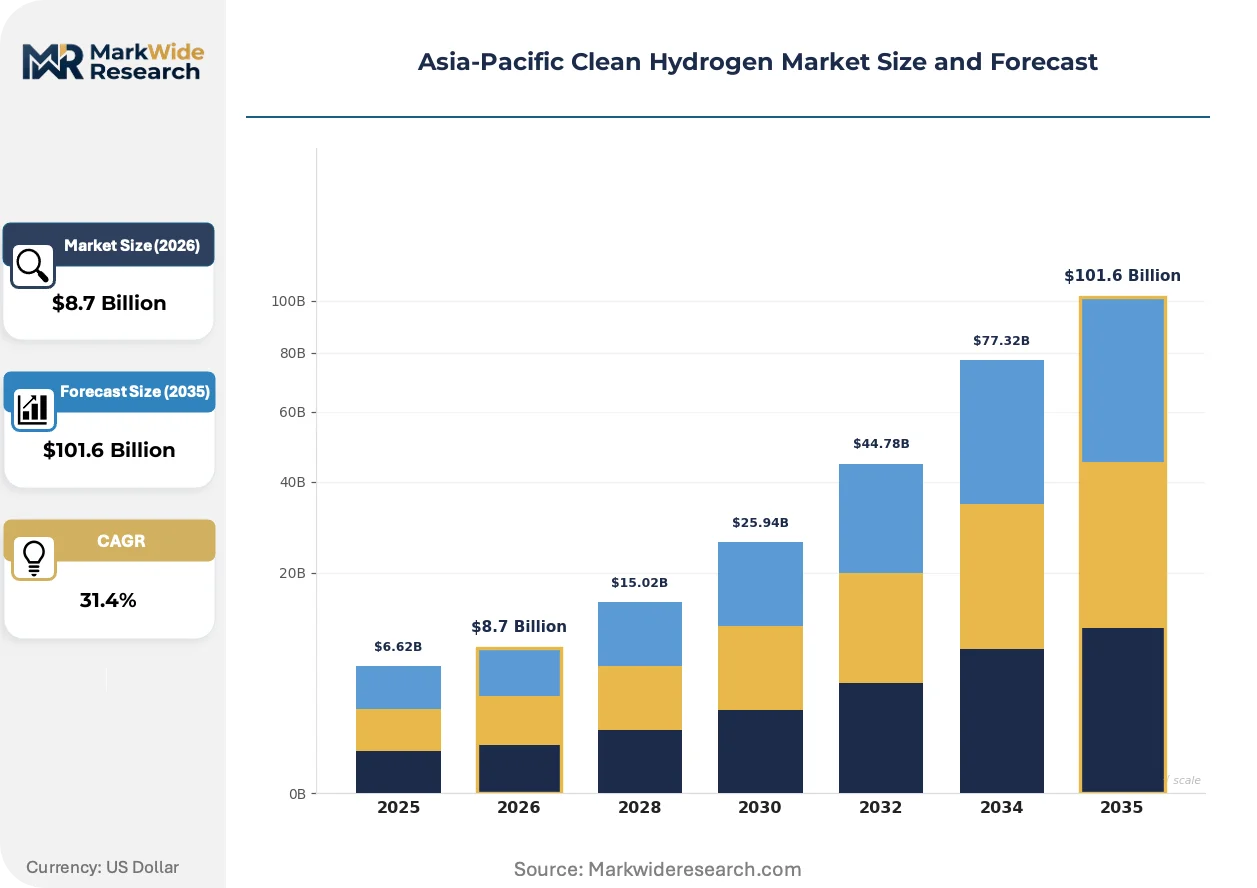
Market Dynamics
Japan's METI hydrogen roadmap and Australia's hydrogen energy supply chain legislation are compressing project development timelines by mandating certification standards and import infrastructure specifications that reshape equipment procurement and offtake contracting across the region.
Growth Catalysts
- Australia's hydrogen energy supply chain framework:This legislation provides sovereign guarantee backstops that de-risk capital deployment for export-scale electrolysis projects in Pilbara and Queensland.
- Steel decarbonization in Japan and South Korea:Steelmakers are scaling hydrogen direct reduction furnaces that displace coking coal, creating anchor demand for industrial-scale clean hydrogen supply.
- Proton exchange membrane technology:Rapid-response electrolyzer stacks capture premium utility-scale tenders where compact footprint and grid-balancing capabilities command price premiums over alkaline systems.
Market Restraints
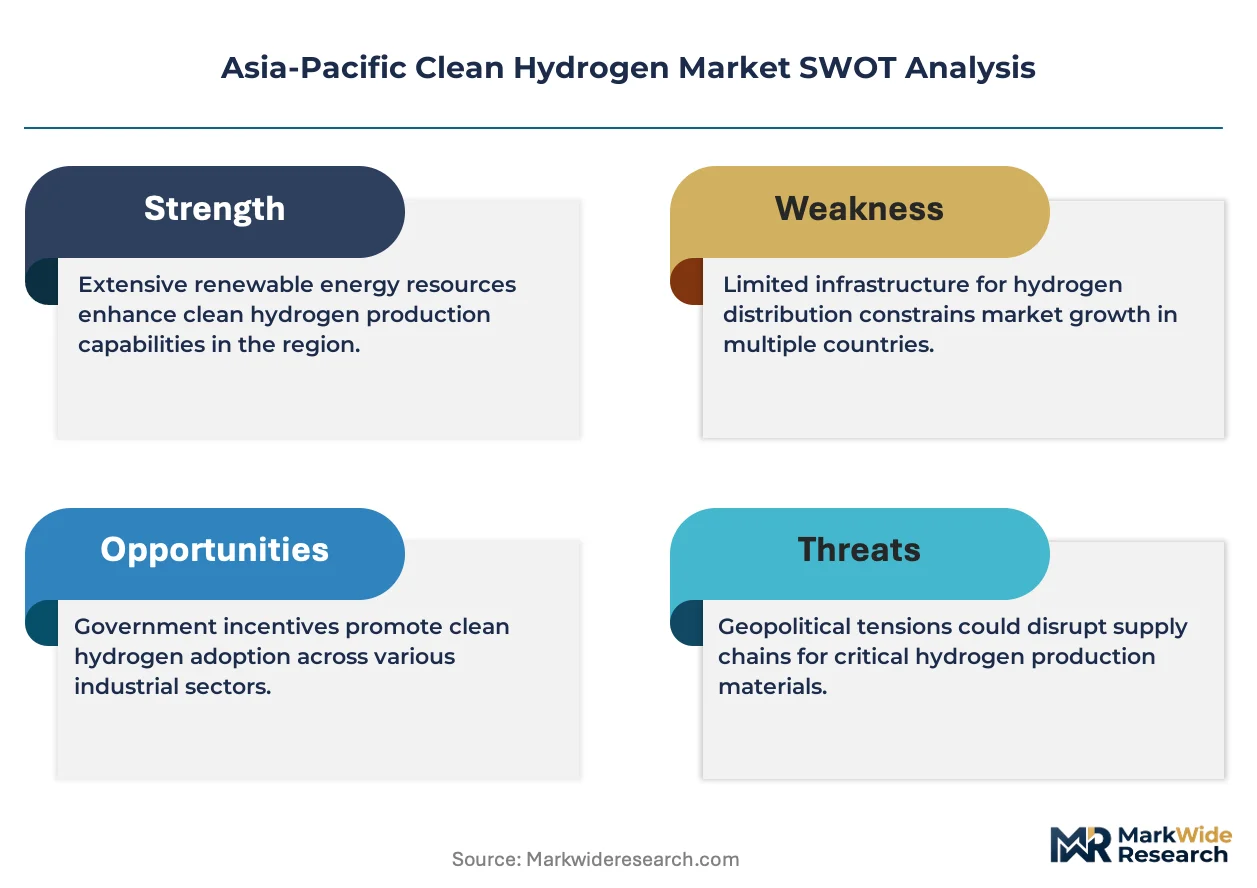
- Renewable electricity cost volatility:Intermittent solar and wind output in Australian hydrogen hubs forces oversized electrolyzer capacity or battery buffering, inflating levelized hydrogen costs.
- Equipment supply concentration:Proton exchange membrane stack manufacturing concentrates in European and Japanese industrial gas specialists, creating procurement bottlenecks for regional developers.
- Liquid hydrogen boil-off rates:Cryogenic transport losses of 0.5-1% per day constrain maritime export economics to short-haul routes between Australia and Japan.
Strategic Opportunities
- South Korea's hydrogen economy implementation plan:Subsidy mechanisms for fuel cell trucks and maritime ammonia engines are opening transportation applications that outpace industrial demand growth rates.
- Ammonia cracking infrastructure:Japan's port terminals are retrofitting for ammonia-to-hydrogen reconversion, enabling hydrogen import without cryogenic liquid transport.
- Alkaline-PEM hybrid systems:Technology convergence pairs cost-efficient alkaline baseload capacity with PEM rapid-response modules, optimizing capacity factors against renewable profiles.
Industry Challenges
- Electrolyzer commissioning timelines:First-of-a-kind utility-scale installations in Queensland and Western Australia face 18-24 month startup delays due to sparse local commissioning expertise.
- Cross-border certification interoperability:Divergent purity specifications between Japan's METI standards and Australia's emerging hydrogen certification create friction in bilateral offtake contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Clean Hydrogen Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $101.6 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolysis, Steam Methane Reforming, Biomass Gasification, Others End User: Transportation, Industrial Processes, Power Generation, Others Technology: Alkaline, Proton Exchange Membrane, Solid Oxide, Others Deployment: Onshore, Offshore, Distributed Generation, Centralized Generation |
| Companies Covered | Linde plc, Air Liquide, Air Products and Chemicals Inc., Mitsubishi Heavy Industries, Siemens Energy AG, Taiyo Nippon Sanso Corporation, Iwatani Corporation, Ballard Power Systems, Plug Power Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Clean Hydrogen Market Trends and Innovations
Electrolyzer control systems and hydrogen logistics platforms are digitizing operational workflows that previously relied on manual monitoring and fragmented data silos across production, storage, and transport nodes.
Digital twin software for electrolyzer fleets is digitizing predictive maintenance protocols that anticipate membrane degradation and stack replacement cycles. Japanese utilities deploying these platforms at 100MW-plus sites report compressed unplanned downtime intervals. The structural consequence is shifting competitive advantage from equipment manufacturers to integrated asset operators with proprietary algorithmic optimization.
South Korea's hydrogen economy implementation plan mandates fuel cell truck deployment quotas and maritime ammonia engine trials that redirect R&D subsidies toward transportation end-uses. Industrial process applications retain deeper absolute volumes but capture shrinking shares of new public funding. Steelmakers and chemical producers are responding by forming consortiums to defend their eligibility for green innovation fund allocations.
Long-term offtake contracting is displacing spot-market exposure as the dominant procurement model for hydrogen offtakers. Japanese steelmakers and South Korean petrochemical complexes now require 10-15 year take-or-pay structures before committing to greenfield supply investments. This behavioral shift concentrates counterparty risk assessment capabilities among a narrow tier of investment-grade buyers, marginalizing smaller industrials without balance sheet depth in Australia and Southeast Asia.
Asia-Pacific Clean Hydrogen Market Segmentation
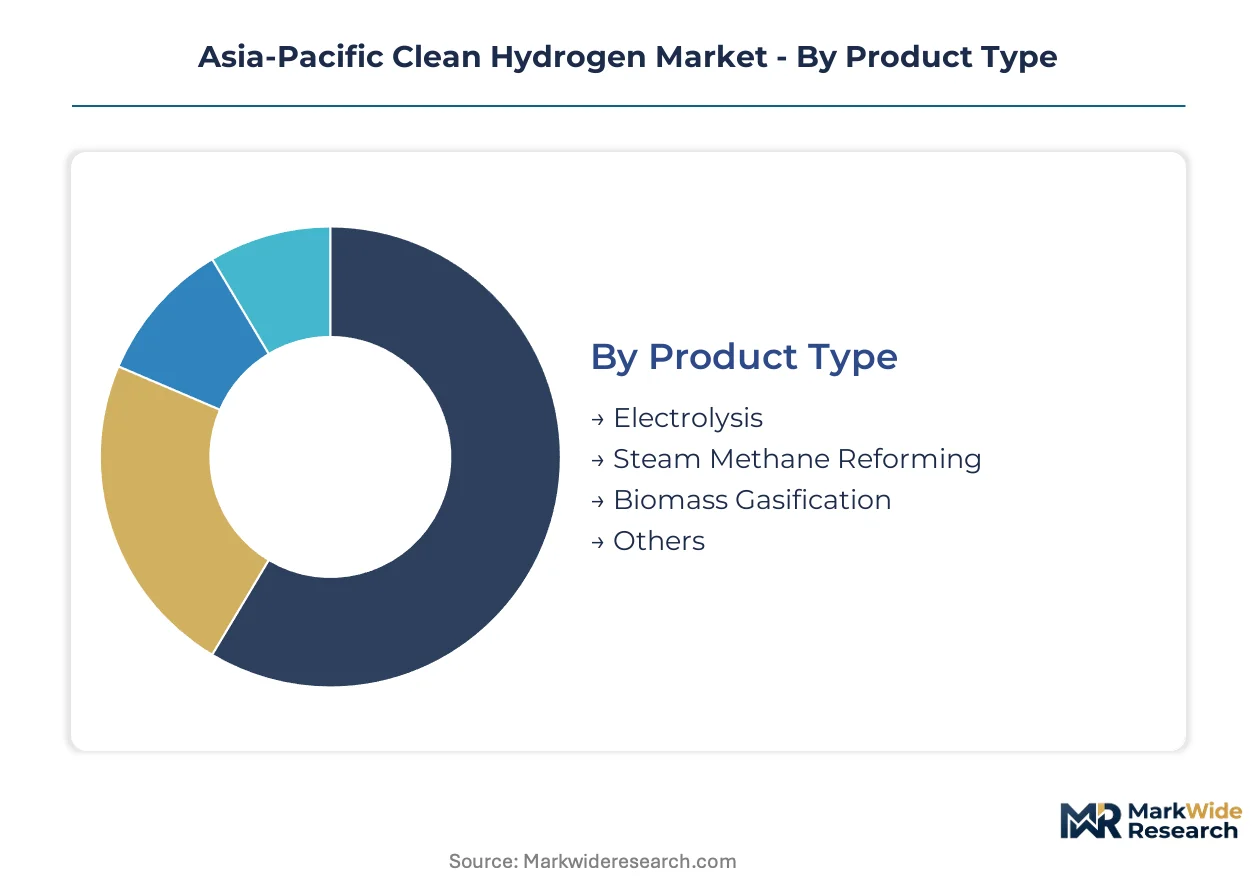
Segmentation in Asia-Pacific clean hydrogen reveals how production pathways, end-use applications, and technology choices determine project economics and equipment procurement patterns. Distinct deployment models across Australia's export hubs versus Japan's import infrastructure create divergent investment profiles.
Product Type:
After-sales service intensity varies sharply across production pathways, with electrolysis requiring membrane replacement protocols and SMR plants demanding catalyst regeneration cycles.
- Electrolysis:Water splitting via renewable-powered electrolyzers yields purity exceeding 99.97 percent for fuel cell applications. Demand concentrates in Australia's Pilbara and Queensland hubs, where solar and wind resources support export-scale deployments, though commissioning delays of 18-24 months strain project timelines.
- Steam Methane Reforming:Natural gas reforming paired with carbon capture achieves lower capital costs than electrolysis but depends on CO2 storage geology. South Korean steelmakers and Japanese petrochemical complexes favor this pathway for near-term decarbonization where pipeline hydrogen infrastructure remains undeveloped.
- Biomass Gasification:Organic feedstock conversion with carbon capture offers negative-emission hydrogen production.
- Others:Emerging thermochemical and photoelectrochemical pathways remain pre-commercial in regional deployment.
By volume, steam methane reforming leads. By growth pace, electrolysis is expanding most quickly.
End User:
Cost tier differentiation separates industrial offtakers with 10-15 year contracting capacity from transportation players seeking shorter payback periods.
- Industrial Processes:Steel direct reduction furnaces and ammonia synthesis represent the deepest demand pool today. Japanese steelmakers scaling hydrogen DRI installations and South Korean petrochemical complexes drive anchor offtake volumes requiring continuous supply reliability.
- Transportation:Heavy-duty fuel cell trucks and maritime ammonia engines are climbing the fastest. South Korea's hydrogen economy implementation plan mandates fuel cell truck deployment quotas, while Japan's port terminals retrofit for ammonia bunkering infrastructure.
- Power Generation:Hydrogen-fired turbines and fuel cell power plants serve grid-balancing applications.
- Others:Residential heating and synthetic fuel production occupy niche positions in regional deployment.
Industrial processes dominate absolute volumes. Transportation applications gain share fastest as public funding redirects toward mobility end-uses.
Technology:
Margin structures favor proton exchange membrane stacks commanding price premiums, while alkaline systems compete on levelized cost in baseload configurations.
- Alkaline:Liquid electrolyte systems using potassium hydroxide achieve lowest capital cost per megawatt and dominate Australian export-scale projects. Queensland and Western Australian developers pair oversized alkaline capacity with battery buffering to manage renewable intermittency.
- Proton Exchange Membrane:Solid polymer electrolyte stacks enable rapid response and compact footprint for utility-scale tenders. Japanese utilities deploying 100MW-plus sites report compressed unplanned downtime through digital twin optimization.
- Solid Oxide:High-temperature ceramic electrolysis achieves superior efficiency where waste heat integration is feasible.
- Others:Anion exchange membrane and reversible fuel cell technologies remain developmental in regional supply chains.
Alkaline technology leads installed capacity. Proton exchange membrane is gaining share fastest in premium utility tenders.
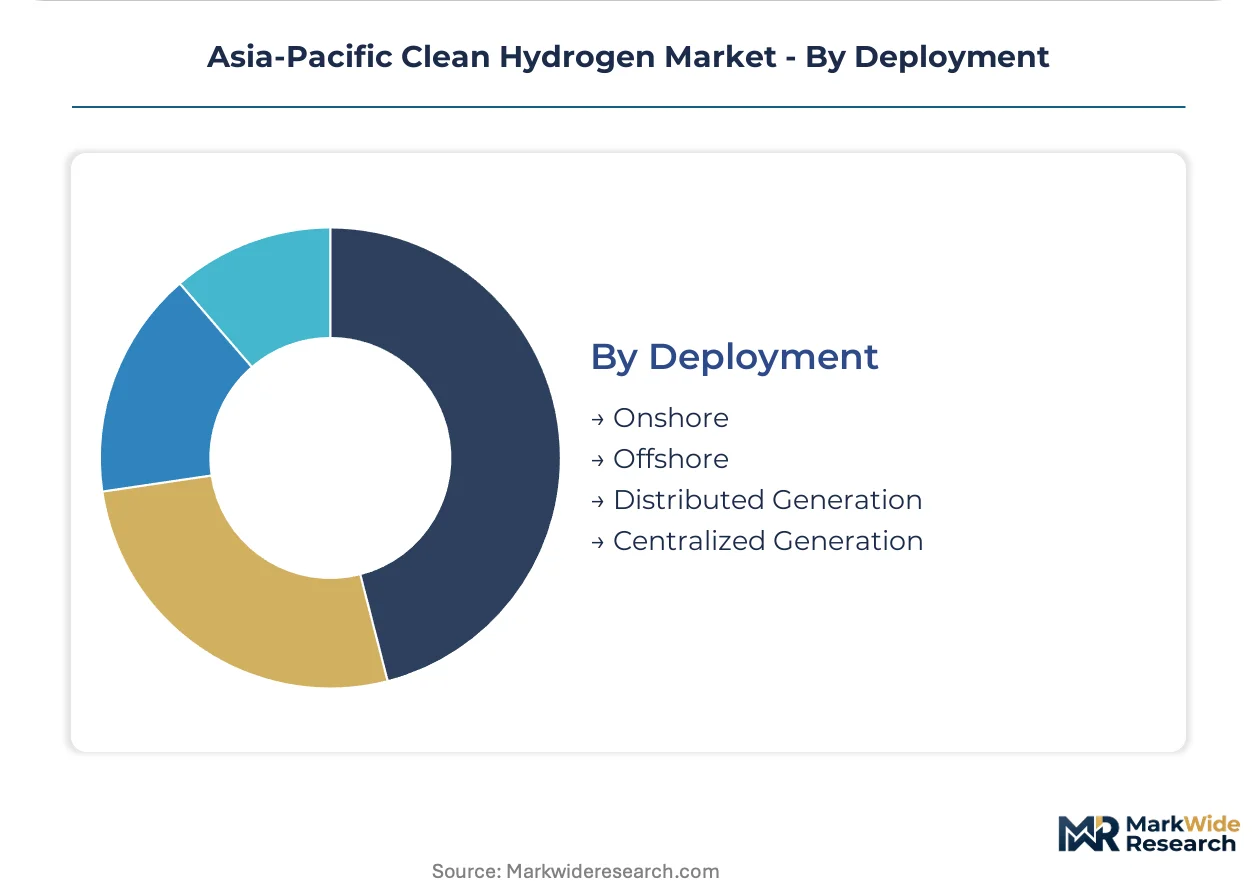
Deployment:
Supply concentration dictates whether projects cluster at centralized export terminals or distribute across demand centers.
- Centralized Generation:Gigawatt-scale electrolyzer arrays co-located with renewable generation and port infrastructure. Australia's hydrogen energy supply chain legislation underpins sovereign-guaranteed project finance for Pilbara and Queensland export hubs serving Japanese offtakers.
- Distributed Generation:Modular electrolyzer installations at industrial demand sites reduce transport costs. Japanese steelworks and South Korean fuel cell truck depots favor this model where pipeline hydrogen networks remain undeveloped.
- Onshore:Terrestrial installations dominate current investment flows across all production pathways.
- Offshore:Floating electrolyzer platforms and ammonia production vessels remain pre-commercial in regional waters.
Centralized generation leads capital deployment. Distributed generation is climbing fastest as industrial offtakers seek supply security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented production in Australia's Pilbara and Queensland hubs contrasts with import-dependent demand centers in Japan and South Korea, creating a bilateral trade architecture that concentrates infrastructure investment along Australia-Japan maritime corridors. Sovereign guarantee mechanisms and certification standard harmonization between METI and Australia's hydrogen energy supply chain framework determine project bankability across this corridor.
Australia
Pilbara and Queensland hydrogen hubs anchor export-scale electrolyzer deployments powered by solar and wind resources. The hydrogen energy supply chain legislation provides sovereign guarantee backstops that de-risk capital deployment for gigawatt-scale projects. Western Australian developers face 18-24 month commissioning delays due to sparse local expertise, compressing first-mover advantages for early entrants.
Japan
Steelmakers scaling hydrogen direct reduction furnaces and port terminals retrofitting for ammonia cracking drive anchor demand for imported clean hydrogen. METI's hydrogen roadmap mandates certification standards and import infrastructure timelines that reshape equipment procurement specifications. Kansai and Chubu industrial corridors concentrate hydrogen DRI investments as steelmakers displace coking coal.
South Korea
Steel decarbonization and fuel cell truck deployment quotas create dual demand anchors for industrial and transportation hydrogen. The hydrogen economy implementation plan subsidizes maritime ammonia engine trials and heavy-duty fuel cell vehicles, redirecting public R&D funding toward mobility end-uses. Busan-Ulsan petrochemical complexes and Seoul Capital Area fuel cell depots represent the densest demand clusters.
China
Dual carbon goals and provincial hydrogen industry plans accelerate electrolyzer manufacturing scale-up for domestic and export markets. Yangtze River Delta and Pearl River Delta industrial zones concentrate alkaline electrolyzer production capacity serving regional steel and chemical decarbonization. MIIT technology roadmaps prioritize proton exchange membrane stack localization to reduce import dependence.
Asia-Pacific Clean Hydrogen Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream, supplying membrane stacks, catalyst coatings, and balance-of-plant equipment to project developers. Market structure concentrates around industrial gas conglomerates with existing hydrogen infrastructure, electrolyzer OEMs with proprietary stack technology, and regional utilities leveraging offtake relationships. Three archetypes dominate: integrated gas suppliers bundling production and logistics, pure-play electrolyzer manufacturers competing on capital cost per megawatt, and project developers securing sovereign-backed offtake contracts. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing renewable power purchase agreements and port terminal access rights.
Within the integrated gas supplier tier, Linde plc and Air Liquide exemplify archetypes that leverage existing industrial hydrogen infrastructure to anchor electrolyzer deployments and logistics networks. Siemens Energy AG occupies a position representing proprietary technology specialists, with its proton exchange membrane stack offerings capturing premium utility-scale tenders. Iwatani Corporation sits within the regional logistics anchor archetype, extending industrial gas distribution dominance into ammonia cracking and liquid hydrogen transport infrastructure across Japanese demand centers.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Air Products and Chemicals Inc. |
| Mitsubishi Heavy Industries |
| Siemens Energy AG |
| Taiyo Nippon Sanso Corporation |
| Iwatani Corporation |
| Ballard Power Systems |
| Plug Power Inc. |
| Others |
Pricing and Supply Chain Analysis
Queensland's gigawatt-scale electrolyzer clusters concentrate production capacity and compress regional hydrogen pricing through economies of scale that smaller distributed installations cannot match. Japanese steelmakers and South Korean petrochemical complexes leverage this supply concentration to negotiate long-term offtake contracts with embedded price ceilings.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake pricing structure that dominates procurement between Australian producers and Northeast Asian offtakers. Price differentiation rests on certification grade under METI's hydrogen roadmap versus Australia's emerging standards, alongside volume scale commitments that unlock tiered discounts. Cost compression in alkaline electrolyzer tiers is intensifying because Chinese manufacturing scale is flooding component markets. Small-scale distributed generators in Japan exhibit highest price sensitivity due to underdeveloped pipeline infrastructure forcing liquid hydrogen transport premiums.
Supply Chain Analysis
Electrolyzer contract manufacturing concentrates with Siemens Energy AG and Linde plc holding proprietary proton exchange membrane stack capacity, while Chinese alkaline system producers dominate cost-efficient baseload segments. Geographic supply concentration centers on Germany, Japan, and China for membrane stacks and catalyst coatings. Raw material dependencies draw from iridium for PEM anodes, nickel mesh for alkaline cells, and fluoropolymers for membrane substrates. Single-source vulnerability in iridium sourcing from South African platinum group metal mines threatens stack production timelines. Distribution runs through port terminal ammonia cracking facilities and cryogenic liquid hydrogen vessels along Australia-Japan maritime corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates sticky offtake relationships that new entrants cannot easily replicate. Sovereign guarantee frameworks and certification standard harmonization between METI and Australian hydrogen energy supply chain legislation embed switching costs for established players.
For Market Incumbents: Insulate market position by deepening backward integration into iridium and platinum group metal recycling to secure catalyst supply chains against South African mining disruptions. Expand electrolyzer commissioning expertise through captive training programs in Queensland and Western Australia to compress 18-24 month startup delays that erode first-mover returns. Lock in channel control by acquiring ammonia cracking terminal access rights at Japanese ports before infrastructure saturation. For New Entrants and Emerging Players: Build out modular alkaline-PEM hybrid system offerings targeting South Korean fuel cell truck depots where distributed generation demand outpaces supply. The most penetrable white space sits in ammonia bunkering infrastructure for maritime applications, where Japan's port terminal retrofit timelines lag South Korea's hydrogen economy implementation plan mandates. A go-to-market angle anchored in after-sales membrane replacement service contracts bypasses capital-intensive equipment sales barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated asset operators with proprietary digital twin platforms for electrolyzer fleet optimization. Long-term viability across the projection horizon favors acquisition targets with secured renewable power purchase agreements in Pilbara or Queensland and validated offtake contracts with investment-grade Japanese steelmakers. The signal to watch as inflection indicator is cross-border certification interoperability between METI and Australian standards, which would unlock bilateral contract velocity and re-rate hub economics.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Japanese steelmakers require 10-15 year take-or-pay structures before committing to greenfield hydrogen investments. |
| Backward Integration | Control over iridium catalyst recycling secures PEM stack production against South African mining supply disruptions. |
| Green Certification Program | METI-Australia certification harmonization determines which hydrogen hubs achieve regional interoperability first. |
| Capacity Buildout | Gigawatt-scale electrolyzer deployments in Queensland leverage sovereign guarantee backstops to de-risk capital deployment. |
| Technology Licensing | Proton exchange membrane stack licensing to Chinese manufacturers accelerates cost compression in premium utility tenders. |
Research Methodology
A spread of perspectives from electrolyzer OEM technical directors, Japanese utility hydrogen procurement officers, Australian project finance lenders, South Korean steelmaker decarbonization leads, and Singapore-based maritime ammonia traders converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through METI hydrogen roadmap filings, Australia's hydrogen energy supply chain legislation documents, IEA hydrogen project databases, and customs trade data for electrolyzer component flows. Bottom-up electrolyzer capacity build-up and top-down demand modeling from steel DRI and fuel cell truck deployment quotas were triangulated against sovereign guarantee commitment announcements.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with electrolyzer manufacturing capacity, renewable power purchase agreement execution, and port terminal ammonia cracking infrastructure build-out tracked as binding constraints. Segmentation dimensions modeled encompassed production pathway, end-use application, technology choice, and deployment configuration alongside regulatory framework cluster. CAGRs were derived from installed capacity ramp schedules and offtake contract velocity. Industry-specific forecast inputs included electrolyzer learning curve cost reductions and maritime ammonia engine trial outcomes under South Korea's hydrogen economy implementation plan.
Stress conditions across renewable electricity cost volatility, iridium price spikes, and certification interoperability delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding sovereign guarantee uptake rates and METI infrastructure timeline adherence. Hydrogen demand from steel decarbonization and maritime ammonia adoption represents the primary revision risk. Quarterly review of electrolyzer commissioning timelines, bilateral offtake contract announcements, and certification standard harmonization progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Alkaline Water Electrolysis Market
Hydrogen Energy
Hydrogen Refueling Protocol and Dispenser Performance Test Systems Market
Hydrogen Energy
Green Hydrogen Storage Technology Market
Hydrogen Energy
Merchant Hydrogen Market
Hydrogen Energy
Hydrogen Ejector Market
Hydrogen Energy
Hydrogen Generation Market
Hydrogen Energy
Black Hydrogen Market
Hydrogen Energy
Liquid Hydrogen Market
Hydrogen Energy
North America Liquid Hydrogen Market
Hydrogen Energy
India Hydrogen Market
Hydrogen Energy
Hydrogen-Cooled Turbine Generator Market
Hydrogen Energy
Green Hydrogen Energy Storage System Market
Hydrogen Energy
Hydrogen Liquefaction Unit Market
Hydrogen Energy
Hydrogen ICE Ignition System Platforms Market
Hydrogen Energy
Europe Hydrogen Generation Market
Hydrogen Energy
Water Electrolysis Green Hydrogen Production Market