
 Hydrogen Generator Market | 2026-2036
Hydrogen Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Generator Market Analysis
The capital-intensity divergence between PEM stack specialists and alkaline incumbents is unwinding as gigawatt-scale manufacturing economics favor standardized platforms. Nel ASA leverages its integrated electrolyzer and fueling station footprint across Nordic industrial clusters. Linde plc anchors global hydrogen supply through its pipeline network and on-site generation contracts. Plug Power Inc. competes in material handling and stationary power with vertically integrated fuel cell stacks and green hydrogen production.
A hydrogen generator converts feedstock water, natural gas, or biomass into high-purity hydrogen gas through electrolytic, thermochemical, or photolytic processes, typically delivering output at 99.9% purity and pressures from 30 to 350 bar for industrial integration. The device serves as a decentralized production node, eliminating compressed gas logistics for refineries, semiconductor fabs, and ammonia synthesis loops. Alkaline electrolysis still dominates installed capacity due to lower catalyst costs and longer operational track records, though PEM systems are capturing margin pools in renewable-coupled installations where rapid response to intermittency commands price premiums. Reforming technology sustains the largest revenue base through steam methane reforming retrofits with carbon capture, while pyrolysis remains nascent but attracts pilot funding for turquoise hydrogen pathways.
The EPA enforces hydrogen purity standards for fuel cell vehicle dispensing under SAE J2719, while the EU F-Gas Regulation and delegated acts under RED III mandate renewable hydrogen certification and greenhouse gas accounting thresholds. Germany's KBA and BNetzA coordinate grid connection rules for electrolyzer parks exceeding 100 MW, shaping where developers site projects. Stakeholders must monitor how delegated act revisions on additionality and temporal correlation redefine project financeability before committing to long-term offtake structures.
Market Dynamics
The transition from centralized hydrogen supply to on-site generation nodes is restructuring capital allocation across the value chain, with electrolyzer OEMs capturing margin previously held by gas distributors and logistics providers.
Growth Catalysts
- EU RED III Delegated Acts:Mandatory renewable hydrogen certification thresholds are forcing refiners and ammonia producers to source electrolytic supply, accelerating project development timelines in Germany's chemical corridor.
- Alkaline Electrolysis Cost Curves:Nickel-based catalyst platforms and standardized cell stack designs are compressing installed costs per kilowatt, opening mid-scale deployments for steel and methanol applications previously served by reforming.
- Gulf Coast Refinery Expansions:Heavy crude processing requirements at Texas and Louisiana facilities are expanding captive hydrogen production capacity to reduce dependence on merchant hydrogen delivery.
Market Restraints
- Platinum Group Metal Concentration:PEM stack manufacturing remains tethered to South African and Russian palladium and iridium supply, creating input cost volatility that undermines project finance assumptions.
- Grid Connection Queues:Germany's BNetzA interconnection rules for electrolyzer parks exceeding 100 MW are extending commissioning timelines by 18-36 months in high-demand zones.
- Steam Methane Reforming Lock-In:Existing SMR assets with carbon capture retrofits deliver hydrogen at 30-40% lower levelized cost than green alternatives, delaying electrolyzer displacement in merchant markets.
Strategic Opportunities
- India's National Hydrogen Mission:PLI scheme allocations for electrolyzer manufacturing and green hydrogen production incentives are creating first-mover advantages for developers securing land and renewable offtake in Gujarat and Tamil Nadu.
- Solid Oxide Electrolysis Convergence:High-temperature co-electrolysis with industrial waste heat integration is opening efficiency pathways for cement and glass manufacturing decarbonization.
- Offshore Wind Coupling:North Sea lease rounds in Denmark and the Netherlands are enabling electrolyzer platform siting that bypasses onshore grid constraints entirely.
Industry Challenges
- Electrolyzer Stack Certification:IEC 62282-2-100 compliance timelines for PEM systems extend 14-22 months, compressing project completion windows against offtake contract deadlines.
- Specialized Welding and Membrane Handling:Titanium cell fabrication and perfluorinated membrane assembly require technician pools that remain concentrated in Nordic and German industrial clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Generator Market |
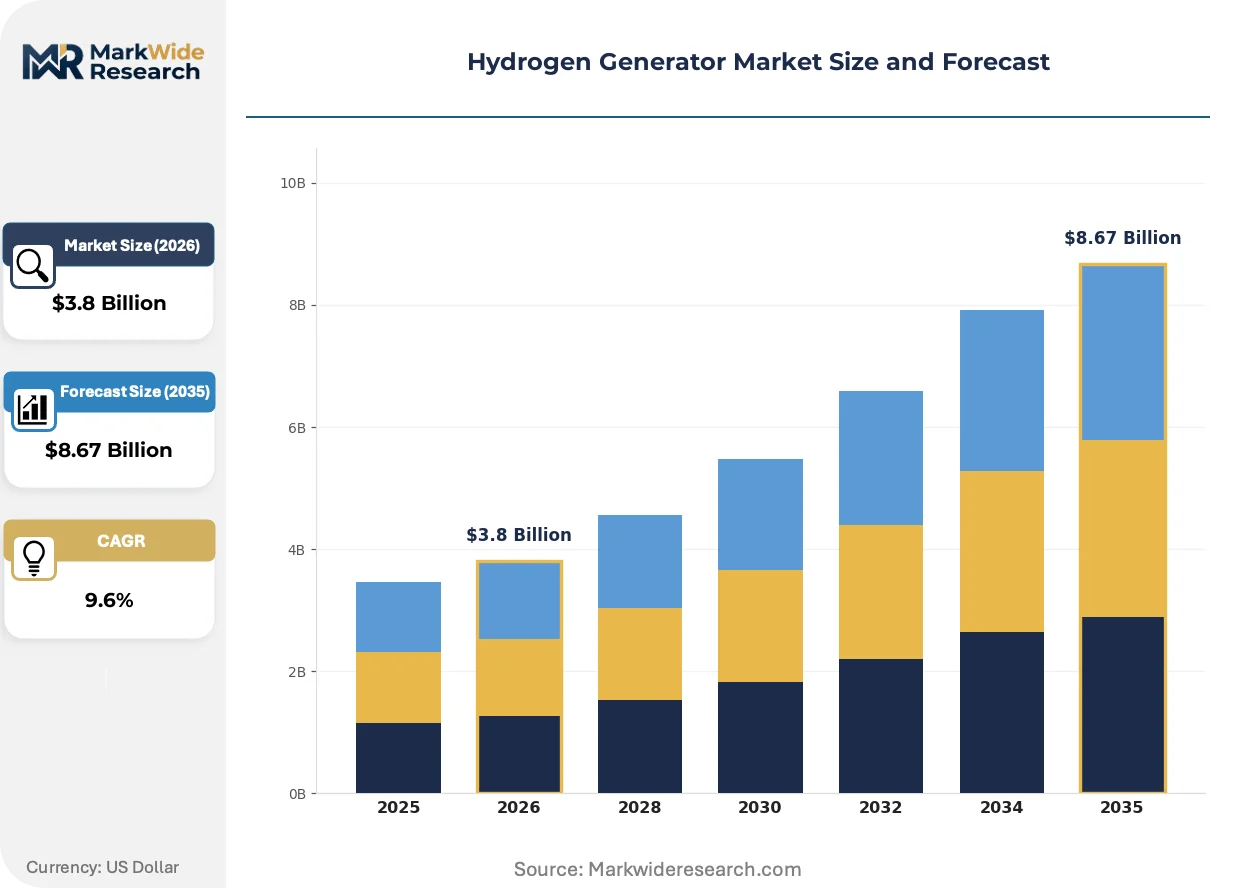
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.67 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PEM, Alkaline, High-Temperature, Photolytic Technology: Electrolysis, Reforming, Pyrolysis, Gasification End User: Industrial, Transportation, Power Generation, Chemical Application: Fuel Cells, Chemical Synthesis, Refining, Energy Storage |
| Companies Covered | Nel ASA, Plug Power Inc., Linde plc, ITM Power PLC, Cummins Inc., Air Liquide S.A., Siemens Energy AG, LNI Swissgas, Air Products and Chemicals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Generator Market Emerging Trajectories
Electrolyzer technology platforms are diverging between cost-optimized alkaline systems for baseload industrial supply and responsiveness-tuned PEM architectures for renewable coupling, with each trajectory demanding distinct manufacturing footprints and supply chain configurations.
Solid oxide electrolysis is bifurcating from low-temperature alternatives by exploiting industrial waste heat integration for efficiency gains above 85% LHV. Steel and cement producers in Scandinavia are piloting SOE units at 10-50 MW scale to validate steam co-feed economics. The technology is bifurcating market segmentation between efficiency-sensitive baseload applications and flexibility-premium renewable-coupled installations.
Delegated acts under RED III are mandating temporal correlation and additionality requirements for renewable hydrogen certification that reshape project structuring. Developers must now secure dedicated renewable generation with hourly matching rather than annual averaging, increasing offtake complexity. German electrolyzer parks are responding by co-locating with offshore wind substations to satisfy correlation thresholds.
Refinery procurement patterns are migrating from long-term merchant hydrogen contracts to integrated on-site generation with performance guarantees. Engineering firms are displacing gas distributors as primary contracting parties, capturing EPC margins and long-term service revenue. This transition is most visible along the US Gulf Coast, where LyondellBasell and Marathon Petroleum facilities are expanding captive electrolyzer and reforming capacity.
Hydrogen Generator Market Segmentation
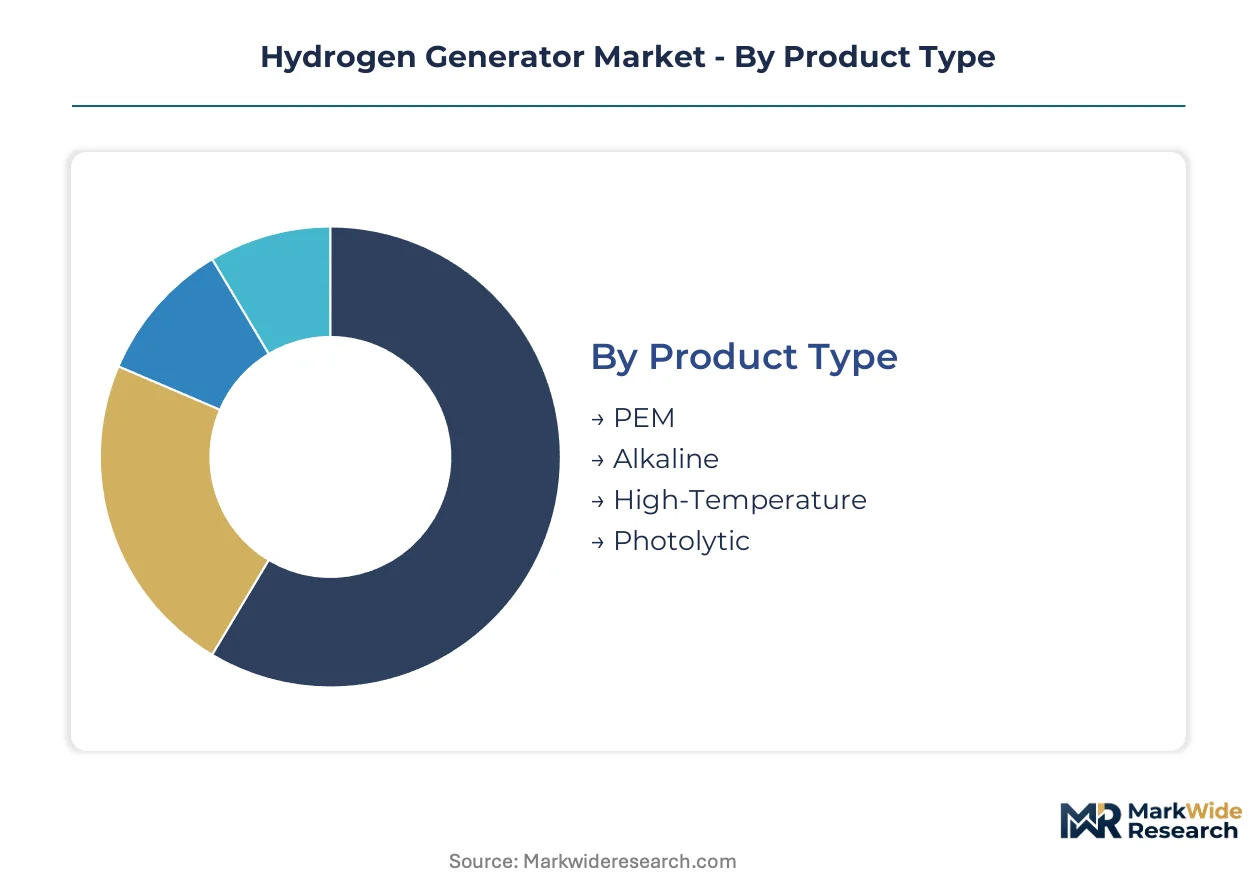
Segmentation in hydrogen generators reveals how technology economics and regulatory thresholds fragment addressable demand across industrial clusters. Each dimension captures distinct substitution pressures, capital intensity profiles, and offtake contract structures that reshape competitive positioning.
Product Type:
Alkaline systems face the strongest substitution pressure from PEM architectures in renewable-coupled installations where response speed commands price premiums.
- PEM:Proton exchange membrane stacks operate at 50-80°C with platinum-group metal catalysts, delivering rapid ramp rates for intermittent renewable integration. Demand concentrates in Germany's chemical corridor where RED III temporal correlation rules favor dispatchable electrolysis.
- Alkaline:Liquid potassium hydroxide electrolyte systems with nickel-based electrodes achieve 60-70% efficiency at lower capital cost per kilowatt. Gulf Coast refineries in Texas and Louisiana deploy these for baseload hydrogen supply to heavy crude processing units.
- High-Temperature:Solid oxide electrolysis cells exploit industrial waste heat above 700°C for efficiency gains exceeding 85% LHV.
- Photolytic:Direct solar-to-hydrogen conversion via semiconductor photoelectrodes remains pre-commercial with pilot deployments in Australia and Japan.
Alkaline anchors the volume base while PEM gains share at the steepest rate.
Technology:
Cost tier stratification separates mature thermochemical platforms from electrolytic alternatives competing on carbon intensity credentials.
- Electrolysis:Water splitting via electrical current dominates green hydrogen production, with alkaline and PEM variants serving distinct load profiles. Nordic industrial clusters in Norway and Sweden favor electrolysis for ammonia and steel decarbonization projects.
- Reforming:Steam methane reforming with carbon capture retrofits delivers hydrogen at the lowest levelized cost, sustaining merchant market dominance. US Gulf Coast facilities maintain reforming capacity for refinery hydrogen loops.
- Pyrolysis:Methane cracking into hydrogen and solid carbon offers turquoise hydrogen pathways without CO2 capture requirements.
- Gasification:Coal or biomass gasification with shift reactors produces hydrogen from solid feedstocks in China and India.
Reforming retains the largest revenue share while electrolysis expands most quickly.
End User:
Application maturity varies sharply across customer types, with industrial offtake agreements commanding longer contract tenors than emerging mobility demand.
- Industrial:Steel, cement, and glass manufacturers procure hydrogen for process heat and reduction reactions. German steelmakers in Duisburg and Salzgitter anchor electrolyzer demand under EU carbon border adjustment pressure.
- Chemical:Ammonia and methanol synthesis loops require high-purity hydrogen at 99.9% specification. Rotterdam and Antwerp harbor zones concentrate chemical sector demand with pipeline infrastructure.
- Transportation:Heavy-duty trucking and maritime fuel cell applications drive demand for high-pressure hydrogen dispensing.
- Power Generation:Gas turbine blending and fuel cell stationary power create seasonal demand peaks.
Industrial offtake dominates contract volume while transportation climbs the fastest.
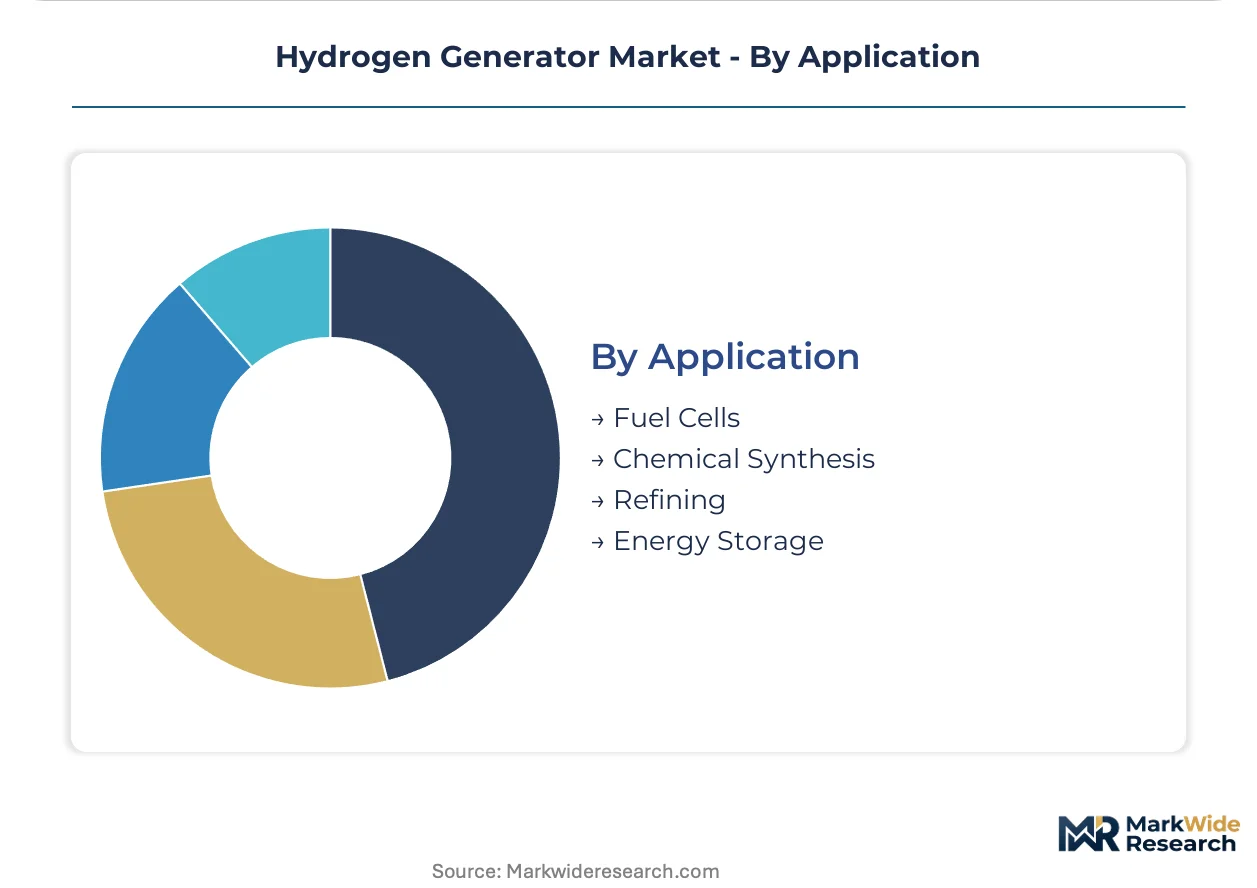
Application:
Supply concentration patterns align with downstream infrastructure ownership, favoring integrated producers in refining and chemical synthesis.
- Chemical Synthesis:Ammonia crackers and methanol reformers consume hydrogen as primary feedstock for fertilizer and chemical intermediates. India's National Hydrogen Mission targets chemical sector decarbonization in Gujarat.
- Refining:Hydrocracking and hydrotreating units demand continuous hydrogen supply for sulfur removal and heavy crude upgrading. Louisiana and Texas refineries expand captive production to reduce merchant dependence.
- Fuel Cells:Proton exchange membrane fuel cells for material handling and stationary power require 99.97% purity hydrogen.
- Energy Storage:Power-to-gas systems convert surplus renewable electricity into hydrogen for seasonal storage and grid balancing.
Chemical synthesis anchors installed capacity while refining drives near-term expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hydrogen generator trade flows are tilting toward electrolyzer exports from European and Asian manufacturing hubs while the United States retains reforming technology dominance. Import dependence for platinum-group metals concentrates procurement risk in South African and Russian supply corridors. Project finance is migrating to jurisdictions with the clearest renewable hydrogen certification frameworks.
United States
Gulf Coast refineries in Texas and Louisiana are expanding captive hydrogen production to process heavier crude slates, reducing reliance on merchant hydrogen delivery. The EPA enforces SAE J2719 purity standards for fuel cell vehicle dispensing, shaping equipment specifications. Engineering firms are displacing gas distributors as primary contracting parties in Houston and Beaumont, capturing EPC margins and long-term service revenue.
Germany
KBA and BNetzA coordinate grid connection rules for electrolyzer parks exceeding 100 MW, extending commissioning timelines by 18-36 months in high-demand zones. Delegated acts under RED III mandate temporal correlation and additionality requirements for renewable hydrogen certification. The chemical corridor around Ludwigshafen and Leuna anchors industrial offtake agreements, with steelmakers in Duisburg and Salzgitter driving electrolyzer demand under EU carbon border adjustment pressure.
China
Coal and biomass gasification with shift reactors produces hydrogen from solid feedstocks, sustaining the largest installed capacity base for thermochemical production. MIIT and MEE shape dual carbon goals that pressure industrial hydrogen users toward lower-carbon alternatives. Manufacturing clusters in the Yangtze River Delta and Shandong Peninsula concentrate electrolyzer component fabrication and alkaline cell stack assembly.
India
PLI scheme allocations for electrolyzer manufacturing and green hydrogen production incentives are creating first-mover advantages for developers securing land and renewable offtake. The CEA and MNRE coordinate grid integration standards for utility-scale electrolyzer deployment. Gujarat and Tamil Nadu harbor zones concentrate project development, with ammonia and methanol producers targeting chemical sector decarbonization under the National Hydrogen Mission.
Netherlands
Rotterdam and Antwerp harbor zones concentrate chemical sector demand with pipeline infrastructure for high-purity hydrogen at 99.9% specification. The EU F-Gas Regulation and delegated acts under RED III mandate renewable hydrogen certification and greenhouse gas accounting thresholds. North Sea lease rounds are enabling electrolyzer platform siting that bypasses onshore grid constraints entirely.
Hydrogen Generator Market Vendor Landscape
Concentration sits with diversified industrial gas conglomerates that anchor global hydrogen supply through pipeline networks and on-site generation contracts. The vendor base spans electrolyzer OEMs, reforming technology licensors, and integrated engineering firms, with each archetype commanding distinct margin pools. Three strategic archetypes dominate: Nordic electrolyzer specialists with integrated fueling station footprints, global industrial gas majors with captive pipeline infrastructure, and vertically integrated fuel cell stack producers. Competitive moves center on gigawatt-scale manufacturing partnerships and performance-guaranteed offtake contracting.
Among Nordic specialists, Nel ASA exemplifies the integrated electrolyzer and fueling station archetype across industrial clusters. Linde plc occupies a position as the global industrial gas major with pipeline network dominance. Plug Power Inc. represents the vertically integrated fuel cell stack producer competing in material handling and stationary power with captive green hydrogen production.
| Leading Market Players |
|---|
| Nel ASA |
| Plug Power Inc. |
| Linde plc |
| ITM Power PLC |
| Cummins Inc. |
| Air Liquide S.A. |
| Siemens Energy AG |
| LNI Swissgas |
| Air Products and Chemicals, Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts with take-or-pay clauses lock in electrolyzer stack supply for German chemical producers while capping exposure to palladium price swings under RED III certification timelines. These structures bind buyers to Nordic and German manufacturing clusters, trading price visibility against 18-36 month commissioning windows.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across the hydrogen generator landscape. Price differentiation stems from certification grade under EU delegated acts and volume scale for gigawatt-class deployments. Cost compression in alkaline systems is intensifying because nickel catalyst platforms achieve manufacturing standardization. Merchant hydrogen buyers exhibit highest price sensitivity, while captive refinery operators prioritize supply security over unit economics.
Supply Chain Analysis
South Africa and Russia anchor platinum-group metal extraction for PEM catalyst layers, while China and Germany concentrate electrolyzer cell stack fabrication. The supply chain draws from titanium cell components, perfluorinated membranes, and nickel mesh electrodes. Single-source vulnerability in palladium and iridium procurement creates input cost volatility. Distribution runs through EPC contractors displacing traditional gas distributors as primary contracting parties.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology platform fragmentation between alkaline baseload and PEM renewable-coupled architectures creates specialized niche opportunities as RED III temporal correlation rules split demand profiles.
For Market Incumbents: Fortify manufacturing footprints through backward integration into membrane and catalyst production, reducing exposure to South African palladium supply disruptions. Expand alkaline stack capacity in Germany's chemical corridor to capture refinery and steelmaker demand under EU carbon border adjustment pressure. Prioritize IEC 62282-2-100 certification investment to compress 14-22 month compliance timelines. For New Entrants and Emerging Players: Aftermarket service gaps for electrolyzer stack refurbishment and membrane replacement present white-space entry points where incumbents under-serve mid-scale industrial deployments. Target India's Gujarat harbor zone for ammonia and methanol producer demand under National Hydrogen Mission incentives. Pursue joint development agreements with offshore wind developers to bypass onshore grid connection queues entirely. For Investors and Strategic Acquirers: Nordic electrolyzer specialists with integrated fueling station footprints represent the most defensible acquisition archetype for long-term positioning across the energy transition window. Monitor delegated act revisions on additionality and hourly matching as the critical signal for project financeability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Production | Captive palladium and iridium supply secures PEM stack margins against South African export volatility. |
| Offshore Wind Coupling Partnership | North Sea platform siting bypasses BNetzA interconnection queues exceeding 100 MW in Germany. |
| Long-term Supply Agreement with Refiners | Gulf Coast captive hydrogen contracts displace merchant delivery for Texas heavy crude processing. |
| Green Certification Program Alignment | RED III temporal correlation compliance unlocks project finance for Ludwigshafen chemical corridor developers. |
| Joint Venture for SOE Waste Heat Integration | Scandinavian cement and glass pilot projects validate 85% LHV efficiency pathways above 700°C. |
Methodological Framework
Desk research of EIA energy outlooks, IEA hydrogen technology reports, and EU delegated act documentation preceded structured interviews with electrolyzer OEM technical directors, refinery hydrogen procurement managers, and EPC project developers. Primary fieldwork with Nordic industrial cluster operators and German grid connection specialists was cross-referenced against SEC filings from listed industrial gas majors and customs data on electrolyzer component trade flows. Bottom-up installation forecasts and top-down hydrogen demand projections were triangulated to validate segment-level outputs.
Variance decomposition across technology platform, end-use application, and regional regulatory framework dimensions shaped the analytical framework over the projection horizon. Modeled segmentation captured alkaline versus PEM versus solid oxide electrolysis trajectories, industrial versus chemical versus transportation offtake patterns, and EU RED III versus US IRA versus India PLI incentive structures. CAGRs were derived from electrolyzer manufacturing capacity buildout schedules and industrial hydrogen demand elasticity assumptions.
Forecasts assume regulatory continuity in EU delegated acts, US EPA SAE J2719 enforcement, and India's National Hydrogen Mission incentive allocations; material policy shifts in additionality rules or carbon border adjustment scope would require re-modeling. Recalibration cycles align with material shifts in platinum-group metal supply corridors and offshore wind lease round outcomes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Green Hydrogen Market
Hydrogen Energy
Photovoltaic Hydrogen Production Market
Hydrogen Energy
Hydrogen Composite Tanks Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Hydrogen Purification Units Market
Hydrogen Energy
High-Pressure Hydrogen Tanks Market
Hydrogen Energy
PEM Water Electrolytic Hydrogen Production System Market
Hydrogen Energy
Green Hydrogen Storage Technology Market
Hydrogen Energy
United States Hydrogen Generation Market
Hydrogen Energy
Hydrogen Powered Engine Market
Hydrogen Energy
Hydrogen Tanks Market
Hydrogen Energy
Black Hydrogen Market
Hydrogen Energy
Green Hydrogen Dispensing Equipment Market
Hydrogen Energy
Hydrogen Production Electrolyser Market
Hydrogen Energy
US Hydrogen Fueling Station Market
Hydrogen Energy
Asia Pacific Liquid Hydrogen Market