
 Gray Hydrogen Market | 2026-2036
Gray Hydrogen Market Size, Share, and Industry Trends Forecast 2026-2036
Gray Hydrogen Market Foresight
Merchant hydrogen supply contracts is fragmenting as regional producers build captive reforming capacity near refineries and ammonia complexes. Air Liquide leverages its pipeline network density in Western Europe to sustain long-term offtake agreements with petrochemical buyers. Linde plc anchors its position through large-scale steam methane reforming installations integrated with carbon capture feasibility studies. Sinopec dominates captive production in China, operating reformers tied directly to its refining and chemical manufacturing complexes.
Gray hydrogen denotes hydrogen produced from fossil fuels—primarily natural gas via steam methane reforming or coal gasification—without carbon capture, yielding a product with carbon intensity typically exceeding ten kilograms of CO₂ per kilogram of H₂. The output serves principally as a feedstock for ammonia synthesis, petroleum refining, and methanol production where process economics override emissions considerations. Steam methane reforming commands the dominant production method position due to its lower unit cost and mature catalyst technology, though gasification retains structural importance in coal-rich economies. Among end users, refineries represent the most mature demand pool, while ammonia production offers the deepest margin pool for merchant suppliers with pipeline access to fertilizer corridors.
The US EPA enforces greenhouse gas reporting requirements for hydrogen production facilities above emission thresholds, shaping investment in monitoring and potential carbon capture retrofits. In Europe, the EU Green Deal and F-Gas Regulation tighten the emissions intensity benchmark for hydrogen eligible for industrial subsidies, pressuring gray hydrogen's market access. India's CEA and Petroleum and Natural Gas Regulatory Board oversee refinery-linked reforming capacity expansions with evolving efficiency mandates. Stakeholders must weigh carbon border adjustment mechanisms against current cost structures when committing to new production assets.
Market Dynamics
The US Inflation Reduction Act's hydrogen production tax credits are redirecting capital toward lower-carbon pathways while gray hydrogen retains its cost advantage in carbon-unpriced jurisdictions. This tension between policy-driven decarbonization and feedstock economics defines current investment calculus across production assets.
Growth Catalysts
- India's refinery expansion mandates:State-owned refiners and fertilizer complexes sustain large-scale steam methane reforming operations with government-backed capacity additions.
- EU Green Deal industrial subsidies:F-Gas Regulation tightening creates transitional demand for gray hydrogen as facilities bridge toward certified low-carbon supply.
- Coal gasification in resource-rich economies:Domestic coal reserves enable cost-competitive hydrogen production where natural gas infrastructure remains underdeveloped.
Market Restraints
- Natural gas price volatility:Feedstock cost swings compress reforming margins and destabilize long-term offtake contract pricing.
- Carbon border adjustment mechanisms:EU CBAM implementation threatens export competitiveness for carbon-intensive hydrogen derivatives.
- Electrolyzer cost declines:Green hydrogen production economics are approaching parity in markets with low-cost renewable electricity.
Strategic Opportunities
- Carbon capture retrofit integration:Existing steam methane reforming infrastructure offers lower-capex pathways to blue hydrogen certification.
- Merchant supply to ammonia corridors:Pipeline-connected production near fertilizer manufacturing clusters captures premium logistics economics.
- India's PLI scheme for clean hydrogen:Domestic manufacturing incentives create transitional demand for gray hydrogen as electrolyzer capacity scales.
Industry Challenges
- Carbon capture engineering talent scarcity:Specialized process design and project execution capabilities remain concentrated among limited engineering firms.
- Emissions verification protocol complexity:ISO 14064 and EU certification timelines extend project financing and offtake agreement finalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gray Hydrogen Market |
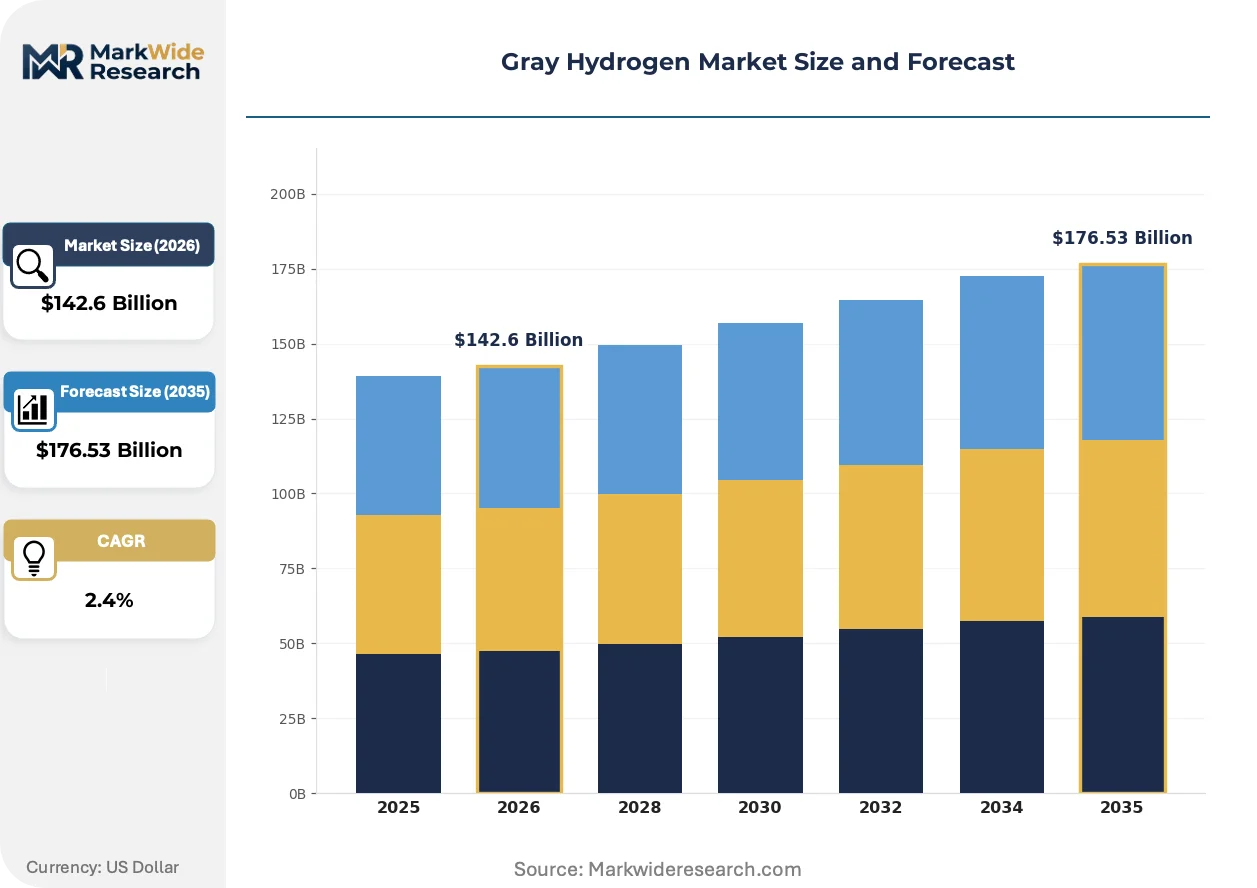
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $176.53 Billion |
| CAGR (2026 – 2036) | 2.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Method: Steam Methane Reforming, Partial Oxidation, Autothermal Reforming, Gasification End User: Refineries, Chemical Manufacturing, Power Generation, Ammonia Production Application: Fuel Cells, Industrial Heating, Synthesis Gas Production, Hydrogenation Distribution Channel: Pipelines, Tankers, Rail Transport, Local Delivery |
| Companies Covered | Air Liquide, Linde plc, Air Products and Chemicals, Inc., Messer Group GmbH, China National Petroleum Corporation, Sinopec, Exxon Mobil Corporation, Indian Oil Corporation Ltd., Reliance Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gray Hydrogen Market Shifts & Advancements
Production technology and regulatory frameworks are simultaneously evolving, compressing the operational window for unabated fossil hydrogen. These shifts favor operators with integrated carbon management capabilities and proximity to demand clusters.
Advanced reforming catalysts with enhanced thermal efficiency are migrating from laboratory validation to commercial deployment. Refinery operators in the US Gulf Coast are piloting these materials to reduce natural gas consumption per unit hydrogen output. The technology is migrating from demonstration scale to baseline specification for new build projects, altering equipment vendor competitive dynamics.
The EU F-Gas Regulation and delegated acts under the EU Green Deal are tightening emissions intensity thresholds for hydrogen eligible for industrial subsidies. Facilities exceeding ten kilograms CO₂ per kilogram H₂ face exclusion from public procurement and state aid. European ammonia producers are responding with accelerated carbon capture feasibility studies and supply contract renegotiations.
Long-term offtake agreements are fragmenting as regional refiners build captive reforming capacity. Merchant suppliers with pipeline networks retain fertilizer corridor contracts, while point-source production displaces delivered hydrogen in coastal refining clusters. This pattern concentrates most acutely in India, where state-owned energy majors integrate reforming with downstream chemical manufacturing.
Gray Hydrogen Market Segmentation
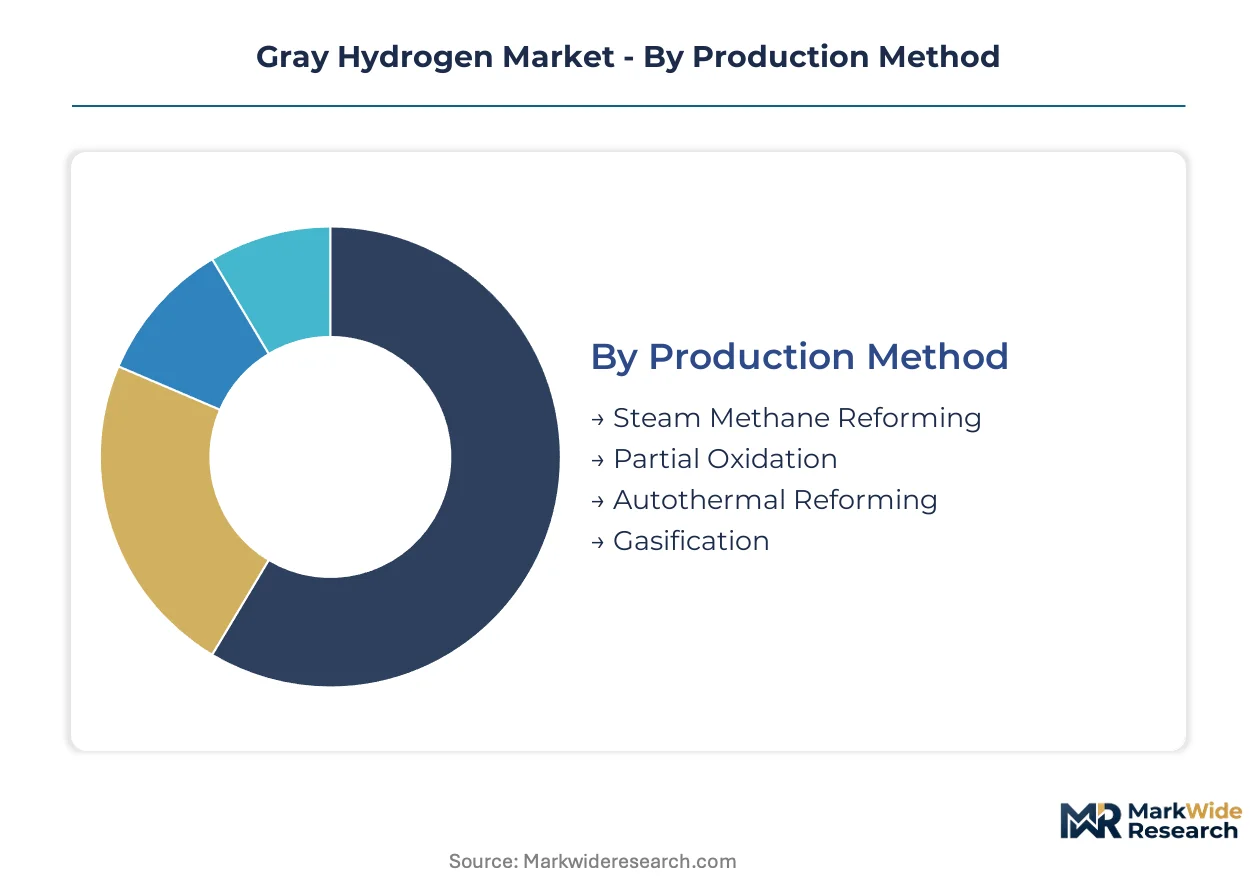
Gray hydrogen producers configure their service infrastructure around production method complexity and end-use reliability requirements. Steam methane reforming plants demand intensive catalyst monitoring and tube replacement programs, while gasification facilities require specialized slag handling and gas cleanup maintenance. Distribution channel selection further shapes aftermarket intensity, with pipeline networks necessitating continuous integrity management versus discrete tanker fleet servicing.
Production Method:
After-sales service intensity varies sharply across reforming technologies, with catalyst replacement cycles and equipment reliability programs driving contract profitability.
- Steam Methane Reforming:Natural gas feedstock passes through nickel-based catalyst tubes at high temperature and pressure, yielding hydrogen with carbon monoxide byproduct. Refineries in India and the US Gulf Coast concentrate demand here, drawn by mature catalyst supply chains and established maintenance protocols that minimize unplanned shutdowns.
- Gasification:Solid feedstocks—coal or petroleum coke—undergo partial oxidation in oxygen-blown reactors, producing syngas requiring extensive cleanup. China's chemical manufacturing clusters and South African synthetic fuel complexes sustain this method where domestic coal reserves offset natural gas infrastructure gaps.
- Partial Oxidation:Heavy hydrocarbon feeds react with limited oxygen to produce hydrogen-rich syngas, common in refinery residue processing units.
- Autothermal Reforming:Combined steam and oxygen reforming achieves thermal balance without external heat input, favored for smaller-scale ammonia and methanol plants.
Steam methane reforming holds the largest share; momentum sits with autothermal reforming as modular designs gain traction in remote production settings.
End User:
Customer type determines contract structure, with merchant suppliers capturing ammonia corridors while refineries increasingly favor captive production.
- Refineries:Hydrocracking and hydrotreating units consume hydrogen to upgrade heavy crude fractions and remove sulfur. India's state-owned refiners and US Gulf Coast operators anchor volume, responding to clean fuel specifications that deepen hydrogen intensity per barrel processed.
- Ammonia Production:Haber-Bosch synthesis requires stoichiometric hydrogen supply for nitrogen fixation, with fertilizer complexes in India, Russia, and Trinidad sustaining dedicated reforming capacity or pipeline-linked merchant contracts.
- Chemical Manufacturing:Methanol synthesis and specialty chemical hydrogenation draw variable-volume offtake, often from multi-product industrial parks.
- Power Generation:Gas turbine blending and fuel cell feedstock applications remain nascent, constrained by emissions accounting and efficiency penalties versus direct electrification.
Refineries command the dominant demand position; ammonia production represents the steepest expansion trajectory as fertilizer capacity additions accelerate in South Asia and the Middle East.
Application:
Margin structure diverges by use case, with synthesis gas production integrating into large-scale chemical complexes while fuel cells demand higher purity grades.
- Synthesis Gas Production:Hydrogen combines with carbon monoxide for methanol and Fischer-Tropsch liquids, requiring precise H₂/CO ratio control.
- Industrial Heating:Direct combustion in high-temperature furnaces competes with electrification and alternative fuels in cement, glass, and steel sectors.
- Hydrogenation:Edible oil processing and petrochemical saturation reactions consume merchant hydrogen in batch or continuous configurations.
- Fuel Cells:Stationary and mobility applications demand ultra-low sulfur and carbon monoxide contamination, typically excluding unabated gray hydrogen from qualification.
Synthesis gas production absorbs the largest volume; fuel cells are climbing fastest as stationary power backup markets expand in data center and telecom applications.
Distribution Channel:
Logistics economics concentrate supply around infrastructure availability, with pipeline density determining merchant market viability.
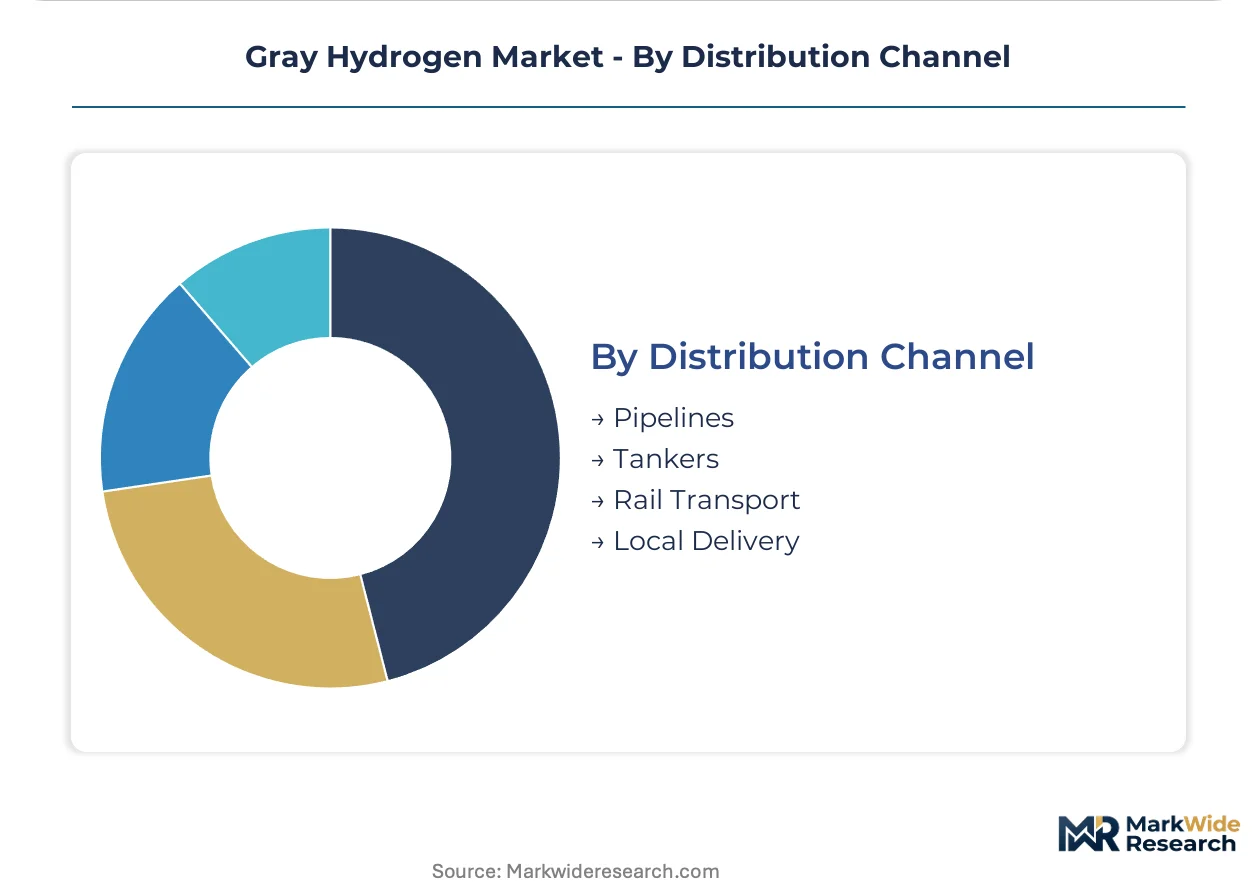
- Pipelines:Dedicated hydrogen networks—Air Liquide's Northern European system, Sinopec's Yangtze River corridor—deliver continuous supply to clustered industrial users at lowest unit cost.
- Tankers:Compressed gas tube trailers and cryogenic liquid tankers serve point-source demand beyond pipeline reach, with fleet utilization critical to route profitability.
- Rail Transport:Cryogenic rail cars move bulk hydrogen to inland industrial zones lacking pipeline connectivity, common in North American and Russian corridors.
- Local Delivery:Cylinder bundles and small-scale liquid supply serve maintenance, laboratory, and specialty chemical applications with high frequency, low volume characteristics.
Pipelines capture the dominant share; tanker-based delivery is gaining share fastest as distributed ammonia and methanol production expands outside established corridor infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Inflation Reduction Act's hydrogen production tax credits are redirecting investment flows across major producing regions, even as gray hydrogen retains cost advantages in jurisdictions without carbon pricing mechanisms. Production clusters concentrate around existing refining and chemical manufacturing infrastructure where feedstock access and demand density justify capital deployment.
United States
Refinery hydrogen demand from hydrocracking and desulfurization processes sustains steam methane reforming capacity along the US Gulf Coast. The EPA enforces greenhouse gas reporting requirements for facilities above emission thresholds, shaping monitoring investments and carbon capture retrofit planning. Houston-area petrochemical complexes anchor merchant supply volumes, with operators piloting advanced reforming catalysts to reduce natural gas consumption per unit output.
India
State-owned refiners and fertilizer complexes sustain large-scale steam methane reforming operations with government-backed capacity additions under evolving efficiency mandates. The CEA and Petroleum and Natural Gas Regulatory Board oversee refinery-linked expansions, while the PLI scheme for clean hydrogen creates transitional demand as electrolyzer capacity scales. Gujarat and Maharashtra host concentrated industrial hydrogen corridors serving ammonia synthesis and petroleum upgrading.
China
Domestic coal reserves enable cost-competitive hydrogen production through gasification where natural gas infrastructure remains underdeveloped, particularly in inland chemical manufacturing clusters. Sinopec dominates captive production, operating reformers tied directly to refining and chemical complexes. The Yangtze River corridor features pipeline-connected supply systems delivering continuous hydrogen to clustered industrial users.
Germany
Air Liquide leverages its pipeline network density in Western Europe to sustain long-term offtake agreements with petrochemical buyers, even as the EU Green Deal tightens emissions intensity benchmarks. The F-Gas Regulation and delegated acts under the EU Green Deal are pressuring gray hydrogen's market access for facilities exceeding ten kilograms CO₂ per kilogram H₂. The Ruhr industrial region maintains reforming capacity serving ammonia and methanol synthesis.
Saudi Arabia
Natural gas feedstock abundance supports steam methane reforming economics for ammonia and methanol export production, with facilities supplying global fertilizer corridors. Domestic industrial diversification programs under Vision 2030 are examining hydrogen's role in downstream chemical manufacturing. The Eastern Province concentrates reforming capacity integrated with petrochemical and export infrastructure.
Gray Hydrogen Market Competitive Landscape
On the supply side, the industry is consolidating around integrated industrial gas majors with pipeline network density and captive production operators tied to refining and chemical complexes. Three strategic archetypes dominate competitive positioning: merchant suppliers with corridor infrastructure, state-owned energy majors with downstream integration, and regional specialists serving point-source demand. Capacity expansion and carbon capture feasibility integration represent the dominant competitive moves as operators position for emissions regulation tightening.
Within the integrated industrial gas tier, Air Liquide and Linde plc exemplify operators leveraging pipeline network density to sustain long-term offtake relationships with petrochemical and fertilizer buyers. Sinopec represents the state-owned captive production archetype, with reforming capacity integrated directly into refining and chemical manufacturing complexes. Among regional merchant suppliers, Messer Group GmbH occupies a position serving point-source industrial demand in European corridors where pipeline connectivity remains limited.
| Leading Market Players |
|---|
| Air Liquide |
| Linde plc |
| Air Products and Chemicals, Inc. |
| Messer Group GmbH |
| China National Petroleum Corporation |
| Sinopec |
| Exxon Mobil Corporation |
| Indian Oil Corporation Ltd. |
| Reliance Industries Ltd. |
| Others |
Supply & Pricing Matrix
Natural gas concentration in Russia, Qatar, and the US Gulf anchors feedstock cost structures that cascade through reforming economics and determine where merchant suppliers capture margin versus where captive production displaces delivered hydrogen.
Pricing Analysis
Volume-discount tiering separates pipeline-connected industrial buyers from spot-market tanker deliveries, with long-term offtake agreements commanding 15-30% cost advantages over interruptible supply. Price differentiation rests on carbon intensity certification under EU delegated acts and after-sales catalyst management bundling. Margins are tightening in European corridors as F-Gas Regulation thresholds disqualify unabated production from state aid eligibility. Ammonia producers exhibit highest price sensitivity due to nitrogen fertilizer margin compression, while specialty chemical hydrogenation tolerates premium grades for batch reliability.
Supply Chain Analysis
Export-control regimes limiting advanced reforming catalyst and pressure-vessel technology flows from Germany, Japan, and the US shape equipment vendor selection in emerging production clusters. Manufacturing concentration centers on China for gasification reactor fabrication, India for refinery-integrated reforming modules, and Germany for high-efficiency catalyst coatings. Nickel and platinum-group metal sourcing from South Africa and Russia creates single-source vulnerability for catalyst production. Distribution runs through pipeline networks in established corridors, with cryogenic tanker fleets serving point-source demand beyond infrastructure reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story where pipeline network density creates switching costs that lock in industrial buyers across multi-decade offtake horizons.
For Market Incumbents: Entrench corridor positions through carbon capture retrofit integration at existing reforming assets, converting unabated gray hydrogen to blue certification ahead of EU CBAM full implementation. Add autothermal reforming capacity in India's Gujarat and Maharashtra industrial zones to capture PLI scheme transitional demand before electrolyzer scale-up completes. Lock in 10-15 year supply contracts with state-owned refiners now negotiating capacity expansions.
For New Entrants and Emerging Players: Southeast Asian fertilizer corridors outside established pipeline networks present the most penetrable white space, particularly Vietnam and Indonesia where ammonia capacity additions outrun infrastructure deployment. Target merchant supply to distributed methanol production facilities lacking captive reforming economics. Enter through mobile steam methane reforming units with rapid deployment timelines, bypassing capital-intensive pipeline commitments.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial gas specialists holding 2015-2019 vintage reforming capacity in European corridors facing regulatory obsolescence. Five-to-ten year viability hinges on successful carbon capture retrofit execution and certification timeline acceleration. Monitor EU delegated act threshold revisions as the critical inflection signal—tightening beyond 4 kg CO₂ per kg H₂ would strand substantial unabated capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Integration | Converts existing SMR assets to blue hydrogen certification under EU Green Deal delegated acts. |
| Pipeline Network Expansion | Air Liquide's Northern European corridor model locks in petrochemical buyers through lowest delivered cost. |
| Autothermal Reforming Modular Deployment | Enables rapid scale-up in India's PLI scheme window before electrolyzer manufacturing matures. |
| Merchant Supply to Ammonia Corridors | Captures premium logistics economics in fertilizer manufacturing clusters lacking captive capacity. |
| Advanced Catalyst Efficiency Programs | Reduces natural gas consumption per unit hydrogen output at US Gulf Coast refinery complexes. |
Research Methodology
A spread of perspectives from refinery operations managers, industrial gas procurement leads, catalyst technology directors, and carbon capture engineering specialists converged on the working assumptions shaping production cost trajectories and regulatory compliance timelines. Primary fieldwork combined structured interviews across hydrogen production, distribution, and end-use facilities with secondary validation through SEC 10-K filings, EIA energy data, EU ETS transaction records, and customs trade databases. Bottom-up capacity installation tracking and top-down demand modeling from ammonia synthesis and petroleum refining throughput triangulated volume estimates.
Demand-supply balance dynamics across the analysis window reflect segmented modeling by production method complexity, end-use reliability requirements, and distribution channel infrastructure availability. The analytical framework incorporated steam methane reforming versus gasification technology economics, refinery captive versus merchant supply contract structures, and pipeline-connected versus tanker-delivered logistics tiers. CAGRs derived from installed capacity expansion timelines, efficiency mandate implementation schedules, and carbon border adjustment mechanism phase-in assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-owned energy majors accelerating electrolyzer manufacturing scale-up would shift outcomes beyond modeled ranges. Material shifts in EU delegated act certification thresholds, natural gas price volatility regimes, or carbon capture engineering talent availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Brown Hydrogen Market
Hydrogen Energy
Hydrogen Liquefaction Unit Market
Hydrogen Energy
PEM Water Electrolytic Hydrogen Production System Market
Hydrogen Energy
Green Hydrogen Dispensing Equipment Market
Hydrogen Energy
Black Hydrogen Market
Hydrogen Energy
Hydrogen Tanks Market
Hydrogen Energy
Photovoltaic Hydrogen Production Market
Hydrogen Energy
India Hydrogen Market
Hydrogen Energy
Hydrogen Station Market
Hydrogen Energy
Global Hydrogen Electrolyzers Market
Hydrogen Energy
Hydrogen Generation Market
Hydrogen Energy
Liquid Organic Hydrogen Carrier (LOHC) Market
Hydrogen Energy
Electrolyzer Market
Hydrogen Energy
Alkaline Water Electrolysis Market
Hydrogen Energy
Partial Oxidation Blue Hydrogen Market
Hydrogen Energy
Water Electrolysis Green Hydrogen Production Market