
 India LNG Bunkering Market | 2026-2036
India LNG Bunkering Market Size, Share, and Industry Trends Forecast 2026-2036
India LNG Bunkering Market Foresight
Market Context
Dual-fuel engine technology is reconfiguring vessel propulsion architecture across Indian coastal and international shipping lanes. Petronet LNG Ltd leverages its Dahej and Kochi terminal network to anchor upstream fuel availability for maritime operators. Indian Oil Corporation Ltd sustains downstream distribution reach through its port-side storage and logistics infrastructure. Shell Plc competes on technical service protocols, offering crew training and engine compatibility certification alongside physical supply.
Technical Definition and Segment Structure
India LNG bunkering denotes the transfer of liquefied natural gas, stored at minus 162 degrees Celsius and atmospheric pressure, from shore or floating facilities to marine vessels for use as primary or dual-fuel propulsion energy. The process requires cryogenic handling systems, boil-off gas management, and specialized coupling interfaces to maintain fuel integrity during transfer. Ship-to-ship bunkering dominates transaction volumes at major ports where dedicated LNG bunker vessels reduce turnaround times for large tankers and cargo ships. Truck-to-ship delivery occupies a growing niche at minor ports and inland waterways where fixed infrastructure remains uneconomical, while barge supply extends coverage to offshore facilities and anchorage zones beyond immediate quay access.
Regulatory Framework and Outlook
The Directorate General of Shipping enforces safety guidelines under the International Maritime Organization's International Code of Safety for Ships using Gases or other Low-flashpoint Fuels, while the Petroleum and Natural Gas Regulatory Board oversees downstream pricing and infrastructure access. India's ratification of IMO emission control standards and the Maritime India Vision framework tightens marine fuel sulfur limits, directly expanding compliant LNG demand. Stakeholders must monitor port authority licensing timelines and coastal regulatory zone clearances, as these approval pathways determine actual bunkering station commissioning speed relative to vessel fleet conversion schedules.
Market Dynamics
The International Maritime Organization's sulfur cap enforcement is compressing residual fuel oil demand across Indian coastal shipping lanes. Fleet operators at Jawaharlal Nehru Port and Mundra Port face accelerated engine conversion timelines as dual-fuel propulsion becomes technically viable at scale.
Growth Catalysts
- Maritime India Vision 2030:The Ministry of Ports, Shipping and Waterways mandates shore power and cleaner marine fuels at major ports, forcing infrastructure investment that anchors LNG bunkering station deployment.
- Dahej-Kochi terminal network:Petronet LNG's cryogenic storage capacity creates physical fuel availability for vessel operators, reducing supply-side uncertainty that previously stalled fleet conversion decisions.
- Dual-fuel engine technology:Wärtsilä and MAN Energy Solutions engine platforms now dominate newbuild orders at Indian shipyards, enabling operators to arbitrage between LNG and conventional bunkers based on relative pricing.
Market Restraints
- Capital intensity of cryogenic infrastructure:LNG storage tanks, regasification units, and specialized coupling systems require upfront investment that exceeds conventional fuel terminal costs by substantial multiples.
- Coastal Regulatory Zone clearance delays:The Ministry of Environment, Forest and Climate Change approval pathways for shore-based bunkering facilities extend commissioning timelines beyond vessel fleet conversion schedules.
- Bunker vessel scarcity:India's dedicated LNG bunker fleet remains concentrated at Hazira and Dahej, leaving Mundra and eastern port operators dependent on truck-to-ship delivery with slower turnaround times.
Strategic Opportunities
- Inland waterway corridors:The National Waterways Act unlocks LNG bunkering demand along the Ganga-Brahmaputra system, where truck-to-ship delivery can substitute for uneconomical fixed infrastructure.
- Petroleum and Natural Gas Regulatory Board pricing reforms:Proposed open-access regulations for LNG terminals would democratize fuel sourcing for smaller shipping operators currently locked into incumbent supplier contracts.
- Ship-to-ship bunkering protocols:Adoption of ISO 20519 standards for LNG bunkering operations would enable Indian-flagged vessels to refuel at Singapore and Rotterdam without compatibility disputes.
Industry Challenges
- Cryogenic handling certification gaps:The Directorate General of Shipping lacks sufficient surveyors trained in IGF Code compliance verification, creating inspection backlogs that delay vessel operational clearance.
- Boil-off gas management complexity:Vessel operators struggle to optimize fuel consumption when holding tanks experience thermal ingress during extended anchorage periods at Indian ports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India LNG Bunkering Market |
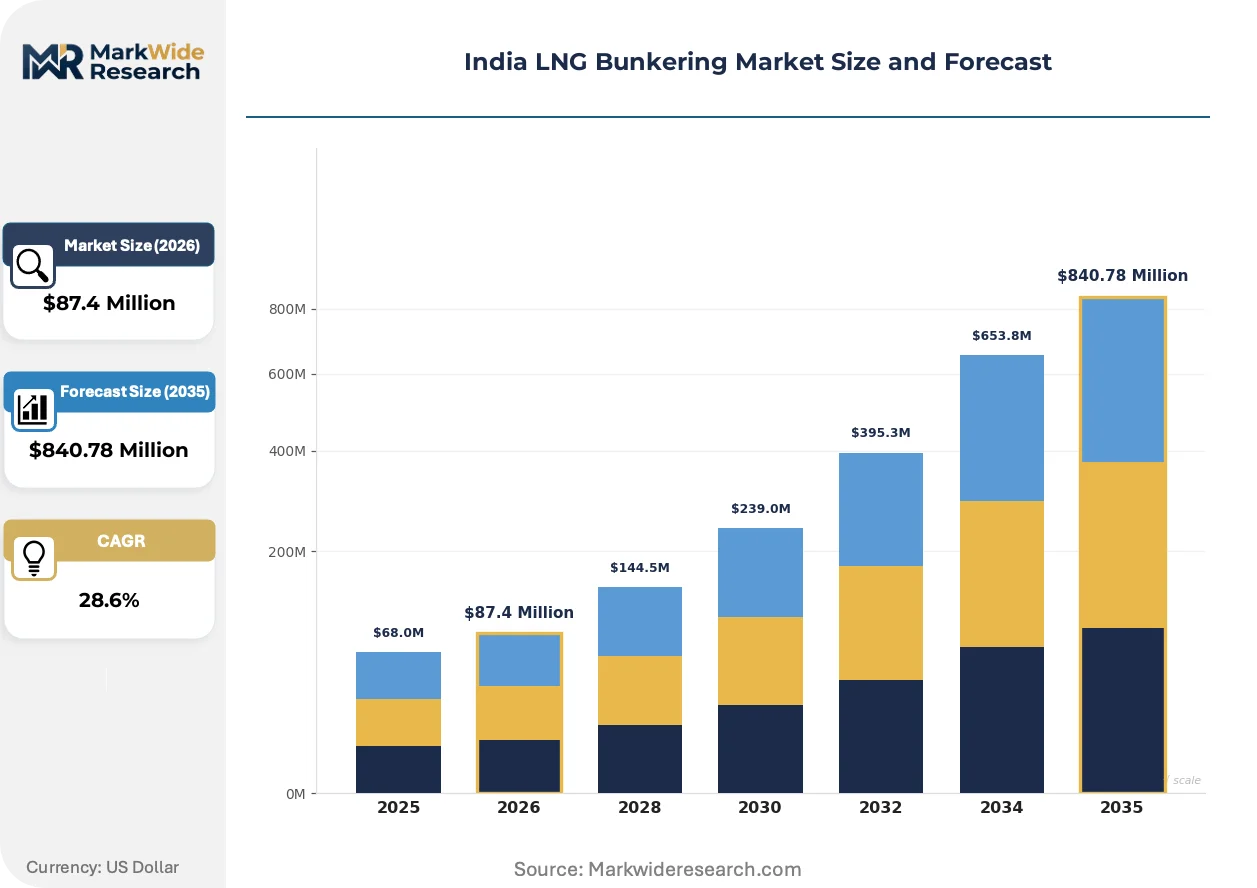
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $840.78 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Port Type: Major Ports, Minor Ports, Inland Ports, Offshore Facilities Vessel Type: Large Tankers, Cargo Ships, Ferries, Service Vessels Bunkering Method: Ship-to-Ship, Port-to-Ship, Truck-to-Ship, Barge Supply Regulatory Framework: Domestic Regulations, International Standards, Safety Guidelines, Emission Controls |
| Companies Covered | Petronet LNG Ltd, Bharat Petroleum Corp Ltd, Adani Enterprises Ltd, H-Energy Private Limited, Indian Oil Corporation Ltd, Bunker Holding A/S, Shell Plc, GAIL India Ltd, HPCL-Mittal Energy Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India LNG Bunkering Market Shifts & Advancements
Propulsion technology migration is reconfiguring vessel architecture across Indian coastal and international routes. Regulatory ratchet mechanisms are compressing compliance timelines faster than infrastructure deployment cycles. Procurement behavior is shifting as fleet operators reassess total-cost-of-ownership models against fuel price volatility exposure.
Type-C independent fuel tanks are migrating from auxiliary applications to primary propulsion storage on container vessels and bulk carriers. Indian shipyards at Visakhapatnam and Cochin are integrating these vacuum-insulated cylindrical tanks into newbuild designs for Middle East-India trade lanes. The technology is migrating from niche ferry retrofits to mainstream deep-sea shipping, enabling longer intervals between bunkering calls and compressing port turnaround economics.
The Directorate General of Shipping's adoption of IGF Code amendments tightens safety protocols for gas-fueled vessels operating in Indian territorial waters. Shipowners must now demonstrate redundant fuel containment systems and emergency shutdown capabilities before obtaining passenger or cargo carriage licenses. Container lines serving the India-Europe route face the steepest compliance costs, responding by consolidating LNG-ready vessel orders at select yards with proven certification track records.
Fleet procurement is fragmenting between asset-light charterers and integrated owners willing to absorb fuel price risk. Container shipping lines at Jawaharlal Nehru Port increasingly prefer time-charter arrangements with bunker-inclusive rates, transferring LNG price exposure to vessel owners. This behavioral shift is most visible among Asia-India trade operators, where volatile spot LNG pricing has eroded confidence in long-term fuel cost forecasting.
India LNG Bunkering Market Segmentation
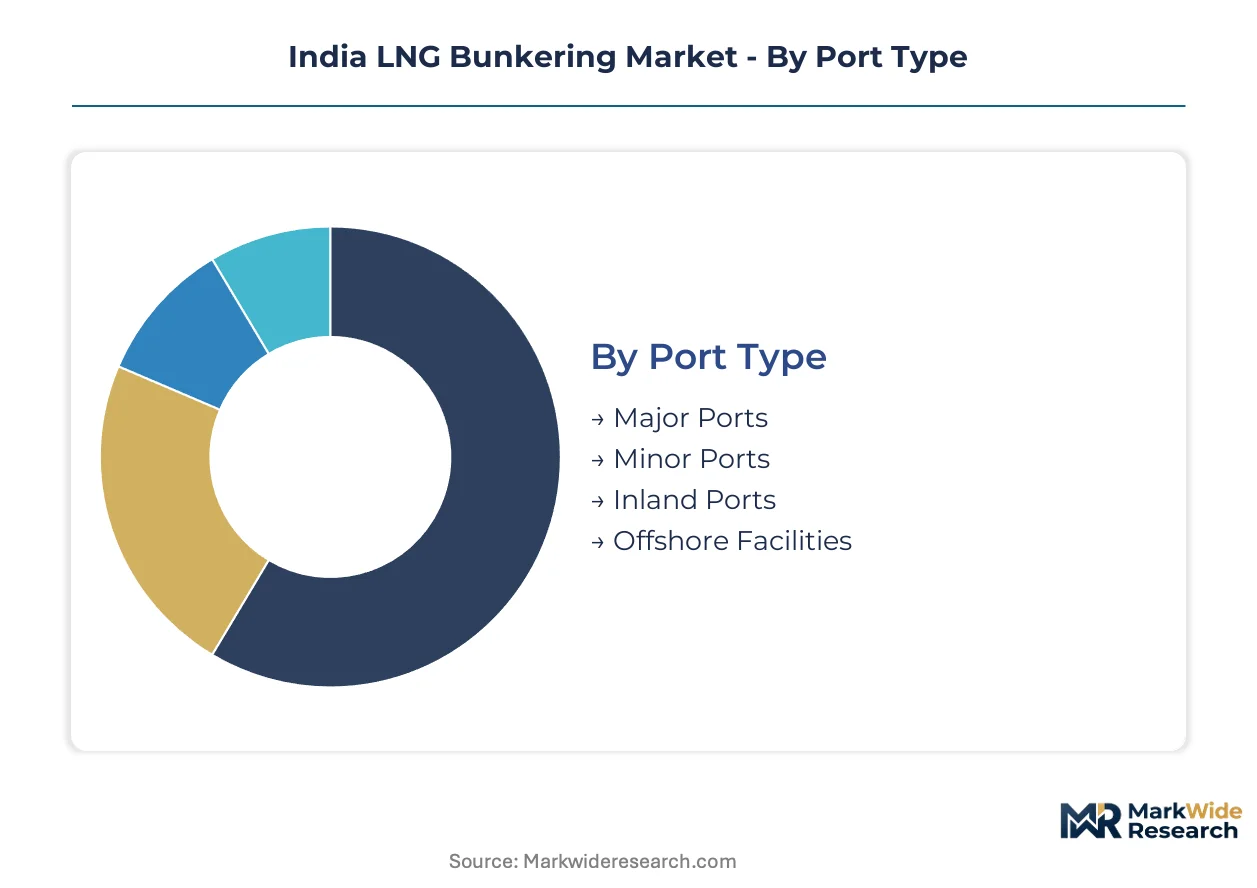
India's LNG bunkering infrastructure fragments across port hierarchies, vessel classes, and fueling modalities that each impose distinct technical and commercial requirements. Understanding these segment boundaries clarifies where capital deployment concentrates and which operational models face margin compression.
Port Type:
Geography determines infrastructure economics, with coastal positioning and cargo throughput dictating cryogenic storage viability.
- Major Ports:Jawaharlal Nehru Port and Mundra Port anchor ship-to-ship bunkering volumes through dedicated LNG receiving terminals. The Ministry of Ports, Shipping and Waterways mandates shore power and cleaner marine fuels here, forcing infrastructure investment that crowds out smaller competitors.
- Minor Ports:Gujarat's secondary harbors along the Gulf of Khambhat rely on truck-to-ship delivery due to insufficient cargo density for fixed installations. Hazira's satellite facilities demonstrate how proximity to Petronet LNG's Dahej terminal enables distributed refueling without dedicated storage.
- Inland Ports:National Waterways Act corridors along the Ganga-Brahmaputra system unlock demand where fixed infrastructure remains uneconomical.
- Offshore Facilities:Anchorage zones beyond immediate quay access require specialized barge supply chains.
Major ports command the established base. The steepest expansion runs through inland ports.
Vessel Type:
Propulsion architecture and fuel tank configuration vary sharply across vessel categories, determining LNG compatibility and bunkering frequency.
- Large Tankers:Crude and product carriers operating Middle East-India routes deploy Type-C independent fuel tanks for primary propulsion. Wärtsilä dual-fuel engine platforms dominate newbuild orders at Indian shipyards serving this segment.
- Cargo Ships:Container lines face the steepest compliance costs under Directorate General of Shipping IGF Code amendments, responding by consolidating LNG-ready vessel orders at select yards with proven certification track records.
- Ferries:Vacuum-insulated cylindrical tanks migrated first to this segment, establishing technical precedents now scaling to deep-sea applications.
- Service Vessels:Tugs and pilot boats at Hazira and Dahej demonstrate rapid fleet conversion where route predictability supports fuel cost forecasting.
Cargo ships anchor current demand. Large tankers are climbing the fastest as long-haul operators arbitrage LNG against conventional bunker pricing.
Bunkering Method:
Modal choice reflects port infrastructure maturity, vessel size, and turnaround time constraints.
- Ship-to-Ship:Dedicated LNG bunker vessels reduce turnaround times for large tankers and cargo ships at major ports where transaction volumes justify specialized fleet investment.
- Port-to-Ship:Fixed quayside infrastructure at Dahej and Kochi enables direct fueling for vessels with extended port stays.
- Truck-to-Ship:Cryogenic road tankers serve minor ports and inland waterways where permanent installations remain uneconomical.
- Barge Supply:Extends coverage to offshore facilities and anchorage zones beyond immediate quay access.
Ship-to-ship dominates transaction volumes. Truck-to-ship is gaining share fastest as inland corridor development outpaces fixed infrastructure deployment.
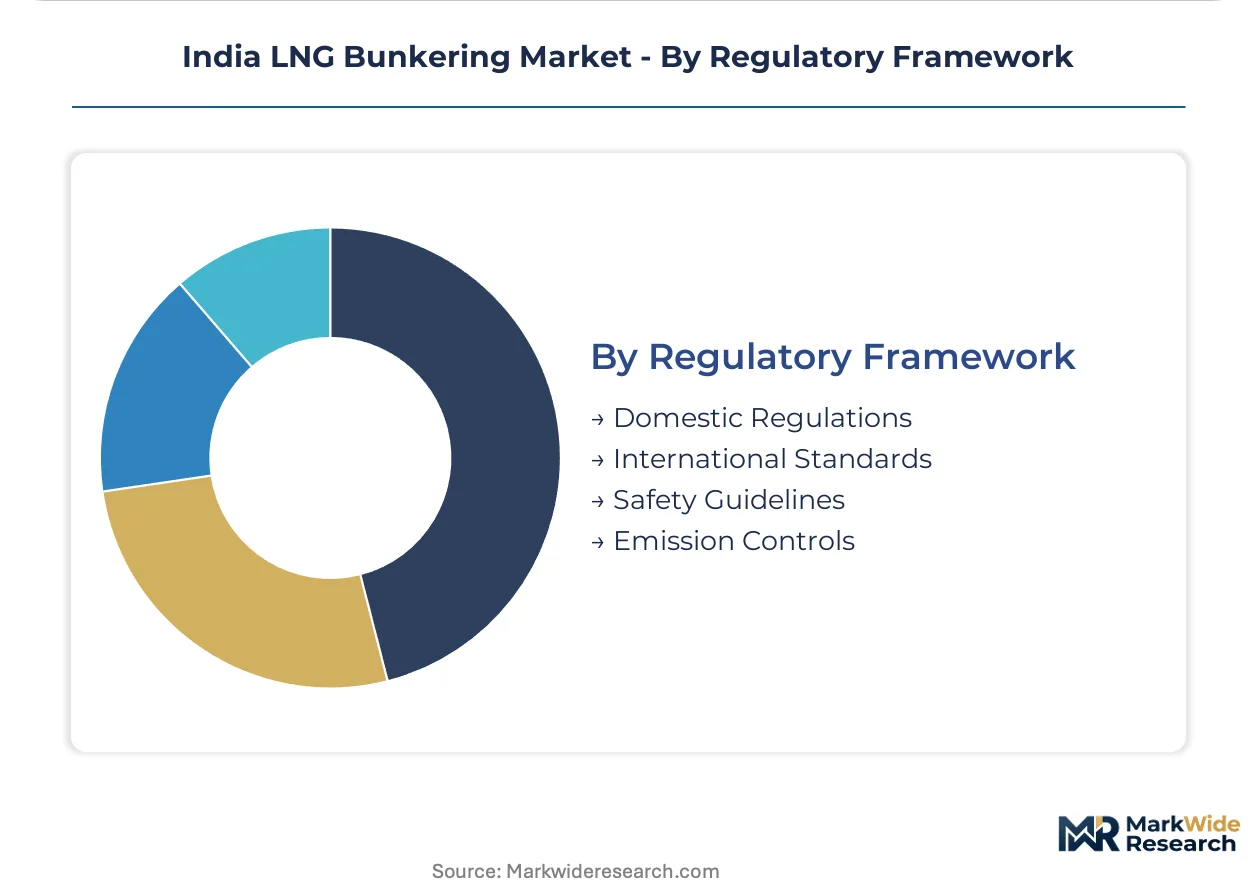
Regulatory Framework:
Compliance architecture spans domestic enforcement, international treaty obligations, and operational safety protocols.
- Domestic Regulations:Petroleum and Natural Gas Regulatory Board pricing reforms and Coastal Regulatory Zone clearances determine bunkering station commissioning speed.
- International Standards:IMO sulfur cap enforcement compresses residual fuel oil demand, while ISO 20519 adoption enables Indian-flagged vessels to refuel at Singapore and Rotterdam without compatibility disputes.
- Safety Guidelines:Directorate General of Shipping surveyor shortages create inspection backlogs that delay vessel operational clearance.
- Emission Controls:Maritime India Vision 2030 tightens marine fuel sulfur limits, directly expanding compliant LNG demand.
Domestic regulations structure operational feasibility. International standards are expanding most quickly as fleet operators seek cross-border fueling interoperability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Middle East-India crude and product tanker routes anchor LNG bunkering demand along Gujarat's coastline, with Dahej and Hazira terminals supplying fuel for vessels transiting the Arabian Sea corridor.
Gujarat
Dahej and Hazira host India's densest LNG import terminal concentration, with Petronet LNG's cryogenic storage anchoring physical fuel availability. The Ministry of Ports, Shipping and Waterways mandates shore power and cleaner marine fuels at major ports, forcing infrastructure investment that crowds out smaller competitors. Mundra Port operators face accelerated engine conversion timelines as dual-fuel propulsion becomes technically viable at scale.
Maharashtra
Jawaharlal Nehru Port commands ship-to-ship bunkering volumes through dedicated LNG receiving terminals serving container shipping lines. The Directorate General of Shipping enforces IGF Code safety guidelines, tightening protocols for gas-fueled vessels operating in Indian territorial waters. Container lines serving India-Europe routes consolidate LNG-ready vessel orders at select yards with proven certification track records.
Kerala
Kochi terminal extends Petronet LNG's network into southern shipping lanes, enabling direct fueling for vessels with extended port stays. Coastal Regulatory Zone clearance delays extend commissioning timelines beyond vessel fleet conversion schedules. The Kochi shipyard cluster demonstrates technical precedents for Type-C independent fuel tank integration into newbuild designs.
West Bengal
The Ganga-Brahmaputra inland waterway system unlocks LNG bunkering demand where fixed infrastructure remains uneconomical. The National Waterways Act enables truck-to-ship delivery substitution for permanent installations. Haldia Port operators demonstrate how proximity to cargo density constraints shapes cryogenic storage viability decisions.
India LNG Bunkering Market Competitive Landscape
Channel-controlling players compete with product-specialist players across India's LNG bunkering infrastructure. Terminal operators leverage import capacity to anchor upstream fuel availability, while downstream distributors extend port-side storage and logistics reach. Two strategic archetypes dominate: integrated energy majors with captive LNG supply chains, and specialized bunkering service providers with technical certification capabilities. Competitive moves concentrate on terminal access partnerships and cryogenic handling certification acquisition.
Among integrated energy majors, Petronet LNG Ltd and Indian Oil Corporation Ltd exemplify the upstream-downstream integrated archetype, leveraging terminal networks and distribution infrastructure respectively. Shell Plc occupies a position within the technical service tier, offering crew training and engine compatibility certification alongside physical supply. These three anchors demonstrate how fuel availability, distribution reach, and technical service protocols constitute distinct competitive vectors in the Indian market.
| Leading Market Players |
|---|
| Petronet LNG Ltd |
| Bharat Petroleum Corp Ltd |
| Adani Enterprises Ltd |
| H-Energy Private Limited |
| Indian Oil Corporation Ltd |
| Bunker Holding A/S |
| Shell Plc |
| GAIL India Ltd |
| HPCL-Mittal Energy Ltd |
| Others |
Supply & Pricing Matrix
Underutilization at Dahej and Hazira import terminals compresses spot LNG premiums for maritime buyers while forcing Petronet LNG Ltd toward long-term offtake contracts that lock in volume commitments from container lines at Jawaharlal Nehru Port.
Pricing Analysis
Dual-fuel engine technology creates a pronounced pricing gap between first-generation diesel-mechanical retrofits, current dual-fuel newbuilds, and next-generation ammonia-ready hull designs. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under IGF Code amendments and boil-off gas management sophistication. Cost compression in standard-tier bunkering runs through truck-to-ship delivery networks where cryogenic road tanker availability remains fragmented. Smaller coastal operators exhibit highest price sensitivity, while integrated container lines absorb premium spreads for ship-to-ship transfer certainty.
Supply Chain Analysis
Export-control restrictions on cryogenic pump technology and specialized coupling systems from European and Japanese suppliers constrain indigenous manufacturing capacity for LNG bunkering infrastructure. Equipment sourcing draws from Germany, South Korea, and Norway for regasification skids, vacuum-insulated piping, and emergency shutdown systems. Nickel-based superalloy dependencies for cryogenic containment create single-source vulnerability through concentrated metallurgical supply. Distribution runs through Petronet LNG's terminal network to port-side storage, then fractures between dedicated bunker vessels and road tanker fleets based on cargo throughput density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
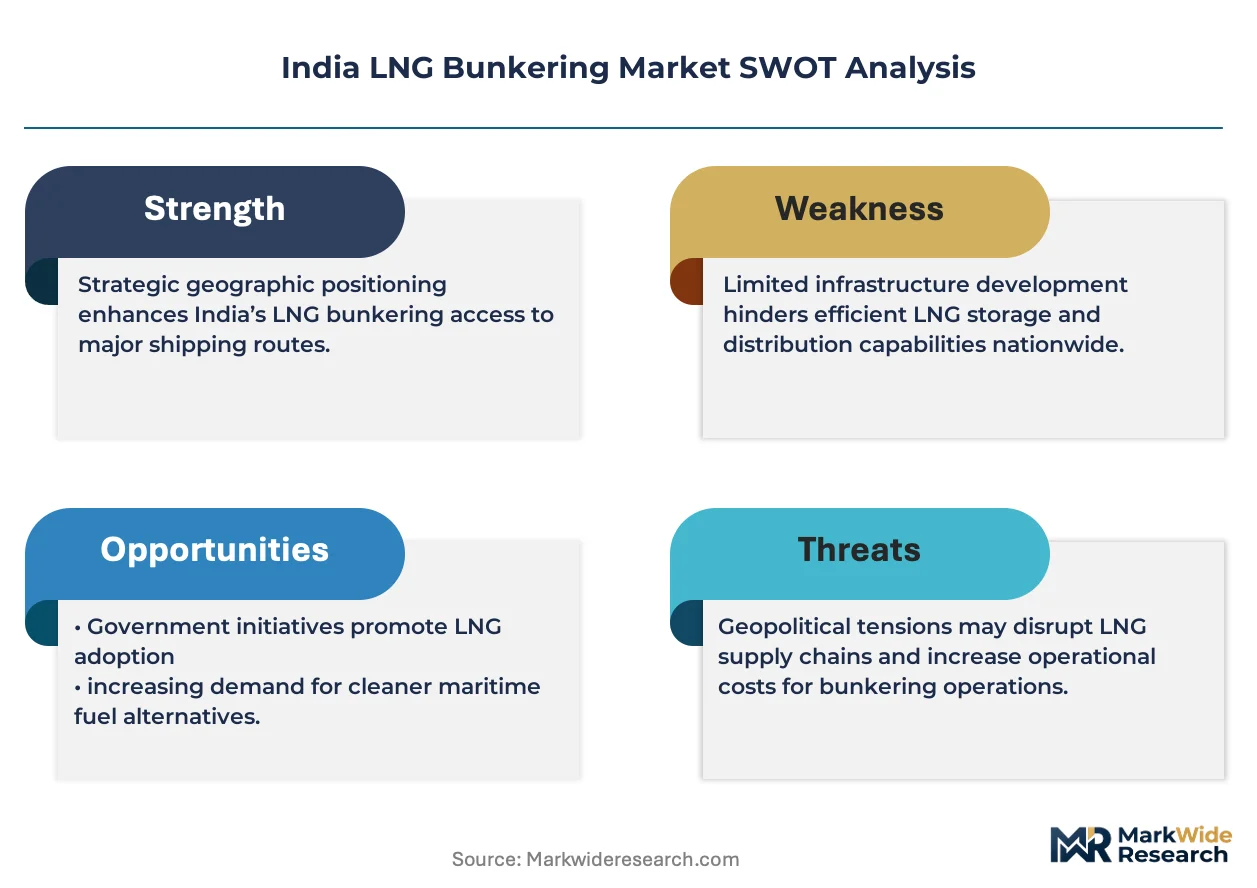
The India LNG bunkering market constitutes a defensive-moat opportunity anchored in regulatory entrenchment, where Coastal Regulatory Zone clearances and Petroleum and Natural Gas Regulatory Board licensing create multi-year barriers to terminal replication.
For Market Incumbents: Pre-empt emerging competition by securing exclusive berth-access agreements at Mundra Port and Kochi before minor port operators achieve critical mass. Anchor backward integration into cryogenic road tanker manufacturing to deflect margin pressure from imported equipment tariffs. Accelerate surveyor training programs to eliminate Directorate General of Shipping inspection backlogs that stall customer vessel certifications.
For New Entrants and Emerging Players: Establish a beachhead in the Ganga-Brahmaputra inland waterway corridor where National Waterways Act infrastructure investment outpaces incumbent coverage. Target truck-to-ship delivery at Haldia and satellite Gujarat harbors where fixed terminal economics fail. Pursue technical service differentiation through crew certification partnerships with engine manufacturers rather than competing on fuel price alone.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cryogenic storage fabrication as nickel alloy costs and specialized welding labor scarcity compound. Long-term viability centers on terminal-access positioning rather than pure trading margins. Monitor Coastal Regulatory Zone approval velocity as the critical inflection signal for infrastructure deployment feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Access Partnership | Secures priority berthing rights at Jawaharlal Nehru Port under Ministry of Ports mandates. |
| Cryogenic Handling Certification | Enables compliance with Directorate General of Shipping IGF Code amendments for vessel licensing. |
| Bunker Vessel Fleet Expansion | Reduces turnaround times at Mundra Port against truck-to-ship delivery constraints. |
| Inland Waterway Infrastructure | Captures National Waterways Act corridor demand ahead of fixed terminal deployment. |
| Dual-Fuel Engine Technical Service | Locks in vessel operator loyalty through crew training and compatibility certification. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with vessel fleet managers, port authority planning officers, cryogenic equipment procurement leads, and LNG terminal operations directors; and secondary validation through Petroleum and Natural Gas Regulatory Board filings, Directorate General of Shipping circulars, customs import data for cryogenic equipment, and project development databases for coastal infrastructure. Bottom-up vessel fleet conversion estimates triangulated against top-down terminal capacity expansion plans.
Forecast inputs considered bunkering method penetration across ship-to-ship, truck-to-ship, and barge supply modalities; vessel type segmentation spanning container lines, crude tankers, and inland waterway fleets; and regional regulatory cluster differentiation between Gujarat, Maharashtra, Kerala, and West Bengal. CAGRs derived from infrastructure commissioning timelines against vessel newbuild delivery schedules. Industry-specific inputs incorporated dual-fuel engine order backlogs at Indian shipyards and Coastal Regulatory Zone clearance velocity.
Macroeconomic conditions sit as an overlay; deviation in LNG spot pricing volatility, rupee-dollar exchange rates, or maritime trade volume would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and infrastructure approval timelines. Material shifts in IMO sulfur cap stringency or Petronet LNG terminal utilization rates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Smart Oilfield Market
Oil & Gas
Saudi Arabia Liner Hanger System Market
Oil & Gas
Australia LNG Bunkering Market
Oil & Gas
Oil and Gas Logistics Market
Oil & Gas
Oil and Gas Separation Equipment Market
Oil & Gas
Mud Logging Unit Market
Oil & Gas
Gabon Oil and Gas Market
Oil & Gas
Oil Field Drill Bits Market
Oil & Gas
Saudi Arabia Drilling Rigs Market
Oil & Gas
Global Upstream Petrotechnical Training Services Market
Oil & Gas
Geothermal Drilling Market
Oil & Gas
Mexico Oil and Gas Market
Oil & Gas
Middle-East Oil Country Tubular Goods (OCTG) Market
Oil & Gas
United Kingdom Oil and Gas Midstream Market
Oil & Gas
North America Wireline Services Market
Oil & Gas
Canada LNG Bunkering Market