
 Liquid Lithium Ion Battery Market | 2026-2036
Liquid Lithium Ion Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Lithium Ion Battery Market Insights
Project finance tied to gigafactory buildouts is tilting competitive access toward firms with sovereign-backed credit lines. Contemporary Amperex Technology Co. Limited leverages its vertical integration into cathode precursors to sustain margin capture. LG Energy Solution anchors its position through multi-year offtake agreements with premium automotive OEMs. BYD Company dominates captive demand through its in-house electric vehicle production pipeline.
Liquid lithium ion batteries employ organic carbonate electrolytes with dissolved lithium hexafluorophosphate salt, enabling ionic conductivity between 5 and 15 mS/cm at room temperature for high-rate charge and discharge cycles. These electrochemical systems primarily store and release electrical energy through intercalation reactions at graphite anodes and metal oxide cathodes. Prismatic cells occupy the dominant share in automotive traction applications where pack-level volumetric efficiency determines range performance. Pouch cells compete aggressively in portable electronics and premium electric vehicles where weight minimization and form factor flexibility command price premiums. Fast charging technology leads R&D allocation as OEMs demand sub-15-minute replenishment protocols without accelerating lithium plating degradation.
FDA oversight of medical device batteries, EPA hazardous waste rules for electrolyte disposal, and NHTSA crashworthiness standards for traction battery enclosures collectively shape product design and liability exposure. China's MIIT enforces GB standards for cell cycle life and thermal runaway propagation resistance that determine market access for domestic and imported suppliers. Stakeholders must track how solid electrolyte prototypes and sodium-ion alternatives redirect capital allocation before committing to liquid-electrolyte capacity expansions.
Market Dynamics
Fast-charging protocols below fifteen minutes are compressing cell chemistry tolerances and forcing thermal management redesigns across automotive and consumer electronics segments. OEMs now specify electrolyte formulations that withstand repeated lithium plating stress without cycle degradation penalties.
Growth Catalysts
- Automotive electrification mandates:China's MIIT enforces GB standards for thermal runaway propagation resistance, compelling cell manufacturers to upgrade separator and electrolyte formulations. Domestic OEM procurement volumes accelerate accordingly.
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases redirect investment toward liquid electrolyte systems with alternative salt chemistries and reduced environmental liability exposure.
- South Korea's cathode cluster:Concentrated precursor production around Samsung SDI and LG Energy Solution suppliers generates captive demand for high-purity lithium hexafluorophosphate and specialized carbonate solvents.
Market Restraints
- Fluorinated salt cost volatility:Lithium hexafluorophosphate pricing fluctuates with fluorspar concentrate availability and Chinese environmental enforcement cycles, compressing margin predictability for electrolyte blenders.
- Graphite anode supply concentration:Spherical natural graphite processing concentrates in China's Shandong and Heilongjiang provinces, exposing cell manufacturers to single-source geographic risk and export quota uncertainty.
- Solid electrolyte substitution timeline:Oxide and sulfide solid-state prototypes from Toyota and Samsung SDI laboratories threaten liquid electrolyte demand in premium automotive segments by the mid-2030s.
Strategic Opportunities
- India's PLI scheme for ACC batteries:Production-linked incentives for advanced chemistry cells create first-mover advantage for electrolyte suppliers establishing local blending capacity ahead of domestic cathode and anode material plants.
- Grid-scale stationary storage:Utility procurement of lithium iron phosphate systems for four-hour duration applications opens volume demand for lower-cost carbonate electrolyte formulations with relaxed high-rate specifications.
- Second-life battery certification:EU Battery Regulation mandatory disclosure of state-of-health data creates service revenue streams for diagnostic and reconditioning platforms using liquid cell electrochemical signatures.
Industry Challenges
- Electrolyte formulator talent scarcity:Formulation chemists with lithium salt stability expertise command premium compensation in South Korea and Japan, constraining R&D velocity for mid-tier cell manufacturers.
- Gigafactory commissioning timelines:Dry room humidity control and electrolyte filling line validation extend facility qualification periods, delaying revenue recognition against offtake commitments.
- UN 38.3 certification complexity:Transportation testing for lithium metal content and thermal stability adds six to nine months to new cell variant commercialization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Lithium Ion Battery Market |
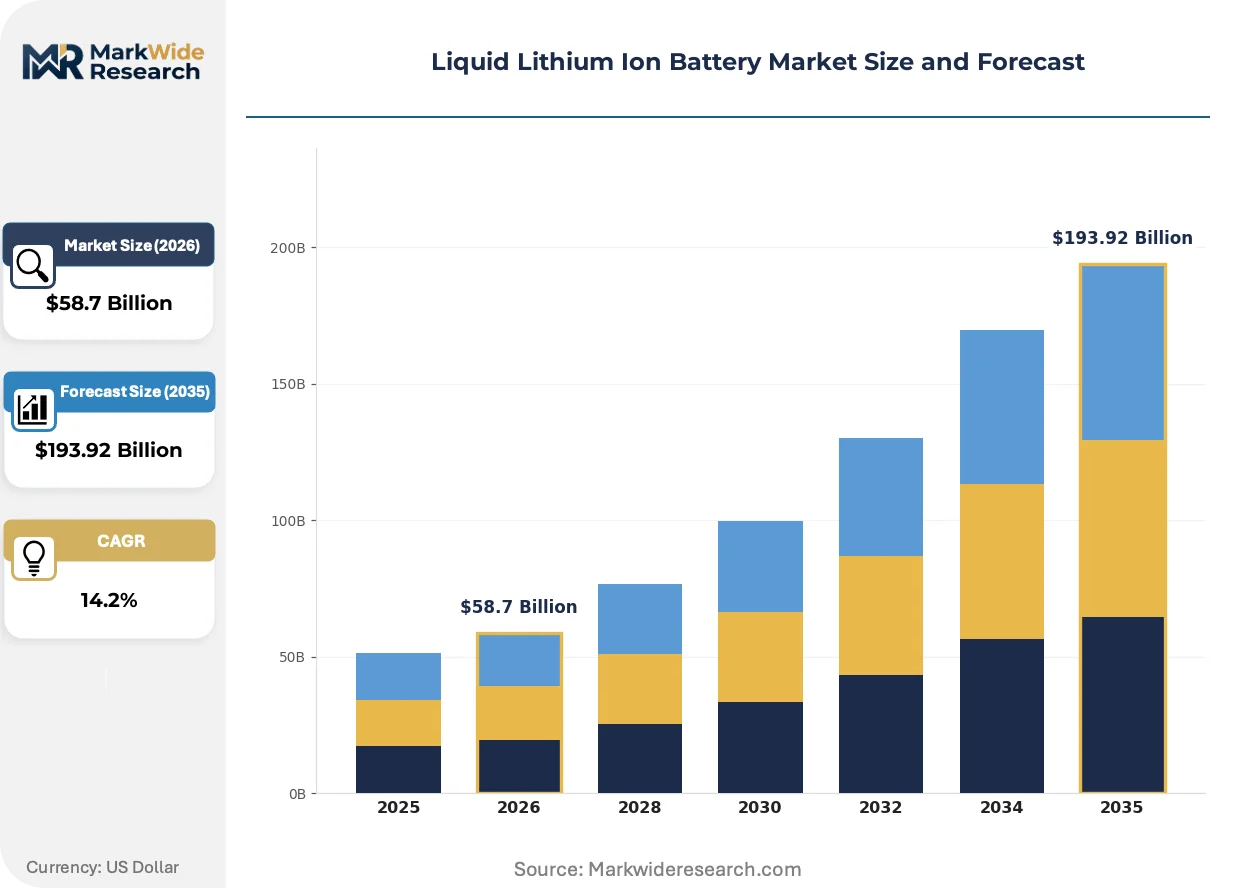
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $193.92 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic Cells, Cylindrical Cells, Coin Cells, Pouch Cells End User: Consumer Electronics, Automotive, Industrial, Aerospace Application: Energy Storage Systems, Electric Vehicles, Power Tools, Portable Electronics Technology: Graphene Technology, Solid Electrolyte, Fast Charging, Deep Cycle |
| Companies Covered | Contemporary Amperex Technology Co. Limited, LG Energy Solution, Panasonic Holdings Corporation, BYD Company, Samsung SDI, Tesla, Amperex Technology Limited, Saft Groupe S.A., A123 Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Lithium Ion Battery Market Trends and Innovations
Silicon oxide anode prelithiation and dual-salt electrolyte formulations are compressing conventional graphite-LiPF6 performance boundaries. Cell manufacturers now digitize manufacturing parameters to trace electrochemical degradation signatures across warranty periods.
Silicon composite anodes with prelithiated oxide coatings are digitizing energy density benchmarks in premium electric vehicle segments. Automotive OEMs in Germany and South Korea specify these materials for 2027 platform launches. The technology is digitizing pack-level gravimetric targets previously constrained by graphite theoretical limits.
China's GB 38031-2025 revision tightens thermal runaway propagation testing from five minutes to no-fire-no-explosion requirements for entire battery packs. Cell manufacturers must redesign venting mechanisms and electrolyte flash point formulations. Prismatic automotive cells face the steepest compliance redesign costs under this standard.
Fleet operators and energy storage developers now unbundle cell procurement from pack integration services, sourcing bare cells directly from manufacturers. This disintermediation compresses margin capture for traditional system integrators. The pattern is most visible in North American utility-scale storage deployments where independent power developers negotiate direct offtake agreements.
Liquid Lithium Ion Battery Market Segmentation
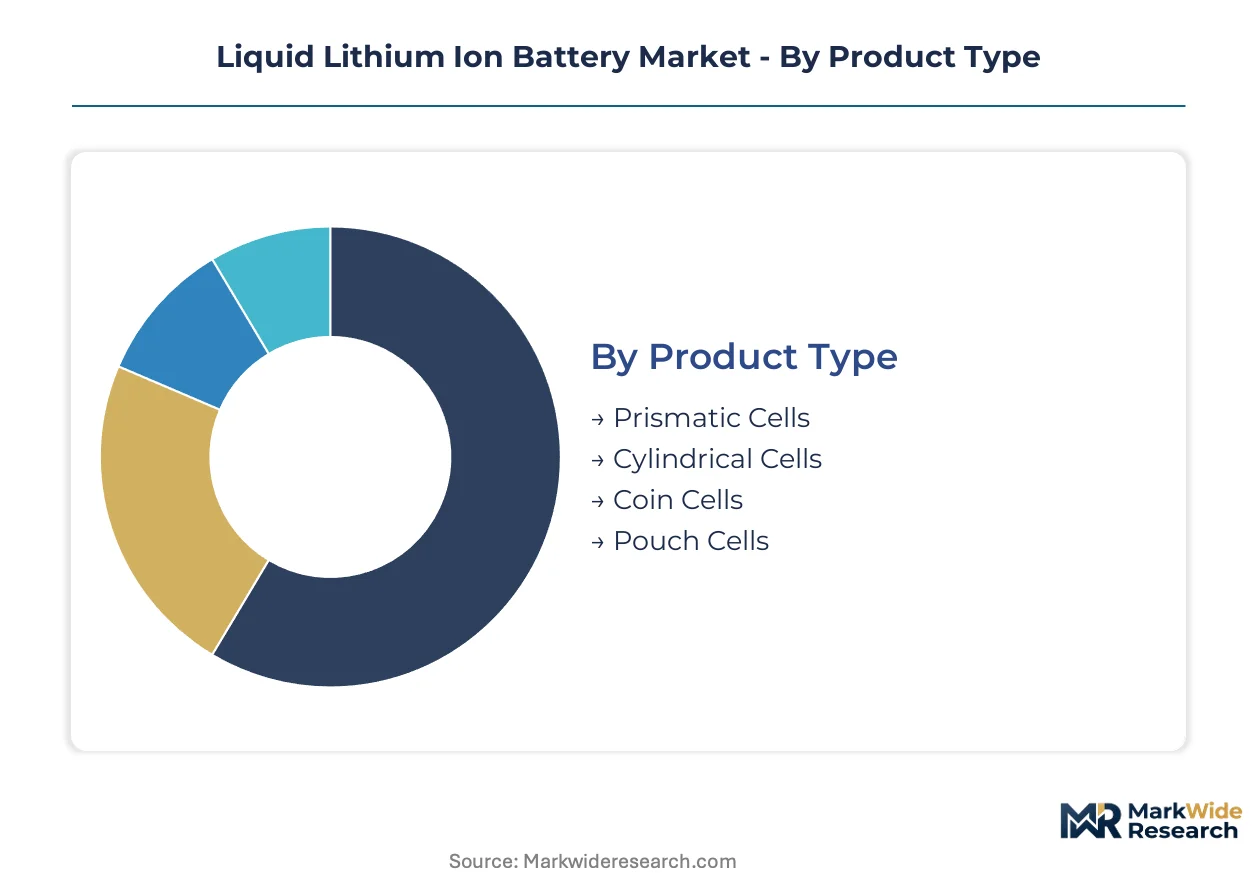
Liquid lithium ion battery segmentation reveals divergent replacement cycles across product architectures, with automotive traction cells turning over every 8-12 years while consumer electronics cells cycle in 2-4 year intervals. Understanding these temporal patterns shapes inventory planning and capacity allocation strategies for manufacturers.
Product Type:
Cycle times stretch from months for coin cells to over a decade for automotive prismatic formats, creating fundamentally different working capital requirements across the product matrix.
- Prismatic Cells:Aluminum-cased rectangular formats with stacked electrode layers deliver superior volumetric packing density for automotive battery packs. Chinese and German OEM procurement concentrates here, driven by GB 38031-2025 thermal propagation standards that favor rigid enclosure designs with integrated venting channels.
- Cylindrical Cells:Rolled jellyroll construction in standardized 18650, 2170, and 4680 formats enables high-speed automated winding and welding. Tesla's Nevada and Texas facilities anchor demand, with 4680 formats displacing smaller diameters as silicon anode loading increases.
- Coin Cells:Compact disc-shaped formats power medical devices, wearables, and IoT sensors with sub-100 mAh capacities. FDA device regulations and miniaturization trends in hearables sustain procurement volumes despite low unit values.
- Pouch Cells:Flexible aluminum-laminated polymer housings maximize gravimetric energy density through conformal pack integration. South Korean and Japanese premium EV platforms specify these for weight-critical applications where form factor adaptability commands price premiums.
Prismatic cells anchor the volume base while pouch cells gain share at the steepest rate.
End User:
Cost tier stratification separates mass-market consumer applications from aerospace qualification premiums that multiply unit economics by orders of magnitude.
- Consumer Electronics:Smartphones, laptops, and tablets drive the highest absolute cell volumes with thin-profile pouch and prismatic dominance. Chinese OEM assembly concentration in Shenzhen and Dongguan shapes regional demand patterns.
- Automotive:Battery electric vehicles and plug-in hybrids consume the largest capacity volumes per unit, with 60-100 kWh packs becoming standard. NHTSA crashworthiness standards and UN 38.3 transportation certification add compliance layers absent in consumer segments.
- Industrial:Forklifts, automated guided vehicles, and material handling equipment demand deep-cycle durability with 3,000+ cycle specifications. Warehouse automation adoption in the US and Germany sustains niche but stable procurement.
- Aerospace:Satellite power systems and electric aircraft prototypes require the most stringent qualification protocols, with DO-311A testing and radiation-hardened designs extending development timelines to 5-7 years.
Consumer electronics delivers the highest cell count while automotive expands most quickly in absolute capacity terms.
Application:
Customer type fragmentation separates utility procurement committees from individual consumer purchasing patterns with radically different decision timelines.
- Energy Storage Systems:Grid-scale lithium iron phosphate installations for 2-4 hour duration shifting prioritize cycle life over energy density. Independent power developers in Texas and California negotiate direct cell offtake agreements, disintermediating traditional integrators.
- Electric Vehicles:Passenger cars, commercial vans, and heavy-duty trucks constitute the dominant capacity sink, with 800V architectures and sub-15-minute fast charging protocols rewriting cell chemistry specifications.
- Power Tools:Cordless construction and garden equipment demand high-rate discharge capability with 20-30C burst tolerance. Milwaukee, DeWalt, and Makita battery platforms create proprietary form factor lock-in.
- Portable Electronics:Tablets, e-readers, and handheld gaming devices represent a contracting segment as smartphone screen sizes absorb adjacent categories.
Electric vehicles command the capacity base while energy storage systems climb the fastest as utility procurement accelerates.
Technology:
Supply concentration for advanced materials separates graphene-enhanced anodes from mature graphite formulations with divergent sourcing risk profiles.
- Fast Charging:Electrolyte additives and anode surface modifications enable 10-15 minute replenishment without lithium plating degradation. Silicon oxide prelithiation and dual-salt LiPF6/LiFSI formulations dominate R&D allocation.
- Deep Cycle:Lithium iron phosphate chemistry with optimized electrode porosity sustains 6,000+ cycles at 80% depth of discharge. Stationary storage and marine applications specify these for 15-year service life requirements.
- Graphene Technology:Conductive additive loading at 0.5-2 wt% improves rate capability and low-temperature performance. Chinese precursor production around Qingdao and Ningbo concentrates supply.
- Solid Electrolyte:Oxide and sulfide ceramic separators in laboratory prototypes threaten liquid electrolyte demand by the mid-2030s. Toyota and Samsung SDI development timelines remain the critical uncertainty.
Fast charging anchors current R&D investment while solid electrolyte development tracks the steepest capability expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands raw material pricing leverage through Shandong graphite processing dominance, while Germany's automotive OEMs absorb premium cathode active material costs. This asymmetry reshapes margin capture across cell manufacturing geographies.
China
MIIT-enforced GB 38031-2025 thermal runaway standards and captive electric vehicle demand from BYD and CATL drive cell procurement volumes. NMPA battery safety certifications create compliance barriers for imported electrolyte formulations. The Yangtze River Delta cluster around Ningbo and Suzhou concentrates lithium hexafluorophosphate blending capacity for domestic and export markets.
Germany
EU F-Gas Regulation restrictions on fluorinated greenhouse gases redirect OEM sourcing toward alternative salt chemistries. KBA vehicle-type approval processes add certification layers for traction battery systems. The Stuttgart-Munich corridor anchors Volkswagen and BMW platform development, with CATL's Erfurt facility supplying localized cell capacity.
United States
IRA production tax credits and NHTSA crashworthiness standards reshape domestic gigafactory investment timelines. EPA hazardous waste rules for electrolyte disposal constrain blending site selection. Tesla's Nevada and Texas facilities anchor cylindrical cell demand, with 4680 format adoption accelerating silicon anode integration.
South Korea
Samsung SDI and LG Energy Solution procurement concentrates cathode precursor demand around the Gyeonggi-Seoul industrial corridor. MFDS medical device battery oversight and KBA-equivalent automotive certifications create dual compliance tracks. The Busan-Ulsan petrochemical cluster supplies specialized carbonate solvents for high-voltage electrolyte formulations.
Japan
Toyota solid-state development timelines and Panasonic cylindrical cell supply agreements to Tesla anchor demand visibility. METI battery supply chain security initiatives promote domestic cathode material production. The Osaka-Kyoto-Kobe manufacturing belt concentrates precision coating equipment suppliers for electrode fabrication.
Liquid Lithium Ion Battery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation and materials leverage. The market exhibits tiered consolidation: three Asian conglomerates control automotive cell procurement volumes, while mid-tier electrolyte blenders compete on regional logistics and regulatory compliance velocity. Strategic archetypes separate vertical integrators with cathode precursor control, automotive-captive producers with demand certainty, and independent component suppliers with formulation specialization. Dominant competitive moves include multi-year offtake anchoring and backward integration into lithium salt production.
Among the named participants, Contemporary Amperex Technology Co. Limited exemplifies vertical integration architecture spanning precursor through cell assembly. LG Energy Solution occupies a position defined by premium automotive OEM anchoring through long-term supply agreements. BYD Company represents automotive-captive demand absorption with in-house electric vehicle production pipelines. These three entities collectively illustrate how geographic origin and corporate structure map to distinct competitive positioning within liquid lithium ion battery value chains.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co. Limited |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| BYD Company |
| Samsung SDI |
| Tesla |
| Amperex Technology Limited |
| Saft Groupe S.A. |
| A123 Systems |
| Others |
Pricing and Supply Chain Analysis
Shandong and Heilongjiang province concentration in spherical natural graphite processing anchors pricing power for Chinese anode suppliers, forcing Korean and Japanese cell manufacturers to absorb feedstock cost volatility or pursue captive mine investments. This geographic lock on critical raw materials concentrates margin capture upstream while compressing blender and pack assembler returns downstream.
Pricing Analysis
Configured-to-order electrolyte formulations command 15-25% premiums over standard carbonate blends, with automotive OEMs specifying additive packages for fast-charge compatibility. Pricing stratifies across premium, standard, and economy tiers based on lithium salt purity grades and UN 38.3 certification status. Cost compression in standard-grade cylindrical cells is intensifying because of 4680 format standardization and silicon anode yield improvements. Utility-scale energy storage developers exhibit highest price sensitivity, while aerospace qualification programs absorb premium multipliers without volume negotiation.
Supply Chain Analysis
Upstream feedstock concentration in China, Chile, and Australia for lithium carbonate and spodumene concentrate creates procurement vulnerability for European and North American cell plants. Electrolyte production draws from fluorspar-derived lithium hexafluorophosphate, specialized carbonate solvents, and high-purity lithium salts. Single-source vulnerability runs through China's Yangtze River Delta for salt blending capacity. Distribution runs through long-term offtake contracts directly to gigafactory sites, bypassing traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Liquid lithium ion battery incumbents face a substitution defense against solid-state oxide and sulfide prototypes from Toyota and Samsung SDI laboratories, requiring chemistry-level differentiation investments before mid-2030s demand erosion.
For Market Incumbents: Insulate core automotive revenue through multi-year offtake anchoring with premium OEM platforms and backward integration into lithium salt production. Solid-state substitution timelines from Korean and Japanese laboratories threaten liquid electrolyte demand in luxury vehicle segments. Certification velocity under China's GB 38031-2025 thermal runaway standards serves as the priority defensive lever. For New Entrants and Emerging Players: Pursue India's PLI scheme for advanced chemistry cells ahead of domestic cathode and anode material plant commissioning. Grid-scale stationary storage offers the most penetrable segment for new electrolyte blenders, with relaxed high-rate specifications enabling cost-competitive entry. Direct cell offtake negotiations with independent power developers in Texas and California provide the clearest go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward electrolyte formulators with established UN 38.3 certification capabilities and existing relationships with cylindrical cell manufacturers. Long-term viability across the next decade hinges on defensible formulation IP and geographic diversification beyond Chinese feedstock dependence. Samsung SDI and Toyota solid-state commercialization announcements signal the critical inflection indicator for liquid electrolyte demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Salt Production | CATL's captive precursor plants in Ningba reduce fluorspar price volatility exposure for automotive contracts. |
| Fast-Charge Electrolyte Formulation Development | Dual-salt LiPF6/LiFSI blends enable sub-15-minute replenishment protocols demanded by German OEM 800V platforms. |
| GB 38031-2025 Thermal Runaway Certification | MIIT-enforced no-fire-no-explosion pack standards create compliance barriers for imported electrolyte suppliers. |
| Direct Cell Offtake with Utility Developers | Texas and California IPP procurement committees now unbundle bare cell sourcing from system integration services. |
| Solid-State Prototype Monitoring Partnership | Toyota and Samsung SDI laboratory timelines determine capital allocation urgency for liquid-electrolyte capacity expansions. |
Research Methodology
A standing panel of cell manufacturing executives, electrolyte formulation chemists, automotive platform engineers, and utility procurement officers provided ongoing calibration against secondary validation. Primary fieldwork combined structured interviews with plant managers at Ningbo and Suzhou blending facilities, procurement leads at Korean cathode precursor suppliers, and distribution channel partners in the Busan-Ulsan petrochemical corridor. Secondary sources included MIIT GB standard filings, EPA hazardous waste disposal records, UN 38.3 certification databases, and SEC 10-K disclosures from publicly traded cell manufacturers. Bottom-up capacity buildout tracking and top-down OEM demand aggregation enabled cross-verification.
Scenario-bracketing around solid-state substitution timelines and fast-charge protocol adoption rates bounded high and low growth paths across the projection horizon. Segmentation modeling incorporated cell format architecture, end-use application, chemistry type, and regional regulatory cluster dimensions. CAGRs derived from installed capacity trajectories, vehicle electrification mandate compliance schedules, and utility storage procurement pipeline analysis. Silicon anode loading percentages and dual-salt electrolyte penetration served as technology-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive acceleration of solid-state commercialization by Toyota or Samsung SDI would shift outcomes beyond modeled ranges. Cross-checking against IEA battery demand projections and MIIT production license filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Lithium-Ion Batteries for Electric Vehicles Market
Lithium-ion Battery
India Electric Vehicle Battery Materials Market
Lithium-ion Battery
EV SOLID State Battery Market
Lithium-ion Battery
Lithium Iron Phosphate (LiFePO4) Battery Market
Lithium-ion Battery
China Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Europe Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
France Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium Solid-State Battery Market
Lithium-ion Battery
Advanced Lithium-Ion Batteries Market
Lithium-ion Battery
Solid State Battery Market
Lithium-ion Battery
Lithium-Ion Batteries Electric Bike Market
Lithium-ion Battery
Dual Carbon Battery Market
Lithium-ion Battery
Automotive Lithium Based Battery Market
Lithium-ion Battery
United States Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Lithium Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Pouch Lithium-Ion Batteries Market