
 USA Hydrogen Electrolyzer Market | 2026-2036
USA Hydrogen Electrolyzer Market Size, Share, and Industry Trends Forecast 2026-2036
USA Hydrogen Electrolyzer Market Analytics
Utility offtake agreements is tilting toward long-term power purchase contracts tied to dedicated renewable assets. Plug Power Inc. leverages its vertically integrated green hydrogen network to secure utility-scale deployments. Cummins Inc. anchors its position through electrolyzer manufacturing capacity in Minnesota. Nel Hydrogen competes on alkaline and PEM platform breadth for industrial clients.
A hydrogen electrolyzer splits water into hydrogen and oxygen using electrical current, with proton exchange membrane units operating at pressures up to 30 bar and temperatures near 80 degrees Celsius to feed fuel cell vehicles and industrial hydrogen pipelines. Alkaline electrolyzers occupy the mature cost-efficient tier for large-scale stationary installations, while solid oxide electrolyzers represent the emerging high-temperature pathway targeting efficiency gains above 80 percent when paired with industrial waste heat. The energy sector end user segment concentrates early megawatt-scale deployments, whereas transportation demand tracks fuel cell truck corridor buildouts.
The Department of Energy hydrogen and fuel cell program shapes R&D funding flows, while FERC interconnection rulings determine project timelines for grid-connected electrolysis. EPA power plant emissions standards indirectly strengthen the case for green hydrogen in fossil-fuel-dependent industrial processes. Stakeholders must weigh technology selection against regional electricity cost structures and offtake contract duration before committing capital.
Market Dynamics
The Inflation Reduction Act hydrogen production tax credit is compressing project payback periods and redrawing capital deployment maps across state lines. This single policy mechanism now dominates electrolyzer procurement timelines and technology selection criteria.
Growth Catalysts
- IRA Section 45V Credit:The tiered hydrogen production tax credit delivers up to three dollars per kilogram for renewable-powered electrolysis, making green hydrogen cost-competitive with gray hydrogen in Texas and Louisiana corridors.
- Steel Decarbonization Mandates:Federal Buy Clean procurement standards and state-level industrial emissions caps are forcing integrated steel mills to source green hydrogen for direct reduction iron furnaces.
- Gulf Coast Infrastructure:Existing hydrogen pipelines, salt cavern storage, and petrochemical offtake agreements cluster procurement decisions in Texas, Louisiana, and Mississippi.
Market Restraints
- Iridium Supply Concentration:PEM electrolyzer stack production depends on South African and Russian iridium refining, exposing project developers to price volatility and supply disruption risks.
- FERC Interconnection Queues:Grid-connected electrolysis projects face interconnection study delays stretching thirty-six to sixty months in ERCOT and CAISO territories.
- Alkaline Technology Efficiency Ceiling:Mature alkaline electrolyzer platforms plateau at sixty-five to seventy percent system efficiency, limiting their competitiveness against emerging solid oxide alternatives.
Strategic Opportunities
- Midwest Industrial Clusters:Ohio and Indiana steel and ammonia facilities lack pipeline hydrogen access, creating captive electrolyzer deployment opportunities for on-site generation.
- Waste Heat Integration:Solid oxide electrolyzer coupling with cement and steel plant exhaust heat streams can push system efficiencies above eighty percent.
- Utility-Scale Storage Arbitrage:ERCOT price volatility enables electrolyzer operators to produce hydrogen during negative pricing events and sell into industrial offtake contracts.
Industry Challenges
- Electrolyzer Technician Shortage:Stack assembly, membrane electrode fabrication, and high-pressure system commissioning require specialized skills that community colleges and trade programs have not yet scaled.
- Stack Degradation Modeling:Developers lack standardized lifetime performance data for PEM and alkaline systems operating on variable renewable power, complicating project finance due diligence.
- State Permitting Fragmentation:Electrolyzer projects trigger divergent air quality, water discharge, and hazardous material regulations across California, Texas, and New York jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Hydrogen Electrolyzer Market |
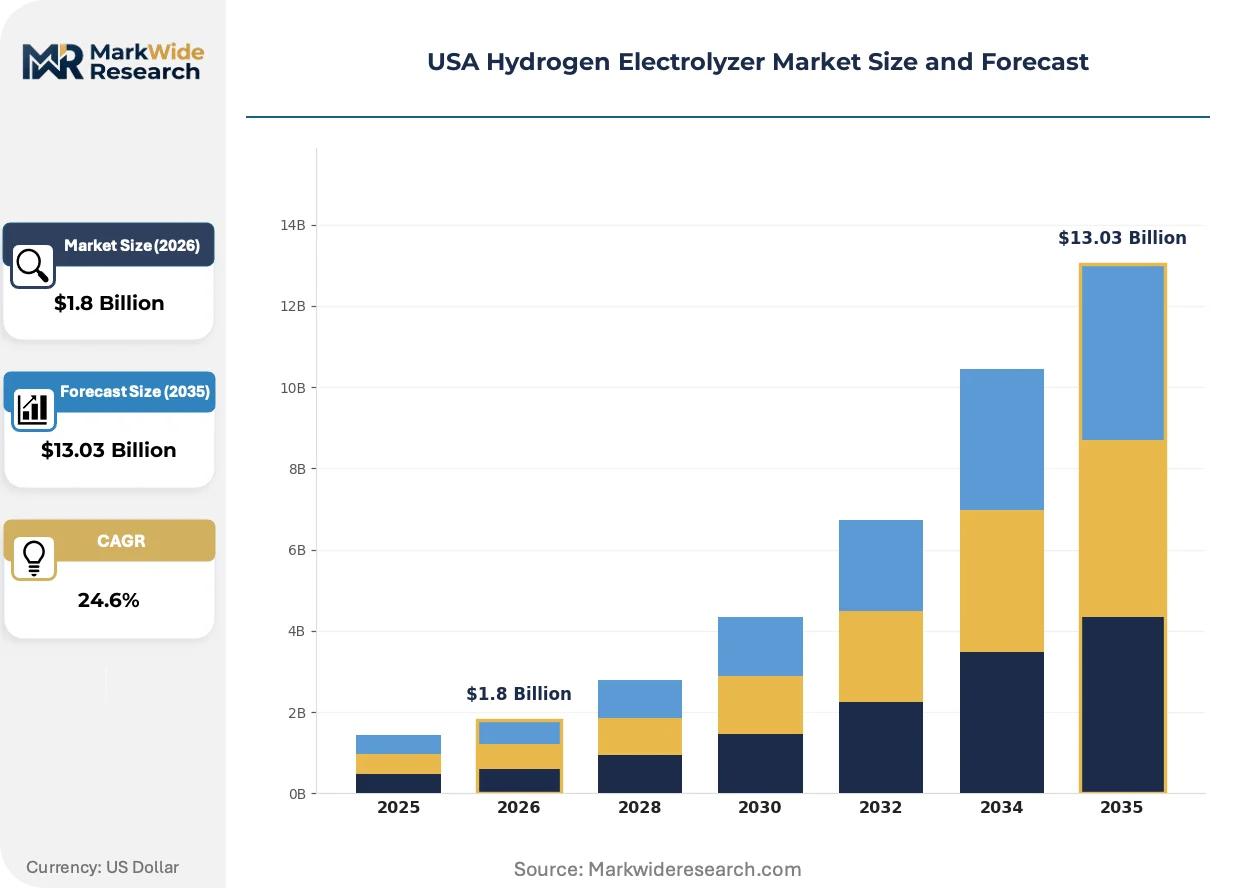
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $13.03 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline Electrolyzers, Proton Exchange Membrane, Solid Oxide Electrolyzers, Others End User: Energy Sector, Industrial Applications, Transportation, Chemical Production Deployment: On-site Generation, Centralized Plants, Modular Systems, Mobile Units Technology: Electrochemical, Renewable Energy Integration, High Temperature, Low Temperature |
| Companies Covered | Plug Power Inc., Bloom Energy, Cummins Inc., Nel Hydrogen, Accelera, Teledyne Energy Systems, Ohmium International, Electric Hydrogen, Next Hydrogen Solutions Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Hydrogen Electrolyzer Market Evolving Landscape
Digitization of electrolyzer control systems and stack manufacturing automation are compressing capital costs while enabling remote performance optimization. These shifts are reconfiguring supplier capabilities and buyer expectations simultaneously.
Advanced manufacturing software is virtualizing electrolyzer stack assembly lines, allowing manufacturers to simulate thermal management and catalyst loading before physical production. Industrial automation vendors are deploying these digital twin platforms across Minnesota and Ohio manufacturing facilities. The technology is virtualizing quality control processes that previously required destructive testing, compressing R&D cycles from months to weeks.
EPA power plant emissions standards are tightening the compliance window for industrial hydrogen consumers, indirectly mandating electrolyzer adoption for process heat applications. The rulemaking creates binding obligations for refineries and chemical plants in the Gulf Coast and Midwest. California and Washington state regulators are mirroring these federal standards with accelerated timelines, forcing early procurement decisions.
Industrial offtake agreements now specify hydrogen delivery obligations rather than equipment ownership, transferring operational risk to electrolyzer operators. Steel and ammonia producers in Texas and Louisiana are signing fifteen to twenty-year contracts with guaranteed carbon intensity thresholds. This contracting shift concentrates capital deployment in merchant electrolyzer projects with utility-scale renewable power purchase agreements.
USA Hydrogen Electrolyzer Market Segmentation
Electrolyzer procurement patterns diverge sharply across technology platforms and deployment configurations. End-use requirements for hydrogen purity, pressure, and carbon intensity reshape equipment specifications for each buyer category.
Product Type:
The maturity spectrum spans decades-old alkaline designs through emerging solid oxide architectures still in pilot phases.
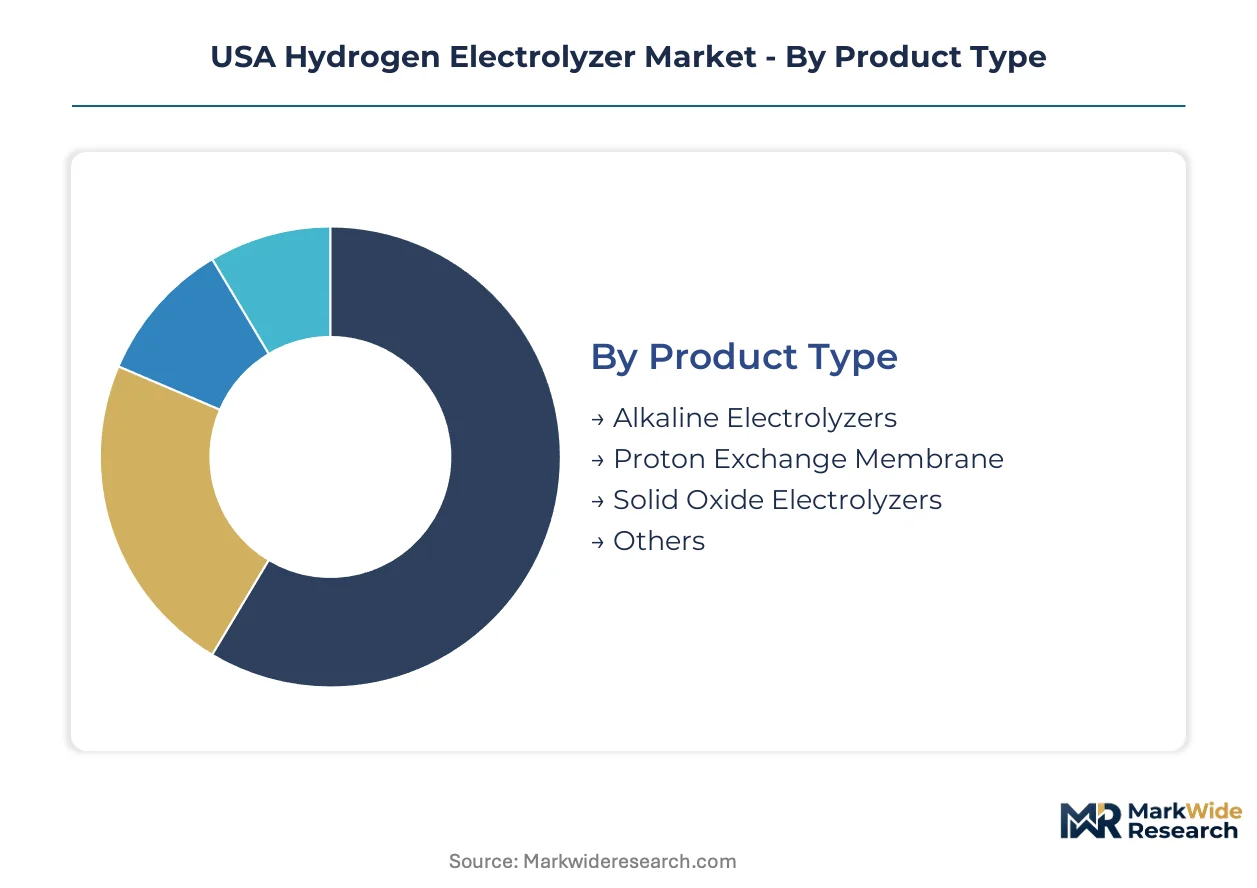
- Alkaline Electrolyzers:These systems deploy liquid potassium hydroxide electrolyte and nickel-based electrodes in bipolar or unipolar configurations, achieving system efficiencies of 65-70 percent at capital costs below PEM alternatives. Demand concentrates in Gulf Coast ammonia plants and Texas refineries where large baseload hydrogen volumes and existing grid infrastructure favor proven reliability over cutting-edge performance.
- Proton Exchange Membrane:PEM units utilize solid polymer electrolyte membranes and platinum-group metal catalysts to deliver high-purity hydrogen at pressures up to 30 bar without external compression. California and Northeast corridor deployments dominate, driven by fuel cell vehicle refueling stations and industrial sites requiring rapid response to variable renewable power.
- Solid Oxide Electrolyzers:High-temperature ceramic cells operating at 700-800°C achieve theoretical efficiencies exceeding 80 percent when integrated with industrial waste heat streams. Steel mills in Ohio and Indiana pilot these systems for direct reduction iron applications.
- Others:Anion exchange membrane and reversible fuel cell electrolyzer hybrids occupy niche demonstration roles at national laboratory testbeds.
Alkaline electrolyzers retain volume leadership; solid oxide electrolyzers hold the steepest expansion curve.
End User:
Application intensity varies from continuous industrial baseload to intermittent transportation fueling cycles.
- Energy Sector:Utility-scale power-to-gas projects and grid balancing services deploy multi-megawatt electrolyzer arrays for seasonal storage and synthetic natural gas production. ERCOT territory installations leverage negative pricing events to arbitrage hydrogen production against wholesale electricity markets.
- Industrial Applications:Steel direct reduction furnaces, ammonia synthesis loops, and methanol production facilities constitute the dominant procurement segment. Federal Buy Clean procurement standards and state industrial emissions caps force integrated mills toward green hydrogen sourcing.
- Transportation:Heavy-duty fuel cell truck corridors and port drayage operations drive demand for high-pressure hydrogen at 350-700 bar. California hydrogen highway stations and Texas freight corridors anchor near-term deployments.
- Chemical Production:Refinery hydrocracking and desulfurization units, plus specialty chemical hydrogenation reactions, source electrolytic hydrogen to meet EPA power plant emissions compliance deadlines.
Industrial applications command the largest installed base; transportation is climbing the fastest toward commercial scale.
Deployment:
Capital deployment models split between captive on-site generation and merchant centralized production with pipeline delivery.
- On-site Generation:Industrial facilities lacking pipeline hydrogen access install dedicated electrolyzer systems with direct renewable power purchase agreements. Ohio and Indiana steel clusters favor this model to bypass Gulf Coast infrastructure constraints.
- Centralized Plants:Utility-scale electrolyzer farms exceeding 100 MW capacity aggregate renewable energy at transmission-scale interconnection points. Texas and Louisiana salt cavern storage complexes enable these merchant hydrogen production hubs.
- Modular Systems:Containerized skid-mounted units allow capacity scaling through standardized replication, reducing engineering procurement construction timelines for project developers facing FERC interconnection queue delays.
- Mobile Units:Trailer-mounted electrolyzer systems serve temporary construction sites, emergency response operations, and remote mining camps with hydrogen fuel cell power.
Centralized plants attract the most capital commitment; modular systems are gaining share fastest among risk-averse industrial offtakers.
Technology:
Thermodynamic operating regimes separate low-temperature aqueous systems from high-temperature solid-state architectures.
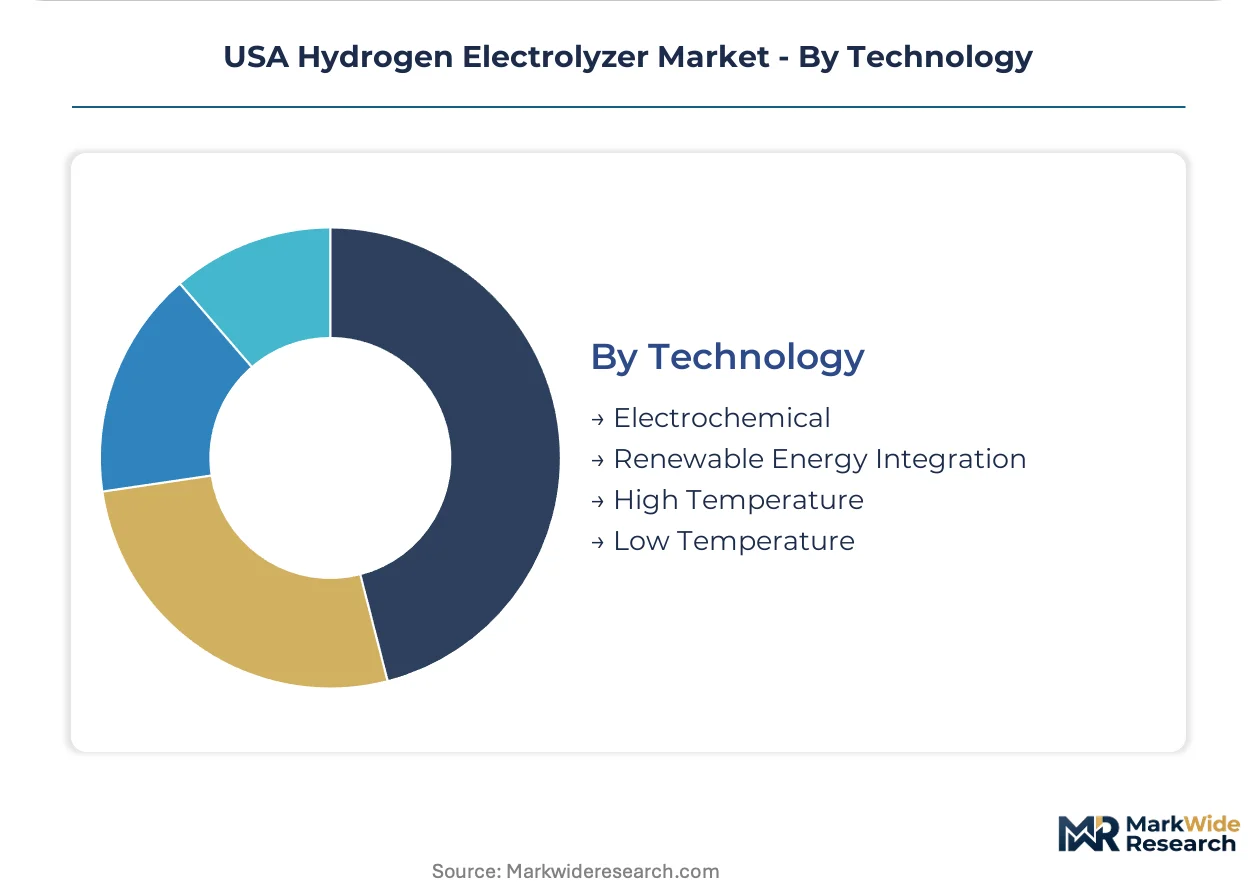
- Electrochemical:Direct current-driven water splitting in alkaline or acidic media constitutes the dominant commercial pathway, with stack designs optimized for either steady-state or variable renewable power input.
- Renewable Energy Integration:Power electronics and control systems enabling direct coupling with solar PV and wind generation without grid interconnection, reducing FERC queue exposure and capture price volatility.
- High Temperature:Solid oxide and molten carbonate systems exploit thermal energy inputs to reduce electrical work requirements, targeting cement and steel plant waste heat integration.
- Low Temperature:Ambient-temperature alkaline and PEM systems minimize materials degradation and thermal management complexity for distributed deployments.
Electrochemical platforms retain manufacturing scale advantages; renewable energy integration capabilities are expanding most quickly as a procurement discriminator.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC interconnection rulings and EPA emissions standards concentrate electrolyzer deployment decisions in Texas and Louisiana corridors where existing hydrogen infrastructure intersects with renewable development zones.
Texas Gulf Coast
Refinery hydrogen demand and salt cavern storage capacity anchor megawatt-scale electrolyzer procurement in Houston and Beaumont-Port Arthur complexes. ERCOT negative pricing events enable production arbitrage against industrial offtake contracts. The Port of Houston and Corpus Christi industrial clusters host pilot deployments tied to ammonia export terminal expansions.
Louisiana Industrial Corridor
Petrochemical hydrogen consumption and existing pipeline networks concentrate project development along the Mississippi River between Baton Rouge and New Orleans. State industrial tax incentives complement federal IRA credits for facilities serving ammonia and methanol producers. The Lake Charles chemical complex advances front-end engineering for integrated renewable hydrogen supply chains.
California Central Valley
Fuel cell vehicle corridor buildouts and port drayage electrification mandate drive high-pressure electrolyzer demand in Fresno and Stockton logistics hubs. CARB Low Carbon Fuel Standard credits stack with federal incentives for renewable hydrogen production. The Port of Long Beach and Oakland container terminals pilot electrolyzer-fed hydrogen fueling for heavy-duty trucking.
Ohio River Valley
Steel direct reduction furnace retrofits and captive ammonia synthesis create on-site electrolyzer opportunities in Cleveland and Pittsburgh industrial clusters. Federal Buy Clean procurement standards force integrated mills toward green hydrogen sourcing. The Youngstown-Warren manufacturing corridor lacks pipeline hydrogen access, favoring modular distributed generation systems.
Pacific Northwest
Low-cost hydroelectric power and aluminum smelter industrial demand position electrolyzer projects in Columbia River Gorge and Portland metro areas. Bonneville Power Administration transmission access reduces interconnection queue exposure for renewable-coupled installations. The region's clean electricity profile satisfies IRA Section 45V carbon intensity thresholds without additional power purchase agreements.
USA Hydrogen Electrolyzer Market Competitive Landscape
Vertically integrated hydrogen networks and specialized electrolyzer manufacturers split the market between captive supply chain control and component-focused scale economics. The vendor base clusters around three strategic archetypes: integrated green hydrogen producers, industrial equipment conglomerates with electrolyzer divisions, and pure-play electrochemical technology specialists. Capacity expansion and strategic partnerships dominate competitive moves as developers secure manufacturing scale and offtake relationships simultaneously.
Among integrated hydrogen network operators, Plug Power Inc. exemplifies the captive supply chain archetype through its vertically positioned generation and distribution assets. Cummins Inc. and Nel Hydrogen occupy distinct positions within the industrial equipment and pure-play technology tiers respectively, with each representing alternative pathways to market participation. These three companies illustrate the strategic divergence between backward integration into renewable generation and focused stack manufacturing specialization.
| Leading Market Players |
|---|
| Plug Power Inc. |
| Bloom Energy |
| Cummins Inc. |
| Nel Hydrogen |
| Accelera |
| Teledyne Energy Systems |
| Ohmium International |
| Electric Hydrogen |
| Next Hydrogen Solutions Inc. |
| Others |
Value Network & Pricing Analysis
Houston-Gulf Coast electrolyzer manufacturing clusters concentrate stack assembly capacity and exert downstream pricing leverage over Midwest industrial buyers lacking pipeline hydrogen access. PEM system premiums widen against alkaline alternatives as South African iridium supply constraints tighten catalyst cost structures. Merchant project developers capture margin through long-term offtake contracts that transfer operational risk to steel and ammonia producers.
Pricing Analysis
Texas-to-California price spreads for equivalent PEM capacity exceed thirty percent due to FERC interconnection queue delays and state-level permitting fragmentation. Project-based long-term contracting dominates, with price differentiation driven by IRA Section 45V credit qualification status and guaranteed carbon intensity thresholds. Cost compression in alkaline tiers intensifies as Chinese stack imports pressure domestic manufacturers. Captive on-site buyers in Ohio and Indiana exhibit highest price sensitivity; utility-scale merchant operators in ERCOT territory show lowest sensitivity due to negative pricing arbitrage opportunities.
Supply Chain Analysis
Export control regimes under the Department of Commerce restrict solid oxide electrolyzer ceramic cell technology transfers, constraining domestic manufacturing scale-up. Stack production draws from South African iridium refining, Chinese nickel mesh substrates, and German power electronics. Single-source vulnerability concentrates in platinum-group metal catalyst supply. Distribution runs through EPC contractors with established utility relationships rather than direct OEM-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating around fifteen-to-twenty-year hydrogen offtake contracts that transfer operational risk to electrolyzer operators and compress vendor margins. Steel mill procurement consortiums in the Ohio River Valley amplify price negotiation leverage against equipment suppliers.
For Market Incumbents: Harden stack manufacturing margins by securing captive iridium supply agreements with South African refiners before export restrictions tighten. Expand Minnesota and Ohio production capacity to serve Midwest industrial clusters bypassing Gulf Coast infrastructure constraints. Defend against solid oxide technology displacement by accelerating alkaline efficiency improvements through waste heat integration partnerships with cement producers.
For New Entrants and Emerging Players: Pacific Northwest hydroelectric zones offer underpenetrated utility-scale opportunities where Bonneville Power Administration transmission access eliminates FERC queue exposure. Target modular containerized systems for Ohio and Indiana steel mills lacking pipeline hydrogen access. Lead with renewable energy integration capabilities that enable direct solar PV coupling without grid interconnection.
For Investors and Strategic Acquirers: Long-term, this sits as a policy-credit arbitrage play because IRA Section 45V qualification status determines project returns more than technology differentiation. Prioritize acquisition targets with established utility offtake relationships and secured renewable power purchase agreements. Watch FERC interconnection queue reform proposals as the signal for capital deployment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Minnesota and Ohio manufacturing expansions serve Midwest steel clusters lacking Gulf Coast pipeline access. |
| Power Purchase Agreement | ERCOT renewable contracts enable negative pricing arbitrage for merchant hydrogen production hubs. |
| Technology Licensing | Solid oxide electrolyzer ceramic cell IP transfers accelerate waste heat integration for steel mill retrofits. |
| Backward Integration | Captive iridium supply agreements with South African refiners mitigate catalyst cost volatility exposure. |
| Green Certification Program | IRA Section 45V carbon intensity verification secures three-dollar-per-kilogram production tax credits. |
Research Methodology
A standing panel of utility planning officers, IPP project developers, EPC contractors, and industrial hydrogen procurement managers provided ongoing calibration across primary interview rounds. Secondary validation drew from EIA generation data, FERC interconnection filings, IEA hydrogen technology reports, and EPA power plant emissions compliance databases. Bottom-up electrolyzer deployment tallies triangulated against top-down IRA credit allocation forecasts.
Scenario-bracketing anchored projections across conservative, baseline, and accelerated IRA implementation pathways. Segmentation dimensions spanned technology platform, end-use application, deployment configuration, and regional grid type. CAGRs derived from installed capacity build rates and industrial offtake contract velocity. Key inputs included FERC queue clearance timelines, steel mill decarbonization mandates, and renewable energy zone interconnection costs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese stack manufacturers or solid oxide technology specialists would shift outcomes. Material shifts in IRA Section 45V credit eligibility thresholds or FERC interconnection reform timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Green Hydrogen Market
Hydrogen Energy
Green Hydrogen Dispensing Equipment Market
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
Hydrogen Purification Market
Hydrogen Energy
Hydrogen Station Market
Hydrogen Energy
Hydrogen for Mobility Market
Hydrogen Energy
Hydrogen Purifiers Market
Hydrogen Energy
High-Pressure Hydrogen Tanks Market
Hydrogen Energy
Global Hydrogen Electrolyzers Market
Hydrogen Energy
Asia-Pacific Clean Hydrogen Market
Hydrogen Energy
Hydrogen Production Electrolyser Market
Hydrogen Energy
Water Electrolysis Green Hydrogen Production Market
Hydrogen Energy
Electrolyzer Market
Hydrogen Energy
Hydrogen Generator Market
Hydrogen Energy
Europe Hydrogen Generation Market
Hydrogen Energy
Alkaline Water Electrolysis Market