
 Smart Meter Battery Market | 2026-2036
Smart Meter Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Meter Battery Market Insights
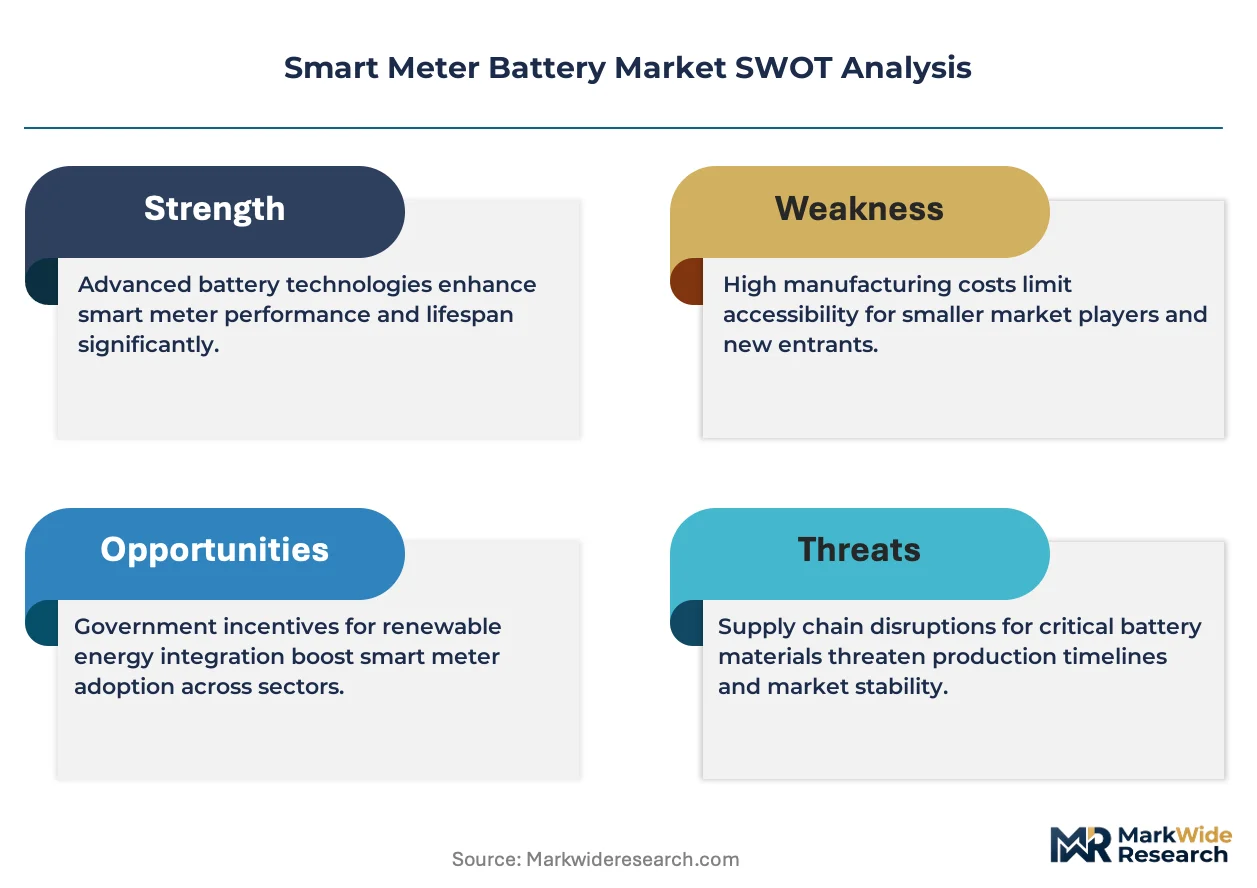
The capital-intensity divergence between large-format lithium producers and niche solid-state developers is bifurcating competitive dynamics in the Smart Meter Battery landscape. Saft Groupe SA leverages its European manufacturing footprint to sustain long-term supply agreements with continental utilities. Tadiran Batteries GmbH specializes in lithium thionyl chloride chemistries for extended-life outdoor installations. Panasonic Corporation anchors its position through backward integration into cell materials and precision engineering capabilities.
Smart meter batteries are electrochemical energy storage devices engineered to deliver stable power across extreme temperature cycles, typically operating between minus forty and plus eighty-five degrees Celsius with decade-plus service life requirements. Their primary purpose is ensuring uninterrupted telemetry, tamper detection, and remote disconnect functionality in distributed metering endpoints. Lithium-ion formulations dominate utility-scale Advanced Metering Infrastructure deployments where high energy density and low self-discharge justify unit economics. Solid-state architectures represent the fastest-expanding technology segment as manufacturers target the safety and thermal stability demands of IoT-integrated grid networks. Nickel Metal Hydride retains residual share in cost-sensitive residential retrofits where legacy compatibility constrains chemistry migration.
The EU Green Deal and F-Gas Regulation restrict fluorinated gas use in battery manufacturing processes, compelling European producers toward cleaner electrolyte formulations. The EPA's hazardous waste rules and OSHA workplace exposure limits shape domestic U.S. production standards and recycling obligations for lithium-based systems. Stakeholders must monitor evolving chemistry certification requirements across multiple jurisdictions while calibrating R&D portfolios between proven lithium platforms and emerging solid-state architectures.
Market Dynamics
Utility procurement departments are compressing supplier qualification timelines from 24 months to 14 months as AMI deployment schedules accelerate, forcing battery manufacturers to front-load certification investments before revenue recognition.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon use in conventional battery electrolytes is redirecting R&D budgets toward fluorine-free formulations, opening procurement windows for compliant suppliers.
- AMI 2.0 specifications:Next-generation metering infrastructure in Germany and the United States demands 20-year battery life guarantees, expanding addressable volume for high-density lithium thionyl chloride systems.
- Water utility digitization:Municipal water districts across China are retrofitting mechanical meters with ultrasonic flow sensors and radio modules, creating parallel demand streams beyond electric and gas metering.
Market Restraints
- Lithium raw material concentration:Spodumene processing capacity clusters in Western Australia and Chile's Salar de Atacama, exposing cell manufacturers to concentrate offtake bottlenecks and freight rate volatility.
- REACH compliance costs:European Chemicals Agency registration fees for novel electrolyte salts exceed €250,000 per substance, deterring mid-tier producers from chemistry innovation.
- Nickel-metal hydride residual demand:Legacy residential meter fleets in cost-constrained utilities continue specifying NiMH cells, delaying full chemistry transition and fragmenting production scale.
Strategic Opportunities
- India smart city mandates:The Ministry of Housing and Urban Affairs targets 100 smart cities with integrated utility metering, creating greenfield deployment opportunities without legacy infrastructure drag.
- Solid-state electrolyte convergence:Sulfide-based ceramic separators combined with lithium metal anodes promise 40% energy density gains for sub-zero climate installations in Nordic countries.
- Direct utility contracting:Bypassing traditional meter OEMs through framework agreements with EDF, Enel, and State Grid reduces channel margin extraction and accelerates specification influence.
Industry Challenges
- Cell matching precision:Smart meter battery packs require milliampere-hour tolerance matching across 10-year production lots, demanding statistical process control capabilities that exceed consumer electronics standards.
- IEC 62055 certification timelines:Utility payment meter battery approvals require 18-month accelerated aging protocols, compressing product launch windows against procurement deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Meter Battery Market |
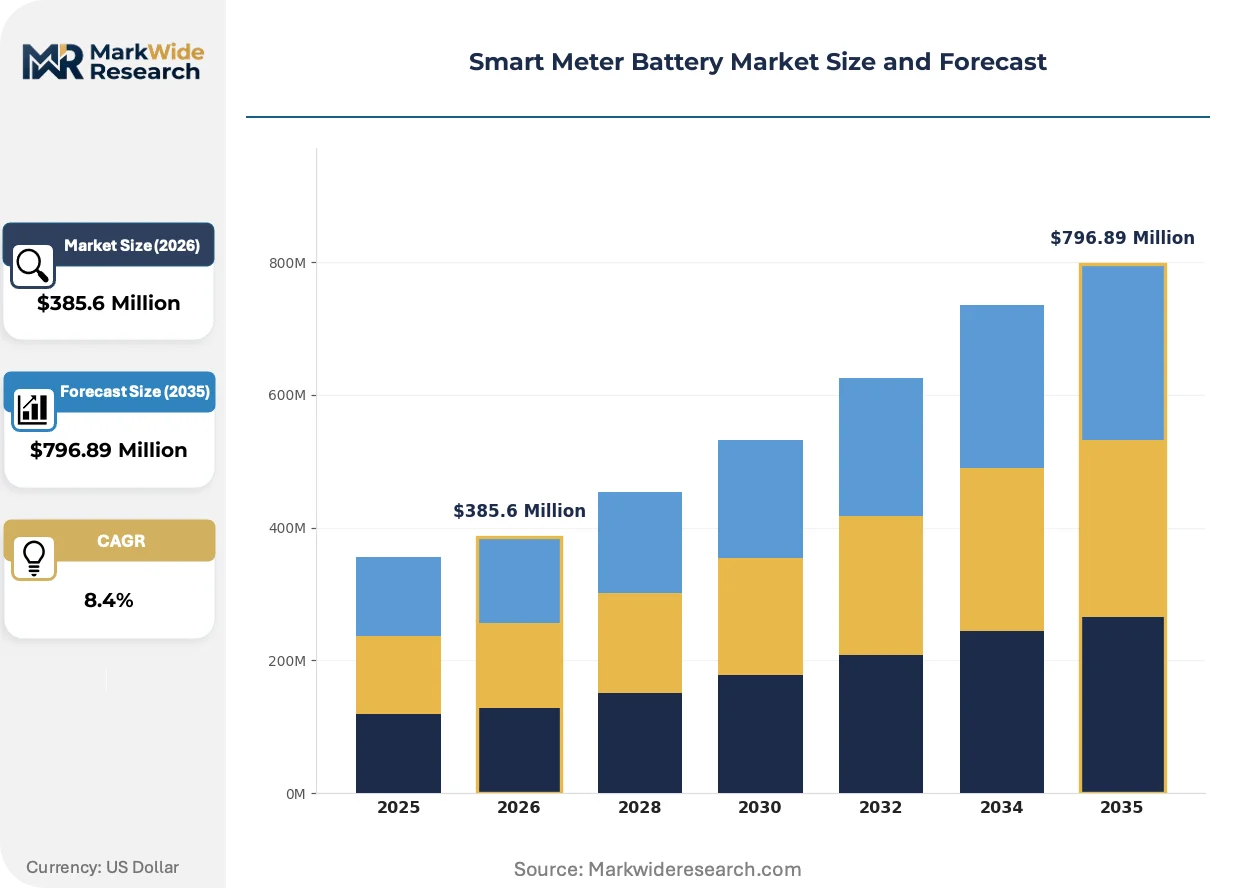
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Lithium-ion, Nickel Metal Hydride, Lead Acid, Solid-State End User: Utilities, Residential, Commercial, Industrial Technology: Advanced Metering Infrastructure, Remote Monitoring, Smart Grid, IoT Installation Type: Indoor, Outdoor, Retrofit, New Installation |
| Companies Covered | Saft Groupe SA, Tadiran Batteries GmbH, VARTA Microbattery GmbH, Panasonic Corporation, Ultralife Corporation, EVE Energy, Duracell, Hitachi Maxell, HCB Battery Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Meter Battery Market Trends and Innovations
Solid-state architectures are forcing a recalibration of manufacturing equipment and quality protocols across the supplier base. Three developments are compressing competitive timelines.
Lithium metal anodes paired with ceramic electrolytes are displacing conventional graphite-silicon composite anodes in pilot production lines. German utilities E.ON and Innogy have qualified solid-state prototypes for 2027 field trials. The technology is displacing incumbent lithium-ion cell formats in premium AMI segments where thermal runaway tolerance commands specification priority.
Europe's F-Gas Regulation mandates 79% hydrofluorocarbon reduction by 2030, prohibiting perfluorinated solvents in electrolyte formulations. Cell manufacturers are reformulating with carbonate-based alternatives that degrade faster at elevated temperatures. The restriction most affects outdoor gas meter deployments in Poland and Romania, where suppliers are pre-qualifying fluorine-free cells two years ahead of mandate deadlines.
Utility procurement departments are consolidating supplier panels from twelve vendors to four per geography, demanding decade-long price locks and dedicated capacity reservations. Aggregated buying cooperatives in Texas and California are replacing individual utility RFPs. The concentration is most visible in the United States, where Edison Electric Institute members have harmonized technical specifications across 30 million meter endpoints.
Smart Meter Battery Market Segmentation
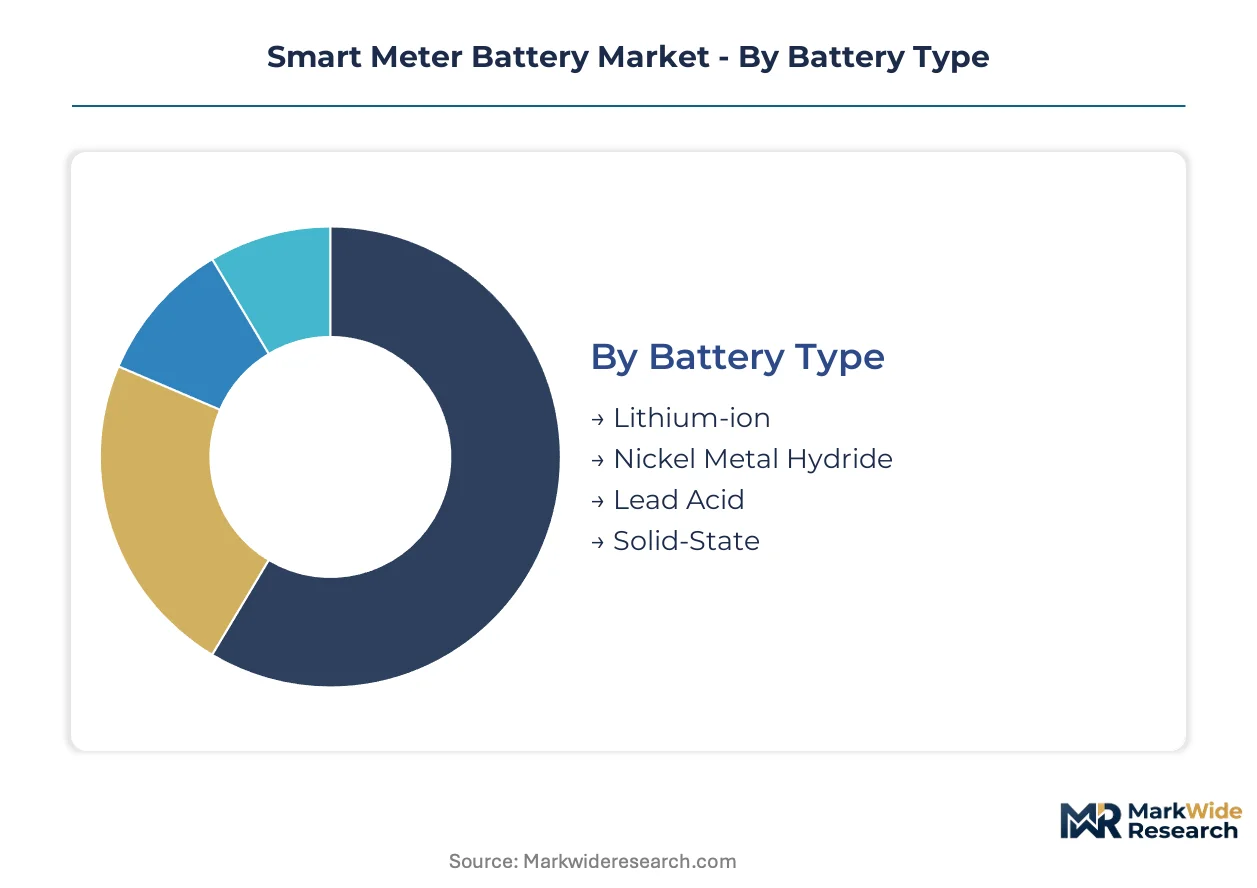
Smart meter battery procurement diverges sharply across chemistry platforms and deployment contexts, with substitution pressures from solid-state architectures reshaping supplier R&D priorities. Understanding segment boundaries clarifies where incumbent lithium-ion formats retain defensible positions versus where emerging chemistries capture specification influence.
Battery Type:
Substitution pressure concentrates most intensely on nickel metal hydride and lead acid formats as lithium thionyl chloride and solid-state alternatives extend service life guarantees.
- Lithium-ion:Dominates utility-scale Advanced Metering Infrastructure deployments through energy density advantages above 200 Wh/kg and self-discharge rates below 3% monthly. Demand concentrates in Germany and the United States where E.ON and Consolidated Edison specify 15-year minimum service intervals for outdoor electric meter installations, though thermal runaway risks constrain adoption in sub-zero Nordic climates.
- Solid-State:Ceramic electrolyte architectures paired with lithium metal anodes eliminate flammable liquid components while targeting 40% energy density gains over conventional lithium-ion. German utilities E.ON and Innogy have qualified prototypes for field trials, with sulfide-based separators showing particular promise for temperature cycling between minus forty and plus eighty-five degrees Celsius in Estonian and Finnish deployments.
- Nickel Metal Hydride:Retains residual specification in cost-constrained residential retrofits where legacy compatibility delays chemistry migration.
- Lead Acid:Survives in isolated rural installations with minimal telemetry requirements and established maintenance infrastructure.
Lithium-ion anchors the volume base while solid-state gains share at the steepest rate.
End User:
Procurement scale and technical sophistication separate utility buyers from fragmented residential and commercial segments.
- Utilities:Centralized procurement departments at State Grid, EDF, and Enel dominate volume through framework agreements covering millions of endpoints. These buyers mandate IEC 62055 certification, 20-year life guarantees under AMI 2.0 specifications, and dedicated capacity reservations that exclude smaller cell manufacturers from qualification.
- Commercial:Property management firms and retail chains specify batteries for sub-metering installations in multi-tenant buildings, prioritizing compact form factors and wireless commissioning over extended service life.
- Residential:Individual homeowners and small landlords drive replacement demand through aftermarket channels, with price sensitivity favoring lower-cost nickel metal hydride options where local regulations permit.
- Industrial:Manufacturing facilities and data centers deploy smart metering for demand response participation, requiring batteries capable of supporting high-frequency telemetry bursts during peak pricing events.
Utility procurement commands the largest absolute volumes while commercial applications expand most quickly through building automation integration.
Technology:
Functional requirements diverge between basic telemetry and grid-interactive intelligence.
- Advanced Metering Infrastructure:The foundational technology layer integrating measurement, communication, and control functions in distributed endpoints. German deployments under the EU Green Deal mandate bidirectional communication capabilities for distributed energy resource coordination, driving demand for high-reliability power sources capable of sustaining continuous RF transmission cycles.
- Smart Grid:Grid-interactive functionality requiring batteries to support remote disconnect commands, voltage monitoring, and outage notification protocols. Texas and California utilities specify these capabilities for wildfire prevention and demand response programs.
- Remote Monitoring:Basic telemetry for asset tracking and tamper detection in isolated installations with intermittent communication windows.
- IoT:Emerging integration of meter batteries with broader sensor networks, requiring ultra-low power consumption during extended sleep cycles.
Advanced Metering Infrastructure generates the dominant revenue pool while smart grid functionality climbs the fastest as utilities modernize distribution networks.
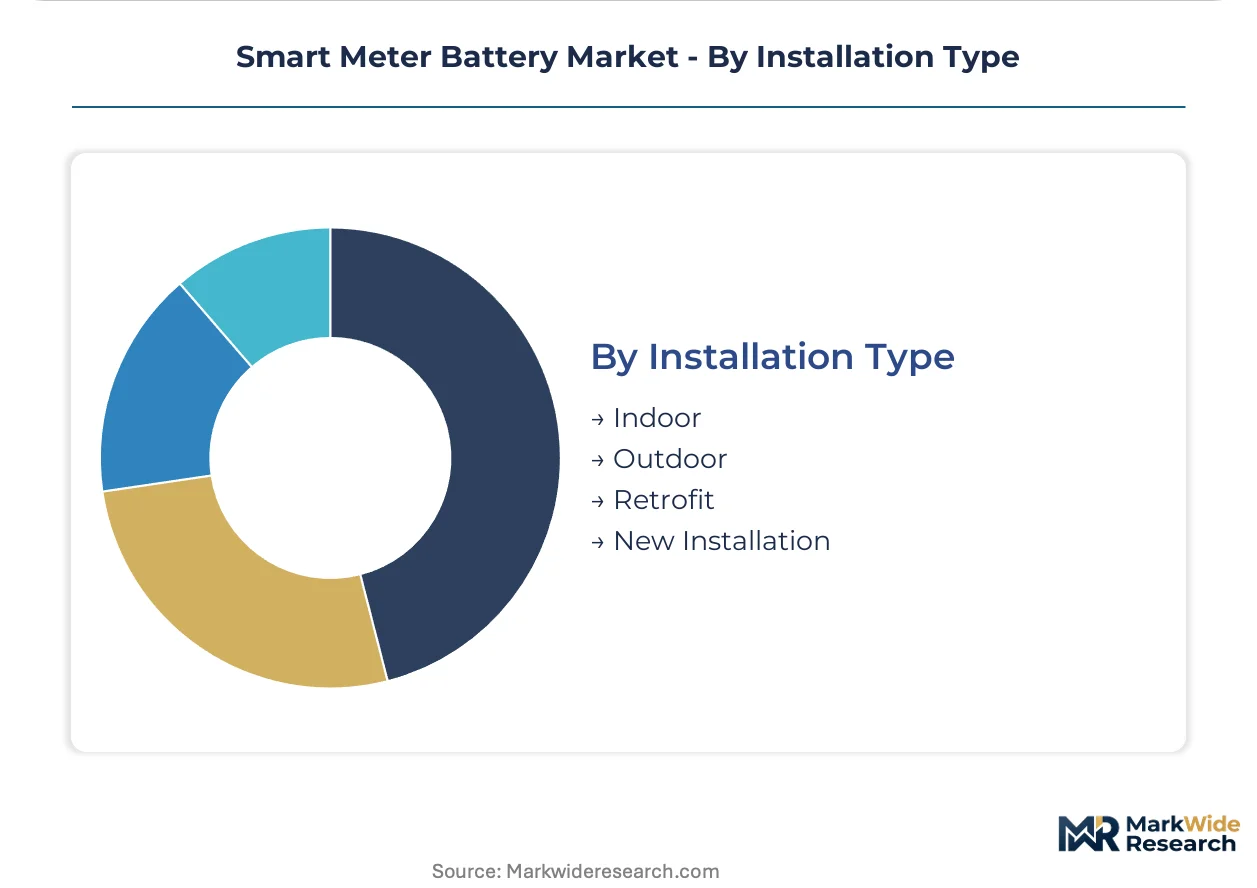
Installation Type:
Environmental exposure and labor economics shape battery specification across deployment modes.
- Outdoor:Extreme temperature cycling and moisture exposure demand hermetic sealing and wide-operating-range electrolyte formulations. Poland and Romania face particular constraints under Europe's F-Gas Regulation, with suppliers pre-qualifying fluorine-free cells two years ahead of mandate deadlines for outdoor gas meter retrofits.
- New Installation:Greenfield deployments in India's 100 smart cities allow integrated battery-meter design optimization without legacy compatibility constraints.
- Indoor:Climate-controlled environments permit broader chemistry options with reduced thermal management requirements.
- Retrofit:Mechanical meter replacement imposes form factor and voltage compatibility constraints that delay adoption of next-generation battery formats.
Outdoor installations anchor the specification complexity while new installation projects expand most rapidly in emerging market deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German utilities command pricing leverage through consolidated procurement cooperatives, while Indian municipal authorities absorb cost premiums for imported lithium cells amid rupee volatility. This asymmetry shapes supplier prioritization across deployment timelines.
United States
Consolidated Edison and Pacific Gas & Electric drive demand through AMI 2.0 retrofits covering 30 million endpoints. The EPA's hazardous waste rules under RCRA shape domestic recycling obligations for lithium-based systems. Texas utilities anchor outdoor gas meter deployments through aggregated buying cooperatives in the ERCOT region.
Germany
E.ON and Innogy specify 20-year battery life guarantees for next-generation metering infrastructure. The EU F-Gas Regulation mandates 79% hydrofluorocarbon reduction by 2030, compelling reformulation of electrolyte solvents. Bavarian industrial clusters around Munich host qualification laboratories for solid-state prototype testing.
China
State Grid Corporation deploys batteries across 500 million smart meter endpoints in the world's largest AMI program. The MIIT's GB standards for battery safety and performance govern domestic certification protocols. Yangtze River Delta manufacturing hubs in Jiangsu and Zhejiang concentrate cell assembly capacity for municipal water utility digitization projects.
India
The Ministry of Housing and Urban Affairs targets 100 smart cities with integrated utility metering mandates. Central Electricity Authority regulations under the Electricity Act govern smart grid equipment standards. Maharashtra and Gujarat host pilot deployments in Mumbai and Ahmedabad metros without legacy infrastructure constraints.
Poland
Gas distributor PGNiG advances outdoor meter retrofits requiring fluorine-free cell pre-qualification ahead of F-Gas deadlines. The country's national energy regulator URE mandates bidirectional communication capabilities for distributed resource coordination. Silesian industrial zones around Katowice concentrate testing facilities for sub-zero temperature cycling protocols.
Smart Meter Battery Market Competitive Landscape
Concentration sits with European and East Asian industrial conglomerates possessing captive materials access and multi-decade utility relationships. Three strategic archetypes dominate: integrated battery-electronics conglomerates with backward integration into cell materials; specialized lithium primary cell manufacturers with hermetic sealing expertise; and emerging solid-state developers targeting premium AMI segments. Capacity reservation agreements and dedicated production lines constitute the dominant competitive moves, compressing qualification timelines from 24 months to 14 months.
Among European-based manufacturers, Saft Groupe SA and Tadiran Batteries GmbH exemplify the specialized primary cell archetype through long-tenured supply relationships with continental utilities. Panasonic Corporation anchors the integrated conglomerate tier through in-house production of precision-engineered cell components. These three occupy positions across the chemistry spectrum from established lithium thionyl chloride formats to solid-state pilot production.
| Leading Market Players |
|---|
| Saft Groupe SA |
| Tadiran Batteries GmbH |
| VARTA Microbattery GmbH |
| Panasonic Corporation |
| Ultralife Corporation |
| EVE Energy |
| Duracell |
| Hitachi Maxell |
| HCB Battery Co. Ltd |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation agreements with State Grid, E.ON, and Enel lock in lithium thionyl chloride cell access while freezing unit prices across decade-long procurement windows. These contracts insulate qualified suppliers from spot market volatility in spodumene concentrate but strand mid-tier manufacturers without dedicated utility relationships.
Pricing Analysis
Configured-to-order pricing for solid-state prototypes commands substantial premiums over standard lithium thionyl chloride formats. Pricing stratifies across premium, standard, and economy tiers based on IEC 62055 certification grade and volume scale commitments. Cost compression in standard lithium-ion cells is intensifying because utility procurement cooperatives in Texas and California aggregate demand across 30 million meter endpoints. Residential retrofit buyers exhibit highest price sensitivity, while German utilities under AMI 2.0 mandates absorb premiums for 20-year life guarantees.
Supply Chain Analysis
Inventory buffers for lithium metal anodes and ceramic electrolytes extend lead times beyond conventional cell chemistries. Spodumene processing capacity clusters in Western Australia and Chile's Salar de Atacama, while cell assembly concentrates in Jiangsu and Zhejiang provinces. The supply chain draws from concentrated lithium concentrate offtake and hermetic sealing equipment, exposing manufacturers to freight rate volatility and single-source vulnerability in sulfide-based ceramic separator supply. Distribution runs through meter OEMs and direct utility framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart meter battery procurement is shifting toward platform economics as AMI 2.0 specifications mandate interoperability across distributed energy resource coordination systems. This ecosystem convergence rewards suppliers with embedded utility relationships and punishes standalone component vendors.
For Market Incumbents: Consolidate supplier panels through dedicated production line investments in Bavarian qualification clusters. Secure backward integration into lithium metal anode supply before solid-state scale-up accelerates. Defend against emerging sulfide-ceramic specialists by pre-qualifying fluorine-free cells two years ahead of F-Gas mandate deadlines. For New Entrants and Emerging Players: Anchor in India's 100 smart cities initiative where greenfield deployments lack legacy compatibility constraints. Target municipal water districts across China retrofitting mechanical meters with ultrasonic flow sensors. Pursue direct contracting with Maharashtra and Gujarat state utilities bypassing established meter OEM channels. For Investors and Strategic Acquirers: Capital is best deployed toward specialized lithium primary cell manufacturers with hermetic sealing expertise and existing IEC 62055 certifications. Long-term viability rests on chemistry diversification between proven lithium thionyl chloride platforms and sulfide-based solid-state architectures. Watch for solid-state prototype qualification announcements from E.ON and Innogy as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Reservation Agreements | Locks in decade-long supply relationships with State Grid and EDF. |
| Fluorine-Free Electrolyte Reformulation | Ensures EU F-Gas Regulation compliance ahead of 2030 deadlines. |
| Solid-State Prototype Qualification | Captures premium AMI 2.0 specifications from E.ON and Innogy. |
| Direct Utility Contracting | Bypasses meter OEM channel margin extraction in Texas cooperatives. |
| Backward Integration into Lithium Metal | Secures anode supply for sulfide-ceramic separator production lines. |
Research Methodology
Initial hypotheses were tested against primary input from utility procurement officers, battery cell manufacturing executives, and regulatory affairs specialists and refined through secondary validation. Utility planning officers at E.ON, Consolidated Edison, and State Grid provided deployment timeline intelligence. Secondary sources included FERC filings, ECHA REACH registration databases, MIIT GB standard documentation, and customs records tracking spodumene concentrate trade flows. Bottom-up endpoint counts triangulated against top-down utility capex disclosures.
Variance decomposition across chemistry platforms, end-user segments, installation types, and regional regulatory clusters shaped the analytical framework. CAGRs were derived from logistic diffusion curves fitted to AMI deployment schedules. Key inputs included IEC 62055 certification timelines, F-Gas Regulation phase-down trajectories, and solid-state pilot production scale assumptions.
Decision-makers should treat outputs as directional under stable lithium concentrate supply and continued utility procurement centralization; material deviation in raw material bottlenecks or regulatory acceleration would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Europe Smart Water Meter Market
Smart Meters
Global Smart Water Meter Market
Smart Meters
Smart Gas Metering Market
Smart Meters
Smart Water Metering Market
Smart Meters
Residential Water Submetering Market
Smart Meters
Smart Meter Antenna Market
Smart Meters
Asia Pacific Smart Water Metering Market
Smart Meters
Global Digital Power Meter Market
Smart Meters
Smart Utility Solutions Market
Smart Meters
Gas Meters Market
Smart Meters
Global Energy and Power Quality Meters Market
Smart Meters
United States Smart Meter Market
Smart Meters
Global Smart Energy Meters Market
Smart Meters
North America Smart Meter Data Management Market
Smart Meters
Digital Gas Meter Market
Smart Meters
Europe Smart Meters Market