
 Black Hydrogen Market | 2026-2036
Black Hydrogen Market Size, Share, and Industry Trends Forecast 2026-2036
Black Hydrogen Market Insights
Pipeline distribution networks for industrial hydrogen is tilting toward established chemical corridors in Western Europe and East Asia. Air Products and Chemicals, Inc. leverages its existing Gulf Coast hydrogen pipeline system to serve refinery customers with reliable throughput. Linde plc anchors large-scale production through steam methane reforming assets integrated with carbon capture retrofits. Shell Global competes by extending its hydrogen trading expertise from oil markets into industrial gas procurement.
Black hydrogen denotes hydrogen produced from fossil feedstocks—primarily natural gas or coal—without operational carbon capture, yielding a carbon intensity profile that distinguishes it from blue or green variants. Steam methane reforming dominates commercial output, operating at temperatures near 850°C with nickel-alumina catalysts to convert methane and steam into syngas rich in H2 and CO. Coal gasification retains structural importance in regions with abundant domestic coal reserves and limited renewable electricity for electrolysis, while catalytic gasification of biomass represents a transitional pathway with moderate emission reductions. Application segmentation shows chemical production absorbing the largest volume share, with ammonia and methanol synthesis driving consistent offtake; power generation and transportation remain nascent demand centers where cost parity with alternatives has not yet materialized.
Regulatory frameworks including the EU ETS, the EU Green Deal taxonomy criteria, and national hydrogen certification schemes in Germany and the Netherlands are reshaping product eligibility for public funding and offtake guarantees. EPA standards in the United States and emerging state-level low-carbon fuel standards in California similarly condition market access on verified emission intensities. Stakeholders must monitor the divergence between grandfathered industrial hydrogen demand and tightening carbon accounting rules that could strand unabated production assets before the end of the forecast horizon.
Market Dynamics
The black hydrogen market faces mounting pressure from carbon border adjustments that threaten to erode cost advantages against blue and green alternatives. Refinery operators in Germany's industrial clusters now confront explicit EU ETS phase-out timelines for unabated fossil hydrogen, forcing immediate strategic recalibration.
Growth Catalysts
- EU Green Deal taxonomy criteria:Grandfathered industrial demand in chemical corridors maintains near-term offtake volumes while transition infrastructure is deployed.
- Rhine-Ruhr pipeline integration:Existing hydrogen distribution networks enable rapid feedstock switching without capital-intensive greenfield construction.
- Steam methane reforming retrofit economics:Carbon capture retrofits on operational SMR assets offer lower capital pathways than electrolysis scale-up.
Market Restraints
- Natural gas price volatility:Feedstock cost swings compress producer margins and destabilize long-term supply contracts with ammonia synthesis operators.
- Carbon accounting divergence:Inconsistent lifecycle emission methodologies across EU member states fragment certification eligibility and public funding access.
- Electrolysis cost curves:Declining renewable hydrogen production costs threaten demand destruction in transportation and power generation segments.
Strategic Opportunities
- Netherlands hydrogen certification schemes:Early compliance with national guarantee-of-origin frameworks secures offtake priority in Rotterdam's industrial cluster.
- Catalytic biomass gasification:Transitional feedstock pathways offer moderate emission reductions while preserving existing gasification infrastructure.
- Carbon capture integration:SMR-CCS hybrid configurations access blue hydrogen premiums without full asset replacement.
Industry Challenges
- Process engineering talent scarcity:Specialized expertise in high-temperature catalytic systems and carbon capture integration commands premium compensation.
- Certification timeline compression:EU ETS phase-down schedules outpace validation protocols for emission intensity verification.
- Legacy asset stranding risk:Unabated production facilities face accelerated depreciation under tightening carbon accounting rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Black Hydrogen Market |
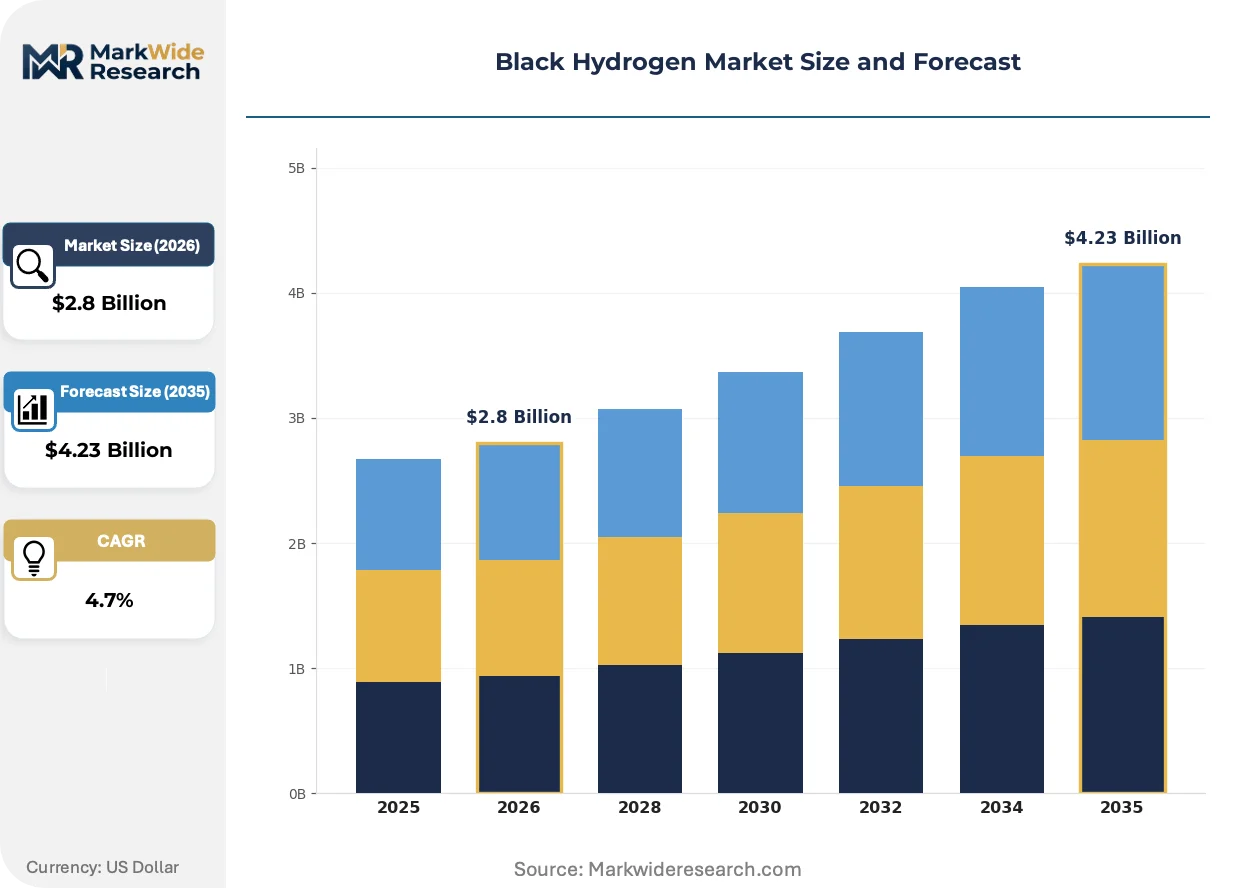
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.23 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Method: Catalytic Gasification, Steam Methane Reforming, Coal Gasification, Biomass Gasification Application: Chemical Production, Power Generation, Transportation, Heating End User: Manufacturing, Energy Sector, Transportation Sector, Utilities Technology: Altered Thermochemical, Biological Conversion, Plasma Arc, Membrane Separation |
| Companies Covered | Air Products and Chemicals, Inc., Linde plc, Air Liquide, Shell Global, Siemens AG, Mitsubishi Heavy Industries, Ltd., Kawasaki Heavy Industries, Sasol, Sinopec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Black Hydrogen Market Trends and Innovations
Carbon intensity verification protocols are redefining product eligibility across European hydrogen procurement. Market participants now navigate simultaneous pressures from emission disclosure mandates and industrial offtake continuity requirements.
Autothermal reforming is collapsing the cost differential between conventional SMR and carbon-captured production. BASF and Linde are deploying autothermal units at Ludwigshafen that operate at lower steam ratios while capturing concentrated CO2 streams. This technology is collapsing the capital barrier that previously separated unabated black hydrogen from certified low-carbon alternatives.
REACH chemical safety registrations now require hydrogen suppliers to document full feedstock provenance chains. The European Chemicals Agency's expanded substance evaluation criteria force reforming operators to disclose natural gas sourcing regions and associated methane leakage rates. German chemical producers are responding by demanding certified low-methane-intensity feedstock contracts from their hydrogen suppliers.
Refinery procurement departments are consolidating supply contracts around certified emission tiers rather than volume discounts. Long-term offtake agreements now index pricing to verified carbon intensity scores from third-party auditors. This behavioral shift is most pronounced in the Netherlands, where Rotterdam's industrial cluster has established standardized certification requirements for all pipeline-delivered hydrogen.
Black Hydrogen Market Segmentation
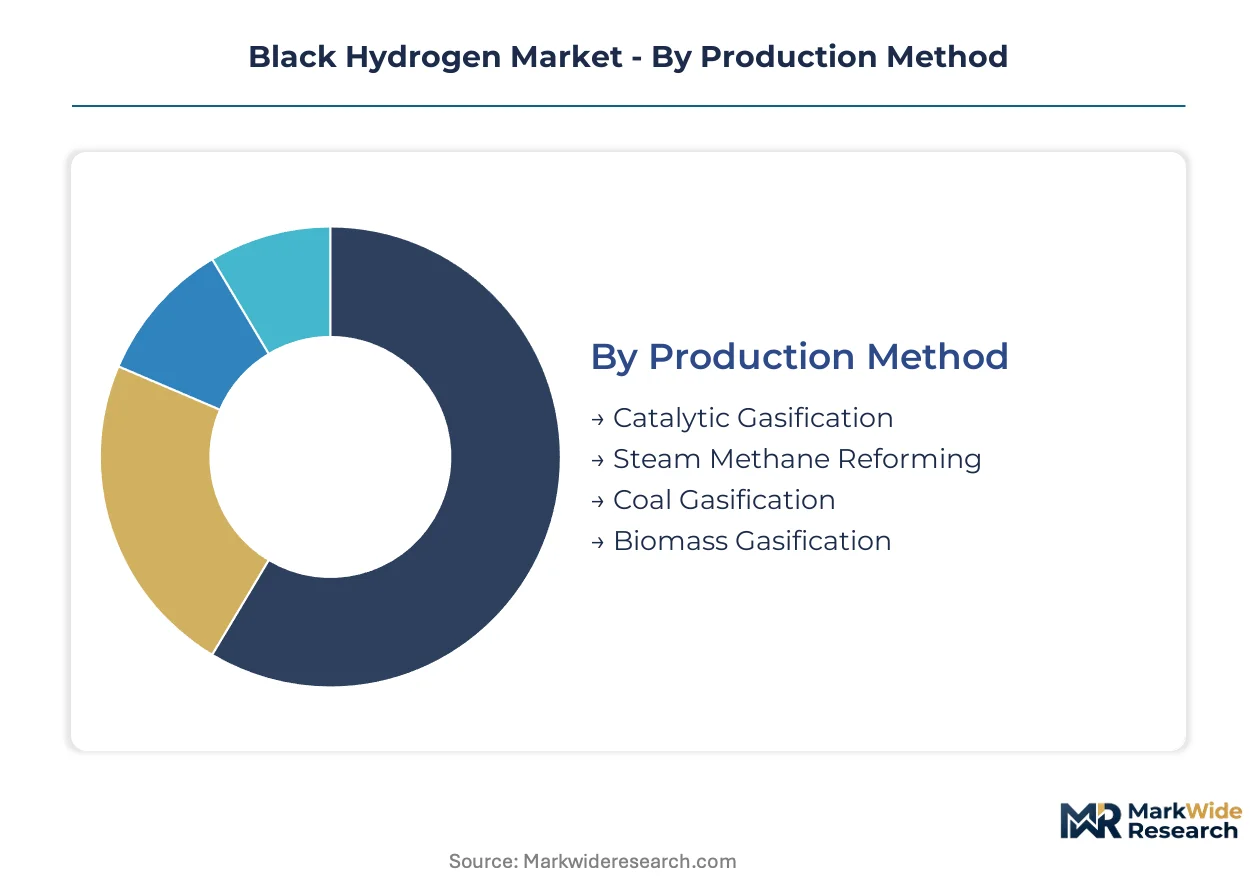
Segmentation in black hydrogen markets determines capital allocation priorities and regulatory exposure. Production method and application type shape emission intensity profiles that increasingly govern offtake eligibility. Technology selection and end-user concentration dictate retrofit economics and infrastructure lock-in risks.
Production Method:
After-sales service intensity varies sharply across production pathways, with high-temperature catalytic systems demanding specialized maintenance networks.
- Steam Methane Reforming:Nickel-alumina catalyst systems operate near 850°C, requiring continuous tube replacement and sulfur guard bed regeneration. German refinery clusters along the Rhine-Ruhr corridor anchor demand for SMR-derived hydrogen, though EU ETS phase-down timelines compress asset utilization windows.
- Coal Gasification:Entrained-flow gasifiers achieve 1400-1600°C operating temperatures with dry-ash or slagging configurations. China's industrial heartland preserves structural demand where domestic coal reserves and limited renewable electrolysis capacity sustain deployment.
- Catalytic Gasification:Lower-temperature pathways using alkali metal catalysts enable partial oxidation with reduced tar formation.
- Biomass Gasification:Fluidized-bed reactors processing lignocellulosic feedstocks offer transitional emission reductions.
Steam Methane Reforming holds the largest share; momentum sits with Coal Gasification in coal-abundant regions.
Application:
Margin structures diverge across application tiers, with chemical synthesis commanding premium contract durations against nascent transportation demand.
- Chemical Production:Ammonia and methanol synthesis absorb the dominant volume share, requiring 99.9% purity hydrogen at sustained pressure. BASF's Ludwigshafen complex exemplifies integrated offtake, where autothermal reforming retrofits preserve feedstock continuity while carbon capture integration progresses.
- Power Generation:Gas turbine co-firing and fuel cell applications remain pre-commercial, constrained by hydrogen delivery economics and combustion modification costs.
- Transportation:Heavy-duty fuel cell deployment and synthetic fuel production face cost parity gaps with battery-electric alternatives.
- Heating:Industrial process heat and district heating trials in the Netherlands test pipeline blending limits.
Chemical Production dominates current offtake; Power Generation represents the steepest expansion trajectory contingent on carbon capture scale-up.
End User:
Customer concentration patterns shape pricing power, with integrated chemical producers exercising backward integration options.
- Manufacturing:Steel, cement, and glass producers pilot hydrogen injection for direct reduction and combustion modification.
- Energy Sector:Oil refineries constitute the anchor demand segment, utilizing hydrogen for hydrotreating and hydrocracking operations.
- Transportation Sector:Fleet operators and synthetic fuel producers negotiate offtake agreements indexed to carbon intensity certification.
- Utilities:Power generators and gas network operators manage blending trials and infrastructure compatibility testing.
Energy Sector absorbs the largest volume; Utilities are gaining share fastest through pipeline repurposing investments.
Technology:
Supply concentration in high-temperature process engineering creates capability scarcity and vendor lock-in.
- Altered Thermochemical:Autothermal and partial oxidation variants reduce steam ratios while concentrating CO2 streams for capture. Linde's deployment at Rotterdam's industrial cluster demonstrates commercial viability of SMR-ATR hybrid configurations.
- Membrane Separation:Palladium-alloy and ceramic membranes enable compact purification with modular scaling advantages.
- Biological Conversion:Dark fermentation and microbial electrolysis remain laboratory-scale with limited thermal efficiency.
- Plasma Arc:Ultra-high-temperature dissociation of hydrocarbons achieves theoretical efficiency advantages but faces materials degradation challenges.
Altered Thermochemical holds the largest share; Membrane Separation is climbing the fastest through modular deployment economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr hydrogen pipeline corridor anchors Western European supply chains, while the Gulf Coast hydrogen network underwrites North American industrial clusters. China's coal gasification belt and Rotterdam's port hydrogen hub complete the quartet of infrastructure assets defining regional production gravity.
Germany
Rhine-Ruhr industrial clusters drive refinery hydrogen demand for hydrotreating and ammonia synthesis operations. The EU ETS phase-down timeline for unabated fossil hydrogen compresses asset utilization windows for steam methane reforming facilities. BASF's Ludwigshafen complex anchors autothermal reforming retrofits that preserve feedstock continuity while carbon capture integration progresses.
United States
Gulf Coast hydrogen pipeline systems serve refinery customers with reliable throughput across Texas and Louisiana petrochemical corridors. EPA standards and California's Low Carbon Fuel Standard condition market access on verified emission intensities. Air Products leverages its existing pipeline infrastructure to maintain supply relationships with ammonia synthesis operators along the Houston Ship Channel.
China
Domestic coal reserves sustain entrained-flow gasification deployment where limited renewable electrolysis capacity constrains green hydrogen scale-up. The country's dual carbon goals and MIIT industrial policy frameworks shape transition timelines for unabated production assets. Sinopec's industrial heartland operations preserve structural demand for coal-derived hydrogen in regions with abundant feedstock access.
Netherlands
Rotterdam's industrial cluster has established standardized certification requirements for all pipeline-delivered hydrogen, creating offtake priority for early compliance. National guarantee-of-origin frameworks from the Dutch government secure eligibility for public funding and procurement contracts. Linde's deployment at the port demonstrates commercial viability of SMR-ATR hybrid configurations with concentrated CO2 capture streams.
Black Hydrogen Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in catalyst and membrane supply. The market structure concentrates around industrial gas conglomerates with integrated production and distribution assets. Three archetypes dominate: pipeline network operators with captive demand bases, technology licensors with reforming process expertise, and regional gasification specialists with feedstock-advantaged positions. Competitive moves center on carbon capture retrofit partnerships and certification scheme pre-qualification to secure offtake priority.
Among the integrated industrial gas majors, Air Products and Chemicals, Inc., Linde plc, and Shell Global exemplify divergent strategic positioning. The Pennsylvania-based corporation leverages Gulf Coast pipeline infrastructure to anchor refinery supply relationships. The UK-German group anchors large-scale production through steam methane reforming assets integrated with carbon capture retrofits. The Anglo-Dutch energy major competes by extending hydrogen trading expertise from oil markets into industrial gas procurement, occupying a position between commodity merchant and infrastructure operator.
| Leading Market Players |
|---|
| Air Products and Chemicals, Inc. |
| Linde plc |
| Air Liquide |
| Shell Global |
| Siemens AG |
| Mitsubishi Heavy Industries, Ltd. |
| Kawasaki Heavy Industries |
| Sasol |
| Sinopec |
| Others |
Pricing and Supply Chain Analysis
Rotterdam's port hydrogen hub concentrates SMR-ATR hybrid capacity that feeds directly into Rhine-Ruhr industrial clusters, concentrating pricing power among pipeline network operators who index long-term offtake contracts to EU ETS carbon price movements. This geographic concentration forces ammonia synthesis operators to accept formula-based pricing with limited spot market alternatives, compressing buyer leverage in contract negotiations.
Pricing Analysis
Volume-discount tiering structures separate certified low-carbon hydrogen from unabated black hydrogen and transitional biomass-derived grades, with pricing stratifying across premium, standard, and economy tiers based on verified carbon intensity scores and methane leakage documentation. Contract durations now stretch 10-15 years for chemical production offtake, while power generation and transportation segments negotiate shorter terms reflecting technology uncertainty. Pricing pressure stems from electrolysis cost curves threatening demand destruction in marginal applications. Refinery procurement departments demonstrate highest price sensitivity due to margin compression in hydrotreating operations, whereas integrated chemical producers at Ludwigshafen exhibit lowest sensitivity through backward integration into autothermal reforming assets.
Supply Chain Analysis
Tariff exposure between EU member states and third-country natural gas suppliers dominates supply chain risk assessment for steam methane reforming operators dependent on imported feedstock. Production concentrates in Germany, the Netherlands, and the United States Gulf Coast, with China's coal gasification belt serving as a parallel supply architecture. Nickel-alumina catalyst systems, sulfur guard beds, and specialized high-temperature alloys constitute critical component dependencies with limited qualified vendors. Single-source vulnerability in palladium-alloy membrane supply creates chokepoint exposure for modular purification deployments. Distribution runs through repurposed natural gas pipelines and dedicated hydrogen corridors, with Rotterdam's industrial cluster establishing standardized certification gateways for all pipeline-delivered product.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated refinery procurement departments and integrated chemical producers who backward integrate into captive hydrogen production, fragmenting demand concentration that previously favored merchant suppliers. This consolidation compresses margin capture for standalone producers without pipeline infrastructure or certification scheme pre-qualification.
For Market Incumbents: Insulate existing offtake relationships by securing early compliance with Netherlands hydrogen certification schemes and Rotterdam's standardized pipeline delivery requirements, while accelerating carbon capture retrofit partnerships on operational SMR assets to access blue hydrogen premiums before EU ETS phase-down timelines strand unabated production capacity. Priority levers include autothermal reforming technology licensing and Rhine-Ruhr pipeline network control points that create switching costs for ammonia synthesis operators. For New Entrants and Emerging Players: Build out catalytic biomass gasification capacity in regions with abundant lignocellulosic feedstock and existing gasification infrastructure, targeting the transitional hydrogen segment where moderate emission reductions satisfy tightening EU Green Deal taxonomy criteria without requiring full electrolysis scale-up. The most penetrable white space sits in industrial process heat applications in the Netherlands, where pipeline blending trials test infrastructure compatibility and create first-mover certification advantages. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded hydrogen production assets lacking carbon capture integration, particularly SMR facilities in Germany's Rhine-Ruhr corridor facing compressed utilization windows under EU ETS phase-down schedules. Long-term viability over the next decade hinges on successful certification scheme navigation and retrofit economics execution. The signal to watch is divergence between grandfathered industrial demand volumes and actual carbon capture deployment rates, which indicates stranded asset risk acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Partnership | SMR-CCS hybrid configurations at Linde's Rotterdam deployment demonstrate commercial viability for concentrated CO2 streams. |
| Certification Scheme Pre-Qualification | Early Netherlands guarantee-of-origin compliance secures offtake priority in Rotterdam's industrial cluster procurement. |
| Autothermal Reforming Technology Licensing | BASF's Ludwigshafen units collapse capital barriers between unabated black hydrogen and certified low-carbon alternatives. |
| Pipeline Network Control Point Acquisition | Air Products' Gulf Coast infrastructure anchors refinery supply relationships with reliable throughput guarantees. |
| Catalytic Biomass Gasification Scale-Up | Transitional feedstock pathways preserve existing gasification infrastructure while offering moderate emission reductions. |
Research Methodology
A spread of perspectives from hydrogen plant managers, refinery procurement leads, chemical R&D directors, and carbon capture project developers converged on the working assumptions underlying this analysis. Primary interviews with pipeline network operators and certification scheme administrators combined with secondary validation from EU ETS regulatory filings, EPA emission standards documentation, and SEC disclosures from integrated industrial gas majors. Customs data on nickel-alumina catalyst trade flows, IEA hydrogen production databases, and national hydrogen strategy publications from Germany and the Netherlands anchored supply-side quantification. Bottom-up capacity assessments triangulated against top-down demand projections from ammonia and methanol synthesis operators.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning production method, application type, end-user concentration, and technology pathway. Steam methane reforming retrofit economics, coal gasification capacity utilization, and electrolysis cost curve trajectories served as industry-specific forecast inputs. CAGRs derived from capacity expansion announcements, regulatory phase-down timelines, and industrial offtake contract durations modeled transition dynamics between grandfathered demand and low-carbon substitution.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed green hydrogen developers or carbon capture technology licensors would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Global Hydrogen Electrolyzers Market
Hydrogen Energy
Hydrogen Refueling Protocol and Dispenser Performance Test Systems Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Gray Hydrogen Market
Hydrogen Energy
Solar Hydrogen Panel Market
Hydrogen Energy
Liquid Hydrogen Tank Market
Hydrogen Energy
Green Hydrogen Dispensing Equipment Market
Hydrogen Energy
Hydrogen Recovery Market
Hydrogen Energy
35MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Hydrogen Powered Engine Market
Hydrogen Energy
Europe Hydrogen Generation Market
Hydrogen Energy
Clean Hydrogen Market
Hydrogen Energy
Liquid Hydrogen Market
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
Hydrogen Storage Tank Market
Hydrogen Energy
Partial Oxidation Blue Hydrogen Market