
 Hyaluronic Acid Raw Material Market | 2026-2036
Hyaluronic Acid Raw Material Market Size, Share, and Industry Trends Forecast 2026-2036
Hyaluronic Acid Raw Material Market Intelligence
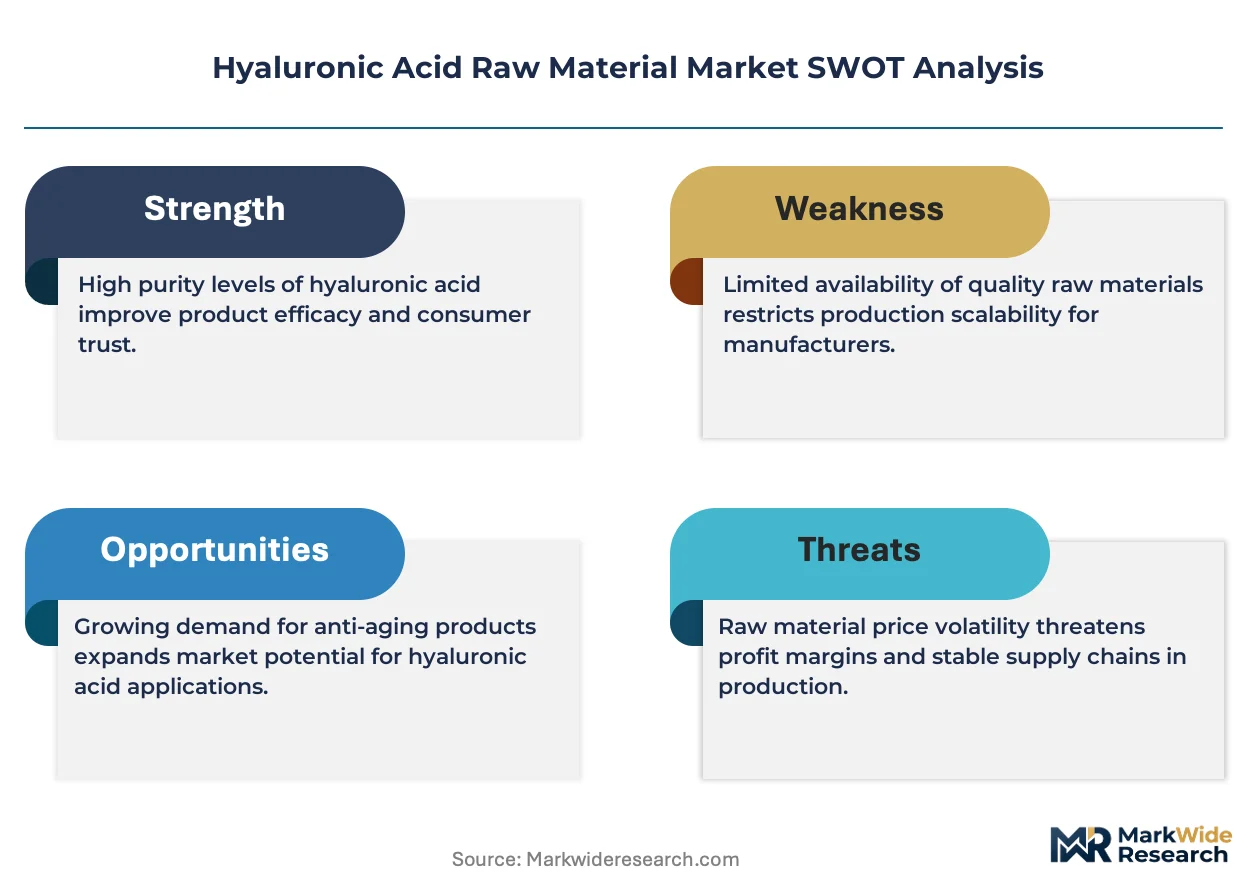
Multi-source fermentation supply is realigning procurement strategies across downstream formulators. Bloomage Biotech leverages vertical integration from microbial culture to finished sodium hyaluronate, securing cost advantages in cosmetic-grade output. Seikagaku Corporation anchors pharmaceutical purity standards through its cGMP-compliant Japanese facilities. HTL Biotechnology specializes in high-molecular-weight fractions for orthopedic and ophthalmic applications, differentiating on European regulatory compliance.
Hyaluronic acid raw material denotes the biopolymer composed of repeating disaccharide units of D-glucuronic acid and N-acetyl-D-glucosamine, produced via Streptococcus zooepidemicus fermentation or rooster comb extraction, then purified to molecular weights spanning 10 kDa to 6 MDa for viscoelastic, humectant, or tissue-scaffolding functions. Injectable-grade product type commands premium pricing due to endotoxin limits and sterility requirements that exceed cosmetic specifications. Fermentation technology dominates capacity expansion as manufacturers seek batch consistency and animal-free provenance aligned with European pharmacopeia standards.
FDA oversight of injectable hyaluronic acid through the Center for Biologics Evaluation and Research imposes stringent master file documentation that shapes market access timelines for new suppliers. EMA's Medical Device Regulation and REACH chemical registration frameworks in Europe compound compliance burdens, particularly for cross-border raw material trade. China's NMPA biologics licensing pathway adds a third jurisdictional gate. Stakeholders must monitor regulatory divergence across these three authorities when siting manufacturing capacity or qualifying alternative supply sources.
Market Dynamics
Fermentation-based production is consolidating supply control among biotech clusters with captive microbial culture capacity, forcing formulators to requalify sourcing strategies around molecular weight specificity and endotoxin certification tiers.
Growth Catalysts
- Ophthalmic Viscosurgical Device Demand:Cataract surgery volumes in aging populations pull pharmaceutical-grade sodium hyaluronate through cGMP-certified channels. Surgeons specify molecular weight ranges for cohesive-dispersive viscoelastic balance.
- REACH-Driven Animal-Free Provenance:European pharmacopeia standards now favor Streptococcus zooepidemicus fermentation over rooster comb extraction. Manufacturers retrofit extraction lines to microbial culture to retain EU market access.
- Orthopedic Injection Expansion:Viscosupplementation for knee osteoarthritis consumes high-molecular-weight fractions above 2 MDa. Hospital procurement committees prioritize suppliers with dual FDA-EMA master file documentation.
Market Restraints
- Glucose Feedstock Volatility:Fermentation economics hinge on corn-derived glucose pricing. Drought cycles in US Midwest grain belts transmit cost spikes through hyaluronic acid contract structures.
- Shandong Supply Concentration:China's biotech corridor houses disproportionate fermentation capacity. Geopolitical friction or regional environmental enforcement triggers raw material allocation disruptions.
- Collagen Substitute Encroachment:Dermal filler formulators experiment with cross-linked collagen and calcium hydroxylapatite microspheres. Alternative biopolymers capture price-sensitive cosmetic segments.
Strategic Opportunities
- Indian Pharmaceutical Manufacturing:CDSCO's streamlined biologics licensing attracts contract fermentation investment. Domestic hyaluronic acid output targets ophthalmic and orthopedic finished-dose export markets.
- Regenerative Medicine Scaffolds:Tissue engineering applications require custom cross-linking chemistry. Suppliers with hydrogel modification capabilities capture premium positioning in cell-therapy supply chains.
- Direct-to-Formulator Digital Platforms:Specialty chemical marketplaces bypass distributor markups for cosmetic-grade sodium hyaluronate. Molecular weight certificates and batch CoAs stream through blockchain-verified documentation.
Industry Challenges
- Bioprocess Engineering Talent Scarcity:Scale-up from lab to industrial fermentation demands expertise in oxygen transfer optimization and contamination control. Universities produce fewer fermentation specialists than bioreactor capacity expansion requires.
- Dual cGMP-ISO Certification Timelines:Injectable-grade qualification spans 18-24 months across FDA master file submission and EMA site inspection queues. Working capital burdens accumulate before revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyaluronic Acid Raw Material Market |
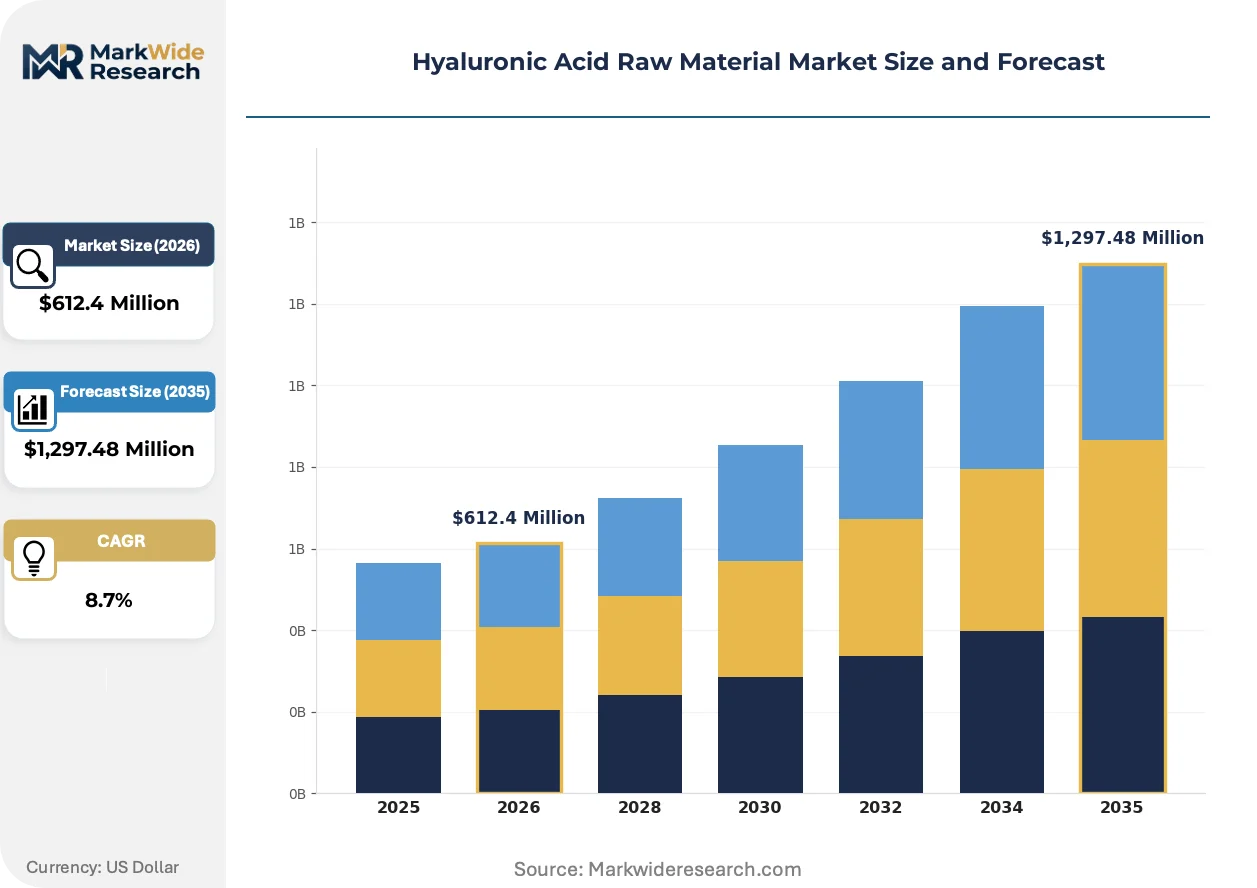
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,297.48 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable, Creams, Serums, Powders End User: Cosmetics, Pharmaceuticals, Nutraceuticals, Dermatology Technology: Synthesis, Fermentation, Extraction, Ultra-filtration Form: Liquid, Gel, Powder, Granule |
| Companies Covered | Lifecore Biomedical, Inc., Contipro a.s., Bloomage Biotech, AbbVie, Inc. (Allergan), Shandong Focuschem Biotech Co., Ltd., Seikagaku Corporation, Fidia Farmaceutici S.p.A., Zimmer Biomet, HTL Biotechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyaluronic Acid Raw Material Market Strategic Shifts & Innovations
Continuous processing technologies and precision fermentation controls are compressing batch-to-batch variability while regulatory authorities tighten endotoxin and molecular weight distribution specifications.
Precision fermentation with CRISPR-engineered microbial strains is rewriting yield economics for high-molecular-weight hyaluronic acid. Orthopedic viscosupplement manufacturers now specify sub-5% polydispersity indices in procurement contracts. This molecular weight consistency is compressing quality-adjusted pricing spreads between premium and standard grades.
EMA's Medical Device Regulation (MDR) reclassification of intra-articular and intraocular devices imposes clinical evidence requirements on raw material suppliers. European formulators now demand extended batch records and stability data from fermentation partners. Injectable-grade producers with existing MDR technical documentation capture accelerated qualification timelines.
Formulator procurement teams are consolidating supplier panels to dual-source arrangements with molecular weight-matched redundancy. Cosmetic-grade buyers bypass distributors for direct mill relationships in Shandong and Japanese cGMP facilities. This channel compression is most visible in South Korean dermocosmetic manufacturing, where vertical brand ownership drives captive raw material specification.
Hyaluronic Acid Raw Material Market Segmentation
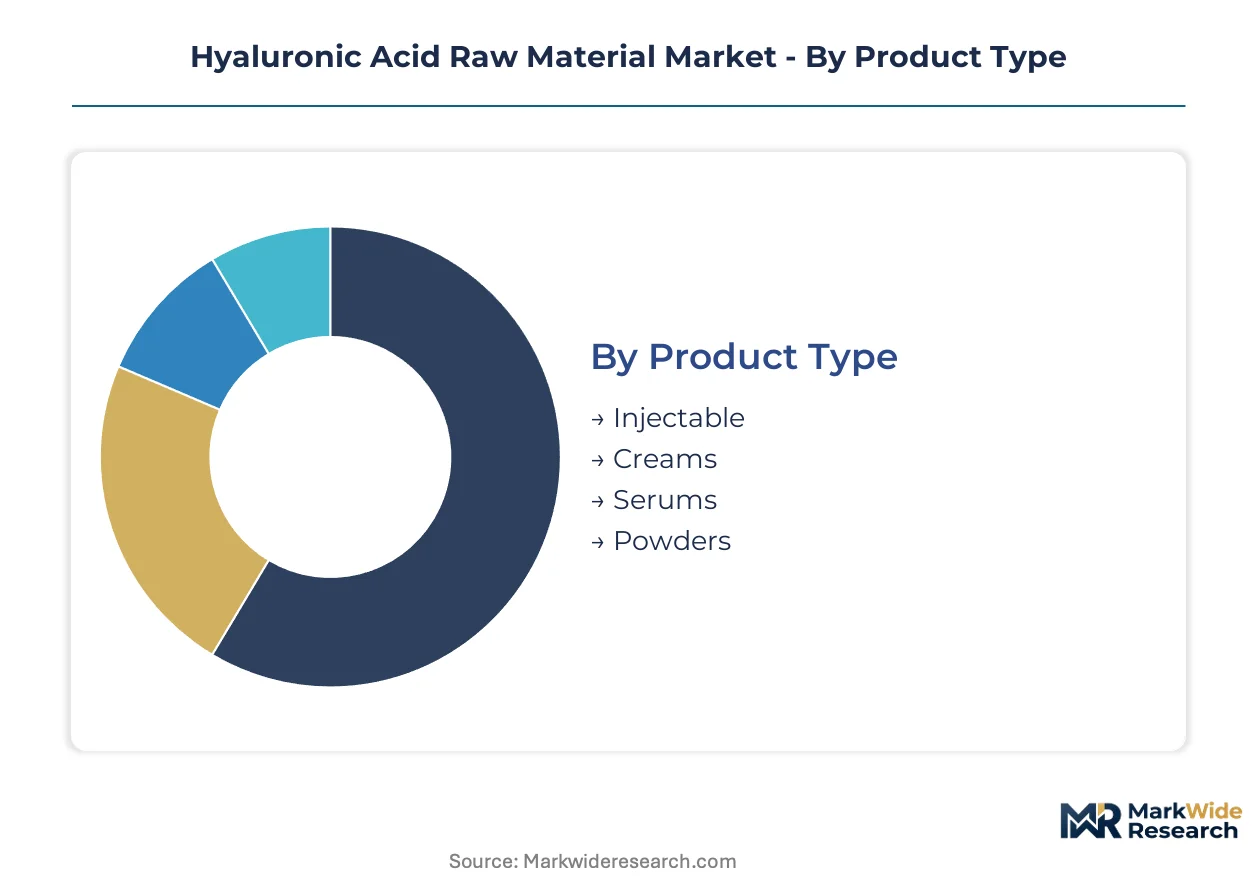
Hyaluronic acid procurement strategies diverge sharply across molecular weight specifications, sterility tiers, and end-use certification requirements. Formulators select raw material grades based on endotoxin limits, cross-linking potential, and regulatory pathway alignment rather than commodity pricing alone.
Product Type:
Buyers differentiate by sterility burden and regulatory filing complexity, with injectable grades commanding exhaustive documentation while cosmetic formats prioritize cost efficiency.
- Injectable:Pharmaceutical-grade sodium hyaluronate meeting USP-NF endotoxin specifications below 0.5 EU/mg. Cataract viscosurgical device manufacturers in Japan and Germany specify cohesive-dispersive viscoelastic balance through molecular weight ranges of 1.5-4.0 MDa.
- Creams:Cosmetic-grade material with relaxed microbial limits, formulated into dermocosmetic emulsions. South Korean beauty manufacturers source directly from Shandong fermentation clusters to compress raw material costs.
- Serums:Low-viscosity aqueous solutions requiring high-purity sodium hyaluronate below 500 kDa for transdermal penetration claims. Direct-to-consumer brands in India leverage CDSCO cosmetic notifications to accelerate launch timelines.
- Powders:Lyophilized sodium hyaluronate for reconstitution in compounding pharmacies and medical device manufacturing. Stability during ambient shipping reduces cold-chain expenditure for orthopedic viscosupplement formulators.
Injectable leads volumes today; serums are gaining share fastest.
End User:
Demand concentration tracks regulatory sophistication, with pharmaceutical buyers imposing master file requirements that cosmetic formulators rarely match.
- Cosmetics:Humectant and film-forming applications in topical skincare. ECHA REACH registration pressures European brands toward fermentation-derived, animal-free provenance certificates.
- Pharmaceuticals:Ophthalmic viscosurgical devices and intra-articular injections demanding cGMP compliance. FDA Center for Biologics Evaluation and Research oversight shapes supplier qualification timelines.
- Nutraceuticals:Oral hyaluronic acid for joint health and skin hydration supplements. Japanese FOSHU notification system and US FDA GRAS self-affirmation create divergent market access pathways.
- Dermatology:Injectable dermal fillers and mesotherapy solutions. PMDA biologics licensing in Japan and ANVISA registration in Brazil impose distinct purity verification protocols.
Pharmaceuticals anchors revenue concentration; nutraceuticals shows steepest expansion trajectory.
Technology:
Production method selection determines molecular weight distribution control, endotoxin baseline, and European pharmacopeia alignment.
- Synthesis:Chemical polymerization approaches yielding precise molecular weight targeting. Limited commercial scale due to cost disadvantages versus microbial fermentation.
- Fermentation:Streptococcus zooepidemicus culture dominates capacity expansion. Shandong biotech clusters and Japanese cGMP facilities compete on batch consistency and dual FDA-EMA master file documentation.
- Extraction:Rooster comb hydrolysis retains niche presence for ultra-high-molecular-weight fractions above 3 MDa. EMA Medical Device Regulation and REACH chemical registration accelerate line closures across European facilities.
- Ultra-filtration:Tangential flow filtration for molecular weight fractionation and endotoxin reduction. Critical downstream step for injectable-grade qualification regardless of upstream production method.
Fermentation commands installed capacity; ultra-filtration investment is climbing fastest.
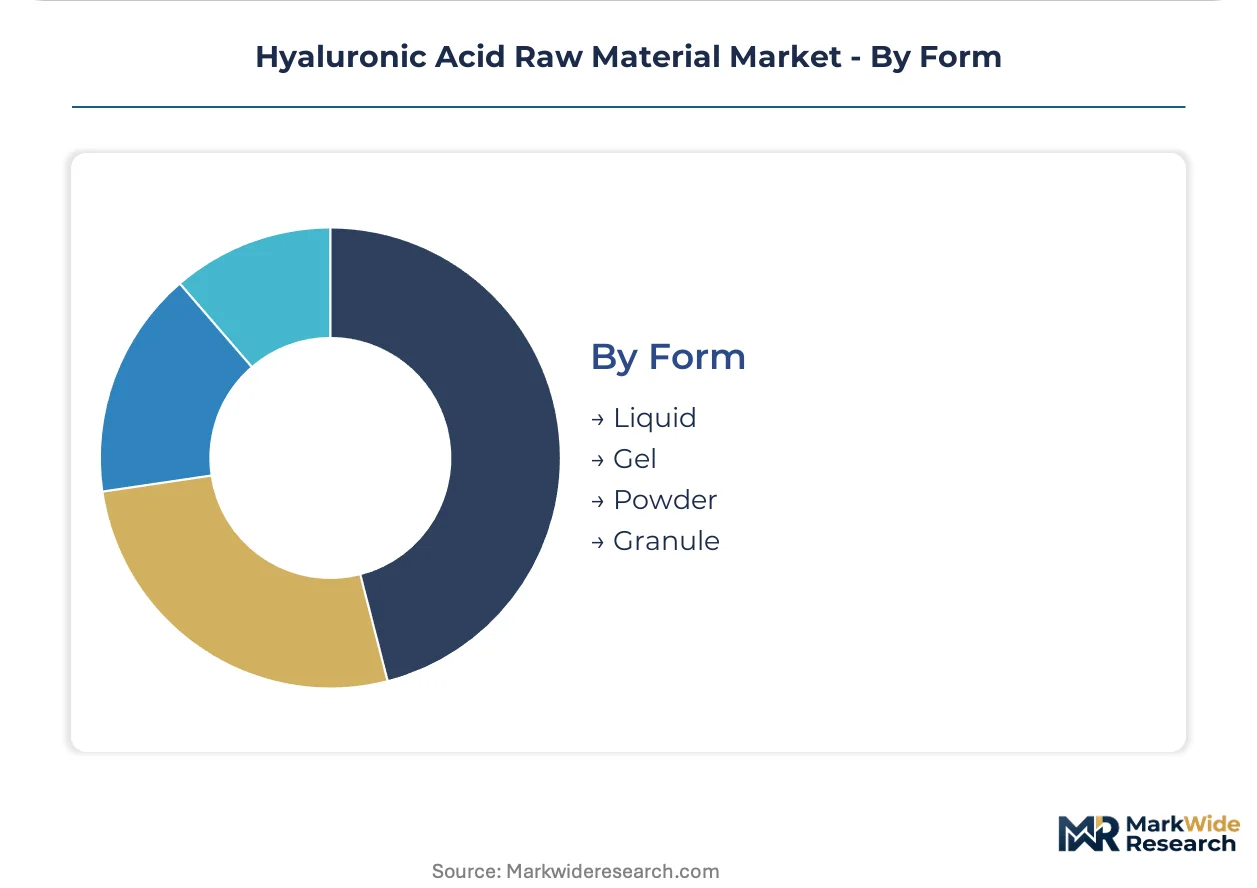
Form:
Physical state dictates handling protocols, stability requirements, and formulation integration complexity for downstream processing.
- Liquid:Buffered aqueous solutions with preserved microbial specifications. Ophthalmic manufacturers prefer pre-sterilized liquid bulk to streamline aseptic filling operations.
- Gel:Cross-linked or high-concentration preparations for orthopedic and aesthetic injection. Rheological properties measured by viscoelastic modulus guide surgeon selection.
- Powder:Spray-dried or lyophilized material with extended shelf stability. Ambient storage and transport economics attract cost-sensitive cosmetic compounders.
- Granule:Intermediate physical form for controlled dissolution in tablet and capsule manufacturing. Nutraceutical formulators value flow properties for high-speed encapsulation lines.
Liquid dominates pharmaceutical procurement; powder is expanding most quickly in cosmetic applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shandong province anchors fermentation capacity expansion for hyaluronic acid raw materials. Cataract surgery volumes and REACH-driven animal-free mandates pull pharmaceutical-grade output toward cGMP-certified channels. Industrial clusters in Weifang and Yantai operate captive Streptococcus zooepidemicus culture lines.
China
Ophthalmic viscosurgical device manufacturers source cohesive-dispersive sodium hyaluronate through NMPA-licensed biologics pathways. The national pharmaceutical regulator enforces dual carbon goals across fermentation facilities. Shandong's Weifang Hi-Tech Zone houses multiple biotech clusters retrofitting extraction lines to microbial culture.
United States
Hospital procurement committees for knee osteoarthritis viscosupplementation specify high-molecular-weight fractions above 2 MDa. FDA Center for Biologics Evaluation and Research oversight shapes 18-24 month master file submission timelines. Midwestern corn belt glucose pricing volatility transmits through contract structures for fermentation feedstock.
Germany
EMA Medical Device Regulation reclassification of intra-articular devices imposes clinical evidence requirements on raw material suppliers. REACH chemical registration and EU Green Deal alignment accelerate rooster comb extraction line closures. Bavarian cGMP facilities compete on batch consistency for European orthopedic formulators.
Japan
PMDA biologics licensing for ophthalmic viscosurgical devices demands exhaustive endotoxin documentation below 0.5 EU/mg. METI standards guide precision fermentation controls for sub-5% polydispersity indices. Tokyo-Osaka pharmaceutical corridors source directly from domestic cGMP-certified fermentation partners.
India
CDSCO's streamlined biologics licensing attracts contract fermentation investment for ophthalmic and orthopedic export markets. FSSAI and DGFT frameworks govern nutraceutical-grade oral hyaluronic acid for joint health supplements. Maharashtra and Gujarat pharmaceutical manufacturing zones target finished-dose export qualification.
Hyaluronic Acid Raw Material Market Key Industry Players
Global majors compete with regional champions across cGMP certification tiers and molecular weight specificity. The vendor base separates into fermentation-dominant biotech clusters, extraction-retaining niche specialists, and hybrid players retrofitting legacy lines. Three archetypes define positioning: vertically integrated Shandong-based producers with captive culture capacity; Japanese and European cGMP-certified facilities anchoring pharmaceutical purity standards; and mid-scale Indian contract manufacturers targeting export markets. Dominant competitive moves include dual FDA-EMA master file documentation pursuit and precision fermentation yield optimization through CRISPR-engineered strain development.
Among the named participants, Bloomage Biotech occupies a position exemplifying vertical integration from microbial culture to finished sodium hyaluronate. Seikagaku Corporation represents the pharmaceutical-grade archetype through cGMP-compliant Japanese facilities. HTL Biotechnology anchors European regulatory compliance positioning for high-molecular-weight orthopedic and ophthalmic applications.
| Leading Market Players |
|---|
| Lifecore Biomedical, Inc. |
| Contipro a.s. |
| Bloomage Biotech |
| AbbVie, Inc. (Allergan) |
| Shandong Focuschem Biotech Co., Ltd. |
| Seikagaku Corporation |
| Fidia Farmaceutici S.p.A. |
| Zimmer Biomet |
| HTL Biotechnology |
| Others |
Cost & Logistics Intelligence
Injectable-cosmetic grade divergence creates distinct procurement economics across fermentation-based supply channels. Pharmaceutical-grade sodium hyaluronate commands exhaustive documentation premiums through cGMP-certified pathways, while cosmetic-grade buyers compress margins through direct mill relationships in Shandong and distributor bypass strategies. This tiered separation manifests in supply chain configurations that concentrate high-purity capacity in Japanese and Bavarian facilities while routing commodity volumes through Chinese biotech clusters.
Pricing Analysis
Corn-derived glucose pass-through dominates fermentation economics, with US Midwest drought cycles transmitting volatility through contract structures. Three-tier pricing structure across injectable, cosmetic, and nutraceutical grades separates buyers by endotoxin certification burden. Cost compression in cosmetic segments intensifies because South Korean dermocosmetic manufacturers source directly from Shandong fermentation clusters. Pharmaceutical buyers show least price sensitivity due to master file requalification costs, while nutraceutical formulators exhibit highest elasticity.
Supply Chain Analysis
Bioprocess engineering talent scarcity in Shandong, Bavaria, and Tokyo-Osaka corridors constrains capacity expansion timelines. Streptococcus zooepidemicus culture lines draw from glucose feedstock, chromatography resins, and sterile filtration assemblies. Single-source vulnerability concentrates in Shandong's Weifang Hi-Tech Zone, where environmental enforcement triggers allocation disruptions. Distribution runs through cGMP-certified channels for pharmaceutical grades and direct-to-formulator digital platforms for cosmetic volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Sub-5% polydispersity indices now specify procurement contracts, shifting demand toward precision fermentation capabilities.
For Market Incumbents: Hedge against collagen substitute encroachment by securing dual FDA-EMA master file documentation and deepening backward integration into CRISPR-engineered strain development. Bioprocess engineering talent scarcity threatens expansion timelines; captive university partnerships in fermentation science mitigate this risk. For New Entrants and Emerging Players: Begin with CDSCO-licensed contract fermentation for ophthalmic export markets, where streamlined biologics pathways reduce qualification barriers. Indian pharmaceutical manufacturing zones offer the most penetrable geography; direct-to-formulator digital platforms provide the optimal go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where cGMP certification burdens exceed working capital capacity of mid-scale fermentation operators. Long-term viability centers on precision fermentation yield optimization and hydrogel modification capabilities for regenerative medicine scaffolds. Monitor EMA Medical Device Regulation technical documentation completeness as inflection indicator for accelerated qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Dual FDA-EMA Master File Documentation | Reduces supplier qualification timelines for orthopedic and ophthalmic formulators. |
| CRISPR-Engineered Strain Development | Compresses yield economics for high-molecular-weight fractions above 2 MDa. |
| Direct-to-Formulator Digital Platforms | Bypasses distributor markups for cosmetic-grade sodium hyaluronate buyers. |
| Hydrogel Modification Capabilities | Captures premium positioning in cell-therapy regenerative medicine supply chains. |
| Backward Integration into Microbial Culture | Secures batch consistency and animal-free provenance for REACH compliance. |
Research Approach
Coverage spans China, United States, Germany, Japan, and India, with primary inputs from each market cluster. Fermentation technology directors, pharmaceutical procurement managers at ophthalmic device manufacturers, cosmetic formulators, and regulatory affairs specialists provided structured interviews. Secondary validation drew from NMPA biologics filings, FDA Center for Biologics Evaluation and Research master file databases, EMA Medical Device Regulation technical documentation, and REACH chemical registration records. Bottom-up volume modeling triangulated against top-down industry capacity assessments.
Rate-of-change decomposition separated volume growth from pricing dynamics across the analysis window. Segmentation dimensions spanned product type, end user, production technology, and molecular weight specification tiers. CAGRs derived from regression analysis of historical fermentation capacity expansion correlated with cataract surgery volume trajectories and orthopedic injection procedure rates. Feedstock cost modeling incorporated corn futures pricing and glucose contract structures.
Several conditions sit outside the modeled scope, including geopolitical friction effects on Shandong supply concentration and breakthrough synthesis technologies displacing microbial fermentation. Forecasts reflect assumptions regarding regulatory divergence stability across FDA, EMA, and NMPA pathways. Practitioners should monitor glucose feedstock volatility, EMA MDR enforcement intensity, and collagen substitute formulation advances for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market
Pharmaceutical Ingredients
Global Cephalosporin Drugs Market
Pharmaceutical Ingredients
Acetaminophen API Market
Pharmaceutical Ingredients
Global Antazoline Market
Pharmaceutical Ingredients
Pharmaceutical Excipients for Taste Masking Market
Pharmaceutical Ingredients
Growth Hormone Inhibiting Hormone Drugs Market
Pharmaceutical Ingredients
Topical Drugs Market
Pharmaceutical Ingredients
Calcium Folinate for Injection Market
Pharmaceutical Ingredients
Germany Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Montelukast API Market
Pharmaceutical Ingredients
Global Tacrolimus Market
Pharmaceutical Ingredients
Transdermal Drugs Market
Pharmaceutical Ingredients
Nuclear Export Inhibitor Drugs Market
Pharmaceutical Ingredients
Synthetic Lethality-Based Drugs and Targets Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
Diclofenac Sodium API Market