
 Resin Capsule Market | 2026-2036
Resin Capsule Market Size, Share, and Industry Trends Forecast 2026-2036
Resin Capsule Market Intelligence
The gap between premium and commodity tiers is shifting as high-performance capsules with extended gel times and superior load-bearing capacity command widening price premiums over standard polyester formulations. DYWIDAG-Systems International leverages its European manufacturing footprint to dominate specialized tunneling applications. Sika AG sustains competitive positioning through integrated supply chains spanning resin chemistry and distribution. Hilti Corporation differentiates via proprietary cartridge designs that reduce installation variability on job sites.
Resin capsules are dual-component cartridges containing reactive resin and hardener systems—typically polyester, epoxy, or polyurethane—that cure upon mixing to form high-strength adhesive bonds for rock bolts, threaded rods, and reinforcement anchors in structural and geotechnical applications. Epoxy resin formulations deliver superior chemical resistance and elevated temperature performance, positioning them as the margin-rich segment for corrosive environments and critical infrastructure. Construction Supplies anchors the volume base as tunneling, mining, and building rehabilitation projects sustain steady consumption of standard polyester capsules across mature markets.
REACH compliance in Europe, OSHA anchorage standards in the United States, and China's GB standards for construction materials collectively elevate product testing burdens and restrict market access for uncertified suppliers. ECHA substance evaluations and EPA VOC regulations are tightening permissible emission profiles, forcing reformulation investments that favor established producers with dedicated regulatory affairs capabilities. Stakeholders must monitor evolving mine safety codes and infrastructure resilience mandates as these frameworks increasingly specify performance-certified anchoring systems over generic alternatives.
Market Dynamics
Reformulation pressures from REACH chemical compliance are compressing margins for commodity polyester producers while rewarding specialized epoxy manufacturers with captive regulatory affairs capabilities.
Growth Catalysts
- Underground mining automation:Mechanized bolting operations in Australia's hard-rock mines demand resin capsules with consistent gel times and rapid strength development.
- REACH low-VOC mandates:European ECHA substance evaluations force reformulation toward compliant epoxy variants, creating upgrade cycles across installed infrastructure.
- China's tunneling corridors:High-speed rail and urban metro expansion in Sichuan and Yunnan provinces consumes specialized anchoring systems for fractured rock conditions.
Market Restraints
- Styrene price volatility:Polyester resin feedstock costs swing with benzene derivative markets, squeezing contract margins for standard capsule producers.
- Supplier concentration in specialty hardeners:European and Japanese chemical houses control amine curing agent supply, creating bottleneck risk for epoxy formulators.
- Mechanical anchor substitution:Expansion bolt systems improve in seismic performance ratings, capturing share in above-ground commercial construction.
Strategic Opportunities
- India's mining modernization:Underground coal operations in Jharkhand and Odisha transition from manual to mechanized bolting, opening import demand for certified systems.
- Digital twin integration:RFID-embedded capsules enable real-time bond integrity monitoring in critical infrastructure, merging materials with IoT infrastructure.
- EU Green Deal construction incentives:Public infrastructure tenders increasingly specify low-carbon anchoring systems, favoring producers with verified lifecycle data.
Industry Challenges
- Rock bolter operator certification:Mine safety codes in Australia and South Africa mandate trained installation crews, constraining deployment velocity.
- Dual-cure formulation complexity:Developing capsules with both rapid gel and extended working time requires R&D investment beyond mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resin Capsule Market |
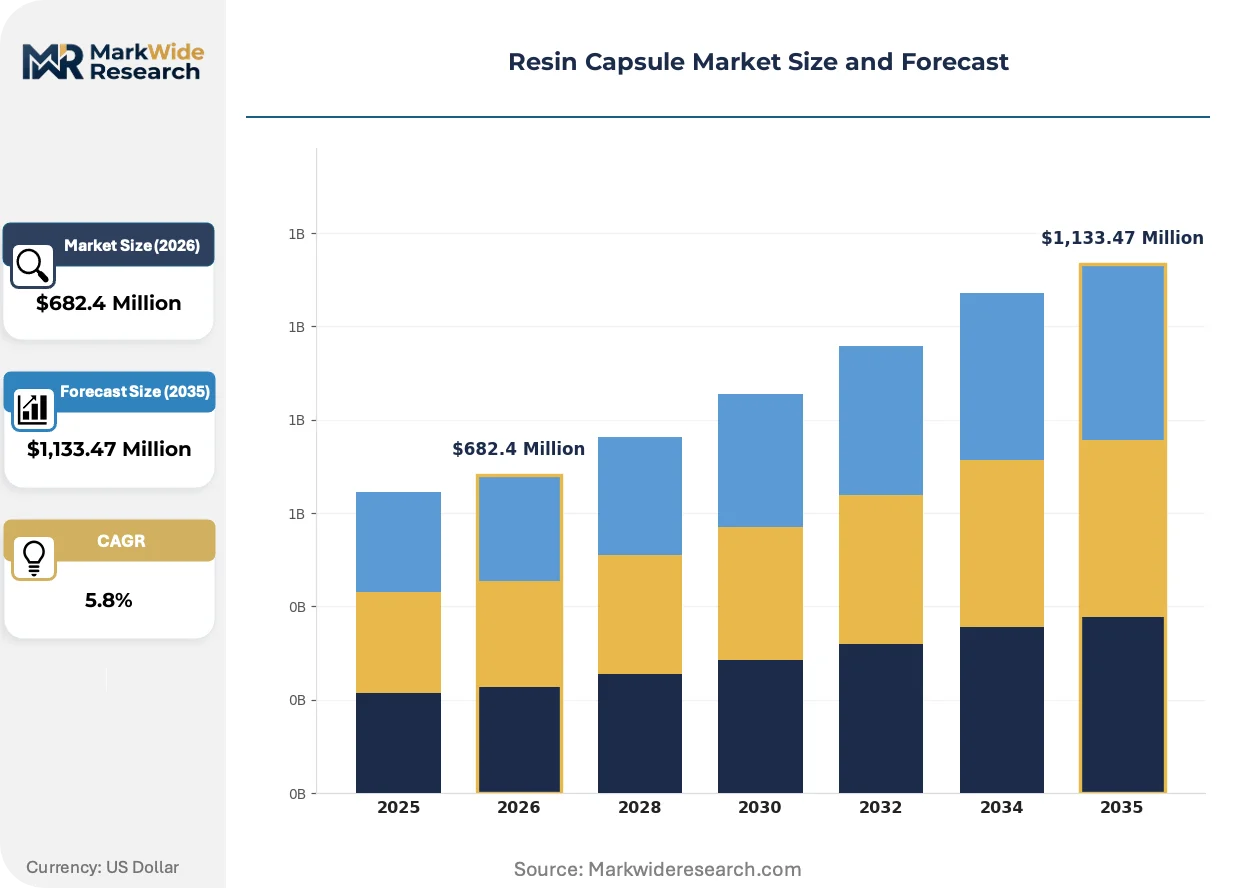
| Market Size in 2026 | $682.4 Million |
| Market Size in 2035 | $1,133.47 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Resin Capsules, High-Performance Capsules, UV-Resistant Capsules, Biodegradable Capsules Material Composition: Polyester Resin, Epoxy Resin, Phenolic Resin, Polyurethane Resin End User Industry: Electronics Manufacturing, Construction Supplies, Aerospace Components, Marine Equipment Application: Coating & Sealing, Structural Bonding, Electrical Insulation, Protective Encapsulation |
| Companies Covered | DYWIDAG-Systems International, Rawlplug, Sika AG, Arkema SA, Sormat OY, Orica Limited, Fischer Holding GmbH & CO., Hilti Corporation, Barnes Group Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resin Capsule Market Strategic Shifts & Innovations
Smart material integration and regulatory chemistry tightening are bifurcating the competitive landscape between premium performance systems and cost-optimized commodity supply.
Nano-silica modified epoxy resin is integrating into high-performance capsule formulations to enhance bond strength in wet rock conditions. Tunneling contractors in Alpine regions adopt these systems for fault-zone anchoring where moisture tolerance determines project viability. The technology is integrating quality-sensitive segments away from price-driven procurement toward specification-based selection.
REACH Annex XIV authorization requirements are expanding restricted substance lists for construction chemicals, forcing reformulation of legacy polyester catalyst systems. German and French regulatory authorities coordinate substance evaluation timelines, compressing compliance windows for multi-market suppliers. Epoxy variants with non-toxic amine hardeners capture preferential positioning in European public infrastructure tenders.
Consolidated procurement by multinational mining houses concentrates volume with approved vendor lists, marginalizing regional distributors. Tier-one contractors in South Africa and Chile now specify manufacturer-direct supply with batch traceability, bypassing traditional construction supply channels. This concentration is most pronounced in copper and platinum group metal operations where shaft safety liability drives specification stringency.
Resin Capsule Market Segmentation
Resin capsule procurement patterns diverge sharply across certification tiers, with mining safety codes and infrastructure resilience mandates creating non-negotiable performance thresholds that reshape supplier selection. Specification stringency varies by end-use liability exposure, driving fragmentation in how customers evaluate gel time consistency, load-bearing capacity, and chemical compliance documentation.
Product Type:
REACH Annex XIV authorizations and OSHA anchorage standards impose divergent testing burdens across performance tiers, with EU public infrastructure tenders now requiring batch traceability for critical applications.
- Standard Resin Capsules:Polyester-based formulations dominate underground mining consumables in Australia's hard-rock operations, where mechanized bolting demands consistent cure profiles. Volume concentrates with approved vendor lists from multinational mining houses, compressing margins for non-certified regional distributors.
- High-Performance Capsules:Extended gel time variants with nano-silica modified epoxy chemistry command specification-based selection in Alpine tunneling fault zones, where moisture tolerance determines project viability. Contractors in Sichuan and Yunnan provinces prioritize these systems for fractured rock conditions.
- UV-Resistant Capsules:Stabilized formulations serve above-ground commercial construction and marine applications requiring extended weathering performance.
- Biodegradable Capsules:Emerging formulations align with EU Green Deal construction incentives specifying low-carbon anchoring systems with verified lifecycle data.
Leading the category by volume: Standard Resin Capsules. Growing fastest: High-Performance Capsules.
Material Composition:
Feedstock concentration and regulatory chemistry tightening create divergent margin structures, with benzene derivative volatility squeezing commodity producers while amine hardener bottlenecks protect specialized epoxy formulators.
- Polyester Resin:Styrene-based systems anchor construction supply volumes across tunneling and building rehabilitation projects in mature markets. Styrene price swings with benzene derivative markets compress contract margins for standard capsule producers serving price-sensitive procurement channels.
- Epoxy Resin:Superior chemical resistance and elevated temperature performance position this chemistry as the margin-rich segment for corrosive environments. ECHA substance evaluations and EPA VOC regulations favor established producers with captive regulatory affairs capabilities and non-toxic amine hardener formulations.
- Phenolic Resin:High-temperature formulations serve aerospace component applications requiring thermal stability beyond standard epoxy limits.
- Polyurethane Resin:Flexible systems address vibration-damping requirements in specialized marine and transportation equipment applications.
Polyester Resin commands the volume base. Epoxy Resin climbs the fastest on regulatory upgrade cycles and infrastructure specification tightening.
End User Industry:
Customer consolidation patterns reshape channel economics, with direct manufacturer supply displacing traditional distribution in liability-sensitive segments.
- Construction Supplies:Tunneling, mining, and building rehabilitation projects sustain steady consumption of standard polyester capsules. Procurement consolidation by tier-one contractors in South Africa and Chile now specifies manufacturer-direct supply with batch traceability, bypassing construction supply channels.
- Electronics Manufacturing:Precision encapsulation demands drive specification of low-shrinkage epoxy systems with controlled thermal expansion coefficients for semiconductor protection.
- Aerospace Components:FAA and EASA certification requirements impose extensive qualification protocols on structural bonding and protective encapsulation systems.
- Marine Equipment:Salt spray resistance specifications from classification societies filter supplier eligibility for vessel construction and offshore platform applications.
Construction Supplies generates the largest volume throughput. Electronics Manufacturing gains share fastest on miniaturization and reliability demands.
Application:
Functional performance requirements determine chemistry selection, with load-bearing applications commanding premium formulations over passive protection roles.
- Structural Bonding:Rock bolt anchoring in underground operations demands rapid strength development and consistent gel times for mechanized installation cycles. Australia's mine safety codes mandate trained installation crews, constraining deployment velocity for uncertified systems.
- Coating & Sealing:Surface protection applications in building rehabilitation tolerate wider performance variation, enabling price-competitive polyester procurement.
- Electrical Insulation:Dielectric strength specifications from IEC and GB standards govern material selection for high-voltage equipment encapsulation.
- Protective Encapsulation:Environmental barrier functions in electronics and marine equipment prioritize moisture resistance and thermal cycling durability.
Structural Bonding leads by value concentration. Electrical Insulation shows steepest expansion trajectory on grid infrastructure and renewable energy growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Johannesburg anchors underground mining demand for resin capsule systems, with mechanized bolting operations across the Witwatersrand Basin consuming specialized anchoring formulations. Australia's hard-rock corridors and China's tunneling megaprojects reshape regional supply priorities.
Australia
Western Australia's Pilbara and Kalgoorlie mining belts drive consumption of rapid-gel polyester capsules for automated bolting cycles. Mine safety codes administered by state regulators mandate installation crew certification, constraining deployment velocity. Perth-based procurement offices of multinational mining houses consolidate approved vendor lists, bypassing traditional distribution channels.
China
Sichuan and Yunnan provinces anchor tunneling demand for high-performance epoxy systems in fractured rock conditions along high-speed rail corridors. GB standards for construction materials impose testing burdens that restrict market access for uncertified suppliers. Chongqing's infrastructure equipment clusters source specialized anchoring systems for urban metro expansion.
Germany
Ruhr Valley mining rehabilitation and Alpine tunneling projects sustain demand for REACH-compliant low-VOC epoxy variants. ECHA substance evaluations force reformulation of legacy polyester catalyst systems, compressing compliance windows for multi-market suppliers. Munich-based engineering contractors specify manufacturer-direct supply with batch traceability for public infrastructure tenders.
South Africa
Platinum group metal operations in the Bushveld Complex and gold mining in the Free State specify performance-certified anchoring systems over generic alternatives. The country's mine safety regulator mandates trained installation crews for mechanized bolting deployment. Rustenburg's shaft safety liability drives specification stringency, concentrating volume with approved vendor lists.
United States
Appalachian coal modernization and Western hard-rock copper operations sustain steady consumption of standard polyester capsules. OSHA anchorage standards elevate product testing burdens, restricting market access for uncertified suppliers. Arizona's open-pit to underground transition projects source specialized systems for slope stabilization and shaft development.
Resin Capsule Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the resin capsule landscape, with integrated chemical manufacturers facing specialized anchor system fabricators. The market structures around three tiers: multinational construction chemical conglomerates with captive resin production, dedicated anchoring system specialists with regional manufacturing footprints, and commodity converters dependent on merchant resin supply. Consolidated procurement by multinational mining houses and tier-one tunneling contractors concentrates volume with approved vendor lists. Strategic moves center on regulatory compliance certification for REACH and OSHA frameworks, plus direct supply relationships that bypass traditional construction distribution.
Within the European specialist tier, DYWIDAG-Systems International and Sika AG occupy positions anchored by integrated supply chains spanning resin chemistry and project distribution. Hilti Corporation represents the premium-system archetype through proprietary cartridge designs. Among diversified chemical conglomerates, Arkema SA exemplifies the backward-integrated model with captive resin production capabilities.
| Leading Market Players |
|---|
| DYWIDAG-Systems International |
| Rawlplug |
| Sika AG |
| Arkema SA |
| Sormat OY |
| Orica Limited |
| Fischer Holding GmbH & CO. |
| Hilti Corporation |
| Barnes Group Inc. |
| Others |
Cost & Logistics Intelligence
Consolidated procurement by multinational mining houses in Australia and South Africa now mandates manufacturer-direct supply with batch traceability, forcing supply chain restructuring and compressing margins for distributors dependent on traditional construction channels.
Pricing Analysis
Outcome-based pricing anchored to load-bearing performance and project uptime dominates specification-sensitive applications. Three-tier pricing structure across premium, standard, and economy levels separates nano-silica modified epoxy systems for Alpine fault zones from commodity polyester capsules for standard mining consumables. Pricing pressure stems from styrene feedstock volatility in benzene derivative markets, squeezing contract margins for standard capsule producers. Price-sensitive procurement concentrates in building rehabilitation and surface protection applications, while mining safety liability renders underground operators least sensitive to premium positioning.
Supply Chain Analysis
Workforce availability constraints in German and Japanese chemical manufacturing clusters limit amine hardener production capacity for epoxy formulators. Supply concentrates in Germany for REACH-compliant formulations, Australia for rapid-gel polyester systems, and China for high-volume tunneling applications. Raw material dependencies rest on benzene derivatives for polyester resins, non-toxic amine curing agents for European compliance, and nano-silica additives for premium performance tiers. Single-source vulnerability in specialty hardener supply creates bottleneck risk for epoxy manufacturers. Distribution runs through approved vendor lists for mining operations, bypassing traditional construction supply channels in favor of manufacturer-direct relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a vertical-integration race where control over resin chemistry and captive regulatory affairs capabilities determines competitive survival against reformulation mandates from ECHA and EPA.
For Market Incumbents: Anticipate REACH Annex XIV expansion by securing backward integration into non-toxic amine hardener production and establishing dedicated regulatory affairs teams in Brussels and Washington. Defend against mechanical anchor substitution in above-ground construction by embedding RFID-enabled capsules for digital twin integration. Prioritize certification investment for Australia's mine safety codes to maintain approved vendor status with multinational mining houses. For New Entrants and Emerging Players: Launch via direct supply relationships with tier-one tunneling contractors in Sichuan and Yunnan provinces, bypassing established distribution channels. Target India's mining modernization in Jharkhand and Odisha as the most penetrable geography, where underground coal operations transition from manual to mechanized bolting. Pursue biodegradable capsule formulations aligned with EU Green Deal construction incentives as a differentiated go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors mid-cap epoxy specialists with captive regulatory capabilities and established European manufacturing footprints. Long-term viability hinges on positioning for infrastructure resilience mandates and mine safety specification tightening across the analysis window. Watch ECHA substance evaluation timelines as the critical inflection signal for reformulation-driven consolidation waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amine Hardeners | Secures supply chain resilience against Japanese and European chemical house concentration for epoxy formulators. |
| REACH Compliance Certification Investment | Enables access to EU public infrastructure tenders specifying low-VOC anchoring systems with verified lifecycle data. |
| RFID-Enabled Smart Capsule Development | Merges materials with IoT infrastructure for real-time bond integrity monitoring in critical mining and tunneling applications. |
| Direct Supply Relationship Establishment | Bypasses traditional construction distribution channels where multinational mining houses consolidate approved vendor lists. |
| Biodegradable Formulation R&D Program | Aligns product portfolio with EU Green Deal construction incentives favoring low-carbon anchoring systems. |
Research Approach
Independent corroboration across plant managers at resin manufacturing facilities, procurement leads at Australian and South African mining operations, distribution channel partners in European construction supply, and technical R&D directors at specialty chemical firms underwrites the qualitative findings. Secondary validation draws from ECHA substance evaluation databases, SEC 10-K filings of listed construction chemical conglomerates, customs and trade data for resin feedstock flows, and mine safety regulator compliance records. Bottom-up volume estimates from end-use application analysis triangulate against top-down market sizing from chemical production capacity data.
Comparable-period anchoring to historical polyester and epoxy resin consumption patterns across mining, tunneling, and construction rehabilitation sectors structures the forecast framework. The analytical framework models volume and value across material composition tiers, end-use industry segments, application functional requirements, and regional regulatory clusters throughout the forecast period. CAGRs derive from segmented growth rate assumptions calibrated to mechanized bolting adoption curves, infrastructure investment pipelines, and regulatory compliance upgrade cycles. Key inputs include mining automation penetration rates and tunneling project development databases for China's high-speed rail corridors.
The model assumes a particular technology adoption path; alternative pathways for nano-silica modified epoxy integration or mechanical anchor substitution would alter the outlook. Forecasts reflect assumptions regarding REACH enforcement timelines, styrene price stability, and mining house procurement consolidation trajectories. Material deviation in ECHA substance evaluation schedules or Australia's mine safety code amendments warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
N-Propyl Propionate Market
Specialty Compounds
Global Stannic Chloride Market
Specialty Compounds
Saudi Arabia Masterbatch Market
Specialty Compounds
Hydroxypropyl Methylcellulose Market
Specialty Compounds
Compounding Systems Market
Specialty Compounds
Phenylacetyl Chloride Market
Specialty Compounds
North America Polyphenylene Sulfide Compounds Market
Specialty Compounds
Global Specialty Oilfield Chemicals Market
Specialty Compounds
Quinidine Sulfate Market
Specialty Compounds
Potassium Monopersulfate (KMPS) Market
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Global Color Masterbatch Market
Specialty Compounds
Global Molding Compounds Market
Specialty Compounds
Potassium Hydrogen Sulphite Market
Specialty Compounds
Opacifiers Market
Specialty Compounds
Global Stable Isotope Labeled Compounds Market