
 Nuclear Export Inhibitor Drugs Market | 2026-2036
Nuclear Export Inhibitor Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Nuclear Export Inhibitor Drugs Market Analytics
Oncology-trained medicinal chemists is reorganizing how quickly nuclear export inhibitor pipelines advance from discovery to clinical testing. Karyopharm Therapeutics anchors this space through its first-mover position with selinexor-based programs. Novartis leverages its global hematology franchise to extend reach into combination regimens. Amgen competes by concentrating on biomarker-driven patient selection for its experimental programs.
Nuclear export inhibitors are small-molecule compounds that block chromosome region maintenance 1 (CRM1)-mediated transport of tumor suppressor proteins from nucleus to cytoplasm, thereby restoring apoptotic signaling in malignant cells. These agents primarily serve oncology by reactivating p53, p21, and other growth-regulatory proteins in cancers with intact nuclear export machinery. Inhibitor molecules currently dominate the product landscape, while combination therapies represent the fastest-expanding segment as developers pair export blockade with proteasome or BCL-2 inhibition. Oral delivery mode captures the largest patient-volume share, though intravenous formulations retain higher per-dose pricing in hospitalized lymphoma and leukemia protocols.
The FDA's accelerated approval framework and orphan drug designation program shape clinical trial design and commercial strategy for developers in this space. EMA's Committee for Medicinal Products for Human Use applies distinct evidentiary standards for conditional marketing authorization that influence European filing timelines. Stakeholders must monitor how evolving FDA guidance on confirmatory trial requirements for accelerated approvals affects post-market commitment burdens and label expansion pathways.
Market Dynamics
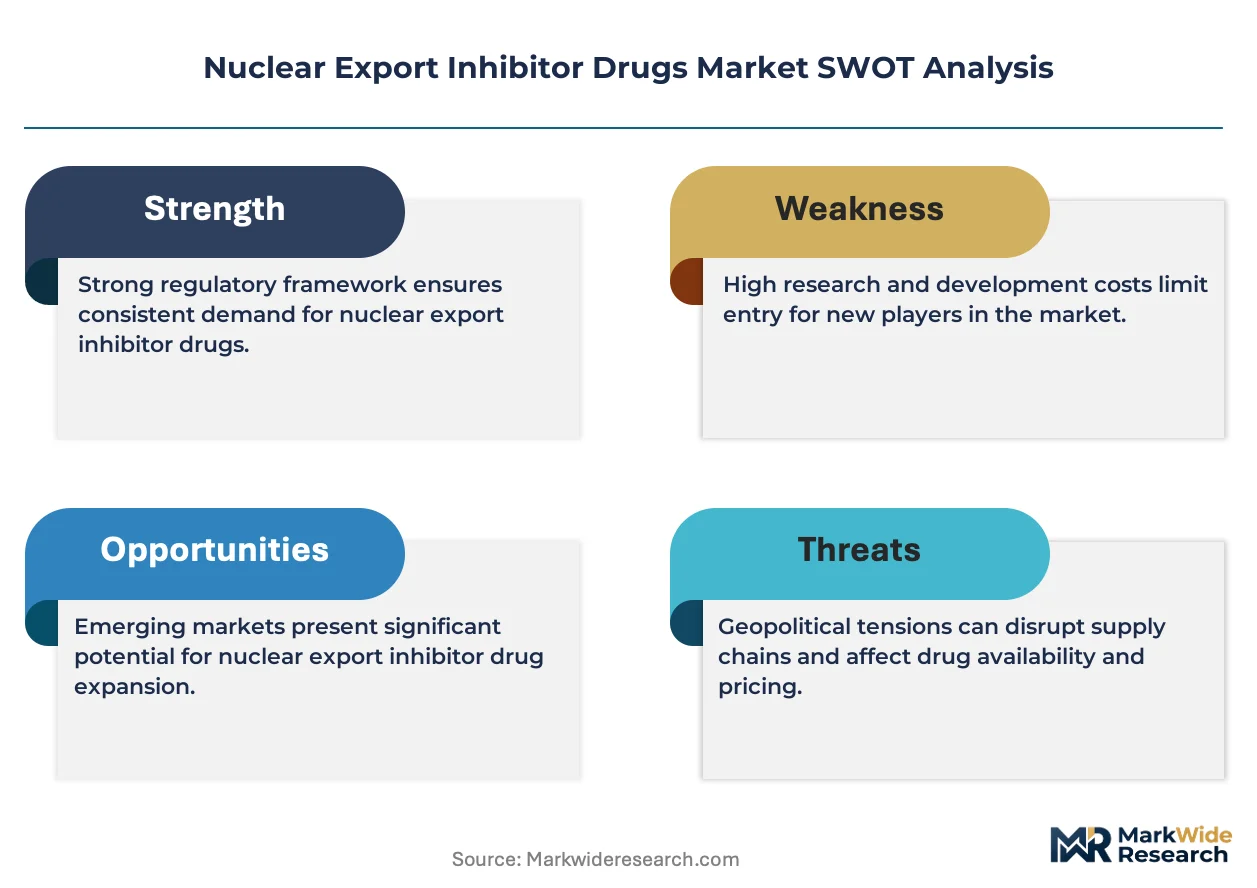
Accelerated approval pathways for hematologic malignancies are compressing development timelines and redirecting capital toward confirmatory trial designs rather than traditional Phase III frameworks.
Growth Catalysts
- Orphan Drug Incentives:The FDA's orphan drug designation program grants seven-year market exclusivity and tax credits for clinical testing, concentrating developer investment on rare lymphoma subtypes with unmet need.
- Combination Protocol Expansion:Academic medical centers in Boston and Houston are integrating export inhibitors with proteasome blockade in multiple myeloma regimens, creating pull-through demand for companion diagnostics.
- Biomarker Stratification:CRM1 expression profiling is segmenting addressable populations, enabling precision enrollment that satisfies FDA evidentiary standards for accelerated approvals.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient synthesis for selinexor analogs depends on a limited base of contract manufacturers in India and China, exposing programs to geopolitical friction and import inspection delays.
- Confirmatory Trial Burden:Post-market commitment requirements under FDA accelerated approval rules demand larger patient cohorts than initial registration studies, stretching R&D budgets across extended timelines.
- Substitution by CAR-T:Chimeric antigen receptor T-cell therapies for relapsed multiple myeloma are capturing transplant-ineligible patients who previously represented the core addressable population for export inhibitors.
Strategic Opportunities
- Solid Tumor Penetration:Sarcoma and glioblastoma indications remain underexplored, with CRM1 overexpression documented in tissue banks but lacking prospective validation in registration-directed trials.
- EMA Conditional Authorization:The Committee for Medicinal Products for Human Use pathway permits earlier European market entry based on surrogate endpoints, enabling revenue generation while US confirmatory trials mature.
- Real-World Evidence Integration:Flatiron Health and similar oncology data platforms are creating infrastructure for post-approval effectiveness studies that satisfy FDA requirements without traditional randomized controls.
Industry Challenges
- Medicinal Chemistry Talent Scarcity:Nuclear transport biology expertise resides at a handful of academic institutions, forcing sponsors to compete for limited translational researchers capable of optimizing CRM1-binding scaffolds.
- Thrombocytopenia Management:Dose-limiting hematologic toxicities require specialized nursing protocols and patient monitoring infrastructure that community oncology practices lack, constraining site expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nuclear Export Inhibitor Drugs Market |
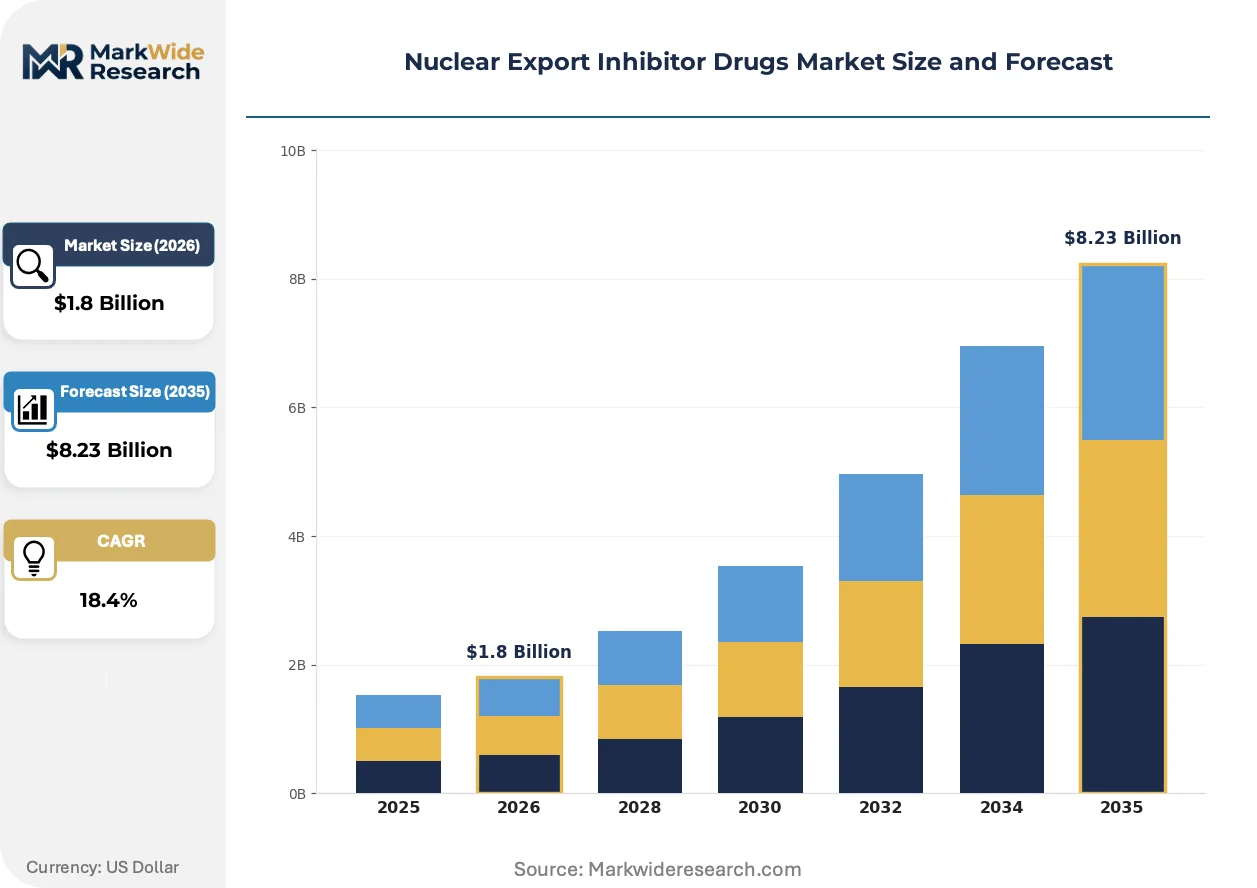
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inhibitor Molecules, Combination Therapies, Targeted Agents, Experimental Drugs End User: Research Institutions, Pharmaceutical Companies, Hospitals, Clinics Therapy Area: Cancer, Autoimmune Diseases, Infectious Diseases, Rare Disorders Delivery Mode: Oral, Intravenous, Subcutaneous, Topical |
| Companies Covered | Biogen, Curis, Karyopharm Therapeutics, Novartis, Incyte, Antengene Corporation, Amgen, AstraZeneca, Accutar Biotech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nuclear Export Inhibitor Drugs Market Evolving Landscape
Development pipelines are splitting between next-generation CRM1 inhibitors with improved therapeutic indices and bispecific constructs that pair nuclear export blockade with immune recruitment mechanisms.
Next-generation scaffolds are bifurcating the clinical landscape. Karyopharm's second-generation compounds and rival programs from academic spinouts are advancing through IND-enabling studies with reduced off-target binding profiles. Hematology departments at Dana-Farber and MD Anderson are prioritizing these candidates for early-phase trials based on preclinical hematologic toxicity data. The technology is bifurcating competitive positioning between first-mover label breadth and late-entrant safety differentiation.
REACH registration requirements in Europe are reshaping environmental risk assessment obligations for small-molecule oncologics. Sponsors must now submit persistent, bioaccumulative, and toxic substance evaluations alongside clinical modules, extending regulatory timelines by four to six months. This friction is concentrating European filing resources on candidates with the clearest accelerated approval pathways.
Hospital pharmacy committees are consolidating formulary decisions for high-cost oral oncolytics under centralized oncology pharmacy directors. This concentration is displacing traditional physician-directed prescribing in community settings. The shift is most visible in Texas and California, where integrated delivery networks are capturing nuclear export inhibitor dispensing through captive specialty pharmacies.
Nuclear Export Inhibitor Drugs Market Segmentation
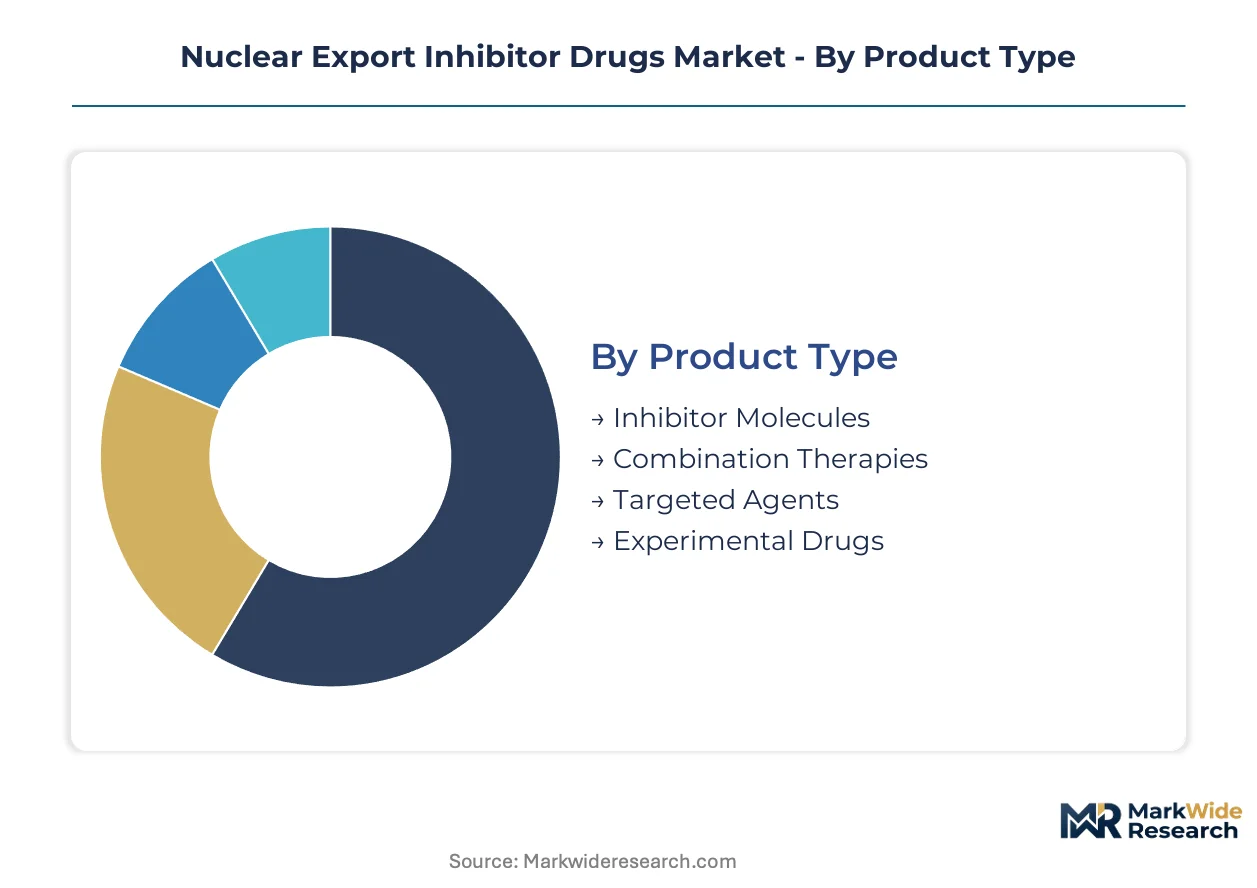
Segmentation in the nuclear export inhibitor space reveals how clinical adoption channels and reimbursement pathways diverge across product formats. Understanding these splits enables developers to align manufacturing scale with the specific infrastructure requirements of each customer type.
Product Type:
Inhibitor molecules flow primarily through hospital pharmacy channels under buy-and-bill arrangements, while combination therapies route through specialty distributors serving academic medical centers.
- Inhibitor Molecules:Single-agent CRM1 blockers such as selinexor analogs constitute the foundational product class. Demand concentrates at Dana-Farber Cancer Institute and MD Anderson Cancer Center, where hematology protocols prioritize monotherapy enrollment for biomarker-selected patients. Dose-limiting thrombocytopenia constrains community oncology expansion.
- Combination Therapies:Regimens pairing export inhibitors with proteasome or BCL-2 blockers represent the most dynamic pipeline segment. Boston and Houston academic networks are driving adoption through investigator-initiated trials combining selinexor with bortezomib or venetoclax. These protocols require specialized nursing infrastructure that community sites lack.
- Targeted Agents:Next-generation compounds with improved therapeutic indices are advancing through IND-enabling studies.
- Experimental Drugs:Academic spinout programs and early-phase biotech assets remain confined to preclinical and Phase I settings.
By volume, inhibitor molecules lead. By growth pace, combination therapies are expanding most quickly.
End User:
Cost tier stratification separates capital-intensive research infrastructure from reimbursed clinical delivery settings.
- Research Institutions:Academic medical centers with dedicated nuclear transport biology programs anchor early-phase trial enrollment. Massachusetts General Hospital and Baylor College of Medicine maintain specialized medicinal chemistry capabilities for scaffold optimization. NIH grant funding supports investigator-initiated protocols.
- Pharmaceutical Companies:Sponsors with global hematology franchises leverage existing KOL relationships to accelerate combination regimen development. These organizations concentrate clinical operations at centralized sites with CRM1 expression profiling capabilities.
- Hospitals:Integrated delivery networks in Texas and California are consolidating formulary decisions under centralized oncology pharmacy directors.
- Clinics:Community oncology practices face exclusion due to thrombocytopenia monitoring requirements.
Research institutions command the highest per-patient revenue. Hospital networks are gaining share fastest as integrated delivery systems expand.
Therapy Area:
Application maturity varies sharply, with oncology dominating commercial infrastructure while adjacent indications lack validated biomarkers.
- Cancer:Hematologic malignancies—multiple myeloma, diffuse large B-cell lymphoma, and acute myeloid leukemia—anchor all approved indications. The FDA's accelerated approval pathway for selinexor in penta-refractory myeloma established the commercial template. Solid tumor penetration in sarcoma and glioblastoma awaits prospective validation.
- Autoimmune Diseases:Preclinical programs are exploring CRM1 inhibition in lupus and rheumatoid arthritis models.
- Infectious Diseases:Viral export pathway research remains academic with no active clinical programs.
- Rare Disorders:Orphan indications with CRM1 dysregulation are attracting exploratory interest.
Cancer applications generate current revenue. Autoimmune disease represents the steepest expansion trajectory if mechanistic validation succeeds.
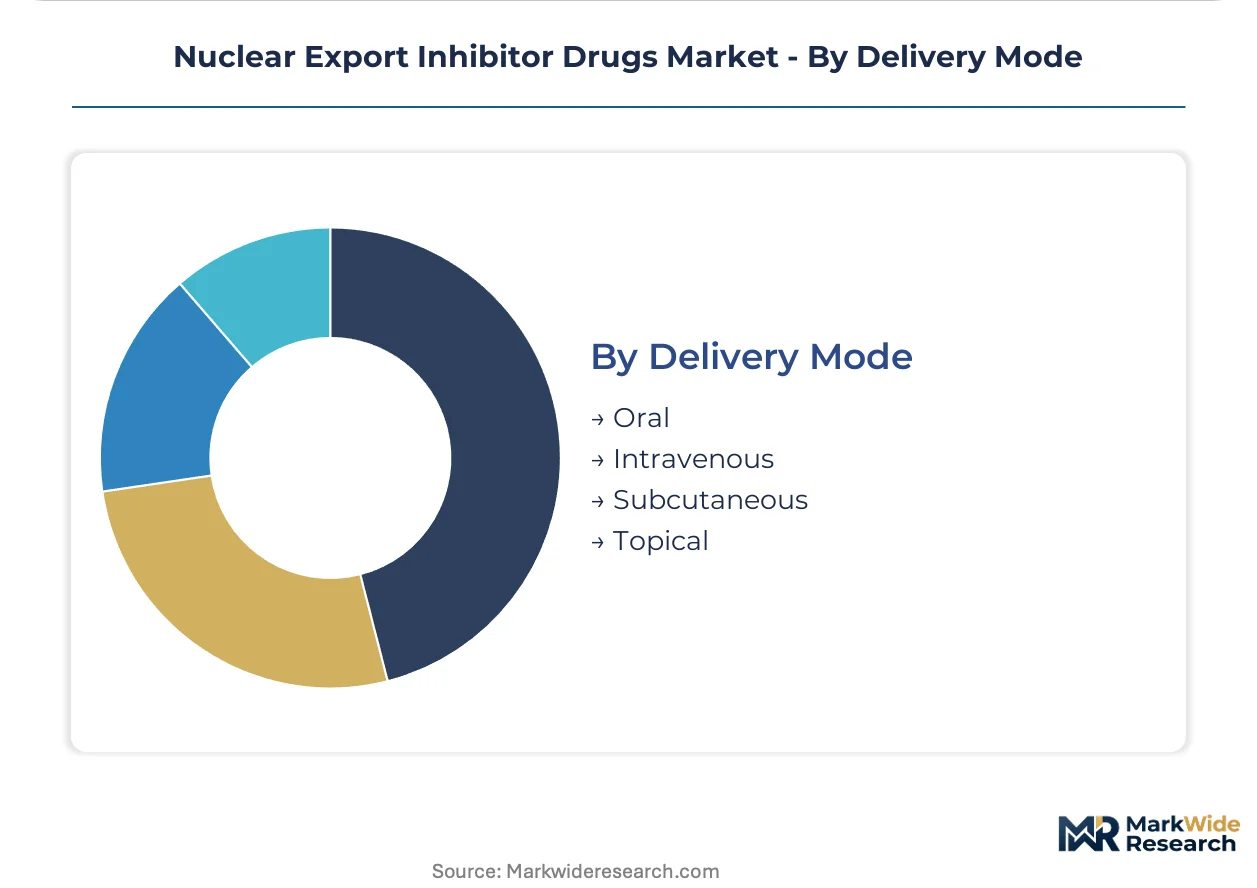
Delivery Mode:
Patient volume and margin structure diverge between outpatient oral dispensing and higher-priced inpatient administration.
- Oral:Tablet formulations capture the largest patient-volume share through specialty pharmacy dispensing. Karyopharm's selinexor tablets enable outpatient management of relapsed myeloma, though adherence monitoring requirements add nursing burden. Hospital pharmacy committees are consolidating these decisions under centralized directors.
- Intravenous:Infusion protocols retain higher per-dose pricing in hospitalized lymphoma and leukemia settings. Academic medical centers prefer IV administration for combination regimens requiring concurrent hydration and antiemetic support.
- Subcutaneous:Depot formulations are in early development for improved adherence.
- Topical:No active programs; skin penetration of CRM1 inhibitors remains unvalidated.
Oral delivery leads by patient volume. Intravenous maintains premium positioning in academic center protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways and orphan drug incentives anchor commercial momentum in the United States. EMA conditional authorization frameworks and national reimbursement negotiations shape European access patterns. Academic medical center concentration determines adoption velocity across all developed markets.
United States
Dana-Farber Cancer Institute and MD Anderson Cancer Center drive investigator-initiated trial enrollment for combination regimens. FDA orphan drug designation grants seven-year exclusivity for rare lymphoma indications. Boston and Houston academic networks concentrate specialized nursing infrastructure for thrombocytopenia monitoring protocols.
Germany
University hospital hematology departments prioritize biomarker-stratified patient selection for early-phase studies. EMA Committee for Medicinal Products for Human Use standards influence European filing timelines for conditional authorization. Heidelberg and Munich cancer centers maintain CRM1 expression profiling capabilities for precision enrollment.
Switzerland
Swissmedic streamlined review pathways attract sponsors seeking parallel US-European submissions. Basel and Zurich pharmaceutical clusters host global hematology franchise operations. Roche and Novartis legacy infrastructure supports combination therapy development through existing KOL networks.
Japan
PMDA sakigake designation program accelerates review for hematologic malignancy innovations with unmet need. Tokyo and Osaka academic medical centers specialize in elderly myeloma patient protocols. METI industrial policy supports domestic biotech incubation for nuclear transport biology programs.
United Kingdom
NHS England specialized commissioning frameworks concentrate high-cost oral oncolytic dispensing at designated cancer centers. MHRA reliance recognition post-Brexit maintains alignment with FDA evidentiary standards. London and Manchester integrated care systems consolidate formulary decisions under regional pharmacy directors.
Nuclear Export Inhibitor Drugs Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the nuclear export inhibitor landscape. First-movers with approved indications command premium positioning through label breadth and KOL relationships. Late-entrant biotechs differentiate through next-generation scaffold safety profiles and biomarker-driven patient selection. Competitive dynamics center on strategic partnerships for combination regimen development and geographic licensing to extend reach into European and Asian markets.
Among established biopharmaceutical developers, Karyopharm Therapeutics anchors the first-mover archetype through its selinexor-based platform and early-phase pipeline breadth. Novartis occupies a position leveraging global hematology franchise infrastructure for combination therapy expansion. Amgen exemplifies the biomarker-specialist approach with experimental programs targeting CRM1 expression-selected populations.
| Leading Market Players |
|---|
| Biogen |
| Curis |
| Karyopharm Therapeutics |
| Novartis |
| Incyte |
| Antengene Corporation |
| Amgen |
| AstraZeneca |
| Accutar Biotech |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between academic medical centers and specialty distributors lock in supply access for oral oncolytics while anchoring price visibility through buy-and-bill arrangements. These contracts shield hospital pharmacy committees from API spot market volatility originating in Indian and Chinese manufacturing zones.
Pricing Analysis
US academic medical centers command premium pricing for intravenous combination regimens compared to oral tablet dispensing in community settings. Three-tier pricing structure across premium IV protocols, standard oral monotherapy, and economy-tier generic substitution candidates reflects nursing infrastructure requirements and biomarker stratification depth. Pricing pressure stems from CAR-T substitution in relapsed multiple myeloma, compressing margins for transplant-ineligible patient segments. Community oncology practices exhibit highest price sensitivity due to thrombocytopenia monitoring cost burdens, while integrated delivery networks leverage volume consolidation for preferential access terms.
Supply Chain Analysis
Strategic stockpiling of selinexor API precursors dominates inventory strategy as sponsors buffer against import inspection delays from contract manufacturers. Active pharmaceutical ingredient synthesis concentrates in India and China, with specialized fermentation and chromatography capabilities anchored in Hyderabad and Shanghai zones. Key inputs include chromatography resins, high-purity solvents, and CRM1-binding scaffold intermediates sourced from German and Japanese chemical suppliers. Single-source vulnerability in chiral separation technology creates exposure to export license restrictions. Distribution runs through captive specialty pharmacies within integrated delivery networks, displacing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Translational expertise in nuclear transport biology resides at fewer than a dozen academic institutions worldwide, creating acute bottlenecks for scaffold optimization and biomarker validation programs.
For Market Incumbents: Consolidate medicinal chemistry talent through exclusive sponsored research agreements with Dana-Farber and MD Anderson nuclear transport programs. Deepen backward integration into API precursor manufacturing to reduce exposure to Indian and Chinese contract manufacturer inspection delays. Prioritize confirmatory trial enrollment velocity to defend label breadth against second-generation entrants with improved hematologic safety profiles. For New Entrants and Emerging Players: Lead with solid tumor indications in sarcoma and glioblastoma where CRM1 overexpression lacks prospective validation but tissue bank evidence supports mechanistic rationale. Target European conditional authorization pathways through EMA Committee for Medicinal Products for Human Use submissions, enabling revenue generation while US confirmatory trials mature. Deploy real-world evidence partnerships with Flatiron Health to satisfy post-approval effectiveness requirements without traditional randomized controls. For Investors and Strategic Acquirers: Capital is best deployed toward biotechs with validated second-generation CRM1 scaffolds and established KOL relationships at academic medical centers. Long-term viability hinges on combination regimen positioning against cellular therapy substitution in hematologic malignancies. Watch for FDA guidance shifts on confirmatory trial requirements as the primary inflection signal for post-market commitment burden reassessment.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates selinexor analogs through IND-enabling studies with reduced thrombocytopenia profiles. |
| Regulatory Approval Pathway | EMA conditional authorization enables European revenue before FDA confirmatory trial completion. |
| Licensing Agreement | Extends reach into Asian markets through PMDA sakigake designation partnerships. |
| Manufacturing Scale-Up | Captive API production mitigates geopolitical friction in Indian and Chinese supply zones. |
| Pipeline Diversification | Autoimmune disease programs in lupus models create optionality beyond oncology saturation. |
Research Methodology
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions for pipeline velocity and adoption curves. Primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases anchored the evidence base. Bottom-up patient-flow modeling and top-down revenue triangulation cross-checked segmentation outputs across the analysis window.
Segmentation dimensions modeled include product type, therapy area, delivery mode, end user, and regional regulatory cluster throughout the forecast period. CAGRs derived from enrollment velocity at anchor academic medical centers and reimbursement pathway progression across US and European markets. Forecast inputs incorporated biomarker stratification penetration rates and combination regimen adoption curves in multiple myeloma protocols.
Forecasts assume regulatory continuity in FDA accelerated approval frameworks and EMA conditional authorization regimes; material policy shifts would require re-modeling of commercial timeline assumptions. Practitioners should keep alternative scenarios live as CAR-T substitution rates and API import inspection protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Small-Molecule Injectable Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
Prescription Hair Loss and Hair Removal Drugs Market
Pharmaceutical Ingredients
Vitamins and Derivatives Market
Pharmaceutical Ingredients
Asia-Pacific Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceutical Ingredients
Calcium Gluconate Market
Pharmaceutical Ingredients
Germany Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Synthetic Small Molecule API Market
Pharmaceutical Ingredients
Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Transdermal Drugs Market
Pharmaceutical Ingredients
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market
Pharmaceutical Ingredients
Biologic Excipients Market
Pharmaceutical Ingredients
Originator Small Molecule Drug Market
Pharmaceutical Ingredients
Fipronil Market
Pharmaceutical Ingredients
Cetrorelix Acetate API Market
Pharmaceutical Ingredients
Pemetrexed Market