
 Pharma-Grade Magnesium Trisilicate Market | 2026-2036
Pharma-Grade Magnesium Trisilicate Market Size, Share, and Industry Trends Forecast 2026-2036
Pharma-Grade Magnesium Trisilicate Market Analytics
The gap between pharmacopeial-grade and technical-grade magnesium trisilicate is recalibrating procurement patterns across pharmaceutical supply chains. Merck KGaA leverages its European manufacturing base to sustain premium positioning in compendial-grade supply. Tomita Pharmaceutical Co. Ltd. anchors Asian distribution through specialized excipient channels. Par Drugs and Chemicals Pvt. Ltd. competes on volume scale within India's domestic formulation sector.
Pharma-grade magnesium trisilicate is a hydrated magnesium silicate compound with the approximate formula Mg2Si3O8·nH2O, manufactured through controlled precipitation and thermal processing to meet USP-NF, EP, and JP monograph specifications for acid-neutralizing capacity and heavy metal limits. Its primary commercial purpose is as an active pharmaceutical ingredient in antacid tablets and suspensions, where it neutralizes gastric acid through slow-acting, sustained buffering. Tablet formulations occupy the largest share of finished-dose demand, while powder grades command margin premiums in compounding pharmacy and export-oriented manufacturing. The antacid application segment leads volume consumption, though dietary supplement positioning is gaining traction in direct-to-consumer channels across North American and European retail.
FDA's Current Good Manufacturing Practice enforcement for excipient qualification and the European Pharmacopoeia's tightening heavy metal thresholds are elevating compliance costs for non-integrated suppliers. India's CDSCO alignment with ICH Q3D elemental impurity guidelines is reshaping domestic manufacturer certification requirements. Stakeholders must monitor pharmacopeial harmonization timelines and excipient master file submission pathways to secure long-term formulation partnerships.
Market Dynamics
Pharmacopeial harmonization between USP-NF, EP, and JP monographs is compressing supplier qualification timelines while elevating purity thresholds, forcing excipient manufacturers to recalibrate precipitation and thermal processing protocols or exit hospital procurement channels entirely.
Growth Catalysts
- ICH Q3D Alignment:India's CDSCO adoption of elemental impurity guidelines is compelling domestic API-to-formulation integrators to upgrade magnesium trisilicate specifications, opening certified supplier slots previously held by technical-grade imports.
- Antacid Suspension Demand:Hospital formulary expansion of liquid antacid protocols in gastroenterology departments is pulling higher-powder-grade volumes through specialized excipient distributors.
- Controlled Precipitation Advances:Continuous manufacturing adaptations in silicate processing are reducing batch-to-batch heavy metal variability, satisfying FDA Current Good Manufacturing Practice enforcement without manual intervention.
Market Restraints
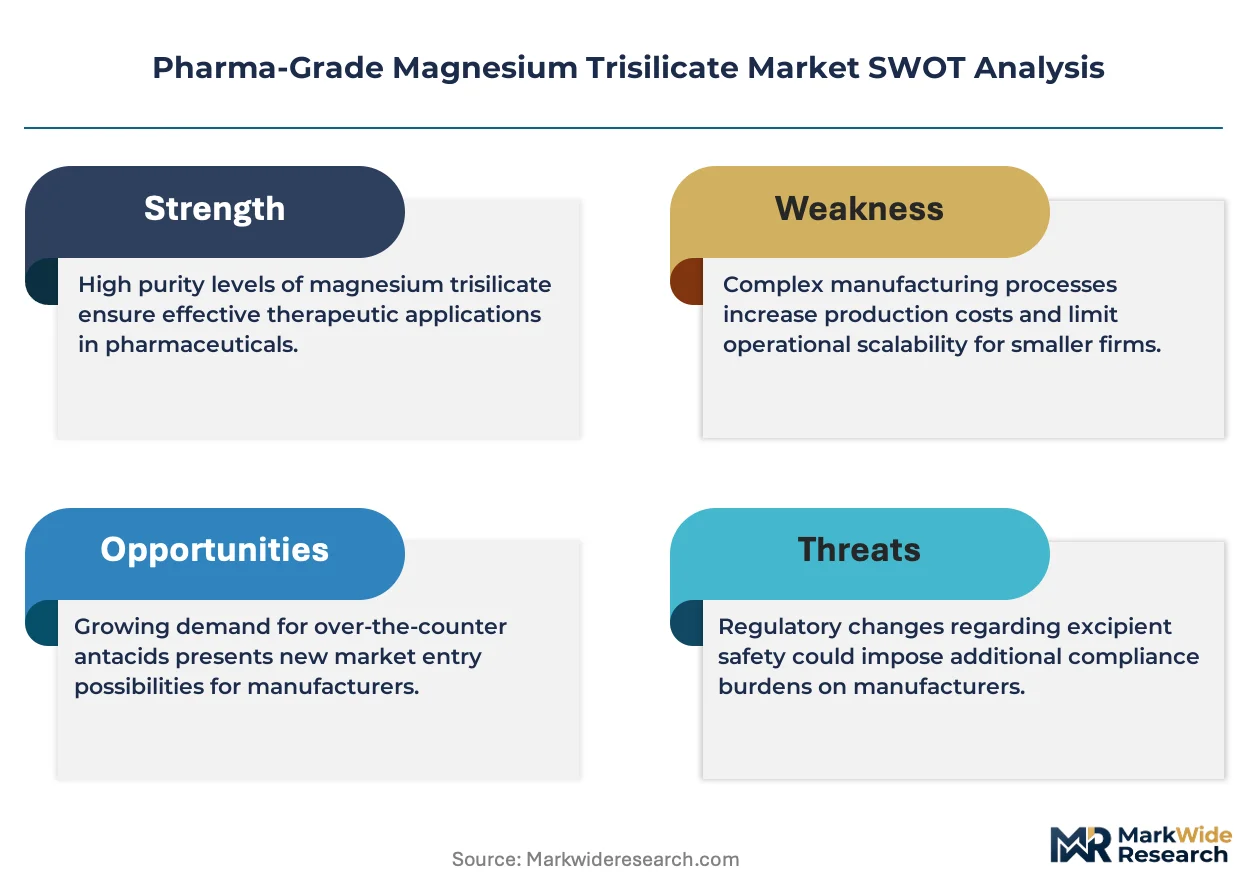
- Magnesium Ore Volatility:Raw material concentration in Chinese mining districts exposes non-integrated European and Indian formulators to input cost swings that compress margin on fixed-price hospital contracts.
- Heavy Metal Threshold Compression:European Pharmacopoeia's tightening limits on lead and arsenic residuals are disqualifying legacy precipitation facilities lacking inductively coupled plasma mass spectrometry verification.
- Aluminum Hydroxide Substitution:Reformulation of antacid tablets toward aluminum-based alternatives in cost-sensitive over-the-counter segments is displacing magnesium trisilicate volume in retail pharmacy channels.
Strategic Opportunities
- Dietary Supplement Repositioning:Direct-to-consumer magnesium positioning in North American retail is creating compounding pharmacy demand for USP-grade powder outside traditional antacid applications.
- Excipient Master File Pathways:FDA's Type II drug master file acceptance for magnesium trisilicate is enabling qualified suppliers to secure long-term formulation partnerships without repeated facility audits.
- Continuous Processing Convergence:Integration of in-line particle size monitoring with thermal processing is overtaking batch manufacturing in new facility designs, reducing qualification documentation burdens.
Industry Challenges
- Analytical Chemistry Talent Scarcity:ICP-MS operation and pharmacopeial method validation expertise is concentrating in contract laboratories, stretching in-house quality control timelines for mid-tier manufacturers.
- Multinational Certification Synchronization:Simultaneous USP-NF, EP, and JP update cycles are forcing redundant stability studies and documentation revisions that delay product release by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharma-Grade Magnesium Trisilicate Market |
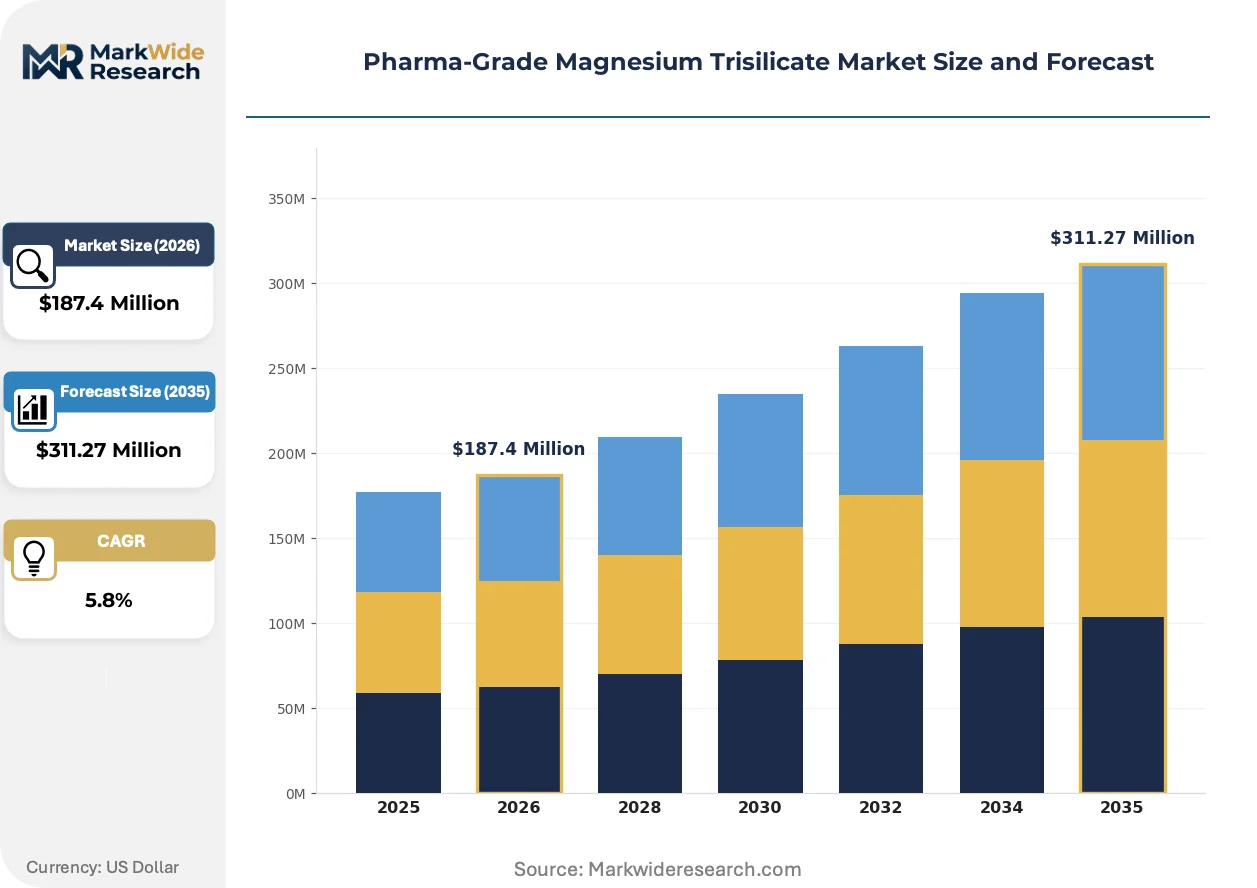
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Powder, Granules, Suspensions Application: Antacid, Anti-Ulcer, Laxative, Dietary Supplement End User: Pharmacies, Hospitals, Clinics, Retail Stores Delivery Mode: Oral, Topical, Injectable, Rectal |
| Companies Covered | Merck KGaA, Tomita Pharmaceutical Co. Ltd., Par Drugs and Chemicals Pvt. Ltd., Osian Marine Chemicals Pvt. Ltd., Meha Chemicals, Jai Radhe Sales, Taurus Chemicals, Priti Industries, Kyowa Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharma-Grade Magnesium Trisilicate Market Evolving Landscape
Processing technology and regulatory documentation protocols are converging to redefine supplier competitiveness, with automation and pharmacopeial alignment displacing legacy batch-oriented qualification models.
Continuous precipitation systems with real-time particle size distribution feedback are overtaking conventional batch reactor configurations in new facility investments. European excipient specialists are deploying these systems to compress USP-NF certification cycles from eighteen months to under nine. The structural consequence is a widening capability gap between automated first-tier suppliers and manual-process competitors facing hospital procurement exclusion.
REACH registration requirements for silicate compounds are compelling European manufacturers to submit full toxicological dossiers that previously qualified under polymer exemptions. This regulatory expansion is raising compliance costs for import-reliant formulation houses. German and French antacid producers are responding by consolidating supplier bases toward REACH-registered domestic sources with established safety data packages.
Hospital group purchasing organizations are consolidating excipient qualification onto centralized platforms that demand electronic excipient information package submissions. This procurement centralization is disintermediating regional distributors who lack digital documentation infrastructure. The shift is most visible in United States health system procurement, where three national GPOs now control the majority of antacid formulation ingredient sourcing decisions.
Pharma-Grade Magnesium Trisilicate Market Segmentation
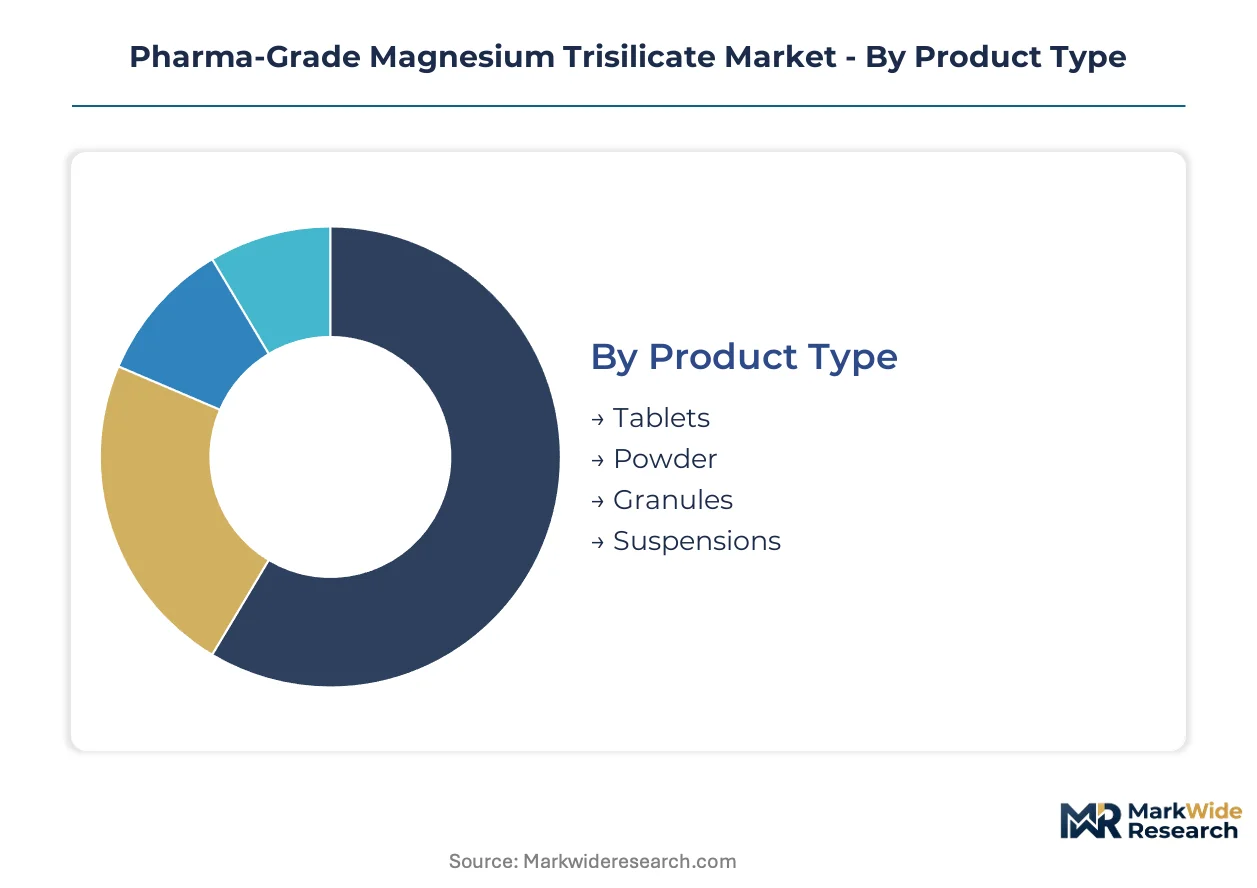
Pharma-grade magnesium trisilicate procurement patterns diverge sharply across formulation formats and clinical settings. Regulatory compliance thresholds and compounding flexibility requirements reshape supplier selection within each segment boundary.
Product Type:
Formulation manufacturers prioritize powder flow properties and dissolution profiles differently depending on their captive tableting capacity versus outsourcing arrangements.
- Tablets:Direct-compression and wet-granulation grades dominate hospital formulary procurement. USP-NF dissolution specifications drive supplier qualification toward European manufacturers with validated particle size distribution controls.
- Powder:Fine-milled compendial grades command margin premiums in compounding pharmacy channels. India's domestic API-to-formulation integrators source powder grades for suspension manufacturing and export-oriented antacid production.
- Granules:Intermediate processing state for sustained-release matrix formulations.
- Suspensions:Colloidal stability requirements favor precipitated grades with controlled surface area.
Tablets lead volumes today; powder is gaining share fastest.
Application:
Clinical efficacy endpoints and reimbursement pathways determine whether magnesium trisilicate serves as active ingredient or functional excipient.
- Antacid:Gastric acid neutralization remains the dominant commercial purpose. Hospital gastroenterology departments specify sustained-buffering tablets for inpatient formulary inclusion.
- Anti-Ulcer:Cytoprotective positioning in combination therapies requires pharmacopeial-grade heavy metal certification under ICH Q3D guidelines.
- Laxative:Osmotic bowel preparation applications favor technical-grade alternatives, limiting pharma-grade penetration.
- Dietary Supplement:Direct-to-consumer magnesium positioning in North American retail channels is expanding compounding pharmacy demand for USP-certified powder outside traditional antacid indications.
Antacid applications dominate current volumes; dietary supplement positioning shows the steepest expansion trajectory.
End User:
Procurement sophistication and documentation requirements separate institutional buyers from retail-channel distributors.
- Pharmacies:Compounding operations require excipient master file documentation and lot-specific certificates of analysis.
- Hospitals:Group purchasing organization consolidation demands electronic excipient information package submissions and validated supplier audit trails.
- Clinics:Outpatient gastroenterology practices source through specialty distributors with regional cold-chain capabilities.
- Retail Stores:Over-the-counter antacid shelf placement competes on unit economics against aluminum hydroxide alternatives.
Hospitals anchor procurement volumes today; retail direct-to-consumer channels are expanding most quickly.
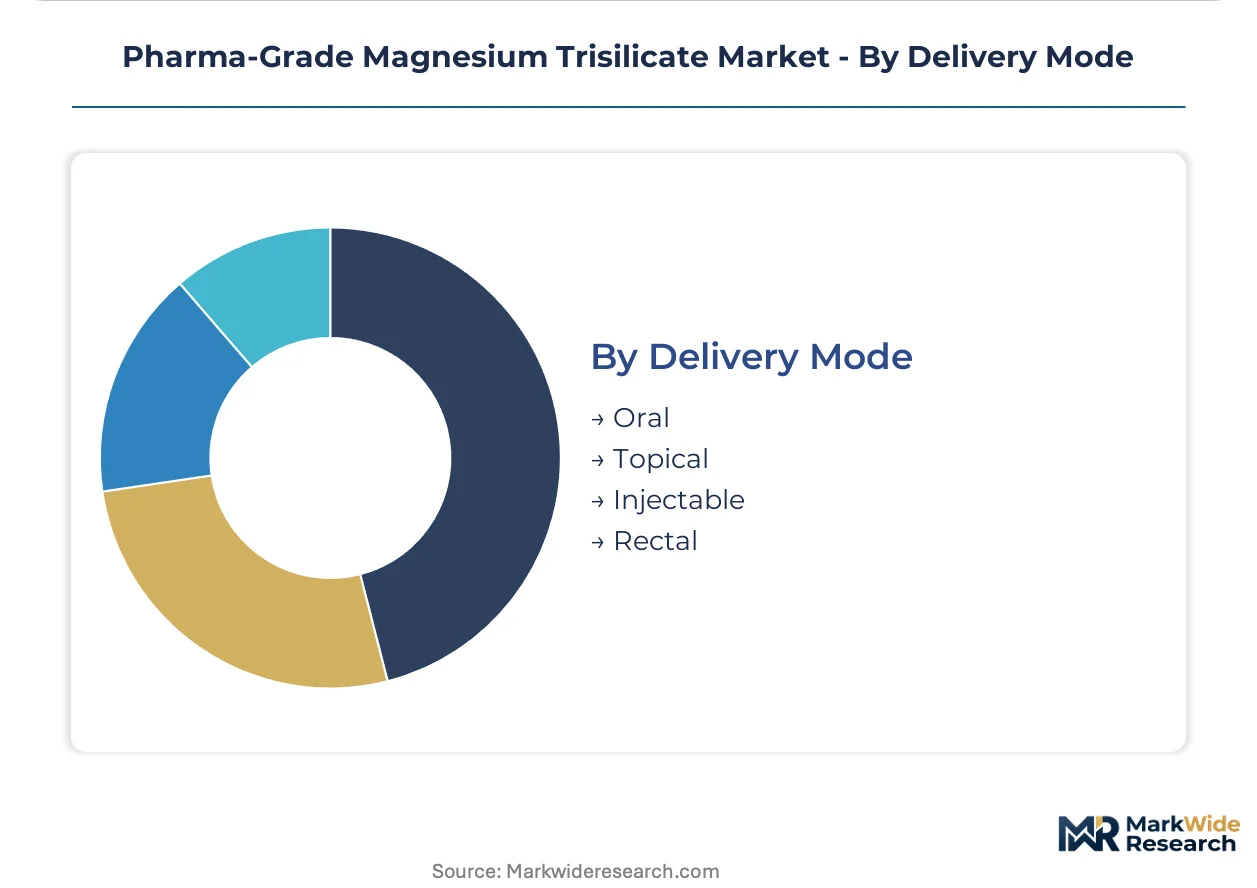
Delivery Mode:
Route of administration dictates particle engineering specifications and sterilization validation burdens.
- Oral:Tablet and suspension formulations constitute virtually all commercial volume. FDA Current Good Manufacturing Practice enforcement elevates precipitation process documentation requirements.
- Topical:Dermatological compounding applications remain niche due to silicate particulate irritation concerns.
- Injectable:Parenteral-grade specifications with endotoxin limits are commercially negligible for magnesium trisilicate.
- Rectal:Suppository base applications compete with cocoa butter and polyethylene glycol alternatives on cost.
Oral delivery commands absolute volume dominance; topical applications show marginal clinical trial activity without commercial scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's pharmaceutical manufacturing belt outpaces German output in antacid excipient volumes, while the United States maintains stricter pharmacopeial enforcement that elevates supplier qualification barriers.
United States
Hospital group purchasing organizations consolidate excipient sourcing onto digital platforms, demanding electronic excipient information package submissions. FDA Current Good Manufacturing Practice enforcement elevates precipitation process documentation requirements for antacid formulation suppliers. The Northeast corridor anchors procurement sophistication, with Boston and New York health systems driving qualification standards.
Germany
REACH registration requirements for silicate compounds compel full toxicological dossier submissions from domestic manufacturers. German antacid producers consolidate supplier bases toward REACH-registered domestic sources with established safety data packages. The Rhine-Ruhr industrial cluster hosts specialized excipient processors serving European formulation houses.
India
CDSCO alignment with ICH Q3D elemental impurity guidelines reshapes domestic manufacturer certification requirements for API-to-formulation integrators. The Mumbai-Pune pharmaceutical belt deepens backward integration into magnesium trisilicate production, displacing technical-grade imports. Gujarat's chemical processing corridor expands compendial-grade precipitation capacity for export-oriented antacid manufacturing.
Japan
PMDA pharmacopeial harmonization with USP-NF and EP monographs compresses supplier qualification timelines for domestic excipient distributors. METI industrial standards guide continuous manufacturing adaptations in silicate processing. The Osaka-Kobe pharmaceutical cluster sustains demand for premium powder grades in compounding pharmacy channels.
China
Magnesium ore concentration in domestic mining districts exposes non-integrated European and Indian formulators to input cost volatility. NMPA excipient master file pathways enable qualified suppliers to secure long-term formulation partnerships without repeated facility audits. The Shandong chemical processing region supplies raw material feedstock to global precipitation facilities.
Pharma-Grade Magnesium Trisilicate Market Competitive Landscape
Top-tier vendors anchor European and Japanese pharmacopeial-grade supply, while mid-tier Indian and Chinese manufacturers compete on volume scale and cost positioning. The vendor base stratifies across three tiers: integrated pharmaceutical conglomerates with in-house excipient divisions, specialized silicate processors with compendial certifications, and regional chemical houses serving technical-grade demand. Two dominant competitive moves reshape positioning: continuous manufacturing investments that compress certification cycles, and backward integration into magnesium ore sourcing that insulates margin from raw material volatility.
Among European-based suppliers, Merck KGaA exemplifies the premium-tier archetype through its established compendial-grade positioning. Japanese specialists occupy the quality-certification vector, with Tomita Pharmaceutical Co. Ltd. representing disciplined pharmacopeial alignment. At the volume-driven end, Par Drugs and Chemicals Pvt. Ltd. anchors Indian domestic formulation supply, competing on scale within the country's deepening API-to-formulation integration.
| Leading Market Players |
|---|
| Merck KGaA |
| Tomita Pharmaceutical Co. Ltd. |
| Par Drugs and Chemicals Pvt. Ltd. |
| Osian Marine Chemicals Pvt. Ltd. |
| Meha Chemicals |
| Jai Radhe Sales |
| Taurus Chemicals |
| Priti Industries |
| Kyowa Chemical |
| Others |
Value Network & Pricing Analysis
Hospital group purchasing organizations concentrate procurement authority across United States health systems, forcing contract-based long-term offtake agreements that lock in volume commitments against raw material volatility. This buyer concentration compresses margin for non-integrated suppliers while rewarding REACH-registered European manufacturers with validated heavy metal controls.
Pricing Analysis
Compendial-grade supply bundles precipitation process documentation with lot-specific certificates of analysis, while technical-grade alternatives trade unbundled on spot markets. Three-tier pricing structure across compendial-certified, pharmacopeial-standard, and technical-economy levels separates suppliers by ICP-MS verification capability and excipient master file status. Cost compression in standard-tier supply intensifies as Indian API-to-formulation integrators displace legacy imports. Retail pharmacy channels exhibit highest price sensitivity, whereas hospital formulary procurement prioritizes certification compliance over unit economics.
Supply Chain Analysis
Freight cost exposure from magnesium ore concentration in Chinese mining districts elevates landed costs for European and Indian precipitation facilities. Supply draws from China for raw material feedstock, India for compendial-grade processing, and Germany for REACH-registered specialty grades. Dependencies center on magnesium ore purity, thermal processing energy inputs, and ICP-MS analytical chemistry capacity. Single-source vulnerability concentrates in Shandong chemical processing corridors. Distribution runs through specialized excipient distributors serving hospital GPOs and compounding pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pharma-grade magnesium trisilicate market reads as a late-cycle quality story, with ICH Q3D alignment in India and tightening EP heavy metal thresholds driving demand-shift toward certified compendial specifications.
For Market Incumbents: Hedge against aluminum hydroxide substitution in over-the-counter retail by deepening backward integration into magnesium ore sourcing. Secure excipient master file pathways with FDA to compress repeated facility audit burdens. Prioritize continuous precipitation investments that reduce batch-to-batch variability and defend hospital formulary positioning against automated European competitors. For New Entrants and Emerging Players: Launch via direct-to-consumer dietary supplement channels in North American retail, where USP-grade powder demand expands outside traditional antacid applications. Target compounding pharmacy white space with fine-milled grades validated for electronic excipient information package submission. Exploit certification gaps among mid-tier Indian technical-grade suppliers displaced by CDSCO enforcement. For Investors and Strategic Acquirers: Pharmaceutical conglomerates with in-house excipient divisions are the most active acquirer in this space, consolidating specialized silicate processors to secure captive API-to-formulation integration. Five-to-ten year viability favors REACH-registered European assets with established toxicological dossiers over import-reliant formulation houses. Monitor pharmacopeial harmonization timelines between USP-NF, EP, and JP as inflection signal for redundant stability study burdens and qualification documentation costs.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Transition | European specialists deploy real-time particle size feedback to compress USP-NF certification cycles. |
| Backward Integration into Ore Sourcing | Indian API-to-formulation integrators displace technical-grade imports through captive magnesium supply. |
| Excipient Master File Submission | Qualified suppliers secure long-term hospital GPO partnerships without repeated FDA facility audits. |
| REACH Registration Compliance | German and French antacid producers consolidate toward domestic sources with established safety data. |
| Dietary Supplement Repositioning | Direct-to-consumer magnesium positioning in North American retail expands compounding pharmacy demand. |
Research Methodology
Direct dialogue with excipient procurement managers, quality control directors, pharmaceutical formulation scientists, and hospital GPO contracts specialists grounded qualitative findings in operational reality. Secondary validation drew from FDA Current Good Manufacturing Practice enforcement records, European Pharmacopoeia monograph revision cycles, CDSCO ICH Q3D alignment notifications, and SEC filings of integrated pharmaceutical conglomerates. Bottom-up volume estimates from precipitation facility capacity and top-down demand triangulation from antacid formulation production reconciled through cross-segment consistency checks.
Bottom-up modeling tracked tablet, powder, granule, and suspension grade volumes across antacid, anti-ulcer, and dietary supplement applications, while top-down analysis anchored total market scale to hospital formulary procurement databases and retail pharmacy channel audits. CAGRs derived from segment-level growth rate reconciliation across dosage form, clinical indication, and regional regulatory cluster dimensions. Forecast inputs incorporated pharmacopeial harmonization timelines, continuous manufacturing adoption curves, and elemental impurity guideline enforcement intensity.
Several conditions sit outside the modeled scope, including parenteral-grade specification development, topical dermatological compounding scale-up, and suppository base substitution dynamics. Forecasts reflect documented assumptions about ICH Q3D implementation pace, ore concentration stability in Chinese mining districts, and aluminum hydroxide reformulation velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Global Glycine Supplement Market
Pharmaceutical Ingredients
Encapsulated Salicylic Acid Market
Pharmaceutical Ingredients
Immunosuppressants Market
Pharmaceutical Ingredients
Pharmaceutical Grade Hyaluronic Acid Market
Pharmaceutical Ingredients
Calcium Folinate for Injection Market
Pharmaceutical Ingredients
India Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Growth Hormone Inhibiting Hormone Drugs Market
Pharmaceutical Ingredients
Global Pharmaceutical Grade Sodium Chloride Market
Pharmaceutical Ingredients
Saudi Arabia Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Biologic Excipients Market
Pharmaceutical Ingredients
Sterile Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Ferrous Succinate Market
Pharmaceutical Ingredients
Global Fibrate Drugs Market
Pharmaceutical Ingredients
Sulphonamides Market
Pharmaceutical Ingredients
Moxifloxacin Hcl (CAS 186826-86-8) Market
Pharmaceutical Ingredients
Pemetrexed Market