
 Montelukast API Market | 2026-2036
Montelukast API Market Size, Share, and Industry Trends Forecast 2026-2036
Montelukast API Market Outlook
Market Context
Pharmacopeial-grade purity specifications above 99.5% is collapsing the supplier base toward integrated manufacturers with in-house crystallization and micronization capabilities. Cipla leverages backward integration into API production to secure cost advantages in respiratory portfolios. Merck sustains premium positioning through proprietary polymorph control and documented stability data. Aurobindo Pharma competes aggressively on volume scale, occupying substantial share in European generic tender markets.
Technical Definition and Segment Structure
Montelukast API is the active pharmaceutical ingredient comprising the sodium salt of montelukast, a selective leukotriene receptor antagonist synthesized through multi-step chiral catalysis and typically specified at minimum 99.0% purity with tight control on individual impurity limits; it serves as the foundational input for formulations targeting chronic asthma prophylaxis and allergic rhinitis management. Tablet formulations dominate value capture given their manufacturing simplicity and patient compliance advantages, while oral granules represent the fastest-expanding pediatric delivery segment as prescribers seek age-appropriate alternatives. Retail pharmacy distribution channels concentrate margin pools through direct-to-patient dispensing, whereas hospital procurement networks drive volume concentration via centralized tender mechanisms.
Regulatory Environment and Outlook
FDA enforcement of ICH Q3D elemental impurity guidelines and EMA implementation of revised nitrosamine risk assessment protocols are elevating analytical burden and documentation requirements for Montelukast API suppliers. CDSCO in India mandates periodic renewal of manufacturing licenses with updated facility inspection records, tightening market access for smaller unregistered producers. WHO prequalification standards increasingly influence procurement decisions by international health organizations and emerging market governments. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and IP standards to anticipate specification drift and qualification timeline compression.
Market Dynamics
Pharmacopeial-grade purity requirements above 99.5% are collapsing the supplier base toward integrated manufacturers with in-house crystallization and micronization capabilities, reshaping competitive economics across respiratory API supply chains.
Growth Catalysts
- ICH Q3D Elemental Impurity Guidelines:FDA enforcement of these standards elevates analytical documentation requirements, disqualifying smaller producers and consolidating procurement toward qualified suppliers with validated testing protocols.
- Pediatric Oral Granule Formulations:Age-appropriate delivery formats for allergic rhinitis management are expanding prescription volumes as prescribers seek alternatives to tablet administration for young patients.
- India and China Production Scale:Generic pharmaceutical manufacturers in these manufacturing clusters are expanding fermentation and chiral catalysis capacity to serve rising hospital procurement volumes.
Market Restraints
- Chiral Catalysis Input Costs:Specialized catalyst metals and enantioselective reagents expose margins to commodity volatility, compressing returns for non-integrated producers lacking captive synthesis capabilities.
- Nitrosamine Risk Assessment Protocols:EMA implementation of revised contamination evaluation frameworks extends qualification timelines and elevates analytical burden for European market access.
- Oral Tablet Substitution Pressure:Fixed-dose combination therapies combining inhaled corticosteroids with long-acting beta-agonists are displacing leukotriene receptor antagonists in severe asthma maintenance protocols.
Strategic Opportunities
- WHO Prequalification Standards:International health organization procurement criteria are opening tender access for documented stability data holders across emerging market government purchasing networks.
- Continuous Flow Chemistry Adoption:Convergence of microreactor technology with process analytical technology enables real-time impurity control and batch size flexibility for contract manufacturing organizations.
- Southeast Asia Hospital Procurement Expansion:Centralized tender mechanisms in Vietnam, Indonesia, and Philippines are concentrating volume pools for qualified API suppliers with established pharmacopeial dossiers.
Industry Challenges
- Polymorph Control Expertise Scarcity:Documented stability data for specific crystal forms requires specialized analytical chemists, constraining expansion timelines for manufacturers lacking in-house solid-state characterization capabilities.
- CDSCO License Renewal Compression:India's mandatory periodic facility inspection record updates tighten compliance timelines, creating bottlenecks for producers with outdated quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Montelukast API Market |
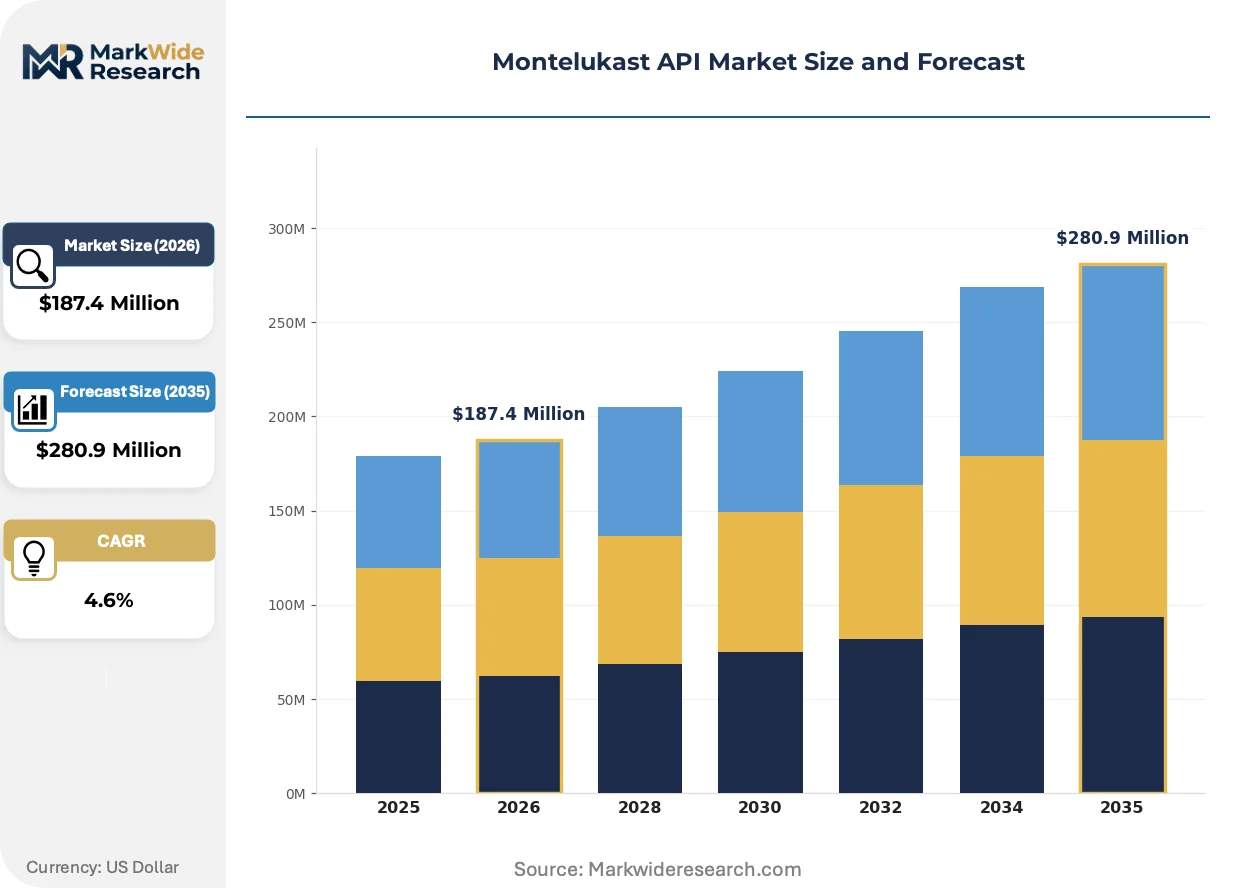
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Oral Granules, Inhalation, Others End User: Hospitals, Clinics, Retail Pharmacies, Online Pharmacies Distribution Channel: Direct Sales, Wholesalers, Distributors, E-commerce Therapy Area: Allergy, Asthma, Chronic Obstructive Pulmonary Disease, Bronchial Disorders |
| Companies Covered | Cipla, Morepen Laboratories, Merck, Aurobindo Pharma, Laurus Labs, Dr. Reddy's Laboratories, Sun Pharmaceuticals Industries, Viatris, Teva Pharmaceutical Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Montelukast API Market Strategic Shifts
Continuous manufacturing platforms and real-time release testing are displacing traditional batch processing in Montelukast API synthesis, while regulatory harmonization pressures force simultaneous compliance with multiple pharmacopeial standards.
Continuous flow microreactor technology is fragmenting traditional batch reactor economics in chiral catalysis steps. Mid-scale API producers in India are adopting these systems to reduce solvent volumes and improve heat transfer control. The technology is fragmenting capital requirements, enabling smaller entrants to achieve pharmacopeial-grade purity without stainless-steel reactor farm investments.
EMA revised nitrosamine risk assessment protocols now mandate comprehensive contamination evaluation across all synthetic routes. This regulatory expansion forces manufacturers to revalidate legacy processes or abandon older production lines. European generic tender markets are responding with extended supplier qualification timelines and heightened documentation demands.
Hospital procurement networks are consolidating volume through centralized tender mechanisms, displacing fragmented distributor purchasing. This concentration shifts margin capture toward direct manufacturer relationships and away from wholesale intermediaries. The pattern is most visible in North American integrated delivery networks and European hospital purchasing alliances.
Montelukast API Market Segmentation
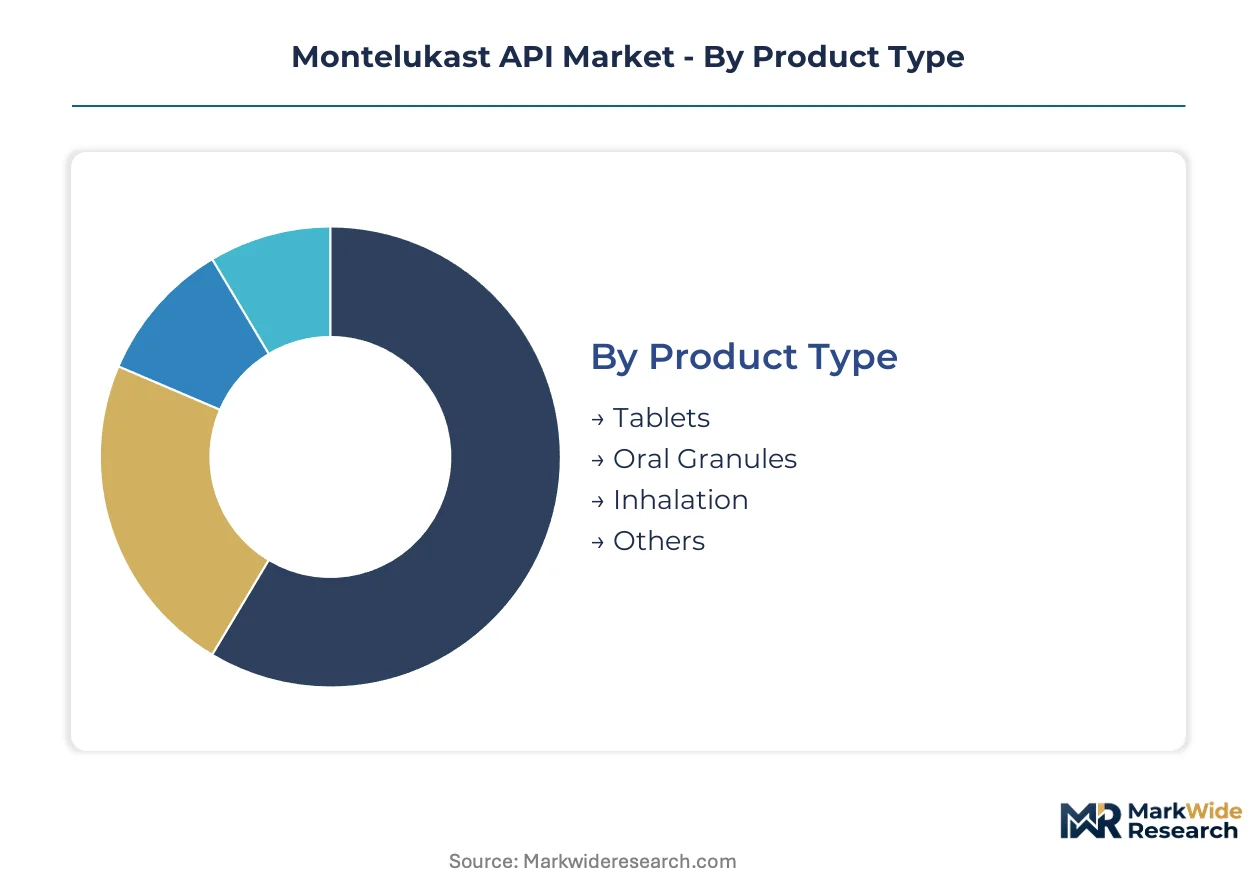
Pharmacopeial-grade purity requirements fragment Montelukast API demand across distinct formulation and delivery specifications. Regulatory differentiation in each segment dictates supplier qualification protocols and margin structures.
Product Type:
FDA bioequivalence standards and EMA stability data requirements create divergent qualification burdens across oral and respiratory delivery formats.
- Tablets:Compressed solid dosage forms specified at 99.5% purity with tight weight uniformity controls dominate hospital procurement tenders in the United States and Germany. Manufacturers with in-house micronization capabilities capture margin through direct relationships with integrated delivery networks.
- Oral Granules:Sachet-based pediatric formulations dissolve in soft food or liquids, expanding prescription volumes as French and Italian prescribers seek age-appropriate alternatives. EMA pediatric investigation plan compliance elevates documentation requirements for suppliers targeting European tender markets.
- Inhalation:Dry powder and nebulized formats require particle size distribution control below 5 microns for pulmonary deposition.
- Others:Chewable tablets and film-coated variants serve niche compliance needs in Japan and South Korea.
Established volume favors tablets; emerging adoption favors oral granules.
End User:
Procurement concentration patterns concentrate margin capture toward direct manufacturer relationships and away from fragmented distributor channels.
- Hospitals:Centralized purchasing alliances in the United States, France, and Germany consolidate volume through multi-year tender contracts with documented stability data requirements. GPO-negotiated pricing compresses returns for non-qualified suppliers lacking WHO prequalification dossiers.
- Clinics:Outpatient respiratory specialists in India and Brazil drive prescription volumes for maintenance therapy protocols. CDSCO and ANVISA facility inspection records determine supplier access to these decentralized procurement networks.
- Retail Pharmacies:Direct-to-patient dispensing captures premium pricing in markets with limited generic penetration.
- Online Pharmacies:Digital distribution platforms expand reach in markets with underdeveloped wholesale infrastructure.
Hospital procurement commands volume concentration; clinic networks represent the steepest expansion trajectory.
Distribution Channel:
Channel economics reflect working capital requirements and documentation burdens that favor integrated manufacturers over trading intermediaries.
- Direct Sales:Manufacturer-to-formulator relationships eliminate distributor margins for large-volume tablet producers with validated supply agreements. Cipla and Aurobindo leverage captive API production to secure preferred supplier status with North American and European generic finished dose manufacturers.
- Wholesalers:Regional pharmaceutical distributors aggregate fragmented demand from mid-tier formulators lacking direct sourcing capabilities. Inventory carrying costs and credit terms constrain participation to well-capitalized trading houses in Mumbai, Hyderabad, and Shanghai.
- Distributors:Specialized API traders maintain pharmacopeial dossier libraries for rapid customer qualification.
- E-commerce:B2B platforms reduce search costs for small-volume buyers in emerging markets.
Direct sales anchor value capture; e-commerce channels are expanding most quickly in procurement digitization.
Therapy Area:
Clinical guideline revisions and combination therapy protocols reshape addressable patient populations across respiratory indications.
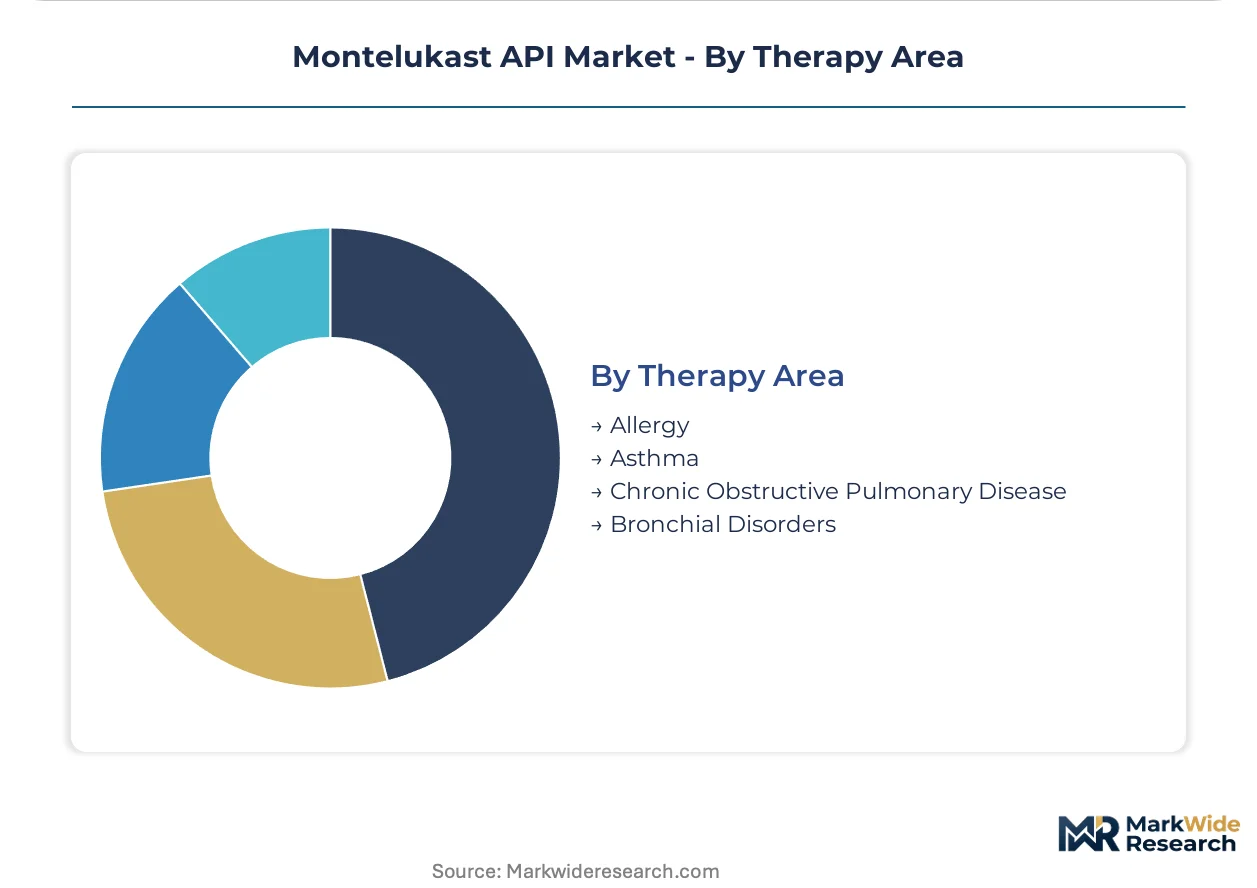
- Allergy:Seasonal and perennial allergic rhinitis management drives year-round prescription demand in temperate climate zones. Japanese and South Korean formulators prioritize oral granule development for pediatric allergy indications.
- Asthma:Chronic prophylaxis represents the foundational indication with established reimbursement pathways across Medicare, NHS, and statutory health insurance systems. Fixed-dose combination displacement pressure from inhaled corticosteroid-long-acting beta-agonist therapies constrains volume growth in severe asthma segments.
- Chronic Obstructive Pulmonary Disease:Maintenance therapy protocols in smoking-prevalent populations expand addressable demand.
- Bronchial Disorders:Exercise-induced bronchospasm and cough-variant indications serve niche prescriber segments.
Asthma maintenance commands established volume; allergy management gains share fastest through pediatric formulation expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated manufacturers with captive crystallization capabilities cluster in specific geographies where regulatory infrastructure and fermentation capacity converge. Hospital procurement networks in mature markets and government tender systems in emerging economies drive divergent qualification requirements across national boundaries.
United States
FDA enforcement of ICH Q3D elemental impurity guidelines elevates analytical documentation burdens for API suppliers seeking access to Medicare-reimbursed formulations. Integrated delivery networks in the Northeast and Midwest consolidate purchasing through group purchasing organizations with multi-year stability data requirements. New Jersey and Massachusetts host formulation science clusters where backward integration into API production secures preferred supplier status.
Germany
EMA nitrosamine risk assessment protocols extend qualification timelines for suppliers targeting statutory health insurance procurement channels. Bavaria and Baden-Württemberg concentrate respiratory API formulation expertise with documented polymorph control capabilities. Hospital purchasing alliances in North Rhine-Westphalia drive volume concentration toward qualified suppliers with established pharmacopeial dossiers.
India
CDSCO license renewal mandates with updated facility inspection records tighten compliance timelines for Hyderabad and Mumbai manufacturing clusters. Maharashtra and Gujarat dominate chiral catalysis capacity expansion serving European and North American generic tender markets. Periodic renewal requirements compress market access for producers with outdated quality management systems.
China
NMPA implementation of revised impurity profiling standards aligns domestic manufacturers with ICH Q3A and Q3B guidelines for export-oriented production. Zhejiang and Jiangsu provinces scale fermentation capacity for leukotriene receptor antagonist intermediates. The country's national pharmaceutical regulator harmonizes pharmacopeial standards with USP and EP specifications for international market access.
Japan
PMDA stability data requirements for pediatric oral granule formulations create specialized documentation burdens for suppliers targeting Japanese tender markets. Osaka and Tokyo metropolitan areas concentrate respiratory portfolio managers seeking age-appropriate delivery alternatives. METI industrial policy supports domestic API production for critical therapeutic categories including asthma maintenance therapy.
Montelukast API Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Montelukast API supply base. Integrated manufacturers with in-house crystallization capabilities command premium positioning through documented polymorph control, while volume-scale producers compete on fermentation throughput and chiral catalysis efficiency. Three archetypes dominate: backward-integrated pharmaceutical conglomerates, specialized API contract manufacturers, and research-driven innovators with proprietary process chemistry. Consolidation proceeds through strategic partnerships for geographic market access and capacity expansion in high-volume generic tender markets.
Among Indian pharmaceutical conglomerates with captive API production, Cipla and Aurobindo Pharma exemplify the backward-integrated archetype securing cost advantages in respiratory portfolios. Dr. Reddy's Laboratories occupies a position within the contract manufacturing tier serving North American and European formulators with established pharmacopeial dossiers. These three anchors represent divergent strategic postures across the cost-technology spectrum.
| Leading Market Players |
|---|
| Cipla |
| Morepen Laboratories |
| Merck |
| Aurobindo Pharma |
| Laurus Labs |
| Dr. Reddy's Laboratories |
| Sun Pharmaceuticals Industries |
| Viatris |
| Teva Pharmaceutical Industries |
| Others |
Value Chain & Pricing Dynamics
Fixed-dose combination therapies displacing leukotriene receptor antagonists in severe asthma maintenance simultaneously compress API demand geography toward pediatric and allergy segments while intensifying price competition among qualified suppliers. This substitution dynamic concentrates procurement power in hospital purchasing alliances and generic tender networks.
Pricing Analysis
ICH Q3D elemental impurity guidelines dictate the pricing tier structure across Montelukast API supply. Three-tier pricing separates pharmacopeial-grade certified suppliers from standard-grade producers and uncertified traders. Price differentiation rests on documented polymorph control capabilities and WHO prequalification status. Pricing pressure stems from chiral catalysis input cost volatility, with volume-scale hospital procurement networks exhibiting highest price sensitivity and specialty pediatric formulators showing lowest.
Supply Chain Analysis
Strategic stockpiling of enantioselective reagents and catalyst metals dominates inventory strategy over just-in-time approaches given supply discontinuity risks. Manufacturing concentrates in India, China, and the United States. Raw material dependencies include specialized chiral ligands, sodium hydroxide for salt formation, and organic solvents for crystallization. Single-source vulnerability in catalyst metal supply creates structural exposure. Distribution runs through direct manufacturer-to-formulator relationships for large-volume tablet producers and regional pharmaceutical distributors for fragmented demand aggregation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against fixed-dose inhaled corticosteroid-long-acting beta-agonist combinations that constrain leukotriene antagonist growth in severe asthma segments.
For Market Incumbents: Compound backward integration into chiral catalysis to secure captive supply of enantioselective reagents and insulate margins from commodity volatility. Deepen polymorph control expertise through specialized analytical chemist recruitment to defend against emerging entrants lacking solid-state characterization capabilities. Prioritize WHO prequalification dossier maintenance to preserve access to emerging market government tenders. For New Entrants and Emerging Players: Differentiate on continuous flow microreactor technology adoption to achieve pharmacopeial-grade purity without capital-intensive stainless-steel reactor investments. Target Southeast Asia hospital procurement expansion in Vietnam, Indonesia, and Philippines where centralized tender mechanisms concentrate volume for qualified suppliers with established pharmacopeial dossiers. Pursue contract manufacturing organization partnerships with mid-tier formulators lacking direct API sourcing capabilities. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated manufacturers with documented stability data and in-house crystallization capabilities. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than pure fermentation scale. Monitor CDSCO license renewal compression rates as an inflection indicator for supplier base attrition and acquisition opportunity timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chiral Catalysis | Cipla and Aurobindo secure cost advantages through captive enantioselective reagent production. |
| WHO Prequalification Dossier Investment | Documented stability data holders unlock emerging market government tender access. |
| Continuous Flow Chemistry Adoption | Microreactor technology enables real-time impurity control for mid-scale API producers. |
| Polymorph Control Expertise Development | Specialized solid-state characterization capabilities constrain expansion timelines for competitors. |
| Pediatric Oral Granule Formulation Partnership | Age-appropriate delivery formats expand prescription volumes in French and Italian markets. |
Study Parameters
A standing panel of regulatory affairs leads, hospital procurement managers, API manufacturing directors, and generic formulator executives provided ongoing calibration throughout the research process. Primary interviews with these stakeholders combined with secondary validation against FDA filings, EMA submissions, CDSCO manufacturing license records, and WHO prequalification databases. Bottom-up volume estimates from individual supplier capacities triangulated against top-down demand projections from hospital tender aggregation and prescription volume trends.
Consistency checks validated outputs against external benchmarks including pharmacopeial harmonization timelines and regulatory enforcement patterns across the analysis window. The analytical framework modeled segmentation dimensions spanning dosage form, end-user procurement channel, therapy area indication, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to baseline volume data, incorporating inputs from chiral catalysis capacity expansion announcements and pediatric formulation pipeline developments.
The analysis sits within stated boundaries; outcomes outside sustained ICH guideline enforcement or stable chiral catalyst metal supply would require recalibration. Forecasts reflect assumptions regarding continued pharmacopeial-grade purity requirements above 99.5% and periodic license renewal compliance. Revision becomes warranted when fixed-dose combination therapy substitution rates or nitrosamine risk assessment protocol stringency cross thresholds that materially alter supplier qualification economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Transdermal Drugs Market
Pharmaceutical Ingredients
Oral Transmucosal Drugs Market
Pharmaceutical Ingredients
Global Dexamethasone Market
Pharmaceutical Ingredients
Histamine H2-Receptor Antagonists Market
Pharmaceutical Ingredients
United Kingdom Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
United States Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Pharmaceutical Suspension Market
Pharmaceutical Ingredients
Fipronil Market
Pharmaceutical Ingredients
Chlorzoxazone Market
Pharmaceutical Ingredients
Antibiotics API Market
Pharmaceutical Ingredients
Fixed-Dose Combination Drugs Market
Pharmaceutical Ingredients
Pharmaceutical Chemicals Market
Pharmaceutical Ingredients
Pharmaceutical Thermal Analysis Market
Pharmaceutical Ingredients
Global Ibuprofen Market
Pharmaceutical Ingredients
Originator Small Molecule Drug Market
Pharmaceutical Ingredients
Global Granisetron Market