
 Organic Rheological Modifiers Market | 2026-2036
Organic Rheological Modifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Rheological Modifiers Market Outlook
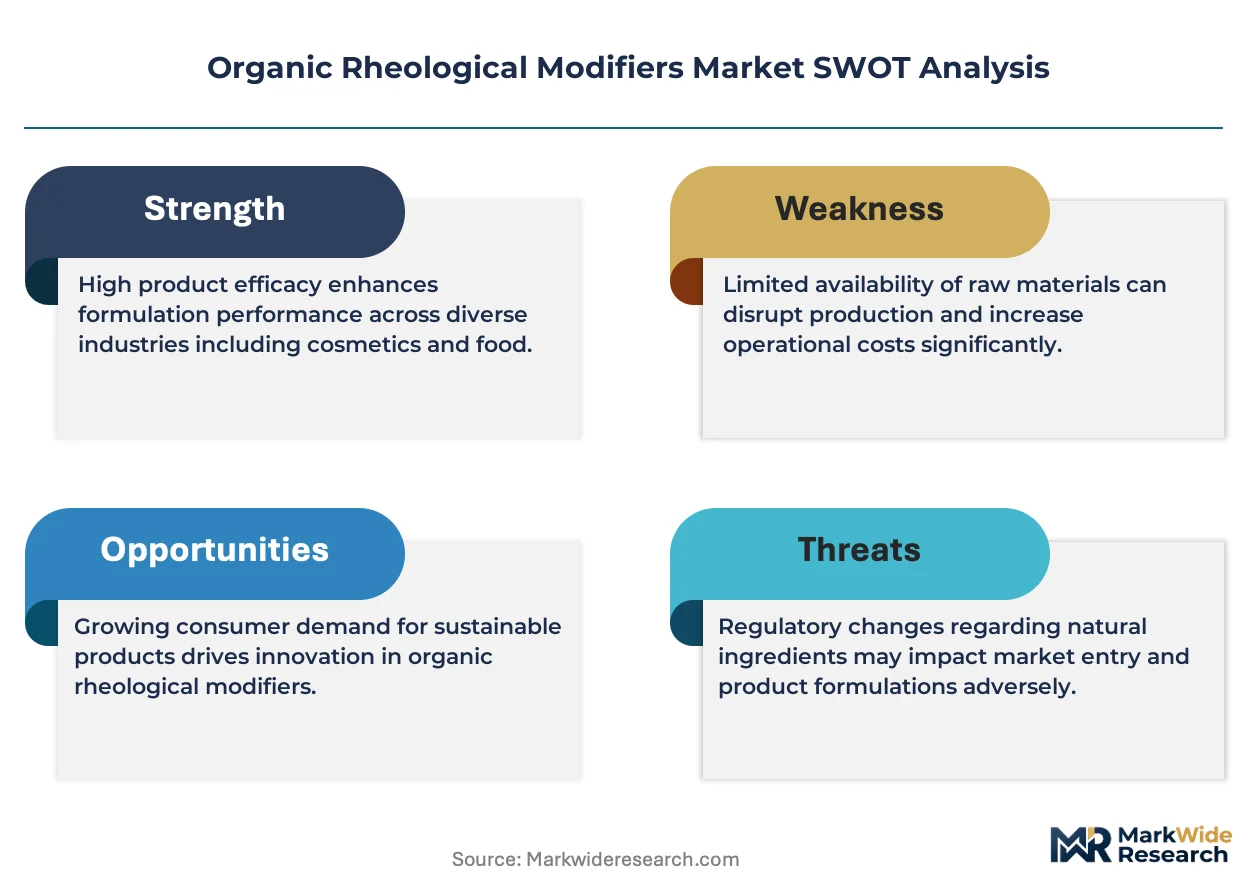
The widening gap between premium bio-based rheological modifiers and commodity-grade cellulosic derivatives is repositioning supplier economics across the value chain. BASF SE leverages its integrated polyurethane modifier platform to sustain pricing power in European coatings. Dow anchors North American supply through manufacturing scale in cellulosic thickeners for construction and industrial applications. Arkema competes via specialized acrylic associative thickeners targeting high-shear stability in waterborne automotive coatings.
Organic rheological modifiers comprise macromolecular additives—typically cellulosic ethers, starch derivatives, polyurethane associative polymers, or natural gums such as xanthan and guar—that increase viscosity, stabilize suspensions, or control flow behavior in liquid and semi-solid formulations. These additives function by forming entangled networks in solution or adsorbing onto particle interfaces, with critical performance parameters including yield stress, thixotropic recovery rate, and compatibility with solvent-borne versus waterborne resin systems. Cellulosic derivatives occupy the largest volume position due to decades of formulation familiarity and cost efficiency across construction and personal care. Polyurethane modifiers command premium positioning in high-performance coatings where sag resistance and leveling must coexist. Natural gums represent the fastest-expanding category as clean-label mandates in food and personal care accelerate substitution of synthetic thickeners.
REACH registration requirements under ECHA constrain raw material sourcing for European producers, while China's GB standards on architectural coatings limit formaldehyde and VOC content, directly shaping modifier selection in domestic manufacturing. FDA food additive regulations and USP compliance standards for pharmaceutical excipients create dual qualification burdens for suppliers serving multiple end-use industries. Stakeholders must monitor evolving bio-based certification schemes and carbon accounting rules, as these will increasingly determine market access and contract eligibility across major consuming regions.
Market Dynamics
Waterborne coating reformulation is forcing additive suppliers to reengineer rheological packages for higher loading efficiency, as automotive OEMs and refinish shops migrate from solvent-borne systems to meet tightening VOC limits.
Growth Catalysts
- REACH registration requirements:ECHA mandates are accelerating substitution of legacy thickeners with compliant bio-based alternatives in German and French coatings manufacturing.
- Automotive refinish sector:China's MEE standards on architectural and industrial coatings are driving modifier purchases from domestic waterborne formulation plants.
- Cellulosic ether technology:Construction-grade thickeners are capturing volume in Southeast Asian infrastructure projects requiring cement compatibility and sag resistance.
Market Restraints
- Raw material volatility:Purified cotton linter and wood pulp supply disruptions in Brazil and Indonesia are compressing margins for cellulosic derivative producers.
- Polyurethane modifier concentration:European supply depends on a narrow base of integrated chemical producers with captive isocyanate access.
- Natural gum performance ceiling:Xanthan and guar derivatives face shear stability limitations in high-speed automotive spray applications, constraining clean-label substitution rates.
Strategic Opportunities
- India's architectural coatings sector:BIS certification requirements and urban infrastructure investment are creating entry points for associative polyurethane thickeners in premium decorative paints.
- Personal care clean-label mandate:FDA and EU EFSA scrutiny of synthetic polymers is expanding addressable market for fermentation-derived polysaccharide thickeners in skincare formulations.
- Carbon accounting integration:EU Green Deal and emerging corporate sustainability reporting obligations are positioning bio-based modifiers for contract eligibility in multinational procurement.
Industry Challenges
- Formulation chemist scarcity:Waterborne rheology optimization requires specialized expertise in associative polymer behavior that outpaces current technical training pipelines.
- Multi-jurisdiction qualification burden:Suppliers serving coatings, food, and pharmaceutical verticals must maintain parallel FDA, USP, and REACH dossiers, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Rheological Modifiers Market |
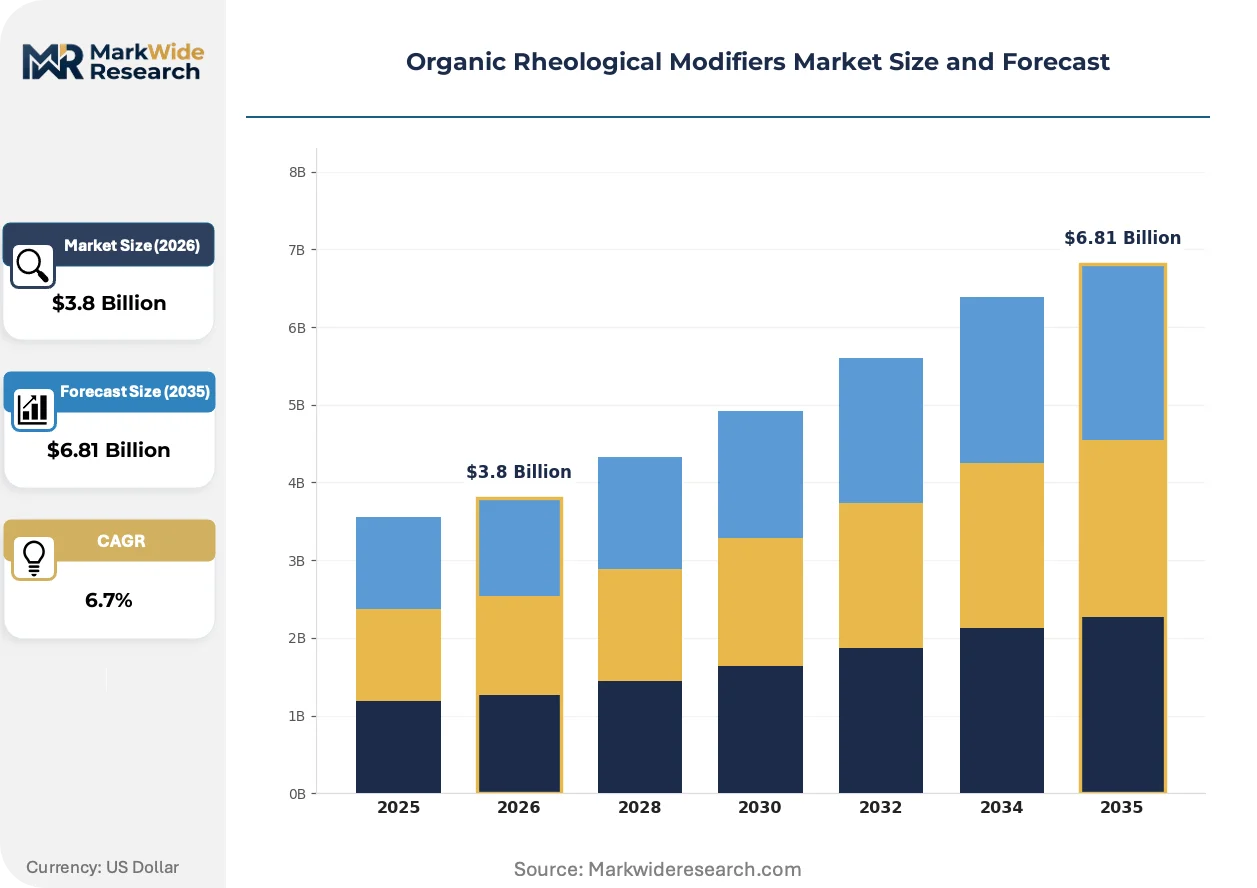
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellulosic Derivatives, Starch-based Modifiers, Polyurethane Modifiers, Natural Gums End Use Industry: Food & Beverage, Pharmaceuticals, Personal Care, Coatings Functionality: Thickening Agent, Stabilizer, Dispersing Agent, Emulsifier Form: Powder, Liquid, Granular, Paste |
| Companies Covered | BASF SE, Dow, Ashland Inc., Clariant, Lubrizol Corporation, Arkema, Croda International, Evonik Industries, AkzoNobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Rheological Modifiers Market Strategic Shifts
Modifier suppliers are converging on hybrid architectures that combine the cost position of cellulosics with the performance profile of associative polymers, reshaping R&D allocation across the competitive set.
Polyurethane associative thickeners are expanding into automotive clearcoat and basecoat layers where sag resistance must coexist with atomization efficiency. Tier-1 coatings suppliers in Germany and Japan are qualifying these systems for robotic spray lines. The technology is expanding into segments previously dominated by high-molecular-weight cellulosics, compressing the premium-mid-market price gap.
China's GB standards on architectural coatings and the country's dual carbon goals are accelerating waterborne formulation mandates across industrial and decorative segments. Domestic modifier producers are reconfiguring product portfolios to eliminate formaldehyde-releasing chemistries. The regulatory pressure is most acute in East China's manufacturing clusters, where provincial MEE enforcement has tightened ahead of national timelines.
Buyers in automotive OEM coatings are consolidating modifier specifications to reduce qualification overhead, favoring suppliers with multi-regional regulatory dossiers. This concentration is displacing smaller regional compounders from approved vendor lists. The pattern is most visible in North American and European automotive supply chains, where platform globalization drives specification harmonization.
Organic Rheological Modifiers Market Segmentation
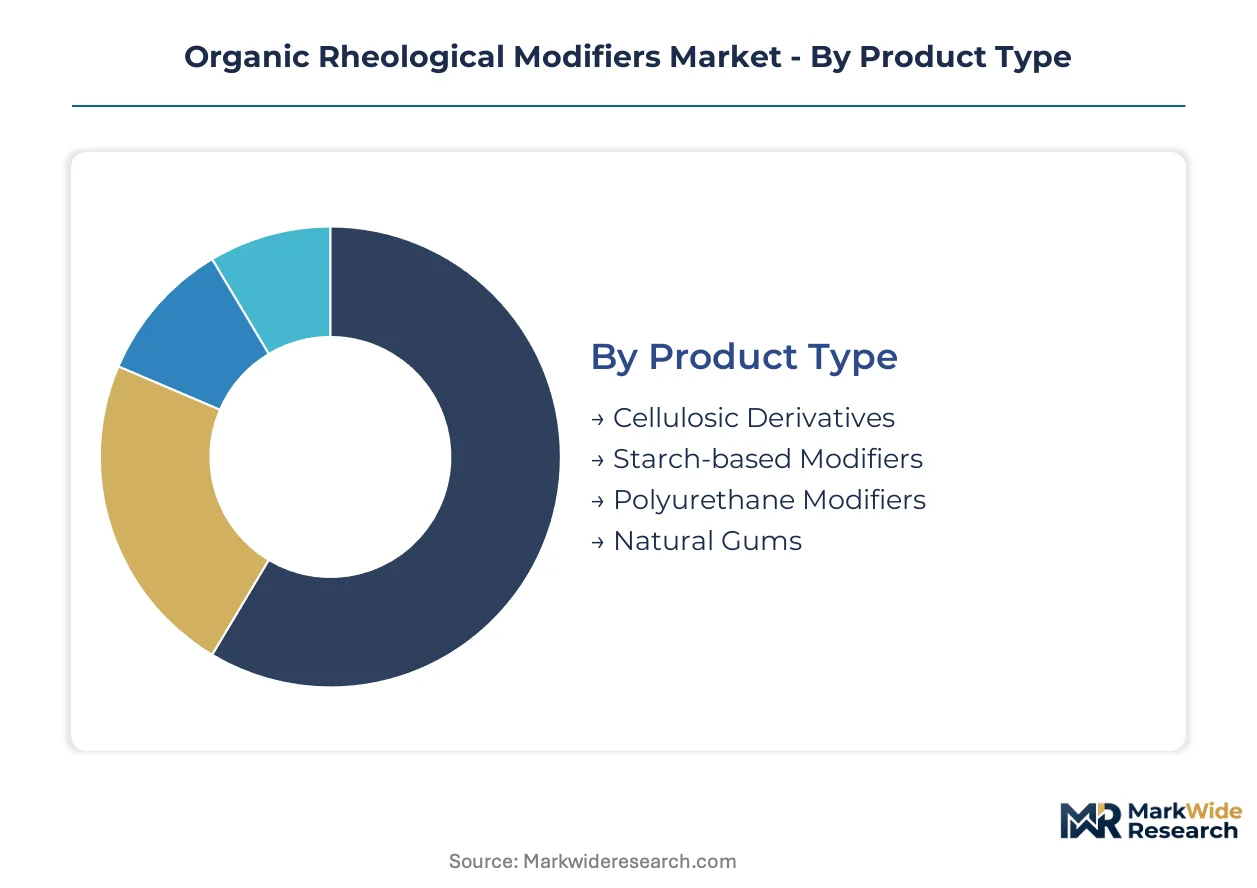
Organic rheological modifiers serve distinct performance requirements across formulation chemistry, regulatory exposure, and processing conditions. Segmentation reveals how suppliers allocate R&D resources between commodity-scale cellulosics and specialty associative polymers.
Product Type:
Cellulosic derivatives function as standalone thickeners in most construction and personal care formulations, while polyurethane modifiers embed within complex coating systems requiring multi-parameter optimization.
- Cellulosic Derivatives:These etherified polysaccharides—hydroxyethyl cellulose and hydroxypropyl methylcellulose—form entangled networks in aqueous media through hydrogen bonding. German coatings manufacturers under ECHA REACH mandates are scaling purchases for waterborne architectural paints where sag resistance and cost efficiency must coexist.
- Polyurethane Modifiers:Associative polymers with hydrophobic end-caps adsorb onto latex particle interfaces, building reversible network structures. Japanese automotive OEMs are qualifying these systems for robotic clearcoat application lines where atomization efficiency and sag control operate in tension.
- Starch-based Modifiers:Chemically modified starches from waxy maize and tapioca serve clean-label food applications under FDA and EU EFSA scrutiny.
- Natural Gums:Xanthan and guar derivatives from fermentation and agricultural processing dominate personal care formulations seeking synthetic polymer replacement.
Cellulosic derivatives lead volumes today; polyurethane modifiers are gaining share fastest in premium coating segments.
End Use Industry:
Coatings demand concentrates modifier purchases through formulation houses serving automotive and construction verticals, while food and pharmaceutical applications impose parallel qualification burdens.
- Coatings:Architectural, industrial, and automotive refinish segments drive bulk consumption. China's MEE enforcement in East China manufacturing clusters is accelerating waterborne reformulation, requiring higher additive loadings than solvent-borne predecessors.
- Personal Care:Skincare and haircare formulators under EU EFSA and FDA pressure are substituting synthetic acrylates with fermentation-derived polysaccharides.
- Food & Beverage:Clean-label mandates expand addressable market for starch and gum thickeners in dairy alternatives and prepared sauces.
- Pharmaceuticals:USP compliance standards for tablet binders and suspension stabilizers create dual dossier requirements alongside food additive registrations.
Coatings commands the largest revenue pool; personal care exhibits the steepest expansion trajectory as clean-label substitution accelerates.
Functionality:
Thickening and stabilization functions dominate volume, while dispersing and emulsification command premium positioning in multi-phase systems.
- Thickening Agent:Primary viscosity builders in aqueous and solvent systems. Cement-compatible cellulosic grades capture infrastructure project demand across Southeast Asia.
- Stabilizer:Suspension maintenance against gravitational separation. Critical for pharmaceutical syrups and personal care emulsions requiring extended shelf stability.
- Dispersing Agent:Particle separation and anti-agglomeration in pigment concentrates and ceramic slurries.
- Emulsifier:Interface stabilization for oil-in-water systems in food and cosmetic applications.
Thickening functions anchor current volumes; stabilization is climbing the fastest as waterborne formulations proliferate.
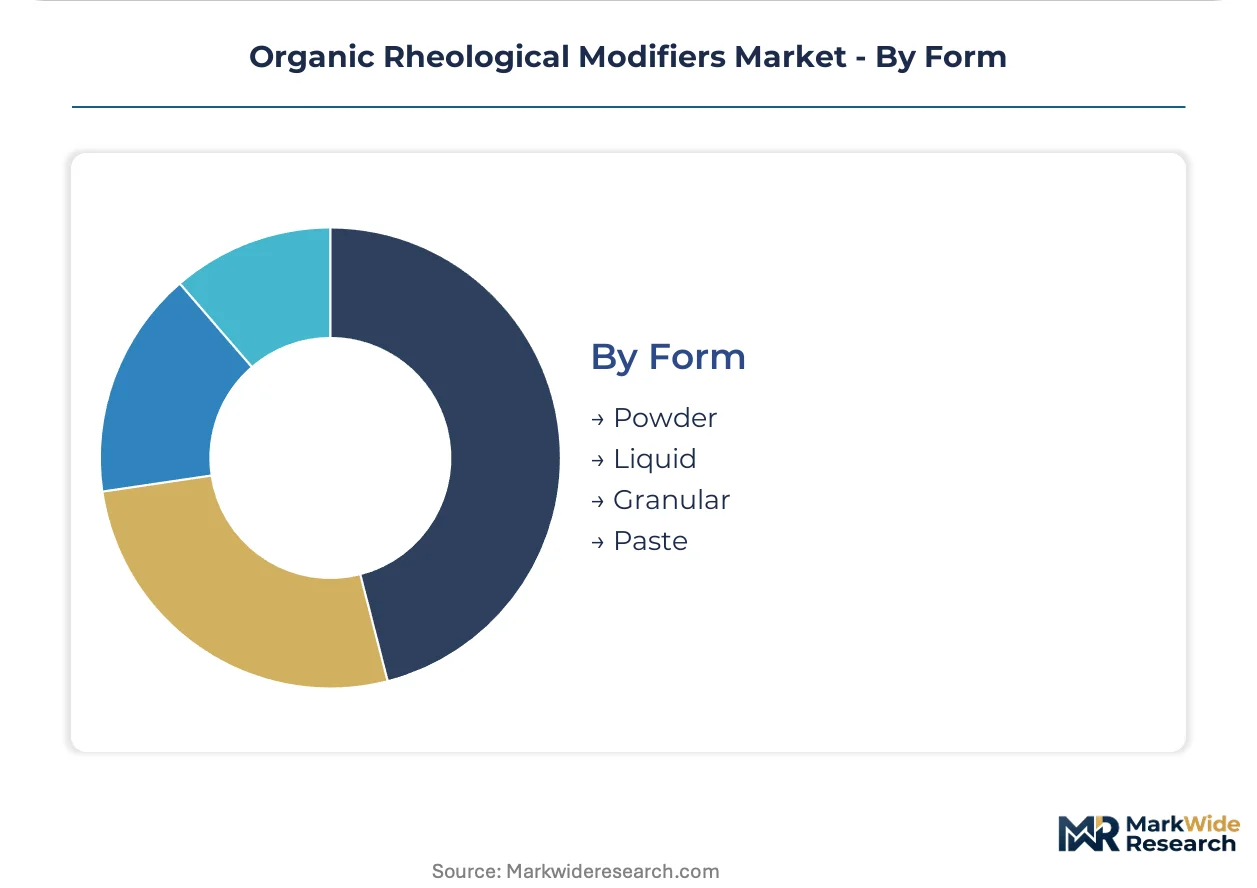
Form:
Powder and liquid presentations reflect downstream processing economics, with granular and paste formats serving niche handling requirements.
- Powder:Dry cellulosic ethers dominate construction and coatings manufacturing for extended shelf stability and freight efficiency.
- Liquid:Pre-dispersed polyurethane associative thickeners eliminate dust exposure and hydration time in automated coating plants.
- Granular:Low-dust starch derivatives serve food processing environments with explosion safety requirements.
- Paste:High-concentration gum dispersions for small-batch personal care and pharmaceutical compounding.
Powder forms retain volume leadership; liquid presentations are expanding most quickly in automated manufacturing installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's coatings manufacturers operate under tighter ECHA REACH enforcement than their counterparts in the United States, driving divergent modifier procurement patterns across Atlantic supply chains.
Germany
Automotive refinish and industrial coatings manufacturers in Bavaria and North Rhine-Westphalia are scaling purchases of polyurethane associative thickeners. ECHA REACH registration requirements constrain raw material sourcing, favoring suppliers with compliant bio-based dossiers. The Rhine-Ruhr manufacturing cluster hosts formulation plants qualifying waterborne systems for robotic spray lines.
China
Domestic waterborne formulation plants in East China's manufacturing corridors are accelerating modifier purchases to meet MEE enforcement timelines. GB standards on architectural coatings limit formaldehyde and VOC content, eliminating legacy thickener chemistries. The Yangtze River Delta concentration of automotive OEM coating facilities is driving qualification of sag-resistant polyurethane systems.
United States
Construction-grade cellulosic thickeners capture volume across Southeast and Midwest infrastructure projects requiring cement compatibility. FDA food additive regulations and USP compliance standards create dual qualification burdens for suppliers serving coatings, food, and pharmaceutical verticals. The Gulf Coast petrochemical corridor maintains integrated polyurethane modifier production with captive isocyanate access.
India
BIS certification requirements and urban infrastructure investment are creating entry points for associative polyurethane thickeners in premium decorative paints. The country's national pharmaceutical regulator imposes parallel dossier standards alongside food safety mandates. Maharashtra and Gujarat host the densest concentration of architectural coatings manufacturing plants reformulating for waterborne compliance.
Japan
Automotive OEMs in the Kanto and Kansai regions are qualifying polyurethane modifiers for robotic clearcoat application lines where atomization efficiency and sag control operate in tension. METI industrial standards shape modifier selection in domestic manufacturing. The Nagoya-Toyota industrial corridor drives specification harmonization across platform-globalized supply chains.
Organic Rheological Modifiers Market Competitive Environment
Top-tier vendors anchor integrated chemical platforms, while mid-scale specialists occupy niche associative polymer segments. The vendor base stratifies across three tiers: multinational diversified chemical producers with captive raw material access, regional compounders with formulation service capabilities, and fermentation-based bio-thickener startups serving clean-label mandates. Consolidation pressure intensifies as automotive OEMs consolidate approved vendor lists to reduce qualification overhead. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers seek multi-regional regulatory dossiers.
Within the integrated chemical producer tier, BASF SE and Dow exemplify divergent strategic positioning. BASF SE anchors European supply through its polyurethane modifier platform with captive isocyanate integration. Dow occupies North American manufacturing scale in cellulosic thickeners for construction and industrial applications. Arkema sits within the specialty tier, representing the associative acrylic segment targeting high-shear stability requirements in waterborne automotive coatings.
| Leading Market Players |
|---|
| BASF SE |
| Dow |
| Ashland Inc. |
| Clariant |
| Lubrizol Corporation |
| Arkema |
| Croda International |
| Evonik Industries |
| AkzoNobel N.V. |
| Others |
Value Chain & Pricing Dynamics
Purified cotton linter and wood pulp costs cascade from Brazilian and Indonesian agricultural suppliers through three distinct pricing tiers for cellulosic derivative producers, with ECHA REACH compliance premiums separating qualified European supply from commodity-grade Asian alternatives.
Pricing Analysis
Capacity additions in China are reshaping price floors for waterborne coating modifiers as domestic producers eliminate formaldehyde-releasing chemistries under MEE enforcement timelines. Three-tier pricing structure across premium polyurethane associative polymers, standard cellulosic ethers, and economy-grade natural gums differentiates on certification grade and shear stability performance. Pricing pressure stems from raw material volatility in purified cotton linter supply, compressing margins for cellulosic producers. Construction-grade buyers in Southeast Asia exhibit highest price sensitivity, while automotive OEMs in Germany and Japan accept premium positioning for robotic spray line compatibility.
Supply Chain Analysis
Formulation chemist scarcity in Germany's Rhine-Ruhr cluster and East China's Yangtze River Delta constrains technical service capacity for waterborne rheology optimization. Supply concentrates in Germany for polyurethane modifiers with captive isocyanate integration, China for cellulosic derivative manufacturing serving domestic waterborne formulation plants, and the United States for construction-grade thickeners with FDA and USP dual qualification capabilities. Raw material dependencies include purified cotton linter from Brazil, wood pulp from Indonesia, and fermentation feedstocks for xanthan gum production. Single-source vulnerability characterizes European polyurethane modifier supply given narrow integrated producer base. Distribution runs through formulation houses serving automotive and construction verticals, with direct procurement relationships consolidating among Tier-1 coatings suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as waterborne coating mandates across automotive and architectural segments create durable additive demand. Regulatory enforcement timelines provide predictable volume catalysts rather than cyclical spikes.
For Market Incumbents: To counter consolidation pressure from automotive OEMs reducing approved vendor lists, BASF SE and Dow should deepen captive raw material positions in isocyanate and purified cotton linter respectively. Certification investment in multi-regulatory dossiers—simultaneous REACH, FDA, and USP compliance—creates defensible moats against regional compounders lacking parallel qualification infrastructure. For New Entrants and Emerging Players: The mid-market gap between premium polyurethane modifiers and commodity cellulosic derivatives offers white-space entry for hybrid architectures combining cost position with performance profile. India's BIS-certified architectural coatings sector presents the most penetrable geography, with Maharashtra and Gujarat hosting dense coatings manufacturing clusters reformulating for waterborne compliance. Go-to-market positioning should emphasize fermentation-derived polysaccharide thickeners for personal care clean-label substitution under EU EFSA and FDA scrutiny. For Investors and Strategic Acquirers: Consolidation pressure builds where automotive OEM qualification requirements exceed regional compounder capabilities. Long-term viability favors suppliers with integrated chemical platforms and multi-vertical regulatory dossiers spanning coatings, food, and pharmaceuticals. Acquisition targets include mid-scale associative polymer specialists with existing robotic spray line qualifications in automotive clearcoat applications. Signal to watch: Tier-1 coatings supplier consolidation of modifier specifications to single-source relationships, indicating which technical service capabilities command premium valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Supply | Captive raw material access secures margin stability for polyurethane modifier producers under ECHA REACH constraints. |
| Multi-Regional Regulatory Dossier Expansion | Parallel FDA, USP, and REACH qualification opens contract eligibility across coatings, food, and pharmaceutical verticals simultaneously. |
| Fermentation-Derived Polysaccharide Scale-Up | Clean-label positioning under EU EFSA clean-label mandates captures personal care substitution demand from synthetic acrylates. |
| Robotic Spray Line Qualification Partnerships | Technical validation with Japanese and German automotive OEMs embeds modifiers into platform-globalized supply chains. |
| Hybrid Architecture R&D Investment | Combining cellulosic cost structures with associative polymer performance compresses the premium-mid-market price gap. |
Study Parameters
Bottom-up coatings and personal care modeling reconciled against top-down chemical additive production tracking forms the analytical core of this study. Primary interviews with plant managers at waterborne formulation facilities, procurement leads at automotive OEM coating divisions, technical R&D directors at modifier suppliers, and distribution channel partners in construction chemicals were validated against secondary sources including customs and trade data, ECHA REACH registration databases, SEC 10-K filings from integrated chemical producers, and national coatings production statistics from Cefic and the American Chemistry Council.
Input-output matrices map modifier consumption intensity across solvent-borne versus waterborne formulation transitions, with segmentation dimensions spanning product type, end-use industry, functionality, and form presentation. CAGRs were derived from regression analysis of historical additive loading rates and projected waterborne penetration curves across automotive refinish, architectural, and industrial coating segments. Forecast inputs include ECHA enforcement timelines for bio-based substitution, China's dual carbon goals accelerating GB standard compliance, and clean-label mandate propagation through EU EFSA and FDA jurisdictions.
Caveats apply where raw material disruptions in Brazilian cotton linter or Indonesian wood pulp supply, abrupt regulatory enforcement acceleration in East China manufacturing clusters, or breakthrough shear-stability improvements in natural gum formulations could materially shift the outlook. Material deviation in these named triggers warrants pause and re-evaluation of volume and value trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Absolute Ethanol Market
Organic Chemicals
Isophthalic Acid Market
Organic Chemicals
Global Benzoic Acid Market
Organic Chemicals
Europe Cycloalkanes Market
Organic Chemicals
4-Tert-Amylphenol Market
Organic Chemicals
Anthracene Market
Organic Chemicals
Phenol Market
Organic Chemicals
Diethyl Ketone Market
Organic Chemicals
Cycloalkanes Market
Organic Chemicals
Chloro -Dimethylsilane (CAS 1066-35-9) Market
Organic Chemicals
Dioxolane Market
Organic Chemicals
Synthetic and Bio-Based Aniline Market
Organic Chemicals
Organic Hydrosols Market
Organic Chemicals
N-Pentane Market
Organic Chemicals
2,5-Dimethyl-2,4-Hexadiene Market
Organic Chemicals
Global Pseudocumene Market