
 Viscoelastic Agents Market | 2026-2036
Viscoelastic Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Viscoelastic Agents Market Analytics
China is fragmenting as domestic biotech firms build hyaluronic acid fermentation capacity to serve regional ophthalmology demand. Haohai Biological Technology leverages vertical integration from raw material extraction to finished sterile syringes. Alcon Laboratories sustains global manufacturing scale across multiple viscoelastic formulations for anterior segment surgery. Johnson & Johnson competes through specialized viscoelastic portfolios tailored to premium cataract workflows.
Viscoelastic agents are high-molecular-weight polymer solutions—principally hyaluronic acid, chondroitin sulfate, and hydroxypropyl methylcellulose—formulated to maintain anterior chamber depth, protect corneal endothelium, and manipulate tissue during intraocular procedures. These agents require precise rheological properties, with zero-shear viscosities exceeding 100,000 mPa·s for cohesive formulations and pseudoplastic flow profiles for dispersive variants, to function as surgical instruments rather than passive lubricants. Ophthalmology applications generate the dominant revenue pool, driven by phacoemulsification volume and premium intraocular lens adoption. Hyaluronic acid products command the widest clinical acceptance, while polyacrylamide formulations occupy niche aesthetic and orthopedic segments where longer residence duration justifies premium positioning.
The FDA enforces stringent sterility and endotoxin limits for intraocular viscoelastic devices under 21 CFR 886, while the EMA's MDR framework demands enhanced clinical evidence for CE-marked ophthalmic viscoelastics entering European markets. Japan's PMDA applies JIS-quality standards to imported hyaluronic acid raw materials, creating compliance friction for non-domestic suppliers. Stakeholders must monitor regulatory divergence on animal-origin versus biofermentation sourcing requirements, as this technical specification is becoming a primary determinant of market access and cost structure across major jurisdictions.
Market Dynamics
Hyaluronic acid fermentation capacity is concentrating among vertically integrated biotech manufacturers, reshaping raw material economics and forcing reformulation strategies across ophthalmic viscoelastic portfolios.
Growth Catalysts
- Phacoemulsification volume expansion:Cataract surgery throughput at ambulatory surgical centers is pulling through higher unit consumption of cohesive viscoelastic agents per procedure.
- FDA purity benchmark elevation:Updated 21 CFR 886 guidance on intraocular medical devices is disqualifying lower-grade hyaluronic acid feedstocks and advantaging GMP-certified fermentation suppliers.
- Aging demographic pull:United States Medicare enrollment patterns are sustaining procedure rates that outpace population growth, cementing North American demand concentration.
Market Restraints
- Animal-origin sourcing friction:Rooster-comb extraction routes face EMA MDR traceability requirements that biofermentation alternatives bypass, fragmenting compliance pathways.
- Endotoxin testing cost inflation:LAL reagent supply volatility and USP <85> harmonization timelines are extending batch release cycles for sterile syringe formats.
- Single-source polymer dependence:High-molecular-weight hyaluronic acid above 2 million Daltons concentrates among three fermentation specialists, creating input bottlenecks.
Strategic Opportunities
- Premium IOL workflow integration:Toric and multifocal lens implantation protocols require specialized dispersive-cohesive combinations that command formulation premiums.
- India ophthalmology infrastructure buildout:CDSCO streamlined medical device registration is opening import pathways for CE-marked viscoelastics into tier-2 cataract centers.
- Orthobiologic adjacency expansion:Viscoelastic rheology expertise transfers into intra-articular osteoarthritis injections, leveraging existing sterile manufacturing assets.
Industry Challenges
- Bioprocess engineering talent scarcity:Mammalian cell culture and precision fermentation skill sets command premium compensation, constraining capacity expansion timelines.
- Legacy sterilization validation:Terminal gamma irradiation protocols for pre-filled syringes require 12-18 month stability studies that delay product line extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Viscoelastic Agents Market |
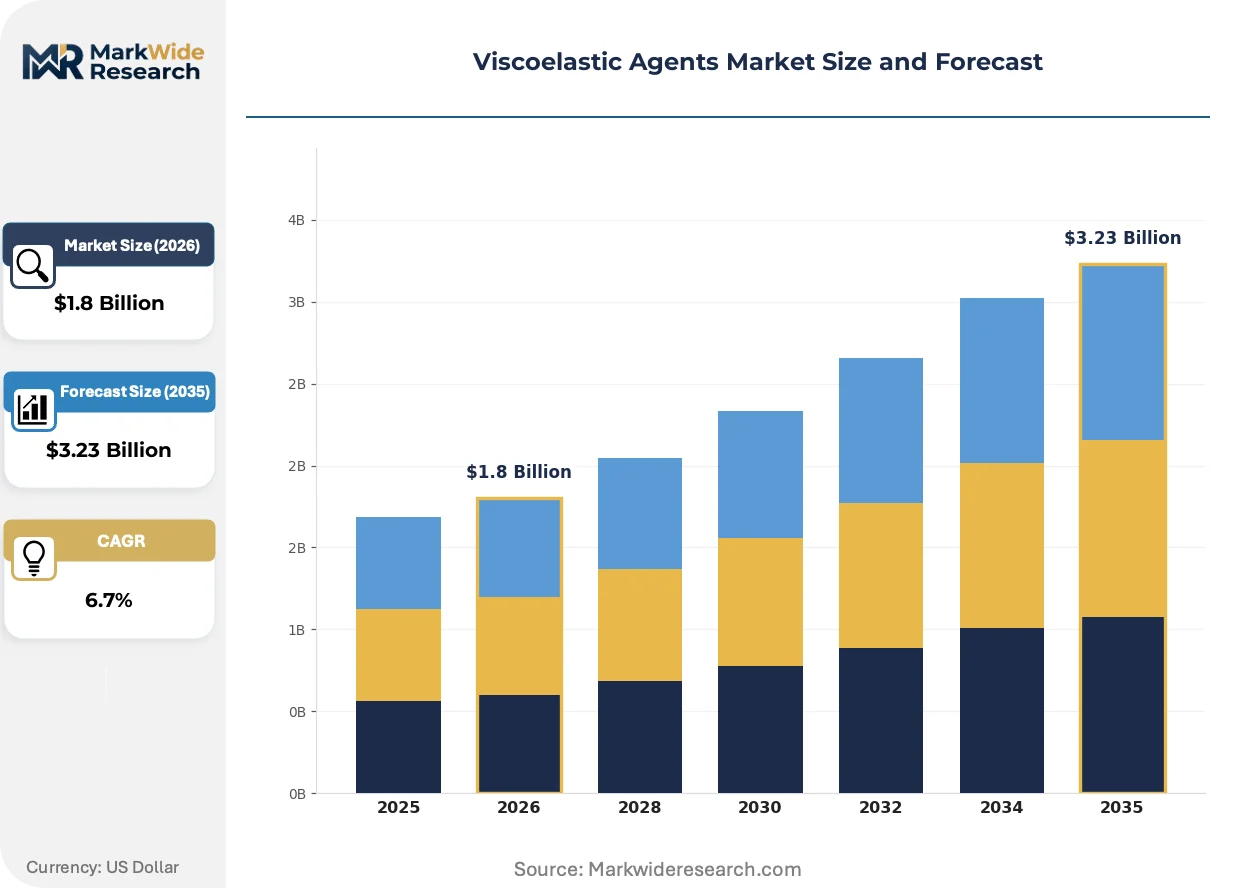
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hyaluronic Acid, Dextran, Polyacrylamide, Gelatin Application: Ophthalmology, Orthopedics, Cardiovascular, Aesthetic Delivery Mode: Injectable, Topical, Intravitreal, Sublingual End User: Clinics, Hospitals, Research Laboratories, Outpatient Centers |
| Companies Covered | Carl Zeiss Meditec AG, Haohai Biological Technology, Alcon Laboratories, Ophtechnics Unlimited, Rumex International, Johnson & Johnson, Rayner Group, Bohus Biotech, Bausch & Lomb Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Viscoelastic Agents Market Evolving Landscape
Digital integration across surgical workflows is compressing the information gap between viscoelastic performance characteristics and real-time procedure outcomes, forcing suppliers to embed traceability deeper into unit-of-use packaging.
Adaptive rheology monitoring systems is digitizing how surgeons select cohesive versus dispersive formulations intraoperatively. Anterior segment specialists at high-volume cataract centers are adopting connected phacoemulsification platforms that log viscoelastic consumption per case. This data layer is compressing brand loyalty cycles and enabling outcome-based formulary negotiations with group purchasing organizations.
EMA MDR Article 10 clinical evidence requirements are tightening post-market surveillance obligations for CE-marked ophthalmic viscoelastics. Manufacturers must now submit periodic safety update reports that aggregate real-world performance data across member states. Small-to-mid scale suppliers lacking European authorized representative infrastructure are withdrawing SKUs rather than absorbing compliance costs, concentrating shelf presence among scaled multinationals.
Direct-to-ambulatory-surgical-center distribution is disintermediating traditional hospital pharmacy procurement for high-turnover viscoelastic SKUs. Specialty distributors with cold-chain capabilities and same-day replenishment networks are capturing volume from broad-line medical-surgical distributors. This channel compression is most visible in United States metropolitan markets where independent ASCs operate outside integrated delivery network formularies and prioritize inventory velocity over contract breadth.
Viscoelastic Agents Market Segmentation
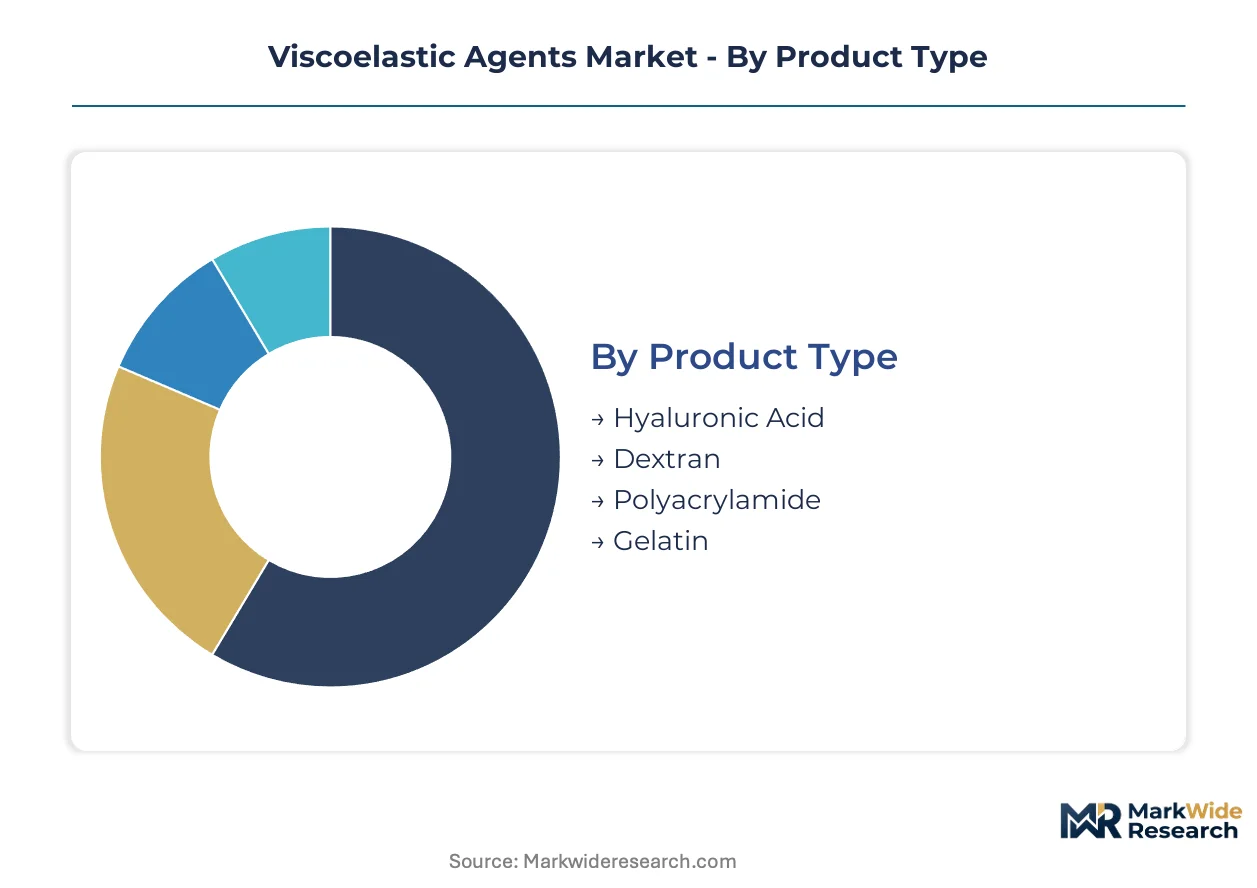
Viscoelastic agent procurement patterns diverge sharply across product chemistry and clinical setting, with anterior segment ophthalmology driving inventory velocity while orthopedic and aesthetic applications stretch replacement cycles. Understanding these turnover differentials enables suppliers to align fermentation batch sizing with actual consumption rhythms rather than aggregate demand signals.
Product Type:
Hyaluronic acid formulations turn over fastest due to cataract surgery volume, while polyacrylamide and gelatin variants sit longer in specialty clinic inventories serving lower-frequency procedures.
- Hyaluronic Acid:High-molecular-weight fermentation-derived polymers exceeding 2 million Daltons dominate cohesive ophthalmic formulations. Phacoemulsification throughput at United States ambulatory surgical centers sustains weekly replenishment cycles for pre-filled syringe formats.
- Polyacrylamide:Synthetic cross-linked hydrogels engineered for extended tissue residence command premium positioning in aesthetic facial volumization. Demand concentrates at dermatology clinics in metropolitan France and Germany where EMA MDR traceability requirements favor documented synthetic sourcing over animal-origin alternatives.
- Dextran:Bacterial polysaccharide solutions serve dispersive ophthalmic roles requiring lower viscosity profiles.
- Gelatin:Collagen-derived matrices occupy niche cardiovascular applications where hemostatic properties outweigh rheological precision requirements.
Hyaluronic acid dominates installed base. Polyacrylamide is where expansion concentrates.
Application:
Procedure reimbursement rates create three distinct margin tiers, with ophthalmology capturing volume premiums and orthopedics trading margin for access scale.
- Ophthalmology:Anterior segment surgery consumes cohesive and dispersive formulations calibrated to maintain anterior chamber depth and protect corneal endothelium. Medicare reimbursement stability in the United States underpins predictable demand forecasting for ASC inventory managers.
- Orthopedics:Intra-articular osteoarthritis injections leverage existing sterile manufacturing assets from ophthalmic production lines. Volume expansion is climbing the fastest in India where CDSCO streamlined registration opens tier-2 urban centers to imported viscoelastics.
- Cardiovascular:Gelatin-based hemostats and sealants serve surgical bleeding control with lower regulatory burden than permanent implants.
- Aesthetic:Facial volumization and wrinkle correction applications prioritize extended residence duration over precise rheological control.
Ophthalmology commands revenue concentration. Orthopedics represents the volume expansion frontier.
Delivery Mode:
Sterile syringe format requirements segment manufacturing complexity, with injectable and intravitreal routes demanding terminal gamma validation that topical formats bypass.
- Injectable:Pre-filled syringes for intra-articular and intracameral administration require 12-18 month stability studies. United States specialty distributors with cold-chain capabilities are capturing volume from broad-line medical-surgical distributors for high-turnover SKUs.
- Intravitreal:Posterior segment administration demands endotoxin limits stricter than anterior chamber applications. PMDA JIS-quality standards in Japan create compliance friction for non-domestic hyaluronic acid raw material suppliers.
- Topical:Surface application formats for wound management carry reduced sterility validation burdens.
- Sublingual:Mucosal absorption routes remain experimental with limited commercial deployment.
Injectable formats anchor production capacity. Intravitreal is gaining share fastest in premium retina workflows.
End User:
Procurement authority fragmentation separates high-velocity ambulatory settings from capital-constrained institutional purchasers with extended decision cycles.
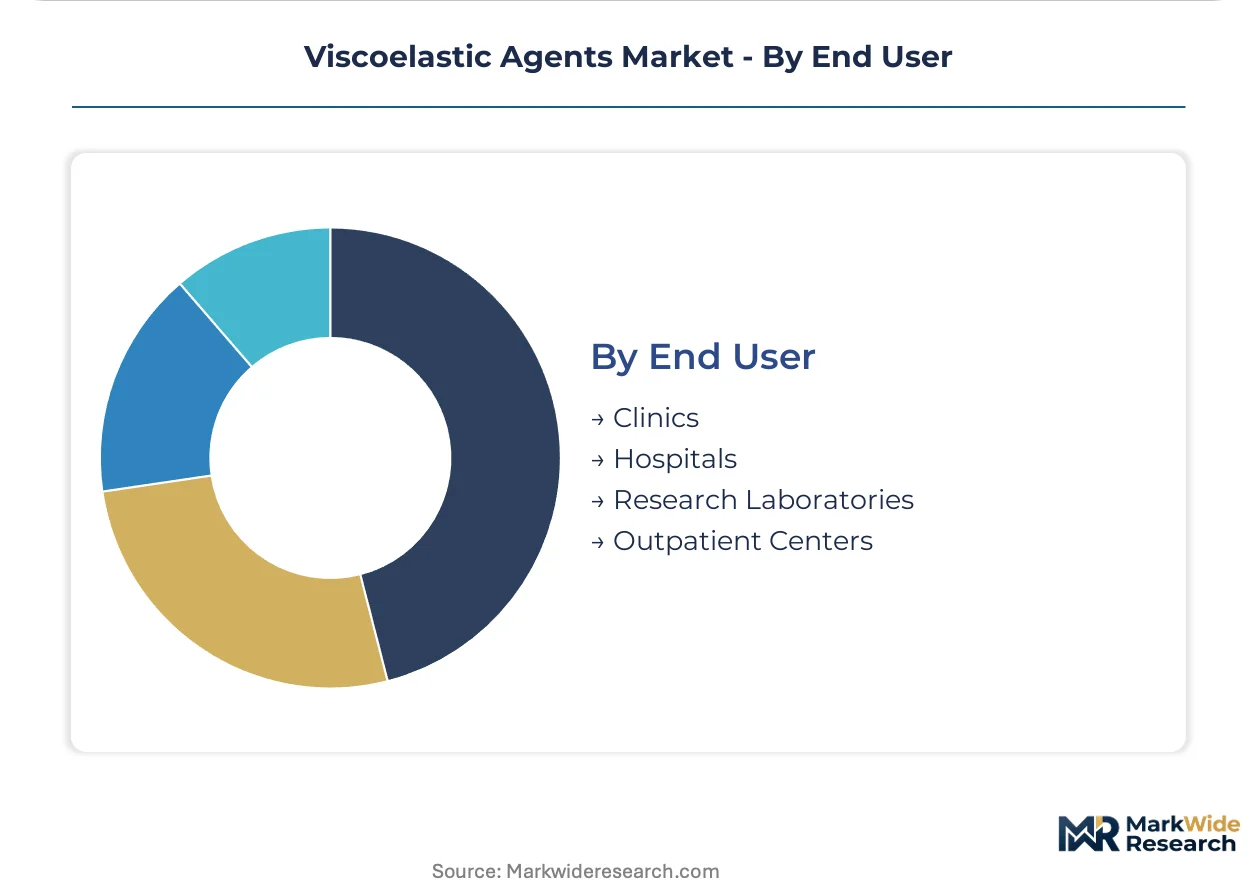
- Outpatient Centers:Independent ambulatory surgical centers in United States metropolitan markets operate outside integrated delivery network formularies. These facilities prioritize inventory velocity and same-day replenishment over contract breadth, disintermediating traditional hospital pharmacy procurement.
- Hospitals:Integrated delivery networks negotiate enterprise-wide contracts that compress unit pricing in exchange for volume commitments. EMA MDR Article 10 clinical evidence requirements are forcing small-to-mid scale suppliers to withdraw SKUs rather than absorb compliance costs.
- Clinics:Private ophthalmology and dermatology practices drive aesthetic and premium IOL workflow demand.
- Research Laboratories:Preclinical and clinical trial supply represents non-recurring procurement with customized formulation requirements.
Outpatient centers dominate unit velocity. Hospitals concentrate contract value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes viscoelastic agents through high-volume cataract workflows at ambulatory surgical centers, while China and India exhibit distinct procurement patterns shaped by domestic manufacturing buildout and regulatory streamlining respectively.
United States
Medicare reimbursement stability sustains predictable demand for cohesive hyaluronic acid formulations at independent ASCs. The FDA enforces updated 21 CFR 886 purity benchmarks that disqualify lower-grade feedstocks. Metropolitan markets in Texas and Florida concentrate same-day replenishment networks serving high-turnover ophthalmology practices.
China
Domestic biotech firms are scaling hyaluronic acid fermentation capacity to serve regional ophthalmology demand. The NMPA applies stringent sterility standards to intraocular medical devices while encouraging local production. Shanghai and Suzhou industrial clusters host vertically integrated manufacturers controlling extraction through finished sterile syringe production.
Germany
EMA MDR Article 10 clinical evidence requirements concentrate CE-marked viscoelastic shelf presence among scaled multinationals. The country's national pharmaceutical regulator enforces enhanced post-market surveillance obligations. Bavaria and Baden-Württemberg house specialized distributors capturing volume from broad-line medical-surgical channels.
India
CDSCO streamlined medical device registration is opening import pathways for CE-marked viscoelastics into tier-2 cataract centers. The central drug regulator applies harmonized quality standards that reduce compliance friction for European-cleared products. Maharashtra and Karnataka ophthalmology infrastructure buildouts represent the fastest volume expansion frontier.
Japan
PMDA JIS-quality standards to imported hyaluronic acid raw materials create compliance friction for non-domestic suppliers. METI industrial policy supports domestic fermentation capacity for medical-grade polymers. The Kanto region around Tokyo concentrates premium retina workflows driving intravitreal format demand.
Viscoelastic Agents Market Competitive Landscape
Capability concentration sits with vertically integrated fermentation specialists; scale advantage sits with diversified ophthalmic portfolio multinationals. The vendor base separates into three tiers: global device conglomerates with sterile manufacturing assets, regional biotech firms with captive polymer supply, and specialized distributors with cold-chain logistics. Dominant competitive moves include backward integration into high-molecular-weight hyaluronic acid production and direct-to-ASC distribution network buildout.
Within the integrated biotech tier, Haohai Biological Technology exemplifies vertical control from raw material extraction through finished syringes. Among diversified ophthalmic multinationals, Alcon Laboratories and Johnson & Johnson occupy positions anchored by global sterile manufacturing scale and specialized viscoelastic portfolios respectively. Carl Zeiss Meditec AG represents the precision device archetype with complementary ophthalmology workflow integration.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Haohai Biological Technology |
| Alcon Laboratories |
| Ophtechnics Unlimited |
| Rumex International |
| Johnson & Johnson |
| Rayner Group |
| Bohus Biotech |
| Bausch & Lomb Incorporated |
| Others |
Value Network & Pricing Analysis
Fermentation capacity for high-molecular-weight hyaluronic acid concentrates among three specialist suppliers in China, South Korea, and Japan, anchoring margin capture downstream at pre-filled syringe manufacturers and specialty distributors serving United States ambulatory surgical centers.
Pricing Analysis
Long-term offtake contracts dominate procurement between GMP-certified fermentation suppliers and sterile syringe manufacturers, insulating premium-tier cohesive formulations from spot-market volatility while dispersive variants trade on shorter procurement cycles. Pricing stratifies across premium, standard, and economy tiers based on molecular weight certification and endotoxin grade, with FDA 21 CFR 886 compliance tiers commanding measurable premiums over CE-marked alternatives. Cost compression in standard-grade hyaluronic acid is intensifying because domestic Chinese fermentation capacity is expanding output. Hospital integrated delivery networks exhibit the highest price sensitivity due to enterprise-wide volume negotiations, while independent ambulatory surgical centers prioritize inventory velocity over unit cost.
Supply Chain Analysis
Contract manufacturing of sterile pre-filled syringes concentrates among specialized CMOs in Germany, Ireland, and the United States with validated terminal gamma irradiation capabilities. Raw material supply draws from biofermentation feedstocks, rooster-comb extraction routes, and synthetic polyacrylamide precursors. Single-source vulnerability sits with fermentation-derived hyaluronic acid above 2 million Daltons, where three suppliers control global capacity. Distribution runs through specialty distributors with cold-chain capabilities and same-day replenishment networks serving metropolitan United States markets, displacing broad-line medical-surgical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation is accelerating as regulatory divergence on animal-origin versus biofermentation sourcing creates distinct compliance pathways, opening niches for regional specialists with captive polymer supply and targeted certification investments.
For Market Incumbents: Harden sterile manufacturing asset utilization through backward integration into high-molecular-weight hyaluronic acid fermentation, securing supply against input bottlenecks from the three dominant fermentation specialists. Prioritize EMA MDR Article 10 clinical evidence infrastructure to defend shelf presence as small-to-mid scale suppliers withdraw SKUs from European markets. Channel control through direct-to-ambulatory-surgical-center distribution networks captures inventory velocity premiums outside integrated delivery network formularies. For New Entrants and Emerging Players: Tier-2 cataract centers in Maharashtra and Karnataka represent the most penetrable geography, where CDSCO streamlined registration reduces compliance friction for CE-marked viscoelastics. Orthobiologic adjacency expansion into intra-articular osteoarthritis injections offers white-space volume with lower regulatory burden than ophthalmic applications. A go-to-market angle anchored to premium IOL workflow integration—toric and multifocal lens protocols requiring specialized dispersive-cohesive combinations—commands formulation premiums and escapes commodity pricing pressure. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated regional biotech firms with captive fermentation capacity and finished sterile syringe production, as these assets compound manufacturing margin capture with regulatory pathway control. Long-term viability across the analysis window rests on defensible input supply and multi-jurisdiction certification breadth. The signal to watch is FDA purity benchmark elevation disqualifying lower-grade feedstocks, which will accelerate consolidation toward GMP-certified fermentation suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Captive supply of high-molecular-weight hyaluronic acid above 2 million Daltons insulates against input bottlenecks. |
| EMA MDR Compliance Infrastructure | European authorized representative capabilities prevent SKU withdrawal and sustain CE-marked shelf presence. |
| Direct-to-ASC Distribution Buildout | Same-day replenishment networks capture volume from hospital pharmacy procurement in metropolitan United States markets. |
| Premium IOL Workflow Integration | Specialized dispersive-cohesive combinations for toric and multifocal lens protocols command formulation premiums. |
| Orthobiologic Adjacency Expansion | Intra-articular osteoarthritis injections leverage existing sterile manufacturing assets for volume growth in India. |
Research Methodology
Cross-validation between primary interviews with ophthalmic surgeons, ASC inventory managers, GPO contracts managers, and biomedical engineers and secondary sources including FDA 21 CFR 886 guidance documents, EMA MDR Article 10 submissions, CDSCO registration databases, and hospital procurement records anchors the qualitative findings. Bottom-up demand modeling from phacoemulsification procedure volumes and premium IOL adoption rates triangulates against top-down market sizing from sterile syringe production capacity and fermentation output estimates.
Calibration against historical CAGRs in ophthalmic device categories and medical-grade polymer markets validates the projection framework across the analysis window. Segmentation dimensions include product chemistry, application, delivery mode, and end-user procurement authority, with regional regulatory cluster serving as an additional modeling layer. Forecast inputs incorporate Medicare reimbursement stability patterns, NMPA domestic production incentives, and CDSCO registration streamlining timelines.
Practitioners should monitor FDA purity benchmark enforcement actions, EMA MDR periodic safety update report obligations, and LAL reagent supply volatility for early signals of forecast revision. Quarterly review of fermentation capacity utilization rates, ASC inventory turnover metrics, and specialty distributor market share shifts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Sol-Gel Processing Market
Specialty Chemicals
Australia and New Zealand Aerosol Market
Specialty Chemicals
Lignin Products Market
Specialty Chemicals
Sodium Ascorbyl Phosphate (SAP) Market
Specialty Chemicals
Colloidal Gold Suspension Market
Specialty Chemicals
Global Vacuum Grease Market
Specialty Chemicals
Ethylhexane Diol Market
Specialty Chemicals
Hyaluronic Acid Products Market
Specialty Chemicals
Barium Derivatives Market
Specialty Chemicals
Global Caffeic Acid Market
Specialty Chemicals
Squalene Market
Specialty Chemicals
2-(2,2,2-Trifluoroethoxy)-1,3,2-Dioxaphospholane-2-Oxide Market
Specialty Chemicals
Sugarcane Wax Market
Specialty Chemicals
Ethyl Cellulose Market
Specialty Chemicals
Zinc Ricinoleate Market
Specialty Chemicals
Global Specialty Fuel Additives Market