
 Global Cephalosporin Drugs Market | 2026-2036
Global Cephalosporin Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cephalosporin Drugs Market Foresight
Aftermarket service revenue from antimicrobial susceptibility testing and stewardship consulting is reshaping how cephalosporin manufacturers capture value beyond the molecule itself. Pfizer Inc leverages its hospital channel infrastructure to sustain formulary positioning across major health systems. Sun Pharmaceutical Industries Limited anchors its competitive stance through backward integration into active pharmaceutical ingredient production. Teva Pharmaceutical Industries Ltd. competes on cost structure by operating high-volume generic injectable facilities across Eastern Europe and Latin America.
Cephalosporin drugs constitute a class of beta-lactam antibiotics derived from Acremonium fungi, characterized by a six-membered dihydrothiazine ring fused to a beta-lactam nucleus that confers bactericidal activity through penicillin-binding protein inhibition. These agents are manufactured via semisynthetic fermentation followed by acylation and side-chain modification, with sterile injectable formulations requiring aseptic filling under ISO 5 cleanroom conditions for hospital-critical applications. Cefepime commands premium positioning in intensive care settings due to its extended-spectrum coverage against Pseudomonas aeruginosa and enterobacteriaceae. The injectable formulation segment generates the highest margin pools as hospital procurement consolidates around parenteral therapy for severe sepsis and nosocomial pneumonia. Ceftriaxone sustains volume leadership in outpatient transition-of-care protocols despite emerging resistance surveillance pressures.
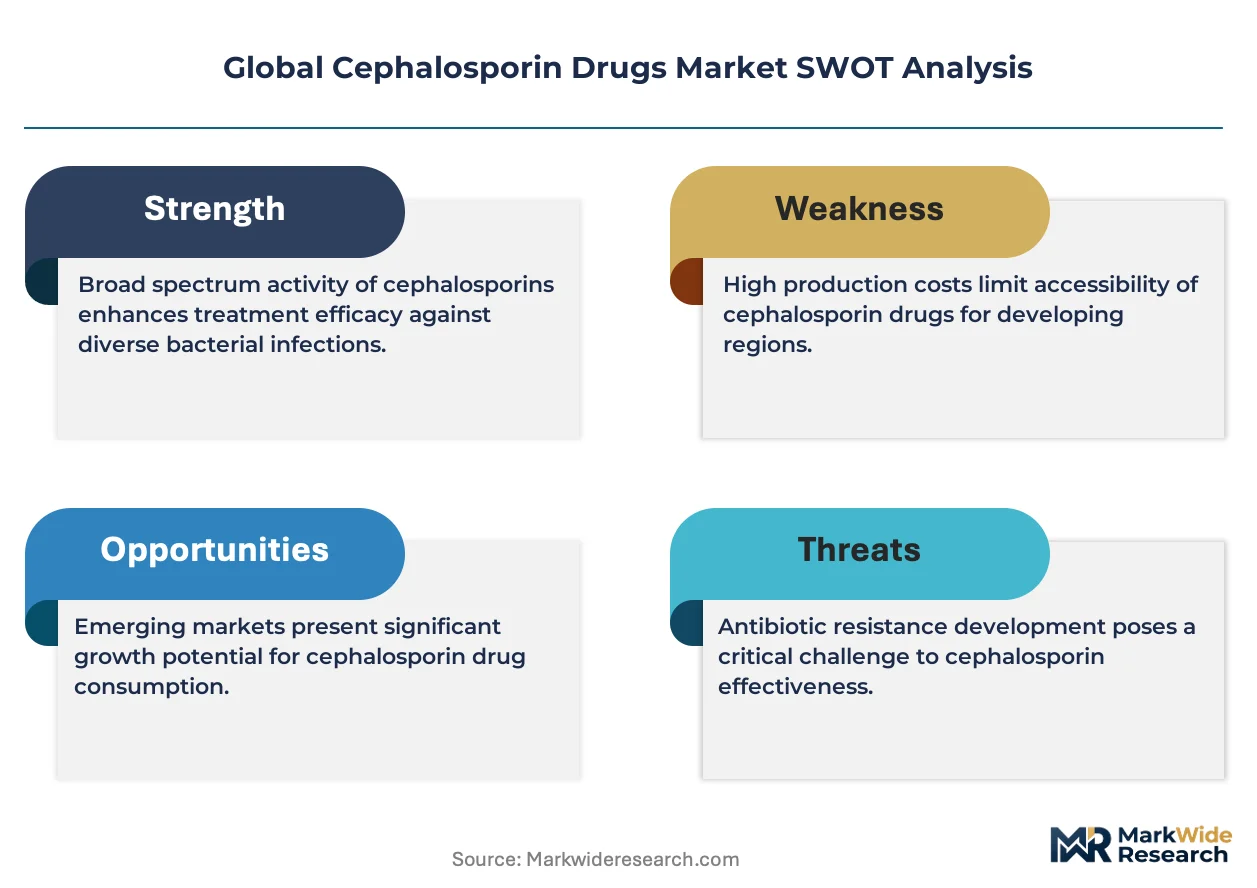
FDA antimicrobial stewardship mandates and EMA's revised veterinary cephalosporin restrictions are tightening manufacturing quality standards and reshaping demand toward human-specialized production lines. CDSCO in India enforces batch-release testing protocols that govern export eligibility to regulated markets. WHO prequalification requirements and ISO 13485 quality management standards determine access to multilateral procurement channels. Stakeholders must monitor resistance surveillance data from CDC and ECDC to anticipate formulary shifts and guide R&D prioritization toward next-generation beta-lactamase inhibitor combinations.
Market Dynamics
Antimicrobial resistance surveillance networks are compressing product lifecycles and forcing manufacturers to accelerate beta-lactamase inhibitor combination development ahead of formulary exclusion thresholds.
Growth Catalysts
- FDA Antimicrobial Stewardship Frameworks:Hospital formulary committees now mandate documented susceptibility testing before broad-spectrum cephalosporin release, expanding demand for companion diagnostics and stewardship consulting services.
- Injectable Formulation Concentration:Parenteral therapy protocols for sepsis and nosocomial pneumonia in tertiary care centers are pulling manufacturing capacity toward sterile fill-finish operations.
- India API Manufacturing:Domestic fermentation and acylation capacity under CDSCO oversight is reducing import dependency for regulated markets.
Market Restraints
- Key Starting Material Volatility:7-ACA and 7-ADCA intermediate prices fluctuate with Chinese environmental enforcement cycles, squeezing margin predictability for semisynthetic producers.
- EMA Veterinary Restrictions:Revised cephalosporin use limits in food-animal production are forcing line conversions to human-specialized sterile capacity without guaranteed volume offsets.
- Carbapenem Substitution:Meropenem and ertapenem are displacing extended-spectrum cephalosporins in ICU protocols where Pseudomonas resistance thresholds exceed institutional cutoffs.
Strategic Opportunities
- Sub-Saharan Africa Access Expansion:WHO prequalification pathways for fixed-dose ceftriaxone combinations are opening multilateral procurement channels previously blocked by batch-release documentation gaps.
- Outpatient Infusion Centers:Transition-of-care protocols are shifting stable sepsis patients from inpatient parenteral therapy to ambulatory settings, requiring novel infusion bag and elastomeric pump compatibility.
- US Inflation Reduction Act:Medicare antimicrobial subscription pilot programs are creating guaranteed revenue mechanisms for novel combination therapies addressing resistant gram-negative pathogens.
Industry Challenges
- Aseptic Manufacturing Workforce Scarcity:ISO 5 cleanroom operators with sterile technique certification are concentrated in legacy manufacturing clusters, constraining greenfield facility ramp rates.
- Cross-Contamination Validation:Beta-lactam dedicated facility requirements under FDA guidance demand segregated HVAC and waste systems, extending facility qualification timelines.
- Pharmacovigilance Integration:Real-world resistance surveillance data from CDC NHSN must feed directly into post-market commitment reporting, straining legacy pharmacovigilance IT architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cephalosporin Drugs Market |
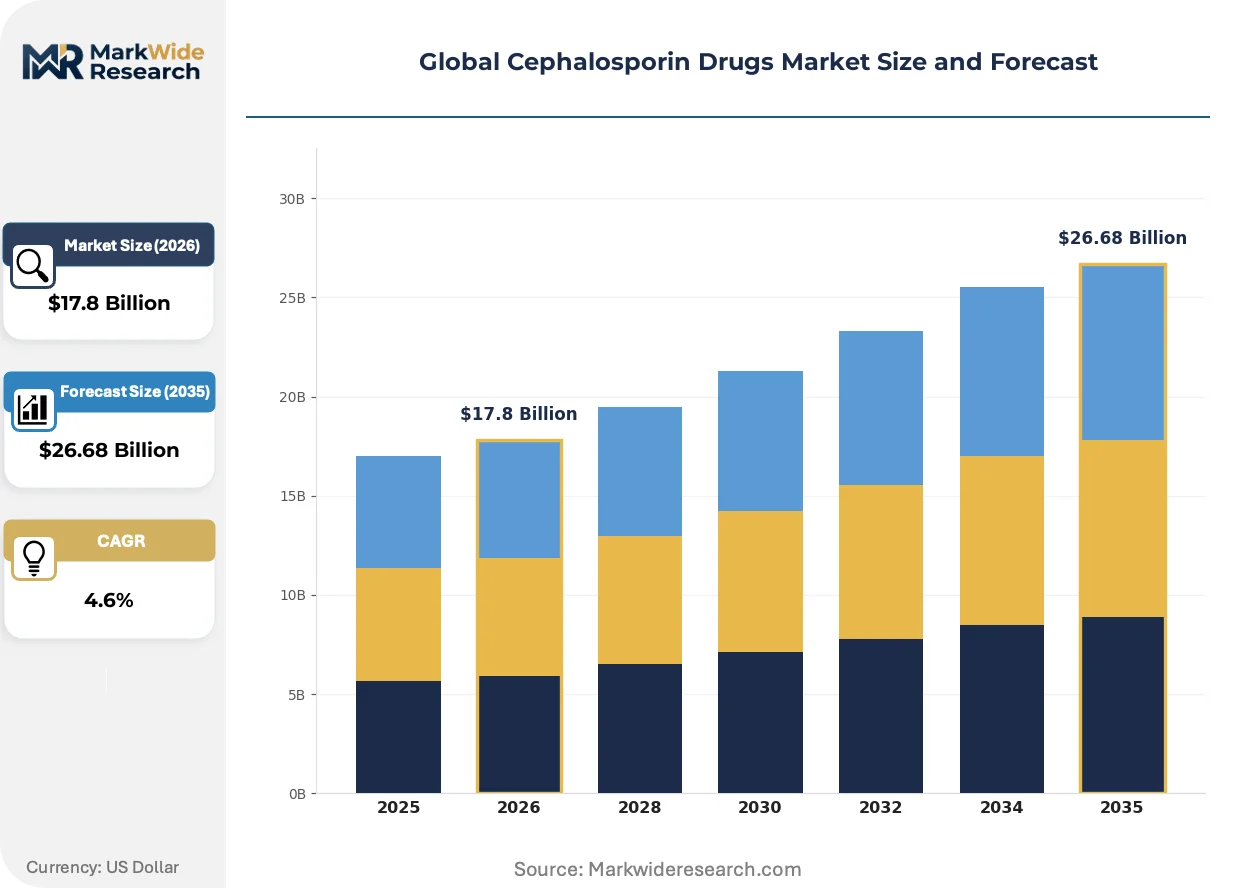
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $26.68 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cefalexin, Cefuroxime, Ceftriaxone, Cefepime Formulation: Tablets, Capsules, Injectable, Liquid Indication: Pneumonia, Urinary Tract Infection, Skin Infections, Otitis Media Distribution Channel: Pharmacies, Hospitals, Online Pharmacies, Clinics |
| Companies Covered | Lupin Limited, Sun Pharmaceutical Industries Limited, Pfizer Inc, Abbott Laboratories, Bristol-Myers Squibb Company, GlaxoSmithKline plc, Teva Pharmaceutical Industries Ltd., Novartis International AG, Merck & Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cephalosporin Drugs Market Shifts & Advancements
Digital integration of susceptibility testing with stewardship decision support is compressing the gap between diagnostic result and therapeutic action, reshaping how cephalosporin value is captured.
Artificial intelligence-guided molecular design platforms are virtualizing early-stage side-chain optimization, replacing empirical structure-activity relationship screening with predictive binding affinity modeling. Large generic manufacturers with captive API operations are deploying these tools to accelerate next-generation beta-lactamase inhibitor pairing. The technology is virtualizing traditional medicinal chemistry timelines, compressing preclinical candidate selection from 18 months to sub-6 month cycles.
EMA's revised Good Manufacturing Practice Annex 1 requirements for sterile medicinal products are mandating continuous environmental monitoring with automated alert systems for Grade A filling zones. Manufacturers must retrofit legacy isolator lines with real-time particle and viable monitoring infrastructure. The injectable cephalosporin segment faces the steepest compliance burden, with German and Italian facilities leading facility reinvestment.
Hospital procurement consortia are consolidating antibiotic purchasing through centralized therapeutic class committees, displacing individual physician preference as the primary formulary determinant. Integrated delivery networks in the US and hospital groups in France are extracting outcome guarantees and resistance surveillance commitments from suppliers. This behavioral shift is most pronounced in academic medical centers with active stewardship programs and dedicated infectious disease pharmacy leadership.
Global Cephalosporin Drugs Market Segmentation
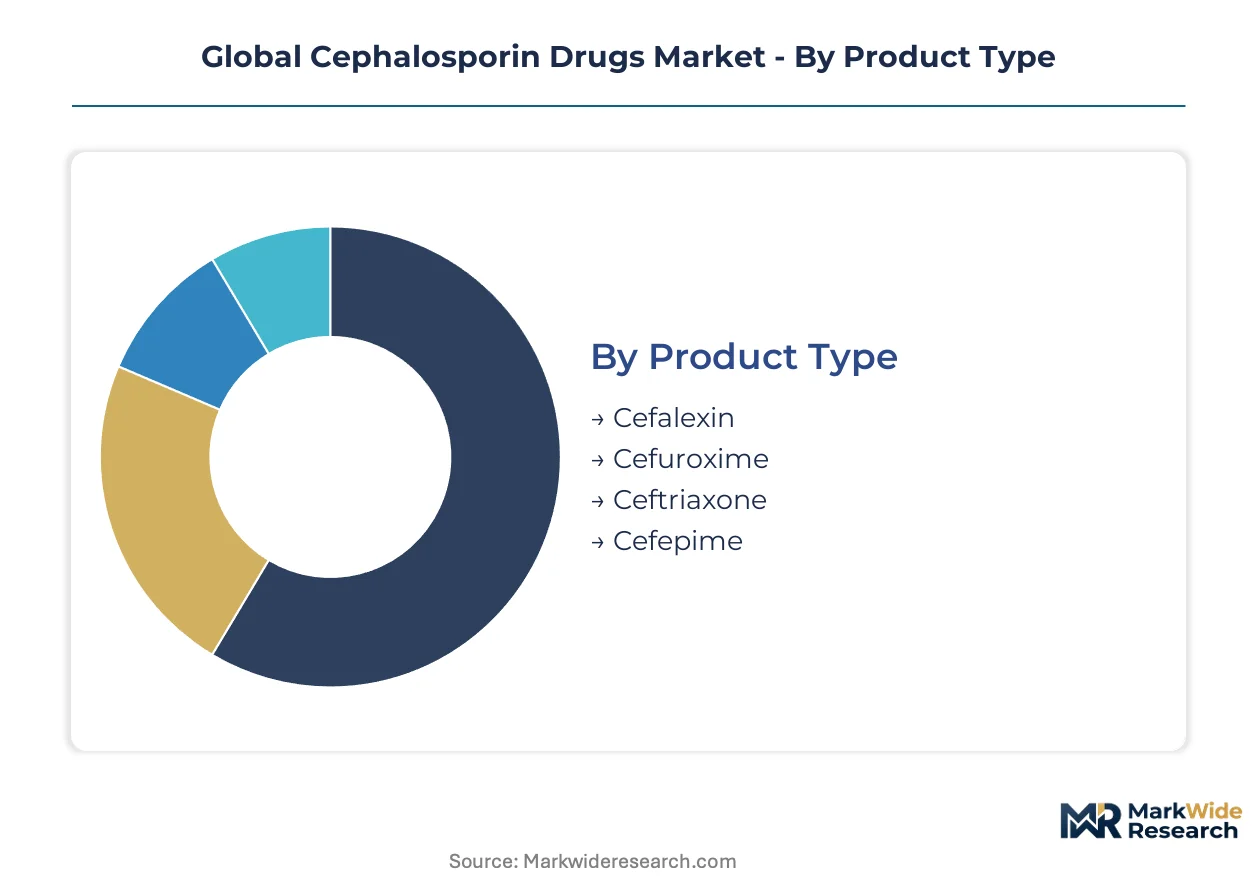
Segmentation in cephalosporin drugs determines where manufacturers invest sterile capacity versus oral solid lines. Each dimension carries distinct margin profiles, regulatory burdens, and after-sales service intensity requirements that shape competitive positioning.
Product Type:
After-sales service intensity varies sharply across cephalosporin generations, with fourth-generation agents requiring stewardship consulting and resistance surveillance support that first-generation oral products rarely demand.
- Cefepime:A fourth-generation cephalosporin with enhanced beta-lactamase stability and Pseudomonas aeruginosa coverage. Demand concentrates in US academic medical centers and German tertiary hospitals where carbapenem-sparing protocols are tightening; FDA antimicrobial stewardship mandates require documented susceptibility testing before release, expanding companion diagnostic attach rates.
- Ceftriaxone:A third-generation agent with extended half-life enabling once-daily dosing. Outpatient infusion centers in France and transition-of-care protocols in India are pulling volume; CDSCO batch-release testing governs export eligibility to regulated markets, adding documentation overhead.
- Cefuroxime:A second-generation cephalosporin with oral and parenteral forms used for community-acquired respiratory infections.
- Cefalexin:A first-generation oral agent prescribed for uncomplicated skin and urinary tract infections in primary care settings.
By volume, ceftriaxone leads. By growth pace, cefepime is ahead.
Formulation:
Cost tier stratification in cephalosporin manufacturing separates commodity oral solids from capital-intensive sterile injectables with dedicated beta-lactam facility requirements.
- Injectable:Sterile fill-finish formulations for hospital parenteral therapy. Tertiary care centers in Italy and Brazil are consolidating procurement around ISO 5 aseptic products; EMA Annex 1 revisions mandate continuous environmental monitoring, forcing German facility reinvestment.
- Tablets:Oral solid dosage forms for outpatient community infections. Indian domestic manufacturing under PLI scheme incentives is expanding capacity; CDSCO oversight of 7-ACA intermediate sourcing affects margin predictability.
- Capsules:Oral cephalosporin delivery with modified release profiles for pediatric and geriatric compliance.
- Liquid:Suspension formulations for pediatric populations and patients with swallowing difficulties.
Injectable commands premium pricing. Tablets dominate unit volume.
Indication:
Application-specific demand patterns determine whether cephalosporin procurement flows through hospital formularies with stewardship oversight or retail pharmacy channels with fewer controls.
- Pneumonia:Community-acquired and nosocomial lung infections requiring broad-spectrum coverage. ICU protocols in Spain and Japan are prioritizing cefepime where Pseudomonas resistance thresholds trigger carbapenem-sparing algorithms.
- Urinary Tract Infection:Uncomplicated and complicated infections across outpatient and inpatient settings. Resistance surveillance from ECDC is compressing product lifecycles for oral agents in France and Germany.
- Skin Infections:Cellulitis and soft tissue infections treated across primary care and emergency departments.
- Otitis Media:Pediatric middle ear infections driving liquid formulation demand with seasonal volume spikes.
Pneumonia generates the highest per-patient revenue. Skin infections represent the largest addressable patient pool.
Distribution Channel:
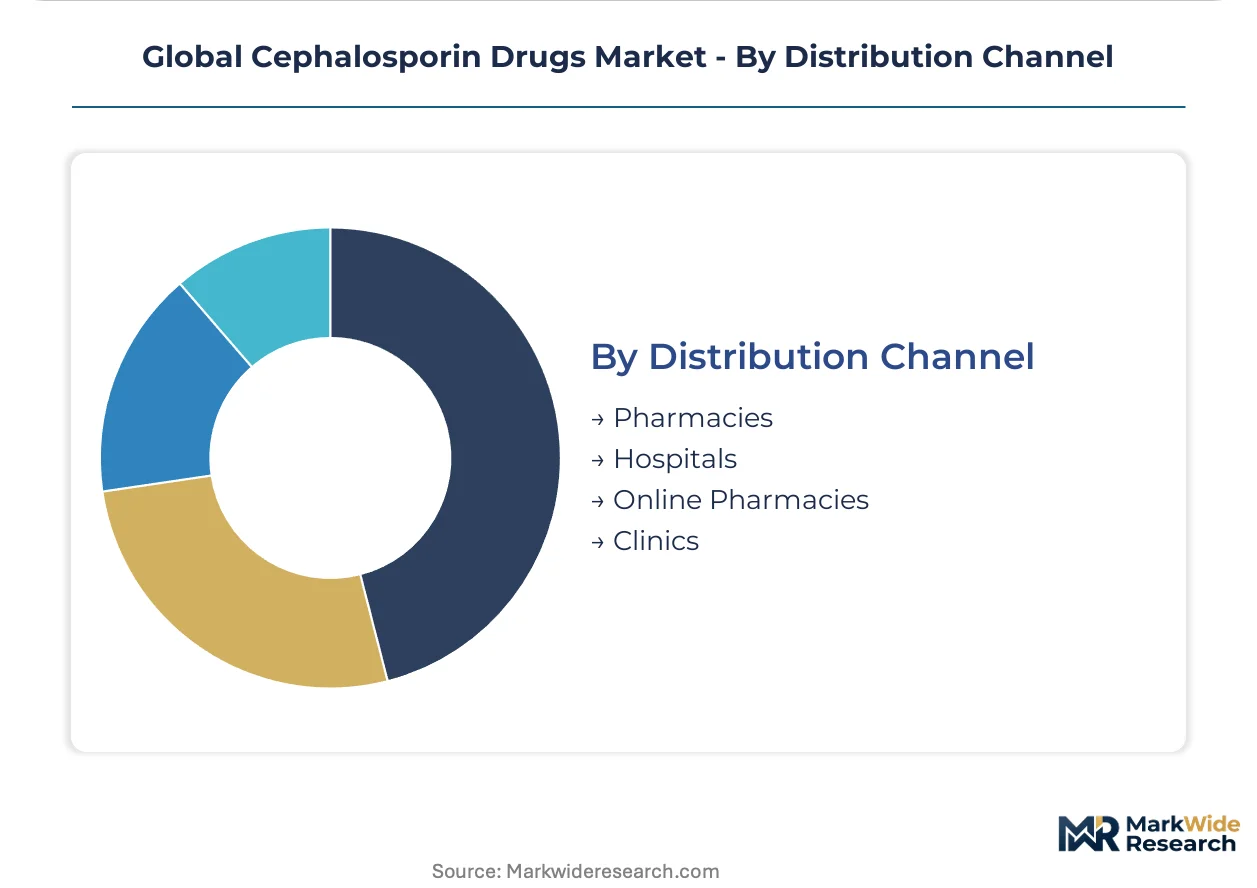
Customer type concentration is reshaping cephalosporin access, with hospital procurement consortia extracting outcome guarantees that retail channels rarely impose.
- Hospitals:Institutional procurement through therapeutic class committees with antimicrobial stewardship oversight. Integrated delivery networks in the US are consolidating antibiotic purchasing and demanding resistance surveillance commitments from suppliers.
- Pharmacies:Retail dispensing of oral cephalosporins for outpatient infections. Indian government-backed essential medicine programs are expanding access through Jan Aushadhi outlets.
- Online Pharmacies:Digital channels with cold-chain requirements for temperature-sensitive liquid formulations.
- Clinics:Ambulatory care settings with limited formulary control and higher physician discretion.
Hospitals anchor value capture. Online pharmacies are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity for 7-ACA intermediates clusters in India and China, while sterile fill-finish operations concentrate in Germany, Italy, and the United States. Hospital procurement consolidation and antimicrobial stewardship mandates are reshaping demand geography.
United States
Academic medical centers in Boston and Baltimore are tightening carbapenem-sparing protocols, expanding cefepime utilization in ICU settings. FDA antimicrobial stewardship mandates require documented susceptibility testing before broad-spectrum release. New Jersey and North Carolina host the principal sterile injectable manufacturing clusters serving hospital procurement consortia.
Germany
Tertiary hospitals in Munich and Berlin are consolidating antibiotic purchasing through therapeutic class committees with resistance surveillance requirements. EMA Annex 1 revisions mandate continuous environmental monitoring for Grade A filling zones. Hesse and Bavaria lead facility reinvestment for ISO 5 aseptic cephalosporin production.
India
Domestic API manufacturing under CDSCO oversight is reducing import dependency for regulated markets. Government-backed essential medicine programs through Jan Aushadhi outlets are expanding outpatient access. Maharashtra and Gujarat anchor fermentation and acylation capacity for 7-ACA intermediate supply.
Italy
Tertiary care centers in Milan and Rome are consolidating procurement around parenteral therapy for nosocomial pneumonia. EMA sterile manufacturing requirements are forcing retrofit of legacy isolator lines with real-time monitoring infrastructure. Lombardy facilities lead reinvestment in beta-lactam dedicated production lines.
Japan
ICU protocols in Tokyo and Osaka academic centers prioritize cefepime where Pseudomonas resistance thresholds trigger carbapenem-sparing algorithms. PMDA oversight governs batch-release testing for export eligibility. Kanto region hosts the principal sterile injectable manufacturing serving domestic hospital procurement.
Global Cephalosporin Drugs Market Competitive Landscape
Integrated pharmaceutical conglomerates and API-anchored generic specialists split the market into distinct capability tiers. Hospital channel infrastructure and backward integration into fermentation capacity represent the primary competitive moats. Three archetypes dominate: multinational innovators with stewardship consulting services, Indian API-integrated generic manufacturers, and cost-focused high-volume injectable producers. Consolidation around sterile capacity and antimicrobial susceptibility testing partnerships are reshaping positioning.
Within the multinational tier, Pfizer Inc and GlaxoSmithKline plc exemplify hospital channel dominance with formulary positioning across major health systems. Sun Pharmaceutical Industries Limited anchors the API-integrated archetype through Maharashtra-based fermentation capacity. Teva Pharmaceutical Industries Ltd. occupies the high-volume generic position with Eastern European and Latin American injectable facilities.
| Leading Market Players |
|---|
| Lupin Limited |
| Sun Pharmaceutical Industries Limited |
| Pfizer Inc |
| Abbott Laboratories |
| Bristol-Myers Squibb Company |
| GlaxoSmithKline plc |
| Teva Pharmaceutical Industries Ltd. |
| Novartis International AG |
| Merck & Co. Inc. |
| Others |
Supply & Pricing Matrix
Chinese environmental enforcement cycles governing 7-ACA and 7-ADCA intermediate production directly determine margin predictability for semisynthetic cephalosporin manufacturers downstream. Hospital procurement consortia extract outcome guarantees that compress pricing power toward sterile injectable specialists with captive API operations.
Pricing Analysis
Stewardship consulting and antimicrobial susceptibility testing services generate lifetime value exceeding molecule sales alone. Three-tier pricing structure across premium fourth-generation agents, standard third-generation formulations, and economy oral generics separates hospital-critical injectables from commodity tablets. Pricing pressure stems from carbapenem substitution in ICU protocols where Pseudomonas resistance thresholds trigger institutional formulary shifts. Generic injectable manufacturers compete most aggressively on unit cost, while innovators with companion diagnostic platforms command premium positioning.
Supply Chain Analysis
Tariff exposure between India and regulated markets in Europe and North America dominates supply chain risk planning for API-integrated manufacturers. Fermentation and acylation capacity concentrates in India, China, and Italy, with sterile fill-finish operations clustering in Germany, the United States, and Japan. Raw material dependencies rest on 7-ACA intermediates, specialized fermentation media, and beta-lactamase inhibitor compounds. Single-source vulnerability in Chinese environmental compliance enforcement disrupts intermediate pricing predictability. Distribution runs through hospital procurement consortia, government essential medicine programs, and multilateral procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from stewardship consulting and resistance surveillance partnerships expands faster than molecule sales, repositioning competitive advantage around clinical outcome guarantees rather than unit volume alone.
For Market Incumbents: Harden formulary positioning through backward integration into 7-ACA fermentation capacity under CDSCO oversight. Expand sterile fill-finish footprints in Germany and Italy ahead of EMA Annex 1 compliance deadlines. Carbapenem substitution in ICU protocols threatens extended-spectrum cephalosporin volume; defend through beta-lactamase inhibitor combination pipelines and susceptibility testing platform partnerships. For New Entrants and Emerging Players: Sub-Saharan Africa access expansion offers the most penetrable geographic white space, with WHO prequalification pathways opening multilateral procurement previously blocked by documentation gaps. Target outpatient infusion center partnerships for transition-of-care protocols in France and India. Pursue fixed-dose combination approvals with simplified batch-release documentation to accelerate market entry. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed generic injectable specialists in Eastern Europe and Latin America lacking stewardship service capabilities. Five-to-ten year viability hinges on antimicrobial resistance surveillance integration and novel combination therapy pipelines. Watch FDA antimicrobial stewardship mandate enforcement intensity as the signal for formulary shift velocity and pricing power compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Fermentation | Captive 7-ACA supply insulates margin predictability from Chinese environmental enforcement volatility. |
| Stewardship Consulting Service Launch | Companion diagnostic attach rates expand lifetime value beyond molecule sales in US academic medical centers. |
| Beta-Lactamase Inhibitor Combination Development | Novel pairings defend against carbapenem substitution in ICU protocols with Pseudomonas resistance thresholds. |
| EMA Annex 1 Facility Reinvestment | Continuous environmental monitoring infrastructure qualifies German and Italian sites for premium hospital procurement. |
| WHO Prequalification Pathway Pursuit | Fixed-dose ceftriaxone combinations unlock multilateral procurement channels in Sub-Saharan Africa. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors informed demand-side assumptions. Secondary validation drew from CDC resistance surveillance reports, CDSCO batch-release documentation, and WHO prequalification records. Bottom-up patient-flow modeling and top-down pharmaceutical market sizing were cross-referenced for triangulation.
Forecast inputs include antimicrobial resistance surveillance trajectories, regulatory enforcement intensity across FDA and EMA jurisdictions, and hospital procurement consolidation patterns. Segmentation dimensions span generation type, formulation route, indication severity, and regional regulatory cluster. CAGRs were derived from volume-demand modeling against sterile capacity expansion timelines. Pricing assumptions incorporate stewardship service attach rates and generic substitution pressures.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Indian API-integrated manufacturers or accelerated carbapenem-sparing protocol adoption would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Pharma Grade Ibuprofen API Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
Rizatriptan Market
Pharmaceutical Ingredients
United Kingdom Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Pharma Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
US Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Penciclovir API Market
Pharmaceutical Ingredients
Large Molecule Drug Substance CDMO Market
Pharmaceutical Ingredients
Kitasamycin Market
Pharmaceutical Ingredients
Furosemide Market
Pharmaceutical Ingredients
Nuclear Export Inhibitor Drugs Market
Pharmaceutical Ingredients
Sterile Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Pharmaceutical Grade Sodium Carbonate Market
Pharmaceutical Ingredients
Albumin (As Excipient) Market
Pharmaceutical Ingredients
Saudi Arabia Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Anti-Allergic Agent Ingredients Market