
 Transdermal Drugs Market | 2026-2036
Transdermal Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Transdermal Drugs Market Analytics
Modular patch formats that separate drug reservoirs from adhesive layers is pivoting how clinicians select transdermal therapies for chronic conditions. Novartis AG leverages its neuroscience portfolio to sustain leadership in pain management patches across European hospital networks. Johnson & Johnson anchors its position through consumer-facing distribution of over-the-counter transdermal products in North American retail pharmacies. Hisamitsu Pharmaceutical Co., Inc dominates microneedle innovation with specialized manufacturing assets in Japan.
Transdermal drugs are pharmaceutical formulations designed for percutaneous absorption, typically achieving bioavailability through skin layers at rates between 0.5 and 5000 Daltons molecular weight, serving primarily to bypass hepatic first-pass metabolism and improve patient compliance for chronic therapies. The patch segment leads value generation due to extended-release formulations commanding premium reimbursement, while microneedle delivery systems represent the fastest-expanding category as manufacturers resolve scale-up challenges for biologic permeation. Pain management occupies the largest therapy area share, though hormonal therapy patches retain durable margins through established gynecological prescribing patterns.
The FDA oversees abbreviated new drug applications for transdermal generics, while the EMA enforces quality guidelines through its Committee for Medicinal Products for Human Use, and Japan's PMDA evaluates Q1/Q2 sameness for patch bioequivalence. These frameworks determine market access timelines and manufacturing inspection intensity for foreign suppliers entering regulated jurisdictions. Stakeholders must monitor evolving bioequivalence standards for complex generics as regulatory science for transdermal absorption modeling advances.
Market Dynamics
Modular patch architectures are separating drug reservoirs from adhesive substrates, forcing manufacturers to retool production lines and renegotiate raw material contracts across polymer supply chains.
Growth Catalysts
- FDA ANDA Pathway:The abbreviated new drug application framework accelerates generic transdermal entry, compressing development timelines for complex patch formulations and expanding therapeutic access.
- Home Care Migration:Chronic pain patients in the United States increasingly receive patch-based therapy outside clinical settings, reducing hospital readmission costs and extending prescription durations.
- Microneedle Manufacturing Scale-Up:Specialized Japanese production assets are resolving biologic permeation barriers, enabling peptide and protein delivery through dissolvable microprojections.
Market Restraints
- Acrylic Adhesive Volatility:Petrochemical feedstock fluctuations for pressure-sensitive adhesives compress gross margins during crude price spikes, particularly affecting extended-wear pain patches.
- Japanese Supply Concentration:Microneedle substrate fabrication depends on a limited cluster of precision-tooling facilities in Kyushu, creating single-source vulnerability for biologic patch developers.
- Skin Permeation Ceiling:The 500 Dalton molecular weight barrier excludes most monoclonal antibodies from passive transdermal routes, restricting addressable therapeutic categories.
Strategic Opportunities
- Pediatric Neurodevelopmental Applications:Attention-deficit disorder patches remain underdeveloped in the United States, where oral stimulant noncompliance drives caregiver demand for alternative delivery.
- EMA Orphan Designation Incentives:Reduced regulatory fees and protocol assistance for rare disease transdermal formulations attract development investment in hormone replacement for niche genetic conditions.
- Direct-to-Patient Subscription Models:Telehealth platforms in Germany are integrating automatic patch replenishment, bypassing traditional pharmacy distribution for chronic hormonal therapy.
Industry Challenges
- Bioequivalence Modeling Talent Scarcity:The FDA's advancing in-vitro permeation test standards require specialized pharmacokinetic modelers, creating recruitment bottlenecks for generic developers.
- Legacy Equipment Retrofit Costs:Conventional solvent-casting lines require seven-figure capital expenditure to produce reservoir-type patches, straining mid-tier contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transdermal Drugs Market |
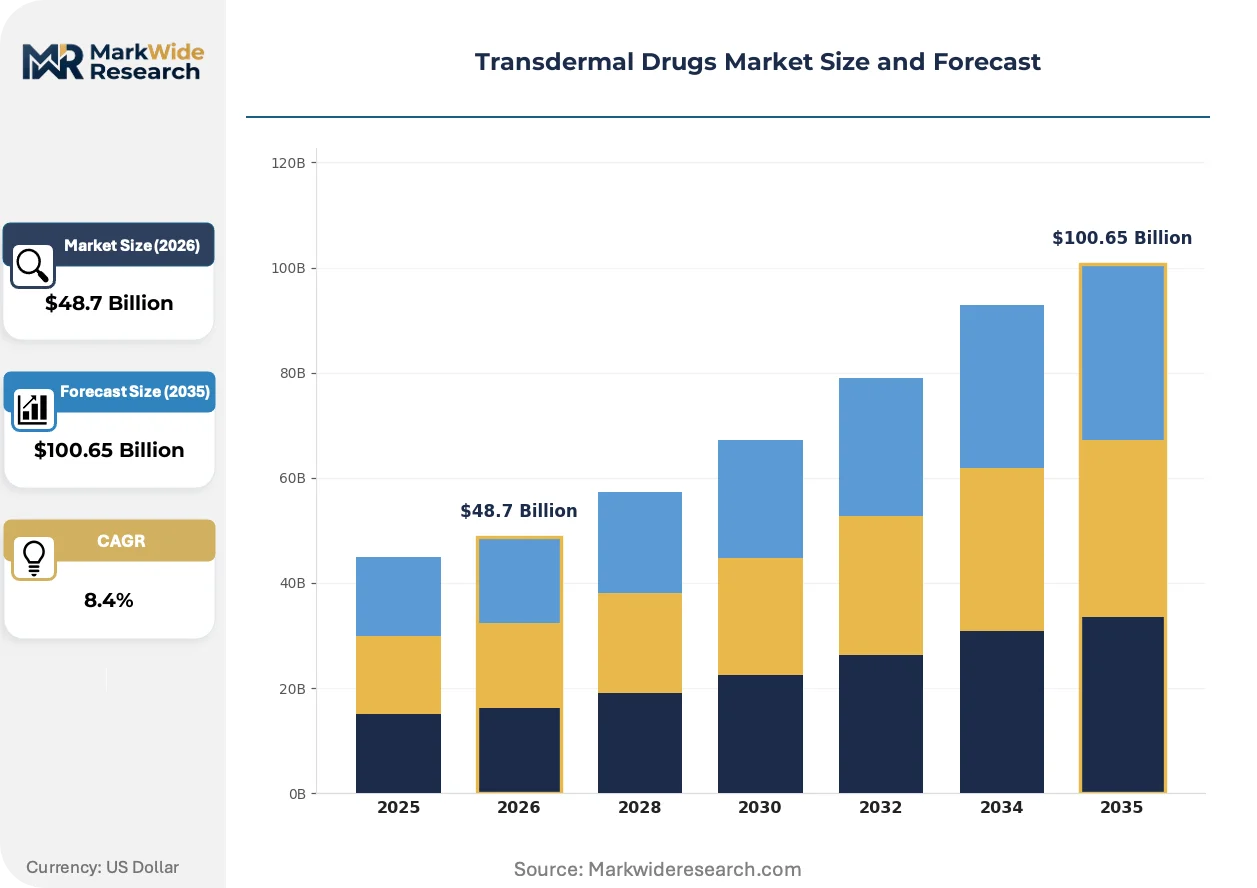
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Patch, Gel, Cream, Spray Therapy Area: Pain Management, Hormonal Therapy, Smoking Cessation, Cardiovascular Therapy End User: Hospitals, Clinics, Home Care, Pharmacies Delivery Mode: Transdermal Patch, Microneedles, Iontophoresis, Thermal Patching |
| Companies Covered | Novartis AG, Johnson & Johnson, Teva Pharmaceutical Industries Ltd, Viatris Inc, Hisamitsu Pharmaceutical Co., Inc, 3M Company, Boehringer Ingelheim GmbH, Teikoku Pharma, Luye Pharma Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transdermal Drugs Market Evolving Landscape
Active pharmaceutical ingredient solubility engineering and adhesive polymer science are converging to expand the molecular weight window for transdermal absorption, reshaping which therapeutic classes become patch-viable.
Iontophoretic delivery systems are integrating electronic control modules with traditional patch formats, enabling programmable dose titration for breakthrough pain episodes. Hospital pain management services in the United States are piloting these devices for post-surgical recovery, where patient-controlled activation reduces nursing burden. The technology is integrating real-time feedback loops that adjust current density based on skin impedance, compressing the gap between passive patches and intravenous patient-controlled analgesia.
Japan's PMDA revised its Q1/Q2 sameness criteria for patch bioequivalence in 2023, tightening specifications for adhesive mass and release liner configuration. Foreign manufacturers must now submit additional in-vitro dissolution profiles and local clinical bridging studies, extending approval timelines by 12-18 months. European generic developers targeting Japanese market entry are responding by establishing captive analytical laboratories in Osaka to preempt regulatory queries.
Chronic disease patients are consolidating prescription fulfillment through specialty pharmacies that offer adherence monitoring and automatic refill synchronization. This channel shift in the United States displaces traditional retail pharmacy relationships for hormonal and cardiovascular patches, concentrating purchasing power among three national distributors. The behavioral change is most visible in Medicare Part D populations, where medication therapy management programs incentivize patch selection over oral equivalents through reduced copay tiers.
Transdermal Drugs Market Segmentation
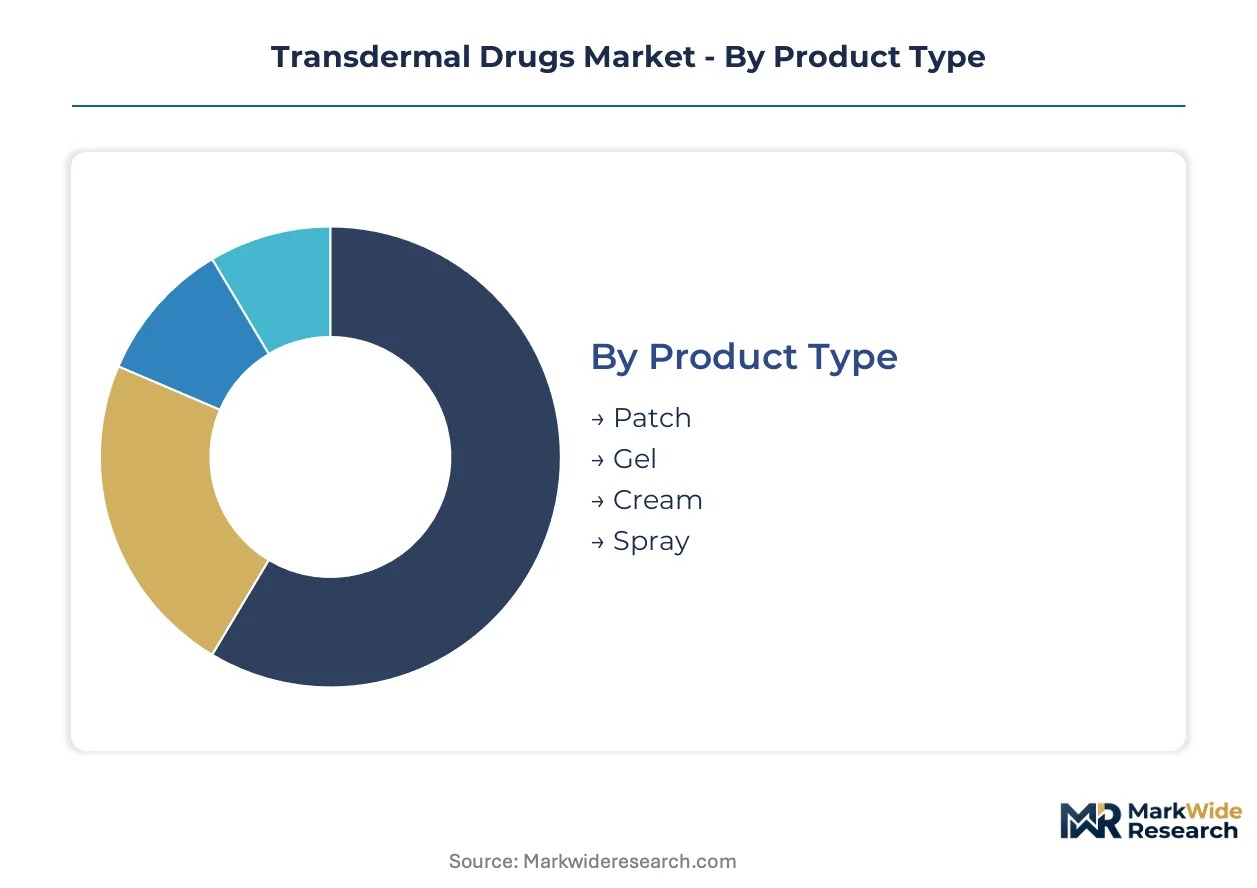
Transdermal drug segmentation reveals how formulation architecture, clinical setting, and molecular delivery constraints partition commercial opportunity. Manufacturers configure R&D pipelines around therapy-specific permeation challenges rather than pursuing universal platform technologies.
Product Type:
Formulation selection tracks patient mobility requirements and dosing frequency tolerance across chronic conditions.
- Patch:Reservoir or matrix designs with multi-day wear capability dominate extended-release pain management. United States Medicare Part D plans favor 7-day fentanyl and buprenorphine patches for opioid rotation protocols, compressing pharmacy visit frequency for homebound elderly patients.
- Gel:Testosterone and estrogen gels penetrate through stratum corneum disruption without occlusive backing. Compounding pharmacies in Germany customize gel concentrations for individualized hormone replacement, bypassing standardized patch dosing limitations.
- Cream:Topical NSAID formulations target localized musculoskeletal inflammation with minimal systemic absorption.
- Spray:Metered-dose nicotine sprays serve acute craving interruption with faster onset than patches.
Volume sits with Patch; growth tilts toward Gel.
Therapy Area:
Reimbursement intensity and prescriber specialty concentration determine which therapeutic categories sustain premium pricing.
- Pain Management:Opioid and non-opioid patches for chronic back pain and cancer breakthrough episodes anchor hospital formularies. Anesthesiology departments in United States academic medical centers specify reservoir-type fentanyl patches for post-discharge continuity, reducing readmission risk in spine surgery populations.
- Hormonal Therapy:Estrogen-progestin combinations and testosterone replacement sustain durable margins through gynecological and urological prescribing loyalty. Japanese endocrinology clinics favor low-dose estradiol patches for menopausal symptom management, reflecting PMDA bioequivalence tolerance for narrow therapeutic index hormones.
- Smoking Cessation:Nicotine replacement patches compete with vaping products for behavioral modification market share.
- Cardiovascular Therapy:Nitroglycerin patches for angina prophylaxis face generic erosion in European markets.
Revenue concentrates in Pain Management; pipeline investment flows toward Hormonal Therapy.
End User:
Site-of-care economics and nursing labor availability reshape which delivery formats gain formulary placement.
- Home Care:Family caregivers administer patch-based therapies for dementia patients with oral medication resistance. United States home health agencies stock fentanyl and rivastigmine patches in automated medication dispensers, reducing skilled nursing visit frequency for rural Medicare beneficiaries.
- Hospitals:Acute care settings prioritize iontophoretic and patient-controlled patch systems for post-surgical analgesia. Surgical wards in German university hospitals pilot programmable lidocaine patches for orthopedic recovery, integrating with electronic health record pain documentation workflows.
- Clinics:Outpatient pain centers manage opioid rotation and dose titration through patch protocols.
- Pharmacies:Retail dispensing concentrates on smoking cessation and over-the-counter hormonal products.
Prescription volume clusters in Home Care; technology upgrade cycles favor Hospitals.
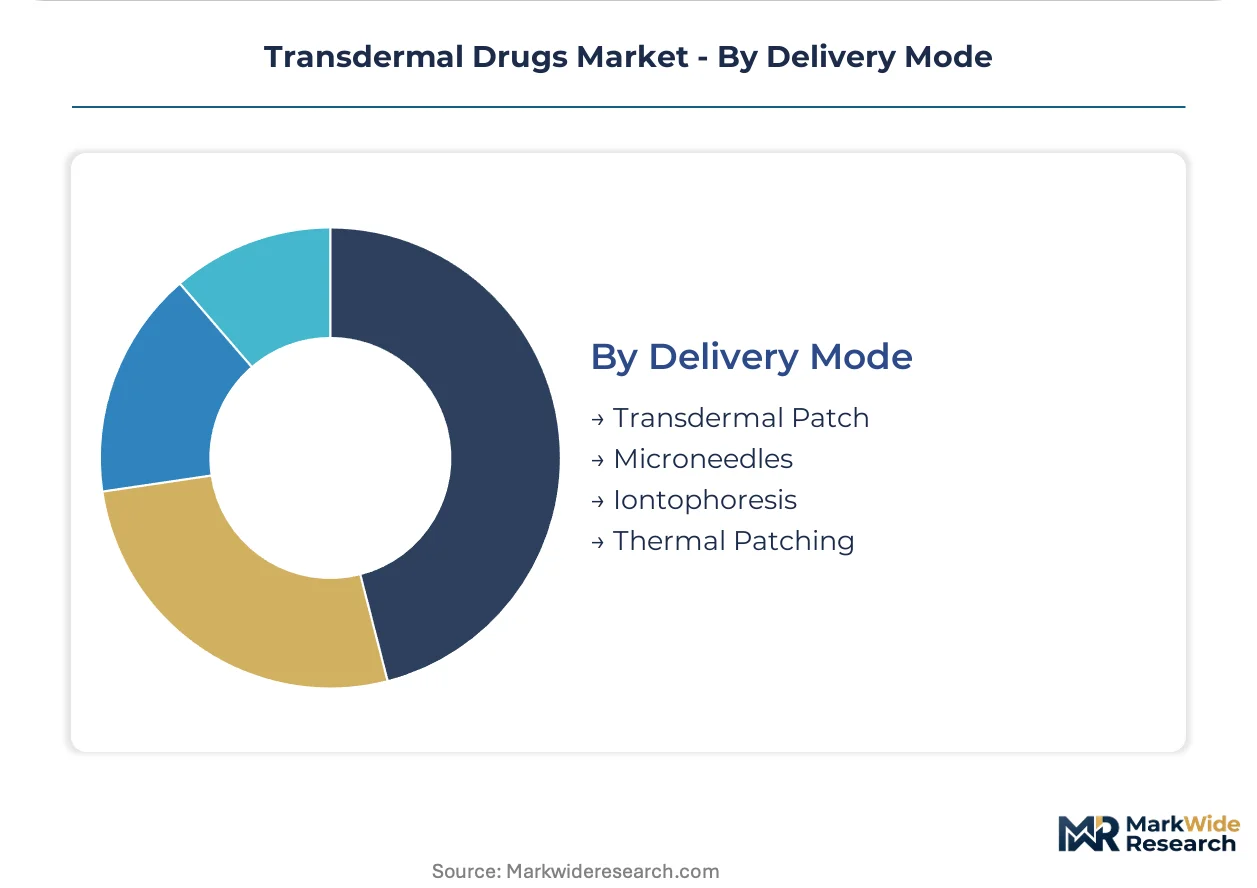
Delivery Mode:
Permeation enhancement technology selection depends on molecular weight barriers and biologic stability requirements.
- Transdermal Patch:Passive diffusion through intact skin serves small-molecule drugs under 500 Daltons. Japanese precision polymer manufacturers supply acrylate adhesive substrates to European generic developers, leveraging PMDA-certified bioequivalence data packages for abbreviated new drug applications.
- Microneedles:Dissolvable microprojections breach stratum corneum for peptide and protein delivery. Kyushu-based fabrication facilities produce titanium master molds for biologic patch developers, resolving scale-up barriers that previously limited influenza vaccine microneedle commercialization.
- Iontophoresis:Electrically assisted delivery enables programmable dose adjustment for breakthrough pain.
- Thermal Patching:Heat-enhanced permeation accelerates NSAID absorption for acute injury management.
Commercial maturity rests with Transdermal Patch; capability investment rushes toward Microneedles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan concentrates precision microneedle fabrication while the United States absorbs the highest prescription volumes for chronic pain patches. European generic developers source adhesive substrates from East Asian suppliers, creating interdependence between manufacturing clusters and consumption markets.
United States
Medicare Part D plans favor seven-day fentanyl patches for homebound elderly patients, compressing pharmacy visit frequency. The FDA's abbreviated new drug application pathway accelerates generic transdermal entry. Home health agencies in rural Texas and Florida stock automated medication dispensers with buprenorphine and rivastigmine patches, reducing skilled nursing visit burdens.
Japan
PMDA bioequivalence tolerance for narrow therapeutic index hormones sustains low-dose estradiol patch prescribing in endocrinology clinics. Kyushu-based fabrication facilities produce titanium master molds for biologic microneedle developers. Osaka laboratories now preempt regulatory queries from European generic developers targeting Japanese market entry.
Germany
Telehealth platforms integrate automatic patch replenishment for chronic hormonal therapy, bypassing traditional pharmacy distribution. EMA orphan designation incentives attract development investment in rare disease transdermal formulations. Surgical wards in Munich and Berlin pilot programmable lidocaine patches integrated with electronic health record pain documentation workflows.
China
Domestic manufacturers expand reservoir-type patch production capacity to serve aging populations with cardiovascular and pain management needs. The national pharmaceutical regulator evaluates bioequivalence standards for complex generic transdermals. Yangtze River Delta polymer suppliers retool production lines to meet modular patch architecture demands from European contract manufacturers.
Switzerland
Swissmedic oversight of biologic patch stability requirements shapes development timelines for peptide delivery systems. Basel-based research clusters advance iontophoretic control modules for programmable dose titration. Precision polymer science firms in the Lake Geneva region engineer adhesive substrates that expand the molecular weight window for transdermal absorption.
Transdermal Drugs Market Competitive Landscape
The competitive structure tilts toward diversified pharmaceutical conglomerates with established pain management portfolios. Mid-tier specialists concentrate microneedle fabrication capabilities in Japanese industrial clusters. Three archetypes dominate: neuroscience-focused multinationals, consumer health divisions with retail pharmacy penetration, and precision manufacturing specialists with captive adhesive supply. Capacity expansion and technology licensing represent the dominant competitive moves as manufacturers resolve scale-up barriers for biologic permeation.
Within the diversified pharmaceutical tier, Novartis AG and Johnson & Johnson exemplify contrasting positioning strategies. Novartis occupies a position anchored in hospital network formularies across European markets, while Johnson & Johnson exemplifies consumer-facing distribution dominance in North American retail channels. Hisamitsu Pharmaceutical Co., Inc represents the precision manufacturing archetype, with Japanese production assets serving as a reference point for microneedle innovation. Teva Pharmaceutical Industries Ltd and Viatris Inc sit within the generic developer tier, navigating FDA abbreviated new drug application pathways to compress development timelines for complex patch formulations.
| Leading Market Players |
|---|
| Novartis AG |
| Johnson & Johnson |
| Teva Pharmaceutical Industries Ltd |
| Viatris Inc |
| Hisamitsu Pharmaceutical Co., Inc |
| 3M Company |
| Boehringer Ingelheim GmbH |
| Teikoku Pharma |
| Luye Pharma Group |
| Others |
Value Network & Pricing Analysis
Specialized pharmacokinetic modelers in Boston and Basel command wage premiums that widen spreads between premium reservoir-patch developers and economy-tier matrix-patch suppliers. Labor-cost differentials in regulatory science talent pools directly stratify pricing tiers across the transdermal market.
Pricing Analysis
Margin tightening in economy-tier matrix patches reflects acrylic adhesive feedstock volatility and Japanese substrate import dependency. Three-tier pricing structure across premium reservoir, standard matrix, and economy adhesive-limited tiers separates developers by bioequivalence certification depth and FDA submission track record. Cost-down pressure on standard-tier products accelerates because Medicare Part D plans consolidate purchasing through specialty pharmacy networks. Hospital formularies exhibit lowest price sensitivity due to clinical workflow integration, while retail smoking cessation patches face acute sensitivity to vaping product substitution.
Supply Chain Analysis
Regional distribution centers in Osaka and Rotterdam consolidate precision polymer inventory for just-in-time delivery to European contract manufacturers. Kyushu-based fabrication facilities in Japan, Yangtze River Delta polymer suppliers in China, and Basel-area adhesive formulators in Switzerland anchor upstream concentration. Raw material dependencies center on acrylate monomers, release liner films, and titanium master molds for microneedle arrays. Single-source vulnerability in Japanese precision-tooling facilities creates structural risk for biologic patch developers. Distribution runs through captive analytical laboratories established by foreign manufacturers seeking PMDA market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's advancing in-vitro permeation test standards erect a cost-of-compliance barrier that entrenches incumbents with established bioequivalence modeling capabilities while screening out undercapitalized generic entrants.
For Market Incumbents: Anchor hospital formulary positions through iontophoretic device integration with electronic health record workflows, defending against programmable patch substitutes. Deepen backward integration into adhesive polymer supply through Osaka laboratory partnerships, preempting PMDA regulatory queries that delay Japanese market entry. For New Entrants and Emerging Players: Pediatric neurodevelopmental applications in United States attention-deficit disorder therapy represent an underserved buyer archetype with caregiver-driven demand for non-oral alternatives. Direct-to-patient subscription models through telehealth platforms offer a go-to-market angle that bypasses consolidated specialty pharmacy purchasing power. For Investors and Strategic Acquirers: Re-rating potential sits with precision manufacturing specialists given microneedle scale-up resolution for biologic permeation. Long-term viability favors assets with captive Kyushu fabrication relationships and PMDA-certified bioequivalence data packages. The signal to watch is EMA orphan designation uptake for rare disease hormonal patches.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Bioequivalence Certification | Osaka laboratory establishment preempts 12-18 month approval timeline extensions for European entrants. |
| Microneedle Manufacturing Scale-Up | Kyushu titanium master mold production resolves biologic permeation barriers for peptide delivery. |
| Hospital System Partnership | Iontophoretic device integration with EHR pain documentation workflows secures post-surgical formulary placement. |
| Direct-to-Patient Subscription Launch | Telehealth platform integration bypasses consolidated specialty pharmacy purchasing in German hormonal therapy. |
| Regulatory Affairs Talent Acquisition | Boston and Basel pharmacokinetic modeler recruitment compresses FDA abbreviated new drug application development timelines. |
Research Methodology
Independent corroboration across FDA abbreviated new drug application filings, EMA quality guideline documentation, and PMDA Q1/Q2 sameness criteria underwrites the qualitative findings. Primary interviews with regulatory affairs leads, formulary directors at United States academic medical centers, and microneedle fabrication engineers in Kyushu combined with secondary validation from ClinicalTrials.gov, SEC 10-K pharmaceutical disclosures, and Japanese Ministry of Health patent filings. Bottom-up prescription volume modeling and top-down therapy-area expenditure analysis triangulate market sizing.
Rate-of-change decomposition across the analysis window segments volume and value by product architecture, therapy area concentration, end-user site-of-care economics, and delivery mode permeation technology. CAGRs derive from patient population growth, patent expiration schedules, and regulatory pathway acceleration effects. Forecast inputs include Medicare Part D formulary placement trends and PMDA bioequivalence standard evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to microneedle manufacturing yield improvements and acrylic adhesive petrochemical price volatility. Base assumptions reflect FDA generic approval velocity, EMA orphan designation incentive utilization, and Japanese supply cluster resilience. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Oxycodone Drugs Market
Pharmaceutical Ingredients
Pharmaceuticals Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Global Antazoline Market
Pharmaceutical Ingredients
Rizatriptan Market
Pharmaceutical Ingredients
Immunosuppressants Market
Pharmaceutical Ingredients
Nortriptyline Hydrochloride Market
Pharmaceutical Ingredients
Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market
Pharmaceutical Ingredients
Kitasamycin Market
Pharmaceutical Ingredients
Pharmaceutical Grade Amino Acid Market
Pharmaceutical Ingredients
Global Glycine Supplement Market
Pharmaceutical Ingredients
France Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Tiapride Hydrochloride API Market
Pharmaceutical Ingredients
Cyprosin Market
Pharmaceutical Ingredients
Saudi Arabia Active Pharmaceutical Ingredients (API) Market