
 Global Antazoline Market | 2026-2036
Global Antazoline Market Size, Share, and Industry Trends Forecast 2026-2036
Global Antazoline Market Foresight
Indian pharmaceutical API manufacturers is shifting capacity toward antihistamine precursors to serve branded formulation demand in Europe and North America. Novartis leverages its ophthalmology division to sustain prescription eye drop portfolios across multiple continents. Teva Pharmaceutical Industries anchors generic antazoline availability through established retail pharmacy networks. Alcon competes on specialized ocular formulation expertise and regulatory dossier depth.
Antazoline is a first-generation H1 antihistamine with imidazoline structural features, typically formulated at concentrations between 0.3% and 0.5% in ophthalmic solutions for rapid relief of allergic conjunctivitis symptoms. The compound functions as a competitive antagonist at histamine receptors with mild vasoconstrictive properties, making it suitable for combination therapies targeting ocular itching and redness simultaneously. Combination formulations containing antazoline and naphazoline dominate current prescription volumes due to dual-action symptom relief, while antazoline hydrochloride as a standalone API retains importance in hospital formulary procurement. Nasal spray presentations represent a faster-growing delivery format as clinicians seek alternatives to first-line intranasal corticosteroids for seasonal rhinitis patients with steroid sensitivity.
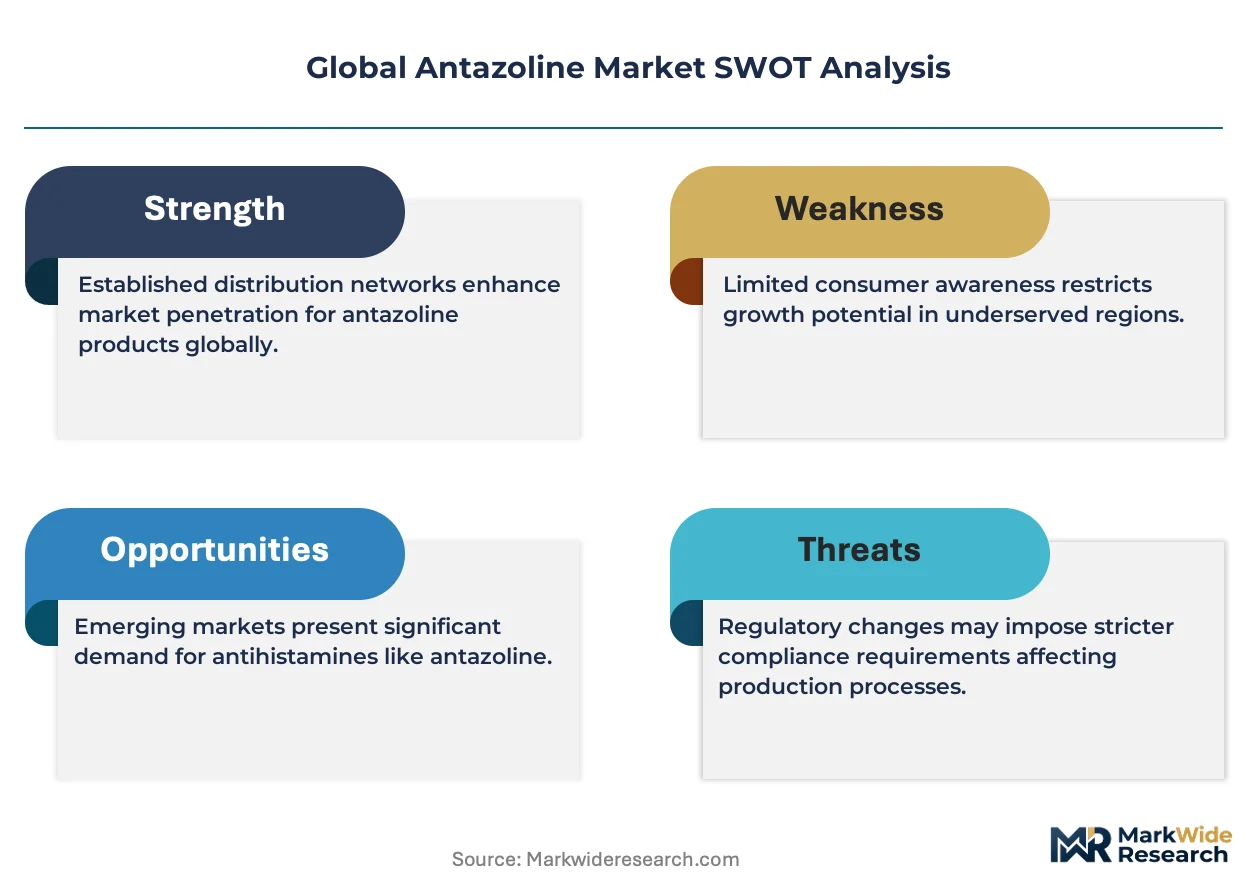
FDA ophthalmic guidance, EMA quality standards, and WHO prequalification protocols collectively elevate manufacturing compliance burdens for antazoline API suppliers and finished dosage form producers. REACH registration requirements in Europe further constrain raw material sourcing flexibility for formulation houses dependent on imported intermediates. Stakeholders must monitor evolving pharmacopeial monograph revisions and regional bioequivalence study mandates to preserve market access across jurisdictions.
Market Dynamics
REACH registration requirements and FDA ophthalmic guidance are compressing supplier margins while concentrating API production among Indian and Chinese manufacturers with dedicated compliance infrastructure.
Growth Catalysts
- Allergic conjunctivitis prevalence:Rising seasonal allergy incidence in Germany, Japan, and the United States drives prescription volumes for combination antazoline-naphazoline eye drops in ophthalmic clinics.
- EMA quality standards harmonization:Unified European pharmacopeial monographs reduce regulatory fragmentation, enabling Indian API suppliers to serve multiple EU member states through single dossier submissions.
- Nasal spray formulation expansion:Clinicians in steroid-sensitive patient populations are adopting intranasal antazoline as a corticosteroid alternative for seasonal rhinitis management.
Market Restraints
- Imidazoline precursor cost volatility:Fluctuating prices for specialty chemical intermediates squeeze formulation margins, particularly for standalone antazoline hydrochloride products.
- API supply concentration:Overreliance on Gujarat and Zhejiang manufacturing clusters creates vulnerability to regional environmental enforcement actions or logistics disruptions.
- Second-generation antihistamine substitution:Olopatadine and ketotifen formulations compete for allergic conjunctivitis prescriptions with longer duration of action and reduced dosing frequency.
Strategic Opportunities
- Brazilian regulatory pathway:ANVISA's streamlined API registration for prequalified suppliers opens access to Latin America's largest ophthalmic pharmaceutical market.
- Pediatric indication expansion:Age-appropriate dosing studies for antazoline-naphazoline combinations address the undertreated allergic conjunctivitis segment in children under twelve.
- Hospital formulary direct contracting:Bypassing retail pharmacy networks through centralized procurement agreements with German and Japanese hospital systems secures volume commitments.
Industry Challenges
- Stability testing timeline compression:Accelerated FDA ANDA review schedules demand completion of forced degradation studies within compressed windows, straining analytical chemistry capacity.
- Legacy excipient compatibility:Reformulating established antazoline solutions for preservative-free presentations requires extensive compatibility testing with novel container-closure systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Antazoline Market |
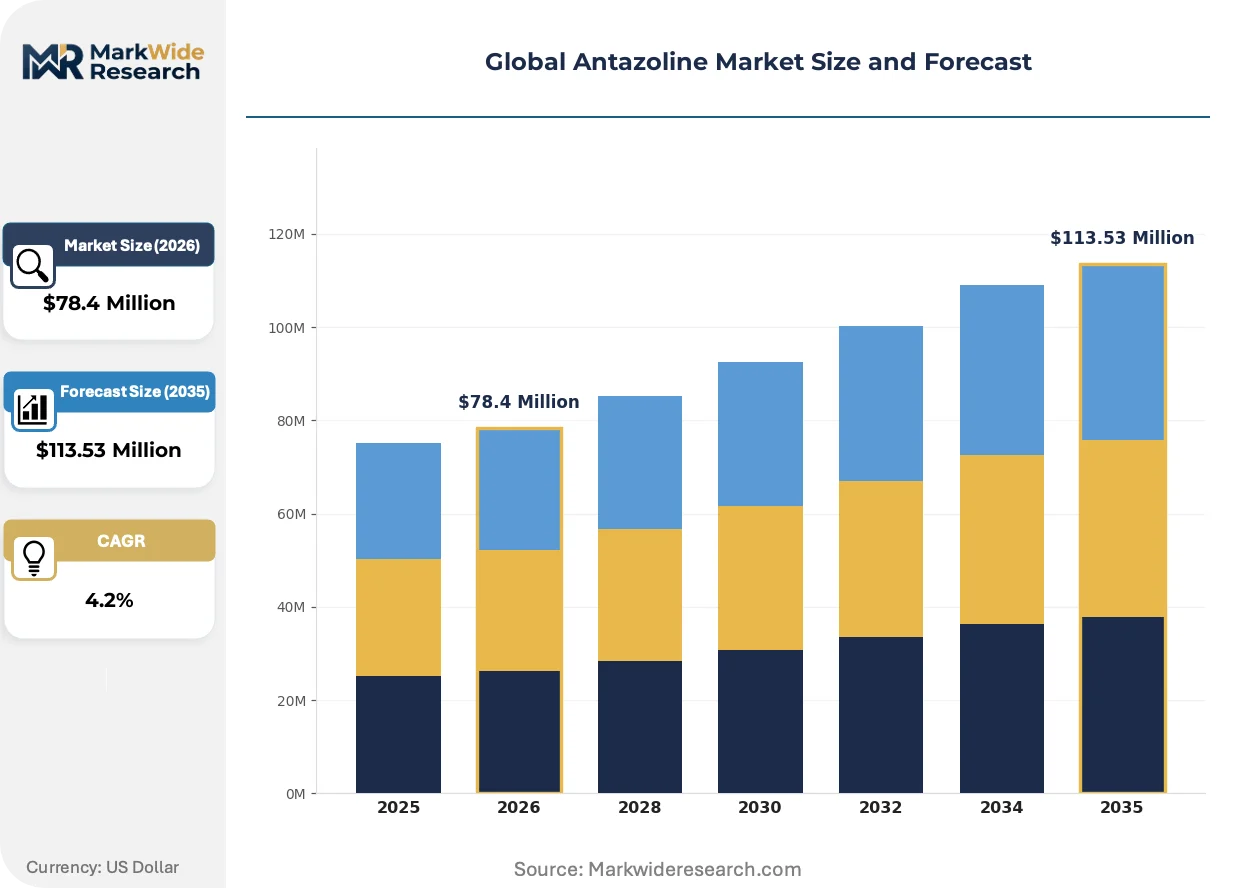
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $113.53 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antazoline Sulfate, Antazoline Hydrochloride, Combination Formulations, Nasal Sprays Application: Allergic Conjunctivitis, Rhinitis Treatment, Ocular Itching Relief, Eye Redness Reduction End User: Pharmacies, Ophthalmic Clinics, Retail Drug Stores, Online Pharmacies Distribution Channel: Hospitals & Clinics, E-commerce Platforms, Wholesale Distributors, Direct Sales |
| Companies Covered | Novartis, Teva Pharmaceutical Industries, Johnson & Johnson, Abbott Laboratories, Sanofi, Bausch Health Companies, Allergan AbbVie, Alcon, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Antazoline Market Shifts & Advancements
Ophthalmic formulation science is converging with regulatory science to redefine how antihistamine APIs demonstrate bioequivalence and therapeutic equivalence across jurisdictions.
Multidose preservative-free delivery systems are consolidating competitive positioning among finished dosage form manufacturers. European ophthalmic clinics are adopting these systems to reduce preservative-related surface toxicity in chronic allergy patients. The technology is consolidating market share around suppliers with validated blow-fill-seal manufacturing lines and documented FDA Type II drug master files.
REACH Annex XVII restrictions on certain chemical substances are tightening raw material qualification requirements for European formulation houses. ECHA substance evaluation workflows now demand extended toxicological data packages for imidazoline derivatives used in pharmaceutical synthesis. German and French contract manufacturers are responding by qualifying alternative intermediate suppliers with pre-registered REACH dossiers.
Hospital procurement consortia are consolidating purchasing decisions for ophthalmic antiallergy products across integrated delivery networks. Group purchasing organizations in the United States are replacing individual hospital formulary reviews with standardized therapeutic class protocols. This concentration is most visible in the Northeast and Midwest, where Catholic health systems and academic medical centers dominate regional market access.
Global Antazoline Market Segmentation
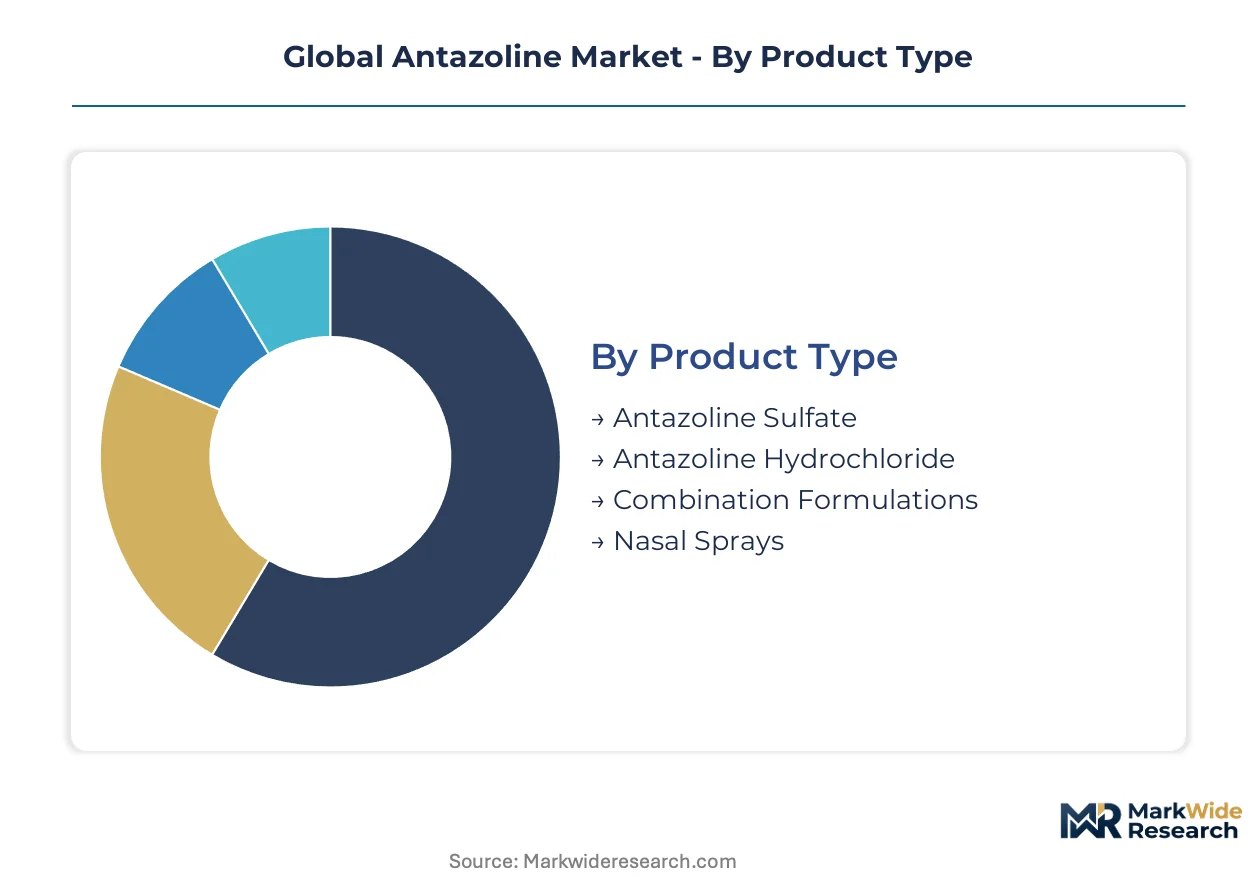
Antazoline market segmentation reveals how formulation chemistry, clinical application, and procurement channel each concentrate margin capture differently. Understanding these splits exposes where API suppliers, formulation houses, and distributors compete for position.
Product Type:
Supply concentration among Indian and Chinese API manufacturers shapes competitive dynamics across antazoline salt forms and delivery systems.
- Combination Formulations:Antazoline-naphazoline ophthalmic solutions dominate prescription volumes through dual-action symptom relief for allergic conjunctivitis. German and Japanese ophthalmic clinics drive demand for these fixed-dose combinations as first-line therapy. REACH-compliant intermediates from Gujarat-based suppliers feed European formulation houses.
- Antazoline Hydrochloride:The standalone API salt form retains critical importance in hospital formulary procurement, particularly for compound pharmacy preparation and intraoperative protocols. Purity specifications under FDA ophthalmic guidance and EMA quality standards elevate manufacturing compliance burdens for API suppliers in Zhejiang province.
- Antazoline Sulfate:Alternative salt form with distinct solubility profiles serving niche formulation requirements in preservative-free presentations.
- Nasal Sprays:Intranasal delivery format gaining clinical traction for seasonal rhinitis management in steroid-sensitive patient populations.
Today's leader: Combination Formulations. Tomorrow's challenger: Nasal Sprays.
Application:
Clinical indication breadth determines pricing power and regulatory pathway complexity for antazoline finished dosage forms.
- Allergic Conjunctivitis:Primary therapeutic indication commanding the majority of prescription volumes across ophthalmology practices. Japanese and United States clinics favor combination eye drops for rapid histamine receptor antagonism with vasoconstrictive adjunct therapy.
- Ocular Itching Relief:Symptom-specific positioning targets patient-reported outcome differentiation in competitive antihistamine markets. Olopatadine and ketotifen formulations challenge antazoline on duration of action, compressing dosing frequency advantages.
- Rhinitis Treatment:Expanding intranasal application addressing seasonal allergy patients with corticosteroid sensitivity or contraindications.
- Eye Redness Reduction:Cosmetic and symptomatic indication leveraging imidazoline vasoconstrictive properties in over-the-counter and prescription channels.
Allergic Conjunctivitis holds volume leadership. Ocular Itching Relief faces the steepest competitive pressure from second-generation antihistamine substitution.
End User:
Procurement authority concentration among integrated health systems and retail consolidation reshape channel economics.
- Ophthalmic Clinics:Specialized prescribers in Germany, Japan, and the United States drive premium formulation adoption and combination therapy preference. Group purchasing organization consolidation in the United States Northeast and Midwest compresses pricing negotiation leverage for individual practices.
- Pharmacies:Community and hospital-based dispensaries anchor generic antazoline availability through established retail networks. Teva Pharmaceutical Industries and Alcon compete for shelf position and pharmacist recommendation protocols.
- Retail Drug Stores:Mass-market distribution channel for over-the-counter antihistamine eye drop presentations with lower regulatory barriers.
- Online Pharmacies:Direct-to-patient dispensing platform expanding fastest for chronic allergy medication refills and subscription models.
Ophthalmic Clinics command premium positioning. Online Pharmacies are climbing fastest on patient convenience and formulary bypass.
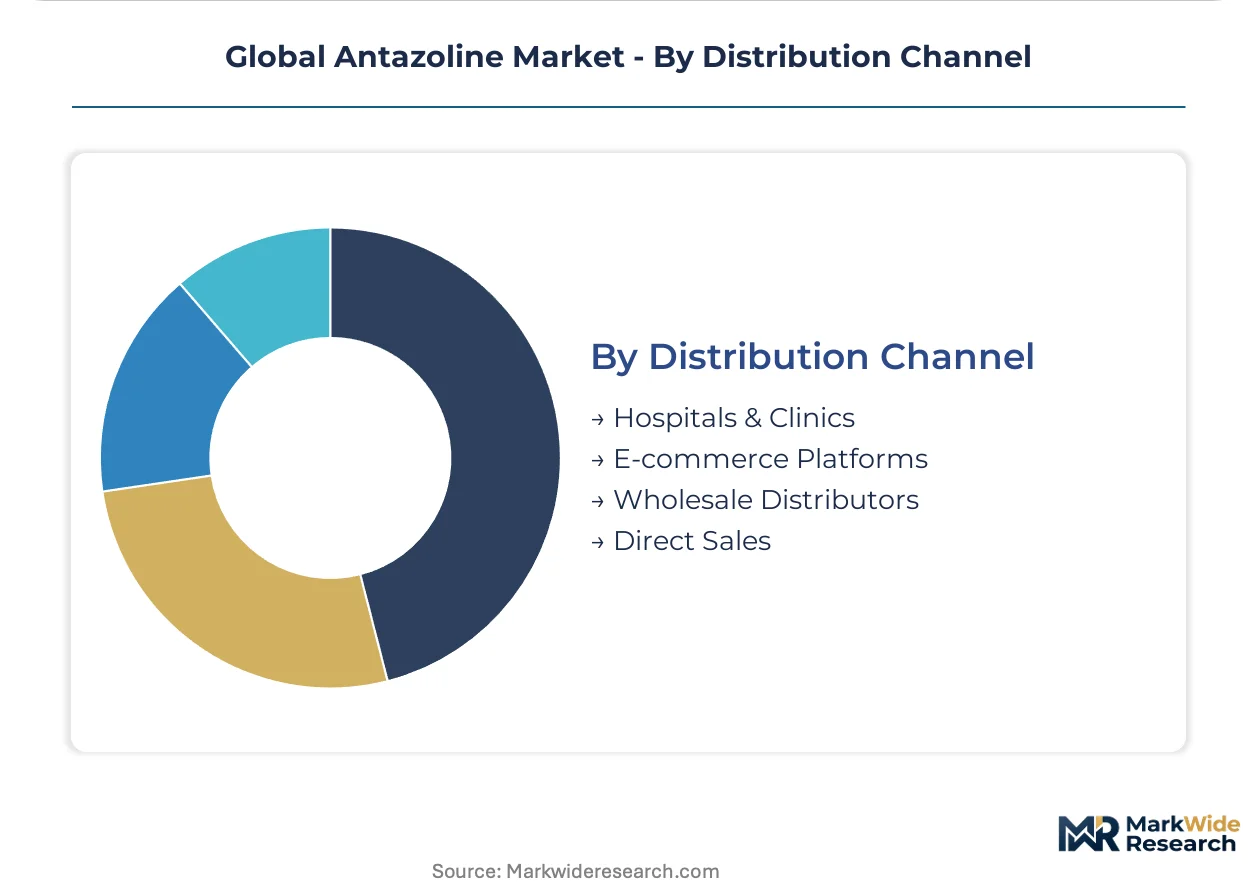
Distribution Channel:
Logistics infrastructure and regulatory compliance capability determine market access for antazoline API and finished dosage forms.
- Hospitals & Clinics:Centralized procurement agreements with German and Japanese hospital systems secure volume commitments and formulary placement. Direct contracting bypasses retail pharmacy margin stacking for standalone antazoline hydrochloride products.
- Wholesale Distributors:McKesson, AmerisourceBergen, and Cardinal Health networks dominate United States pharmaceutical distribution with cold-chain capabilities for ophthalmic solutions.
- E-commerce Platforms:Amazon Pharmacy and specialized ophthalmic suppliers expanding fastest in direct-to-consumer channels for chronic allergy management.
- Direct Sales:Manufacturer field forces targeting ophthalmology practices with clinical education and sample distribution for new combination launches.
Hospitals & Clinics anchor institutional volume. E-commerce Platforms represent the most rapidly expanding access pathway for patient-direct procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping antazoline production geography. API manufacturers in India and China leverage lower compliance-cost structures to supply formulation houses in Germany, Japan, and the United States. This cost-of-compliance gap concentrates intermediate chemical production in Gujarat and Zhejiang while finished dosage form manufacturing remains anchored near high-value ophthalmic markets.
United States
Ophthalmic clinics in the Northeast and Midwest drive prescription volumes for combination antazoline-naphazoline therapies. FDA ophthalmic guidance tightens purity benchmarks for imported APIs. McKesson and AmerisourceBergen distribution networks in California and Texas handle cold-chain logistics for finished eye drop formulations.
Germany
Hospital procurement consortia across Bavaria and North Rhine-Westphalia consolidate purchasing for antihistamine eye drops through centralized agreements. REACH Annex XVII restrictions constrain raw material qualification for imidazoline derivatives. Frankfurt and Hamburg formulation houses source pre-registered intermediates from Indian suppliers with documented ECHA dossiers.
India
Gujarat-based API manufacturers scale antihistamine precursor capacity to serve European and North American branded formulation demand. CDSCO manufacturing standards align with WHO prequalification protocols for export-oriented production. Ahmedabad and Vadodara chemical clusters specialize in imidazoline derivative synthesis under REACH-compliant quality systems.
Japan
PMDA quality standards elevate manufacturing compliance burdens for antazoline finished dosage forms used in Tokyo and Osaka ophthalmology practices. METI industrial policy supports domestic formulation expertise while permitting API imports from prequalified Asian suppliers. Kanto region clinics favor preservative-free multidose presentations for chronic allergy management.
China
Zhejiang province manufacturers dominate antazoline hydrochloride API output for hospital formulary procurement across Asia-Pacific markets. NMPA regulatory harmonization with ICH guidelines accelerates export dossier preparation for European submission. Hangzhou and Shaoxing chemical parks invest in dedicated compliance infrastructure for ophthalmic-grade intermediate production.
Global Antazoline Market Competitive Landscape
Indian producers anchor the API supply tier; Swiss and American specialists hold branded formulation dominance. The market structure concentrates around three strategic archetypes: vertically integrated pharmaceutical conglomerates with ophthalmology divisions, generic manufacturers competing on regulatory dossier depth, and specialized ocular formulation houses with blow-fill-seal manufacturing capabilities. Capacity expansion in Gujarat and Zhejiang manufacturing clusters and strategic partnerships between API suppliers and European contract manufacturers represent the dominant competitive moves reshaping supply-side positioning.
Within the integrated pharmaceutical tier, Novartis and Alcon exemplify archetypes combining ophthalmology division scale with regulatory dossier expertise across multiple continents. Teva Pharmaceutical Industries occupies a position representing generic manufacturers competing through established retail pharmacy networks and hospital formulary penetration. These three companies anchor competitive dynamics without exhausting the vendor landscape, as regional specialists and emerging API suppliers continue fragmenting lower-tier supply segments.
| Leading Market Players |
|---|
| Novartis |
| Teva Pharmaceutical Industries |
| Johnson & Johnson |
| Abbott Laboratories |
| Sanofi |
| Bausch Health Companies |
| Allergan AbbVie |
| Alcon |
| Bayer AG |
| Others |
Supply & Pricing Matrix
Specialized analytical chemistry talent pools in Gujarat and Zhejiang manufacturing clusters anchor labor-cost differentials that widen pricing spreads between REACH-certified premium formulations and standard-grade hospital procurement alternatives. These workforce concentrations enable Indian and Chinese API suppliers to undercut European contract manufacturing on imidazoline derivative production while FDA ophthalmic guidance compliance costs concentrate premium pricing among Swiss and American finished dosage form houses.
Pricing Analysis
Distributor margin stacking through McKesson and AmerisourceBergen networks in the United States compresses net realized prices for generic antazoline hydrochloride while direct-to-hospital contracting preserves premium positioning for preservative-free multidose presentations. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by FDA Type II drug master file status, EMA quality certification tier, and blow-fill-seal manufacturing validation. Pricing pressure stems from olopatadine and ketotifen substitution in allergic conjunctivitis prescriptions, with retail pharmacy channels exhibiting highest price sensitivity and ophthalmic clinic direct procurement showing lowest.
Supply Chain Analysis
India's PLI scheme for active pharmaceutical ingredients and China's NMPA regulatory harmonization with ICH guidelines are reshaping sourcing patterns for European formulation houses previously dependent on Swiss and German intermediate suppliers. API production concentrates in Gujarat, Zhejiang, and selected Hyderabad chemical parks, drawing from imidazoline precursors, naphazoline intermediates, and specialty-grade sodium chloride for ophthalmic buffer systems. Single-source vulnerability pervades the naphazoline intermediate stream where two Zhejiang manufacturers control majority supply. Distribution runs through temperature-controlled logistics networks anchored by Cardinal Health cold-chain infrastructure and regional hospital procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Antazoline Market compounds steadily as allergic conjunctivitis prevalence rises in aging populations across Germany, Japan, and the United States, sustaining prescription volume growth for combination therapies despite second-generation antihistamine competition.
For Market Incumbents: Deploy blow-fill-seal manufacturing capacity expansion in Ahmedabad and Vadodara to capture preservative-free multidose demand from Tokyo and Osaka ophthalmology practices. Consolidate regulatory dossier depth through EMA quality standards harmonization and FDA ophthalmic guidance pre-submission meetings. Second-generation antihistamine substitution from olopatadine and ketotifen formulations threatens volume share in ocular itching relief segments. For New Entrants and Emerging Players: Hospital procurement consortia in Bavaria and North Rhine-Westphalia represent the most penetrable channel for standalone antazoline hydrochloride products bypassing retail pharmacy margin stacking. ANVISA's streamlined API registration pathway for prequalified suppliers opens Brazilian market access with lower competitive density than United States Northeast and Midwest GPO concentration. Target pediatric indication expansion through age-appropriate dosing studies as the primary go-to-market angle. For Investors and Strategic Acquirers: Specialized pharmaceutical conglomerates with ophthalmology divisions are the most active acquirer in this space, seeking blow-fill-seal manufacturing capabilities and REACH-registered intermediate supply chains. Long-term viability frames around chronic allergy management tailwinds and hospital formulary consolidation trends. Acquisition targets include Gujarat-based API suppliers with documented ECHA dossiers and European contract manufacturers with validated multidose preservative-free lines. Monitor PMDA quality standards revision timelines as the signal to watch for Japanese market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Intermediate Qualification | Frankfurt formulation houses secure ECHA-registered supply from Ahmedabad chemical clusters. |
| Preservative-Free Multidose Launch | Kanto region ophthalmic clinics adopt validated blow-fill-seal systems for chronic allergy patients. |
| Pediatric Indication Expansion | ANVISA pathway enables age-appropriate dosing studies for undertreated children under twelve. |
| Hospital Procurement Direct Contracting | Bavarian hospital consortia bypass retail pharmacy networks for standalone antazoline hydrochloride. |
| Nasal Spray Formulation Development | Steroid-sensitive seasonal rhinitis populations drive intranasal delivery format clinical adoption. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation through regulatory filings and trade databases. Primary interviews engaged drug development executives at ophthalmology-focused pharmaceutical houses, regulatory affairs leads managing FDA ophthalmic guidance submissions, formulary directors at German hospital procurement consortia, and hospital procurement managers in Tokyo and Osaka integrated delivery networks. Secondary sources incorporated FDA ANDA filings, EMA quality standard submissions, ClinicalTrials.gov intervention records, and Japanese PMDA approval databases. Bottom-up prescription volume modeling triangulated against top-down API production estimates from Gujarat and Zhejiang manufacturing cluster outputs.
Granularity-level modeling distinguished combination formulations from standalone antazoline hydrochloride by dosage form, administration route, patient population age tier, and regional regulatory cluster. Segmentation dimensions spanned product type, application indication, end-user procurement authority, and distribution channel logistics capability. CAGRs derived from fitted growth curves applied to prescription volume trajectories across ophthalmic clinic, pharmacy, and hospital channels. Industry-specific forecast inputs incorporated allergic conjunctivitis epidemiology trends, imidazoline precursor cost volatility indices, and second-generation antihistamine substitution rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH Annex XVII restriction expansions, PMDA quality standards revision timing, and environmental enforcement actions affecting Zhejiang chemical park operations. Forecasts reflect assumptions around regulatory pathway stability, hospital procurement consolidation continuity, and API supply concentration persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
India Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market
Pharmaceutical Ingredients
Tiapride Hydrochloride API Market
Pharmaceutical Ingredients
Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Alpha Lipoic Acid API Market
Pharmaceutical Ingredients
Global Pharmaceutical Excipients Market
Pharmaceutical Ingredients
Lidocaine Hydrochloride Market
Pharmaceutical Ingredients
Sulphonamides Market
Pharmaceutical Ingredients
Pharma Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Sennosides Market
Pharmaceutical Ingredients
Asia-Pacific Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Germany Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Pharmaceutical Lactose Market
Pharmaceutical Ingredients
Saudi Arabia Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
MEK Inhibitors Market