
 Growth Hormone Inhibiting Hormone Drugs Market | 2026-2036
Growth Hormone Inhibiting Hormone Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Growth Hormone Inhibiting Hormone Drugs Market Foresight
Long-acting depot formulations is rotating toward dominance as the preferred quality tier in growth hormone inhibiting hormone therapy. Novartis AG leverages its established manufacturing infrastructure for sustained-release somatostatin analogues across European and North American markets. Pfizer Inc anchors its position through R&D intensity focused on next-generation peptide engineering. Ipsen SA differentiates via specialized endocrinology channel control in hospital-centric procurement systems.
Growth hormone inhibiting hormone drugs comprise synthetic or recombinant peptides that mimic or modulate somatostatin activity to suppress pituitary growth hormone secretion, typically formulated as cyclic octapeptides with half-life extension through depot microsphere encapsulation or fatty acid conjugation. Their primary purpose is normalizing insulin-like growth factor-1 levels in acromegaly and controlling hormone secretion in neuroendocrine tumors. Somatostatin analogues occupy the mature revenue core where brand loyalty and reimbursement familiarity protect margin pools, while peptide inhibitors represent the fastest-expanding structural category as oral bioavailability improvements unlock homecare administration. Injectable delivery modes still dominate hospital procurement budgets, though transdermal development programs are redirecting R&D capital toward patient convenience differentiation.
FDA orphan drug incentives and EMA's priority medicines scheme jointly shape clinical trial investment and accelerated market access pathways for novel somatostatin modulators. The EU MDR and FDA's updated bioanalytical method validation guidance impose escalating purity and stability documentation burdens that favor manufacturers with captive analytical capabilities. Stakeholders must monitor how decentralized homecare reimbursement policies in Germany and Japan reshape delivery mode preferences away from hospital-administered injectables.
Market Dynamics
The transition from hospital-administered injections to patient-managed depot formulations is compressing treatment cycles and redistributing value capture toward formulation specialists with microsphere encapsulation expertise.
Growth Catalysts
- FDA Orphan Drug Designation:The accelerated approval pathway for somatostatin analogues targeting acromegaly reduces clinical trial timelines and market entry costs for developers of novel peptide therapies.
- Homecare Administration Models:Long-acting depot formulations enabling monthly rather than daily dosing are shifting administration sites from infusion centers to patient residences, expanding addressable patient populations.
- Neuroendocrine Tumor Center Expansion:Specialized treatment facilities in the United States are concentrating prescription volumes and creating preferential access channels for premium somatostatin analogue products.
Market Restraints
- Peptide Manufacturing Concentration:Cyclic octapeptide synthesis requires specialized solid-phase equipment concentrated among European contract manufacturers, creating single-source vulnerability for active pharmaceutical ingredient supply.
- EMA MDR Compliance Burden:The EU Medical Device Regulation imposes escalating purity documentation requirements on depot microsphere delivery systems, extending certification timelines for new market entrants.
- Oral Peptide Bioavailability Ceiling:Gastric degradation and hepatic first-pass metabolism limit systemic absorption of non-injectable somatostatin mimetics, constraining patient convenience gains.
Strategic Opportunities
- German Decentralized Reimbursement:Shifting homecare reimbursement policies in Germany are creating direct-to-patient distribution channels that bypass hospital pharmacy procurement controls.
- Transdermal Patch Convergence:Microneedle array technology combined with iontophoretic delivery is opening non-injection administration routes for chronic acromegaly maintenance therapy.
- Japan PMDA Sakigake Pathway:The conditional early approval system for innovative pharmaceuticals is accelerating market access timelines for novel somatostatin receptor ligands in the Asia-Pacific region.
Industry Challenges
- Peptide Analytical Talent Scarcity:Bioanalytical method validation for cyclic peptides requires specialized chromatography expertise that outpaces current training program output.
- Cold Chain Integration Complexity:Depot microsphere stability requirements demand continuous temperature monitoring across fragmented last-mile distribution networks.
- Patent Thicket Navigation:Dense intellectual property coverage surrounding somatostatin receptor subtype selectivity is complicating freedom-to-operate assessments for next-generation analogues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Growth Hormone Inhibiting Hormone Drugs Market |
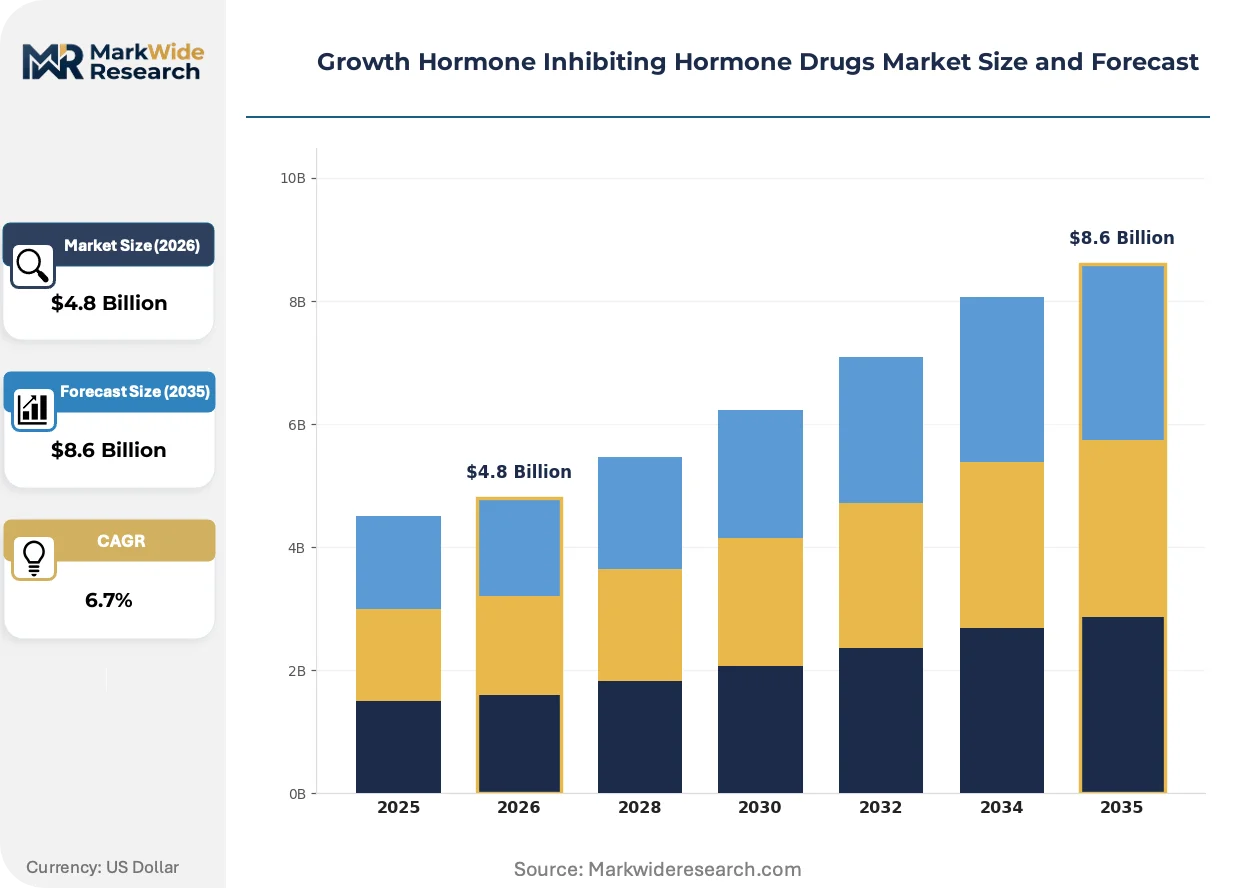
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Somatostatin Analogues, Growth Hormone Releasers, Antagonists, Peptide Inhibitors Therapy Area: Acromegaly, Cushing's Syndrome, Neuroendocrine Tumors, Gigantism Delivery Mode: Injectable, Oral, Transdermal, Intranasal End User: Hospitals, Clinics, Homecare, Pharmacies |
| Companies Covered | Novartis AG, Merck KGaA, Pfizer Inc, Novo Nordisk A/S, Ipsen SA, GeneScience Pharmaceuticals, Chiesi Farmaceutici, Crinetics Pharmaceuticals, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Growth Hormone Inhibiting Hormone Drugs Market Shifts & Advancements
Formulation science and regulatory science are converging to redefine competitive advantage, with half-life extension technologies and accelerated approval mechanisms creating divergent paths to market leadership.
Depot microsphere encapsulation technology is miniaturizing particle size distributions to enable subcutaneous administration through finer-gauge needles. Endocrinology clinics in the United States are adopting these refined formulations to reduce injection site reactions and improve patient compliance. The structural consequence is compressing differentiation windows between originator and follow-on products, forcing investment into secondary release kinetics optimization.
EMA's priority medicines scheme is redirecting clinical trial investment toward somatostatin analogues with demonstrated neuroendocrine tumor progression-free survival benefits. The industrial consequence is concentrating Phase III endpoints on hard oncology outcomes rather than biochemical control surrogates. Products targeting gastroenteropancreatic neuroendocrine tumors are most affected, with sponsors restructuring protocols to incorporate radiographic progression criteria.
Patient-administered dosing is displacing clinic-based infusion as the dominant care model for stable acromegaly patients. Hospital outpatient departments are losing prescription control to specialty pharmacy channels that manage prior authorization and home delivery logistics. This behavioral shift is most visible in the United States, where consolidated pharmacy benefit managers are extracting rebates in exchange for formulary placement of long-acting depot options.
Growth Hormone Inhibiting Hormone Drugs Market Segmentation
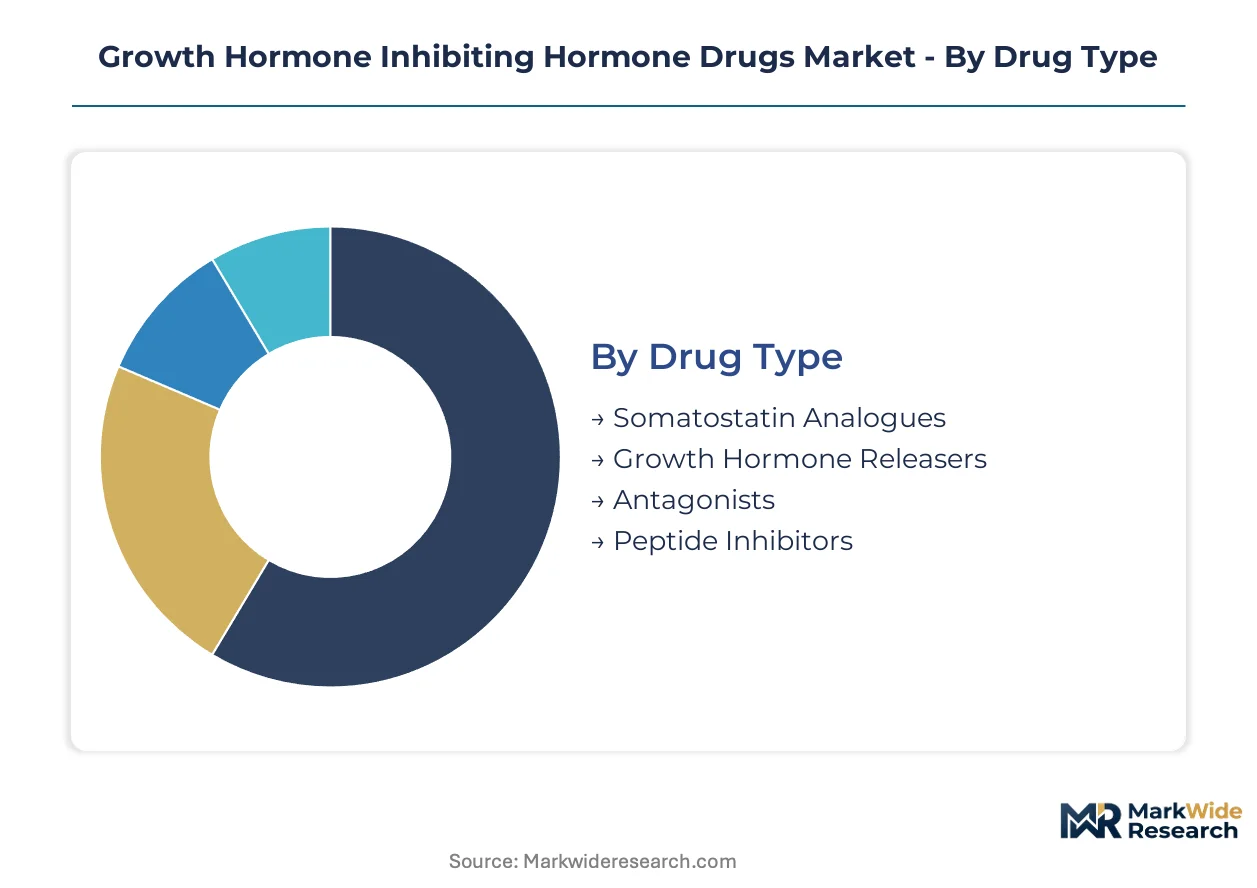
Segmentation in growth hormone inhibiting hormone drugs reveals how formulation technology and care setting migration reshape competitive boundaries. Manufacturers must align R&D investment with the specific biochemical requirements and administration constraints of each patient population.
Drug Type:
Somatostatin analogues face intensifying substitution pressure from oral peptide inhibitors as bioavailability barriers erode, while antagonists and releasers defend niche positions through mechanism-specific efficacy profiles.
- Somatostatin Analogues:Cyclic octapeptides engineered for extended half-life through fatty acid conjugation or microsphere encapsulation dominate hospital procurement budgets. United States neuroendocrine tumor centers concentrate demand for these established depot formulations, though EMA MDR compliance burdens extend certification timelines for new entrants.
- Peptide Inhibitors:Synthetic molecules blocking growth hormone secretion through non-receptor-mediated pathways represent the most dynamic structural category. German decentralized reimbursement policies are redirecting development toward these oral candidates that bypass injection requirements.
- Growth Hormone Releasers:Short-acting secretagogues used in diagnostic protocols and intermittent stimulation regimens.
- Antagonists:Competitive receptor blockers reserved for refractory cases where analogue therapy fails.
Somatostatin analogues retain volume leadership; peptide inhibitors hold the steepest expansion curve.
Therapy Area:
Cost tier stratification separates chronic maintenance indications from acute intervention segments, with oncology applications commanding premium pricing against endocrine disorder management.
- Neuroendocrine Tumors:Gastroenteropancreatic and bronchial carcinoid applications drive the highest revenue intensity per patient. FDA orphan drug designation accelerates clinical timelines for somatostatin analogues demonstrating progression-free survival benefits in this indication.
- Acromegaly:Chronic pituitary adenoma management requires lifelong therapy, creating stable recurring demand. United States endocrinology clinics are shifting stable patients from hospital infusions to home-administered depot formulations.
- Cushing's Syndrome:ACTH-secreting tumor applications where somatostatin receptor subtype selectivity determines efficacy.
- Gigantism:Pediatric growth hormone excess requiring dose-adjusted protocols and specialized pediatric endocrinology access.
Acromegaly retains volume leadership; neuroendocrine tumors hold the steepest expansion curve.
Delivery Mode:
Volume concentration in hospital-administered injectables is accelerating competition among formulation specialists with microsphere encapsulation expertise.
- Injectable:Subcutaneous and intramuscular depot formulations with sustained-release kinetics capture the dominant share of pharmaceutical procurement spending. Cold chain integration complexity favors manufacturers with captive distribution infrastructure.
- Oral:Enteric-coated and permeation-enhanced peptides are gaining share in German and Japanese markets where homecare reimbursement supports patient-administered alternatives.
- Transdermal:Microneedle array and iontophoretic systems under development for chronic maintenance therapy.
- Intranasal:Absorption-limited formulations restricted to diagnostic and acute rescue applications.
Injectable formulations retain volume leadership; oral delivery holds the steepest expansion curve.
End User:
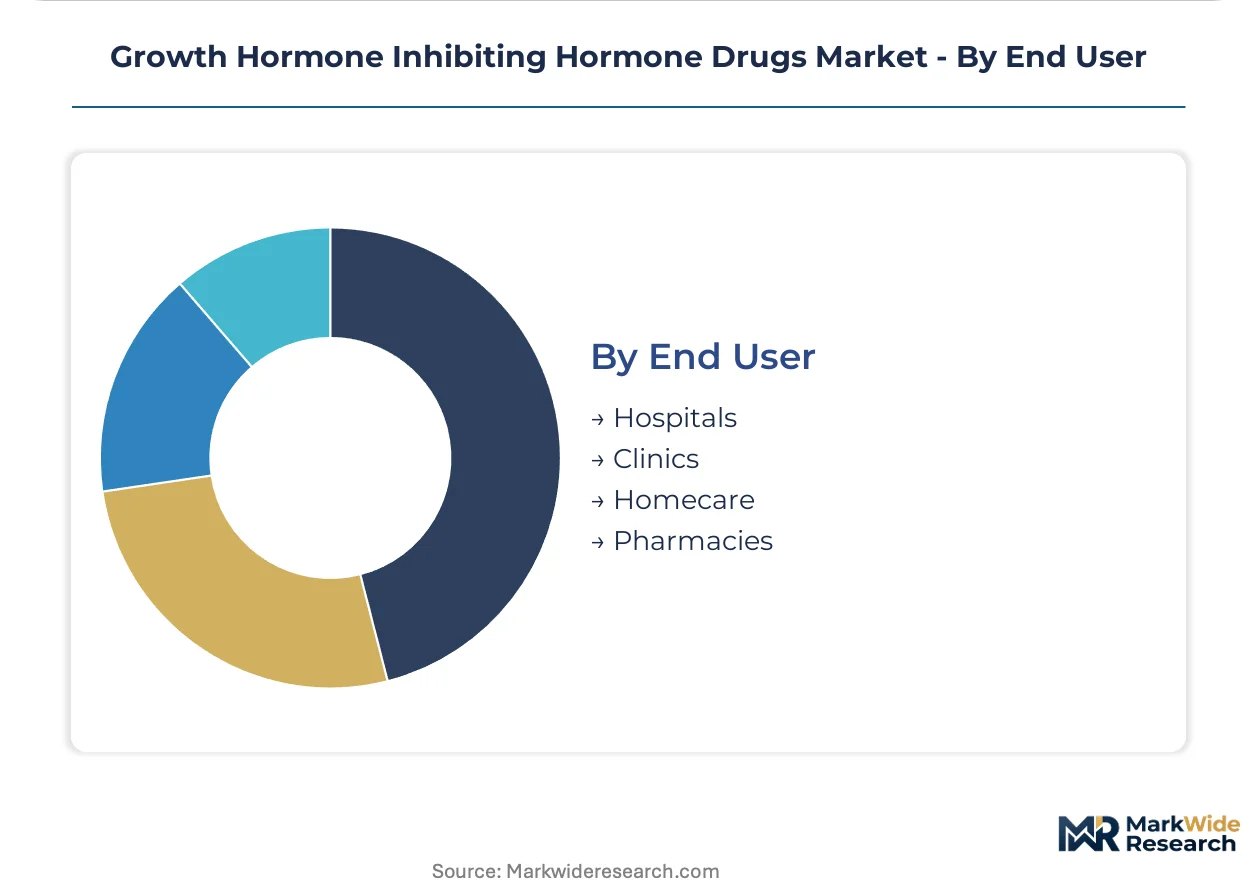
Customer type fragmentation reflects the migration from institutional procurement toward direct-to-patient distribution channels.
- Hospitals:Inpatient and outpatient departments administer intramuscular depot formulations for treatment initiation and unstable patients. United States hospital pharmacy procurement controls are eroding as specialty pharmacy channels capture stable patient volumes.
- Homecare:Patient-administered subcutaneous dosing is expanding fastest in markets with decentralized reimbursement. Pharmacy benefit managers in the United States extract rebates for formulary placement of long-acting options.
- Clinics:Endocrinology and oncology infusion centers managing dose titration and adverse event monitoring.
- Pharmacies:Retail and specialty pharmacy channels handling prior authorization and home delivery logistics.
Hospitals retain volume leadership; homecare holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of somatostatin analogue APIs concentrate among European contract manufacturers, while import demand clusters in the United States and Japan where specialized neuroendocrine tumor centers drive prescription volumes. This trade imbalance shapes regulatory harmonization pressures and cold chain infrastructure investment patterns across major markets.
United States
FDA orphan drug designation accelerates clinical timelines for acromegaly therapies, while neuroendocrine tumor centers in Houston and New York concentrate prescription volumes for premium depot formulations. The 340B drug pricing program reshapes hospital procurement economics for injectable somatostatin analogues.
Germany
Decentralized homecare reimbursement policies redirect patient volumes from hospital infusion centers to specialty pharmacy channels. EMA MDR compliance requirements extend certification timelines for depot microsphere delivery systems. The Baden-Württemberg pharmaceutical cluster anchors solid-phase peptide synthesis capacity for cyclic octapeptide APIs.
Japan
PMDA Sakigake conditional early approval accelerates market access for novel somatostatin receptor ligands targeting gastroenteropancreatic neuroendocrine tumors. Tokyo and Osaka endocrinology clinics drive adoption of patient-administered depot formulations. METI's regenerative medicine promotion framework indirectly supports peptide engineering R&D investment.
Switzerland
Swissmedic's streamlined authorization procedures attract headquarters operations for somatostatin analogue developers. The Basel pharmaceutical corridor concentrates formulation science expertise for sustained-release microsphere technologies. Domestic demand remains modest; the country functions primarily as an export platform for high-purity peptide APIs.
India
CDSCO accelerated approval pathways for orphan indications reduce regulatory lag for imported somatostatin analogues. Mumbai and Hyderabad specialty hospital networks expand neuroendocrine tumor diagnosis capacity, creating latent demand for long-acting depot options. Domestic peptide manufacturing capabilities remain concentrated in Bangalore bioscience parks.
Growth Hormone Inhibiting Hormone Drugs Market Competitive Landscape
Listed leaders compete with private specialists across formulation technology tiers, creating a bifurcated structure where public companies anchor R&D intensity and private entities capture niche manufacturing margins. The market consolidates around three strategic archetypes: multinational pharmaceutical conglomerates with captive peptide synthesis infrastructure, mid-cap biotech specialists focused on receptor subtype selectivity, and contract development organizations with microsphere encapsulation expertise. Competitive moves center on strategic partnerships for depot technology licensing and backward integration into cyclic octapeptide API production.
Within the multinational tier, Novartis AG and Pfizer Inc exemplify scale-driven positioning through established somatostatin analogue portfolios, while Ipsen SA occupies a specialized position in hospital-centric endocrinology channels. These three entities anchor competitive dynamics across North American and European markets, with their collective manufacturing footprints shaping supply availability for long-acting depot formulations. Their strategic positioning reflects divergent bets on formulation innovation versus channel control.
| Leading Market Players |
|---|
| Novartis AG |
| Merck KGaA |
| Pfizer Inc |
| Novo Nordisk A/S |
| Ipsen SA |
| GeneScience Pharmaceuticals |
| Chiesi Farmaceutici |
| Crinetics Pharmaceuticals |
| Sanofi |
| Others |
Supply & Pricing Matrix
EMA MDR compliance certification gates both supplier qualification and price stratification in growth hormone inhibiting hormone drugs, forcing manufacturers to absorb escalating purity documentation costs that concentrate pricing power among established European formulators with captive analytical capabilities.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels in growth hormone inhibiting hormone procurement. Price differentiation rests on FDA orphan drug designation status and depot microsphere encapsulation sophistication. Pricing pressure stems from German decentralized reimbursement policies compressing hospital pharmacy margins. Specialty pharmacy channels demonstrate highest price sensitivity; neuroendocrine tumor centers show lowest sensitivity due to clinical outcome prioritization.
Supply Chain Analysis
Strategic stockpile preferences dominate inventory strategy for cyclic octapeptide APIs given single-source European contract manufacturing concentration and cold chain stability requirements. Supply concentrates in Switzerland, Germany, and Denmark for solid-phase peptide synthesis equipment. Raw material dependencies include protected amino acids, resin supports, and fatty acid conjugation agents. Tariff exposure on Chinese-sourced starting materials creates structural vulnerability. Distribution runs through hospital pharmacy procurement systems shifting toward specialty pharmacy direct-to-patient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Growth hormone inhibiting hormone drugs represent early-cycle expansion as patient-administered depot formulations displace hospital-based infusion models, with homecare reimbursement tailwinds accelerating addressable patient population growth.
For Market Incumbents: Fortify backward integration into cyclic octapeptide API production to neutralize European contract manufacturing concentration risk. Expand manufacturing footprint in Baden-Württemberg pharmaceutical cluster to secure solid-phase synthesis capacity. Patent thicket navigation around somatostatin receptor subtype selectivity demands intensified R&D investment in next-generation peptide engineering.
For New Entrants and Emerging Players: Anchor in oral peptide inhibitor development where bioavailability improvements unlock homecare administration white space. Target German decentralized reimbursement channels bypassing hospital pharmacy procurement controls. Pursue microneedle array transdermal convergence as differentiation angle against established injectable incumbents.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across depot microsphere encapsulation manufacturing as EMA MDR compliance burdens extend certification timelines. Long-term viability favors acquisition of mid-cap biotech specialists with receptor subtype selectivity pipelines. Monitor PMDA Sakigake pathway approval velocity as inflection indicator for Asia-Pacific market access momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Depot Microsphere Scale-Up | Captive manufacturing infrastructure secures supply continuity against European API concentration. |
| Oral Peptide Bioavailability Program | Permeation-enhanced formulations unlock patient-administered alternatives to injectable standards. |
| FDA Orphan Drug Designation Pursuit | Accelerated approval pathway compresses clinical timelines for acromegaly indication expansion. |
| Specialty Pharmacy Partnership | Direct-to-patient distribution channels capture stable patient volumes from hospital outpatient departments. |
| Receptor Subtype Selectivity R&D | Next-generation somatostatin analogues differentiate through gastroenteropancreatic neuroendocrine tumor efficacy. |
Research Methodology
The analysis maps somatostatin analogue formulations, peptide inhibitors, and depot delivery technologies, each validated through endocrinology clinic directors, hospital pharmacy procurement managers, regulatory affairs specialists at peptide manufacturers, and specialty pharmacy channel operators. Primary interview insights triangulate against FDA orphan drug designation filings, EMA priority medicines scheme decisions, ClinicalTrials.gov protocol endpoints, and German homecare reimbursement policy documents. Bottom-up patient population modeling and top-down pharmaceutical procurement spending estimates converge across the analysis window.
Consistency checks against external benchmarks validate volume and value outputs across drug type, therapy area, delivery mode, and end user segmentation dimensions. CAGRs derive from treatment line penetration curves and administration site migration patterns. Forecast inputs incorporate neuroendocrine tumor center expansion rates and decentralized reimbursement policy adoption timelines throughout the projection horizon.
Material uncertainties — regulatory pathway delays, peptide manufacturing supply disruptions, and oral bioavailability technical setbacks — sit outside the modeled envelope. Forecasts reflect assumptions on homecare administration adoption velocity and orphan drug incentive continuity. Revision becomes warranted when EMA MDR certification timeline extensions cross thresholds that alter competitive entry dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Oral Doxycycline Hyclate Market
Pharmaceutical Ingredients
Global Penicillin Drug Market
Pharmaceutical Ingredients
Acetaminophen API Market
Pharmaceutical Ingredients
Co-Crystal Ingredient Market
Pharmaceutical Ingredients
Pharma Grade Synthetic Camphor Market
Pharmaceutical Ingredients
Pharmaceutical Grade Hyaluronic Acid Market
Pharmaceutical Ingredients
Lidocaine Hydrochloride Market
Pharmaceutical Ingredients
United Kingdom Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Ferrous Succinate Market
Pharmaceutical Ingredients
Sulphonamides Market
Pharmaceutical Ingredients
China Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Global Tacrolimus Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
Albumin (As Excipient) Market
Pharmaceutical Ingredients
Germany Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Duloxetine API Market