
 Germany Active Pharmaceutical Ingredients (API) Market | 2026-2036
Germany Active Pharmaceutical Ingredients (API) Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Active Pharmaceutical Ingredients (API) Market Foresight
Asset-light contract manufacturing partnerships is reconfiguring competitive dynamics in Germany's API sector, lowering capital barriers for mid-scale entrants. Boehringer Ingelheim leverages captive fermentation capacity to anchor its position in biologic APIs. Merck KGaA sustains leadership through advanced crystallization technology for high-potency compounds. BASF SE dominates specialty chemical intermediates, extending its upstream control into pharmaceutical-grade outputs.
Active pharmaceutical ingredients are pharmacologically active substances, typically exceeding 99.5% purity, produced through fermentation, chemical synthesis, or biocatalysis for incorporation into finished drug formulations. Fermentation-derived APIs command premium positioning as biologics expand, while chemical synthesis retains volume leadership in generic small-molecule production. Oncology and cardiovascular applications concentrate the highest margin pools, reflecting chronic disease burdens and specialty therapy complexity.
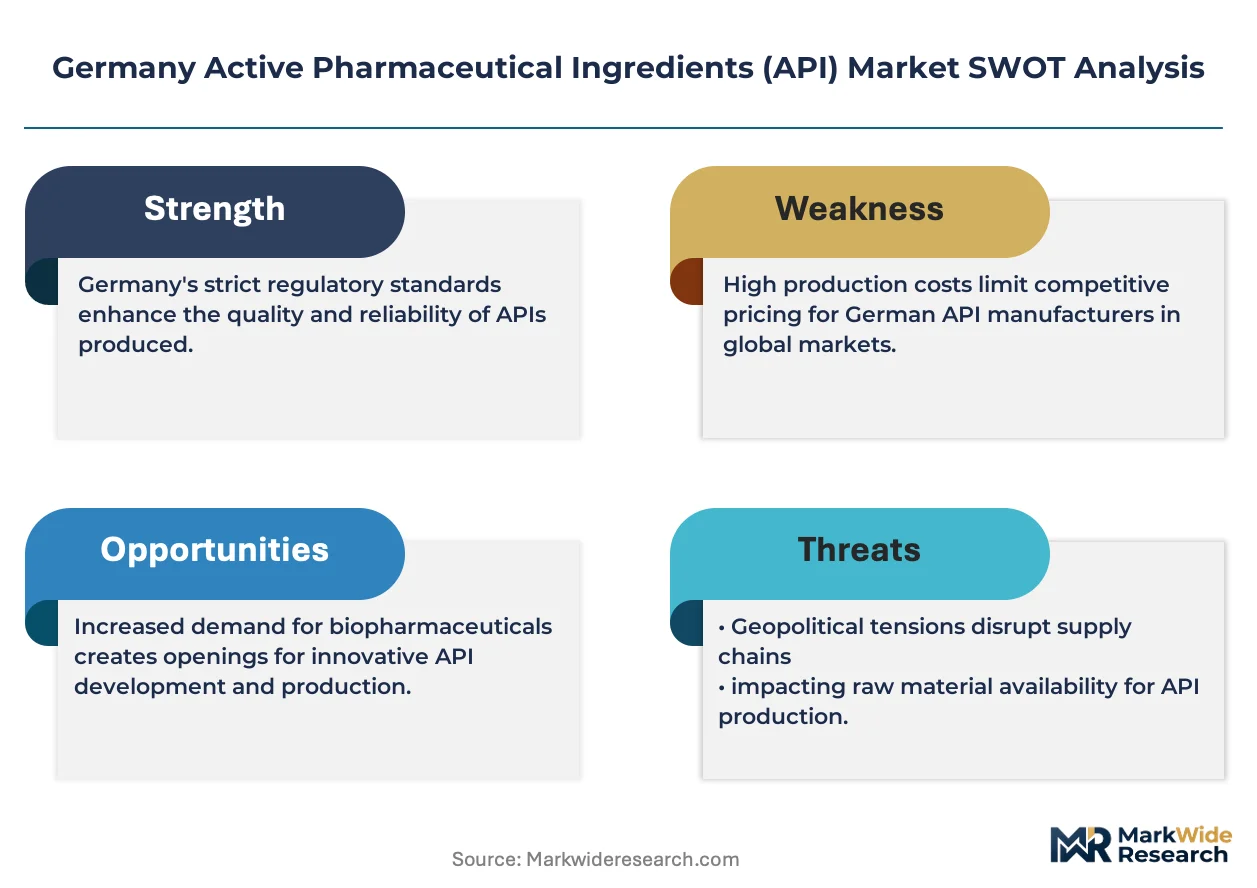
Germany's API sector operates under EMA marketing authorization requirements, REACH chemical safety protocols, and EU GMP manufacturing standards that elevate compliance costs while filtering out subscale competitors. The EU Green Deal and national carbon pricing mechanisms are forcing solvent-intensive processes toward closed-loop recovery systems. Stakeholders must monitor how delegated acts under the EU pharmaceutical strategy reshape local manufacturing obligations versus import reliance.
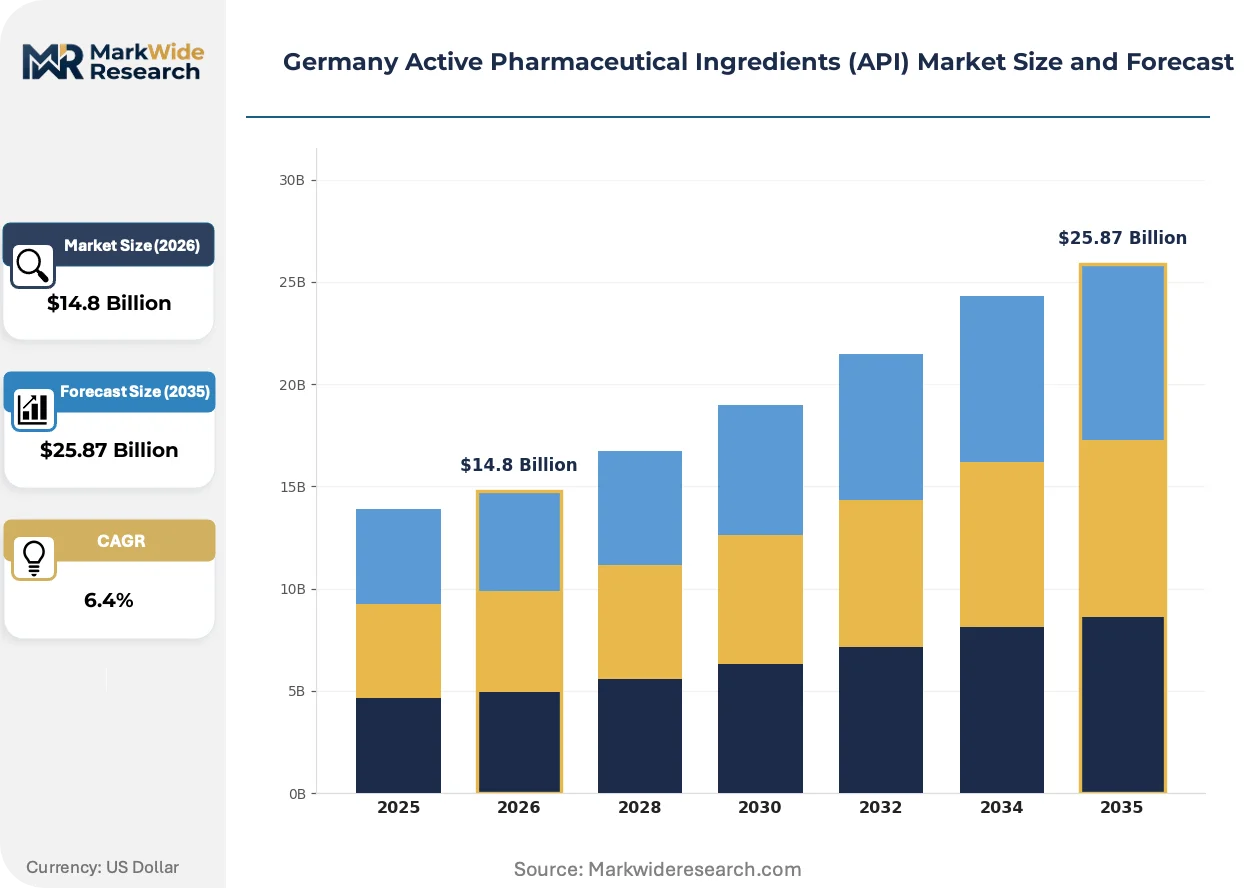
Market Dynamics
The EU's F-Gas Regulation and carbon border adjustment mechanisms are forcing German API manufacturers to abandon solvent-intensive batch processes in favor of continuous flow chemistry and biocatalytic routes.
Growth Catalysts
- Oncology API demand surge:Personalized cancer therapies require complex high-potency intermediates that German chemical clusters specialize in producing. The Rhine-Main infrastructure supports multi-step synthesis with integrated waste recovery.
- EMA regulatory harmonization:Streamlined marketing authorization pathways across EU member states reduce time-to-market for fermentation-derived biologics manufactured in Saxony and Bavaria.
- Green chemistry mandates:The EU Green Deal's solvent recovery requirements accelerate adoption of closed-loop systems in Ludwigshafen and Frankfurt production facilities.
Market Restraints
- Energy cost volatility:Natural gas price fluctuations directly impact fermentation temperature control and solvent distillation economics at BASF SE and Merck KGaA production sites.
- Critical intermediate import dependence:Kharasch reaction precursors and organometallic catalysts concentrate in Chinese suppliers, exposing German formulators to supply disruption risk.
- REACH compliance burden:ECHA registration requirements for novel synthetic intermediates add 18-24 month delays to pipeline commercialization timelines.
Strategic Opportunities
- Baden-Württemberg biotech corridor:Underutilized fermentation capacity in Heidelberg and Mannheim offers expansion platforms for monoclonal antibody APIs serving European biopharma sponsors.
- Continuous manufacturing retrofit:Microreactor technology convergence with AI-driven process control enables real-time quality assurance for high-potency oncology compounds.
- Carbon border adjustment arbitrage:Early compliance with EU CBAM documentation positions German exporters against Indian and Chinese API imports facing tariff exposure.
Industry Challenges
- Biocatalysis skill scarcity:Enzyme engineering and directed evolution expertise concentrates in academic institutions rather than production facilities, constraining scale-up of green synthesis routes.
- Legacy quality system integration:Paper-based batch records at mid-tier CMOs conflict with EMA's push for electronic data integrity standards, requiring multimillion-euro ERP overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Active Pharmaceutical Ingredients (API) Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Hormones, Vitamins, Steroids, Enzymes Technology: Fermentation, Chemical Synthesis, Biocatalysis, Extraction, Crystallization Application: Cardiovascular, Neurology, Oncology, Dermatology, Respiratory End User: Pharmaceutical Manufacturers, Biotechnology Firms, Contract Manufacturers, Research Laboratories |
| Companies Covered | Boehringer Ingelheim, Bayer, Merck KGaA, BASF SE, Sanofi Deutschland GmbH, Novartis Pharma GmbH, Teva GmbH / ratiopharm, Siegfried Holding AG, Corden Pharma GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Active Pharmaceutical Ingredients (API) Market Shifts & Advancements
Digital twins and AI-driven process optimization are compressing development timelines for complex APIs while regulatory pressure on carbon intensity accelerates biocatalytic adoption across German manufacturing sites.
Flow chemistry platforms are virtualizing traditional batch manufacturing by enabling real-time parameter adjustment and eliminating scale-up risks. Boehringer Ingelheim and specialized CMOs in Hesse deploy modular microreactor systems for hazardous nitration and hydrogenation steps previously requiring dedicated explosion-proof facilities. This virtualization collapses the capital barrier between pilot and commercial production, allowing mid-scale entrants to compete on flexibility rather than volume.
REACH authorization requirements for persistent organic pollutants are forcing reformulation of palladium-catalyzed cross-coupling processes. German manufacturers face substitution pressure for phosphine ligands and heavy metal catalysts, driving investment in iron and copper-based alternatives. The specialty API segment bears disproportionate compliance costs, with high-potency compound producers in the Rhine-Neckar triangle accelerating partnerships with academic catalysis groups.
Pharma sponsors are consolidating their CMO panels from twenty-plus suppliers to three-to-five strategic partners with integrated analytical and regulatory capabilities. This concentration favors German contract manufacturers with captive stability testing and EMA submission expertise. Bavarian and Rhineland-Palatinate facilities report extended master service agreement terms and co-investment in dedicated production lines as biotech sponsors seek supply security for commercial-stage biologics.
Germany Active Pharmaceutical Ingredients (API) Market Segmentation
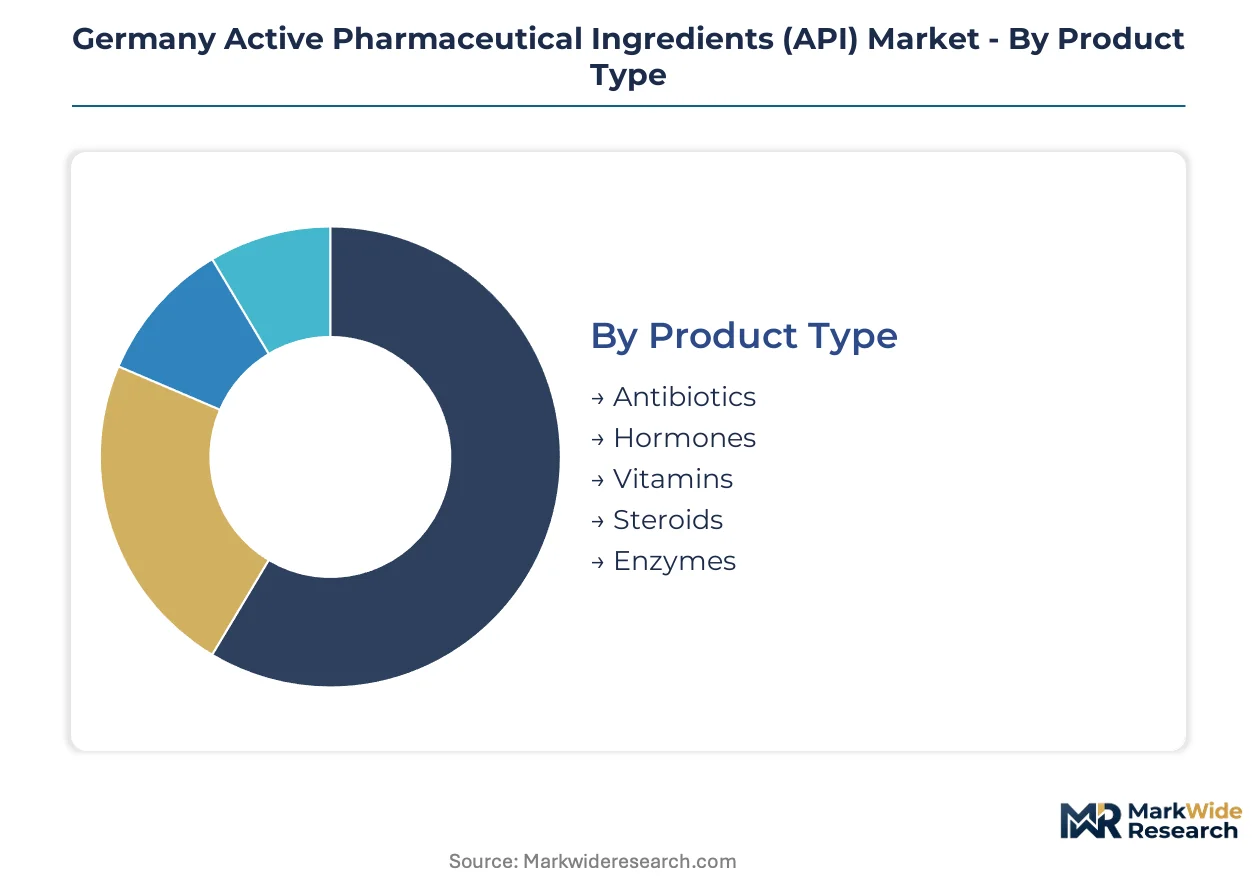
German API manufacturers configure production assets around distinct technical and demand characteristics. Segmentation reveals how fermentation capacity concentrates in biologics while chemical synthesis retains generic small-molecule dominance.
Product Type:
Cost tier differentiation separates commodity APIs from specialty compounds requiring dedicated containment infrastructure.
- Antibiotics:Beta-lactam and macrolide APIs dominate fermentation output at Ludwigshafen and Frankfurt facilities. Demand from European hospital procurement networks concentrates on narrow-spectrum compounds as antimicrobial stewardship tightens prescribing protocols.
- Hormones:Steroidal hormone APIs require explosion-proof hydrogenation capacity and dedicated containment for potent compound handling. Saxony-based manufacturers supply contraceptive and endocrine therapy sponsors with EMA-certified synthetic intermediates.
- Vitamins:Bulk ascorbic acid and B-complex APIs compete on fermentation yield optimization against Asian imports.
- Steroids:Corticosteroid and sex hormone precursors demand multi-step synthesis with strict impurity profiling under REACH protocols.
- Enzymes:Therapeutic enzyme APIs from recombinant fermentation serve rare disease indications with orphan drug pricing structures.
Antibiotics holds installed capacity. Hormones is rotating up the share rankings.
Technology:
Application requirements dictate whether batch fermentation, continuous flow, or biocatalytic routes deliver viable economics.
- Fermentation:Microbial and mammalian cell culture platforms produce monoclonal antibodies and therapeutic proteins. Bavarian facilities leverage single-use bioreactor technology to reduce cross-contamination risk between campaigns for different biotech sponsors.
- Chemical Synthesis:Multi-step organic synthesis retains volume leadership for generic small molecules. Rhine-Main cluster manufacturers deploy continuous flow microreactors for hazardous nitration steps previously requiring dedicated explosion-proof buildings.
- Biocatalysis:Enzyme-driven transformations reduce solvent intensity and enable stereoselective reactions impossible through traditional chemistry. Academic partnerships in Heidelberg and Mannheim constrain scale-up due to limited protein engineering talent pools.
- Extraction:Botanical APIs from plant material processing serve phytopharmaceutical niches with variable batch-to-batch consistency challenges.
- Crystallization:Polymorph control and particle size distribution engineering determine bioavailability for poorly soluble compounds.
Chemical synthesis holds installed capacity. Biocatalysis is rotating up the share rankings.
Application:
Margin structure varies sharply across therapeutic areas based on molecule complexity and regulatory scrutiny intensity.
- Oncology:High-potency cytotoxic APIs and antibody-drug conjugate payloads command premium positioning. Rhine-Neckar triangle manufacturers invest in isolator technology and dedicated containment suites for handling microgram-quantity potent compounds.
- Cardiovascular:Statins, beta-blockers, and anticoagulant APIs represent mature markets with intense generic competition. German producers differentiate through crystallization expertise and EMA-compliant impurity control.
- Neurology:CNS-active APIs face blood-brain barrier permeability challenges and DEA-style scheduling constraints for controlled substances.
- Dermatology:Topical API formulations require specific particle size distributions and excipient compatibility testing.
- Respiratory:Inhalation-grade APIs demand micronization to specific aerodynamic particle sizes for pulmonary deposition efficacy.
Cardiovascular holds installed capacity. Oncology is rotating up the share rankings.
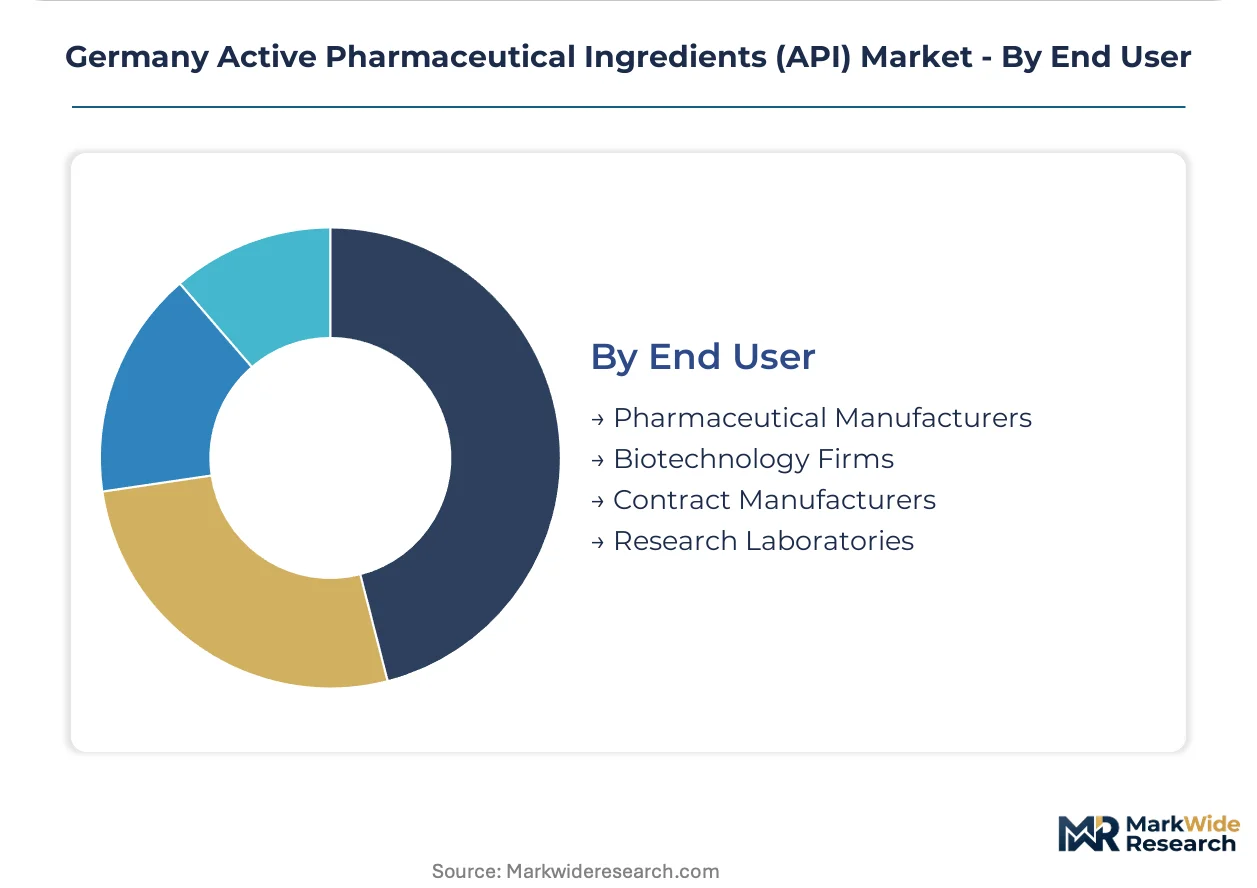
End User:
Customer type determines contract structure, regulatory documentation burden, and technical service intensity.
- Pharmaceutical Manufacturers:Large pharma sponsors source APIs through long-term supply agreements with integrated quality and regulatory support. Boehringer Ingelheim and Merck KGaA leverage captive production for proprietary portfolios while selling excess capacity to third parties.
- Biotechnology Firms:Venture-backed biotechs rely on German CMOs for clinical-to-commercial manufacturing transitions. Co-investment in dedicated production lines secures capacity allocation for commercial-stage monoclonal antibodies.
- Contract Manufacturers:Mid-tier CMOs compete on flexibility and EMA submission expertise rather than scale.
- Research Laboratories:Academic and institutional buyers procure reference standards and analytical-grade materials in small quantities.
Pharmaceutical manufacturers hold installed capacity. Biotechnology firms is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers and biotechnology sponsors concentrate procurement decisions in chemical clusters with integrated regulatory infrastructure. German API demand distributes across federal states based on fermentation capacity, specialty synthesis expertise, and proximity to EMA submission pathways.
Bavaria
Monoclonal antibody production drives facility investment in Munich and surrounding biotech corridors. The Bavarian state government coordinates with EMA on streamlined GMP inspection protocols for mammalian cell culture platforms. Single-use bioreactor deployments in Martinsried and Penzberg reduce cross-contamination risk between sponsor campaigns.
North Rhine-Westphalia
Chemical synthesis for generic small molecules dominates output in Leverkusen and Düsseldorf industrial zones. REACH enforcement through ECHA registration requirements filters subscale competitors from novel intermediate commercialization. The Rhine-Ruhr cluster maintains dedicated hydrogenation capacity for steroidal hormone APIs under explosion-proof containment standards.
Baden-Württemberg
Underutilized fermentation assets in Heidelberg and Mannheim attract biotech sponsor co-investment for clinical-to-commercial transitions. State-level biotech funding programs support protein engineering partnerships with academic institutions. The Rhine-Neckar triangle concentrates high-potency compound handling infrastructure with isolator technology for cytotoxic payloads.
Hesse
Continuous flow chemistry adoption accelerates in Frankfurt and Ludwigshafen production facilities under EU Green Deal solvent recovery mandates. Modular microreactor systems enable real-time parameter adjustment for hazardous nitration steps. The Rhine-Main infrastructure supports multi-step synthesis with integrated waste recovery and carbon border adjustment documentation.
Lower Saxony
Antibiotic fermentation capacity concentrates in Hannover and Braunschweig chemical parks serving European hospital procurement networks. National antimicrobial stewardship policies narrow demand toward narrow-spectrum beta-lactam compounds. State environmental agencies enforce closed-loop solvent systems for fermentation temperature control operations.
Germany Active Pharmaceutical Ingredients (API) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Captive pharmaceutical manufacturers leverage internal demand to amortize dedicated production lines, while contract manufacturers compete on EMA submission expertise and flexibility. Strategic archetypes include integrated pharma-chemical conglomerates, mid-scale fermentation specialists, and asset-light CMO platforms. Competitive moves concentrate on strategic partnerships for capacity allocation and technology licensing for continuous manufacturing retrofits.
Among Germany-based integrated manufacturers, Boehringer Ingelheim, Merck KGaA, and BASF SE exemplify distinct archetype positions. Boehringer Ingelheim occupies a captive biologics position with internal demand anchoring fermentation infrastructure. Merck KGaA represents specialty chemical intermediates with upstream control into pharmaceutical-grade outputs. BASF SE sits within the diversified chemical conglomerate tier, extending Ludwigshafen-based production networks into API-grade material supply.
| Leading Market Players |
|---|
| Boehringer Ingelheim |
| Bayer |
| Merck KGaA |
| BASF SE |
| Sanofi Deutschland GmbH |
| Novartis Pharma GmbH |
| Teva GmbH / ratiopharm |
| Siegfried Holding AG |
| Corden Pharma GmbH |
| Others |
Supply & Pricing Matrix
Underutilized fermentation capacity in Baden-Württemberg is compressing spot pricing for monoclonal antibody APIs while simultaneously incentivizing long-term contract structures that lock in sponsor relationships. This utilization dynamic shapes how Boehringer Ingelheim and Merck KGaA negotiate master service agreements with biotech sponsors seeking supply security.
Pricing Analysis
Cost-plus contracts indexed to natural gas and solvent feedstock benchmarks dominate long-term API supply agreements in the Rhine-Main cluster. Price differentiation rests on EMA certification tier and volume scale, with high-potency oncology compounds commanding substantial premiums over commodity antibiotics. Pricing pressure stems from Asian import competition in generic small-molecule segments, where Indian and Chinese manufacturers exploit carbon border adjustment documentation gaps. Hospital procurement networks exhibit the highest price sensitivity for narrow-spectrum antibiotics, while biotechnology sponsors prioritize supply reliability over unit cost for commercial-stage biologics.
Supply Chain Analysis
Contract manufacturing concentration at Siegfried Holding AG and Corden Pharma GmbH anchors mid-scale capacity for European biotech sponsors. API supply draws from India, China, and domestic German facilities, with Kharasch reaction precursors and organometallic catalysts sourcing predominantly from Chinese specialty chemical producers. Single-source vulnerability concentrates in palladium-catalyzed cross-coupling intermediates subject to REACH authorization delays. Distribution runs through pharmaceutical manufacturers with captive logistics networks and specialized cold-chain CMOs handling biologic APIs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German API incumbents face substitution defense imperatives as biocatalytic routes displace traditional solvent-intensive synthesis, threatening the technical moats that currently justify premium positioning.
For Market Incumbents: Pre-empt biocatalysis disruption by acquiring protein engineering capabilities from Heidelberg and Mannheim academic partnerships before scale-up talent pools deplete further. Anchor backward integration into fermentation raw materials to offset energy cost volatility at Ludwigshafen and Bavarian production sites. Lock in biotechnology sponsor relationships through co-investment in dedicated single-use bioreactor lines that raise switching costs.
For New Entrants and Emerging Players: Underutilized capacity in Lower Saxony antibiotic fermentation offers white-space entry for narrow-spectrum beta-lactam compounds as antimicrobial stewardship policies reshape hospital procurement. Target the Baden-Württemberg biotech corridor with modular microreactor platforms that bypass legacy explosion-proof infrastructure requirements. Lead with EMA submission expertise and electronic batch record capabilities to differentiate against paper-based mid-tier CMOs.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across continuous manufacturing retrofit programs as AI-driven process control systems require substantial upfront investment. Prioritize acquisition targets with captive stability testing infrastructure and existing EMA master file submissions that compress regulatory timelines for sponsor transitions. Monitor EU delegated acts under the pharmaceutical strategy for early signals of local manufacturing obligation expansion that would revalue domestic production assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Retrofit | Microreactor deployment at Hesse facilities satisfies EU Green Deal solvent recovery mandates while reducing batch-to-batch variability. |
| Biocatalysis Partnership | Academic collaboration in Mannheim addresses enzyme engineering scarcity constraining green synthesis route scale-up. |
| Carbon Border Adjustment Compliance | Early documentation positioning at Rhine-Main cluster sites creates tariff arbitrage against Indian and Chinese import competition. |
| Biotech Sponsor Co-Investment | Dedicated production line commitments in Bavaria secure capacity allocation for commercial-stage monoclonal antibody transitions. |
| EMA Electronic Data Integrity Upgrade | ERP overhaul at mid-tier CMOs aligns with regulator push for paperless batch records and real-time quality assurance. |
Research Methodology
A spread of perspectives from fermentation plant managers, regulatory affairs leads at EMA-submission sponsors, hospital procurement directors, and specialty chemical distribution partners converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against EMA marketing authorization databases, REACH registration filings, and customs trade records. Bottom-up capacity utilization estimates from Ludwigshafen, Bavarian, and Baden-Württemberg facilities triangulated against top-down demand projections from European hospital procurement networks and biotechnology pipeline databases.
Demand-supply-balance modeling across the analysis window integrated patient population forecasts, treatment line penetration assumptions, and manufacturing capacity expansion timelines. Segmentation dimensions included synthesis technology, therapeutic application, and regulatory compliance tier. CAGRs derived from volume trajectory analysis of fermentation output and chemical synthesis campaigns, cross-referenced with sponsor R&D pipeline disclosures and EMA approval pathway timelines.
Practitioners should monitor EU pharmaceutical strategy delegated acts, carbon border adjustment tariff schedules, and REACH authorization delays for early signals of forecast revision. Quarterly review of natural gas price indices, biotech sponsor financing rounds, and EMA GMP inspection enforcement patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Oridonin Market
Pharmaceutical Ingredients
Medicinal Chemistry for Drug Discovery Market
Pharmaceutical Ingredients
Pharmaceutical Grade Sodium Carbonate Market
Pharmaceutical Ingredients
Calcium Folinate for Injection Market
Pharmaceutical Ingredients
Small-Molecule Injectable Market
Pharmaceutical Ingredients
Antipyretic Analgesic Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Hyaluronic Acid Raw Material Market
Pharmaceutical Ingredients
Global Tizanidine Market
Pharmaceutical Ingredients
Cyclooxygenase 2 Inhibitor Market
Pharmaceutical Ingredients
Global High Potency Active Pharmaceutical Ingredient (HPAPI) Market
Pharmaceutical Ingredients
Global Fibrate Drugs Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Pharmaceuticals Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Quinoline Market
Pharmaceutical Ingredients
Antibiotics Active Pharmaceutical Ingredient (API) Market