
 Hyaluronic Acid Products Market | 2026-2036
Hyaluronic Acid Products Market Size, Share, and Industry Trends Forecast 2026-2036
Hyaluronic Acid Products Market Outlook
Injectable-grade formulation revenue is reconfiguring margin pools away from topical cosmetics toward regulated medical devices. Galderma S.A. dominates the aesthetic injectables channel through its Restylane portfolio and direct clinician relationships. AbbVie Inc leverages its Allergan Aesthetics division to sustain high-margin dermal filler sales across North American and European markets. Seikagaku Corporation anchors the orthopedic viscosupplementation segment with proprietary high-molecular-weight production technology.
Hyaluronic acid products comprise biocompatible glycosaminoglycan formulations synthesized through bacterial fermentation or avian extraction, with molecular weights spanning 50 kDa to 6 MDa determining tissue residency and mechanical properties. These products serve therapeutic and cosmetic functions ranging from joint lubrication to dermal volume restoration and ocular surface hydration. The injections segment commands premium pricing due to sterilization requirements and clinical administration protocols, while creams and gels occupy mass-market channels with lower regulatory barriers. Dermatology and aesthetic applications lead volume consumption, whereas ophthalmology sustains steady demand through surgical adjuvant use.
The FDA enforces Good Manufacturing Practice standards for injectable hyaluronic acid under device regulations, while the EMA's Medical Device Regulation imposes stricter clinical evidence requirements for CE-marked dermal fillers. REACH compliance in Europe governs raw material sourcing transparency, particularly for crosslinking agents used in gel formulations. Stakeholders must monitor evolving purity specifications and traceability mandates that will determine manufacturing cost structures and market access eligibility.
Market Dynamics
Injectable-grade hyaluronic acid production is consolidating around high-molecular-weight bacterial fermentation platforms as FDA and EMA purity mandates render small-batch avian extraction economically unviable for medical device applications.
Growth Catalysts
- MDR Clinical Evidence Requirements:The EMA's Medical Device Regulation is compressing competitor pipelines by mandating extended safety studies for CE-marked dermal fillers, favoring incumbent manufacturers with established clinical dossiers.
- Orthopedic Viscosupplementation:Aging populations in Germany and Japan are expanding intra-articular injection volumes for osteoarthritis management, driving demand for high-viscosity formulations with extended joint residency.
- Crosslinking Chemistry Advances:Novel BDDE-free crosslinking technologies are enabling longer-lasting gel matrices that reduce patient touch-up frequency and improve practitioner throughput.
Market Restraints
- Raw Material Concentration:Pharmaceutical-grade sodium hyaluronate supply concentrates among three fermentation specialists, creating input vulnerability for mid-tier formulators lacking backward integration.
- Avian Extraction Cost Volatility:Rooster comb sourcing costs fluctuate with poultry commodity cycles and avian influenza containment protocols, pressuring margins for manufacturers dependent on traditional extraction methods.
- Substitution Threat from Calcium Hydroxylapatite:Longer-lasting synthetic fillers are capturing volume in deep dermal and subdermal applications where HA's shorter duration disadvantages premium positioning.
Strategic Opportunities
- Men's Aesthetic Segment:Underpenetrated male patient populations in the United States and United Kingdom present whitespace as social stigma erodes and targeted marketing protocols emerge.
- Combination Device-Drug Platforms:Convergence of HA carriers with botulinum toxin or biostimulatory agents is creating novel therapeutic categories requiring differentiated regulatory pathways.
- Direct-to-Clinic Distribution:Bypassing traditional aesthetic distributors through proprietary e-commerce portals and inventory management apps is capturing margin from consolidated group purchasing organizations.
Industry Challenges
- Biopolymer Purification Expertise Gap:Scarcity of process engineers capable of scaling GMP-compliant endotoxin removal and molecular weight fractionation is constraining capacity expansion timelines.
- MDR Technical Documentation Burden:Small and mid-sized manufacturers face 18-24 month certification delays as notified bodies struggle with post-MDR transition backlogs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyaluronic Acid Products Market |
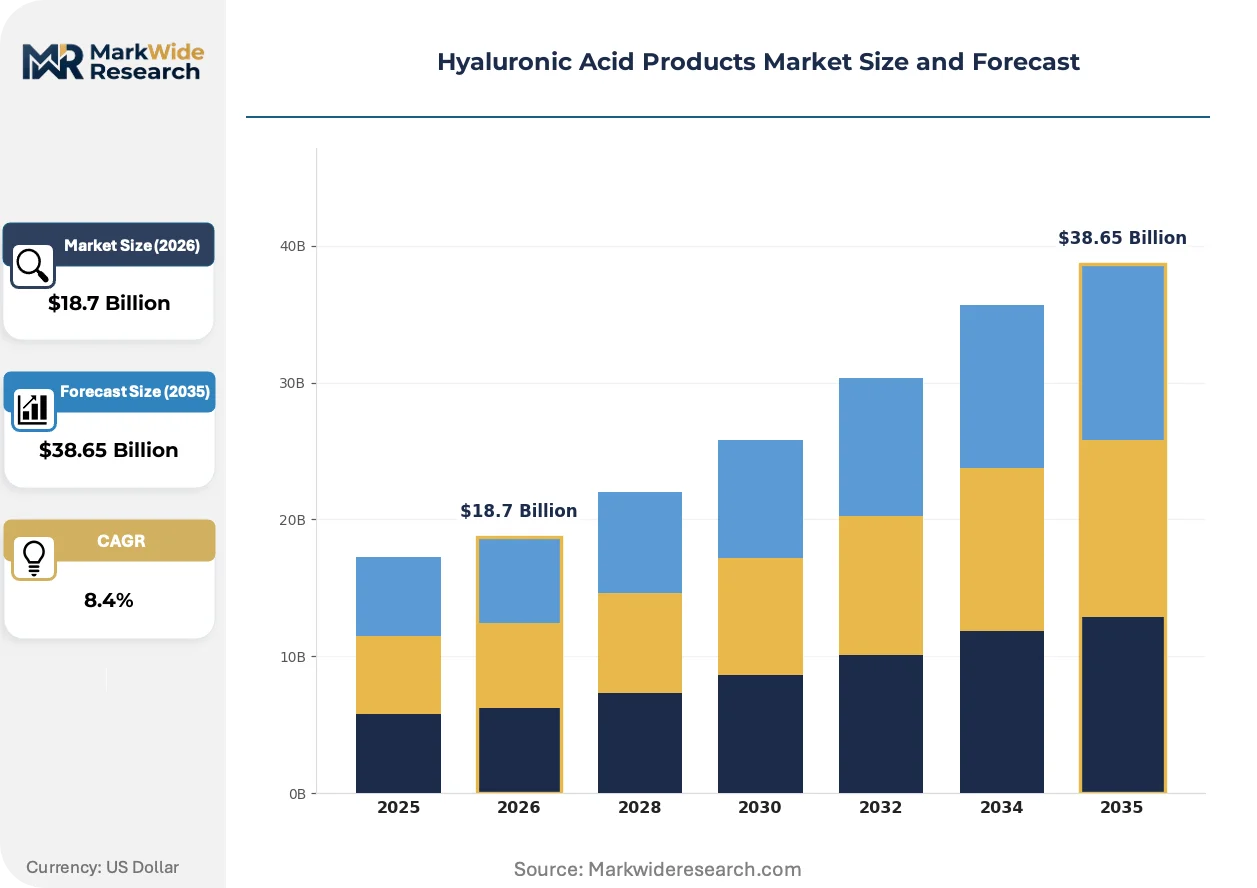
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sera, Creams, Gels, Injections Application: Dermatology, Ophthalmology, Orthopedics, Aesthetic End User: Hospitals, Clinics, Homecare, Beauty Clinics Distribution Channel: Online, Retail, Pharmacies, Direct Sales |
| Companies Covered | AbbVie Inc, Anika Therapeutics, Inc., Galderma S.A., Seikagaku Corporation, Bioventus Inc., Sanofi, Alcon, Fidia Farmaceutici S.p.A., Bloomage Biotechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyaluronic Acid Products Market Strategic Shifts
Formulation science is pivoting toward tunable degradation profiles and bioactive modifications that extend functional duration while preserving the reversibility that distinguishes HA from permanent implants.
Multi-crosslink density gel architectures are hybridizing single-phase and biphasic rheological properties within single syringe formulations. Aesthetic practitioners in South Korea and Brazil are adopting these hybrid matrices at accelerating rates for simultaneous volumization and superficial line correction. The technology is hybridizing previously distinct product tiers, compressing SKU proliferation and forcing portfolio consolidation among manufacturers with redundant legacy lines.
REACH transparency mandates for crosslinking agent sourcing are compelling European manufacturers to document supply chain provenance for BDDE and DVS reagents. Industrial consequence includes accelerated qualification of alternative chemistries with superior toxicological profiles. Dermal filler segments bound for EU distribution are responding with dedicated production runs employing REACH-compliant raw material streams, bifurcating global formulation specifications.
Clinician procurement patterns are consolidating around outcome-guarantee contracts that bundle product supply with complication management and patient satisfaction warranties. Aesthetic clinic chains in Australia and Canada are displacing transactional purchasing with multi-year vendor partnerships incorporating volume commitments and exclusive territory arrangements. This restructuring concentrates purchasing power among consolidated practice groups, compressing pricing leverage for manufacturers without differentiated clinical support infrastructure.
Hyaluronic Acid Products Market Segmentation
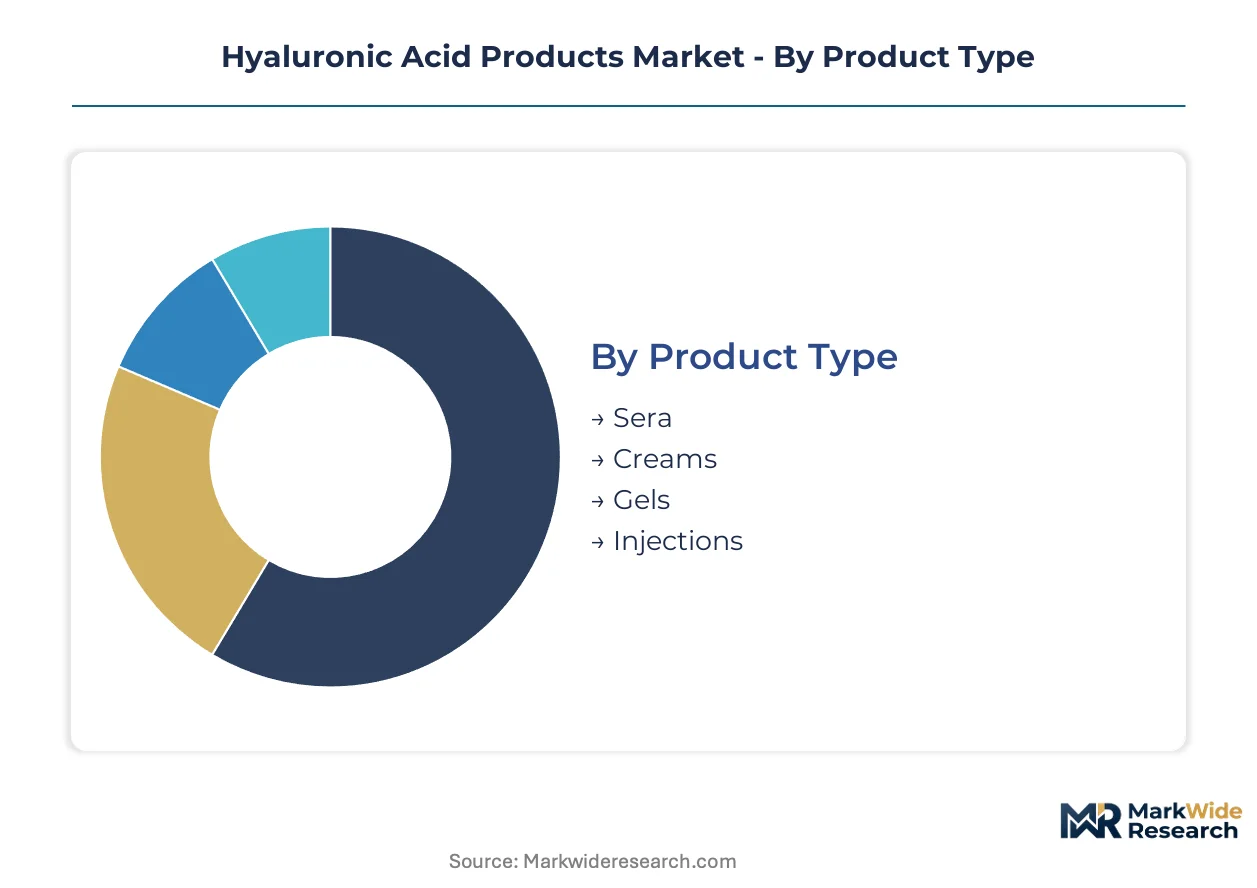
Hyaluronic acid products span radically different value chains depending on molecular weight, sterility requirements, and administration protocols. Segmentation reveals how formulation grade dictates pricing power, regulatory burden, and channel economics across therapeutic and cosmetic applications.
Product Type:
Injectable formulations command the steepest price premiums due to sterilization validation and clinical administration requirements, while topical formats compete on volume and accessibility.
- Injections:Sterile, crosslinked gel matrices requiring GMP-certified manufacturing and endotoxin control below 0.5 EU/mL. Demand concentrates in aesthetic clinics across the United States and South Korea, where practitioner certification programs and direct-to-clinic distribution models sustain margin structures.
- Creams:Low-molecular-weight formulations (50-500 kDa) optimized for epidermal penetration without injection trauma. Mass-market adoption in Japan and Germany drives volume, though price compression from private-label competition constrains manufacturer profitability.
- Gels:Semi-occlusive topical vehicles bridging cosmetic and quasi-medical positioning, often bundled with post-procedure protocols in dermatology practices.
- Sera:Concentrated aqueous solutions for targeted hydration, prevalent in Korean beauty retail and professional spa channels.
The dominant share belongs to Injections, while Creams is closing the gap fastest through pharmacy channel expansion and cosmeceutical positioning.
Application:
Clinical outcomes and reimbursement status fragment the market into insured therapeutic use and out-of-pocket aesthetic consumption with divergent growth trajectories.
- Aesthetic:Dermal volumization and wrinkle correction using crosslinked HA with tunable degradation profiles. United States outpatient procedure volumes and Brazilian clinic density sustain the highest per-unit pricing globally.
- Dermatology:Wound healing, scar revision, and barrier repair applications leveraging HA's moisture-retention properties. German and Swiss dermatology practices favor prescription-grade topical formulations with documented clinical evidence.
- Orthopedics:Intra-articular viscosupplementation for osteoarthritis management, with Japanese and German aging populations driving repeat injection cycles.
- Ophthalmology:Surgical adjuvants for cataract extraction and corneal protection, characterized by stable demand from hospital operating theaters and limited substitution risk.
Aesthetic captures the largest revenue pool, though Orthopedics is expanding most quickly through aging demographics and extended joint residency formulations.
End User:
Facility type determines procurement sophistication, with institutional buyers demanding outcome guarantees and individual practitioners prioritizing inventory flexibility.
- Beauty Clinics:Specialized aesthetic practices with high patient throughput and preference for multi-crosslink density portfolios. Australian and Canadian clinic chains are consolidating purchasing through multi-year vendor partnerships with exclusive territory arrangements.
- Hospitals:Orthopedic and ophthalmic surgical departments with formal tender processes and group purchasing organization affiliation. EMA MDR compliance documentation weighs heavily in supplier selection.
- Clinics:Mixed dermatology and aesthetic practices with moderate volume and price sensitivity to distributor markups.
- Homecare:Self-administered topical use through retail and e-commerce channels, with minimal regulatory oversight and highest price elasticity.
Beauty Clinics command the steepest pricing tier, while Hospitals are gaining procurement leverage fastest through GPO consolidation.
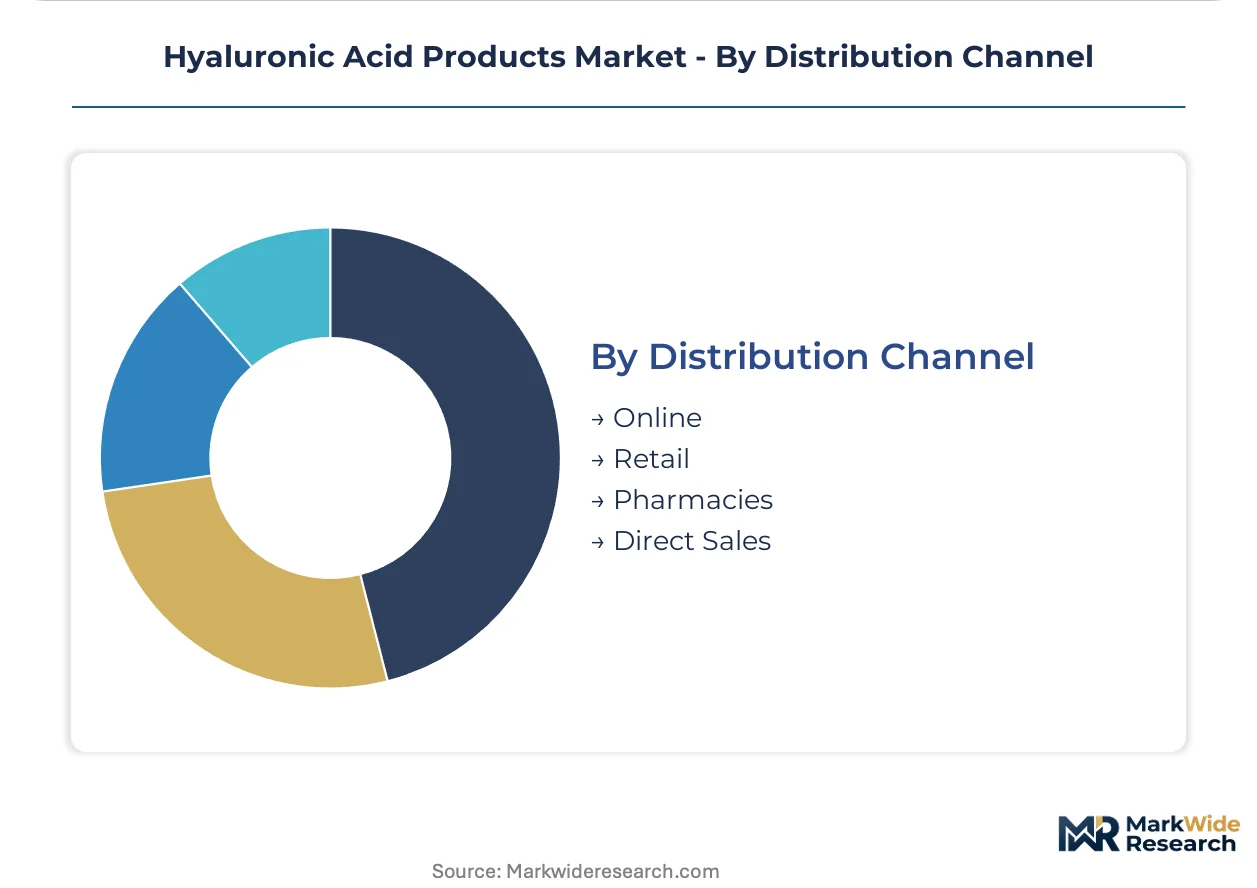
Distribution Channel:
Channel selection reflects product classification, with regulated devices requiring traceable supply chains and cosmetics exploiting digital reach.
- Direct Sales:Manufacturer-to-clinic relationships for injectable devices, capturing margin from distributor intermediaries. Galderma and AbbVie Aesthetics deploy field forces for clinical training and inventory management.
- Pharmacies:Regulated access point for prescription-grade topical and ophthalmic formulations in Germany, Japan, and Switzerland.
- Online:E-commerce portals and clinic-facing apps for consumable replenishment, accelerating in South Korea and the United States.
- Retail:Mass-market cosmetics placement in beauty specialty and department stores, concentrated in Asian urban centers.
Direct Sales retains the highest value capture, though Online is climbing the fastest as inventory management apps displace traditional distributor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for hyaluronic acid products diverges sharply across geographies. Brazilian and South Korean consumers absorb premium pricing for aesthetic injectables with minimal volume sensitivity, while German and Japanese procurement offices drive hard bargains on orthopedic viscosupplementation through tender processes.
United States
Outpatient cosmetic procedure volumes sustain the world's highest per-unit pricing for dermal fillers. FDA Good Manufacturing Practice enforcement under device regulations elevates compliance costs for entrants. Los Angeles and Miami clinic clusters concentrate demand for multi-crosslink density portfolios with outcome-guarantee contracts.
Germany
Aging demographics expand intra-articular injection cycles for osteoarthritis management. EMA Medical Device Regulation imposes extended clinical evidence requirements that compress competitor pipelines. Berlin and Munich hospital networks leverage group purchasing organization consolidation to extract price concessions on viscosupplementation.
South Korea
Aesthetic clinic density per capita exceeds all other markets, driving rapid adoption of hybrid gel architectures. MFDS maintains stringent purity standards for injectable grades that favor established manufacturers. Seoul's Gangnam district functions as a global trendsetter for formulation preferences and practitioner training protocols.
Brazil
Social acceptance of cosmetic procedures sustains premium consumption despite macroeconomic volatility. ANVISA registration requirements create lead-time barriers for new entrants. São Paulo's clinic chains are consolidating purchasing through multi-year vendor partnerships with exclusive territory arrangements.
Japan
Elderly population ratios drive repeat injection demand for joint lubrication therapies. PMDA enforces pharmacovigilance reporting that extends post-market surveillance burdens. Osaka and Nagoya orthopedic centers favor high-molecular-weight formulations with documented extended joint residency.
Hyaluronic Acid Products Market Competitive Environment
Capability concentration sits with fermentation technology specialists; scale advantage sits with diversified pharmaceutical conglomerates. The market exhibits tiered structure with three to five fermentation specialists controlling pharmaceutical-grade sodium hyaluronate supply, while downstream formulators fragment across aesthetic, orthopedic, and ophthalmic applications. Strategic archetypes include backward-integrated fermentation leaders, brand-dependent aesthetic device marketers, and contract manufacturing organizations serving institutional tenders. Dominant competitive moves encompass direct-to-clinic distribution bypasses and multi-year exclusive partnership contracts with consolidating clinic chains.
Within the diversified pharmaceutical tier, AbbVie Inc and Sanofi exemplify scale-driven positioning through aesthetic and ophthalmic divisions respectively. Among fermentation specialists, Seikagaku Corporation occupies a position representing high-molecular-weight production technology leadership. Galderma S.A. anchors the aesthetic injectables channel archetype through direct clinician relationship models.
| Leading Market Players |
|---|
| AbbVie Inc |
| Anika Therapeutics, Inc. |
| Galderma S.A. |
| Seikagaku Corporation |
| Bioventus Inc. |
| Sanofi |
| Alcon |
| Fidia Farmaceutici S.p.A. |
| Bloomage Biotechnology |
| Others |
Value Chain & Pricing Dynamics
Shandong Province's fermentation capacity clusters anchor global pharmaceutical-grade sodium hyaluronate output, with bacterial fermentation platforms in Weifang and Jinan feeding downstream pricing power to crosslinked gel formulators who command premium positioning in aesthetic clinics across the United States and South Korea.
Pricing Analysis
Outcome-guarantee contracts bundling product supply with complication management drive lifetime value for clinic chains. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified injectable grades from cosmetic-grade topicals and mass-market creams. Cost compression in the topical segment is intensifying because private-label competition from Korean and Japanese retailers erodes branded positioning. Homecare self-administered products exhibit highest price elasticity, while beauty clinics with exclusive territory arrangements absorb premium pricing with minimal volume sensitivity.
Supply Chain Analysis
Pharmaceutical-grade sodium hyaluronate feedstock concentrates in China, Japan, and South Korea among fermentation specialists with proprietary high-molecular-weight platforms. Downstream formulation draws from rooster comb extraction for select orthopedic applications and bacterial fermentation for injectable medical devices. Single-source vulnerability concentrates among three fermentation specialists controlling input supply for mid-tier formulators lacking backward integration. Distribution runs through direct-to-clinic portals and field force relationships for injectable devices, bypassing traditional aesthetic distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as men's aesthetic demand and combination device-drug platforms create niches underserved by incumbent portfolios optimized for traditional dermal volumization applications.
For Market Incumbents: Pre-empt substitution threats from calcium hydroxylapatite fillers in deep dermal applications by accelerating BDDE-free crosslinking chemistry deployment and securing exclusive multi-year partnerships with consolidating Australian and Canadian clinic chains before competitors establish clinical training infrastructure. For New Entrants and Emerging Players: Pursue underpenetrated male patient populations in the United States and United Kingdom through targeted marketing protocols and direct-to-clinic e-commerce portals that bypass established distributor relationships controlling legacy aesthetic channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation specialists with captive GMP-certified capacity and proprietary endotoxin removal expertise; acquisition targets should demonstrate scalable molecular weight fractionation capabilities and established FDA or EMA clinical dossiers. Watch for inflection signals in men's aesthetic procedure volumes as validation of whitespace thesis.| Strategic Initiative | Industry Significance |
|---|---|
| BDDE-Free Crosslinking Chemistry Development | Novel gel matrices with superior toxicological profiles address REACH compliance mandates in European markets. |
| Direct-to-Clinic Distribution Portal Launch | Proprietary e-commerce platforms capture margin from consolidated group purchasing organizations in North America. |
| Men's Aesthetic Marketing Protocol Investment | Targeted campaigns erode social stigma and unlock whitespace in underpenetrated male patient demographics. |
| Combination Device-Drug Platform Partnership | Convergence with botulinum toxin carriers creates novel therapeutic categories requiring differentiated regulatory pathways. |
| High-Molecular-Weight Fermentation Capacity Expansion | GMP-certified bacterial fermentation platforms satisfy FDA and EMA purity mandates for orthopedic viscosupplementation. |
Study Parameters
Desk research of FDA 510(k) filings, EMA MDR technical documentation, and pharmaceutical trade customs data preceded structured interviews with aesthetic clinic medical directors, orthopedic surgeons, GPO contracts managers, and fermentation platform process engineers. Primary fieldwork with downstream formulators and upstream raw material suppliers combined with secondary validation against hospital procurement databases and clinic chain purchasing records. Bottom-up volume triangulation across product grades, applications, and end-user facilities reconciled against top-down market sizing from regulatory submission trends.
Assumptions held fixed include FDA and EMA purity standard trajectories, while variables encompassed men's aesthetic adoption curves and REACH crosslinking agent sourcing transitions across the analysis window. Segmentation modeling incorporated molecular weight tiers, sterility requirements, administration protocols, and regional regulatory clusters. CAGRs derived from procedure volume elasticity analysis and per-unit pricing trajectory assessment, with inputs from aging demographic projections and outpatient cosmetic surgery trend data.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending or poultry commodity cycles would shift the trajectory for topical and avian-extracted segments respectively. Cross-checking against Medicare reimbursement rate filings for orthopedic viscosupplementation and private-pay aesthetic procedure reporting is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Specialty Fuel Additives Market
Specialty Chemicals
UV Filters Market
Specialty Chemicals
Global Blowing Agent Market
Specialty Chemicals
Superoxide Dismutase Market
Specialty Chemicals
Shikimic Acid Market
Specialty Chemicals
Automotive Silicone Market
Specialty Chemicals
Methyl Salicylate Market
Specialty Chemicals
Solanesol Market
Specialty Chemicals
Global Bio Based Esters Market
Specialty Chemicals
Polyphosphate Market
Specialty Chemicals
Alkylene Carbonates Market
Specialty Chemicals
Global Curing Agents Market
Specialty Chemicals
PPG-20 Methyl Glucose Ether Market
Specialty Chemicals
LAMEA Metal Biocides Market
Specialty Chemicals
Global Fabric Softener Sheet Market
Specialty Chemicals
Marine Hyaluronic Acid Market