
 Pharmaceutical Excipients for Taste Masking Market | 2026-2036
Pharmaceutical Excipients for Taste Masking Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Excipients for Taste Masking Market Outlook
Project finance for dedicated excipient manufacturing facilities is fragmenting competitive barriers in taste masking, allowing mid-scale entrants to access multi-purpose coating lines without full capital ownership. BASF SE leverages its polymer chemistry backbone to sustain leadership in methacrylate-based coating systems across oral solid dosage forms. Evonik Industries AG anchors its position through backward integration into amino methacrylate copolymer production, controlling raw material quality for high-performance taste barriers. SPI Pharma differentiates via ion-exchange resin complexation technologies that compete directly with traditional polymer coatings in liquid formulation applications.
Pharmaceutical excipients for taste masking comprise functional additives—primarily polymers, sweeteners, and ion-exchange resins—that chemically or physically block interaction between bitter APIs and human taste receptors, typically achieving bitterness suppression thresholds below detection limits of microgram-per-milliliter concentrations. Their primary commercial purpose centers on enabling pediatric, geriatric, and psychiatric medication adherence where palatability directly determines therapeutic outcomes. Coatings dominate current formulation portfolios due to established process compatibility with standard fluid-bed equipment, while complexation agents represent the fastest-expanding segment as manufacturers seek aqueous-compatible alternatives for heat-sensitive biologics. Immediate release formulations occupy the largest volume share, though sustained release taste-masked systems command premium positioning through differentiated pharmacokinetic profiles.
FDA guidance on pediatric formulation development and EMA's quality-by-design expectations for oral dosage forms collectively elevate documentation requirements for taste masking efficacy, pushing manufacturers toward validated in-vitro dissolution models. USP-NF monographs for specific coating polymers and the ICH Q3D elemental impurity guidelines further constrain supplier qualification, favoring excipient producers with established regulatory dossiers. Stakeholders must monitor evolving pharmacopeial standards for novel natural disguisers and decide whether to build in-house taste assessment capabilities or outsource to specialized contract research organizations.
Market Dynamics
The shift from solvent-based to aqueous coating systems is restructuring competitive advantage in taste masking, as pharmaceutical manufacturers face mounting pressure from pediatric formulation guidelines and sustainability mandates.
Growth Catalysts
- Pediatric formulation mandates:FDA guidance on pediatric drug development compels manufacturers to prioritize palatability in new molecular entity filings, expanding the addressable base for advanced masking technologies.
- Geriatric polypharmacy trends:Aging populations across developed economies generate sustained demand for multi-dose regimens where taste acceptance determines adherence rates.
- Biologics expansion:Heat-sensitive protein and peptide formulations require aqueous-compatible masking approaches that bypass traditional thermal coating processes.
Market Restraints
- Specialty polymer supply concentration:Amino methacrylate copolymer production clusters among three European chemical conglomerates, creating single-source vulnerability for high-barrier coatings.
- Regulatory dossier accumulation costs:USP-NF monograph compliance and ICH Q3D elemental impurity documentation impose six-figure qualification burdens that exclude regional excipient suppliers.
- Natural disguiser performance gaps:Botanical taste modifiers from stevia and monk fruit extracts fail to achieve microgram-per-milliliter suppression thresholds required for highly bitter APIs.
Strategic Opportunities
- Indian contract manufacturing expansion:CDSCO's streamlined excipient approval pathways and PLI scheme incentives position domestic suppliers to capture share in generic oral solid dosage exports.
- Orally disintegrating tablet formats:ODT platforms for psychiatric and neurologic indications create demand for rapid-dissolve masking systems that maintain bioavailability.
- Quality-by-design integration:EMA's QbD expectations for oral dosage forms reward excipient producers offering validated in-vitro dissolution models as bundled regulatory support.
Industry Challenges
- In-vitro taste assessment standardization:Lack of harmonized protocols between electronic tongue systems and human panel correlation creates validation bottlenecks for new excipient submissions.
- Fluid-bed coating scale-up complexity:Transfer from pilot to commercial batch sizes frequently compromises coating uniformity, requiring dedicated process engineering talent that mid-scale CDMOs struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Excipients for Taste Masking Market |
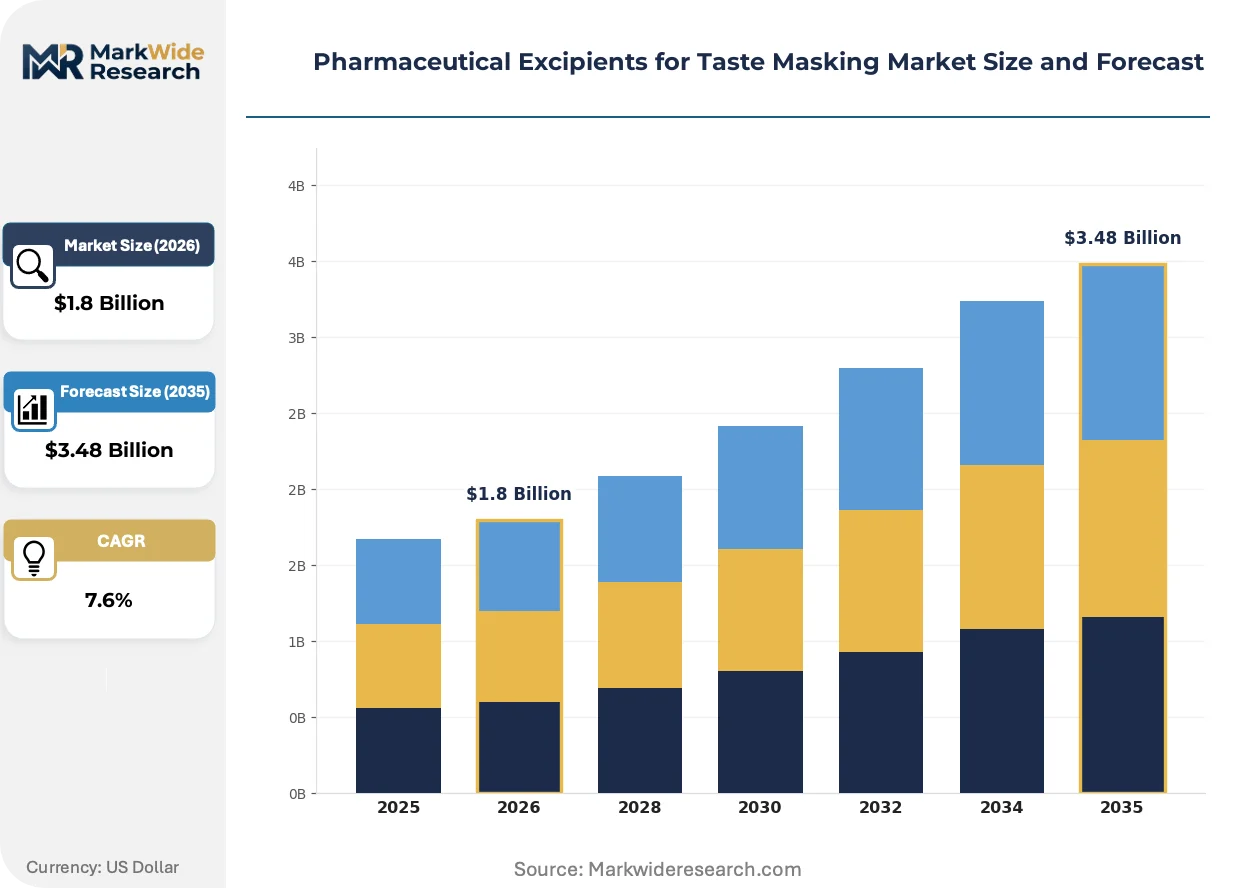
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coatings, Complexation Agents, Sweeteners, Disguisers Application: Oral Solutions, Solid Dosage Forms, Liquid Formulations, Chewable Tablets Delivery Mode: Tablets, Capsules, Powders, Liquids Formulation Type: Immediate Release, Sustained Release, Controlled Release, Taste-Masked Formulations |
| Companies Covered | SPI Pharma, DuPont de Nemours, Dow Pharma Solutions, Roquette Frères, Asahi Kasei Corporation, BASF SE, Evonik Industries AG, Colorcon Inc., Ashland Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Excipients for Taste Masking Market Strategic Shifts
Formulation science is converging with sensory evaluation methods to create predictive bitterness suppression systems that reduce reliance on iterative human taste panels.
Hot-melt extrusion combined with lipid-based carriers is rendering obsolete conventional aqueous coating approaches for moisture-sensitive APIs, with specialty CDMOs in New Jersey and Pennsylvania adopting continuous processing lines to serve biotech clients developing heat-labile compounds.
REACH restrictions on residual solvent content in pharmaceutical coatings are forcing European manufacturers to abandon ethyl acetate and acetone-based systems, accelerating migration to supercritical carbon dioxide coating technologies that eliminate organic solvent recovery infrastructure entirely.
Buyer consolidation among the top fifteen global generic pharmaceutical firms is compressing excipient supplier rosters, with procurement teams demanding integrated taste assessment services and regulatory documentation packages that only integrated polymer producers can deliver at scale.
Pharmaceutical Excipients for Taste Masking Market Segmentation
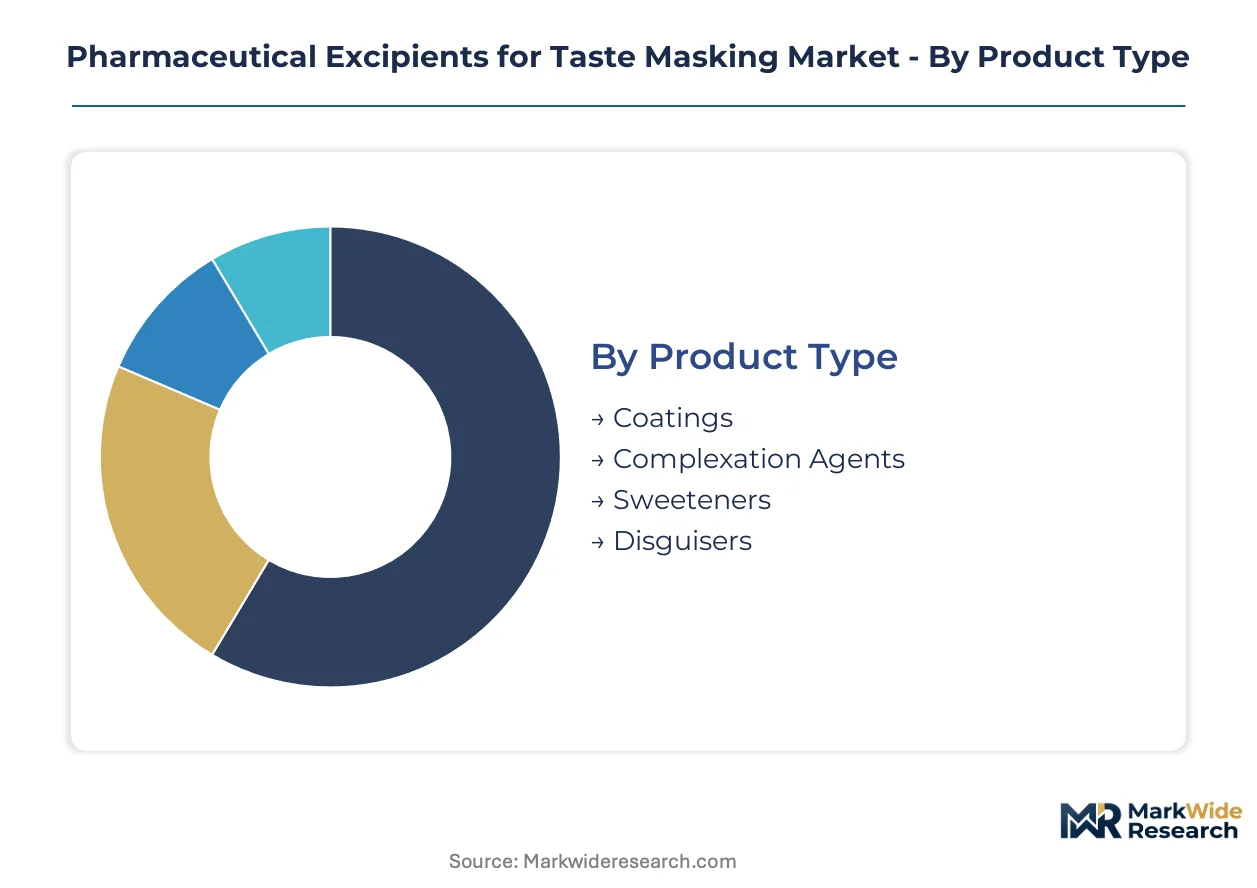
Segmentation in taste masking excipients reveals how formulation requirements diverge across pediatric, geriatric, and psychiatric patient populations. Each dimension—product chemistry, application format, delivery mode, and release kinetics—creates distinct supplier qualification criteria and regulatory documentation burdens.
Product Type:
Mature polymer systems dominate current manufacturing capacity while emerging molecular complexation approaches capture biologics-oriented demand.
- Coatings:Methacrylate and ethylcellulose film-forming systems constitute the established standard for oral solid dosage forms. Fluid-bed coating equipment in New Jersey and Pennsylvania pharmaceutical corridors processes the majority of pediatric tablet volumes, though REACH solvent restrictions are forcing aqueous formulation migrations.
- Complexation Agents:Ion-exchange resins and cyclodextrin inclusion complexes enable bitterness suppression without thermal processing. SPI Pharma's resin technologies compete directly with polymer coatings in liquid applications where heat-sensitive biologics require aqueous-compatible masking.
- Sweeteners:High-intensity compounds including sucralose and neotame provide palatability enhancement for liquid formulations.
- Disguisers:Flavor-masking systems using botanical extracts and synthetic flavor compounds complement primary masking technologies.
Coatings retain volume leadership across oral solid dosage production; complexation agents hold the steepest expansion curve as biologics pipelines mature.
Application:
Cost tier stratification separates commodity liquid formulations from premium-positioned solid dosage development programs.
- Oral Solutions:Liquid formulations for pediatric and geriatric populations require water-soluble masking systems compatible with standard bottling lines. FDA pediatric guidance mandates palatability validation for new molecular entity filings in this category.
- Solid Dosage Forms:Tablets and capsules dominate commercial volumes through established coating infrastructure. BASF SE's methacrylate systems serve the majority of immediate-release and sustained-release applications across North American and European manufacturing sites.
- Liquid Formulations:Suspensions and syrups demand rapid-dissolve masking without coating equipment investment.
- Chewable Tablets:Orally disintegrating formats for psychiatric and neurologic indications create specialized taste assessment requirements.
Solid dosage forms retain volume leadership; chewable tablets hold the steepest expansion curve as psychiatric medication adherence gains priority.
Delivery Mode:
Customer type differentiation separates hospital pharmacy procurement from retail channel formulations.
- Tablets:Film-coated and sugar-coated tablets represent the most mature taste masking application with standardized USP-NF monograph compliance pathways.
- Capsules:Gelatin and HPMC capsule shells incorporate bitter API isolation through enteric coatings or powder blending with excipient matrices.
- Powders:Sachet and bulk powder formulations for reconstitution require granulation-stage masking prior to packaging.
- Liquids:Ready-to-use oral solutions bypass coating infrastructure entirely, relying on complexation and sweetener combinations.
Tablets retain volume leadership; liquids hold the steepest expansion curve as geriatric polypharmacy drives adherence-focused formulation design.
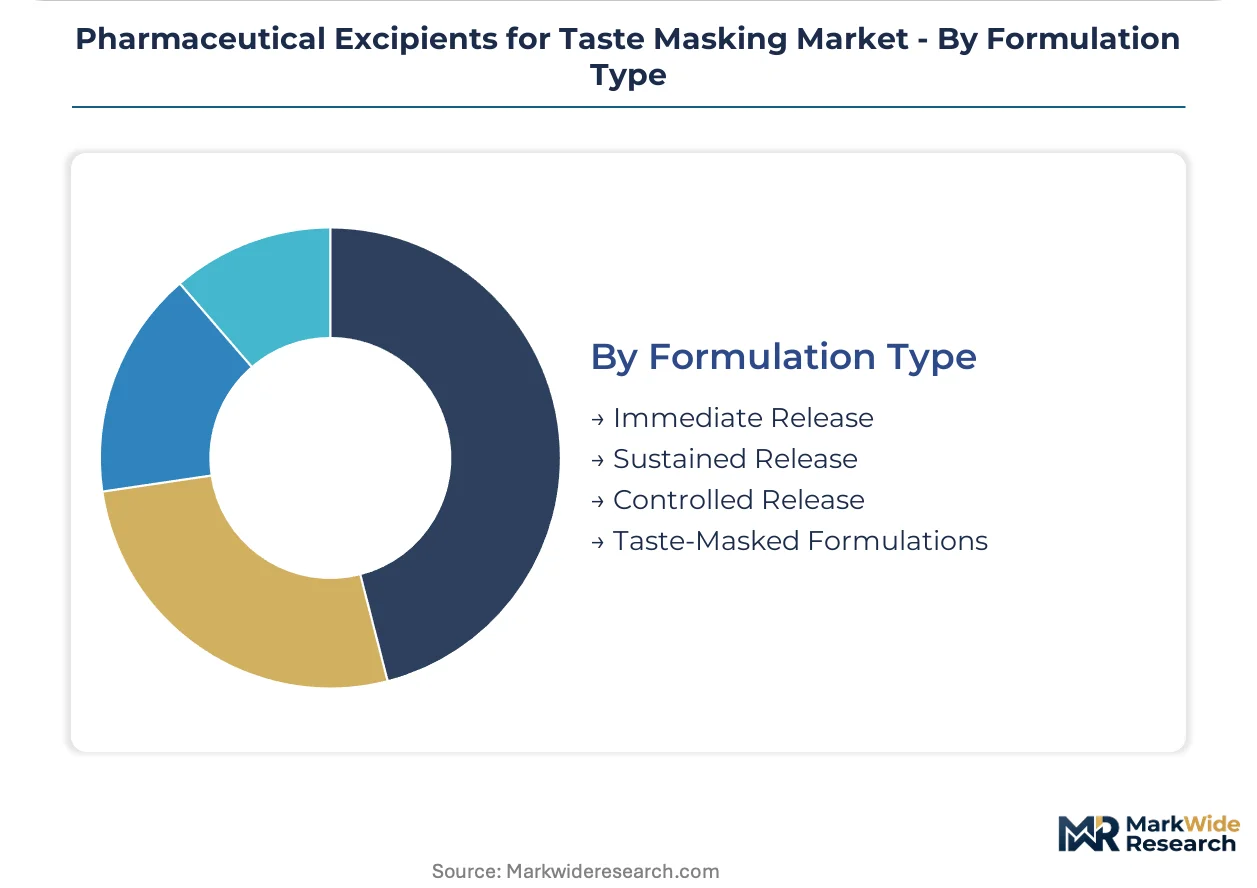
Formulation Type:
Margin structure separates immediate-release commodities from sustained-release premium positioning.
- Immediate Release:Rapid-disintegration formulations with standard coating thickness dominate generic pharmaceutical procurement. Evonik Industries AG's amino methacrylate copolymers serve high-volume immediate-release applications through backward-integrated raw material control.
- Sustained Release:Extended-delivery taste-masked systems command differentiated pharmacokinetic premiums through multi-layer coating architectures and pore-forming excipient combinations.
- Controlled Release:Zero-order and pulsatile delivery systems integrate taste masking with precise release kinetics for chronotherapeutic applications.
- Taste-Masked Formulations:Dedicated development programs optimize palatability as primary design objective rather than secondary coating consideration.
Immediate release retains volume leadership; taste-masked formulations hold the steepest expansion curve as pediatric drug development guidelines harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA pediatric formulation guidance and CDSCO's PLI scheme incentives are redirecting manufacturing investment toward specialized taste masking facilities in North America and South Asia.
United States
Specialty excipient production clusters around New Jersey and Pennsylvania pharmaceutical corridors where fluid-bed coating infrastructure serves pediatric tablet volumes. FDA guidance on pediatric drug development mandates palatability validation for new molecular entity filings. Philadelphia-area CDMOs are adopting continuous processing lines for heat-labile compounds.
Germany
REACH restrictions on residual solvent content are forcing abandonment of ethyl acetate and acetone-based coating systems. EMA quality-by-design expectations elevate documentation requirements for taste masking efficacy. Ludwigshafen and Frankfurt chemical hubs anchor methacrylate copolymer production for oral solid dosage exports.
India
CDSCO streamlined excipient approval pathways reduce qualification timelines for domestic suppliers entering generic oral solid dosage export markets. PLI scheme incentives support multi-purpose coating line investments without full capital ownership. Hyderabad and Ahmedabad pharmaceutical corridors attract project finance for dedicated excipient manufacturing.
Japan
PMDA expectations for pediatric formulation development align with global regulatory convergence on taste assessment protocols. METI industrial policy supports aqueous-compatible masking technology transfers from European partners. Osaka-Kobe chemical manufacturing belt concentrates ion-exchange resin complexation capacity.
Switzerland
Swissmedic pharmacopeial standards for novel natural disguisers create qualification pathways for botanical extract suppliers. Basel-region polymer chemistry heritage sustains backward-integrated amino methacrylate production. Geneva-area CROs specialize in electronic tongue validation for excipient submissions.
Pharmaceutical Excipients for Taste Masking Market Competitive Environment
On the supply side, the industry is consolidating around integrated polymer producers capable of delivering bundled regulatory documentation packages. Three strategic archetypes dominate: diversified chemical conglomerates with captive excipient divisions, specialty excipient pure-plays focused on ion-exchange or cyclodextrin technologies, and CDMOs offering taste assessment as a value-added service. Competitive moves center on backward integration into raw material production and strategic partnerships with pediatric formulation specialists.
Within the integrated chemical tier, BASF SE and Evonik Industries AG exemplify archetypes of polymer chemistry backbone leverage and backward-integrated raw material control respectively. SPI Pharma occupies a distinct position representing specialty pure-plays competing through aqueous-compatible complexation technologies rather than thermal coating approaches.
| Leading Market Players |
|---|
| SPI Pharma |
| DuPont de Nemours |
| Dow Pharma Solutions |
| Roquette Frères |
| Asahi Kasei Corporation |
| BASF SE |
| Evonik Industries AG |
| Colorcon Inc. |
| Ashland Inc. |
| Others |
Value Chain & Pricing Dynamics
Amino methacrylate copolymer production concentrates among three European chemical conglomerates, channeling margin pools toward high-barrier coating tiers and squeezing mid-scale generic pharmaceutical buyers into commodity methacrylate alternatives.
Pricing Analysis
Certification level creates the primary spread between USP-NF monograph-compliant coating polymers and unvalidated regional alternatives. Pricing stratifies across premium, standard, and economy tiers, with FDA-grade amino methacrylate copolymers commanding substantial premiums over ethylcellulose-based substitutes. Cost compression in standard-tier methacrylate coatings is intensifying because Indian contract manufacturers are scaling aqueous-compatible production lines. Generic pharmaceutical procurement teams exhibit the highest price sensitivity, while pediatric formulation specialists developing new molecular entities demonstrate minimal elasticity.
Supply Chain Analysis
Tariff exposure between Germany and India dominates supply chain risk calculations as European REACH restrictions force coating system migrations. Raw material sourcing draws from Ludwigshafen chemical hubs for methacrylate monomers, Ahmedabad for generic-grade polymer finishing, and Osaka-Kobe for ion-exchange resin precursors. Single-source vulnerability persists for high-performance amino methacrylate copolymers where Evonik Industries AG maintains backward-integrated control. Distribution runs through pharmaceutical CDMOs in New Jersey and Pennsylvania corridors before final formulation at generic manufacturer sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA pediatric formulation guidance represents a regulatory inflection accelerating technology shifts toward aqueous-compatible masking systems, creating asymmetric growth windows for suppliers with validated in-vitro dissolution models.
For Market Incumbents: Insulate market position by deepening backward integration into amino methacrylate monomer production and securing exclusive supply agreements with New Jersey-area pediatric formulation CDMOs. Threats from ion-exchange resin complexation technologies require defensive patent filings around multi-layer coating architectures. Certification investment in USP-NF monograph expansion provides the most durable lever against emerging aqueous-compatible competitors.
For New Entrants and Emerging Players: Establish a beachhead in orally disintegrating tablet masking systems for psychiatric indications where established coating infrastructure offers limited compatibility. The most penetrable segment lies in heat-sensitive biologics requiring aqueous complexation rather than thermal processing. A go-to-market angle bundling electronic tongue validation services with excipient supply addresses the standardization bottleneck hampering competitor submissions.
For Investors and Strategic Acquirers: Capital is best deployed toward specialty excipient pure-plays with ion-exchange or cyclodextrin technology platforms rather than integrated chemical conglomerates where excipient divisions compete for internal capital allocation. Long-term viability over the coming decade hinges on aqueous-compatible masking capabilities as biologics pipelines mature. The signal to watch is CDSCO approval pathway streamlining for Indian domestic suppliers entering export markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Amino Methacrylate Monomers | Evonik's captive supply of raw materials secures quality control for high-barrier coatings. |
| Aqueous Coating System Migration | REACH solvent restrictions are forcing abandonment of ethyl acetate-based European production. |
| In-Vitro Dissolution Model Validation | EMA quality-by-design expectations reward bundled regulatory documentation from excipient producers. |
| Continuous Processing Line Adoption | Philadelphia-area CDMOs serve biotech clients developing heat-labile protein formulations. |
| Ion-Exchange Resin Capacity Expansion | SPI Pharma's complexation technologies compete directly with polymer coatings in liquid applications. |
Study Parameters
A spread of perspectives from pharmaceutical formulation scientists, regulatory affairs directors, CDMO procurement managers, and excipient R&D leads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA guidance documents, EMA quality-by-design submissions, USP-NF monograph revisions, and ICH Q3D elemental impurity guidelines. Customs data from India and Germany, SEC filings from integrated chemical producers, and pharmaceutical trade association reports provided additional triangulation anchors. Bottom-up excipient volume estimates and top-down pharmaceutical formulation demand projections were reconciled through iterative stakeholder feedback.
Demand-supply balance dynamics across the analysis window were modeled through segmented forecasting incorporating product chemistry, application format, delivery mode, and release kinetics dimensions. CAGRs were derived from growth rate convergence analysis across pediatric, geriatric, and psychiatric patient population demand trajectories. Forecast inputs included pipeline stage distributions for heat-sensitive biologics, fluid-bed coating equipment capacity expansion announcements, and regulatory submission timelines for novel natural disguisers.
Sensitivities concentrate around FDA pediatric guidance enforcement intensity, REACH solvent restriction implementation timelines, and CDSCO PLI scheme incentive continuity. Forecasts reflect assumptions about aqueous coating technology adoption curves and ion-exchange resin performance validation rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Oridonin Market
Pharmaceutical Ingredients
Synthetic Small Molecule API Market
Pharmaceutical Ingredients
Pharma Grade Synthetic Camphor Market
Pharmaceutical Ingredients
Epcam Antagonists Market
Pharmaceutical Ingredients
Celecoxib API Market
Pharmaceutical Ingredients
Scopolamine Market
Pharmaceutical Ingredients
Tranexamic Acid API Market
Pharmaceutical Ingredients
Pharmaceutical Chemicals Market
Pharmaceutical Ingredients
Cetrorelix Acetate API Market
Pharmaceutical Ingredients
Moxifloxacin Hcl (CAS 186826-86-8) Market
Pharmaceutical Ingredients
Transdermal Drugs Market
Pharmaceutical Ingredients
Global Antazoline Market
Pharmaceutical Ingredients
India Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Pharmaceutical Grade Hyaluronic Acid Market
Pharmaceutical Ingredients
Global Pharmaceutical Grade Silica Gel Market
Pharmaceutical Ingredients
United Kingdom Active Pharmaceutical Ingredients (API) Market