
 Topical Drugs Market | 2026-2036
Topical Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Topical Drugs Market Intelligence
Aftermarket service revenue from compounding pharmacy partnerships is narrowing as integrated health systems bring topical formulation capabilities in-house. Johnson & Johnson leverages its consumer-health division to sustain shelf presence across retail pharmacy channels. Galderma anchors its position through dermatologist-directed sampling programs that bypass traditional wholesale distribution. Bayer AG competes on manufacturing scale, operating multi-purpose facilities that switch between corticosteroid creams and antifungal ointments based on demand signals.
Topical drugs are pharmaceutical formulations applied directly to body surfaces—skin, mucous membranes, or wounds—typically containing active concentrations between 0.01% and 5% in semi-solid bases designed for percutaneous absorption or local action. These products serve primarily to deliver therapy without systemic exposure, minimizing adverse effects in dermatologic, analgesic, and anti-infective indications. Corticosteroids and antifungals command the deepest margin pools due to chronic-use prescribing patterns and limited therapeutic substitution. Dermatology applications generate the highest prescription volumes, while pain management through transdermal and topical analgesic gels represents the fastest-expanding segment as opioid-sparing protocols gain clinical traction. Creams dominate unit volume across retail and institutional channels, though gels are capturing share in cosmetic-sensitive patient populations where residue and occlusion concerns drive formulary preference.
FDA bioequivalence requirements for semi-solid dosage forms, EMA quality guidelines for transdermal delivery systems, and ISO 10993 biocompatibility testing standards collectively determine product development timelines and market access pathways for topical drug manufacturers. These frameworks elevate R&D expenditure for formulation stability and skin irritation profiling, effectively filtering out undercapitalized entrants. Stakeholders must monitor evolving FDA guidance on in vitro release testing methodologies, as these determinations will reshape which generic topical products achieve abbreviated new drug application approval and when therapeutic equivalence ratings shift.
Market Dynamics
FDA bioequivalence refinements for semi-solid dosage forms are compressing generic entry timelines while forcing incumbent reformulators to rebuild stability data packages from scratch.
Growth Catalysts
- Opioid-sparing protocols:Pain management protocols in United States hospital systems are expanding formulary slots for topical analgesic gels as first-line therapy.
- EMA quality guidelines:Transdermal delivery system standards are harmonizing across European markets, reducing duplicate testing for multi-country launches.
- Dermatology clinic consolidation:Integrated health systems in the United States are standardizing topical formularies, creating volume concentration for approved suppliers.
Market Restraints
- API supply concentration:Corticosteroid active pharmaceutical ingredients rely on a limited base of Indian and Chinese manufacturers, creating input vulnerability.
- ISO 10993 biocompatibility testing:Extended skin irritation profiling timelines add months to development cycles for novel formulations.
- Systemic biologics substitution:Injectable biologics for psoriasis and atopic dermatitis are capturing refractory cases that previously escalated to high-potency topicals.
Strategic Opportunities
- Compounding pharmacy channel:Specialty compounding partnerships offer customization pathways for pediatric and geriatric populations with absorption variability.
- India PLI scheme:Production-linked incentives for pharmaceutical manufacturing are attracting topical formulation investments to serve export markets.
- Cosmetic-sensitive gel formulations:Residue-free hydrogel bases are opening preference share among adult acne and rosacea patient segments.
Industry Challenges
- Formulation scientist scarcity:Percutaneous absorption modeling and semi-solid rheology expertise is concentrated among a small cohort of specialized practitioners.
- In vitro release testing standardization:Pending FDA guidance on methodology is freezing investment decisions for generic pipeline candidates.
- Multi-purpose facility validation:Switching between corticosteroid and antifungal production requires extensive cleaning validation and downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Topical Drugs Market |
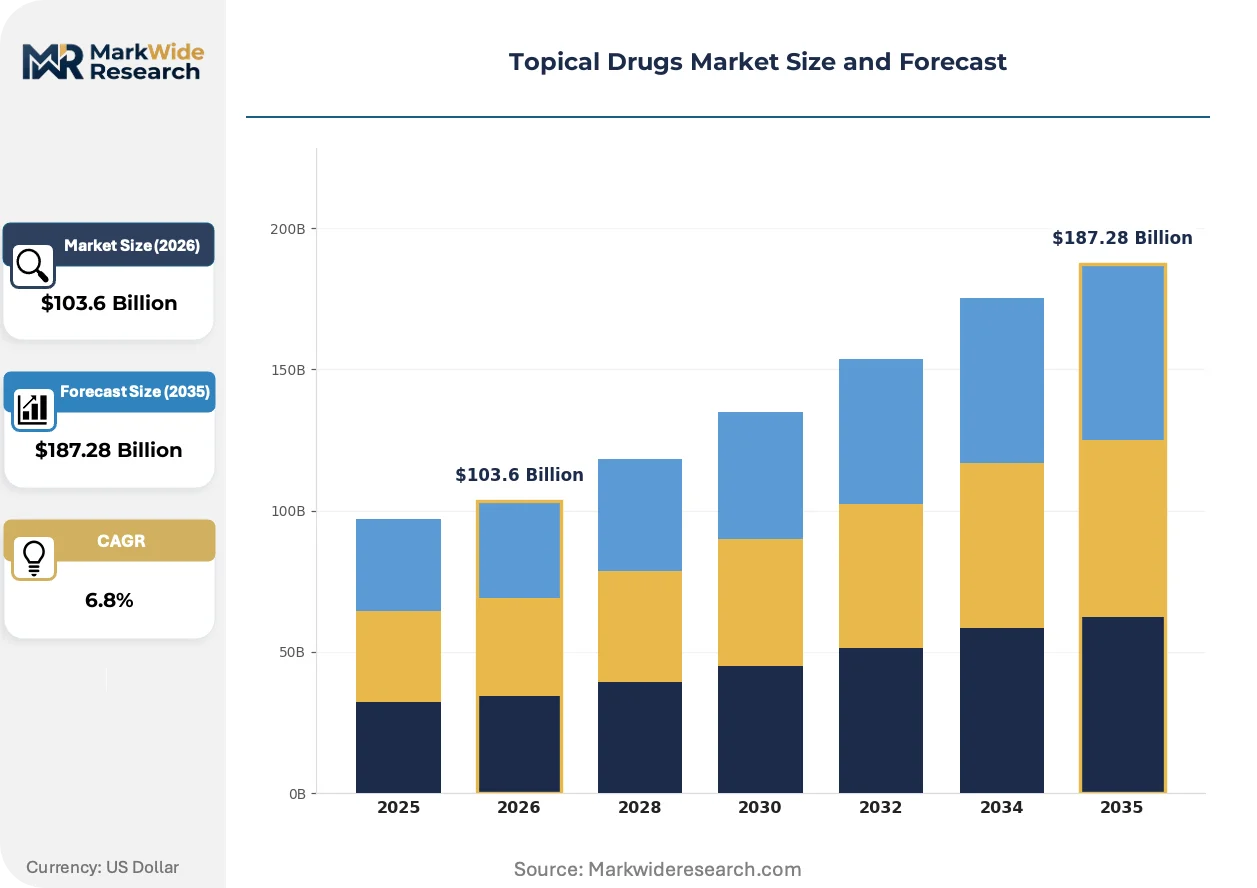
| Market Size in 2026 | $103.6 Billion |
| Market Size in 2035 | $187.28 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Corticosteroids, Antifungals, Analgesics Application: Dermatology, Pain Management, Wound Care, Infection Control Delivery Mode: Creams, Gels, Ointments, Solutions End User: Clinics, Hospitals, Home Care, Pharmacies |
| Companies Covered | Johnson & Johnson, Galderma, Bayer AG, GSK plc, AbbVie Inc., Bausch Health Companies Inc., Hisamitsu Pharmaceuticals Inc., Novartis AG, Glenmark Pharmaceuticals Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Topical Drugs Market Strategic Shifts & Innovations
Formulation science is pivoting toward patient-centric delivery systems that reconcile efficacy with cosmetic elegance, reshaping R&D priorities across the value chain.
Nanosuspension technology is migrating from oral solid dosage applications into topical corticosteroid formulations, enabling enhanced skin penetration for refractory plaques. Dermatology-focused biotech firms are licensing these platforms to compress development timelines for patent-expired molecules. The shift is migrating from traditional cream bases toward engineered particle systems that modify release kinetics.
REACH restrictions on certain penetration enhancers are forcing European formulators to reformulate established products with alternative excipient portfolios. The industrial consequence is a wave of line extensions positioning as "clean label" alternatives to legacy compositions. Transdermal patch manufacturers serving Northern European markets are most affected, accelerating substitution timelines for dimethyl sulfoxide alternatives.
Integrated health system procurement is consolidating topical drug purchasing through specialty pharmacy networks, disintermediating traditional wholesale distribution. Hospital-owned specialty pharmacies are capturing dispensing volume previously routed through retail channels. This concentration is most visible in United States Medicare Part B reimbursement environments where site-of-care economics favor institutional dispensing.
Topical Drugs Market Segmentation
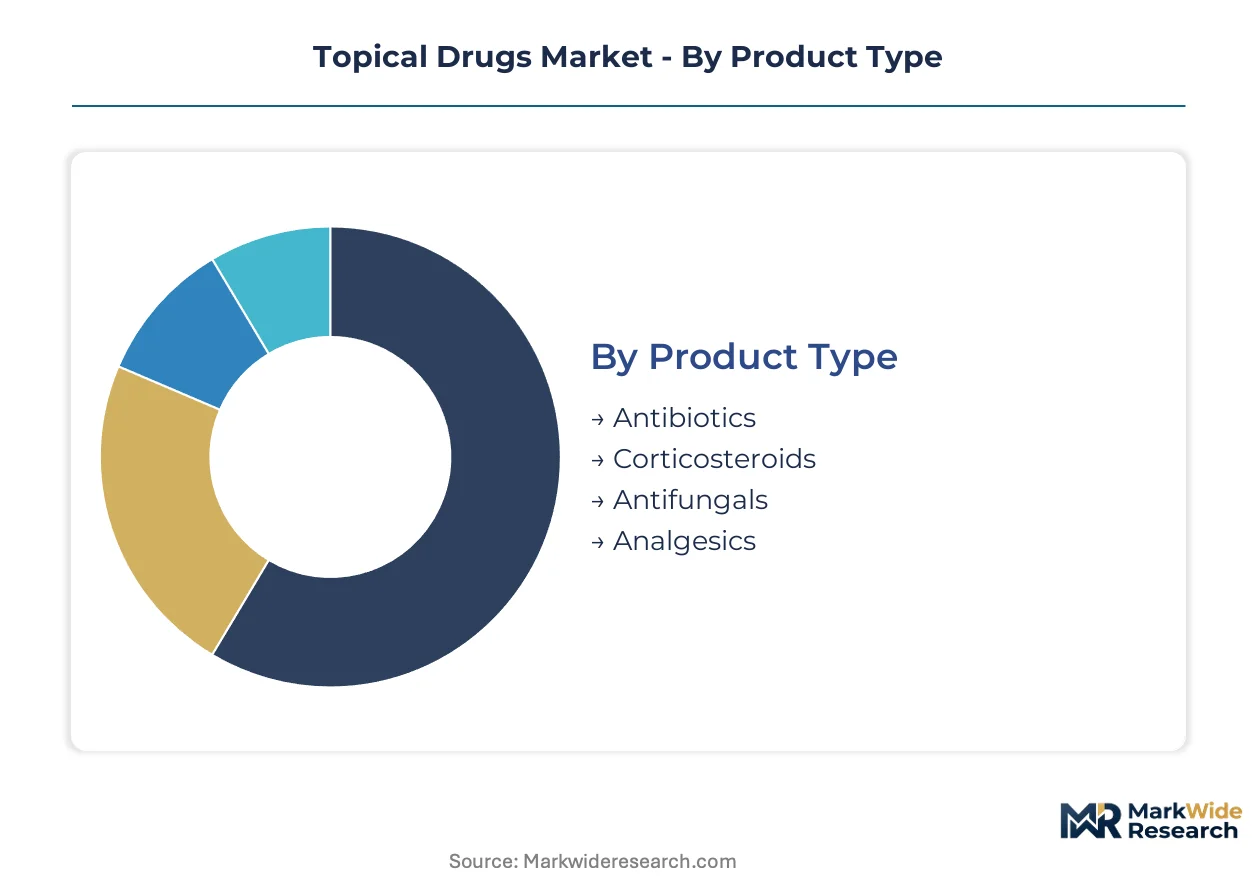
Topical drug segmentation reveals how formulation choices, clinical settings, and patient self-administration patterns fragment commercial opportunity. Manufacturers must align R&D investment with the specific absorption profiles and regulatory pathways governing each product category.
Product Type:
Cost tier stratification across active pharmaceutical ingredients determines margin architecture and competitive intensity within each therapeutic class.
- Corticosteroids:Hydrocortisone, betamethasone, and clobetasol formulations deliver anti-inflammatory action through percutaneous absorption with potency gradients from Class VII (low) to Class I (super-high). Dermatology clinics in the United States prescribe these for chronic eczema and psoriasis management, with generic substitution rates highest among mid-potency agents where FDA bioequivalence pathways are well-established.
- Analgesics:Topical NSAIDs, lidocaine patches, and capsaicin creams provide localized pain relief without systemic opioid exposure. Hospital formulary committees in the United States are expanding analgesic gel slots under opioid-sparing protocols, creating volume concentration for lidocaine and diclofenac formulations that bypass first-pass metabolism concerns.
- Antibiotics:Mupirocin, fusidic acid, and neomycin-polymyxin combinations target localized bacterial infections with minimal systemic absorption. Demand concentrates in wound care protocols and post-surgical prophylaxis within institutional settings.
- Antifungals:Clotrimazole, miconazole, and terbinafine formulations address dermatophyte and yeast infections across intertriginous zones. Chronic recurrence patterns in toenail and foot applications sustain repeat prescribing volumes.
Corticosteroids command the established base. The steepest expansion runs through Analgesics.
Application:
Clinical indication determines reimbursement coding, prescriber specialty, and the balance between institutional procurement and retail pharmacy dispensing.
- Dermatology:Psoriasis, atopic dermatitis, acne, and rosacea indications generate the deepest prescription volumes through dermatologist-directed care. United States specialty pharmacy networks capture biologic-adjacent topical dispensing as integrated health systems consolidate formulary control.
- Pain Management:Musculoskeletal, neuropathic, and post-operative pain applications are expanding fastest as transdermal and topical gel alternatives displace oral NSAIDs in geriatric populations with polypharmacy risks. EMA quality guidelines for transdermal delivery systems are harmonizing testing requirements across European markets.
- Wound Care:Chronic ulcer, burn, and surgical site management relies on antimicrobial and moisture-retentive topical formulations. Home care nursing protocols drive demand for easy-application formats.
- Infection Control:Topical antimicrobial prophylaxis in surgical and catheter-site applications serves institutional infection prevention mandates.
Dermatology anchors volume concentration. Pain Management is gaining share fastest.
Delivery Mode:
Formulation rheology and cosmetic elegance shape patient adherence, prescriber preference, and the technical complexity of manufacturing scale-up.
- Creams:Oil-in-water emulsions spread easily and wash off readily, making them the default for moist, weeping dermatoses. Creams dominate unit volume across United States retail and institutional channels due to manufacturing flexibility and patient familiarity.
- Gels:Hydrogel and organogel bases offer greaseless, residue-free application prized in cosmetic-sensitive adult acne and facial rosacea segments. Formulators are capturing preference share by engineering rapid-dry, non-occlusive vehicles that accommodate makeup and sunscreen layering.
- Ointments:Occlusive petrolatum-based vehicles maximize drug retention for dry, lichenified plaques but carry cosmetic and staining liabilities that limit daytime use.
- Solutions:Liquid vehicles suit scalp, hair-bearing, and intertriginous applications where spreadability and drying speed matter more than emollience.
Creams hold the volume base. Gels are climbing the fastest.
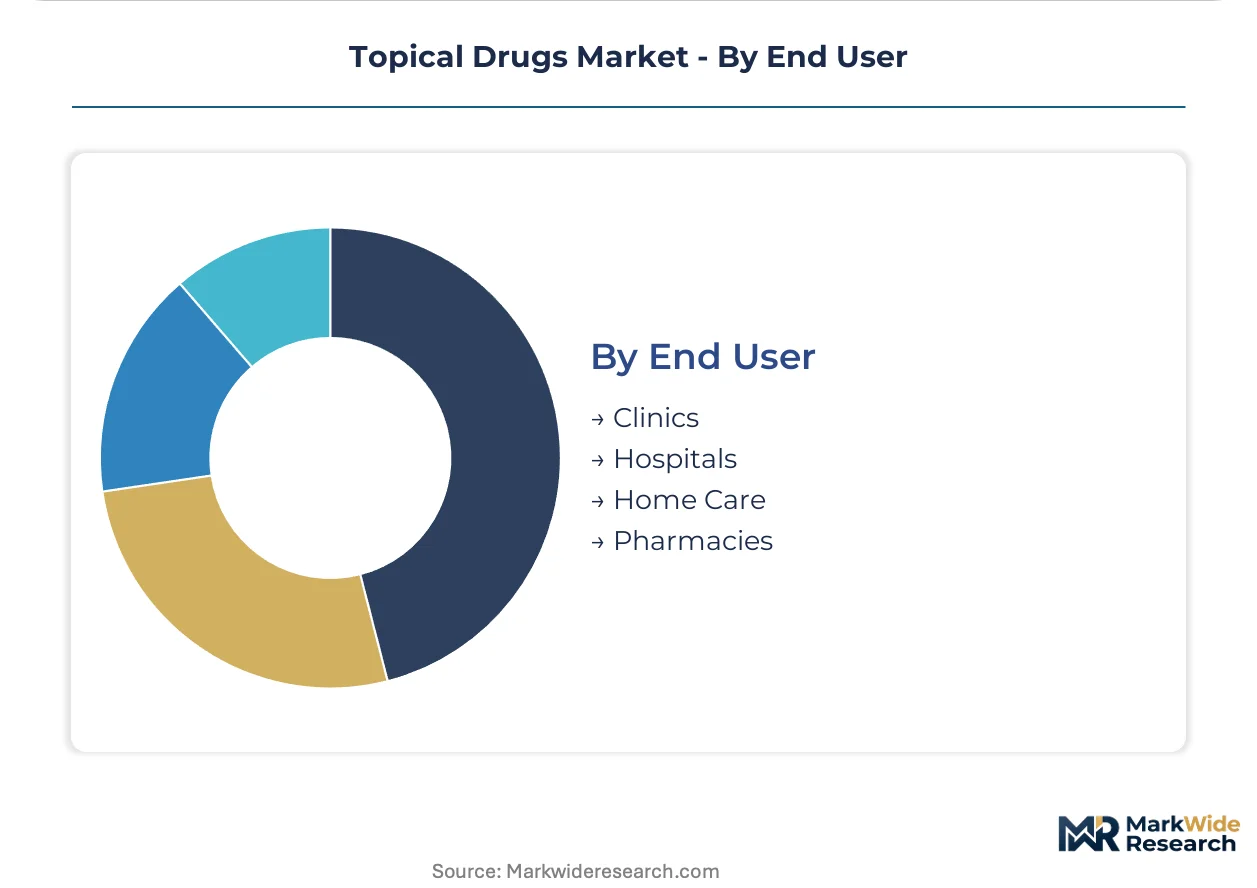
End User:
Site-of-care economics and reimbursement mechanics determine whether topical drugs flow through institutional specialty pharmacies or retail channels.
- Hospitals:Inpatient and emergency department formularies prioritize unit-dose packaging, rapid onset, and formulary standardization. United States Medicare Part B reimbursement environments favor hospital-owned specialty pharmacy dispensing.
- Clinics:Dermatology and pain management clinics drive prescriber-directed sampling and direct dispensing models that bypass wholesale distribution. Galderma and similar firms anchor position through physician office inventory programs.
- Pharmacies:Retail and specialty pharmacy networks handle the majority of prescription fulfillment, with consolidation toward 90-day dispensing and mail-order channels for chronic therapies.
- Home Care:Post-acute and long-term care settings demand caregiver-friendly packaging and application aids for patients with limited dexterity or cognitive impairment.
Pharmacies retain the dispensing base. Hospitals are capturing volume fastest through vertical integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland demonstrate the lowest price elasticity for branded dermatology formulations, while Indian and Chinese purchasers drive volume through cost-optimized generic substitution. This demand-elasticity contrast shapes where manufacturers deploy premium innovation versus scale production.
United States
Specialty pharmacy networks and integrated health systems concentrate dispensing volume for both branded and generic topical products. FDA bioequivalence refinements for semi-solid dosage forms are compressing generic entry timelines while forcing reformulators to rebuild stability data. The Northeast corridor anchors dermatology clinic consolidation, with hospital-owned specialty pharmacies capturing Medicare Part B reimbursement flows.
Germany
Dermatology-focused prescribing patterns sustain premium positioning for corticosteroid and antifungal formulations. EMA quality guidelines for transdermal delivery systems harmonize testing requirements across European markets, reducing duplicate validation burdens. The Rhine-Ruhr industrial cluster hosts multi-purpose pharmaceutical manufacturing facilities switching between semi-solid dosage forms based on demand signals.
India
Production-linked incentive schemes for pharmaceutical manufacturing attract topical formulation investments targeting export markets. CDSCO regulatory pathways for generic semi-solids are streamlining as domestic manufacturers build bioequivalence capabilities. Gujarat and Maharashtra industrial corridors concentrate corticosteroid API production, though input supply remains vulnerable to upstream concentration.
Japan
Aging demographics and polypharmacy risks expand formulary slots for topical analgesics as opioid-sparing alternatives. PMDA stability requirements for transdermal patches maintain rigorous validation standards that filter undercapitalized entrants. The Kansai region around Osaka anchors domestic manufacturing of hydrogel and cream formulations for cosmetic-sensitive patient segments.
United Kingdom
NHS procurement consolidation drives volume concentration toward approved suppliers of chronic-use dermatology therapies. MHRA alignment with EMA post-Brexit maintains regulatory coherence for multi-country launch strategies. The Southeast England pharmaceutical corridor sustains formulation science expertise in percutaneous absorption modeling and semi-solid rheology.
Topical Drugs Market Key Industry Players
Capability concentration sits with specialized dermatology-focused firms possessing formulation science depth; scale advantage sits with diversified pharmaceutical conglomerates operating multi-purpose manufacturing networks. The market structures around three tiers: global diversifieds with consumer health divisions, mid-cap dermatology specialists, and regional generic manufacturers. Strategic moves center on physician-directed sampling programs that bypass wholesale distribution, and backward integration into semi-solid manufacturing to capture margin from API through finished dose.
Within the diversified pharmaceutical tier, Johnson & Johnson leverages its consumer-health division to sustain retail pharmacy shelf presence across multiple continents. Galderma anchors the dermatology-specialist vector through physician office inventory programs that disintermediate traditional distribution. Bayer AG occupies the scale-manufacturing position, operating flexible facilities that alternate between therapeutic categories based on demand fluctuations.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Galderma |
| Bayer AG |
| GSK plc |
| AbbVie Inc. |
| Bausch Health Companies Inc. |
| Hisamitsu Pharmaceuticals Inc. |
| Novartis AG |
| Glenmark Pharmaceuticals Ltd. |
| Others |
Cost & Logistics Intelligence
Indian and Chinese corticosteroid API manufacturers anchor upstream supply, concentrating margin capture in finished-dose formulators with backward integration into semi-solid manufacturing. This concentration funnels pricing power toward integrated health systems and specialty pharmacy networks that consolidate procurement volume.
Pricing Analysis
Aftermarket service revenue from compounding pharmacy partnerships is narrowing as health systems bring formulation capabilities in-house. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA bioequivalence certification tier and prescriber-directed sampling intensity. Cost compression in mid-potency corticosteroid generics is intensifying because abbreviated new drug application pathways compress development timelines. Retail pharmacy chains exhibit highest price sensitivity; dermatology clinics anchored by physician sampling programs show lowest.
Supply Chain Analysis
Export-control scrutiny on nanosuspension manufacturing equipment limits technology transfer to emerging formulation hubs. Active pharmaceutical ingredient production concentrates in India, China, and Switzerland. Semi-solid manufacturing draws from petrolatum bases, penetration enhancers, and specialized rheology modifiers. Single-source vulnerability runs through Indian API suppliers subject to regulatory inspection cycles. Distribution runs through specialty pharmacy networks disintermediating traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA bioequivalence refinements for semi-solid dosage forms constitute a regulatory inflection compressing generic entry timelines and forcing incumbent reformulators to rebuild stability data packages from scratch.
For Market Incumbents: Insulate formulation science capabilities by acquiring specialized percutaneous absorption modeling expertise concentrated among limited practitioner cohorts. Backward integration into corticosteroid API production hedges against Indian and Chinese supply concentration. Channel control through physician office inventory programs defends against specialty pharmacy network consolidation. For New Entrants and Emerging Players: Build out residue-free hydrogel formulation capabilities targeting cosmetic-sensitive adult acne and rosacea segments where established cream bases carry cosmetic liabilities. Compounding pharmacy partnerships for pediatric and geriatric populations represent the most penetrable white-space target. Go-to-market execution should anchor on institutional formulary committees expanding opioid-sparing analgesic slots. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dermatology-specialist firms possessing physician-directed sampling infrastructure but lacking manufacturing scale. Long-term viability across the projection horizon hinges on FDA therapeutic equivalence rating stability and EMA quality guideline harmonization. Monitor in vitro release testing guidance publication as inflection indicator for generic pipeline investment decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA abbreviated new drug application submissions for semi-solid generics reshape competitive entry timelines. |
| Backward Integration | In-house corticosteroid API production captures margin from raw material through finished dose. |
| Manufacturing Scale-Up | Multi-purpose facility flexibility enables switching between therapeutic categories based on demand signals. |
| Strategic Partnership | Compounding pharmacy alliances address pediatric and geriatric absorption variability segments. |
| Pipeline Diversification | Nanosuspension technology licensing accelerates development timelines for patent-expired molecules. |
Research Approach
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration against market developments. Primary interview findings triangulated with FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up prescription volume modeling and top-down manufacturer revenue analysis converged on segment-level estimates.
Scenario-bracketing framed low, base, and high cases across the projection horizon. Segmentation dimensions encompassed product type, application, delivery mode, and end-user channel. CAGRs derived from regression analysis against historical prescription trends and regulatory approval velocity. Forecast inputs incorporated FDA bioequivalence guidance evolution and EMA transdermal quality guideline implementation pace.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Indian PLI scheme beneficiaries would shift outcomes. Material shifts in FDA in vitro release testing methodology or corticosteroid API supply disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Mrna Synthesis Raw Materials Market
Pharmaceutical Ingredients
MEK Inhibitors Market
Pharmaceutical Ingredients
Pharmaceutical Thermal Analysis Market
Pharmaceutical Ingredients
Calcium Citrate Market
Pharmaceutical Ingredients
Small Molecule Drug Discovery Market
Pharmaceutical Ingredients
Vitamins and Derivatives Market
Pharmaceutical Ingredients
Oral Doxycycline Hyclate Market
Pharmaceutical Ingredients
Pharmaceutical Indicator Strips Market
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market
Pharmaceutical Ingredients
Global Tacrolimus Market
Pharmaceutical Ingredients
Active Ingredients Market
Pharmaceutical Ingredients
Penciclovir API Market
Pharmaceutical Ingredients
Encapsulated Salicylic Acid Market
Pharmaceutical Ingredients
Pharmaceutical Propellants Market
Pharmaceutical Ingredients
Quinoline Market
Pharmaceutical Ingredients
Scopolamine Market