
 Synthetic Lethality-Based Drugs and Targets Market | 2026-2036
Synthetic Lethality-Based Drugs and Targets Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Lethality-Based Drugs and Targets Market Outlook
CRISPR-based functional genomics screening is fragmenting traditional target discovery workflows, enabling systematic identification of synthetic lethal gene pairs at unprecedented scale. AstraZeneca leverages its PARP franchise to anchor commercial infrastructure across DNA damage response pathways. BeiGene competes through geographic diversification, building regulatory dossiers across multiple health authorities simultaneously. IDEAYA Biosciences specializes in biomarker-driven patient stratification, concentrating development resources on genetically defined tumor subsets.
Synthetic lethality-based drugs and targets exploit pairwise genetic dependencies where mutation in one gene creates lethal vulnerability to inhibition of a partner gene, with PARP inhibitors in BRCA-mutant cancers representing the clinically validated prototype. Small molecules dominate current revenue as established oral inhibitors command premium pricing in maintenance settings, while cell-based therapies attract venture funding for addressing solid tumor indications beyond reach of conventional modalities. Monoclonal antibodies targeting DNA repair machinery occupy an emerging niche, with several programs advancing through proof-of-concept studies in hematologic malignancies.
FDA breakthrough therapy designation and EMA PRIME eligibility compress development timelines for synthetic lethality candidates, reshaping competitive dynamics around regulatory strategy execution. The FDA's Project Orbis facilitates concurrent oncology program reviews with Health Canada, TGA, and Swissmedic, expanding market access pathways for developers with multinational ambitions. Stakeholders must monitor biomarker assay standardization across jurisdictions, as companion diagnostic harmonization determines addressable patient populations and reimbursement outcomes.
Market Dynamics
CRISPR-based functional genomics screening is collapsing traditional target discovery timelines, compressing decade-long validation cycles into months while fragmenting competitive moats around established DNA damage response pathways.
Growth Catalysts
- FDA Breakthrough Therapy Designation:The FDA's accelerated review pathway compresses clinical development timelines for synthetic lethality candidates, attracting biopharma R&D investment toward DNA repair targets.
- Companion Diagnostic Harmonization:Standardized biomarker assays across health authorities expand addressable patient populations for genetically defined tumor subsets.
- Academic Medical Center Clustering:Specialized cancer institutes in the United States, the United Kingdom, and Switzerland concentrate trial infrastructure and investigator expertise.
Market Restraints
- Biomarker Assay Fragmentation:Lack of cross-jurisdictional standardization for BRCA and homologous recombination deficiency testing limits patient identification.
- High-Throughput Screening Costs:CRISPR library construction and single-cell sequencing infrastructure require substantial capital deployment.
- Resistance Mechanism Emergence:PARP inhibitor salvage pathways and reversion mutations erode durable response rates in maintenance settings.
Strategic Opportunities
- Project Orbis Expansion:The FDA's concurrent review mechanism with Health Canada, TGA, and Swissmedic enables simultaneous multinational regulatory submissions.
- Solid Tumor Cell Therapy:Engineered cellular modalities address indications beyond reach of small-molecule DNA damage response inhibitors.
- Japan PMDA Early Engagement:Sakigake designation pathways accelerate access for innovative oncology mechanisms in the Asia-Pacific region.
Industry Challenges
- Computational Biology Talent Scarcity:Shortage of specialists integrating CRISPR screening data with synthetic lethal network modeling constrains target prioritization.
- Legacy Clinical Trial Infrastructure:Traditional oncology endpoints require adaptation to capture synthetic lethality-specific response patterns and delayed treatment effects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Lethality-Based Drugs and Targets Market |
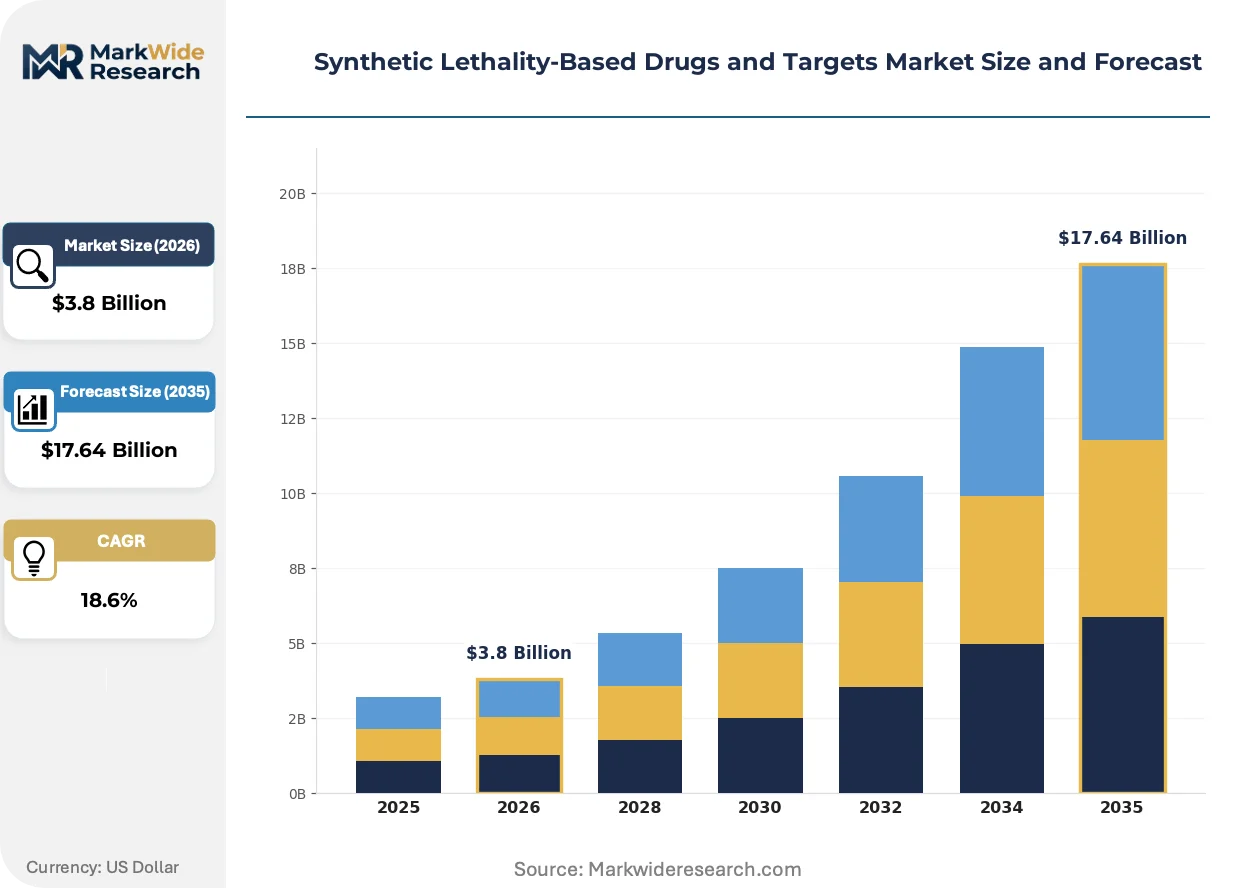
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecules, Monoclonal Antibodies, Combinations, Cell-Based Therapies Therapy Area: Oncology, Hematology, Neurology, Infectious Diseases Delivery Mode: Intravenous, Oral, Subcutaneous, Topical End User: Hospitals, Clinics, Research Institutes, Contract Research Organizations |
| Companies Covered | AstraZeneca, AbbVie, Pfizer, GlaxoSmithKline, BeiGene, Repare Therapeutics, Clovis Oncology, IDEAYA Biosciences, Mission Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Lethality-Based Drugs and Targets Market Strategic Shifts
Systematic functional genomics platforms are actively displacing hypothesis-driven target selection, while regulatory convergence mechanisms and biomarker-driven trial designs compress development economics across the synthetic lethality landscape.
CRISPR-Cas9 pooled screening libraries is collapsing the cost structure of synthetic lethal target identification. Biopharma R&D organizations now deploy genome-wide dropout screens at scale. Academic-industry consortia compress validation timelines from years to months.
EMA PRIME eligibility criteria now prioritize synthetic lethality mechanisms with companion diagnostic stratification. The European regulator's accelerated assessment reshapes portfolio prioritization. Developers with multinational dossier strategies capture priority review benefits across EU member states.
Oncology procurement departments now mandate biomarker confirmation before PARP inhibitor authorization. Hospital formularies restrict maintenance therapy to genetically defined subsets. This pattern concentrates most visibly in United States integrated delivery networks and United Kingdom NHS specialized commissioning frameworks.
Synthetic Lethality-Based Drugs and Targets Market Segmentation
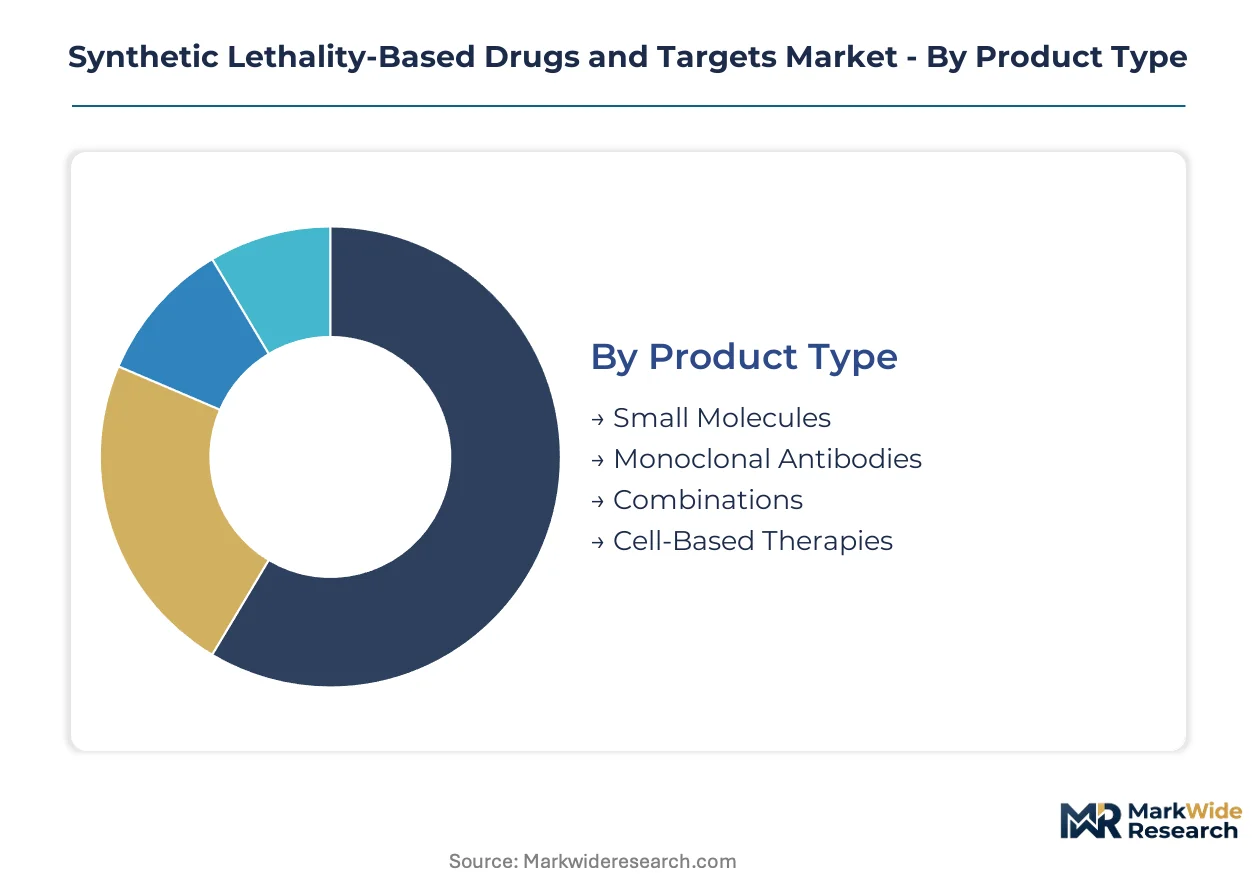
Synthetic lethality therapeutics fragment across four distinct dimensions that reshape competitive positioning. Product type stratification determines manufacturing complexity and pricing power. Therapy area concentration in oncology absorbs the majority of clinical development resources.
Product Type:
Cost tier differentiation separates established oral inhibitors from emerging biologic modalities with divergent capital requirements and reimbursement pathways.
- Small Molecules:Oral PARP inhibitors and DNA damage response modulators dominate current revenue through established manufacturing scale and maintenance therapy positioning. Demand concentrates in United States integrated delivery networks where biomarker-mandated formularies restrict access to genetically confirmed patient subsets, with FDA breakthrough therapy designations accelerating prior authorization pathways.
- Cell-Based Therapies:Engineered cellular modalities targeting solid tumor synthetic lethality mechanisms attract venture funding for indications beyond small-molecule reach. Manufacturing complexity limits initial deployment to specialized academic medical centers in Switzerland and the United Kingdom with dedicated cell therapy infrastructure.
- Monoclonal Antibodies:DNA repair machinery targeting programs advance through proof-of-concept studies in hematologic malignancies with distinct pharmacokinetic profiles from small-molecule competitors.
- Combinations:Rational pairing of synthetic lethality agents with immunotherapy or chemotherapy requires complex clinical trial designs and biomarker stratification.
Small molecules hold installed capacity. Cell-based therapies are rotating up the share rankings.
Therapy Area:
Application concentration determines regulatory strategy execution and companion diagnostic development priorities.
- Oncology:BRCA-mutant breast, ovarian, and prostate cancers anchor the clinically validated synthetic lethality paradigm with PARP inhibitors. EMA PRIME eligibility and FDA breakthrough designations compress development timelines for DNA damage response targets, while biomarker assay standardization across jurisdictions expands addressable populations.
- Hematology:Myeloid malignancies with synthetic lethal dependencies on splicing machinery or metabolic pathways represent emerging target spaces with distinct resistance profiles from solid tumor applications.
- Neurology:Synthetic lethality approaches targeting neurodegenerative disease mechanisms remain preclinical with unvalidated biomarker strategies.
- Infectious Diseases:Pathogen-specific synthetic lethal vulnerabilities in host-pathogen interactions attract limited biopharma investment relative to oncology priorities.
Oncology commands development bandwidth. Hematology is climbing the fastest as mechanistic understanding deepens.
Delivery Mode:
Volume distribution across administration routes reflects patient convenience requirements and therapeutic index considerations.
- Oral:Maintenance therapy positioning for PARP inhibitors drives preference for outpatient administration with established adherence monitoring protocols.
- Intravenous:Cell-based therapies and monoclonal antibodies require infusion center infrastructure concentrated at major cancer institutes.
- Subcutaneous:Emerging formulations seek to bridge convenience and bioavailability for DNA damage response modulators.
- Topical:Limited applicability for synthetic lethality mechanisms given systemic target engagement requirements.
Oral delivery holds installed capacity. Subcutaneous formulations are rotating up the share rankings.
End User:
Customer type fragmentation determines commercial infrastructure requirements and clinical trial site selection.
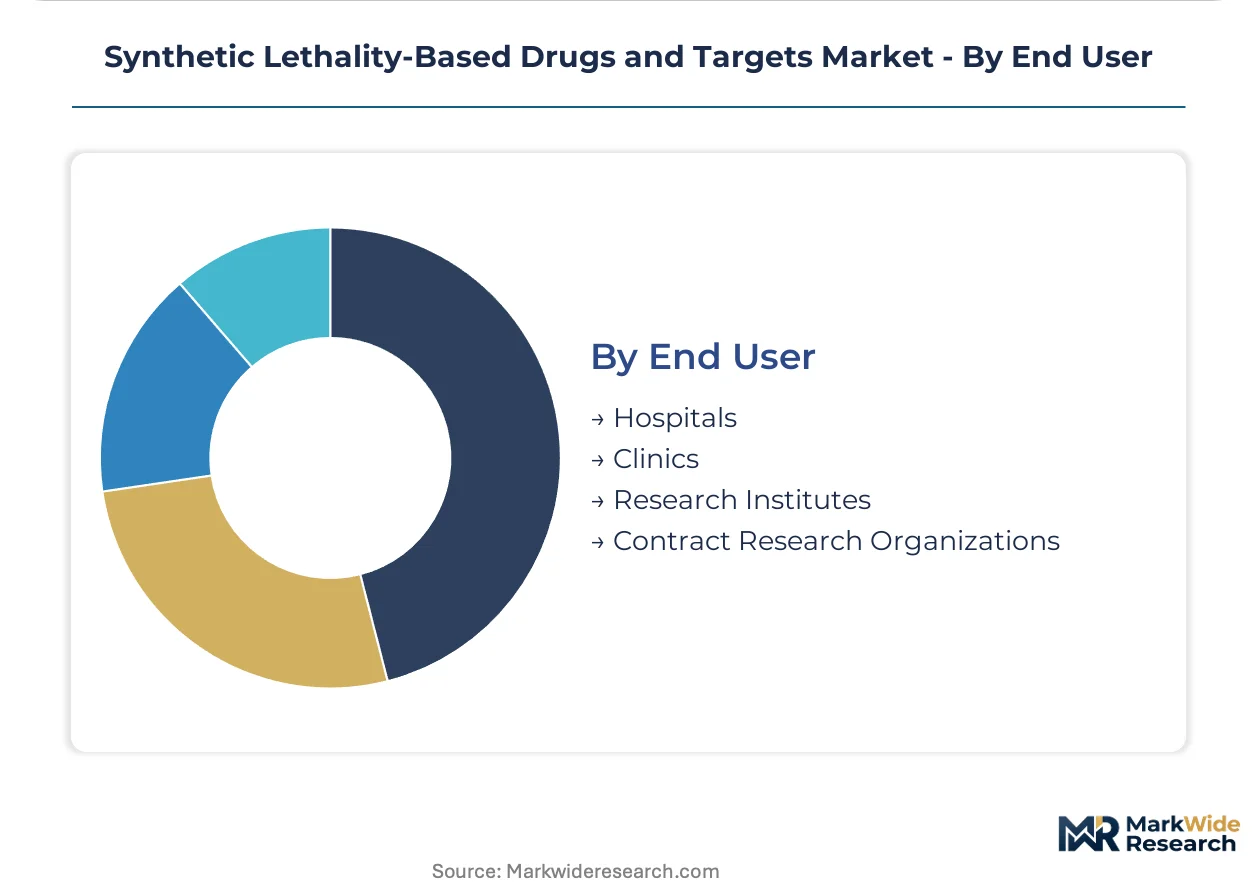
- Hospitals:Integrated delivery networks in the United States and NHS specialized commissioning frameworks in the United Kingdom mandate biomarker confirmation before PARP inhibitor authorization, concentrating procurement decisions at institutional level.
- Research Institutes:Academic medical centers in Switzerland, the United Kingdom, and the United States anchor early-phase synthetic lethality trials with CRISPR screening capabilities and specialized investigator expertise.
- Clinics:Community oncology practices depend on centralized reference laboratories for homologous recombination deficiency testing.
- Contract Research Organizations:Functional genomics screening services and biomarker assay development support target discovery and companion diagnostic harmonization across jurisdictions.
Hospitals hold installed capacity. Research institutes are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated delivery networks in the United States, the United Kingdom, and Switzerland concentrate procurement decisions for synthetic lethality therapeutics. Academic medical centers in these countries anchor clinical trial infrastructure. Regulatory convergence through FDA Project Orbis and EMA PRIME mechanisms accelerates multinational market access.
United States
FDA breakthrough therapy designations compress development timelines for DNA damage response modulators. The Medicare Coverage of Innovative Technologies pathway supports reimbursement for companion diagnostic-directed PARP inhibitor therapy. Memorial Sloan Kettering Cancer Center and MD Anderson anchor early-phase synthetic lethality trials with integrated CRISPR screening capabilities.
United Kingdom
NHS specialized commissioning frameworks mandate biomarker confirmation before PARP inhibitor authorization in ovarian and breast cancer maintenance settings. The MHRA's Innovative Licensing and Access Pathway accelerates market entry for synthetic lethality candidates with genetically defined patient populations. The Cambridge-London corridor concentrates functional genomics expertise and early-phase clinical trial infrastructure.
Switzerland
Swissmedic's participation in FDA Project Orbis enables concurrent regulatory review with North American and Asia-Pacific authorities. The country's national pharmaceutical regulator maintains accelerated assessment pathways for oncology innovations with companion diagnostic stratification. Basel and Zurich host specialized cancer institutes with dedicated cell therapy manufacturing infrastructure for solid tumor synthetic lethality programs.
Japan
PMDA Sakigake designation pathways accelerate priority review for innovative oncology mechanisms including next-generation DNA repair targets. The Pharmaceuticals and Medical Devices Agency's early engagement consultations support biomarker assay harmonization with FDA and EMA standards. Tokyo and Osaka academic medical centers concentrate investigator expertise in synthetic lethality clinical development.
China
NMPA breakthrough therapy designation and conditional approval pathways compress timelines for synthetic lethality candidates addressing unmet oncology needs. The National Medical Products Administration's streamlined review for innovative drugs with companion diagnostics expands addressable patient populations. Beijing and Shanghai biotech clusters attract venture funding for CRISPR-based target discovery platforms.
Synthetic Lethality-Based Drugs and Targets Market Competitive Environment
Channel-controlling players compete with product-specialist players across the synthetic lethality landscape. Large-cap pharmaceutical companies leverage established PARP inhibitor franchises to anchor commercial infrastructure across DNA damage response pathways. Mid-cap biotech specialists concentrate resources on biomarker-driven patient stratification and genetically defined tumor subsets. Competitive moves center on regulatory dossier diversification across multiple health authorities and functional genomics platform licensing.
Within the large-cap anchored tier, AstraZeneca and Pfizer occupy positions leveraging established oncology commercial infrastructure. Among biotech specialists, IDEAYA Biosciences exemplifies the biomarker-driven development archetype. BeiGene represents geographic diversification strategy execution with simultaneous regulatory submissions across FDA, EMA, and NMPA pathways.
| Leading Market Players |
|---|
| AstraZeneca |
| AbbVie |
| Pfizer |
| GlaxoSmithKline |
| BeiGene |
| Repare Therapeutics |
| Clovis Oncology |
| IDEAYA Biosciences |
| Mission Therapeutics |
| Others |
Value Chain & Pricing Dynamics
The Basel-Zurich pharmaceutical logistics corridor carries CRISPR library reagents and single-cell sequencing consumables at premium freight rates, concentrating supply costs in Swiss and United Kingdom cell therapy manufacturing nodes while forcing three-tier pricing stratification across small-molecule, biologic, and combination therapy tiers.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate synthetic lethality API procurement, tying PARP inhibitor active pharmaceutical ingredient costs to specialty chemical commodity benchmarks. Price differentiation rests on FDA breakthrough therapy designation status and companion diagnostic bundling, with biomarker-mandated formularies in United States integrated delivery networks commanding premium positioning. Pricing pressure stems from biosimilar preparedness programs eroding maintenance therapy margins. Community oncology practices exhibit highest price sensitivity due to centralized reference laboratory cost pass-through, while academic medical centers absorb premium positioning for early-phase cell therapy access.
Supply Chain Analysis
Tariff exposure between United States and Chinese territories dominates synthetic lethality supply chain risk planning, particularly for CRISPR-Cas9 pooled screening library components and DNA damage response modulator precursors. Manufacturing concentration centers on Switzerland, the United Kingdom, and the United States for cell-based therapy fill-finish, while small-molecule API production draws from Indian and Chinese chemical synthesis hubs. Raw material dependencies include oligonucleotide synthesis reagents, viral vector production media, and specialized chromatography resins. Single-source vulnerability characterizes GMP-grade plasmid DNA supply. Distribution runs through specialized cold-chain logistics providers serving hospital-based infusion centers and academic research institutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic lethality therapeutics occupy an early-cycle expansion trajectory, with CRISPR-based target discovery platforms compressing validation timelines and expanding addressable genetically defined tumor populations faster than prior oncology paradigms permitted.
For Market Incumbents: Pre-empt CRISPR screening platform commoditization by locking exclusive academic center partnerships and anchoring commercial infrastructure across DNA damage response pathway adjacencies. Defensive consolidation should prioritize backward integration into companion diagnostic assay development to control patient identification workflows. Capacity addition in Swiss and United Kingdom cell therapy manufacturing nodes secures fill-finish capacity before specialist infrastructure saturates.
For New Entrants and Emerging Players: Hematologic malignancies with splicing machinery synthetic lethal dependencies represent the most penetrable entry point, offering distinct resistance profiles from PARP inhibitor-saturated solid tumor markets. Japan PMDA Sakigake designation pathways provide regulatory acceleration with lower competitive density than FDA breakthrough therapy routes. Go-to-market execution should emphasize biomarker-driven investigator-initiated trials at Tokyo and Osaka academic medical centers.
For Investors and Strategic Acquirers: Carve-out targets emerge from large-cap pharmaceutical DNA damage response pipeline rationalizations, particularly Phase I assets lacking companion diagnostic stratification. Long-term viability favors specialists with integrated CRISPR screening-to-clinic platforms over single-asset developers. The signal to watch is EMA PRIME eligibility conversion rates, which indicate regulatory strategy execution quality and multinational dossier preparation discipline.
| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Harmonization | Standardized BRCA and HRD assays across FDA, EMA, and PMDA jurisdictions expand addressable patient populations for PARP inhibitors. |
| CRISPR Platform Licensing | Academic-industry consortia accelerate synthetic lethal target validation from years to months through pooled screening infrastructure. |
| Project Orbis Expansion | Concurrent FDA-Swissmedic-TGA reviews compress regulatory timelines for DNA damage response modulators seeking multinational market entry. |
| Cell Therapy Manufacturing Scale-Up | Dedicated Swiss and United Kingdom infrastructure addresses solid tumor synthetic lethality indications beyond small-molecule reach. |
| Biomarker-Driven Trial Design | Genetically defined patient stratification concentrates development resources on responsive subsets, improving probability of technical success. |
Study Parameters
Operator-level perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers anchored the qualitative base for this analysis. Primary interview intelligence combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Bottom-up patient population modeling and top-down therapeutic class spend analysis provided triangulation across data sources.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product type, therapy area, delivery mode, and end user. Treatment line positioning and regional regulatory cluster membership provided additional stratification layers. CAGRs derived from indication-specific adoption curves, biomarker prevalence epidemiology, and pricing elasticity assumptions for maintenance versus active therapy settings. Forecast inputs incorporated companion diagnostic penetration rates and resistance mechanism emergence timelines.
Macroeconomic conditions sit as an overlay; deviation in biopharma R&D allocation patterns or reimbursement policy stringency would shift the trajectory. Forecasts reflect assumptions regarding regulatory pathway success rates and biomarker assay standardization progress. Material shifts in CRISPR intellectual property landscape or DNA damage response resistance mechanism prevalence would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Montelukast API Market
Pharmaceutical Ingredients
Flurbiprofen Market
Pharmaceutical Ingredients
Vitamins and Derivatives Market
Pharmaceutical Ingredients
Metformin Hydrochloride API Market
Pharmaceutical Ingredients
Chlorzoxazone Market
Pharmaceutical Ingredients
Taxifolin Market
Pharmaceutical Ingredients
Fosfomycin Trometamol Powder Market
Pharmaceutical Ingredients
Oral Transmucosal Drugs Market
Pharmaceutical Ingredients
Rizatriptan Market
Pharmaceutical Ingredients
Global Ibuprofen Market
Pharmaceutical Ingredients
Calcium Gluconate Market
Pharmaceutical Ingredients
Originator Small Molecule Drug Market
Pharmaceutical Ingredients
Fixed-Dose Combination Drugs Market
Pharmaceutical Ingredients
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market
Pharmaceutical Ingredients
Saudi Arabia Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Pharmaceutical Indicator Strips Market