
 Acetaminophen API Market | 2026-2036
Acetaminophen API Market Size, Share, and Industry Trends Forecast 2026-2036
Acetaminophen API Market Analysis
ICH Q3D guidelines on elemental impurities is rebalancing the cost-of-entry calculus for acetaminophen API suppliers, forcing upgrades in purification infrastructure and analytical capabilities. Farmson Pharmaceuticals leverages its backward integration into para-aminophenol intermediates to control raw material costs across volatile feedstock cycles. Granules India Limited anchors a significant share of contract manufacturing volumes through dedicated acetaminophen facilities serving European and North American clients. Teva Pharmaceutical Industries Ltd competes on regulatory dossier depth, sustaining multiple FDA-approved supply pathways for its integrated generics portfolio.
Acetaminophen API, or paracetamol active pharmaceutical ingredient, refers to the bulk chemical substance N-acetyl-p-aminophenol synthesized primarily through the acetylation of p-aminophenol, with specifications typically requiring purity levels exceeding 99.0% and strict limits on para-chloroaniline and other genotoxic impurities. The compound serves as the foundational analgesic and antipyretic agent in pharmaceutical formulations ranging from single-entity tablets to combination therapies with opioids and NSAIDs. Tablet formulations dominate volume consumption across the therapy area dimension, while pain management commands the largest share of end-user demand from pharmaceutical companies and contract manufacturers. Liquid forms represent the fastest-expanding product category, driven by pediatric and geriatric patient populations requiring dose-flexible delivery modes.
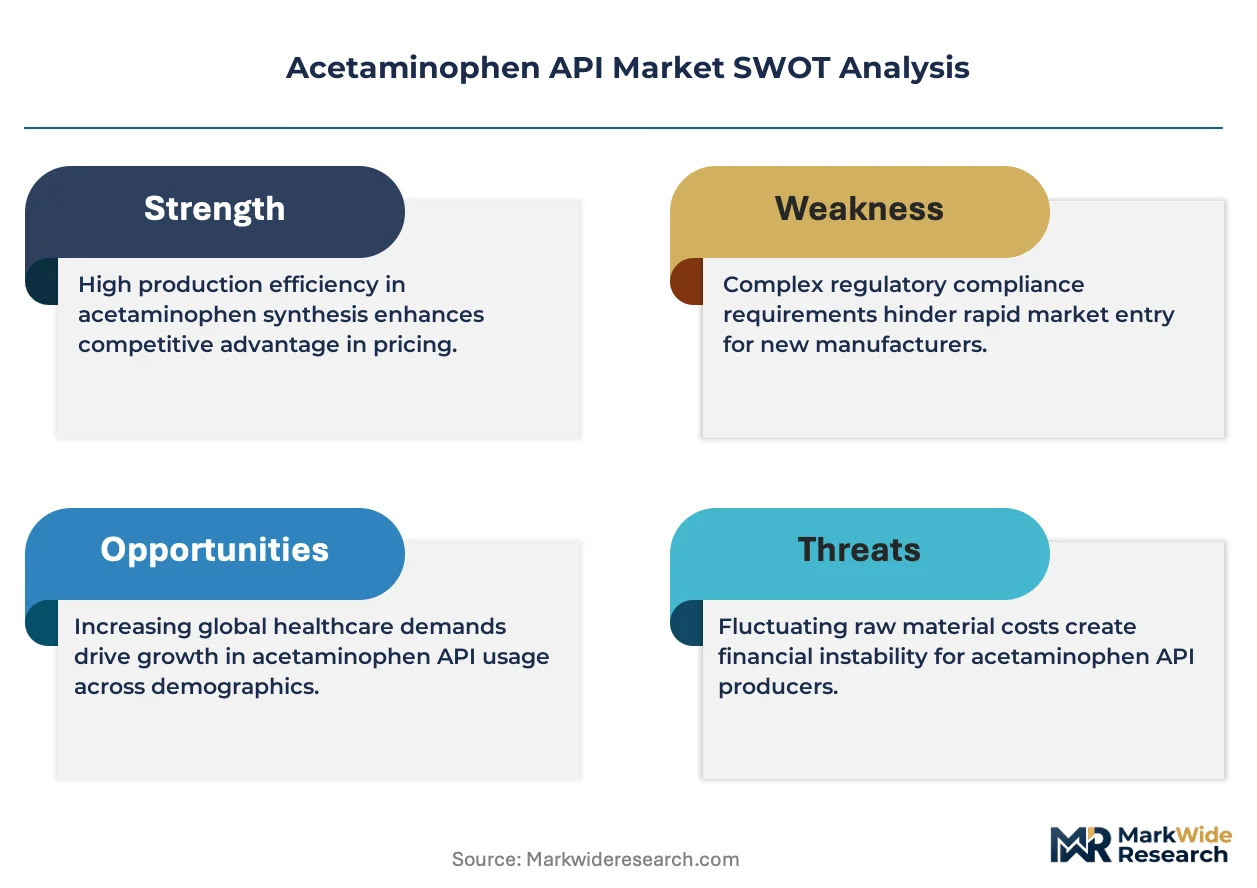
FDA enforcement of enhanced cGMP inspections, EMA oversight through the EU API registration framework, and India's CDSCO alignment with ICH quality standards collectively elevate compliance burdens while filtering subscale suppliers from approved vendor lists. These regulatory architectures favor manufacturers with dedicated quality systems, multi-site redundancy, and proven regulatory inspection histories. Stakeholders must monitor evolving impurity threshold revisions and regional inspection intensity as primary determinants of supplier viability and contract renewal probability.
Market Dynamics
ICH Q3D compliance costs are compressing the supplier base for acetaminophen API, as elemental impurity testing requirements force capital upgrades that only scaled manufacturers can absorb. This regulatory pressure is restructuring competitive positions around analytical capabilities and multi-site redundancy.
Growth Catalysts
- Pain management formulation demand:Pharmaceutical companies are expanding acetaminophen procurement for combination therapies with opioids and NSAIDs, sustaining volume pull through contract manufacturing channels.
- EMA EU API registration framework:The centralized oversight system is streamlining vendor qualification for European formulation houses, reducing regulatory friction for compliant suppliers.
- Liquid dosage form expansion:Pediatric and geriatric populations are driving demand for dose-flexible delivery modes, creating new volume channels beyond solid oral formulations.
Market Restraints
- Para-aminophenol feedstock volatility:Crude oil-linked pricing for acetanilide and nitrobenzene precursors compresses margin stability for non-integrated manufacturers.
- Hyderabad-Ahmedabad supply concentration:Geographic clustering of API manufacturing in India's western corridor creates single-point vulnerability for North American and European buyers.
- Genotoxic impurity thresholds:FDA enforcement of tightened para-chloroaniline limits under ICH M7 guidelines forces batch rejection rates that strain subscale producers.
Strategic Opportunities
- CDSCO-aligned Indian export expansion:India's alignment with ICH quality standards is opening accelerated approval pathways for domestic manufacturers into regulated markets.
- Continuous flow manufacturing adoption:Microreactor and flow chemistry technologies are enabling smaller-footprint production with enhanced impurity control and reduced solvent waste.
- Pediatric liquid formulation contracts:Geriatric care facilities and children's hospitals are consolidating procurement around dedicated liquid API supply agreements with traceable cold-chain documentation.
Industry Challenges
- Analytical chemist talent scarcity:ICP-MS and HPLC method development expertise for elemental impurity profiling commands premium compensation, constraining quality team expansion.
- Multi-site cGMP certification timelines:FDA pre-approval inspection queues and EU GMP certificate renewal cycles delay new capacity activation by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetaminophen API Market |
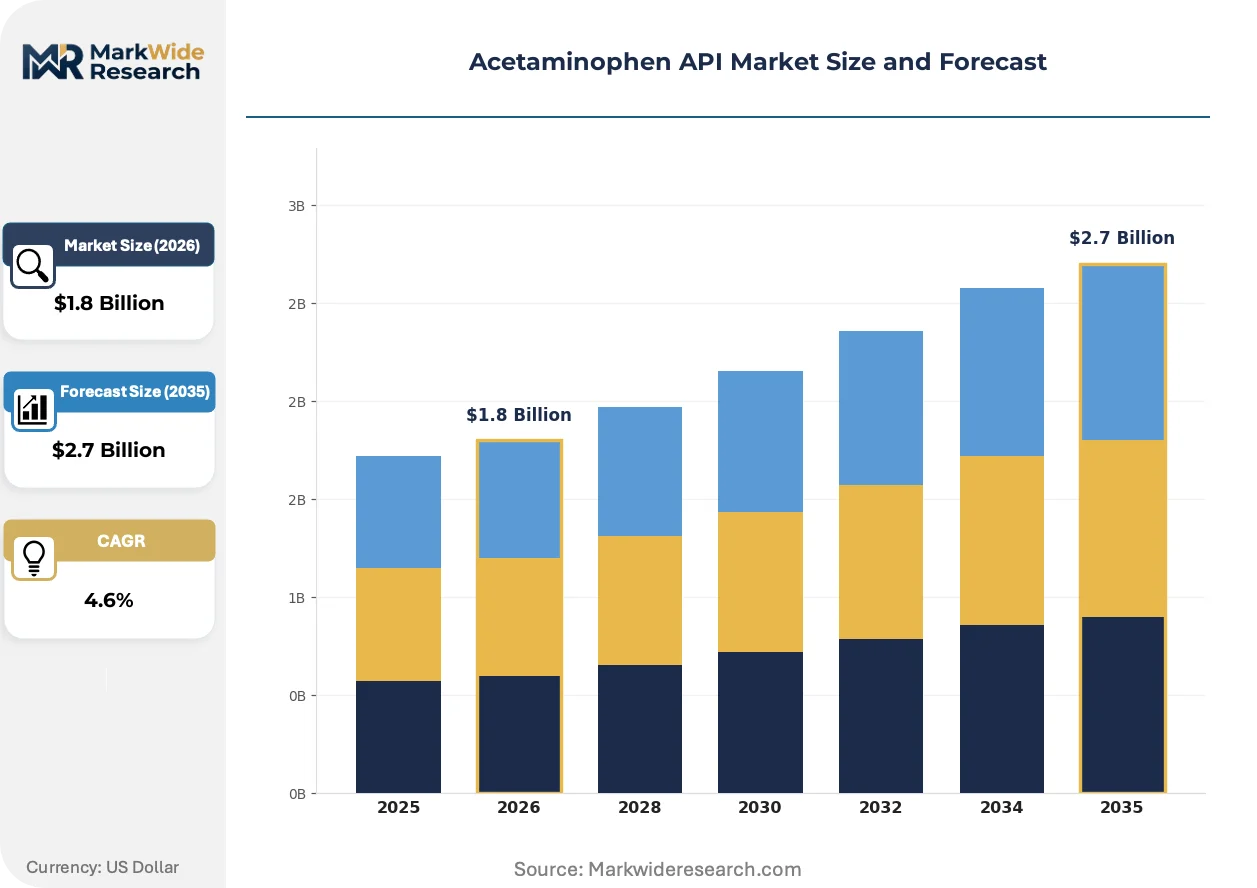
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Liquid Forms, Granules Therapy Area: Pain Management, Fever Relief, Inflammation, Cold & Flu End User: Pharmaceutical Companies, Contract Manufacturers, Research Institutions, Retail Pharmacies Delivery Mode: Oral, Injectable, Transdermal, Topical |
| Companies Covered | Farmson Pharmaceuticals, Hebei Jiheng Acetaminophen, Granules India Limited, Teva Pharmaceutical Industries Ltd, Sri Krishna Pharmaceuticals, Mallinckrodt Pharmaceuticals, IOL Chemicals and Pharmaceuticals, Rochem International Inc, Anhui BBCA Pharmaceutical Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetaminophen API Market Emerging Trajectories
Process intensification and regulatory harmonization are converging to reshape how acetaminophen API is manufactured, tested, and qualified across supply chains. These shifts favor capital-rich incumbents while raising barriers for new entrants.
Continuous flow chemistry is unifying reaction and purification steps into integrated microreactor systems that reduce solvent consumption and thermal degradation risks. Mid-scale Indian and Chinese manufacturers are piloting these installations to meet ICH Q3D impurity consistency requirements. The technology is compressing batch-to-batch variability and enabling real-time release testing that shortens quality hold times.
EMA's enhanced GMP inspection intensity for third-country manufacturers is tightening documentary expectations for starting material traceability and supplier qualification. European formulation houses are responding by consolidating approved vendor lists around manufacturers with dedicated EU QP release capabilities. This regulatory pressure is filtering out traders and re-packagers from direct supply relationships.
Buyers are consolidating procurement around manufacturers offering integrated regulatory dossier packages covering FDA, EMA, and Health Canada submissions. Pharmaceutical companies are displacing fragmented multi-supplier strategies with single-source or dual-source frameworks anchored by long-term offtake agreements. This concentration is most visible among North American generic houses seeking supply security through dedicated manufacturing arrangements.
Acetaminophen API Market Segmentation
Acetaminophen API procurement patterns diverge sharply across formulation types and end-user channels, with regulatory dossier requirements determining supplier eligibility for each segment. Pharmaceutical buyers segment their vendor lists by certification scope, creating tiered supply relationships that favor manufacturers with multi-market approval coverage.
Product Type:
FDA and EMA dossier specifications vary substantially across solid and liquid dosage forms, with liquid formulations demanding additional stability data and container closure integrity studies that elevate supplier qualification barriers.
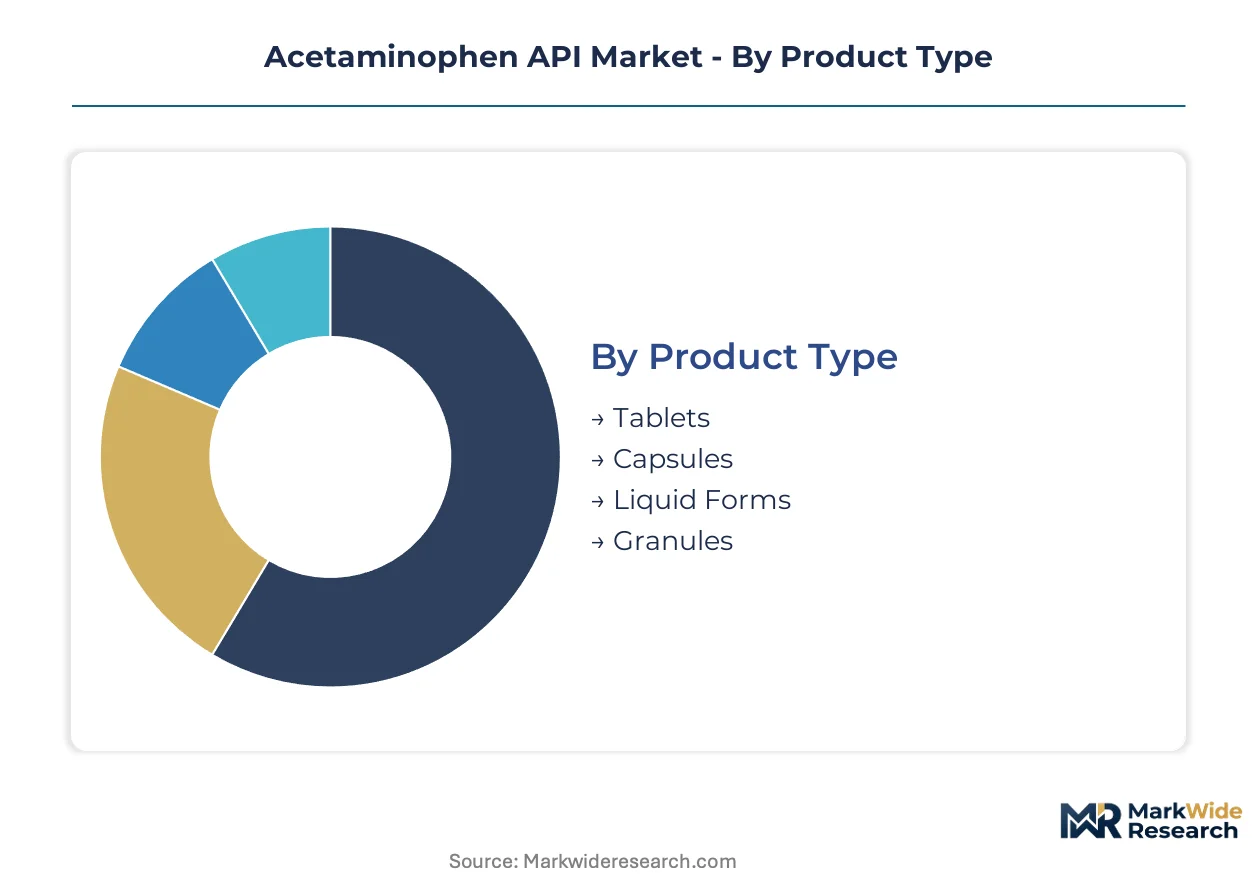
- Tablets:Compressed solid dosage forms dominate commercial volumes due to established manufacturing infrastructure and lower per-unit packaging costs. North American generic houses concentrate procurement here for combination therapies with opioids, though FDA dissolution profile requirements limit supplier flexibility.
- Liquid Forms:Oral solutions and suspensions require specialized impurity control for pediatric and geriatric populations where dose titration is critical. European contract manufacturers are expanding dedicated liquid API supply agreements with cold-chain documentation requirements.
- Capsules:Gelatin and HPMC encapsulation formats serve niche markets requiring taste masking or modified release profiles.
- Granules:Sachet and effervescent formulations target over-the-counter markets in Asia with convenience-driven dosing formats.
Tablets sit at the top of the volume ranking, with liquid forms climbing the fastest.
Therapy Area:
Margin structures across therapy segments reflect formulation complexity and regulatory scrutiny intensity, with pain management commanding premium pricing for opioid combination dossiers.
- Pain Management:Analgesic formulations including opioid combinations and NSAID co-formulations represent the largest revenue pool. North American demand concentrates here amid chronic pain prevalence and post-surgical protocol requirements.
- Fever Relief:Antipyretic monotherapy and combination cold medicines sustain high-volume, lower-margin procurement patterns. Indian API manufacturers supply bulk volumes to European over-the-counter formulation houses under EMA simplified registration pathways.
- Inflammation:Adjunctive acetaminophen use in inflammatory conditions creates specialized demand from rheumatology-focused pharmaceutical companies.
- Cold & Flu:Multi-symptom combination products drive seasonal demand spikes requiring flexible manufacturing arrangements.
Pain management commands the highest margin tier, while cold and flu exhibits the most pronounced demand seasonality.
End User:
Procurement scale and regulatory sophistication create distinct customer tiers, with pharmaceutical companies and contract manufacturers representing divergent vendor relationship models.
- Pharmaceutical Companies:Integrated generic houses and innovator firms with internal formulation capabilities purchase API against long-term offtake agreements with locked pricing. These buyers demand complete regulatory dossier packages covering FDA, EMA, and Health Canada submissions.
- Contract Manufacturers:CDMOs serving multiple pharmaceutical clients require flexible supply arrangements with rapid batch release capabilities. European contract manufacturers are consolidating approved vendor lists around manufacturers with dedicated EU QP release infrastructure.
- Research Institutions:Academic and clinical trial material suppliers purchase small-batch API with customized impurity profiling for investigational formulations.
- Retail Pharmacies:Compounding pharmacy chains and hospital procurement consortia source API for extemporaneous preparation under national pharmacy regulations.
Pharmaceutical companies anchor the procurement volume base, with contract manufacturers expanding their share through outsourcing trends.
Delivery Mode:
Manufacturing complexity and sterility requirements segment the supplier base, with oral delivery dominating and parenteral formats imposing specialized facility investments.
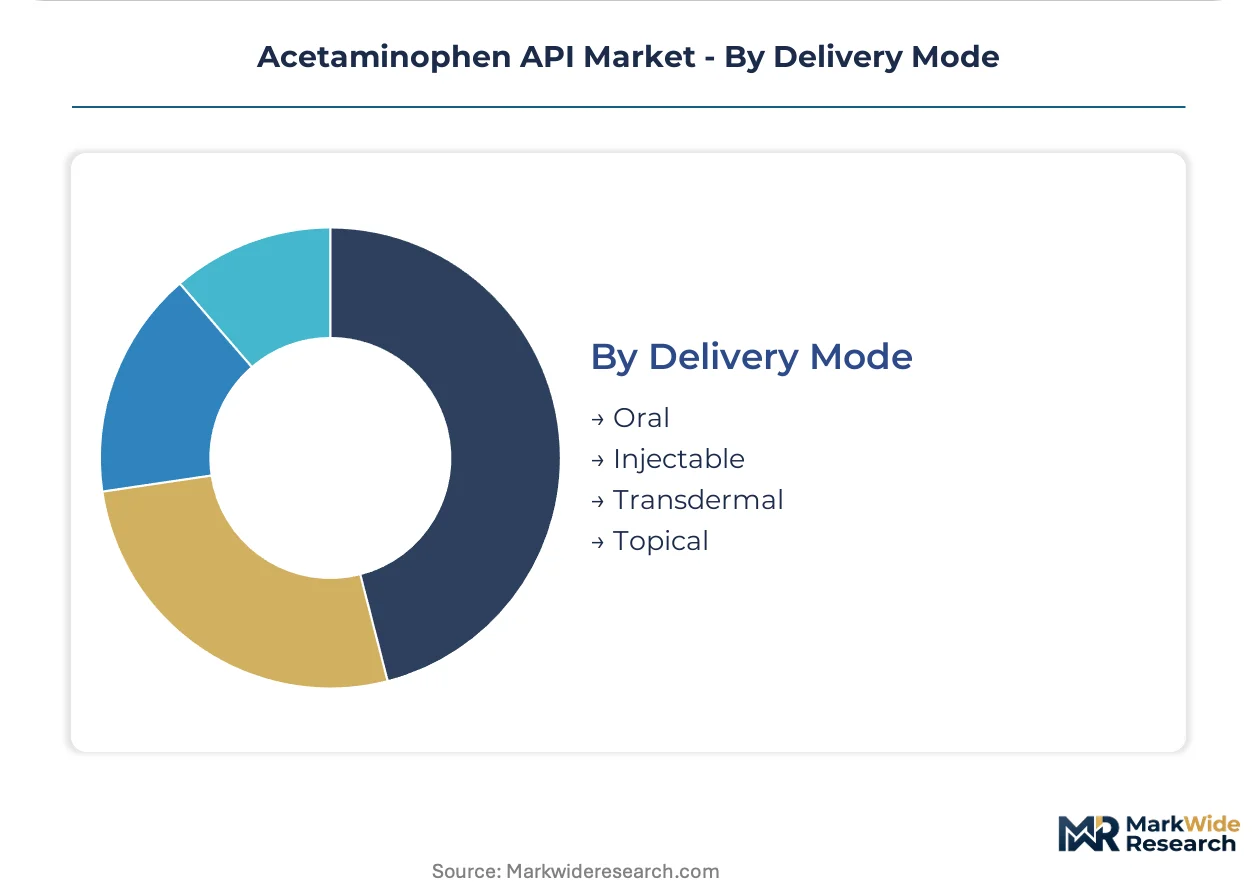
- Oral:Solid and liquid oral formulations absorb the vast majority of API volume, leveraging established tableting and bottling infrastructure. Indian manufacturers in Hyderabad and Ahmedabad supply bulk oral-grade API to North American and European formulation houses.
- Injectable:Sterile solution formulations for hospital and emergency settings demand endotoxin-controlled manufacturing and specialized packaging that limits the qualified supplier pool.
- Transdermal:Patch and gel formulations require permeation-enhancing excipient compatibility testing that extends development timelines.
- Topical:Cream and ointment applications serve localized pain management with lower regulatory barriers than systemic delivery routes.
Oral delivery maintains absolute volume dominance, while injectable formats carry the steepest expansion trajectory in value terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized analytical chemists with ICP-MS expertise cluster around Hyderabad and Ahmedabad, anchoring India's dominance in acetaminophen API export capacity. This workforce concentration shapes procurement patterns across North American and European formulation houses.
United States
Chronic pain management protocols and opioid combination therapies sustain steady API demand from domestic generic houses. FDA enforcement of ICH M7 genotoxic impurity thresholds filters subscale suppliers from approved vendor lists. New Jersey and Pennsylvania host formulation clusters that source acetaminophen under long-term offtake agreements with locked pricing mechanisms.
India
CDSCO alignment with ICH quality standards accelerates export pathways into regulated markets for domestic manufacturers. The PLI scheme for pharmaceuticals incentivizes capacity expansion in API manufacturing. Hyderabad and Ahmedabad manufacturing corridors supply bulk acetaminophen to European and North American clients under dedicated EU QP release arrangements.
China
Cost-competitive para-aminophenol feedstock production supports integrated API manufacturing at scale. NMPA oversight of drug substance registration tightens documentary requirements for starting material traceability. Zhejiang and Jiangsu provinces concentrate acetylation capacity serving both domestic formulation houses and export markets.
Germany
EMA centralized oversight streamlines vendor qualification for European formulation houses seeking compliant acetaminophen sources. REACH compliance for chemical intermediates adds regulatory layers to import sourcing decisions. North Rhine-Westphalia hosts CDMO clusters consolidating procurement around manufacturers with dedicated EU GMP certification.
Switzerland
Swissmedic's stringent GMP inspection protocols elevate barriers for API suppliers seeking direct supply relationships. High-value combination therapies for pain management command premium pricing from domestic innovator firms. Basel and Zurich anchor pharmaceutical R&D clusters that influence specification standards across European supply chains.
Acetaminophen API Market Vendor Landscape
The competitive structure tilts toward scaled manufacturers with backward integration into para-aminophenol intermediates. Regulatory compliance costs under ICH Q3D and ICH M7 guidelines compress the viable supplier base to capital-rich incumbents. Three archetypes dominate: integrated Indian exporters with dedicated EU QP infrastructure, Chinese cost leaders with feedstock control, and Western generics houses with multi-market dossier depth. Capacity expansion and regulatory dossier consolidation represent the dominant competitive moves reshaping vendor relationships.
Among Indian integrated manufacturers, Farmson Pharmaceuticals exemplifies the backward-integrated archetype through captive para-aminophenol production. Granules India Limited occupies a position within the contract manufacturing specialist tier, anchoring dedicated facility arrangements for European and North American clients. Teva Pharmaceutical Industries Ltd represents the Western generics house archetype, sustaining multiple FDA-approved supply pathways for integrated portfolio coverage.
| Leading Market Players |
|---|
| Farmson Pharmaceuticals |
| Hebei Jiheng Acetaminophen |
| Granules India Limited |
| Teva Pharmaceutical Industries Ltd |
| Sri Krishna Pharmaceuticals |
| Mallinckrodt Pharmaceuticals |
| IOL Chemicals and Pharmaceuticals |
| Rochem International Inc |
| Anhui BBCA Pharmaceutical Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Continuous flow chemistry adoption is compressing batch-to-batch variability while concentrating production economics among scaled manufacturers with capital reserves for microreactor installations. This technology transition simultaneously elevates quality consistency for ICH Q3D compliance and filters subscale suppliers from contract eligibility, reshaping how North American and European formulation houses evaluate total cost of ownership.
Pricing Analysis
Regulatory dossier bundling separates pricing tiers across the acetaminophen API market. Pharmaceutical companies purchasing complete FDA-EMA-Health Canada submission packages pay premiums over unbundled transactional volumes. Price differentiation hinges on EU QP release infrastructure and multi-site cGMP certification depth. Cost compression in standard-grade supply is intensifying as Chinese para-aminophenol feedstock volatility transmits downstream. Contract manufacturers exhibit highest price sensitivity due to thin margin structures, while innovator firms prioritize supply security over unit economics.
Supply Chain Analysis
Domestic-content requirements under India's PLI scheme for pharmaceuticals are redirecting capacity expansion toward export-oriented manufacturing corridors. Supply concentrates in India, China, and the United States, with Hyderabad-Ahmedabad clusters and Zhejiang-Jiangsu provinces anchoring global acetylation capacity. Feedstock dependencies rest on para-aminophenol intermediates, nitrobenzene, and acetanilide precursors tied to crude oil pricing cycles. Single-source vulnerability concentrates in India's western manufacturing corridor for European and North American buyers. Distribution runs through long-term offtake agreements with locked pricing mechanisms rather than spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in acetaminophen API hinges on continuous manufacturing adoption reducing solvent waste and quality hold times, while premium-tier pricing concentrates around integrated regulatory dossier offerings.
For Market Incumbents: Deepen backward integration into para-aminophenol intermediates to insulate margin stability from feedstock volatility cycles. Expand dedicated EU QP release infrastructure across secondary manufacturing sites to reduce single-point vulnerability under EMA enhanced inspection intensity. Anchor long-term offtake agreements with North American generic houses before CDSCO-aligned Indian competitors consolidate export pathways. For New Entrants and Emerging Players: Launch via specialized liquid formulation API supply with cold-chain documentation targeting pediatric and geriatric contract manufacturing channels. White-space concentration sits in sterile injectable-grade production where endotoxin-controlled manufacturing limits qualified competition. Penetrate through dedicated facility arrangements with European CDMOs consolidating approved vendor lists around traceable supply agreements. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Indian manufacturers lacking EU QP infrastructure but possessing CDSCO-aligned quality systems and PLI scheme eligibility. Long-term viability favors acquisition targets with captive para-aminophenol production and proven FDA inspection histories. Watch EMA third-country inspection intensity as the inflection signal for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Para-aminophenol | Captive intermediate production insulates margin stability from nitrobenzene feedstock volatility cycles. |
| Continuous Flow Manufacturing Adoption | Microreactor installations enable real-time release testing under ICH Q3D impurity consistency requirements. |
| EU QP Release Infrastructure Expansion | Dedicated qualified person capabilities filter subscale competitors from European formulation house vendor lists. |
| Long-term Offtake Agreement Structuring | Locked pricing mechanisms with North American generic houses displace fragmented multi-supplier procurement. |
| Pediatric Liquid Formulation Specialization | Dose-flexible API supply with cold-chain documentation captures geriatric care facility consolidation trends. |
Methodological Framework
Direct dialogue with API procurement directors at North American generic houses, regulatory affairs leads at Indian manufacturing exporters, EMA qualified persons overseeing EU release operations, and contract manufacturing officers at European CDMOs grounded qualitative findings. Secondary validation drew from FDA 483 inspection observations, EMA GMP certificates, CDSCO export approvals, and USP monograph revisions. Bottom-up capacity assessments across Hyderabad-Ahmedabad and Zhejiang-Jiangsu corridors triangulated against top-down demand modeling from formulation house procurement disclosures.
Segment-level projections across oral and injectable delivery modes, pain management and fever relief therapy areas, and pharmaceutical company versus contract manufacturer end users informed the analytical framework. CAGRs derived from regression analysis of historical API trade volumes, capacity utilization rates at major manufacturing clusters, and regulatory approval pathway timelines. Feedstock pricing volatility indices for para-aminophenol precursors and ICP-MS analytical equipment deployment rates served as industry-specific forecast inputs across the projection horizon.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sudden ICH impurity threshold revisions or FDA inspection queue disruptions. Forecasts reflect assumptions around CDSCO-ICH alignment maintenance, PLI scheme continuity, and EMA third-country inspection intensity without anticipating specific regulatory announcements. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Citicoline Market
Pharmaceutical Ingredients
Moxifloxacin Hcl (CAS 186826-86-8) Market
Pharmaceutical Ingredients
Alpha Lipoic Acid API Market
Pharmaceutical Ingredients
Pharmaceutical Suspension Market
Pharmaceutical Ingredients
Global Pharmaceutical Grade Silica Gel Market
Pharmaceutical Ingredients
Pemetrexed Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients CDMO Market
Pharmaceutical Ingredients
Originator Small Molecule Drug Market
Pharmaceutical Ingredients
Flurbiprofen Market
Pharmaceutical Ingredients
Celecoxib API Market
Pharmaceutical Ingredients
Large Molecule Drug Substance CDMO Market
Pharmaceutical Ingredients
Pharmaceuticals Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Small-Molecule Injectable Drugs Market
Pharmaceutical Ingredients
Global Tizanidine Market
Pharmaceutical Ingredients
Oridonin Market
Pharmaceutical Ingredients
India Active Pharmaceutical Ingredients (API) Market