
 Calcium Folinate for Injection Market | 2026-2036
Calcium Folinate for Injection Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Folinate for Injection Market Insights
Single-dose vial bundling with chemotherapy protocols is restructuring procurement decisions for hospital pharmacies. Fresenius Kabi leverages its European sterile manufacturing footprint to supply bundled folinate-chemotherapy kits to oncology centers. Jiangsu Hengrui Pharmaceutical anchors the Chinese market through backward integration into API production. Teva competes across North American and European channels with established ANDA portfolios.
Calcium folinate for injection is the calcium salt of folinic acid, supplied as a sterile solution or lyophilized powder reconstituted with water for injection, typically dosed at 50 mg/mL or 100 mg/vial for intravenous or intramuscular administration. It functions primarily as a rescue agent in high-dose methotrexate therapy and in combination with 5-fluorouracil for colorectal cancer regimens. The lyophilized powder segment carries higher stability margins and commands premium positioning in cold-chain-constrained markets, while the injectable solution format dominates hospital throughput settings where preparation speed governs workflow. End-user concentration tilts toward oncology centers, where patient volume and protocol standardization create captive demand pools that lock in supplier relationships.
The FDA's sterile drug guidance and EMA's GMP Annex 1 revisions for aseptic processing jointly elevate barrier requirements for folinate manufacturing, filtering smaller API producers from the finished-dose supply base. China's NMPA aligns domestic injectable standards with ICH Q7 through intensified on-site inspections, compressing the qualified supplier list for hospital tenders. India's CDSCO mandates bioequivalence documentation for generic folinate approvals, extending registration timelines for new entrants. Stakeholders must monitor regulatory divergence between US and Chinese sterility standards as it threatens to fragment formulation strategies and duplicate validation costs.
Market Dynamics
China's NMPA intensified GMP inspection protocols for sterile injectables, compressing qualified supplier lists and forcing hospital procurement departments to rebundle folinate-chemotherapy kits around fewer certified manufacturers.
Growth Catalysts
- High-dose methotrexate rescue protocols:Oncology centers in Jiangsu and Zhejiang provinces are expanding folinate co-administration in pediatric leukemia and osteosarcoma regimens, locking in recurring demand pools through treatment standardization.
- EMA GMP Annex 1 barrier elevation:Revised aseptic processing requirements are filtering subscale API producers from European finished-dose supply chains, consolidating volume with sterile manufacturing specialists.
- Lyophilized powder stability advantages:Cold-chain-constrained markets across inland China are prioritizing powder formats over liquid solutions, reshaping formulation R&D priorities toward longer shelf-life profiles.
Market Restraints
- API supply concentration:Backward-integrated Chinese producers control key folinic acid precursor streams, exposing non-integrated finished-dose manufacturers to input allocation risk during capacity crunches.
- CDSCO bioequivalence documentation:India's regulator mandates extended clinical bridging studies for generic folinate approvals, stretching registration timelines and freezing new entrant pipelines.
- Leucovorin oral substitution:Bioequivalent oral formulations for low-dose rescue indications are displacing injectable volumes in outpatient oncology settings where IV access is not protocol-mandated.
Strategic Opportunities
- Centralized compounding pharmacy expansion:US hospital systems are outsourcing sterile folinate preparation to 503B facilities, creating channel consolidation openings for high-volume contract manufacturers.
- Bundled chemotherapy kit penetration:Single-vial folinate packaging integrated with 5-FU infusion systems is capturing procurement preference in European day-treatment centers seeking workflow compression.
- PLI scheme API incentives:India's production-linked incentive framework for critical drug intermediates is attracting greenfield folinic acid capacity, potentially diversifying precursor sourcing beyond eastern China.
Industry Challenges
- Aseptic processing technician scarcity:FDA and EMA barrier-isolator requirements have outpaced sterile manufacturing workforce training pipelines, extending qualification timelines for new production lines.
- ICH Q7 validation duplication:Divergent US and Chinese sterility documentation standards are forcing parallel validation runs, inflating compliance costs for suppliers serving both markets.
- Legacy ERP integration friction:Hospital pharmacy inventory systems struggle to track lot-level folinate serialization under evolving DSCSA traceability mandates, delaying automated replenishment adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Folinate for Injection Market |
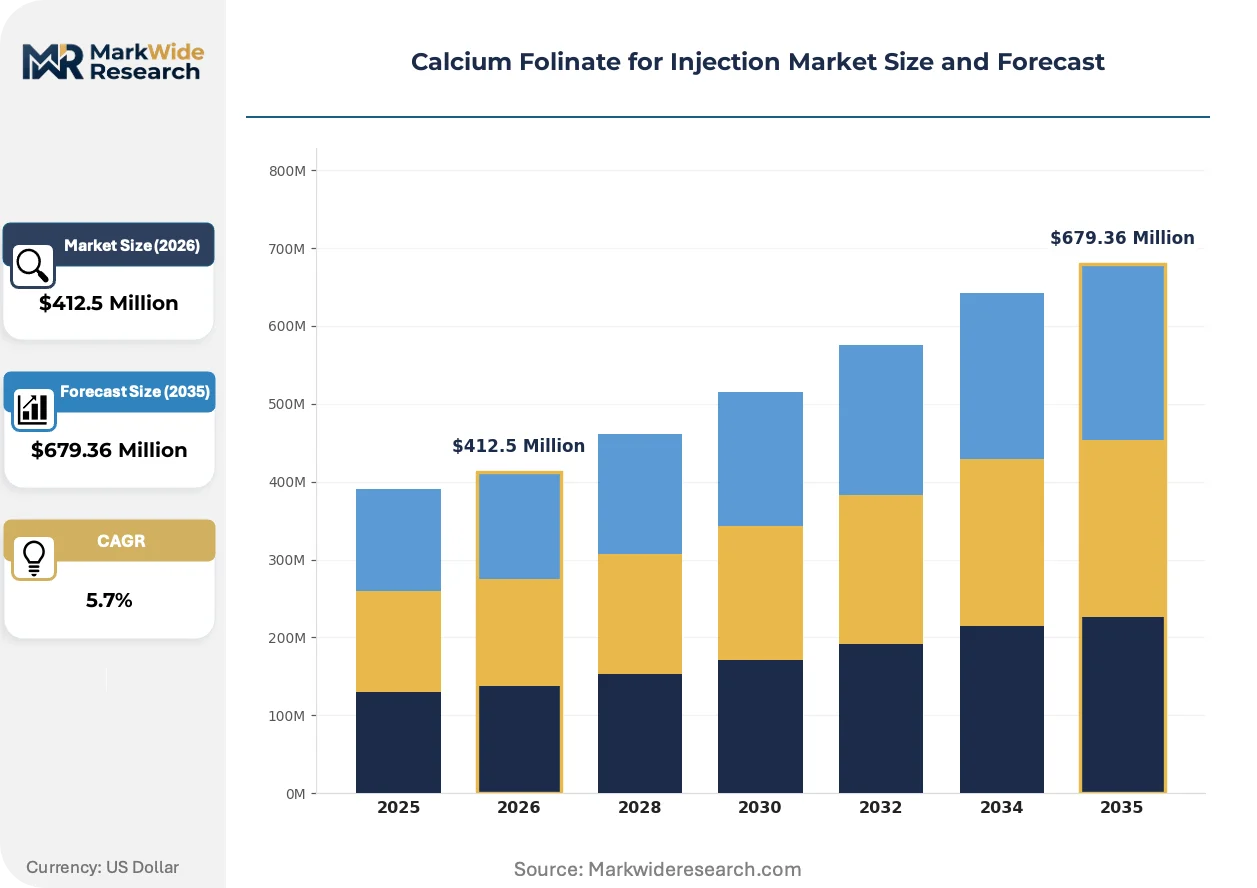
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $679.36 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Solution, Powder for Injection, Premixed Solution, Lyophilized Powder End User: Hospitals, Clinics, Oncology Centers, Research Laboratories Administration Route: Intravenous Injection, Intramuscular Injection, Subcutaneous Injection, Intra-arterial Injection Therapeutic Area: Cancer Treatment, Vitamin Deficiency, Surgical Support, Chemotherapy |
| Companies Covered | SL Pharmaceutical, Jiangsu Hengrui Pharmaceutical, Harbin Medisan Pharmaceutical, Fresenius Kabi, Zhejiang Wansheng Pharmaceutical, Youcare Pharmaceutical, Shanxi PUDE Pharmaceutical, Teva, Luoxin Pharmaceutical Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Folinate for Injection Market Trends and Innovations
Closed-system drug-transfer devices and isolator-based filling lines are compressing contamination risk profiles while robotic compounding is restructuring pharmacy labor models across high-throughput oncology centers.
Isolator-integrated filling technology is automating aseptic folinate vial processing by enclosing critical exposure zones within unidirectional airflow barriers. Fresenius Kabi and Jiangsu Hengrui are deploying these systems at European and Chinese sites respectively to reduce human intervention during lyophilization loading. The technology is automating batch release timelines and compressing environmental monitoring overhead, enabling faster throughput without proportional headcount expansion.
China's NMPA alignment with ICH Q7 through intensified on-site inspections is elevating documentation burdens for sterile injectable exporters. Domestic manufacturers must now submit real-time production data streams to provincial regulators, mirroring FDA's quality metrics initiative. The policy is accelerating facility upgrade cycles among mid-tier Chinese folinate producers who previously relied on paper-based batch records.
Single-dose vial bundling with chemotherapy protocols is restructuring hospital pharmacy procurement from standalone folinate purchasing to integrated kit tenders. Oncology centers in Zhejiang province now specify folinate-5-FU compatibility in single-cart configurations, displacing separate vial sourcing. This pattern is most visible in China's tier-1 city hospital consortia where standardization committees govern formulary decisions.
Calcium Folinate for Injection Market Segmentation
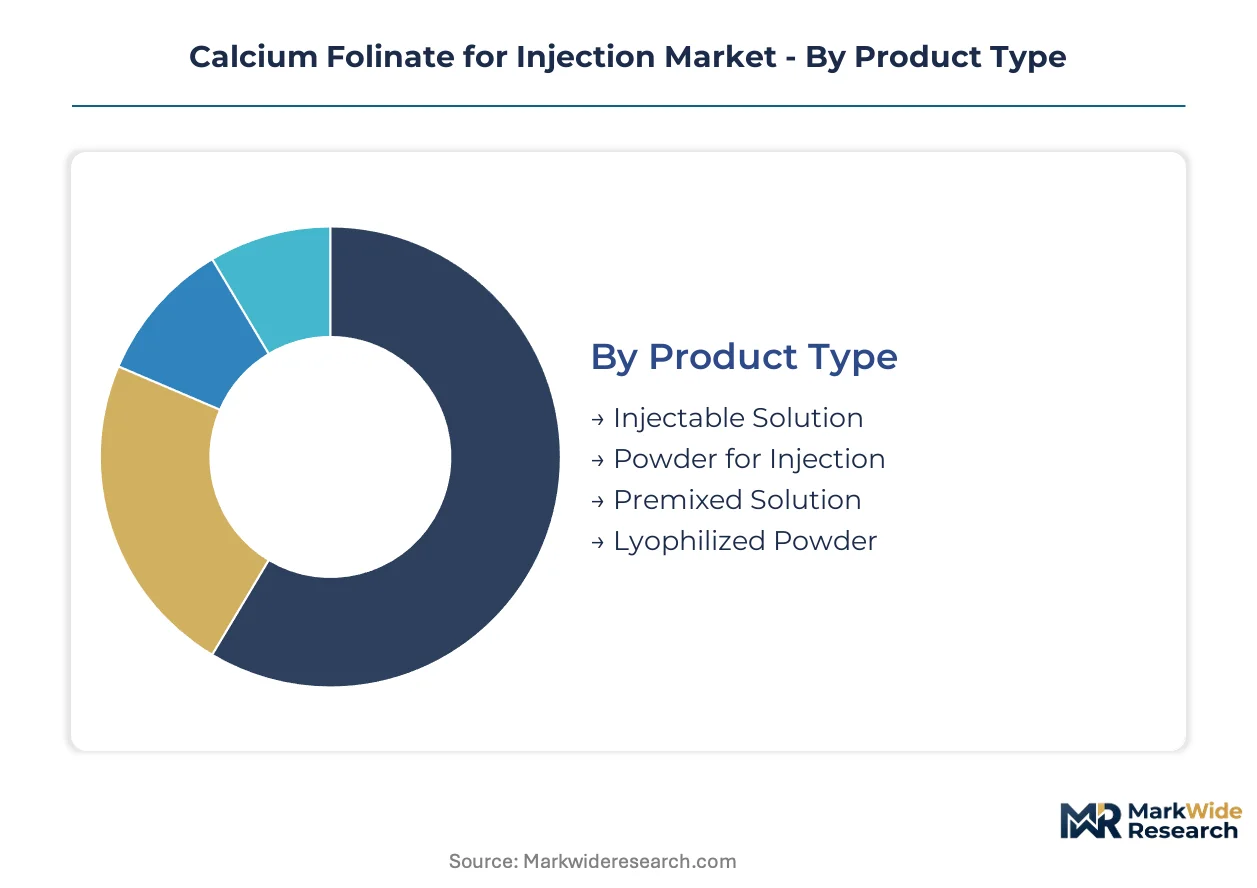
Calcium folinate for injection segments around formulation stability, administration workflow, and therapeutic protocol requirements. Procurement patterns diverge sharply between hospital pharmacies prioritizing preparation speed and oncology centers demanding cold-chain resilience.
Product Type:
Customization spans from ready-to-use liquid formats requiring minimal handling to lyophilized powders demanding reconstitution protocols but offering extended shelf stability.
- Injectable Solution:Supplied as sterile 50 mg/mL ready-to-administer liquid in single-dose vials or ampoules. Hospital throughput settings in Jiangsu province favor this format for same-day chemotherapy preparation cycles where workflow speed governs pharmacy labor allocation.
- Lyophilized Powder:Freeze-dried calcium folinate requiring sterile water reconstitution before administration. Cold-chain-constrained markets across inland China and tier-2 city hospitals prioritize this segment for 24-month stability margins and reduced refrigeration infrastructure.
- Powder for Injection:Sterile crystalline powder packaged in vials with separate diluent. This format occupies mid-tier positioning between convenience and stability, common in clinic settings with intermittent patient volume.
- Premixed Solution:Factory-prepared folinate in ready-to-hang infusion bags. Oncology day-treatment centers in Zhejiang province specify this segment for bundled 5-FU protocol administration.
Leading the category by volume: Injectable Solution. Growing fastest: Lyophilized Powder.
End User:
Cost tier stratification separates high-volume institutional purchasers from specialized research consumers with distinct specification requirements.
- Oncology Centers:Dedicated cancer treatment facilities administering high-dose methotrexate rescue and 5-FU combination protocols. These centers lock in supplier relationships through standardized regimen purchasing and captive patient volume.
- Hospitals:General acute-care institutions with diversified pharmacy formularies. Multi-department sourcing creates fragmented procurement patterns compared to specialized oncology settings.
- Clinics:Outpatient facilities with lower patient throughput and reduced cold-chain infrastructure. Oral leucovorin substitution is displacing injectable volumes in this segment where IV access is not mandated.
- Research Laboratories:Academic and clinical trial sites requiring GMP-compliant investigational supplies. Specification stringency and lot documentation burdens exceed commercial pharmaceutical standards.
Highest procurement volume concentrates in Oncology Centers. Steepest expansion trajectory appears in Research Laboratories supporting folinate combination trials.
Administration Route:
Volume scale differentiates high-frequency intravenous delivery from specialized intra-arterial applications with restricted practitioner pools.
- Intravenous Injection:Direct bolus or infusion into venous circulation. This route dominates methotrexate rescue protocols and 5-FU combination regimens across hospital oncology departments.
- Intramuscular Injection:Depot administration into skeletal muscle for sustained absorption. Lower-cost clinic settings employ this route where IV infrastructure is limited.
- Subcutaneous Injection:Delivery into adipose tissue beneath dermis. Specialized protocols for outpatient folinate supplementation utilize this minimally invasive approach.
- Intra-arterial Injection:Catheter-directed delivery to specific vascular territories. Regional chemotherapy protocols for hepatic metastases require interventional radiology collaboration and restricted to tertiary oncology centers.
Intravenous Injection commands the volume majority. Intra-arterial Injection shows the fastest uptake in regional chemotherapy expansion.
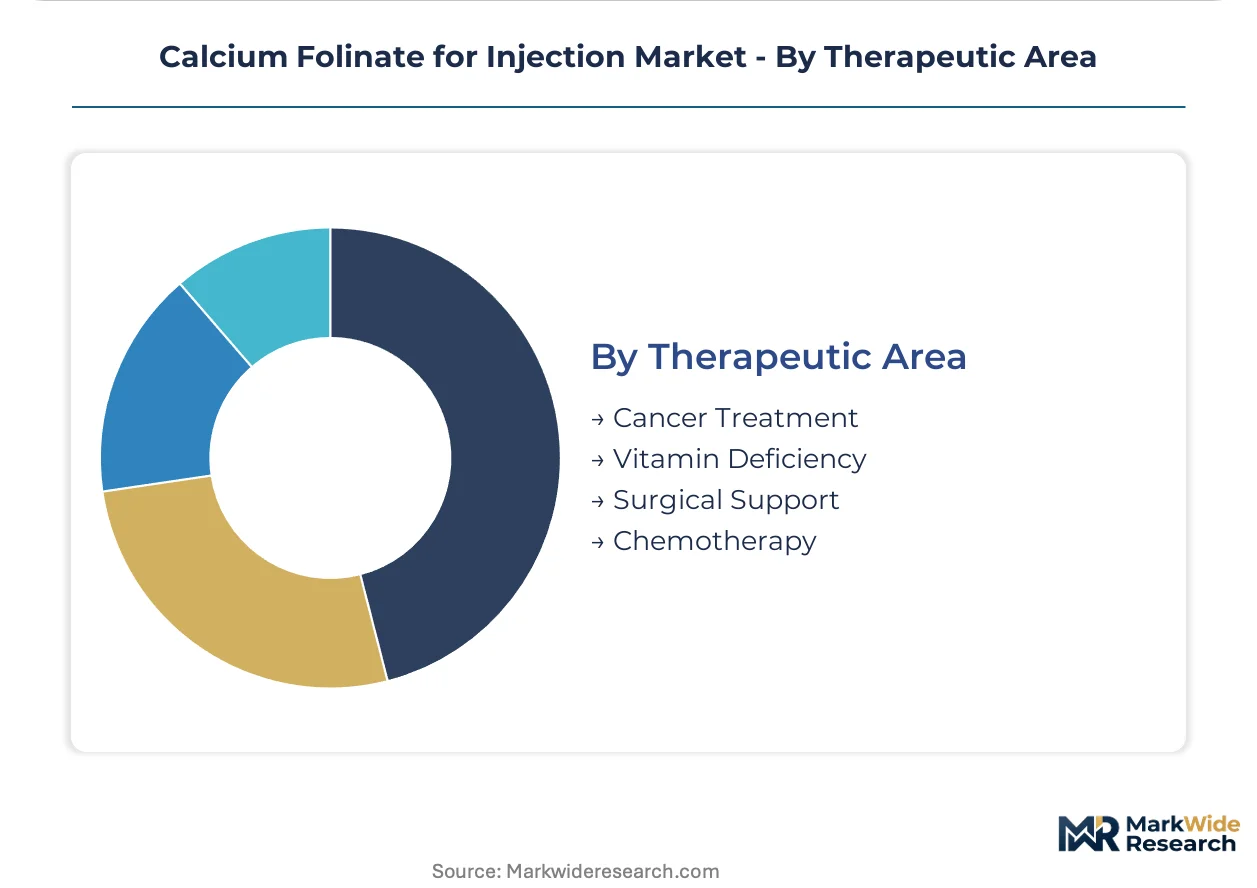
Therapeutic Area:
Maturity gradients separate established oncology applications from emerging surgical support indications with evolving evidence bases.
- Chemotherapy:Folinic acid rescue following high-dose methotrexate and potentiation of 5-fluorouracil cytotoxicity. This indication anchors commercial demand through protocol standardization in pediatric leukemia and colorectal regimens.
- Cancer Treatment:Broader oncological applications beyond cytotoxic rescue, including folate pathway modulation in targeted therapy combinations. Research pipelines are exploring folinate synergy with immune checkpoint inhibitors.
- Vitamin Deficiency:Replacement therapy for folate deficiency states unresponsive to oral supplementation. Hospitalized patients with malabsorption or NPO status require parenteral delivery.
- Surgical Support:Perioperative folate repletion in gastrointestinal surgery patients. Evidence development for this indication remains preliminary compared to oncology applications.
Chemotherapy holds the established volume base. Cancer Treatment applications are gaining share fastest through combination therapy expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu province's biomedical industrial parks anchor concentration through tax incentives and streamlined NMPA registration pathways for sterile injectable exporters.
China
Oncology centers in Jiangsu and Zhejiang provinces drive lyophilized powder procurement through backward-integrated API-to-finished-dose manufacturing. NMPA intensified GMP inspection protocols for sterile injectables, compressing qualified supplier lists for hospital tenders. Zhejiang's Hangzhou biomedical cluster hosts multiple folinate producers upgrading to isolator-based filling lines under provincial regulator supervision.
United States
Hospital systems and 503B centralized compounding pharmacies sustain demand for bundled folinate-chemotherapy kits in high-dose methotrexate rescue protocols. FDA sterile drug guidance elevates barrier requirements for aseptic processing, filtering subscale manufacturers from finished-dose supply chains. New Jersey and Massachusetts pharmaceutical corridors concentrate sterile manufacturing specialists serving oncology networks.
Germany
European oncology day-treatment centers specify premixed folinate solutions for 5-FU combination regimens. EMA GMP Annex 1 revisions for aseptic processing mandate isolator-integrated filling technology, consolidating volume with sterile manufacturing specialists. Baden-Württemberg's pharmaceutical manufacturing belt houses production facilities supplying bundled chemotherapy kits across EU markets.
India
Domestic oncology centers and export-oriented finished-dose manufacturers create dual-track demand for folinate APIs and injectables. CDSCO mandates bioequivalence documentation for generic approvals, extending registration timelines for new entrants. Gujarat and Maharashtra pharmaceutical clusters attract PLI scheme incentives for critical drug intermediate production, diversifying precursor sourcing.
Japan
Tertiary oncology centers maintain protocol-standardized folinate procurement for pediatric leukemia and colorectal regimens. PMDA aligns sterile injectable standards with ICH Q7 through intensified manufacturing site inspections. Tokyo-Osaka pharmaceutical corridors concentrate finished-dose producers serving domestic hospital consortia with premium stability-profile requirements.
Calcium Folinate for Injection Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation and API supply tiers. The market structure tilts toward consolidation as regulatory barrier elevation filters subscale participants from sterile manufacturing. Three archetypes dominate: backward-integrated Chinese pharmaceutical groups controlling precursor streams, European sterile manufacturing specialists leveraging aseptic processing expertise, and generic finished-dose competitors with established ANDA portfolios. Capacity expansion and bundled kit integration represent the dominant competitive moves reshaping procurement relationships.
Among Chinese producers, Jiangsu Hengrui Pharmaceutical and Zhejiang Wansheng Pharmaceutical occupy positions within the backward-integrated tier, exemplifying domestic API-to-finished-dose control. Fresenius Kabi represents the European sterile manufacturing specialist archetype, anchoring supply to oncology centers through aseptic processing capabilities. Teva sits within the generic finished-dose competitor category, serving North American and European channels through established regulatory filings.
| Leading Market Players |
|---|
| SL Pharmaceutical |
| Jiangsu Hengrui Pharmaceutical |
| Harbin Medisan Pharmaceutical |
| Fresenius Kabi |
| Zhejiang Wansheng Pharmaceutical |
| Youcare Pharmaceutical |
| Shanxi PUDE Pharmaceutical |
| Teva |
| Luoxin Pharmaceutical Group |
| Others |
Pricing and Supply Chain Analysis
Backward-integrated Chinese pharmaceutical groups, anchored by state-supported financing through provincial industrial funds, exercise pricing discipline through captive API production while European sterile manufacturing specialists command premiums via isolator-technology certification tiers. This ownership-financing divergence creates tiered pricing power where hospital procurement departments face bundled-kit premiums from aseptic processing leaders or absorb allocation risk from non-integrated finished-dose suppliers.
Pricing Analysis
Cost-down pressure on lyophilized powder formats accelerates because NMPA inspection intensity has compressed qualified supplier lists, forcing oncology centers in Jiangsu and Zhejiang to absorb premium positioning for isolator-certified production. Three-tier pricing structure across premium isolator-grade, standard barrier-technology, and economy non-integrated tiers separates contract manufacturers with EMA Annex 1 compliance from mid-tier domestic producers. Hospital pharmacy buyers exhibit highest price sensitivity in standalone folinate procurement, while bundled chemotherapy kit purchasers accept premium positioning for workflow compression.
Supply Chain Analysis
China's domestic-content mandates for sterile injectables under NMPA localization policies are reshaping sourcing toward backward-integrated producers in Jiangsu and Zhejiang provinces, reducing import dependency for folinic acid precursors. Raw material supply draws from folinic acid API streams, sterile water for injection, and lyophilization excipients, with single-source vulnerability concentrated in eastern Chinese precursor manufacturing. Distribution runs through hospital consortia tenders and 503B centralized compounding pharmacy networks in the United States, with tariff exposure minimal given localized production clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aseptic processing technician scarcity across FDA and EMA jurisdictions props pricing by extending new production line qualification timelines, creating supply-constrained conditions that favor incumbent sterile manufacturing specialists with trained workforce pipelines.
For Market Incumbents: Acquire isolator-integrated filling capacity in Baden-Württemberg or Hangzhou biomedical clusters to preempt EMA Annex 1 and NMPA barrier-elevation requirements. Defend against oral leucovorin substitution by locking oncology center relationships through bundled 5-FU protocol kits with single-cart configurations. For New Entrants and Emerging Players: Begin with 503B centralized compounding pharmacy outsourcing contracts in United States hospital systems, where regulatory entry barriers are lower than finished-dose NDA pathways. Target research laboratory segments supplying folinate for combination therapy trials, leveraging GMP-compliant investigational supply specifications as a go-to-market angle distinct from commercial pharmaceutical standards. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier Chinese folinate producers facing NMPA documentation upgrade burdens in Jiangsu province. Long-term viability hinges on isolator-technology deployment timelines and API-to-finished-dose integration depth. Watch CDSCO bioequivalence documentation requirements as the signal for Indian market entry inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator-Integrated Filling Technology Deployment | Fresenius Kabi and Jiangsu Hengrui compress contamination risk while automating batch release timelines. |
| Backward Integration into Folinic Acid API Production | Hengrui and Zhejiang Wansheng control precursor streams, reducing input allocation exposure. |
| Bundled Chemotherapy Kit Integration | Single-vial folinate-5-FU configurations capture Zhejiang province hospital consortia procurement preference. |
| 503B Centralized Compounding Pharmacy Partnership | US hospital systems outsource sterile preparation, creating channel consolidation for high-volume manufacturers. |
| EMA GMP Annex 1 Compliance Certification | European sterile manufacturing specialists filter subscale competitors from finished-dose supply chains. |
Research Methodology
Multi-period observation of NMPA inspection intensity, EMA Annex 1 adoption timelines, and CDSCO registration backlogs anchored the trend analysis, supplemented by interviews with sterile manufacturing plant managers, hospital pharmacy procurement directors, oncology center formulary committees, and regulatory affairs leads at finished-dose exporters. Secondary validation drew from FDA sterile drug guidance filings, EMA GMP inspection databases, NMPA provincial registration disclosures, and hospital tender documentation across Jiangsu and Zhejiang provinces. Bottom-up volume triangulation from API production capacity and top-down demand modeling from chemotherapy protocol standardization were cross-referenced for convergence.
Input-output matrices mapped folinic acid precursor availability through finished-dose formulation output across lyophilized powder, injectable solution, and premixed bag segments, with dosage form, administration route, therapeutic protocol, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from regression analysis of historical procurement volume against protocol expansion rates and barrier-technology adoption curves, incorporating isolator-technology deployment schedules and PLI scheme incentive uptake as industry-specific forecast inputs.
Regulatory inspection intensity divergence between US and Chinese sterility standards, oral leucovorin substitution velocity in outpatient settings, and aseptic processing workforce training pipeline constraints are the dominant revision risks to projection assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Global Granisetron Market
Pharmaceutical Ingredients
Immunosuppressants Market
Pharmaceutical Ingredients
Pharmaceutical Grade Magnesium Hydroxide Market
Pharmaceutical Ingredients
Small Molecule Drug Discovery Market
Pharmaceutical Ingredients
Tranexamic Acid API Market
Pharmaceutical Ingredients
Pharmaceuticals Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Antipyretic Analgesic Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Calcium Citrate Market
Pharmaceutical Ingredients
Pharma Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
France Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Ferrous Succinate Market
Pharmaceutical Ingredients
Oral Transmucosal Drugs Market
Pharmaceutical Ingredients
Asia-Pacific Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceutical Ingredients
Global Chlorpheniramine Maleate Market
Pharmaceutical Ingredients
Mitotic Inhibitors Market
Pharmaceutical Ingredients
Diclofenac Sodium API Market