
 Pharmaceutical Grade Beta-Alanine Market | 2026-2036
Pharmaceutical Grade Beta-Alanine Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Grade Beta-Alanine Market Insights
Precision fermentation is tilting pharmaceutical-grade amino acid production away from traditional chemical synthesis toward biosynthetic platforms with higher chiral purity and lower residual solvent profiles. Natural Alternatives International, Inc. leverages its vertically integrated Carlsbad facility to control raw material quality from fermentation through finished powder. Anhui Huaheng Biotechnology Co., Ltd. anchors Chinese supply through industrial-scale bioreactor capacity serving domestic and export nutraceutical formulators. Evonik Industries AG differentiates via pharmaceutical-grade cGMP compliance that qualifies its beta-alanine for parenteral and high-purity oral applications.
Pharmaceutical grade beta-alanine denotes L-enantiomer-pure amino acid meeting USP/EP monograph specifications, typically assaying at minimum 98.5 percent purity with heavy metal limits below 10 ppm and microbial contamination controlled per ICH Q3D guidelines; manufacturers employ either enzymatic resolution or recombinant fermentation followed by crystallization and spray-drying to achieve these parameters. The compound functions primarily as a carnosine precursor in skeletal muscle, with secondary applications in neuromodulatory formulations and anti-aging cosmeceuticals where cellular buffering capacity matters. Powder dominates current volume due to bulk blending economics in sports nutrition and pharmaceutical compounding, while injectable formats command the steepest margin pools as hospital and clinical trial demand rises for rapid bioavailability. Capsules sustain steady growth in direct-to-consumer channels where unit-dose convenience offsets higher per-gram pricing.
FDA enforces pharmaceutical-grade amino acid standards through 21 CFR 211 cGMP regulations and USP-NF monograph compliance, while EMA's ICH Q3D elemental impurity guidelines constrain heavy metal thresholds for EU market access. China's NMPA implements GB standards for pharmaceutical amino acids that foreign producers must meet through on-site inspections and registration dossiers. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP standards, as divergence in purity or validation requirements would fragment qualification costs and complicate multi-regional supply strategies.
Market Dynamics
Precision fermentation platforms are compressing synthetic amino acid margins while cGMP certification requirements bifurcate supply tiers between hospital-grade and nutraceutical-grade producers.
Growth Catalysts
- Clean-label fermentation:Biosynthetic beta-alanine eliminates petrochemical residues, satisfying EU EFSA Novel Food requirements and US FDA GRAS petitions for sports nutrition applications.
- Carnosine precursor demand:Clinical validation of muscle buffering drives hospital compounding pharmacy procurement for sarcopenia and chronic fatigue protocols.
- EMA ICH Q3D harmonization:Heavy metal thresholds below 10 ppm enable single-qualification dossiers across Germany, France, and Benelux markets.
Market Restraints
- Feedstock volatility:Corn-derived glucose prices fluctuate with Midwest US agricultural yields, squeezing fermentation cost structures.
- Chinese supply concentration:Industrial-scale bioreactor capacity clusters in Anhui and Shandong provinces, creating geographic single-source risk for European formulators.
- Chiral purity ceiling:Enzymatic resolution methods plateau at 99.2% L-enantiomer purity, constraining parenteral-grade expansion.
Strategic Opportunities
- Anti-aging cosmeceuticals:Cellular buffering claims in topical formulations open dermatology channel penetration beyond sports nutrition.
- India PLI scheme:Pharmaceutical-grade amino acid manufacturing incentives under the Production Linked Incentive program attract cGMP facility investment.
- Direct-to-consumer capsules:Unit-dose convenience commands 40-60% per-gram premiums over bulk powder in subscription wellness channels.
Industry Challenges
- Bioprocess engineering talent:Scarcity of fermentation scale-up specialists delays industrial bioreactor commissioning timelines by 8-14 months.
- Multi-pharmacopeial validation:Divergent USP, EP, and ChP residual solvent testing methods force redundant analytical method development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Grade Beta-Alanine Market |
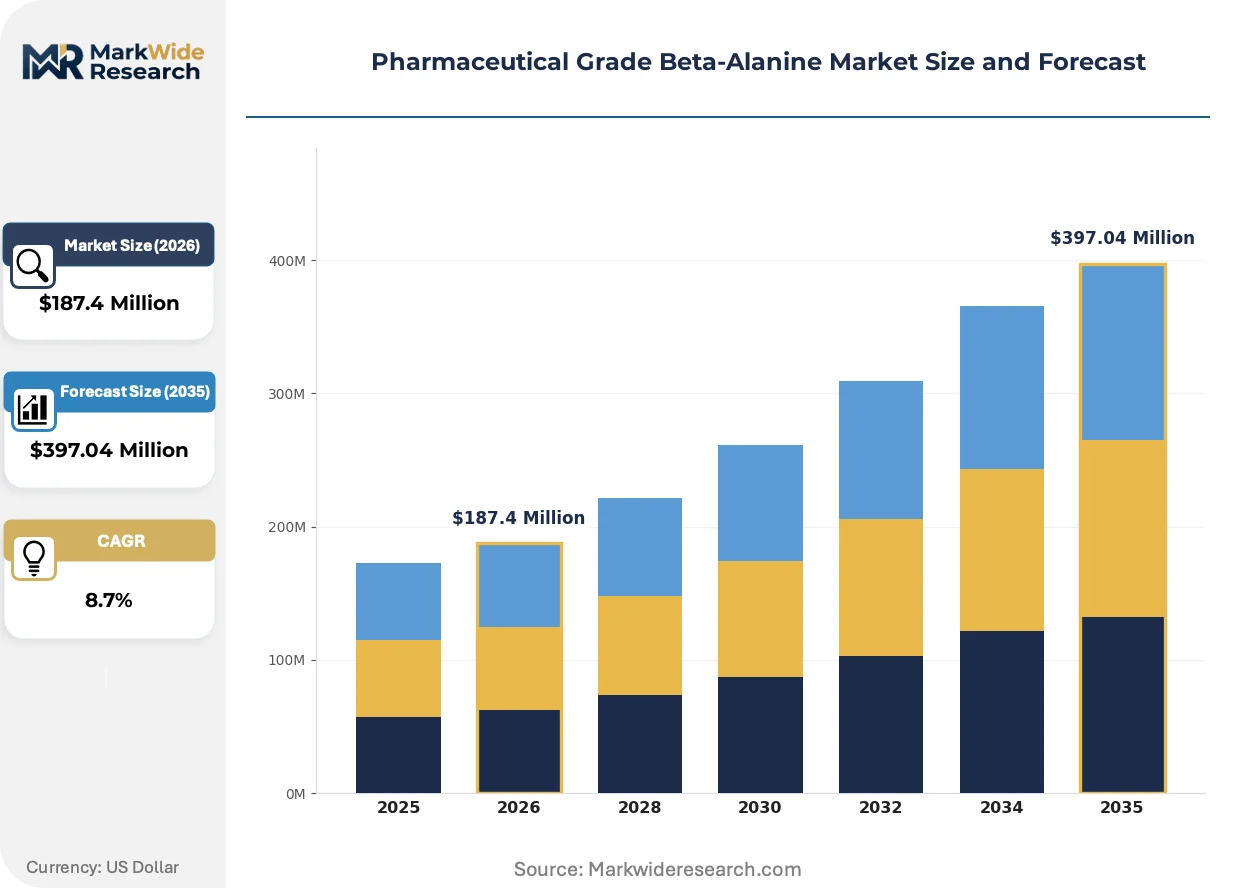
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powder, Tablets, Injectable End User: Pharmaceutical Companies, Nutraceutical Companies, Research Institutes, Sports Nutrition Application: Muscle Endurance, Anti-Aging, Neurological Disorders, Sports Performance Distribution Channel: Online Retail, Pharmacies, Health Food Stores, Direct Sales |
| Companies Covered | Natural Alternatives International, Inc., Anhui Huaheng Biotechnology Co., Ltd., NOW Foods Inc., Prinova Group LLC., Spectrum Chemical, Wuxi Jinghai Amino Acid Co., Ltd., Xinfa Pharmaceuticals Co., Ltd., Merck KGaA, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Grade Beta-Alanine Market Trends and Innovations
Continuous bioprocessing and single-use bioreactor technologies are collapsing batch cycle times while regulatory data integrity mandates reshape quality management system investments.
Recombinant microbial strains engineered for beta-alanine overproduction achieve titers above 120 g/L in fed-batch fermentation, compressing unit economics below traditional chemical synthesis routes. Contract manufacturers in Germany and Switzerland are retrofitting legacy antibiotic fermentation lines for amino acid production. Chemical synthesis employing acrylonitrile precursors is rendering obsolete for pharmaceutical-grade applications due to residual solvent and racemic mixture limitations.
EMA's updated ICH Q3D elemental impurity guidelines now mandate risk assessments for cobalt and nickel catalyst residues in enzymatic resolution processes. European formulators must submit updated control strategies or face import detention at Rotterdam and Hamburg ports. Parenteral nutrition compounders face the steepest compliance burden, as intravenous applications trigger the strictest endotoxin and particulate specifications.
Hospital procurement consortiums in the United States are consolidating amino acid purchasing through group purchasing organizations, squeezing spot-market spot buyers. Direct contracts between IDN pharmacy directors and cGMP-certified manufacturers are displacing traditional distributor intermediaries. This concentration is most pronounced in the Southeast and Midwest, where Catholic Health Initiatives and CommonSpirit Health networks command multi-year supply agreements.
Pharmaceutical Grade Beta-Alanine Market Segmentation
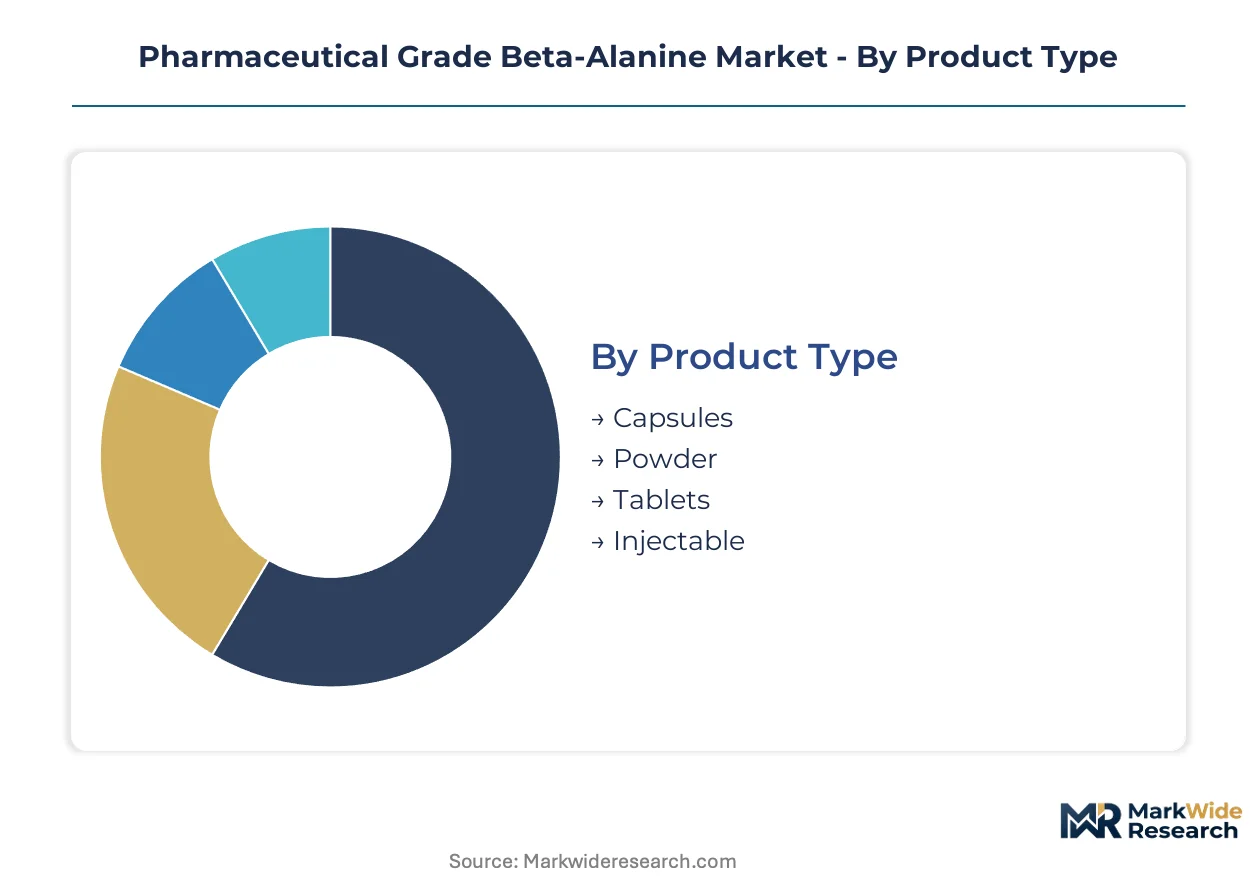
Pharmaceutical grade beta-alanine demand fragments across four distinct axes: physical form dictates manufacturing investment and margin structure; end-user type determines regulatory burden and contract terms; application focus shapes clinical validation requirements; and channel selection controls price realization and customer acquisition costs.
Product Type:
Physical format determines production equipment, stability protocols, and margin capture across the value chain.
- Powder:Bulk crystalline form dominates volume through blending economics in sports nutrition compounding and pharmaceutical manufacturing. cGMP-certified facilities in Germany and the United States command premium offtake for hospital-grade powder meeting USP-NF monograph specifications.
- Injectable:Sterile solution formats trigger the strictest endotoxin and particulate specifications per FDA 21 CFR 211 and EMA ICH Q3D guidelines. Hospital procurement consortiums in the United States consolidate purchasing through group purchasing organizations for rapid bioavailability in clinical settings.
- Capsules:Unit-dose convenience commands 40-60% per-gram premiums over bulk powder in direct-to-consumer subscription wellness channels.
- Tablets:Compressed solid dosage forms serve retail pharmacy distribution with extended shelf stability requirements.
Powder commands the established base. The steepest expansion runs through injectable formats as parenteral nutrition compounders scale hospital procurement.
End User:
Customer type bifurcates the market between regulated pharmaceutical procurement and performance-oriented nutraceutical channels.
- Sports Nutrition:Clean-label fermentation demand from formulation houses drives bulk procurement as EFSA Novel Food requirements displace petrochemical-derived inputs. Precision fermentation platforms in China and Germany supply this segment with biosynthetic beta-alanine achieving titers above 120 g/L.
- Pharmaceutical Companies:cGMP compliance mandates for parenteral and high-purity oral applications require validated analytical methods against USP, EP, and ChP standards. Multi-pharmacopeial validation forces redundant method development for residual solvent testing.
- Nutraceutical Companies:Direct-to-consumer brands prioritize unit-dose convenience and subscription channel economics over bulk powder sourcing.
- Research Institutes:Clinical trial material supply demands batch documentation and certificate of analysis rigor for investigational new drug applications.
Sports Nutrition anchors current volume. Pharmaceutical Companies are gaining share fastest as sarcopenia and chronic fatigue protocols drive hospital compounding pharmacy procurement.
Application:
Therapeutic focus areas determine clinical validation depth and regulatory pathway requirements.
- Muscle Endurance:Carnosine precursor function in skeletal muscle buffering supports sports nutrition formulation and hospital protocols for muscle wasting conditions. Clinical validation drives procurement from compounding pharmacies in the United States and Germany.
- Anti-Aging:Cellular buffering capacity claims open dermatology channel penetration for topical formulations and oral cosmeceutical applications beyond traditional sports nutrition.
- Sports Performance:Athletic optimization applications concentrate demand in powder and capsule formats through online retail and direct sales channels.
- Neurological Disorders:Neuromodulatory formulation applications require higher purity grades and specialized stability data for central nervous system targeting.
Muscle Endurance holds the volume base. Anti-Aging is climbing the fastest as cellular buffering claims expand dermatology and wellness channel penetration.
Distribution Channel:
Channel structure controls price realization, customer relationships, and regulatory touchpoint density.
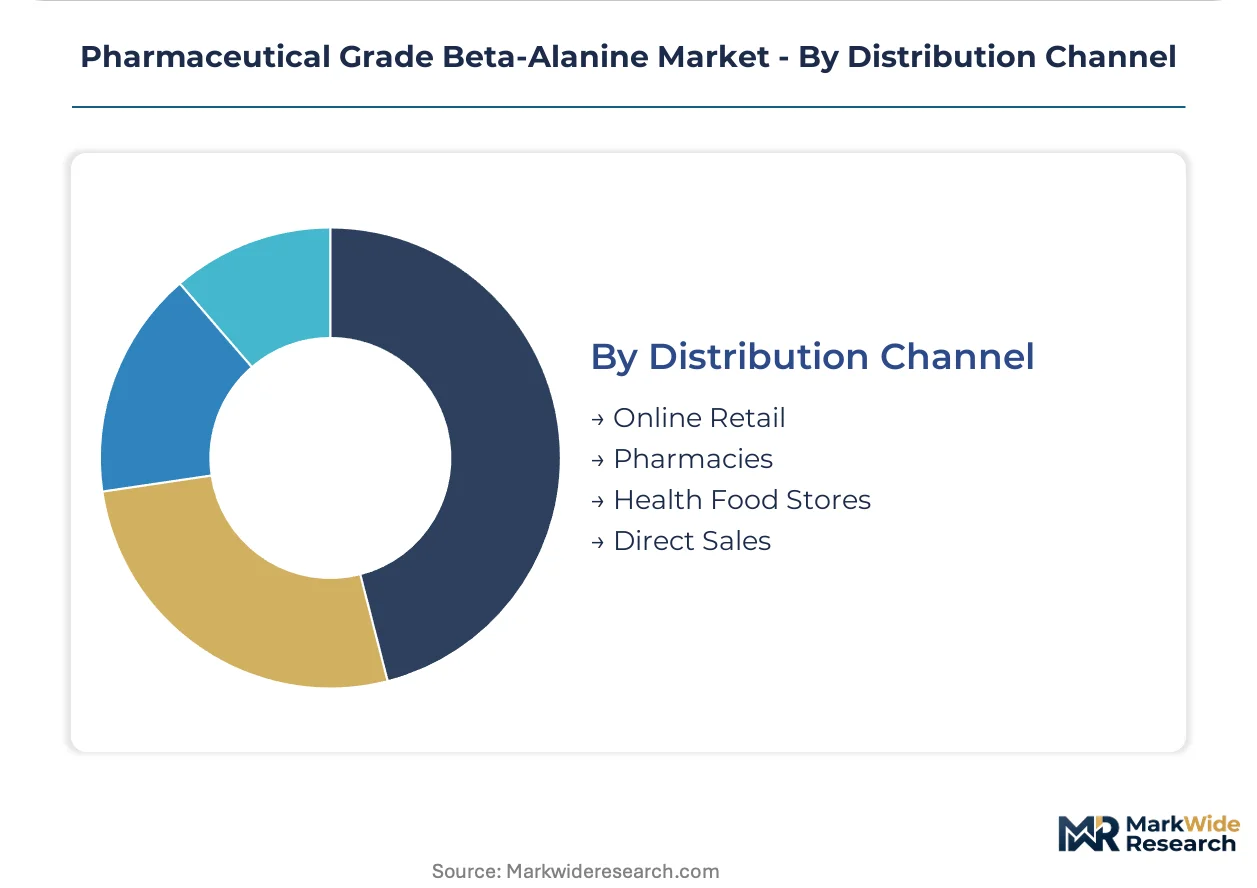
- Direct Sales:Manufacturer-to-formulator contracts displace distributor intermediaries as integrated delivery networks consolidate amino acid purchasing. Catholic Health Initiatives and CommonSpirit Health networks in the United States command multi-year supply agreements with cGMP-certified producers.
- Online Retail:Subscription wellness channels capture 40-60% per-gram premiums through unit-dose convenience and direct-to-consumer marketing efficiency.
- Pharmacies:Retail pharmacy distribution requires extended stability data and child-resistant packaging compliance for over-the-counter positioning.
- Health Food Stores:Specialty retail channels emphasize clean-label credentials and third-party certification for differentiation in crowded supplement aisles.
Direct Sales controls the institutional base. Online Retail is expanding most quickly as subscription models reshape consumer purchasing patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consortiums and cGMP-certified manufacturing clusters concentrate demand across Germany, China, and the United States. Sports nutrition formulators and pharmaceutical compounders drive divergent sourcing patterns by purity tier. Regulatory harmonization efforts between FDA, EMA, and NMPA reshape multi-regional qualification strategies.
United States
Integrated delivery networks consolidate amino acid purchasing through group purchasing organizations, displacing traditional distributor intermediaries. FDA enforces pharmaceutical-grade standards through 21 CFR 211 cGMP regulations and USP-NF monograph compliance. Catholic Health Initiatives and CommonSpirit Health networks in the Southeast and Midwest command multi-year supply agreements with certified manufacturers.
Germany
Contract manufacturers retrofit legacy antibiotic fermentation lines for amino acid production to serve hospital and clinical trial demand. EMA's ICH Q3D elemental impurity guidelines mandate risk assessments for cobalt and nickel catalyst residues in enzymatic resolution processes. Industrial-scale facilities in North Rhine-Westphalia and Bavaria supply parenteral nutrition compounders across Benelux and French markets.
China
Industrial-scale bioreactor capacity clusters in Anhui and Shandong provinces serve domestic nutraceutical formulators and export markets. NMPA implements GB standards for pharmaceutical amino acids requiring foreign producers to complete on-site inspections and registration dossiers. Precision fermentation platforms achieve titers above 120 g/L, compressing unit economics below traditional chemical synthesis routes.
Switzerland
Swissmedic compliance requirements attract high-purity oral and parenteral applications from European hospital networks. Contract manufacturers leverage pharmaceutical-grade cGMP infrastructure originally developed for biologics production. Basel and Zurich clusters specialize in clinical trial material supply with batch documentation rigor for investigational new drug applications.
India
Production Linked Incentive schemes under the national pharmaceutical manufacturing program attract cGMP facility investment for amino acid production. CDSCO registration pathways align with ICH guidelines to enable export qualification for regulated markets. Maharashtra and Gujarat pharmaceutical corridors develop fermentation capacity to reduce import dependence for sports nutrition and hospital-grade applications.
Pharmaceutical Grade Beta-Alanine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered purity grades and end-use applications. The market structures around cGMP certification thresholds that bifurcate supply between hospital-grade and nutraceutical-grade producers. Three archetypes dominate: vertically integrated fermentation specialists, contract manufacturers with legacy antibiotic line conversions, and pharmaceutical-grade purity specialists serving parenteral applications. Competitive moves concentrate on strategic partnerships with hospital procurement consortiums and technology licensing for continuous bioprocessing platforms.
Among United States-based integrated manufacturers, Natural Alternatives International, Inc. represents the vertically controlled archetype with in-house fermentation through finished powder capabilities. Anhui Huaheng Biotechnology Co., Ltd. anchors Chinese supply through industrial-scale bioreactor capacity. Evonik Industries AG occupies a position exemplifying pharmaceutical-grade cGMP compliance for parenteral and high-purity oral applications.
| Leading Market Players |
|---|
| Natural Alternatives International, Inc. |
| Anhui Huaheng Biotechnology Co., Ltd. |
| NOW Foods Inc. |
| Prinova Group LLC. |
| Spectrum Chemical |
| Wuxi Jinghai Amino Acid Co., Ltd. |
| Xinfa Pharmaceuticals Co., Ltd. |
| Merck KGaA |
| Evonik Industries AG |
| Others |
Pricing and Supply Chain Analysis
Anhui and Shandong provinces anchor global fermentation capacity, with industrial-scale bioreactor clusters translating raw glucose throughput into downstream pricing leverage for pharmaceutical-grade output. Corn-derived feedstock volatility in the US Midwest feeds directly into contract renegotiation cycles, squeezing margin buffers for spot-market buyers while cGMP-certified facilities command fixed-price multi-year offtake premiums.
Pricing Analysis
Cost-plus contracts with corn futures indexation dominate long-term supply agreements between Chinese fermentation houses and European formulators. Three-tier pricing structure across parenteral-grade, oral-grade, and nutraceutical-grade levels separates hospital procurement from sports nutrition blending. Pricing pressure stems from enzymatic resolution yield plateaus constraining high-purity expansion. Hospital pharmacy directors show least price sensitivity due to patient-safety procurement mandates, while direct-to-consumer subscription brands face acute margin compression.
Supply Chain Analysis
Export-control regimes on recombinant strain biotechnology limit technology transfer from German and Swiss contract manufacturers to emerging production regions. Supply concentrates in China, Germany, and the United States, with Anhui Huaheng and Evonik Industries anchoring respective hemispheres. Raw material dependencies rest on corn-derived glucose, pharmaceutical-grade crystallization solvents, and cobalt catalyst systems for chiral resolution. Single-source vulnerability runs through Anhui-Shandong fermentation corridors. Distribution runs through direct manufacturer-to-formulator contracts displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation platforms are shifting pharmaceutical-grade amino acid production toward ecosystem economics where strain engineering capabilities and cGMP certification interoperability determine competitive positioning. Hospital procurement consortiums and integrated delivery networks now function as platform gatekeepers consolidating supplier access.
For Market Incumbents: Entrench cGMP certification barriers by retrofitting legacy antibiotic fermentation lines for beta-alanine production in North Rhine-Westphalia and Bavaria clusters. Backward integration into captive glucose supply from Midwest agricultural processors defends margin position against feedstock volatility. Deepen relationships with Catholic Health Initiatives and CommonSpirit Health networks through multi-year direct contracts that displace spot-market competitors.
For New Entrants and Emerging Players: Establish a beachhead in anti-aging cosmeceutical formulations where cellular buffering claims command dermatology channel premiums beyond saturated sports nutrition. Target direct-to-consumer capsule subscription models capturing per-gram premiums through unit-dose convenience. Pursue technology licensing from continuous bioprocessing specialists to bypass 8-14 month fermentation scale-up talent scarcity.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated fermentation specialists with in-house strain engineering and finished powder capabilities. Long-term viability hinges on pharmacopeial harmonization between USP, EP, and ChP standards reducing redundant validation costs. Watch for CDSCO registration pathway alignment under India's PLI scheme as inflection signal for geographic supply diversification.
| Strategic Initiative | Industry Significance |
|---|---|
| cGMP Certification Investment | EMA ICH Q3D compliance qualifies output for parenteral nutrition compounding pharmacies. |
| Continuous Bioprocessing Adoption | Single-use bioreactor technologies collapse batch cycle times below traditional fed-batch methods. |
| Direct Hospital Contracting | Group purchasing organization consolidation displaces distributor intermediaries in Southeast and Midwest IDNs. |
| Strain Engineering Partnership | Recombinant microbial titers above 120 g/L compress unit economics below chemical synthesis routes. |
| Anti-Aging Formulation Development | Cellular buffering claims open dermatology channel penetration beyond commoditized sports nutrition. |
Research Methodology
A standing panel of fermentation process engineers, hospital pharmacy procurement directors, regulatory affairs specialists at amino acid manufacturers, and sports nutrition formulators provided ongoing calibration across the research period. Primary interviews combined with secondary validation from USP-NF monograph databases, EMA ICH Q3D guidance documents, FDA 21 CFR 211 cGMP regulations, and NMPA GB standards registration filings. Bottom-up capacity assessments at Anhui, Shandong, North Rhine-Westphalia, and Bavaria production facilities triangulated against top-down demand modeling from hospital procurement consortiums and nutraceutical formulators.
Scenario-bracketing around feedstock volatility, pharmacopeial harmonization timelines, and cGMP certification adoption rates bounded the forecast range across the projection horizon. Segmentation dimensions modeled include physical form, end-user type, application focus, and distribution channel structure, with purity grade tier and regional regulatory cluster as cross-cutting variables. CAGRs derived from iterative convergence between capacity expansion announcements and procurement contract visibility. Industry-specific inputs encompassed corn futures price trajectories and enzymatic resolution yield curves.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, freight rates, or currency exchange corridors would shift the trajectory. Forecasts reflect documented assumptions regarding fermentation titer improvements and regulatory harmonization progress. Material shifts in USP-EP-ChP standard divergence or novel export-control restrictions on biotechnology would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Asia-Pacific Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Lipids Active Pharmaceutical Ingredient Market
Pharmaceutical Ingredients
Pharmaceutical Indicator Strips Market
Pharmaceutical Ingredients
Pharmaceutical Lactose Market
Pharmaceutical Ingredients
Folinic Acid Market
Pharmaceutical Ingredients
India Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
United States Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Anti-Allergic Agent Ingredients Market
Pharmaceutical Ingredients
Calcium Gluconate Market
Pharmaceutical Ingredients
Diclofenac Sodium API Market
Pharmaceutical Ingredients
France Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Zinc Bacitracin Market
Pharmaceutical Ingredients
China Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Antibiotics Active Pharmaceutical Ingredient (API) Market
Pharmaceutical Ingredients
Alpha Lipoic Acid API Market
Pharmaceutical Ingredients
Fosfomycin Trometamol Powder Market