
 Global Tacrolimus Market | 2026-2036
Global Tacrolimus Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tacrolimus Market Foresight
Tacrolimus pricing and clinical positioning is decoupling sharply between originator formulations and commoditized generics. Astellas Pharma anchors the premium segment through its proprietary extended-release technology and transplant center relationships. Dr. Reddy's Laboratories competes aggressively in the oral capsule space, leveraging cost-optimized manufacturing to capture volume in emerging markets.
Tacrolimus is a macrolide calcineurin inhibitor produced via fermentation-derived biosynthesis, with a molecular formula of C44H69NO12 and potent T-cell suppression used primarily to prevent allograft rejection in organ transplantation. The therapy area dimension shows organ transplantation commanding the largest revenue pool while autoimmune disorders represent the fastest-expanding indication as rheumatologists adopt off-label protocols. Capsules sustain dominant volume share, though extended release tablets concentrate margin pools through improved adherence profiles and patent-protected dosing regimens.
The FDA's bioequivalence standards for narrow therapeutic index drugs and EMA's MDR requirements for immunosuppressive biologics jointly elevate manufacturing compliance costs and filter subscale producers from supply chains. China's NMPA has tightened impurity profiling rules for tacrolimus APIs, redirecting procurement toward certified manufacturers. Stakeholders must monitor evolving pharmacogenomic testing adoption and its potential to reshape dosing protocols and formulation preferences.
Market Dynamics
Extended-release formulation patents and narrow therapeutic index bioequivalence standards are concentrating manufacturing capability among fermentation specialists with validated impurity profiling systems.
Growth Catalysts
- Solid organ transplant expansion:Academic medical centers in the United States, China, and India are scaling transplant infrastructure, driving volume uptake of immunosuppressive protocols.
- EMA MDR compliance:Stricter immunosuppressive biologics requirements are filtering subscale API producers from European supply chains, consolidating procurement toward certified manufacturers.
- Pharmacogenomic testing adoption:CYP3A5 genotype screening is enabling personalized tacrolimus dosing, expanding precision medicine protocols in rheumatology and nephrology practices.
Market Restraints
- Fermentation input volatility:Streptomyces tsukubaensis culture media costs fluctuate with agricultural commodity prices, compressing margins for biosynthetic API producers.
- Chinese API supply concentration:NMPA-certified tacrolimus active pharmaceutical ingredient manufacturing clusters in Zhejiang and Jiangsu provinces create geographic single-point vulnerability.
- Narrow therapeutic index constraints:FDA bioequivalence standards for immunosuppressants require costly clinical endpoint studies, blocking rapid generic substitution.
Strategic Opportunities
- Autoimmune disorder protocols:Off-label lupus nephritis and rheumatoid arthritis applications represent the fastest-expanding indication as specialty physicians adopt calcineurin inhibitor regimens.
- Indian transplant infrastructure:Government-funded organ donation networks and specialty hospital construction in Tamil Nadu and Maharashtra are creating new prescription volume pools.
- Continuous manufacturing adoption:FDA's emerging technology program is unifying process analytical technology with real-time release testing for extended-release tablet production.
Industry Challenges
- Specialized fermentation workforce scarcity:Industrial microbiologists with Streptomyces scale-up expertise command premium compensation, constraining capacity expansion timelines.
- Legacy quality system integration:API producers acquiring continuous manufacturing equipment face validation complexity bridging batch record systems with process analytical technology platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tacrolimus Market |
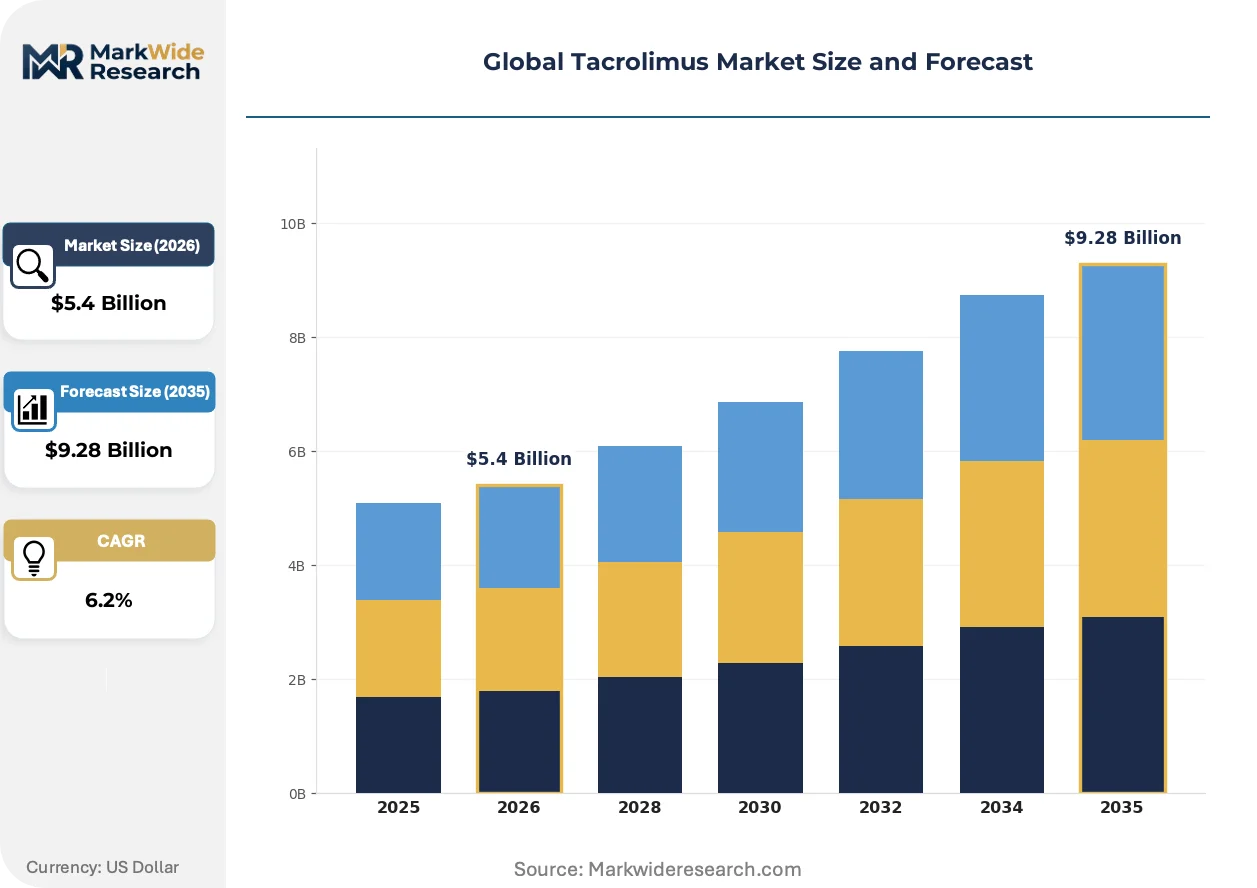
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Oral Suspension, Injectable Solution, Extended Release Tablets Therapy Area: Organ Transplantation, Autoimmune Disorders, Dermatological Conditions, Nephrotic Syndrome End User: Hospitals, Specialty Clinics, Ambulatory Surgery Centers, Research Institutes Delivery Mode: Oral, Intravenous, Subcutaneous, Topical Applications |
| Companies Covered | Astellas Pharma Inc., Pfizer Inc., Novartis AG, Dr. Reddy's Laboratories Ltd., Lupin Limited, Sandoz Inc., Viatris Inc., Sun Pharmaceutical Industries Ltd., Glenmark Pharmaceuticals Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tacrolimus Market Shifts & Advancements
Formulation science and regulatory science are converging to reshape competitive advantage around bioequivalence demonstration capabilities rather than molecule exclusivity alone.
Amorphous solid dispersion technology is unifying tacrolimus solubility enhancement with extended-release kinetics in single-unit dosage forms. Transplant centers in Germany and the United States are adopting these formulations to improve patient adherence through reduced dosing frequency. The technology is compressing generic substitution timelines by creating additional bioequivalence study requirements that favor established players with clinical trial infrastructure.
REACH Annex XIV authorization requirements for residual solvents in immunosuppressive APIs are tightening analytical method specifications across European manufacturing sites. ECHA's classification of specific fermentation byproducts as substances of very high concern is forcing reformulation of downstream purification protocols. Oral solid dosage producers serving EU markets are responding by qualifying alternative solvent systems and submitting updated regulatory dossiers.
Specialty pharmacy distribution is displacing traditional wholesale channels for high-value immunosuppressant prescriptions. Payer-mandated specialty pharmacy networks in the United States are capturing patient adherence monitoring and refill coordination functions previously managed by hospital discharge pharmacies. This channel consolidation is most visible in Medicare and commercial transplant benefit management programs where outcomes data reporting requirements favor integrated pharmacy providers.
Global Tacrolimus Market Segmentation
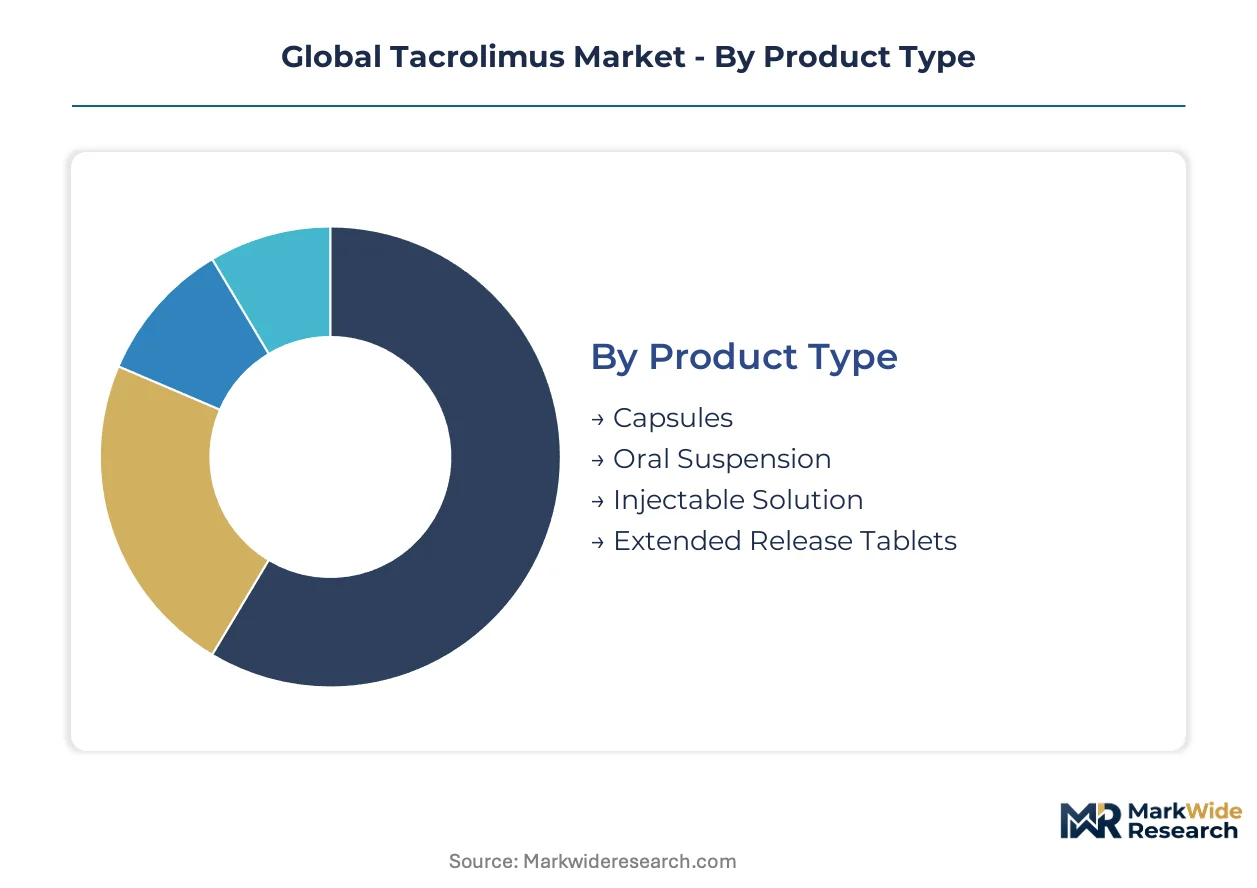
Tacrolimus market segmentation reflects the tension between commoditized oral generics and value-added formulation technologies. Product differentiation increasingly centers on bioequivalence demonstration capabilities and adherence-optimized dosing regimens rather than molecular exclusivity.
Product Type:
Extended-release kinetics and solubility enhancement technologies are concentrating competitive advantage among fermentation specialists with validated impurity profiling systems.
- Capsules:Immediate-release gelatin shells containing tacrolimus API with standard dissolution profiles dominate prescription volumes across solid organ transplant protocols. Demand concentrates in India and the United States where cost-optimized manufacturing from Dr. Reddy's Laboratories and domestic generic houses captures volume in government-funded transplant programs.
- Extended Release Tablets:Proprietary matrix-forming polymers enable once-daily dosing with improved Cmin trough stability and reduced peak-trough fluctuations. Astellas Pharma's Advagraf and Envarsus XR formulations command premium positioning through patent-protected coating technologies and transplant center loyalty programs.
- Oral Suspension:Liquid formulation with particle size-controlled API for pediatric dosing and patients with dysphagia.
- Injectable Solution:Intravenous concentrate for perioperative immunosuppression in hospitalized transplant recipients.
Capsules lead on scale; Extended Release Tablets lead on momentum.
Therapy Area:
Clinical positioning diverges sharply between established transplant protocols and emerging off-label applications in specialty rheumatology and nephrology practices.
- Organ Transplantation:Prophylaxis against allograft rejection in kidney, liver, heart, and lung transplantation with trough-level therapeutic drug monitoring. Academic medical centers in the United States, China, and Germany anchor volume through standardized calcineurin inhibitor protocols.
- Autoimmune Disorders:Off-label lupus nephritis, rheumatoid arthritis, and inflammatory bowel disease applications with CYP3A5 genotype-guided dosing. Rheumatology practices in the United States and Japan are expanding prescriptions fastest as pharmacogenomic testing adoption enables personalized protocols.
- Dermatological Conditions:Topical and systemic regimens for atopic dermatitis and psoriasis unresponsive to first-line therapies.
- Nephrotic Syndrome:Steroid-sparing maintenance therapy for steroid-dependent minimal change disease and focal segmental glomerulosclerosis.
Organ Transplantation leads on scale; Autoimmune Disorders expand most quickly.
End User:
Channel consolidation toward specialty pharmacy networks is restructuring procurement relationships and adherence monitoring responsibilities.
- Hospitals:Inpatient transplant units and discharge pharmacies managing perioperative immunosuppression induction and initial maintenance dosing. Major academic medical centers in Tamil Nadu, Maharashtra, and Texas concentrate surgical volume and protocol-driven prescription authority.
- Specialty Clinics:Transplant nephrology and hepatology outpatient practices with dedicated pharmacist-led therapeutic drug monitoring programs.
- Ambulatory Surgery Centers:Limited penetration due to narrow therapeutic index monitoring requirements and need for laboratory infrastructure.
- Research Institutes:Clinical trial sites investigating novel combination immunosuppressive regimens and pharmacogenomic stratification protocols.
Hospitals lead on scale; Specialty Clinics lead on margin capture.
Delivery Mode:
Route selection balances bioavailability optimization against patient adherence and healthcare setting constraints.
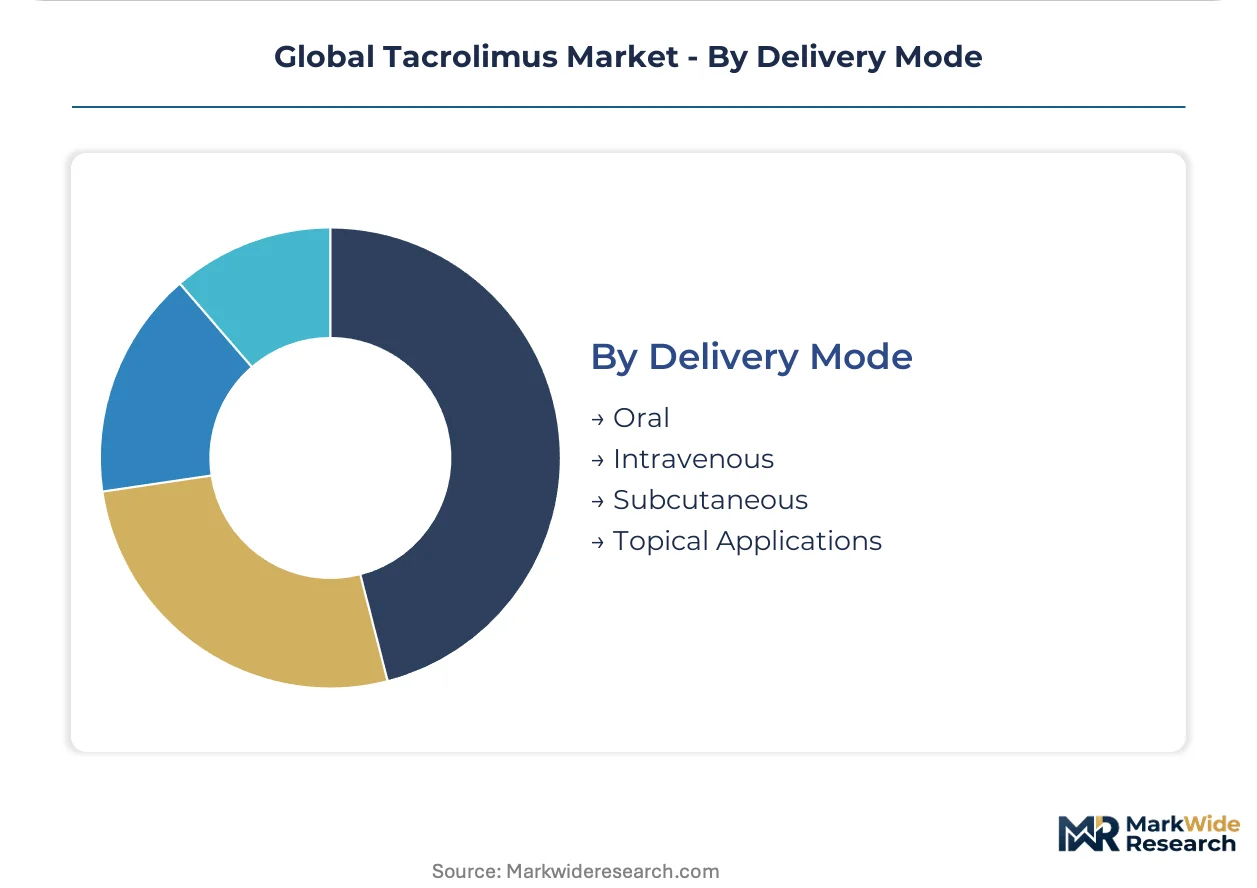
- Oral:First-line maintenance immunosuppression with established bioequivalence pathways and broad generic availability.
- Intravenous:Perioperative and critical care administration when oral intake is contraindicated.
- Subcutaneous:Emerging delivery route for select extended-release formulations in development.
- Topical Applications:Localized immunosuppression for dermatological conditions with minimal systemic exposure.
Oral leads on scale; Topical Applications gain share fastest in dermatology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation specialists with Streptomyces scale-up expertise cluster in industrial microbiology hubs across Germany, the United States, India, China, and Japan. These talent concentrations anchor tacrolimus API production and finished dosage manufacturing.
United States
Academic medical centers in Texas and the Northeast Corridor drive transplant protocol standardization and immunosuppressant procurement volume. FDA bioequivalence standards for narrow therapeutic index drugs elevate clinical endpoint study requirements for generic entrants. Philadelphia and Boston host specialty pharmacy networks that capture patient adherence monitoring and refill coordination from hospital discharge pharmacies.
Germany
Transplant centers in Berlin and Munich adopt amorphous solid dispersion formulations to improve patient adherence through reduced dosing frequency. EMA MDR compliance requirements for immunosuppressive biologics filter subscale API producers from European supply chains. The Rhine-Ruhr industrial corridor concentrates analytical method development for REACH Annex XIV residual solvent compliance.
India
Government-funded organ donation networks in Tamil Nadu and Maharashtra create new prescription volume pools as transplant infrastructure expands. CDSCO alignment with FDA bioequivalence standards shapes generic approval pathways for immunosuppressants. Hyderabad and Ahmedabad house cost-optimized manufacturing operations that capture volume in government-funded transplant programs across emerging markets.
China
NMPA-certified tacrolimus API manufacturing clusters in Zhejiang and Jiangsu provinces concentrate biosynthetic production capacity. Tightened impurity profiling rules redirect procurement toward certified manufacturers with validated quality systems. Shanghai and Beijing academic medical centers scale transplant infrastructure and drive volume uptake of calcineurin inhibitor protocols.
Japan
Rheumatology practices in Tokyo and Osaka expand off-label prescriptions fastest as pharmacogenomic testing adoption enables personalized tacrolimus dosing. PMDA guidance on immunosuppressive drug development shapes formulation standards for extended-release technologies. The Kansai region hosts specialty clinics with dedicated pharmacist-led therapeutic drug monitoring programs.
Global Tacrolimus Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the tacrolimus value chain. Fermentation-based API manufacturing demands substantial fixed investment in bioreactor infrastructure and industrial microbiology workforce, while finished dosage specialists deploy formulation science and regulatory dossier capabilities without captive biosynthetic capacity. The market structures around three archetypes: originator firms with patent-protected extended-release technologies, mid-scale generic houses with FDA-approved narrow therapeutic index portfolios, and emerging market producers with cost-optimized fermentation operations. Dominant competitive moves include strategic partnerships between API manufacturers and specialty pharmacy distributors, plus geographic expansion into Indian and Chinese transplant infrastructure buildouts.
Among originator-tier multinationals, Astellas Pharma Inc. occupies a position exemplifying premium formulation technology and transplant center relationship depth. Within the high-volume generic segment, Dr. Reddy's Laboratories Ltd. and Lupin Limited represent archetypes of cost-optimized manufacturing and emerging market penetration. Sun Pharmaceutical Industries Ltd. anchors a position bridging API fermentation capability with finished dosage scale. These named entities illustrate competitive positioning rather than exhaust market participation.
| Leading Market Players |
|---|
| Astellas Pharma Inc. |
| Pfizer Inc. |
| Novartis AG |
| Dr. Reddy's Laboratories Ltd. |
| Lupin Limited |
| Sandoz Inc. |
| Viatris Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Glenmark Pharmaceuticals Ltd. |
| Others |
Supply & Pricing Matrix
Continuous manufacturing adoption at FDA-registered sites is compressing unit production costs while simultaneously concentrating supply among fermentation specialists with validated PAT infrastructure. This technology transition rewards capital-intensive players capable of bridging legacy batch records with real-time release testing platforms, filtering subscale API producers from procurement shortlists.
Pricing Analysis
Pharmacy service bundling separates originator formulations with adherence monitoring from unbundled generic capsules competing on acquisition cost alone. Three-tier pricing structure across premium extended-release, standard immediate-release, and economy oral generics reflects FDA bioequivalence study investment levels and transplant center loyalty contract depth. Cost compression in the generic capsule tier intensifies as Dr. Reddy's Laboratories and domestic Indian houses expand fermentation capacity. Government-funded transplant programs in emerging markets exhibit highest price sensitivity; academic medical centers with outcomes-based contracts show lowest.
Supply Chain Analysis
NMPA certification requirements for tacrolimus API producers in Zhejiang and Jiangsu provinces are gating European and North American procurement toward validated manufacturers with REACH Annex XIV compliance documentation. Streptomyces tsukubaensis culture media, amorphous solid dispersion polymers, and gelatin capsule shells feed from agricultural commodity markets and specialty chemical suppliers respectively. Single-source vulnerability concentrates in Chinese fermentation clusters exposed to environmental regulatory enforcement actions. Distribution runs through specialty pharmacy networks displacing traditional wholesale channels for high-value immunosuppressant prescriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tacrolimus market compounds steadily as solid organ transplant infrastructure expansion in India, China, and the United States drives protocol-driven volume growth with limited substitution risk.
For Market Incumbents: Lock in transplant center relationships through integrated therapeutic drug monitoring programs and pharmacist-led adherence services that generic houses cannot replicate. Deepen backward integration into Streptomyces fermentation capacity to secure API supply against NMPA regulatory enforcement actions in Chinese manufacturing clusters. Prioritize continuous manufacturing validation to capture FDA emerging technology program benefits and extend bioequivalence demonstration advantages over mid-scale generic entrants. For New Entrants and Emerging Players: CDSCO alignment with FDA bioequivalence standards in India opens a window for cost-optimized capsule producers to capture volume in Tamil Nadu and Maharashtra government-funded transplant programs. Target the autoimmune disorder off-label segment where CYP3A5 genotype-guided dosing protocols are expanding fastest in United States rheumatology practices. Pursue specialty pharmacy distribution partnerships rather than hospital discharge pharmacy channels to secure patient adherence monitoring revenue streams. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale fermentation specialists with validated impurity profiling systems because EMA MDR compliance and FDA narrow therapeutic index standards are filtering subscale producers from supply chains. Five-to-ten year viability hinges on captive API production and extended-release formulation capabilities rather than pure finished dosage scale. Watch pharmacogenomic testing adoption rates in nephrology and rheumatology practices as the inflection indicator for autoimmune disorder protocol expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Scale-Up | FDA emerging technology program qualification unifies PAT with real-time release testing for extended-release tablets. |
| Pharmacogenomic Testing Partnership | CYP3A5 genotype screening integration enables personalized dosing protocols in rheumatology and nephrology practices. |
| Specialty Pharmacy Network Expansion | Medicare and commercial transplant benefit management programs favor integrated adherence monitoring providers. |
| REACH Annex XIV Compliance Investment | ECHA classification of fermentation byproducts forces solvent system reformulation for European market access. |
| Indian Transplant Infrastructure Alignment | Government-funded organ donation networks in Tamil Nadu and Maharashtra create new prescription volume pools. |
Research Methodology
Multiple input streams — primary interviews with transplant surgeons, formulary directors, and industrial microbiologists; secondary validation through FDA ANDA filings, EMA EPAR assessments, and ClinicalTrials.gov records; plus customs data on tacrolimus API trade flows — were reconciled through bottom-up prescription volume modeling and top-down market sizing across the analysis window.
Data-stream reconciliation anchored the analytical framework across product type, therapy area, end user, and delivery mode segmentation dimensions throughout the forecast period. CAGRs were derived from trend extrapolation of transplant program expansion rates, pharmacogenomic testing penetration curves, and generic substitution timelines. Industry-specific inputs included CYP3A5 genotype prevalence data and narrow therapeutic index bioequivalence study success rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA regulatory enforcement actions in Chinese API manufacturing clusters or abrupt shifts in Medicare specialty pharmacy network reimbursement policies. Deviation in fermentation input commodity prices or REACH Annex XIV substance of very high concern reclassifications would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Quinoline Market
Pharmaceutical Ingredients
Small-Molecule Injectable Drugs Market
Pharmaceutical Ingredients
Oridonin Market
Pharmaceutical Ingredients
MEK Inhibitors Market
Pharmaceutical Ingredients
Cyprosin Market
Pharmaceutical Ingredients
Histamine H2-Receptor Antagonists Market
Pharmaceutical Ingredients
Global Cephalosporin Drugs Market
Pharmaceutical Ingredients
Germany Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Mrna Synthesis Raw Materials Market
Pharmaceutical Ingredients
Asia-Pacific Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Global Chlorpheniramine Maleate Market
Pharmaceutical Ingredients
Citicoline Market
Pharmaceutical Ingredients
Calcium Citrate Market
Pharmaceutical Ingredients
Anti-Allergic Agent Ingredients Market
Pharmaceutical Ingredients
Montelukast API Market
Pharmaceutical Ingredients
Global Pharmaceutical Grade Sodium Chloride Market