
 Hot Cocoa Mix Market | 2026-2036
Hot Cocoa Mix Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Cocoa Mix Market Analytics
Subscription-based replenishment models is repositioning how households purchase hot cocoa mix, shifting volume from impulse retail to predictable direct-to-consumer channels. Nestlé leverages its global logistics network to sustain recurring delivery programs across North American and European markets. Lindt & Sprüngli anchors premium positioning through limited-edition seasonal subscriptions that command higher per-unit margins. The Hershey Company competes on price-accessible auto-ship formats targeting family pantries.
Hot cocoa mix comprises processed cocoa powder combined with sweeteners, dairy or non-dairy creamers, and stabilizers, typically reconstituted with hot water or milk to produce a chocolate beverage with minimum 10% cocoa content by weight. The formulation serves both retail consumers seeking convenience and foodservice operators requiring consistent batch preparation. Instant powder dominates volume due to extended shelf stability and lower shipping costs, while organic mix captures expanding margin pools as certification premiums justify price escalation. Single-serve packets lead in on-the-go and hospitality channels, whereas bulk bags concentrate in institutional foodservice procurement.
FDA nutritional labeling mandates and WHO sugar reduction guidance are forcing reformulations across conventional product lines, elevating R&D costs but opening compliant product categories. EFSA and national regulators within Europe enforce strict cocoa origin traceability under deforestation-free supply chain regulations, reshaping sourcing requirements for market access. Stakeholders must monitor evolving clean-label certification standards and decide whether to absorb compliance costs or pass them through premium positioning.
Market Dynamics
Clean-label reformulation pressure from FDA nutritional labeling mandates and WHO dietary guidelines is compressing formulation margins while opening certified organic and reduced-sugar product lines. This regulatory pivot forces simultaneous R&D investment and supply chain reconfiguration across conventional and premium segments.
Growth Catalysts
- Subscription replenishment models:Direct-to-consumer auto-ship programs lock in recurring revenue streams and reduce customer acquisition costs for established brands.
- Deforestation-free sourcing mandates:EFSA traceability requirements under EU supply chain regulations create competitive moats for early-compliant producers accessing European retail channels.
- Plant-based creamer integration:Oat and coconut milk powder formulations expand addressable markets among lactose-intolerant and vegan consumer segments.
Market Restraints
- Cocoa bean price volatility:Weather-driven supply disruptions in West African growing regions transmit directly to input cost instability for powder processors.
- Sugar reduction technical limits:Reformulation thresholds for palatability constrain how far clean-label products can compress carbohydrate content without taste degradation.
- Single-origin certification bottlenecks:Limited third-party audit capacity for deforestation-free verification creates queue delays for market access documentation.
Strategic Opportunities
- Functional ingredient fortification:Adaptogen and probiotic infusions create premium positioning in wellness-oriented millennial and Gen-Z households.
- Bulk foodservice contract penetration:Institutional procurement channels in education and healthcare facilities remain underdeveloped relative to retail saturation.
- Japanese convenience store channels:Vending-compatible single-serve formats align with established hot beverage infrastructure in high-foot-traffic urban locations.
Industry Challenges
- Clean-label R&D talent scarcity:Formulation chemists with dual expertise in sensory science and regulatory compliance command premium compensation and extended hiring timelines.
- Legacy equipment retrofit costs:Dedicated processing lines for allergen-free and organic SKUs require capital outlays that strain mid-tier manufacturer balance sheets.
- Multi-jurisdiction certification synchronization:USDA Organic, EU Organic, and JAS standards maintain divergent input restrictions that complicate unified global product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Cocoa Mix Market |
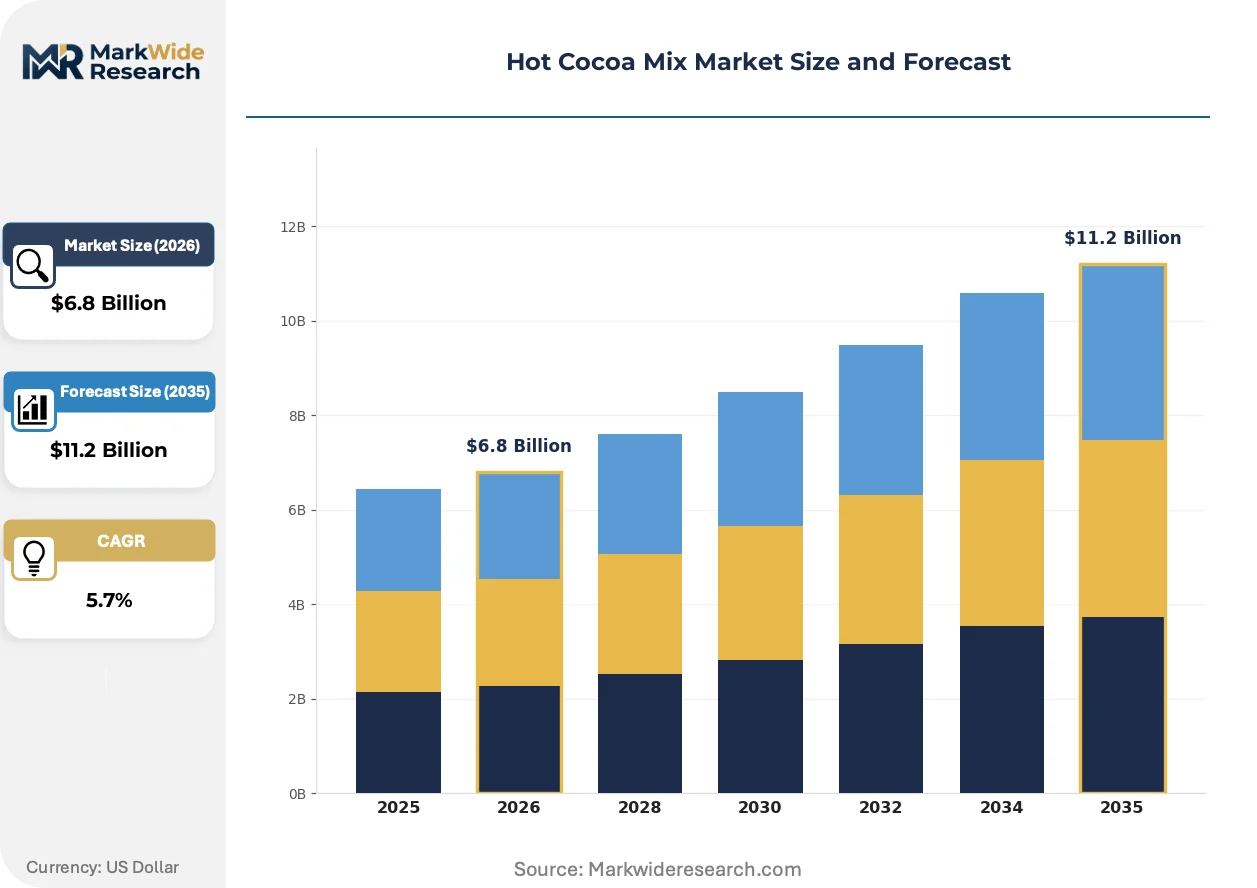
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Instant Powder, Ready-to-Drink, Organic Mix, Sugar-Free Mix Flavor Profile: Classic Chocolate, Mint Chocolate, Mocha, Spiced Packaging Type: Single-Serve Packets, Bulk Bags, Jars, Tubs Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Convenience Stores |
| Companies Covered | Unilever, Lindt & Sprüngli, Nestlé, Godiva, Ghirardelli Chocolate Company, The Hershey Company, Mondelez International, Conagra Brands, Starbucks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Cocoa Mix Market Evolving Landscape
Formulation science and distribution infrastructure are undergoing parallel transformation as at-home consumption patterns stabilize post-pandemic. Three intersecting developments are compressing legacy operating models while opening margin pools for agile participants.
Precision fermentation-derived cocoa compounds are decentralizing supply chain risk for chocolate flavor replication. Biotech startups and ingredient suppliers are deploying cellular agriculture to produce cocoa butter equivalents and flavor molecules independent of agricultural harvest cycles. Food manufacturers facing origin traceability mandates are piloting these inputs to insulate formulations from commodity price spikes and deforestation compliance exposure.
FDA added-sugar disclosure rules and front-of-pack labeling schemes are forcing portfolio-wide reformulation timelines. Manufacturers must rebase entire product architectures around reduced-sugar thresholds while maintaining taste parity through bulking agents and natural high-intensity sweeteners. Premium private-label suppliers serving US retail channels are absorbing the steepest compliance costs as they lack the volume scale to amortize R&D across massive unit bases.
Pantry-loading behavior has given way to just-in-time replenishment through direct subscription interfaces. Households that built buffer stocks during supply uncertainty now favor predictable auto-ship cadences over retail impulse purchases. This pattern concentrates most visibly in German and US suburban markets where delivery density supports cost-efficient last-mile logistics and where pantry consolidation trends reduce brand-switching frequency.
Hot Cocoa Mix Market Segmentation
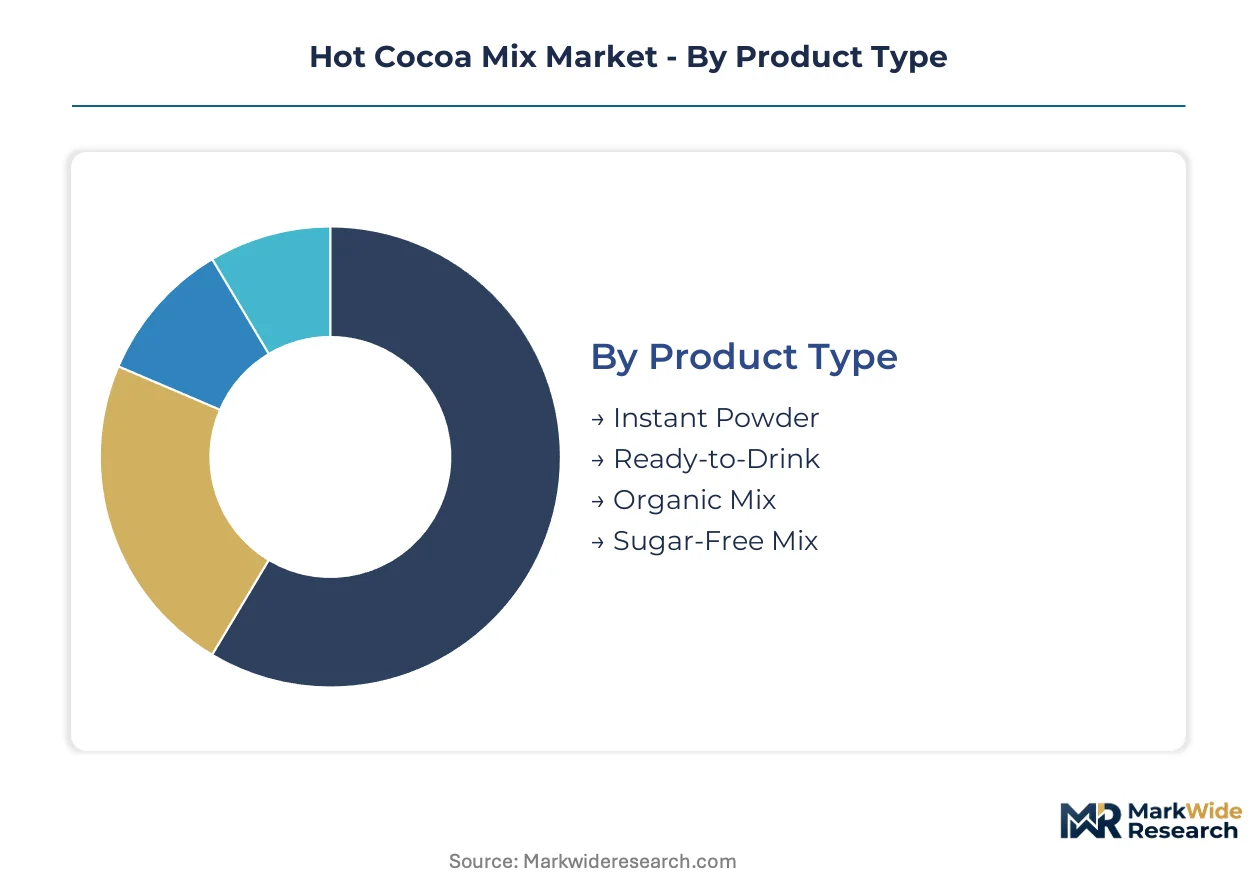
Hot cocoa mix segmentation reveals divergent margin structures across convenience-oriented and premium-positioned formats. Product architecture, packaging economics, and channel access collectively determine which households and foodservice operators each configuration can profitably serve.
Product Type:
Buyers in this category separate along price tolerance and preparation time constraints rather than taste preference alone.
- Instant Powder:Dehydrated cocoa solids combined with sweeteners and dairy or non-dairy creamers requiring hot water reconstitution. Volume concentrates in US and German suburban households subscribing to auto-replenishment programs, constrained by sugar reduction technical limits that threaten palatability thresholds.
- Organic Mix:Certified cocoa powder meeting USDA Organic, EU Organic, or JAS standards with restricted pesticide and synthetic fertilizer inputs. Demand clusters in millennial and Gen-Z households seeking clean-label credentials, driven by FDA nutritional labeling mandates that elevate compliant product premiums.
- Ready-to-Drink:Pre-mixed liquid formulations in shelf-stable or refrigerated formats.
- Sugar-Free Mix:Reformulated powders utilizing high-intensity sweeteners and bulking agents to achieve reduced carbohydrate content.
Volume sits with Instant Powder; growth tilts toward Organic Mix.
Flavor Profile:
Flavor selection maps to seasonal purchasing patterns and cross-category beverage substitution behavior.
- Classic Chocolate:Standard cocoa powder formulations with 10-15% cocoa content by weight representing the baseline taste expectation. US family pantries and German retail channels sustain the highest per-capita consumption rates, pressured by cocoa bean price volatility from West African supply disruptions.
- Mocha:Coffee-cocoa hybrid formulations targeting morning beverage occasions and coffeehouse substitution. Japanese convenience store channels and US millennial households drive adoption, supported by vending-compatible single-serve infrastructure in high-foot-traffic urban locations.
- Mint Chocolate:Peppermint or spearmint oil-infused variants associated with winter seasonal purchasing.
- Spiced:Cinnamon, chili, or cardamom-enhanced formulations appealing to ethnic cuisine crossover and warming sensory positioning.
Classic Chocolate dominates absolute volume; Mocha gains share fastest among flavor variants.
Packaging Type:
Packaging economics separate individual convenience from household pantry efficiency and institutional procurement scale.
- Single-Serve Packets:Pre-portioned sachets containing 20-30 grams of mix optimized for on-the-go consumption and hospitality channel distribution. Japanese vending machines and US hotel breakfast programs anchor demand, constrained by higher per-unit packaging costs that compress margins versus bulk formats.
- Bulk Bags:Multi-kilogram institutional packaging designed for foodservice batch preparation and commercial kitchen inventory efficiency. US education and healthcare facilities represent underdeveloped procurement channels relative to retail saturation, creating contract penetration opportunities for compliant suppliers.
- Jars:Medium-capacity rigid containers targeting household pantry storage and visual brand presence.
- Tubs:Large-format rigid packaging for high-frequency household consumption and club store distribution.
Bulk Bags capture institutional volume; Single-Serve Packets expand most quickly in convenience-oriented channels.
Distribution Channel:
Channel selection determines margin capture versus customer acquisition cost tradeoffs and inventory velocity requirements.
- Online Retailers:Direct-to-consumer platforms and third-party marketplaces enabling subscription replenishment and auto-ship program deployment. Nestlé sustains recurring delivery programs across North American and European markets through global logistics network integration, reshaping volume away from impulse retail.
- Supermarkets:Traditional brick-and-mortar retail with shelf placement determining brand visibility and promotional velocity. Price-accessible auto-ship formats from mass-market competitors target family pantry stocking occasions, pressured by just-in-time replenishment behavior shifting toward predictable delivery cadences.
- Specialty Stores:Premium retail channels emphasizing organic certification, single-origin sourcing, and limited-edition seasonal offerings.
- Convenience Stores:High-foot-traffic urban locations with grab-and-go purchasing patterns and immediate consumption orientation.
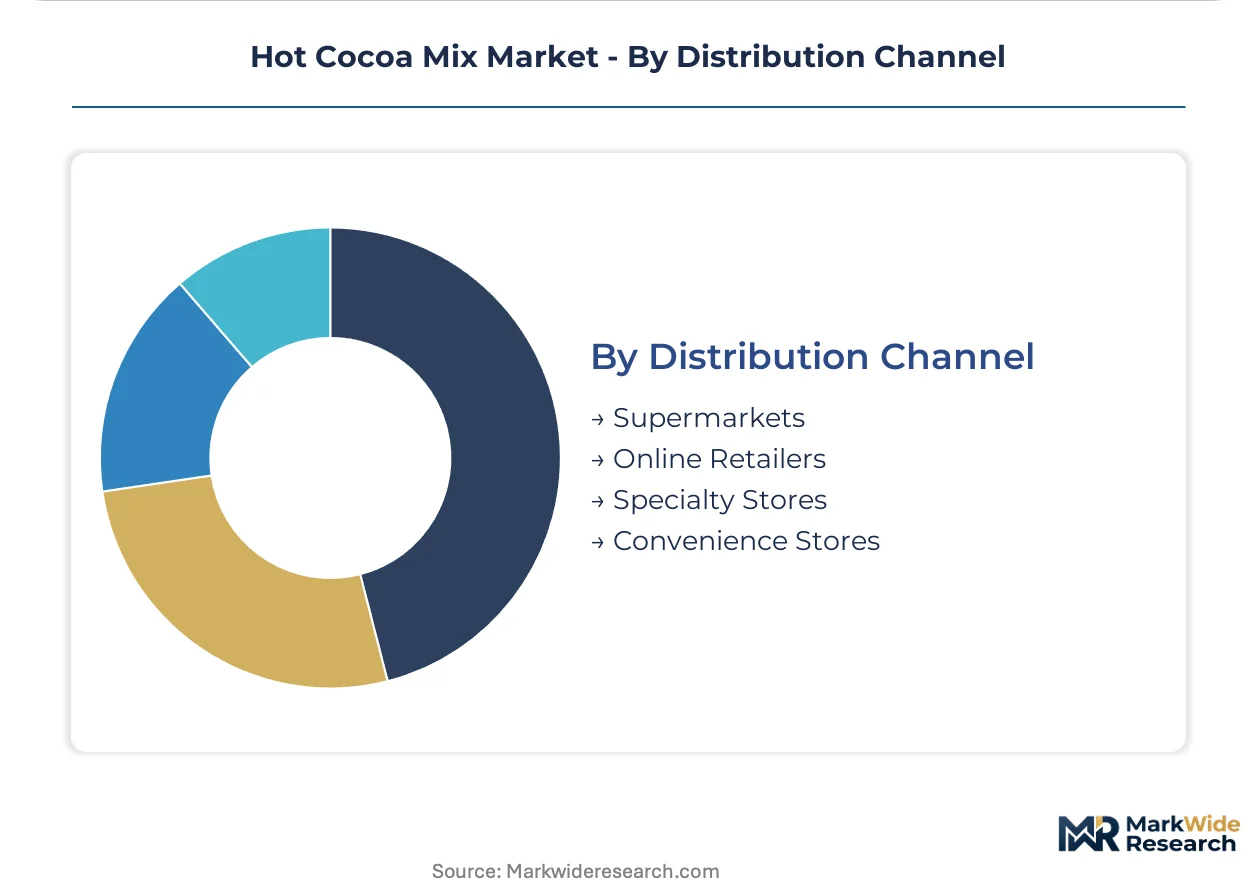
Supermarkets retain volume concentration; Online Retailers show the steepest expansion trajectory as subscription models lock in recurring revenue streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American hot cocoa mix distribution through its integrated rail-truck logistics corridor serving retail and foodservice channels nationwide.
United States
Millennial and Gen-Z households in suburban markets drive subscription replenishment adoption, with auto-ship programs displacing impulse retail purchases. FDA nutritional labeling mandates force reformulation timelines across conventional product lines. The Chicago-Milwaukee industrial corridor concentrates powder processing capacity for national distribution.
Germany
Established cocoa-drinking culture sustains per-capita consumption leadership among European markets, with pantry consolidation reducing brand-switching frequency. EFSA traceability requirements under EU deforestation-free supply chain regulations reshape sourcing documentation for market access. The Cologne-Düsseldorf logistics cluster supports efficient last-mile delivery density for recurring household replenishment.
Japan
Vending-compatible single-serve formats align with convenience store infrastructure in high-foot-traffic Tokyo and Osaka metropolitan areas. METI standards govern food additive approvals and labeling requirements for imported cocoa products. The Kanto region's automated beverage distribution networks enable precise inventory turnover for seasonal and year-round SKUs.
United Kingdom
Premium at-home consumption expands among urban households seeking café-style experiences, with direct-to-consumer channels capturing volume from traditional retail. FSA enforcement of front-of-pack nutritional labeling accelerates clean-label product development timelines. Greater Manchester's food manufacturing cluster hosts contract packaging operations for both domestic and export markets.
Switzerland
Single-origin certification premiums justify price escalation in premium-positioned retail channels serving high-income households. Swissmedic-aligned food safety protocols exceed baseline EU requirements for contaminant thresholds and origin documentation. The Zurich-Basel corridor concentrates chocolate and cocoa processing R&D facilities with proximity to Lindt & Sprüngli headquarters operations.
Hot Cocoa Mix Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a consolidated tier-one and fragmented long-tail structure. Integrated multinationals with captive cocoa sourcing operations occupy premium positioning through vertical control over supply chains. Three archetypes dominate: global FMCG conglomerates with logistics networks, premium chocolate heritage brands with seasonal subscription expertise, and private-label suppliers serving price-sensitive retail channels. Competitive moves concentrate on M&A for regional brand portfolios and capacity expansion for allergen-free production lines.
Among Swiss heritage chocolate houses, Lindt & Sprüngli occupies a position exemplifying premium-tier seasonal subscription strategies. Nestlé represents the scale-driven FMCG archetype with recurring delivery program infrastructure. The Hershey Company anchors price-accessible auto-ship formats targeting family pantry replenishment patterns.
| Leading Market Players |
|---|
| Unilever |
| Lindt & Sprüngli |
| Nestlé |
| Godiva |
| Ghirardelli Chocolate Company |
| The Hershey Company |
| Mondelez International |
| Conagra Brands |
| Starbucks |
| Others |
Value Network & Pricing Analysis
Subscription-program households in US and German suburban markets concentrate purchasing power toward predictable auto-ship cadences, anchoring a pricing model that trades per-unit premium for lifetime value capture and reduced customer acquisition spend.
Pricing Analysis
Certification-grade anchoring ties price premiums to deforestation-free origin documentation and organic compliance tiers. Three-tier pricing structure across premium, standard, and economy levels separates Lindt's seasonal subscription positioning from Nestlé's mass-market recurring delivery and Hershey's price-accessible family formats. Cost compression in conventional instant powder is intensifying because FDA sugar-reduction mandates force expensive reformulation cycles. Price sensitivity concentrates among family pantry buyers in supermarket channels, while specialty store shoppers exhibit inelastic demand for single-origin certified SKUs.
Supply Chain Analysis
Dual-sourcing requirements from EFSA traceability mandates compel processors to qualify multiple West African and Latin American origin suppliers simultaneously, elevating documentation costs but insulating against single-origin disruption. Cocoa bean inputs draw from Côte d'Ivoire, Ghana, and Ecuador processing hubs. Powder production rests on dairy and oat milk powder inputs alongside stabilizer chemicals. Single-source vulnerability in third-party deforestation audit capacity creates queue delays for market access. Distribution runs through Chicago-Milwaukee rail-truck corridors for North American retail and foodservice penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from clean-label R&D talent scarcity and legacy equipment retrofit costs will force mid-tier manufacturers toward acquisition or exit, favoring capital-heavy incumbents with captive compliance infrastructure.
For Market Incumbents: Anchor defensible positioning through backward integration into certified cocoa sourcing and dedicated allergen-free processing lines in the Cologne-Düsseldorf corridor. Precision fermentation-derived cocoa compounds threaten agricultural-origin supply chains; early pilot partnerships with biotech ingredient suppliers hedge this substitution risk. Certification investment in USDA Organic and EU Organic dual compliance creates switching costs for retail channel access. For New Entrants and Emerging Players: Direct-to-consumer subscription interfaces offer the lowest customer acquisition friction for unbranded challengers, bypassing supermarket slotting fee barriers. White-space concentrates in Japanese convenience store vending-compatible single-serve formats and US institutional foodservice contracts for education and healthcare facilities. Functional ingredient fortification with adaptogens and probiotics captures wellness-oriented millennial household spend at premium price points. For Investors and Strategic Acquirers: The window for entry favors private-label suppliers with established co-manufacturing relationships and clean-label formulation capabilities. Long-term viability hinges on deforestation-free certification infrastructure and multi-jurisdiction organic compliance. Watch for inflection when EFSA audit queue delays compress to under six months, signaling supply chain normalization and margin recovery for compliant producers.| Strategic Initiative | Industry Significance |
|---|---|
| Deforestation-Free Certification Program | EFSA traceability mandates create competitive moats for early-compliant producers accessing European retail. |
| Precision Fermentation Partnership | Biotech-derived cocoa compounds insulate formulations from West African commodity price volatility. |
| Subscription Platform Launch | Auto-ship programs lock recurring revenue and reduce customer acquisition costs versus impulse retail. |
| Functional Ingredient Fortification | Adaptogen and probiotic infusions capture wellness-oriented millennial and Gen-Z household premiums. |
| Institutional Foodservice Contract | US education and healthcare facilities remain underdeveloped relative to retail saturation. |
Research Methodology
Independent corroboration across brand managers at Nestlé and Lindt & Sprüngli, category buyers at US and German supermarket chains, and supply planners at cocoa powder processors underwrites the qualitative findings. Secondary validation draws from FDA nutritional labeling filings, EFSA deforestation traceability documentation, USDA Organic certification databases, and Nielsen retail audit data. Bottom-up volume modeling from individual SKU shipment data triangulates against top-down category spend estimates across the analysis window.
Comparable-period anchoring to pre-pandemic pantry-loading baselines and post-stabilization subscription adoption curves shapes the projection horizon. Segmentation dimensions span product type, flavor profile, packaging format, and distribution channel, with organic certification status and deforestation-free origin documentation as cocoa-specific forecast inputs. CAGRs derive from trend extrapolation moderated by regulatory compliance cost absorption rates and precision fermentation technology penetration assumptions.
Inputs from primary interviews and secondary regulatory filings were available through the study window; gaps in real-time cocoa futures price volatility data introduce uncertainty bands around input cost assumptions. Deviation in EFSA audit capacity expansion or West African harvest conditions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
North America Cold Pressed Juices Market
Beverages
Maple Water Market
Beverages
Relaxation Beverages Market
Beverages
Direct Piping Water Dispenser Market
Beverages
Asia-Pacific Energy Bar Market
Beverages
Ginger Beer Market
Beverages
Rose Floral Water Market
Beverages
Asia-Pacific Juices Market
Beverages
China Orange Juice Market
Beverages
Fruit Juice Market
Beverages
Premium Water Market
Beverages
Flavored Powder Drinks Market
Beverages
CBD-Infused Beverages Market
Beverages
Global Squash Drinks Market
Beverages
Saudi Arabia Bottled Water Market
Beverages
Collagen Drinks Market