
 Cocoa Powder Market | 2026-2036
Cocoa Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Cocoa Powder Market Analysis
The EU Deforestation Regulation is repositioning procurement standards across the cocoa powder value chain, compelling traceable farm-to-factory documentation for European market access. Barry Callebaut AG leverages its integrated grinding network to secure certified bean streams from West African cooperatives. Guan Chong Berhad (GCB) anchors its competitiveness through Malaysian processing scale and Asian distribution density. Cargill sustains supply continuity through direct farmer engagement programs in Ivory Coast and Ghana.
Cocoa powder is the partially defatted solid residue of fermented, dried, roasted cacao beans, typically containing 10-24% cocoa butter retained after hydraulic pressing, and serves as the foundational coloring, flavoring, and functional ingredient in chocolate confectionery, baked goods, and beverage formulations. Dutch-Processed cocoa dominates industrial procurement due to its neutral pH, darker color profile, and superior solubility in dairy matrices. Natural cocoa retains acidity preferred in specific bakery applications where chemical leavening reactivity matters. The beverage industry segment is expanding fastest as ready-to-drink chocolate formulations and protein-fortified shakes multiply on retail shelves.
The Food and Drug Administration sets identity standards for cocoa products under 21 CFR 163, while the European Food Safety Authority monitors cadmium and lead thresholds in cocoa powder imports through updated maximum residue limits. EUDR compliance documentation requirements are forcing exporters to deploy geolocation verification and satellite monitoring across plantation boundaries. Stakeholders must now decide whether to absorb traceability technology costs or reorient supply toward less regulated destination markets.
Market Dynamics
The EU Deforestation Regulation is forcing a structural rewiring of cocoa powder procurement, as European buyers now demand geolocated farm documentation and satellite-verified plantation boundaries before accepting shipments.
Growth Catalysts
- Clean-label confectionery reformulation:Food manufacturers are removing artificial colorants and substituting with cocoa powder's natural pigment properties, particularly in premium chocolate coatings and bakery glazes.
- Indonesia's processing capacity expansion:Domestic chocolate production lines in Jakarta and Surabaya are absorbing larger cocoa powder volumes, reducing reliance on re-exported finished goods.
- Protein-fortified beverage proliferation:Ready-to-drink chocolate shakes and meal-replacement formulations are incorporating alkalized cocoa powder for flavor masking and visual appeal.
Market Restraints
- Cocoa butter price volatility:Press cake economics fluctuate with cocoa butter futures, compressing margins for natural cocoa powder producers when fat extraction yields deteriorate.
- West African supply concentration:Ivory Coast and Ghana collectively control roughly two-thirds of global bean origination, creating origination risk during political transitions or port disruptions.
- Cadmium threshold enforcement:EFSA's tightened maximum residue limits for heavy metals in cocoa imports are disqualifying certain Ecuadorian and Peruvian origins from European food-grade channels.
Strategic Opportunities
- Southeast Asian bakery modernization:Vietnam and the Philippines are expanding industrial croissant and pastry manufacturing, creating new alkalized cocoa powder demand for laminated dough applications.
- EUDR compliance services:Traceability technology providers can capture value by offering geolocation verification and satellite monitoring bundled with physical cocoa powder shipments.
- Natural cocoa acidity positioning:Chemical leavening reactivity in American-style devil's food cake mixes presents a defendable niche against Dutch-processed commoditization.
Industry Challenges
- Fermentation expertise scarcity:Bean-to-powder facilities struggle to recruit technicians capable of managing microbial succession during the critical 5-7 day heap fermentation phase.
- Legacy ERP integration:Established grinders face friction deploying blockchain traceability modules alongside decades-old inventory management systems.
- Organic certification timelines:The 36-month conversion period for conventional plantations locks suppliers out of premium organic cocoa powder markets during transition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cocoa Powder Market |
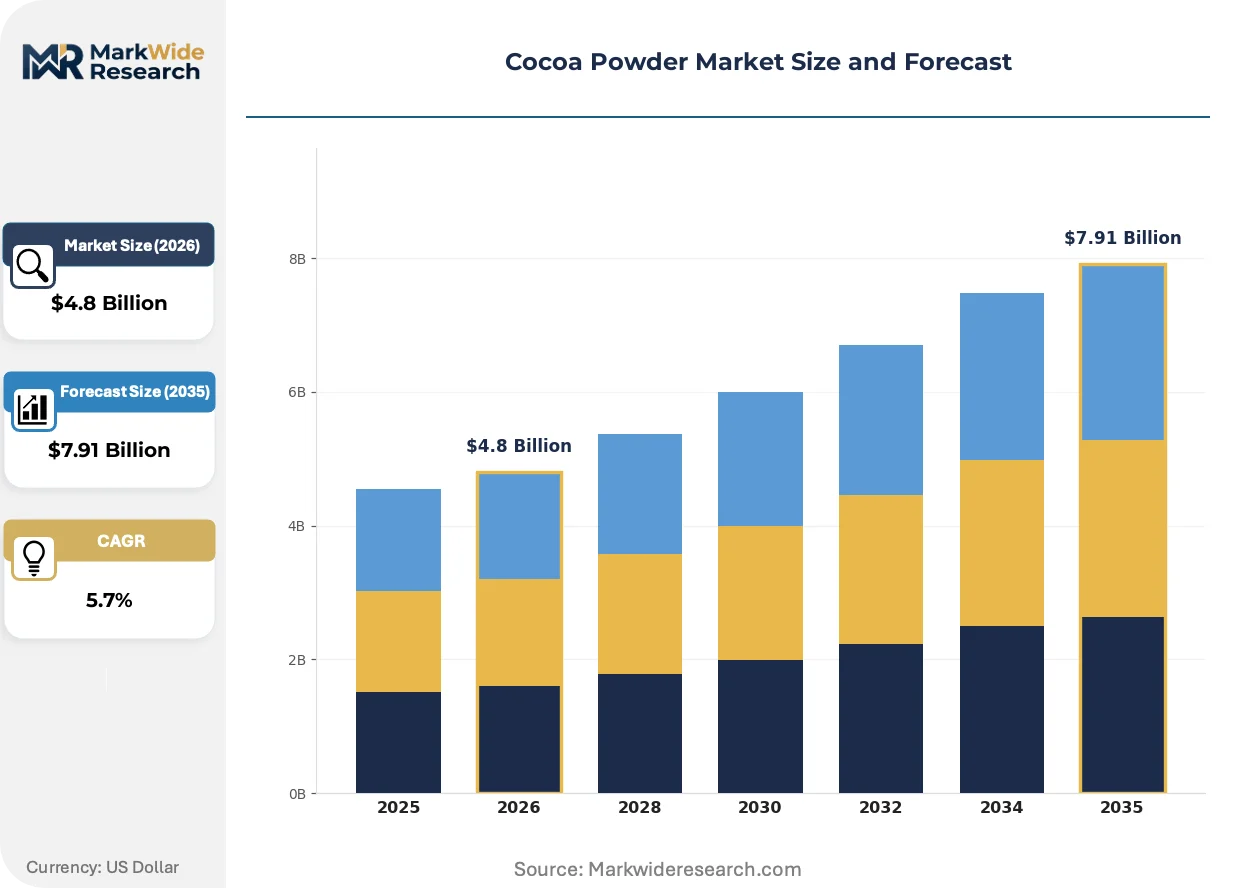
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Cocoa, Dutch-Processed Cocoa, Organic Cocoa, Unsweetened Cocoa End User: Food Manufacturers, Confectioneries, Bakeries, Beverage Industry Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Application: Bakery Products, Chocolates, Dairy Products, Health Supplements |
| Companies Covered | Nestlé S.A., Guan Chong Berhad (GCB), Barry Callebaut AG, Puratos Group, Touton S.A., Cargill, Mondelēz International, FUJI OIL CO., LTD., Mars, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cocoa Powder Market Emerging Trajectories
Processing technology and regulatory documentation requirements are converging to reshape how cocoa powder moves from plantation to formulation facility, with traceability and alkalization chemistry at the center of competitive differentiation.
Alkalization control systems are unifying pH precision with energy recovery in modern pressing facilities. Dutch-processed cocoa manufacturers in Malaysia and Indonesia are retrofitting hydraulic presses with real-time alkalinity sensors and closed-loop heat exchangers. This convergence is compressing batch-to-batch color variation while reducing thermal energy consumption per metric ton of press cake output.
EFSA's updated cadmium and lead maximum residue limits are disqualifying high-elevation Ecuadorian origins from European food-grade channels. Cocoa powder importers are redirecting sourcing toward lower-cadmium West African cooperatives or investing in soil remediation partnerships. The confectionery segment is most affected, as dark chocolate formulations with elevated cocoa solids face stricter scrutiny than milk chocolate variants.
Buyers are consolidating supplier relationships around integrated grinders with captive traceability infrastructure. Mid-sized confectionery manufacturers in Germany and the Netherlands are abandoning spot market purchases in favor of multi-year contracts with processors offering EUDR-compliant documentation packages. This concentration is most visible in the industrial chocolate compound sector, where formulation consistency and audit readiness outweigh marginal price advantages.
Cocoa Powder Market Segmentation
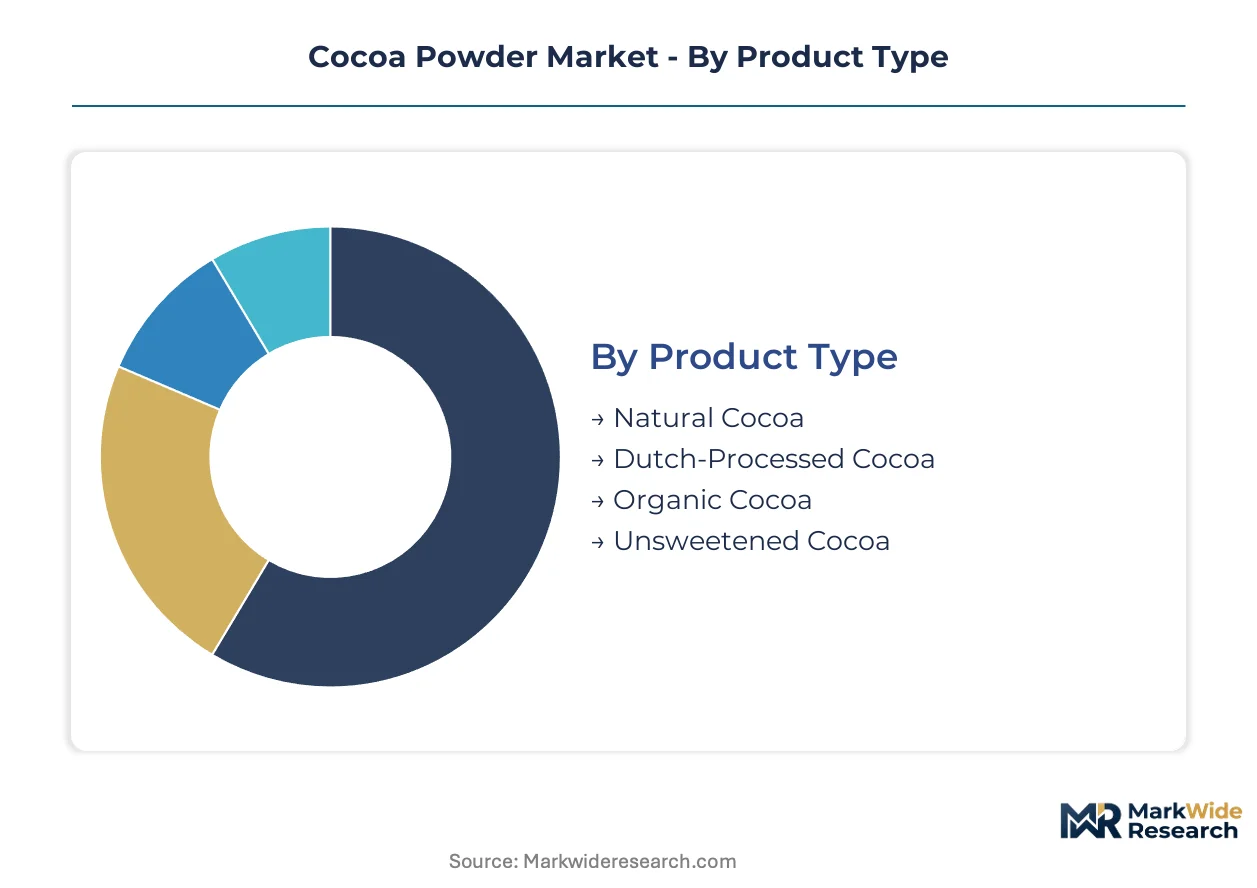
Cocoa powder segmentation reveals how processing chemistry, end-use specifications, and channel economics fragment procurement patterns. Manufacturers configure alkalization levels and fat content precisely to match formulation requirements across confectionery, bakery, and beverage verticals.
Product Type:
Volume concentrates in mass-market alkalized grades while premium positioning shifts toward certified organic and single-origin natural variants.
- Dutch-Processed Cocoa:Alkalized to pH 6.5-7.5 through potassium carbonate treatment, yielding darker color and reduced astringency. European industrial chocolate compound manufacturers in Belgium and the Netherlands specify this grade for consistent viscosity in enrobing operations. EUDR traceability requirements favor integrated processors with captive alkalization facilities.
- Natural Cocoa:Retains native acidity (pH 5.0-5.8) with pronounced fruit-forward flavor notes. American devil's food cake mixes and chemical-leavened bakery applications require this reactivity profile. West African bean origins dominate supply contracts for this segment due to lower baseline cadmium levels.
- Organic Cocoa:Certified through 36-month conversion protocols with premium positioning in clean-label confectionery. European specialist chocolatiers in Switzerland and France anchor procurement.
- Unsweetened Cocoa:Pure press cake milled without additives, serving keto-formulation and sugar-restricted product lines. Health supplement manufacturers in California and Texas drive volume.
Today's leader: Dutch-Processed Cocoa. Tomorrow's challenger: Organic Cocoa.
End User:
Customer scale determines contract structure, with multinational food manufacturers locking multi-year supply agreements while artisanal confectioneries remain spot-market dependent.
- Food Manufacturers:Industrial-scale compound chocolate and coating producers in Indonesia, Germany, and Brazil run continuous alkalized cocoa powder through automated batching systems. These buyers prioritize EUDR-compliant documentation packages over marginal price differentials.
- Confectioneries:Premium truffle and praline specialists specify origin-labeled natural cocoa with traceable fermentation protocols. Belgian and Swiss processors dominate this tier.
- Bakeries:Industrial croissant and laminated dough manufacturers in Vietnam and the Philippines are expanding alkalized cocoa procurement for chocolate-filled pastry lines.
- Beverage Industry:Ready-to-drink chocolate shake and protein-fortified meal replacement formulators favor high-fat Dutch-processed grades for mouthfeel and suspension stability.
Food Manufacturers command volume share. Beverage Industry climbs fastest on functional formulation trends.
Distribution Channel:
Channel selection tracks buyer sophistication, with integrated processors disintermediating traditional wholesale layers for large accounts.
- Direct Sales:Captive supply relationships between Malaysian and Indonesian grinders and European industrial chocolate manufacturers. EUDR documentation flows directly through these channels.
- Supermarkets:Mass-market retail cocoa powder for home baking, dominated by private-label offerings from West African origin processors.
- Specialty Stores:Premium single-origin and organic variants targeting artisanal chocolatiers and high-end bakery supply shops in Paris, Brussels, and Zurich.
- Online Retail:Direct-to-consumer growth in specialty cocoa for home bakers and keto-formulation enthusiasts, particularly in US and UK markets.
Direct Sales anchors industrial procurement. Online Retail gains fastest on formulation democratization.
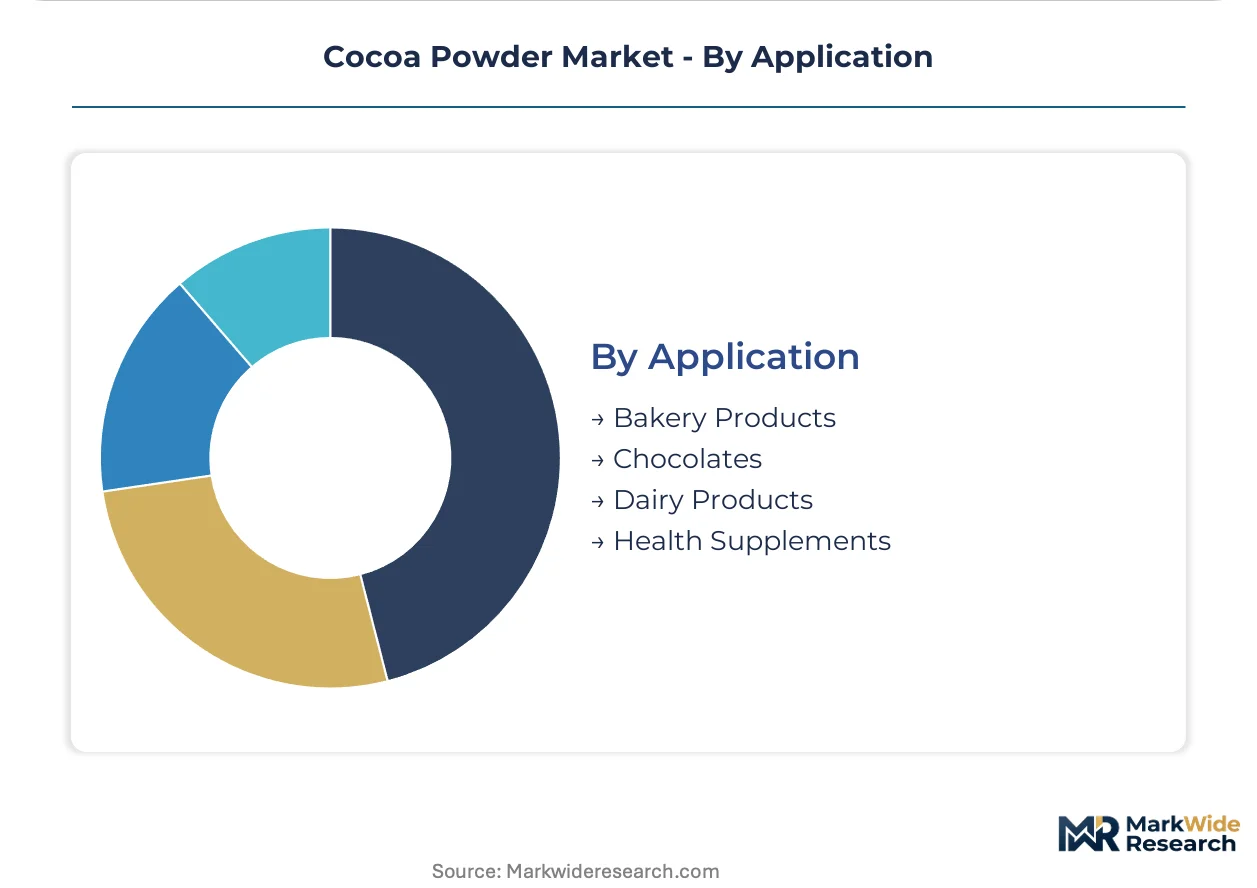
Application:
Application economics vary dramatically by cocoa butter retention requirements and color intensity specifications.
- Chocolates:Industrial compound coatings and enrobing masses specify alkalized cocoa with 10-12% residual fat for snap and gloss. European confectionery manufacturers face EFSA cadmium threshold compliance pressure.
- Bakery Products:Chemical-leavened cakes and pastries utilize natural cocoa acidity for proper rise, while laminated doughs require alkalized grades for color stability through thermal processing.
- Dairy Products:Chocolate milk and ice cream applications demand high solubility Dutch-processed cocoa with fat content calibrated to prevent serum separation.
- Health Supplements:Protein powders and meal replacements incorporate alkalized cocoa for flavor masking and antioxidant positioning in functional nutrition markets.
Chocolates retains volume dominance. Health Supplements expands most quickly on functional food positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial cocoa grinding first achieved scale in the Netherlands during the nineteenth century, establishing Dutch-processing chemistry as the foundational technology for modern cocoa powder production. European regulatory frameworks now extend that legacy through EUDR traceability mandates and EFSA contaminant thresholds.
Netherlands
Amsterdam and Zaandam retain concentrated alkalization capacity serving compound chocolate manufacturers throughout the Rhine-Ruhr industrial corridor. EUDR geolocation documentation requirements flow through Rotterdam port customs before cocoa powder enters German or Belgian processing facilities. Zaanstad's legacy grinding infrastructure now retrofits satellite-verified traceability modules to maintain European market access.
Germany
Industrial bakeries in Lower Saxony and North Rhine-Westphalia absorb substantial Dutch-processed volumes for laminated dough applications. The country's Federal Ministry of Food and Agriculture enforces EFSA cadmium maximum residue limits through import inspection protocols at Hamburg and Bremen ports. Cologne's chocolate compound sector locks multi-year supply contracts with Malaysian grinders offering bundled EUDR compliance documentation.
Indonesia
Domestic chocolate production lines in Jakarta and Surabaya have expanded capacity, redirecting cocoa powder flows that previously re-exported as finished goods. The national food and drug regulator, BPOM, aligns local standards with Codex Alimentarius frameworks while processing investment incentives accelerate. Batam's free trade zone hosts grinding facilities supplying both ASEAN confectionery markets and European re-export channels.
United States
Devil's food cake mix manufacturers and protein-fortified beverage formulators in the Midwest and California drive natural and alkalized cocoa procurement respectively. FDA identity standards under 21 CFR 163 govern product classification while California Proposition 65 litigation risk shapes heavy metal testing protocols. Chicago's industrial chocolate compound sector sources West African origins to minimize cadmium exposure in dark chocolate formulations.
Malaysia
Johor Bahru and Port Klang grinding facilities leverage proximity to Indonesian bean origination and Asian distribution density. The country's Department of Standards Malaysia certifies processing facilities for halal compliance, unlocking Middle Eastern and Southeast Asian market segments. Malaysian grinders now market EUDR-ready documentation packages to European buyers seeking supply chain alternatives to West African concentration.
Cocoa Powder Market Vendor Landscape
Capital-heavy integrated grinders compete with asset-light traders and specialty processors for cocoa powder market positioning. The structure concentrates around three to five major alkalization facilities per continent, with mid-tier regional processors occupying price-sensitive segments. Strategic archetypes include integrated bean-to-powder operators, regional toll processors, and certified organic specialists. Capacity expansion and backward integration into plantation traceability infrastructure represent the dominant competitive moves as EUDR deadlines approach.
Among integrated Swiss and Belgian processors, Barry Callebaut AG exemplifies the captive traceability archetype through cooperative partnerships in West Africa. Malaysian-scale operators include Guan Chong Berhad, which anchors Asian distribution density through Johor-based processing capacity. American agricultural conglomerates such as Cargill occupy positions linking Ivory Coast and Ghana farmer programs with European industrial chocolate accounts.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Guan Chong Berhad (GCB) |
| Barry Callebaut AG |
| Puratos Group |
| Touton S.A. |
| Cargill |
| Mondelēz International |
| FUJI OIL CO., LTD. |
| Mars, Incorporated |
| Others |
Supply Flow & Price Mechanics
The EU Deforestation Regulation gates qualified supply and premium-tier pricing access for European-bound cocoa powder, compelling exporters to absorb geolocation verification costs or forfeit market entry. Buyers now bundle traceability documentation with volume contracts, compressing spot-market premiums while elevating multi-year agreement values.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the cocoa powder market by certification grade and volume scale. EUDR-compliant alkalized grades command premium positioning against uncertified natural cocoa, while industrial food manufacturers exhibit lowest price sensitivity due to formulation lock-in requirements. Cost compression in standard-tier natural cocoa is intensifying because West African bean origination faces cadmium threshold disqualification from European channels.
Supply Chain Analysis
Dual-sourcing requirements now mandate multi-supplier qualification for European industrial chocolate manufacturers seeking EUDR audit readiness. Supply concentrates in Ivory Coast, Ghana, and Indonesia for bean origination, with Malaysian and Dutch facilities handling alkalization and pressing. The chain draws from fermented cacao beans, potassium carbonate alkalizing agents, and hydraulic pressing equipment, with single-source vulnerability concentrated in West African political transitions. Distribution runs through direct captive relationships between integrated grinders and compound chocolate manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cocoa powder market functions as a regulatory compounder, with EUDR compliance deadlines accelerating procurement consolidation among qualified suppliers.
For Market Incumbents: Anchor defensibility through backward integration into plantation traceability infrastructure and captive alkalization capacity in Malaysia or Indonesia. EUDR documentation bundling creates switching costs that neutralize price competition from uncertified traders. Invest in real-time pH control systems to compress batch-to-batch color variation for industrial chocolate accounts. For New Entrants and Emerging Players: Capture white-space in EUDR compliance services by offering satellite-verified geolocation documentation bundled with physical shipments. Southeast Asian bakery modernization in Vietnam and the Philippines presents the most penetrable demand segment. Pursue toll-processing partnerships with established grinders rather than greenfield capacity builds. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier alkalization specialists because EUDR deadlines are forcing consolidation around processors with captive traceability infrastructure. Target facilities with existing West African cooperative networks and European customer lock-in. Watch cadmium threshold enforcement patterns as the signal indicating which origin regions face permanent European market exclusion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Traceability | EUDR compliance documentation secures European market access for integrated processors. |
| Real-Time Alkalization Control Systems | Malaysian facilities reduce energy consumption while compressing color variation for industrial buyers. |
| Multi-Year Supply Contract Lock-In | German compound chocolate manufacturers prioritize audit readiness over marginal price advantages. |
| Soil Remediation Partnerships | Ecuadorian and Peruvian origins seek pathway back into European food-grade channels. |
| Southeast Asian Capacity Expansion | Indonesian domestic chocolate production absorbs volumes previously re-exported as finished goods. |
Methodological Framework
Bottom-up beverage and confectionery modeling reconciled against top-down grinding capacity tracking forms the analytical core of this study. Primary interviews with alkalization facility managers, European industrial chocolate procurement leads, and West African cooperative agronomists combined with secondary validation from customs trade data, EFSA contaminant threshold filings, and SEC 10-K disclosures from listed processors. This approach triangulates demand-side formulation trends against supply-side pressing economics.
Historical trendline analysis of alkalized versus natural cocoa powder price spreads informed the projection framework across the analysis window. Segmentation dimensions modeled include processing chemistry, residual fat content, certification tier, and end-use vertical. CAGRs were derived from capacity utilization rates at major grinding facilities and formulation substitution patterns in protein-fortified beverages.
Regulatory enforcement variance, cocoa butter futures volatility, and fermentation expertise scarcity are the dominant revision risks to the outlook. Deviation in EUDR implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cold Water-Soluble Creamer Market
Ingredients
Global Distillers Grains Market
Ingredients
Virginiamycin Market
Ingredients
Europe Fermented Ingredients Market
Ingredients
Milk Ingredients Market
Ingredients
Freeze-Dried Pea Isolates Market
Ingredients
Egg Yolk Lecithin Market
Ingredients
Mediterranean Marine Ingredients for Pet Health Market
Ingredients
North America Malt Ingredients Market
Ingredients
Collagen Casings Market
Ingredients
Zero-Calorie Oil Market
Ingredients
North America Bioactive Ingredients Market
Ingredients
Pet Food Premix Market
Ingredients
Rice Starch Market
Ingredients
Europe Sodium Reduction Ingredient Market
Ingredients
Europe Agar Market