
 Asia-Pacific Energy Bar Market | 2026-2036
Asia-Pacific Energy Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Energy Bar Market Outlook
Convenience store distribution in Asia-Pacific is fragmenting as local chains and health-focused micro-retailers challenge supermarket dominance. General Mills leverages its cereal supply infrastructure to secure shelf space across Japan's Lawson and 7-Eleven networks. Abbott Laboratories anchors its position through pharmacy-channel placement of meal replacement bars targeting diabetic consumers. KIND Snacks competes by emphasizing whole-nut ingredient transparency that resonates with Australia's health-conscious shoppers.
Asia-Pacific energy bars are shelf-stable, nutrient-dense food products typically formulated with protein isolates, dried fruits, and binding syrups, manufactured through cold-press or extrusion processes to preserve micronutrient integrity; they serve as portable caloric supplements for active lifestyles and time-constrained eating occasions. Protein bars sustain the largest revenue share due to gym culture proliferation across South Korea and Singapore, while organic bars represent the fastest-expanding margin pool as consumers reject artificial preservatives. Nutritional bars targeting busy professionals command premium positioning in airport retail and central business district vending networks, whereas meal replacement bars face slower uptake outside Japan's aging consumer base.
FSSAI in India enforces progressively stricter sodium and sugar disclosure thresholds, compelling reformulation of imported bar portfolios. Japan's Consumer Affairs Agency and Australia's FSANZ coordinate on novel protein source approvals, creating divergent compliance timelines for brands launching pea or insect-based formulations. China's SAMR scrutinizes functional health claims on e-commerce listings, forcing direct-to-consumer brands to recalibrate marketing language. Stakeholders must monitor evolving front-of-pack labeling mandates across ASEAN member states to preempt distribution disruptions.
Market Dynamics
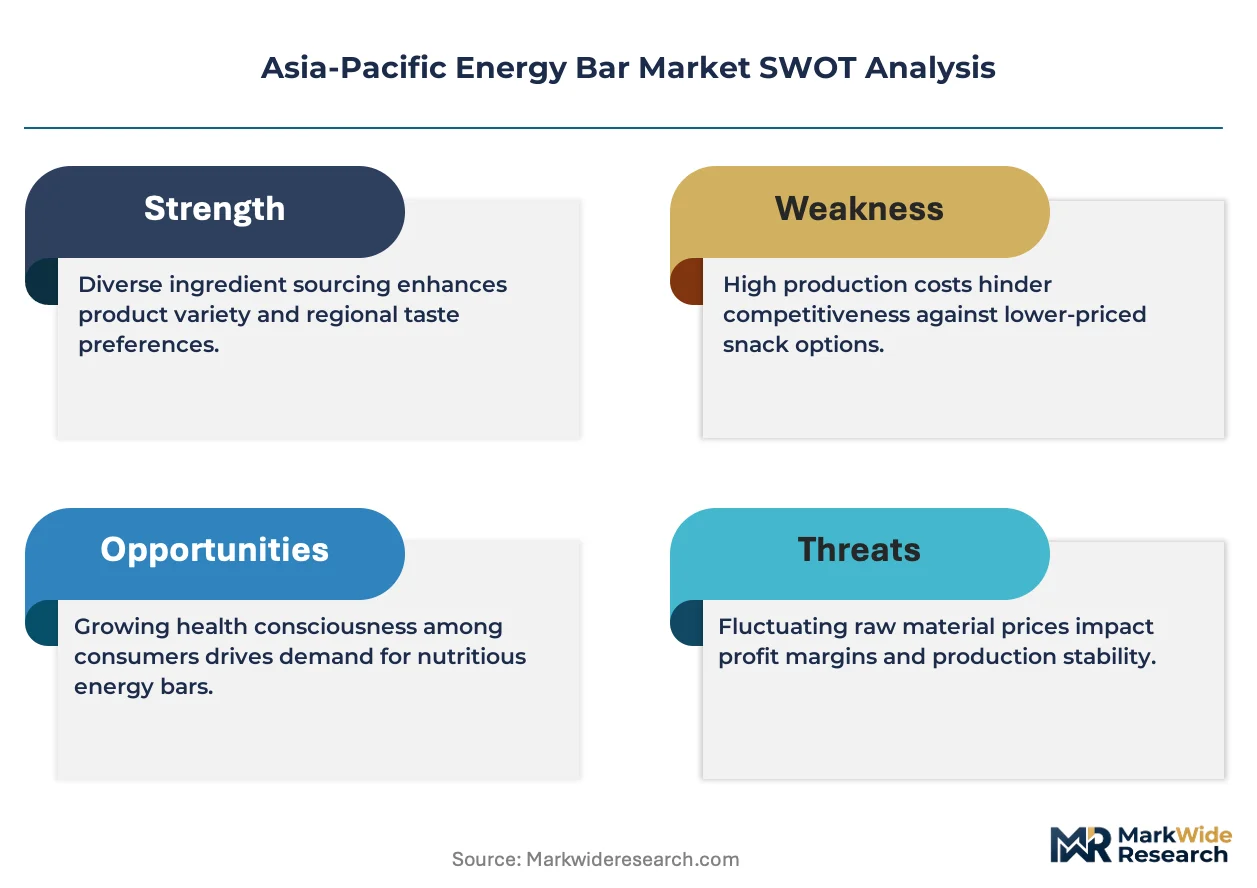
Clean-label reformulation pressure from India's FSSAI and China's SAMR is compressing formulation cycles across the Asia-Pacific energy bar sector, forcing manufacturers to rebuild supply chains around minimally processed binders and natural preservatives.
Growth Catalysts
- FSSAI Labeling Mandates:India's tightening sodium and sugar disclosure thresholds compel domestic and imported brands to reformulate portfolios, accelerating clean-label ingredient sourcing from local nut and dried-fruit processors.
- Corporate Wellness Procurement:Bulk purchasing by technology and finance sector employers in Seoul, Tokyo, and Sydney creates predictable revenue streams for protein bar suppliers serving white-collar wellness programs.
- Convenience Store Network Expansion:Lawson, 7-Eleven Japan, and domestic Chinese chains are dedicating premium shelf space to meal replacement bars, normalizing energy bars as commuter meal substitutes in tier-one cities.
Market Restraints
- Whey Protein Import Dependence:Australian and New Zealand dairy concentrate supplies dominate regional protein sourcing, exposing formulators to ocean freight volatility and currency fluctuation risks.
- SAMR Functional Claims Scrutiny:China's e-commerce regulator forces direct-to-consumer brands to strip performance marketing language from product pages, extending compliance review timelines by 4-6 months.
- Fresh Food Substitution:Traditional wet markets and prepared meal delivery services in Southeast Asian cities compete aggressively on price and perceived freshness, limiting bar penetration outside gym and airport channels.
Strategic Opportunities
- Indonesia's Underserved Archipelago:Java's secondary cities and Sumatra's urban corridors lack dedicated sports nutrition retail, creating first-mover advantage for brands building pharmacy and minimart distribution.
- Insect Protein Regulatory Alignment:Coordinated novel food approvals between Japan's Consumer Affairs Agency and Australia's FSANZ will unlock cricket and mealworm flour formulations for sustainability-positioned product lines.
- Airport Retail Premium Positioning:Central business district and aviation hub vending networks in Singapore, Hong Kong, and Shanghai accept 40-60% price premiums for nutritional bars targeting time-constrained business travelers.
Industry Challenges
- Pea Protein Extrusion Expertise Gap:Cold-press and low-temperature processing specialists capable of preserving legume isolate functionality remain concentrated in North American and European equipment vendors, complicating regional manufacturing scale-up.
- ASEAN Labeling Fragmentation:Divergent front-of-pack mandate timelines across Thailand, Vietnam, Philippines, and Malaysia force portfolio versioning that strains packaging procurement and inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Energy Bar Market |
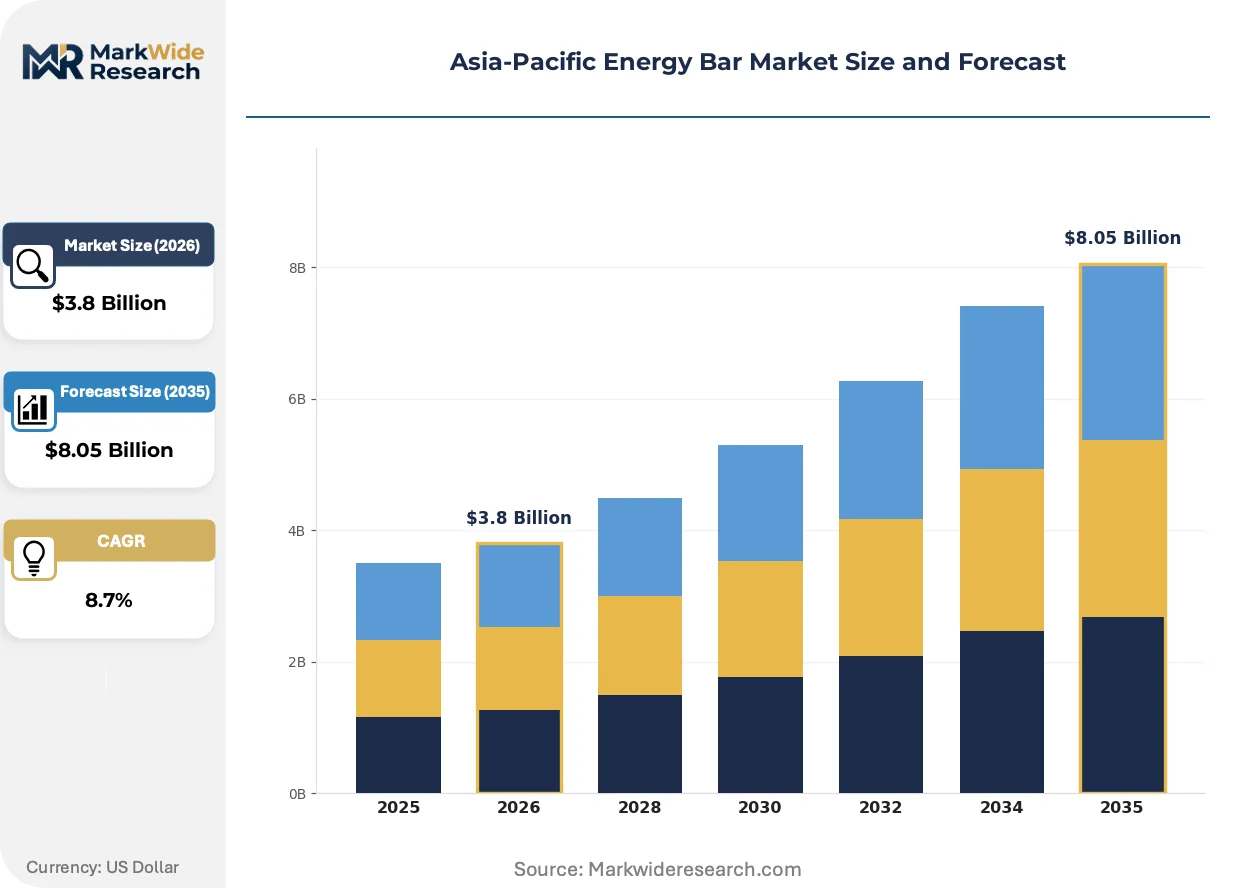
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nutritional Bars, Protein Bars, Meal Replacement Bars, Organic Bars Ingredient Type: Fruits, Nuts, Grains, Sweeteners Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Convenience Stores Consumer Type: Athletes, Fitness Enthusiasts, Busy Professionals, Health Conscious Individuals |
| Companies Covered | Clif Bar and Company, General Mills, Kellanova, Probar LLC, Abbott Laboratories, KIND Snacks, Asahi Group Holdings Ltd, Nestlé SA, Otsuka Holdings Co. Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Energy Bar Market Strategic Shifts
Formulation science and channel strategy are converging to reshape how energy bars are composed, positioned, and distributed across Asia-Pacific consumer touchpoints.
Cold-pressed binding technology is collapsing the traditional trade-off between shelf stability and clean-label positioning. Manufacturers in Australia and South Korea are adopting enzymatic fruit puree binding systems that eliminate maltitol and glycerin while maintaining 12-month ambient shelf life. This compression of the stability-purity spectrum allows premium brands to enter mainstream convenience retail without reformulating for mass-market preservative tolerance.
FSANZ and Japan's Consumer Affairs Agency are harmonizing approval pathways for novel protein sources, reducing regulatory lag for insect and algae-based formulations. This coordination accelerates commercialization timelines for sustainable protein claims that resonate with environmentally conscious urban consumers. Australian brands are leveraging this alignment to launch simultaneously across both markets, capturing early positioning in the alternative protein segment before larger multinationals complete reformulation cycles.
White-collar commuters in Shanghai, Beijing, and Shenzhen are displacing traditional breakfast occasions with convenience store energy bar purchases during subway transfers. This behavioral shift concentrates demand in central business district retail clusters and rewards brands securing exclusive placement in metro-adjacent 7-Eleven and FamilyMart locations. Airport retail networks are extending this pattern to business travel corridors, where meal replacement bars command sustained price premiums from time-constrained passengers.
Asia-Pacific Energy Bar Market Segmentation
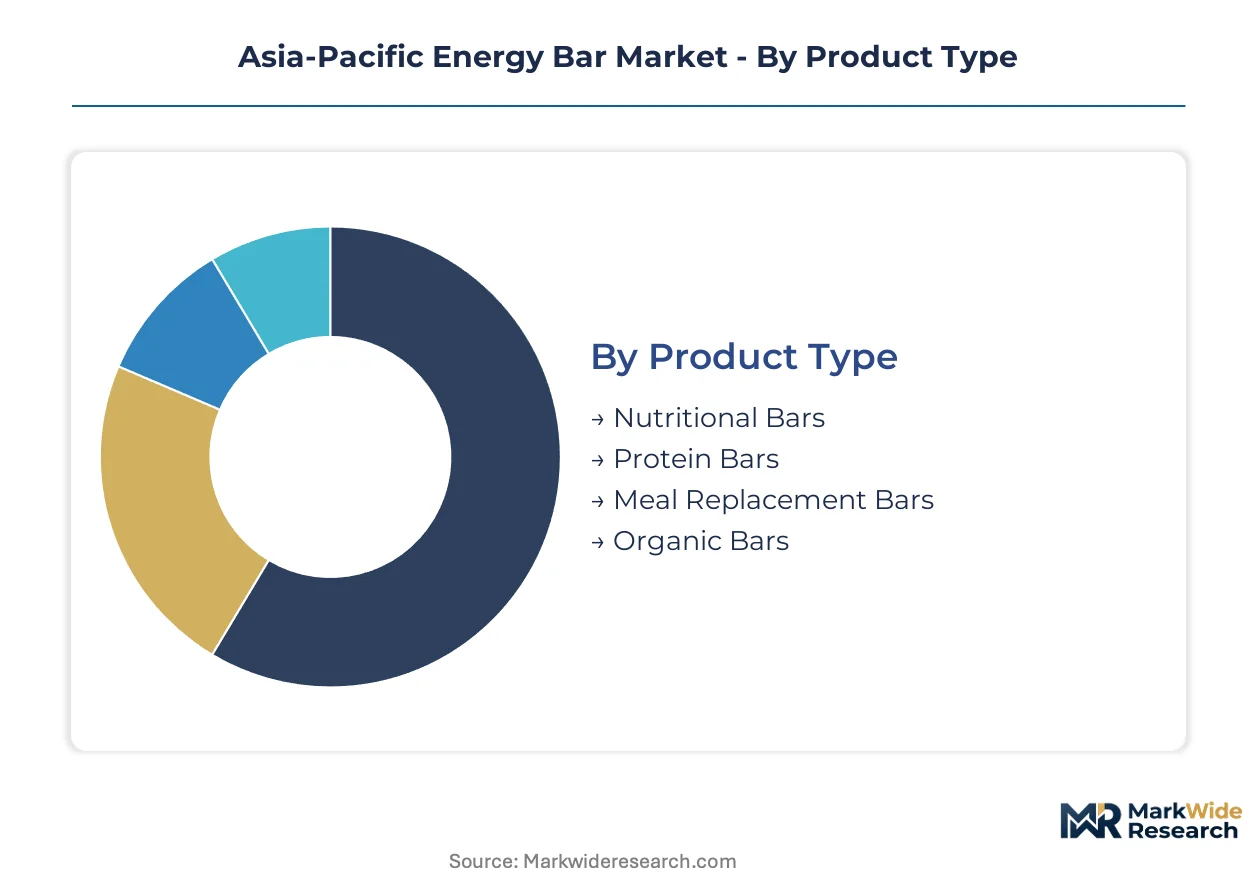
Energy bar manufacturers in Asia-Pacific configure production lines and procurement strategies around four distinct segmentation axes. Each dimension shapes margin structures, regulatory exposure, and channel access differently across Seoul gym chains, Mumbai pharmacies, and Shanghai convenience stores.
Product Type:
Cost tier determines formulation complexity and shelf placement economics across the region's retail networks.
- Protein Bars:Formulated with whey or plant isolates delivering 15-25g protein per serving, these bars command premium positioning in South Korean and Australian gym retail. Seoul's corporate wellness programs drive bulk procurement of chocolate and peanut butter variants for white-collar distribution.
- Nutritional Bars:Balanced macronutrient profiles targeting general wellness consumers, manufactured through cold-press processes to preserve micronutrient density. China's tier-one city commuters substitute these for breakfast during subway transfers, concentrating demand in metro-adjacent Lawson and FamilyMart locations.
- Meal Replacement Bars:Calorically dense formulations with vitamin fortification, finding strongest uptake among Japan's aging demographic seeking portion-controlled nutrition.
- Organic Bars:Certified ingredient sourcing with natural binding systems, gaining share fastest in Australian health food retail where FSANZ labeling transparency resonates with environmentally conscious shoppers.
Protein bars hold installed capacity. Organic bars are rotating up the share rankings.
Ingredient Type:
Application use case dictates sourcing geography and processing requirements for binders and flavor systems.
- Nuts:Almond, cashew, and macadamia bases provide structural integrity and clean-label appeal, with Australian and Vietnamese processors supplying regional manufacturers. India's FSSAI tightening on sodium disclosure pushes brands toward unsalted nut varieties to simplify label compliance.
- Fruits:Dried date, apricot, and berry inclusions deliver natural sweetness and binding functionality through enzymatic puree systems. South Korean manufacturers lead adoption of enzymatic fruit binding that eliminates glycerin while maintaining shelf stability.
- Grains:Oat, quinoa, and rice crisp inclusions add texture and fiber claims, sourced predominantly from domestic Chinese and Indian suppliers to minimize import tariff exposure.
- Sweeteners:Maltitol, erythritol, and monk fruit extracts balance taste with glycemic positioning, facing reformulation pressure as China's SAMR scrutinizes sugar reduction claims on e-commerce listings.
Nut-based formulations anchor premium positioning. Fruit-binding technology is climbing the fastest as clean-label mandates tighten.
Distribution Channel:
Customer type concentration varies sharply by channel, determining whether brands prioritize impulse packaging or subscription logistics.
- Convenience Stores:Lawson, 7-Eleven Japan, and domestic Chinese chains dedicate premium shelf space to single-serve formats. White-collar commuters in Shanghai and Beijing displace traditional breakfast with grab-and-go bar purchases during transit.
- Online Retail:Direct-to-consumer platforms and Tmall flagship stores serve fitness enthusiasts seeking bulk pricing and flavor variety. SAMR functional claims scrutiny forces brands to strip performance language from product pages, extending compliance timelines.
- Supermarkets:Multi-pack formats and family-oriented SKUs target health-conscious households in Australian Coles and Woolworths networks, competing against fresh food perimeter offerings.
- Health Food Stores:Pharmacy-channel placement in Japan and specialized retailers in Australia serve diabetic consumers and clinical nutrition needs, with Abbott Laboratories anchoring position through meal replacement bar distribution.
Convenience stores hold installed capacity. Online retail is gaining share fastest as direct-to-consumer brands bypass traditional slotting fee structures.
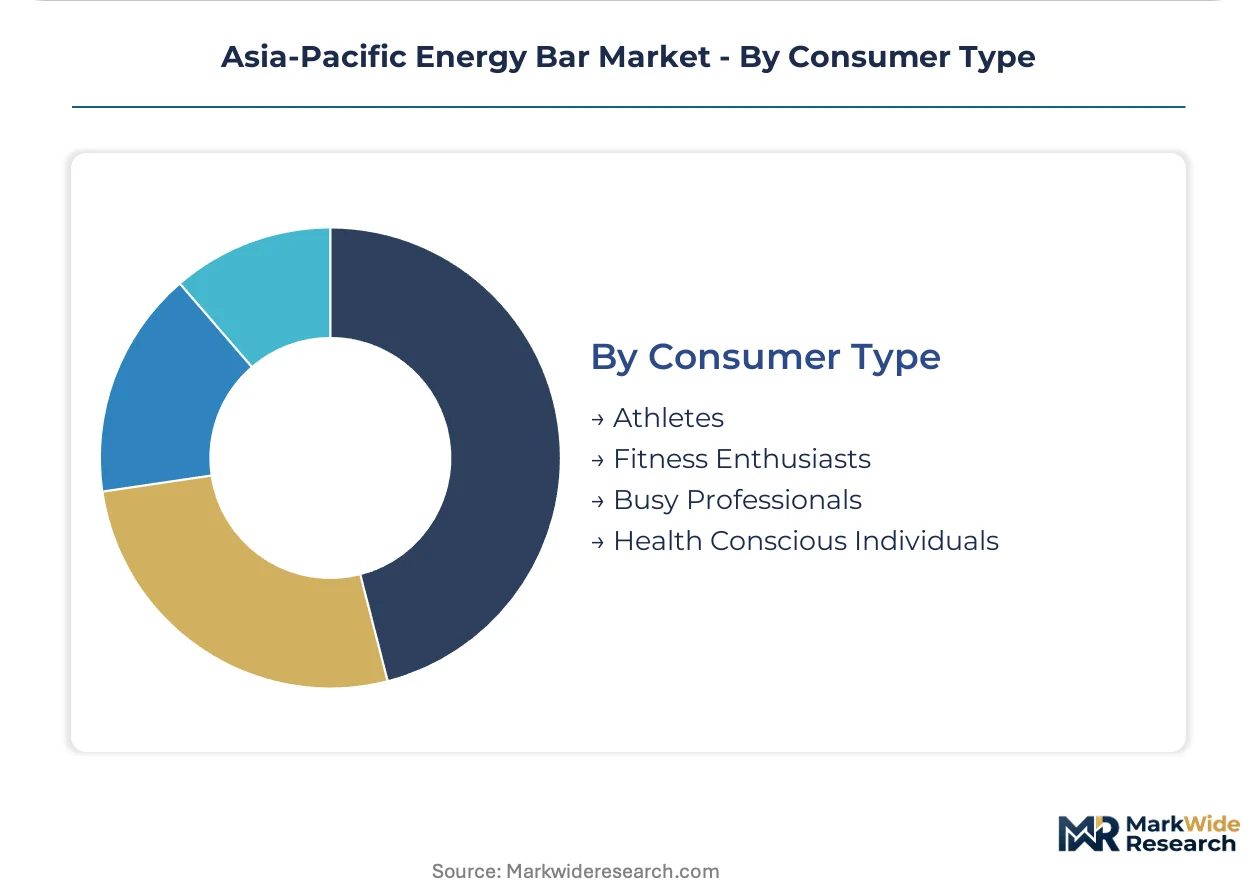
Consumer Type:
Volume concentration and price elasticity diverge sharply across activity levels and time constraints.
- Busy Professionals:Time-constrained commuters in Tokyo, Seoul, and Singapore's central business districts sustain premium pricing for meal replacement and nutritional bars. Airport retail networks in Hong Kong and Shanghai accept substantial markups for travel-format packaging.
- Fitness Enthusiasts:Gym culture proliferation across South Korea and Singapore drives protein bar consumption, with urban chains negotiating bulk supply contracts for locker room and reception placement.
- Athletes:Competitive and recreational athletes seeking performance-optimized macronutrient timing represent a concentrated but smaller addressable market, served through specialized sports nutrition retail and coaching network distribution.
- Health Conscious Individuals:Broad wellness-oriented consumers responding to organic and clean-label positioning, concentrated in Australian urban centers and India's tier-one cities where FSSAI disclosure mandates heighten ingredient transparency awareness.
Busy professionals hold installed capacity. Health conscious individuals are rotating up the share rankings as clean-label reformulation expands addressable demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Japan's pharmacy and airport channels, while Southeast Asian markets compete on volume accessibility through minimart networks. This asymmetry shapes where multinationals deploy reformulated SKUs versus standardized global formulations.
China
Tier-one city commuters in Shanghai and Shenzhen displace breakfast occasions with convenience store energy bar purchases during subway transfers. SAMR scrutinizes functional health claims on Tmall listings, forcing direct-to-consumer brands to recalibrate marketing language. Metro-adjacent Lawson and FamilyMart locations in Beijing command exclusive placement premiums for nutritional bars.
Japan
Aging consumers seeking portion-controlled nutrition drive meal replacement bar uptake through pharmacy channels. The Consumer Affairs Agency coordinates novel protein approvals with Australia's FSANZ, accelerating insect-based formulation timelines. Tokyo's central business district vending networks sustain 40-60% price premiums for time-constrained white-collar professionals.
India
FSSAI tightening of sodium and sugar disclosure thresholds compels reformulation of imported portfolios toward clean-label ingredients. Tier-one cities concentrate demand among health-conscious consumers responding to ingredient transparency mandates. Mumbai and Delhi pharmacy chains increasingly stock nutritional bars targeting diabetic management needs.
South Korea
Urban gym chains and corporate wellness programs in Seoul drive bulk procurement of protein bars for white-collar distribution. MFDS regulations on novel food ingredients create compliance lead times for sustainable protein launches. Gangnam and Yeouido business districts anchor premium positioning for meal replacement formats.
Australia
FSANZ labeling transparency requirements resonate with environmentally conscious shoppers in Sydney and Melbourne health food retail. Cold-pressed binding technology adoption preserves micronutrient density for premium positioning. Airport retail networks in Brisbane and Perth accept substantial markups for travel-format nutritional bars.
Asia-Pacific Energy Bar Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in ingredient and binding technology. The Asia-Pacific energy bar sector exhibits tiered concentration, with multinational CPG conglomerates controlling pharmacy and convenience store shelf space while regional specialists capture health food and direct-to-consumer channels. Three archetypes dominate: cereal infrastructure leverage, clinical nutrition anchoring, and clean-label transparency positioning. Competitive dynamics center on cold-press processing partnerships and regulatory pre-approval coordination across Japan-Australia alignment.
Within the multinational tier, General Mills leverages cereal supply infrastructure across Japan's Lawson and 7-Eleven networks, while Abbott Laboratories anchors clinical positioning through pharmacy-channel meal replacement distribution. KIND Snacks exemplifies the transparency-focused archetype, emphasizing whole-nut ingredient positioning that resonates with Australian health-conscious consumers. These three represent divergent vectors for securing shelf space: supply chain scale, medical-channel credibility, and clean-label differentiation.
| Leading Market Players |
|---|
| Clif Bar and Company |
| General Mills |
| Kellanova |
| Probar LLC |
| Abbott Laboratories |
| KIND Snacks |
| Asahi Group Holdings Ltd |
| Nestlé SA |
| Otsuka Holdings Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Australian and New Zealand whey protein concentrate supplies anchor regional formulation costs, concentrating margin capture with brands that have secured long-term dairy contracts or invested in plant-protein alternatives. This upstream dependency creates pricing power asymmetry between established multinationals with hedged positions and smaller players exposed to ocean freight volatility and currency fluctuation.
Pricing Analysis
Configured-to-order pricing for clean-label formulations commands substantial premiums over standard preservative-tolerant variants, with enzymatic fruit-binding technology and organic certification driving the widest spreads. Three-tier pricing structure across premium, standard, and economy levels stratifies by ingredient transparency and channel placement, with airport retail and pharmacy channels accepting the highest markups. Pricing pressure stems from India's FSSAI disclosure mandates compelling costly reformulation cycles. Fitness enthusiasts in Seoul and Singapore show lowest price sensitivity, while Southeast Asian wet-market shoppers remain highly elastic.
Supply Chain Analysis
Toll manufacturing capacity concentrates with Australian cold-press specialists and South Korean extrusion houses serving regional brand owners. Raw material sourcing draws from Vietnamese cashew processors, Indian dried-fruit suppliers, and domestic Chinese grain mills for oat and quinoa inclusions. Single-source vulnerability runs through Australian-New Zealand dairy concentrate supply, with no near-term regional alternatives for whey protein isolate quality. Distribution runs through Lawson and 7-Eleven Japan networks for impulse purchases, supplemented by Tmall flagship stores for subscription bulk orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific energy bars sit in early-cycle expansion as clean-label reformulation unlocks new consumer segments previously alienated by artificial ingredient skepticism. Corporate wellness procurement and convenience store normalization of meal replacement occasions provide durable adoption tailwinds.
For Market Incumbents: Harden supply chain resilience by securing multi-year contracts with Australian dairy processors or backward integration into plant-protein extrusion capability. Invest in cold-press equipment partnerships to preserve technical differentiation as enzymatic binding technology commoditizes. Threats include direct-to-consumer brands bypassing slotting fees through Tmall and regulatory lag from divergent ASEAN labeling timelines. For New Entrants and Emerging Players: Indonesia's secondary cities on Java and Sumatra present the most penetrable white space, with pharmacy and minimart channels undersupplied for sports nutrition. Target white-collar commuters in Vietnam's Ho Chi Minh City and Thailand's Bangkok with metro-adjacent convenience store placement. Launch through direct-to-consumer platforms to avoid incumbent-controlled retail gatekeeping, then migrate to physical retail upon volume proof. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale clean-label specialists with established FSANZ or FSSAI compliance track records and proprietary binding technology partnerships. Long-term viability favors brands that have solved the stability-purity trade-off through enzymatic systems rather than preservative dependence. Watch for coordinated Japan-Australia novel protein approvals as inflection signal for insect and algae-based formulation viability.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | FSSAI and SAMR disclosure mandates force ingredient transparency upgrades across imported portfolios. |
| Convenience Store Channel Expansion | Lawson and FamilyMart metro placement captures Shanghai commuter breakfast substitution behavior. |
| Novel Protein Regulatory Alignment | FSANZ-Japan Consumer Affairs Agency coordination accelerates cricket and mealworm flour commercialization. |
| Corporate Wellness Procurement | Seoul and Tokyo technology sector bulk purchasing creates predictable revenue streams for protein suppliers. |
| Airport Retail Premium Positioning | Singapore and Hong Kong aviation hubs accept substantial markups for travel-format nutritional bars. |
Study Parameters
Operator-level perspectives from brand managers, category buyers at Lawson and 7-Eleven, supply planners at nut and dried-fruit processors, and regulatory affairs leads anchored the qualitative base. Primary interviews combined with secondary validation from FSSAI disclosure filings, FSANZ novel food approval registers, SAMR e-commerce enforcement notices, and Nielsen retail audit data. Bottom-up volume modeling and top-down macroeconomic triangulation ensured convergence across estimation approaches.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning product type, ingredient sourcing, distribution channel, and consumer archetype. CAGRs derived from category growth rate decomposition and penetration curve analysis for clean-label adoption. Forecast inputs included corporate wellness program expansion rates, convenience store shelf-space reallocation trends, and regulatory approval timelines for alternative proteins.
The forecast holds incumbent behavior within observed patterns; aggressive moves by direct-to-consumer brands or coordinated regulatory acceleration by Japan and Australia would shift outcomes. Quarterly review of FSSAI enforcement actions, SAMR e-commerce claim scrutiny, and FSANZ novel protein approvals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Saudi Arabia Food & Beverage Market
Beverages
Vegetable Juice Market
Beverages
China Orange Juice Market
Beverages
Adaptogenic Beverages Market
Beverages
Plant Based Beverages Market
Beverages
Beverage Cooler Market
Beverages
United States and Australia Coconut Water Market
Beverages
Italy Bottled Water Market
Beverages
Fruit Beverages Market
Beverages
GCC Sports and Energy Drinks Market
Beverages
Pineapple Juice Market
Beverages
Craft Soda Market
Beverages
Commercial Drink Mixers Market
Beverages
Japan Kombucha Market
Beverages
United States Soy Beverages Market
Beverages
Europe Ready-To-Drink Beverages Market