
 North America Cold Pressed Juices Market | 2026-2036
North America Cold Pressed Juices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cold Pressed Juices Market Analytics
The FDA's updated Nutrition Facts labeling requirements for added sugars is hardening demand for unsweetened, single-ingredient cold pressed juices. Suja Life leverages its organic supply chain to sustain shelf-stable distribution across conventional retail. Pressed Juicery anchors its position through company-owned stores in California and New York. Evolution Fresh competes via Starbucks' licensed channel control, dominating grab-and-go placement in urban centers.
Cold pressed juices are beverages extracted through hydraulic pressure without heat application, typically operating below 85 degrees Fahrenheit to preserve enzymatic activity and nutrient density; this non-thermal process yields juice with extended enzyme viability compared to centrifugal methods. The primary commercial purpose centers on delivering premium, minimally processed nutrition to health-conscious consumers seeking alternatives to pasteurized concentrates. Fruits and blends occupy the largest volume share, though superfood formulations command the strongest per-unit margins due to ingredient scarcity. Online platforms represent the fastest-growing distribution channel, while bottles remain the dominant packaging format despite rising pouch adoption in fitness channels.
The FDA oversees juice safety through Hazard Analysis Critical Control Point requirements, while USDA Organic certification governs premium positioning and pricing authority across the North American supply base. Health Canada and PMRA coordinate cross-border pesticide residue standards that directly determine which California and Florida growers qualify for organic cold pressed supply contracts. Stakeholders must monitor evolving state-level extended producer responsibility laws for beverage packaging, as these frameworks will reshape cost structures and material choices without federal harmonization.
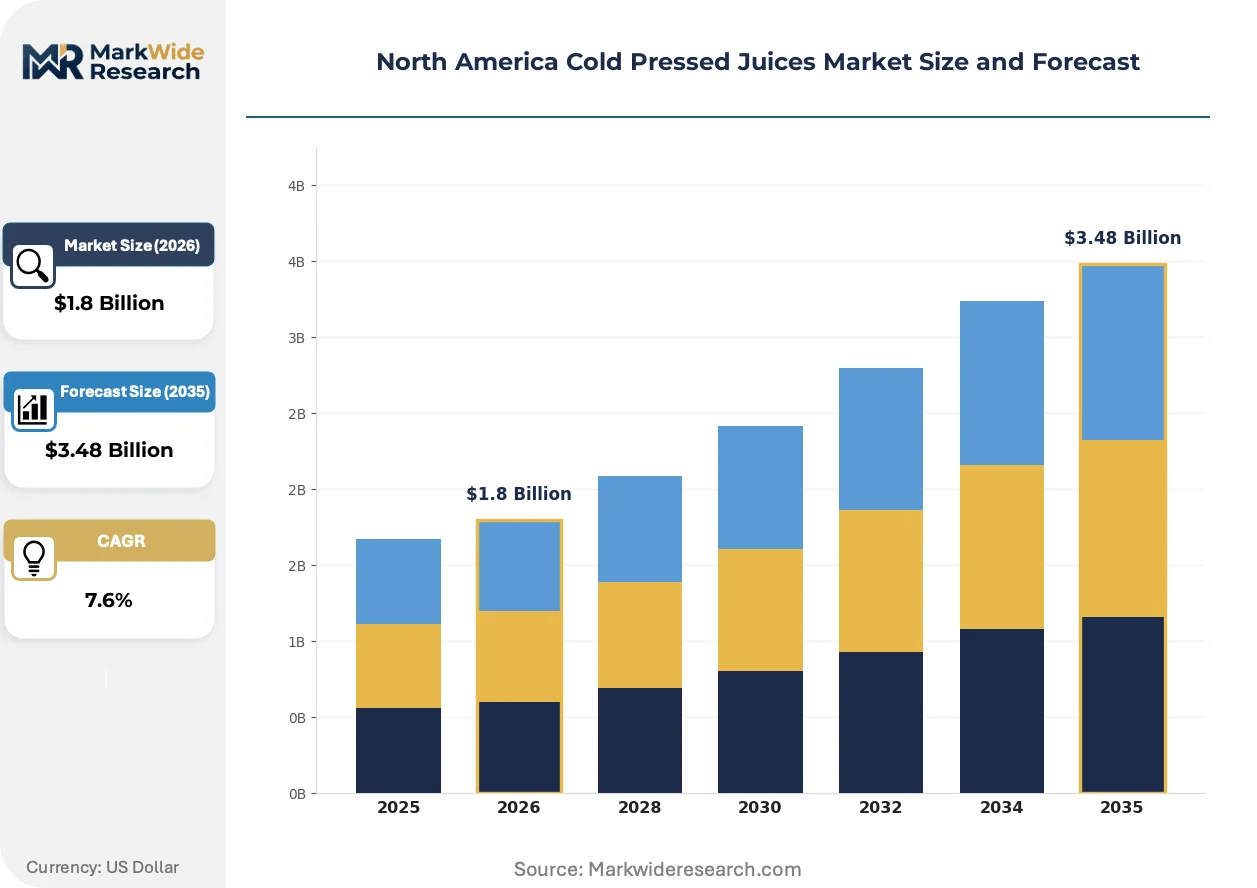
Market Dynamics
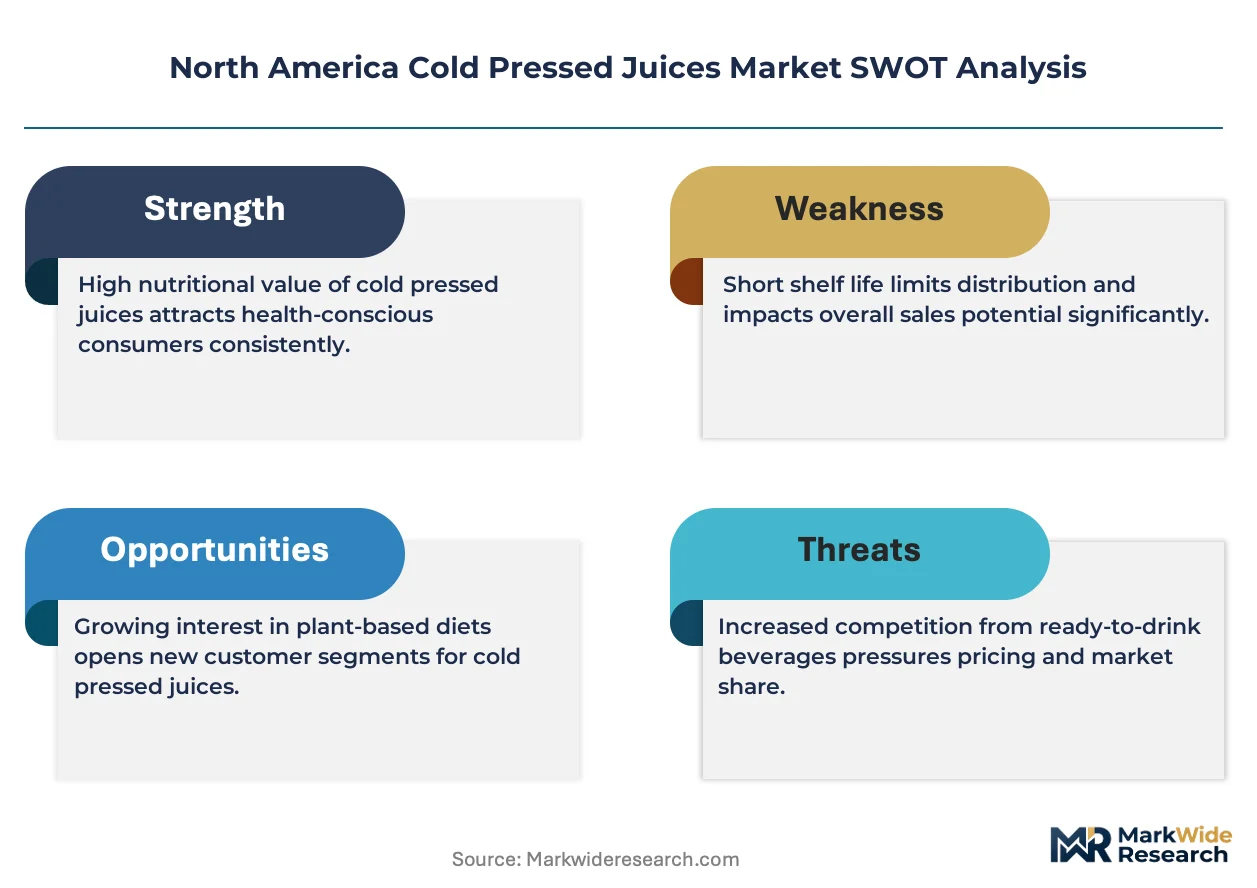
The FDA's updated Nutrition Facts labeling requirements for added sugars is compressing formulation cycles across North American cold pressed juice production, forcing manufacturers to reformulate around single-ingredient positioning and clean-label claims.
Growth Catalysts
- Clean-Label Certification:USDA Organic certification governs premium positioning and pricing authority across California and Florida supply bases. Growers with dual organic-non-GMO verification capture preferential contracting terms.
- Health Canada:Cross-border pesticide residue standards coordinated with PMRA determine which growers qualify for organic cold pressed supply contracts, expanding addressable supply pools.
- High-Pressure Processing:HPP technology extends shelf life without thermal degradation, enabling conventional retail distribution for previously direct-to-consumer brands.
Market Restraints
- Perishable Input Costs:Organic produce price volatility concentrates margin pressure on California-sourced leafy greens and citrus, with weather-driven supply shocks recurring quarterly.
- Cold Chain Concentration:Refrigerated distribution infrastructure clusters in coastal metropolitan corridors, leaving interior North American markets underserved and logistics-cost prohibitive.
- Centrifugal Substitution:Lower-cost pasteurized juices from conventional processing retain price-positioning advantages in mass-market retail, constraining cold pressed penetration.
Strategic Opportunities
- Canadian Market Expansion:Underpenetrated metropolitan markets in Toronto and Vancouver present whitespace for premium wellness retail formats with localized supply partnerships.
- Fitness Channel Innovation:Pouch packaging adoption accelerates in gym and studio channels, replacing bottle formats for on-premise consumption occasions.
- Extended Producer Responsibility:Evolving state-level EPR laws for beverage packaging will reshape material choices, rewarding early movers with compliant rPET and aluminum solutions.
Industry Challenges
- HACCP Compliance Talent:FDA Hazard Analysis Critical Control Point requirements demand specialized food safety personnel, with qualified candidates concentrated in legacy processed food regions rather than emerging cold pressed hubs.
- Organic Certification Timelines:USDA Organic transition periods lock supply contracts for 36 months, constraining rapid scaling for brands seeking to pivot ingredient sourcing.
- Legacy System Integration:ERP platforms from conventional beverage manufacturing require customization for lot-traceability and short-cycle production inherent to cold pressed operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cold Pressed Juices Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Blends, Superfood Distribution Channel: Retail Stores, Online Platforms, Cafes, Gyms Packaging Type: Bottles, Tetra Packs, Pouches, Cans End User: Health Enthusiasts, Fitness Professionals, Busy Professionals, Families |
| Companies Covered | Evolution Fresh, Juice Generation, Pressed Juicery, Greenhouse Juice Co., Organic Avenue, Suja Life, Hain Celestial Group, Village Juicery, PepsiCo Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cold Pressed Juices Market Evolving Landscape
Reformulation around single-ingredient transparency is compressing product development timelines while reshaping competitive positioning across North American cold pressed juice manufacturing.
HPP technology is unifying shelf-stable distribution capabilities with raw nutritional claims. Premium wellness retailers and conventional grocers alike are adopting HPP-treated lines to reduce shrink and expand geographic reach. This convergence is collapsing the historical divide between direct-to-consumer freshness and mass retail accessibility.
The FDA's updated Nutrition Facts labeling requirements for added sugars is hardening formulation standards across North American production. Manufacturers must now substantiate zero-sugar claims through ingredient-level documentation, raising compliance costs for blended formulations. Single-ingredient SKUs in California and New York distribution networks are capturing disproportionate shelf space as a result.
Subscription-based replenishment models are displacing traditional retail stocking patterns among health enthusiasts. Direct-to-consumer platforms with customizable flavor rotations are capturing recurring revenue streams that brick-and-mortar channels struggle to replicate. This shift concentrates highest lifetime-value customers in owned digital ecosystems, particularly in metropolitan California corridors where delivery density optimizes logistics.
North America Cold Pressed Juices Market Segmentation
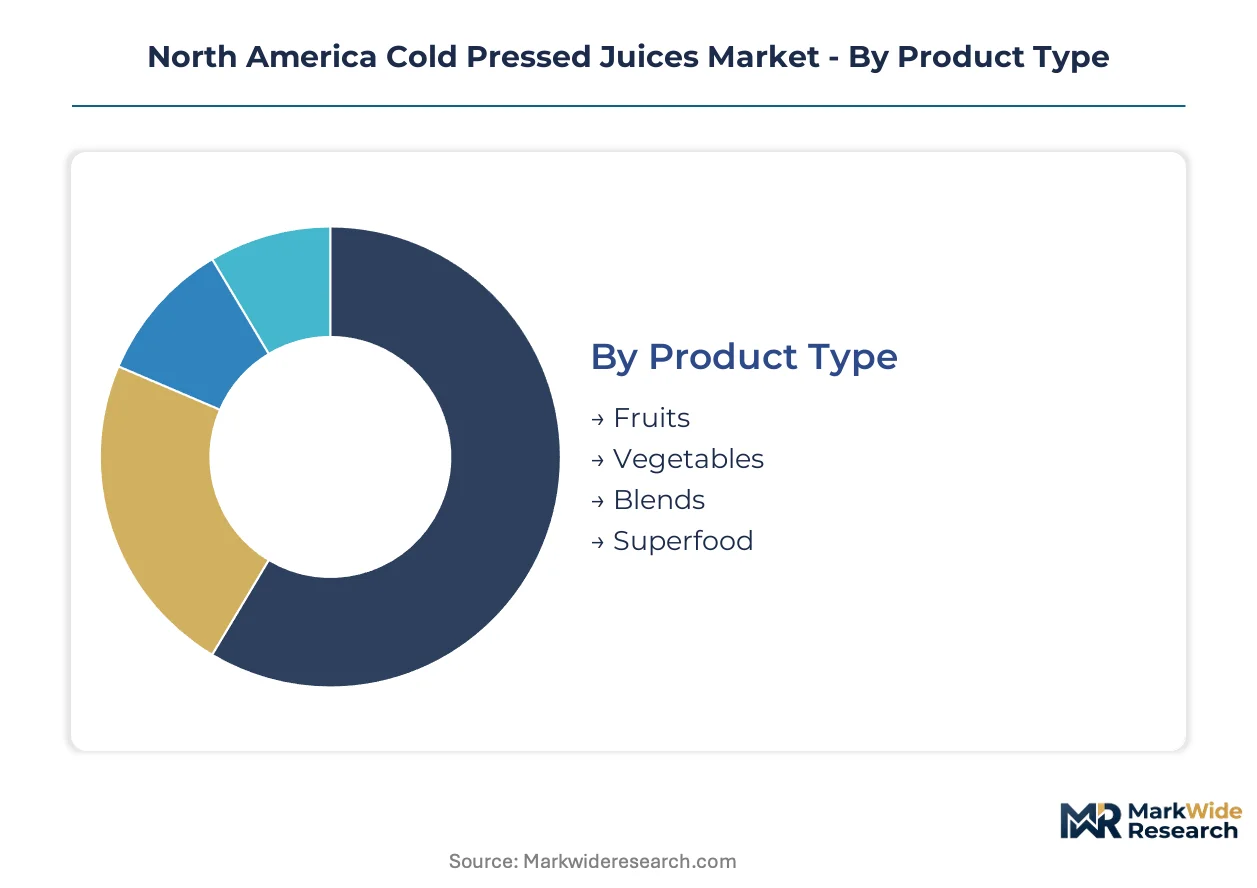
Cold pressed juice manufacturers calibrate product architecture around four distinct segmentation axes. Each dimension governs margin structure, shelf placement, and consumer acquisition economics differently across California, New York, and Toronto metropolitan corridors.
Product Type:
Reformulation cycles accelerate as brands replace legacy blends with cleaner single-ingredient positioning to satisfy label-conscious consumers.
- Fruits:Citrus and apple bases dominate volume throughput due to year-round supply availability from Florida and California growers. Demand concentrates in conventional retail channels across Los Angeles and New York metropolitan areas, where grab-and-go placement drives impulse purchase frequency.
- Blends:Multi-ingredient formulations combine fruits with vegetables for palatability masking, though FDA added-sugar labeling requirements are compressing development timelines for these SKUs. California health enthusiasts represent the core purchasing cohort, with subscription platforms capturing highest retention rates.
- Vegetables:Leafy green concentrates command premium positioning through functional nutrition claims.
- Superfood:Acai, turmeric, and adaptogen infusions target fitness professionals seeking recovery positioning.
Fruits sits at the top of the volume ranking, with Superfood climbing the fastest.
Distribution Channel:
Channel economics diverge sharply between high-touch physical placement and digital recurring revenue models.
- Retail Stores:Conventional grocery and premium wellness retailers anchor mass-market penetration, with HPP-treated lines reducing shrink and enabling geographic expansion beyond coastal corridors. Toronto and Vancouver metropolitan markets show whitespace for format replication.
- Online Platforms:Direct-to-consumer subscription models with customizable flavor rotations are displacing traditional stocking patterns among health enthusiasts. California delivery density optimizes logistics economics for recurring revenue capture.
- Cafes:Licensed placement through coffee chains dominates urban grab-and-go occasions.
- Gyms:On-premise consumption drives pouch format adoption in fitness studio channels.
Retail Stores maintains volume leadership, with Online Platforms gaining share fastest through subscription retention mechanics.
Packaging Type:
Material selection increasingly reflects state-level extended producer responsibility compliance requirements rather than purely cost optimization.
- Bottles:rPET and glass containers remain dominant across conventional retail, though California EPR frameworks are accelerating compliant material transitions. Premium wellness retailers in Los Angeles and San Francisco metropolitan areas favor transparent bottles for visual freshness signaling.
- Pouches:Flexible packaging collapses shipping cube and enables fitness channel placement where glass breakage risk constrains bottle adoption. New York and Chicago gym studio networks are standardizing pouch formats for on-premise consumption.
- Tetra Packs:Aseptic cartons target ambient shelf-stable distribution in underserved interior markets.
- Cans:Aluminum solutions appeal to sustainability-positioned brands seeking EPR-compliant circularity claims.
Bottles holds the volume position, with Pouches expanding most quickly through fitness channel penetration.
End User:
Customer lifetime value stratifies sharply across usage occasion frequency and price elasticity profiles.
- Health Enthusiasts:Daily consumption patterns and subscription platform loyalty generate highest lifetime value, with clean-label certification requirements driving purchase decisions. California and New York metropolitan corridors concentrate this cohort through premium wellness retail density.
- Busy Professionals:Convenience-oriented purchasing favors grab-and-go placement in urban centers, with single-serve bottles capturing commute occasion revenue. Toronto financial district placement mirrors New York and Chicago channel strategies.
- Fitness Professionals:Recovery and performance positioning drives pre/post-workout consumption timing.
- Families:Multi-serve formats and palatability-optimized blends target household replenishment occasions.
Health Enthusiasts commands the highest value concentration, with Busy Professionals showing steepest expansion trajectory through urban channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cold pressed juice production originated in California's wellness corridors during the early 2000s, spreading through coastal metropolitan networks before establishing licensed manufacturing partnerships across the continent.
United States
California's organic agriculture belt supplies the majority of leafy greens and citrus inputs, with Los Angeles and San Francisco metropolitan corridors hosting the densest retail placement. The FDA's updated Nutrition Facts labeling requirements for added sugars is compressing formulation cycles for domestic manufacturers. New York City anchors East Coast distribution, where grab-and-go placement in financial districts drives commuter-oriented consumption patterns.
Canada
Toronto and Vancouver metropolitan markets present underpenetrated whitespace for premium wellness retail formats, with localized supply partnerships emerging through British Columbia's organic greenhouse sector. Health Canada coordinates pesticide residue standards with the PMRA, determining which California and Florida growers qualify for cross-border organic contracts. Cold chain infrastructure gaps in Prairie Provinces constrain interior market penetration, concentrating demand in coastal population centers.
Mexico
Jalisco's citrus belt and Michoacán's avocado groves supply raw material inputs for North American blend formulations, though HACCP-compliant processing capacity remains concentrated near Mexico City. Mexican regulatory alignment with FDA juice safety protocols enables integrated supply chains serving US metropolitan markets. Guadalajara's emerging food processing corridor attracts contract manufacturing investment from California-based brands seeking cost-advantaged production.
North America Cold Pressed Juices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers, with USDA Organic and HPP-treated positioning commanding shelf-space allocation in conventional retail. The vendor base stratifies between vertically integrated California specialists and licensed distribution partners leveraging Starbucks-scale channel control. Three archetypes dominate: direct-to-consumer subscription platforms, conventional retail HPP suppliers, and licensed coffee-chain placement specialists. Competitive moves concentrate on geographic whitespace expansion into Toronto and Vancouver, plus format innovation shifting gym-channel placement from bottles to pouches.
Among California-based organic specialists, Suja Life and Pressed Juicery exemplify divergent channel strategies within the premium tier. Suja Life occupies a position anchored in shelf-stable HPP distribution across conventional grocery networks. Pressed Juicery represents the company-owned retail archetype, with density concentrated in Los Angeles and New York metropolitan corridors. Evolution Fresh sits within the licensed-placement vector, leveraging Starbucks' urban real estate for grab-and-go dominance.
| Leading Market Players |
|---|
| Evolution Fresh |
| Juice Generation |
| Pressed Juicery |
| Greenhouse Juice Co. |
| Organic Avenue |
| Suja Life |
| Hain Celestial Group |
| Village Juicery |
| PepsiCo Inc. |
| Others |
Value Network & Pricing Analysis
Health enthusiast subscription density in California and New York metropolitan corridors anchors the dominant pricing model across North American cold pressed juice production. This buyer concentration enables recurring revenue capture that insulates premium tiers from commodity juice price erosion.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates USDA Organic HPP-treated lines from conventional certified and non-certified alternatives. Price differentiation hinges on organic certification grade and cold chain delivery cost to interior markets. Cost compression in economy tiers is intensifying because centrifugal juice substitution retains mass retail positioning. Busy professionals in urban grab-and-go channels exhibit highest price sensitivity, while health enthusiast subscribers show lowest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from FDA HACCP-compliant processors mandate multi-supplier qualification across California, Florida, and Mexico input bases. Raw material dependencies center on organic leafy greens from California's Central Valley, citrus from Florida and Jalisco, and tropical inputs from Michoacán. Single-source vulnerability concentrates in California organic certification timelines that lock supply contracts for thirty-six months. Distribution runs through refrigerated coastal corridors with conventional retail and direct-to-consumer subscription platforms as dominant downstream structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's updated Nutrition Facts labeling requirements for added sugars functions as a regulatory compounder, hardening demand for single-ingredient positioning that rewards certified supply chain investments.
For Market Incumbents: Deepen backward integration into California organic acreage to defend margin position against weather-driven supply shocks and centrifugal substitution threats. Prioritize HPP capacity addition in underpenetrated Toronto and Vancouver corridors to extend geographic control before new entrants establish localized partnerships. For New Entrants and Emerging Players: Capture whitespace in Canadian metropolitan markets through British Columbia greenhouse supply partnerships and Health Canada-aligned organic certification. Target fitness channel pouch format innovation as the most penetrable segment, leveraging gym studio networks in Chicago and New York with on-premise consumption positioning. For Investors and Strategic Acquirers: Beverage conglomerates seeking wellness portfolio expansion are the most active acquirer in this space, with direct-to-consumer subscription platforms commanding premium multiples. Long-term viability rests on owned digital ecosystems that concentrate highest lifetime-value health enthusiasts. Watch HPP technology cost curves as the inflection signal determining mass retail accessibility.| Strategic Initiative | Industry Significance |
|---|---|
| HPP Technology Deployment | Extends shelf-stable distribution for raw nutritional claims across conventional retail networks. |
| Canadian Market Entry | Opens underpenetrated Toronto and Vancouver corridors through Health Canada-aligned supply partnerships. |
| Subscription Platform Buildout | Concentrates highest lifetime-value health enthusiasts in owned digital ecosystems with recurring revenue. |
| Pouch Format Innovation | Captures fitness channel placement in New York and Chicago gym studio networks. |
| Organic Certification Investment | Secures USDA Organic positioning that governs premium shelf-space allocation in California retail. |
Research Methodology
Direct dialogue with cold pressed juice brand executives, organic supply chain managers, FDA regulatory affairs specialists, and premium wellness retail category buyers grounds the qualitative foundation. Secondary validation draws from FDA juice safety filings, USDA organic certification databases, Nielsen retail audit data, and Health Canada pesticide residue standards. Bottom-up and top-down triangulation cross-checks volume assumptions across production facility capacities and channel-level sell-through patterns.
Bottom-up modeling builds from individual SKU economics across product type, distribution channel, packaging format, and end user segments, while top-down analysis cross-references category spending patterns in metropolitan corridors. CAGRs derive from segment-level growth rate blending across the projection horizon. Industry-specific forecast inputs include organic produce price volatility indices and HPP technology penetration curves in conventional retail.
Organic supply shocks, FDA labeling requirement enforcement intensity, and cold chain infrastructure expansion delays are the dominant revision risks to the outlook. Deviation in California weather-driven input cost spikes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Water Bottle Market
Beverages
Growlers Market
Beverages
Craft Soda Market
Beverages
Bubble Food and Beverages Market
Beverages
Hot Chocolate Market
Beverages
Drinking Bottled Mineral Water Market
Beverages
Still Drinks Market
Beverages
Hydrogen Water Bottle Market
Beverages
Soft Serve Premix Market
Beverages
Mixers Market
Beverages
Collagen Drinks Market
Beverages
Ready-To-Drink (RTD) Beverages Market
Beverages
Fruit Water Market
Beverages
Whole Grain Drinks Market
Beverages
Asia Pacific Soy Beverages Market
Beverages
Hot Beverages Market