
 Relaxation Beverages Market | 2026-2036
Relaxation Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Relaxation Beverages Market Insights
Aftermarket subscription revenue is reconfiguring how beverage brands monetize recurring consumer relationships. Neurobrands LLC leverages direct-to-consumer replenishment models to sustain repeat purchase rates. TranQuini anchors its European presence through pharmacy channel partnerships. Recess differentiates via lifestyle-oriented branding that occupies premium shelf space in specialty retailers.
Relaxation beverages comprise non-alcoholic drinks formulated with adaptogens, botanical extracts, amino acids, or hemp-derived compounds designed to reduce stress response and promote calm without sedation. Manufacturing typically involves cold-brew extraction of L-theanine, ashwagandha, or GABA at sub-boiling temperatures to preserve bioactive integrity. Functional drinks and CBD infused variants command expanding shelf allocations as retailers chase margin premiums over conventional soft drinks. Ready-to-Drink formats lead volume through convenience positioning, though powder concentrates attract fitness enthusiasts seeking portable dosing control.
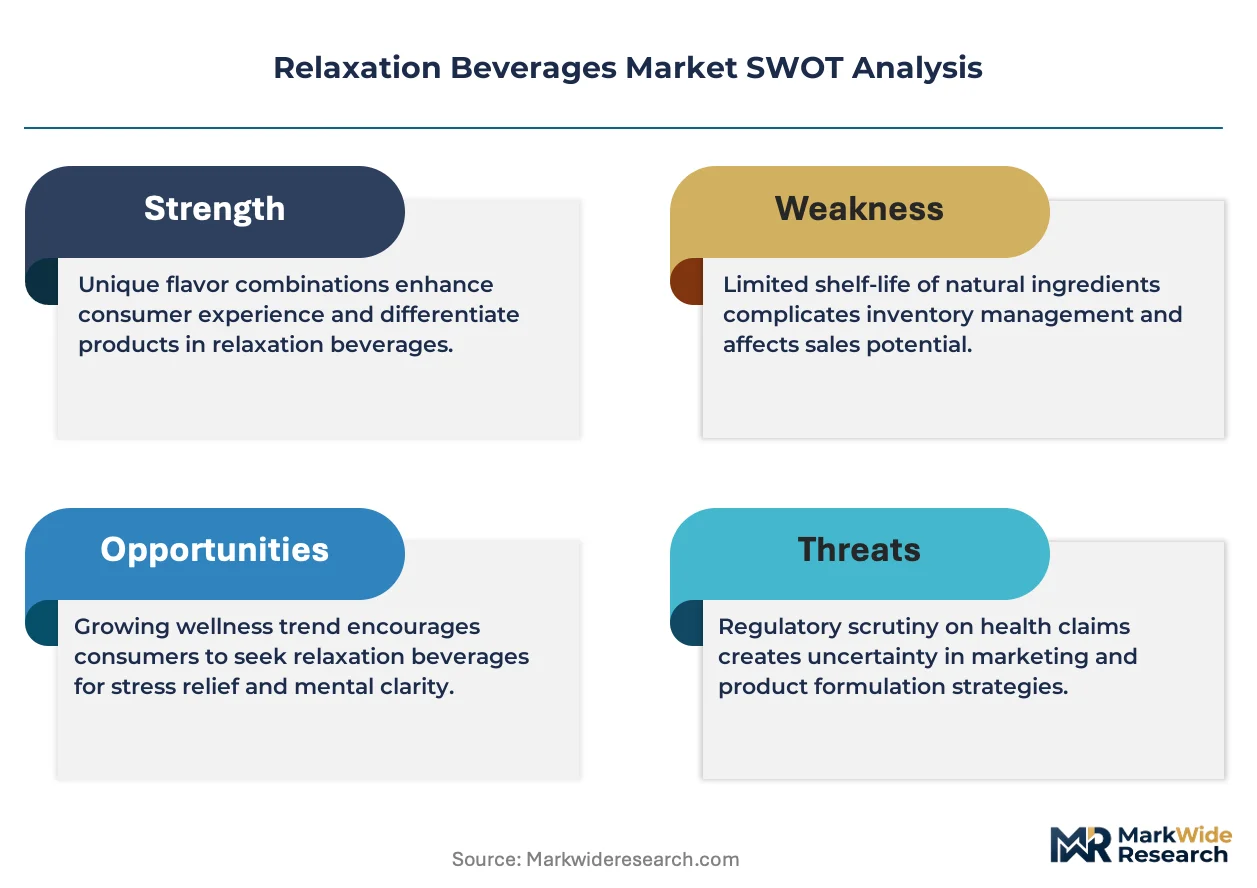
The FDA exercises oversight of new dietary ingredient notifications under DSHEA, while EFSA evaluates novel food safety dossiers for European market entry. Both frameworks elevate compliance costs for startups but also screen out unsubstantiated anxiety-relief claims that would erode consumer trust. Stakeholders must monitor evolving cannabinoid scheduling decisions and adaptogen GRAS status determinations that could abruptly expand or contract addressable formulation space.
Market Dynamics
Corporate wellness programs now mandate functional beverage provisioning for employee stress management, converting employer procurement budgets into a demand anchor that reduces price sensitivity and stabilizes volume commitments for suppliers.
Growth Catalysts
- DSHEA notification pathways:The FDA's clarified new dietary ingredient procedures reduce entry uncertainty for adaptogen formulations, accelerating time-to-market for L-theanine and ashwagandha SKUs.
- Pharmacy channel expansion:European retailers are carving dedicated shelf space for functional drinks, with EFSA novel food approvals enabling cross-border distribution of hemp-derived compounds.
- Employer wellness subsidies:US corporations now classify relaxation beverages as reimbursable wellness expenses, creating institutional demand that insulates producers from consumer discretionary volatility.
Market Restraints
- Raw material concentration:Organic ashwagandha supply concentrates in Madhya Pradesh and Karnataka, exposing formulators to monsoon-dependent harvest volatility and quality inconsistency.
- EFSA novel food dossier costs:Safety substantiation requirements for botanical extracts impose six-figure compliance burdens that exclude capital-constrained entrants from European distribution.
- Non-alcoholic craft alternatives:Sophisticated zero-proof spirits and hop waters compete for identical consumption occasions, fragmenting shelf space and marketing attention in premium retail.
Strategic Opportunities
- German pharmacy network penetration:Apotheke channel partnerships offer margin premiums and clinician endorsement credibility unavailable in mass retail, with reimbursement discussions advancing for stress-management positioning.
- Cold-brew GABA extraction:Sub-boiling temperature protocols preserve bioactive integrity superior to conventional heat processing, enabling premium positioning around efficacy substantiation.
- Direct-to-clinic sampling:Healthcare practitioner education programs convert prescriptive authority into trial generation, bypassing conventional advertising restrictions on anxiety-related claims.
Industry Challenges
- GRAS self-determination complexity:FDA enforcement discretion on adaptogen status creates liability exposure for brands marketing pre-DSHEA ingredients without formal notification.
- Cannabinoid scheduling uncertainty:DEA and state-level hemp derivative classifications require formulation flexibility and geographic SKU fragmentation that complicates supply chain planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Relaxation Beverages Market |
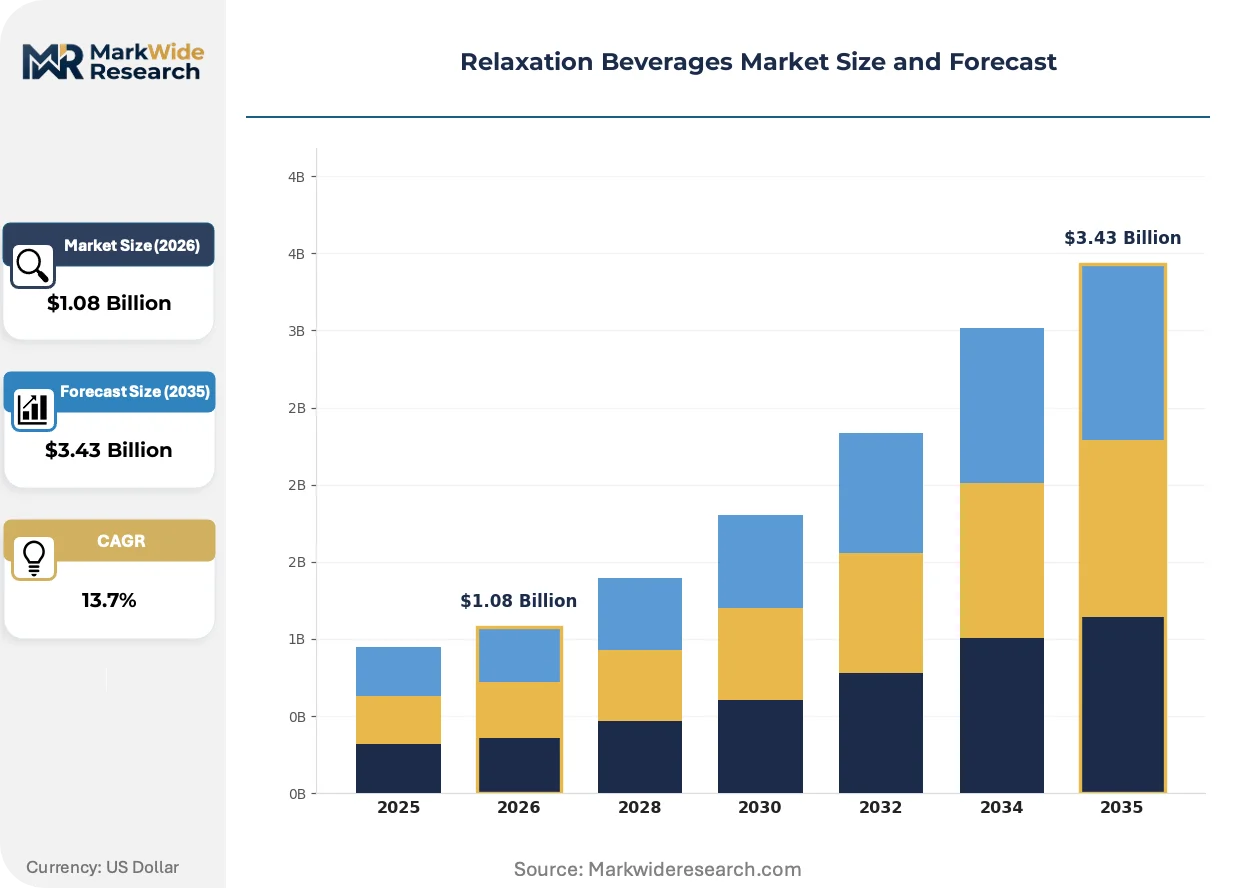
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $3.43 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbal Teas, CBD Infused, Functional Drinks, Ready-to-Drink Consumer Type: Health-Conscious, Millennials, Working Professionals, Fitness Enthusiasts Distribution Channel: Supermarkets, Health Stores, E-commerce, Specialty Shops Formulation: Liquid, Powder, Concentrate, Tablet |
| Companies Covered | The Coca-Cola Company, Neurobrands LLC, CENTR Brands Corp., Herbalife International of America Inc., TranQuini, Chillbev, Slow Cow, Som Sleep, Recess, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Relaxation Beverages Market Trends and Innovations
Formulation science is converging with behavioral health positioning, as brands abandon sedative associations in favor of stress-resilience narratives that align with performance culture rather than retreat.
Microencapsulation technology for lipid-soluble adaptogens is migrating from pharmaceutical applications into beverage manufacturing, enabling stable dispersion of ashwagandha and CBD in aqueous matrices without emulsion separation. Sports nutrition brands are adopting these delivery systems fastest, compressing the traditional supplement-to-beverage adoption cycle from years to months.
EFSA's tightened novel food safety dossier requirements are forcing reformulation of legacy botanical extracts that previously entered under mutual recognition. Industrial consequence includes abandonment of certain Ayurvedic ingredients by risk-averse multinationals, while specialized consultancies profit from dossier preparation services. German and Dutch regulators are applying the strictest interpretive standards, creating a two-speed European market.
Subscription replenishment models are displacing conventional retail trial-and-repeat cycles, with direct-to-consumer platforms capturing consumption data that enables predictive flavor and efficacy personalization. Fitness enthusiasts and remote workers represent the densest subscriber concentrations, with urban coastal markets showing highest retention rates and lowest churn sensitivity to price adjustments.
Relaxation Beverages Market Segmentation
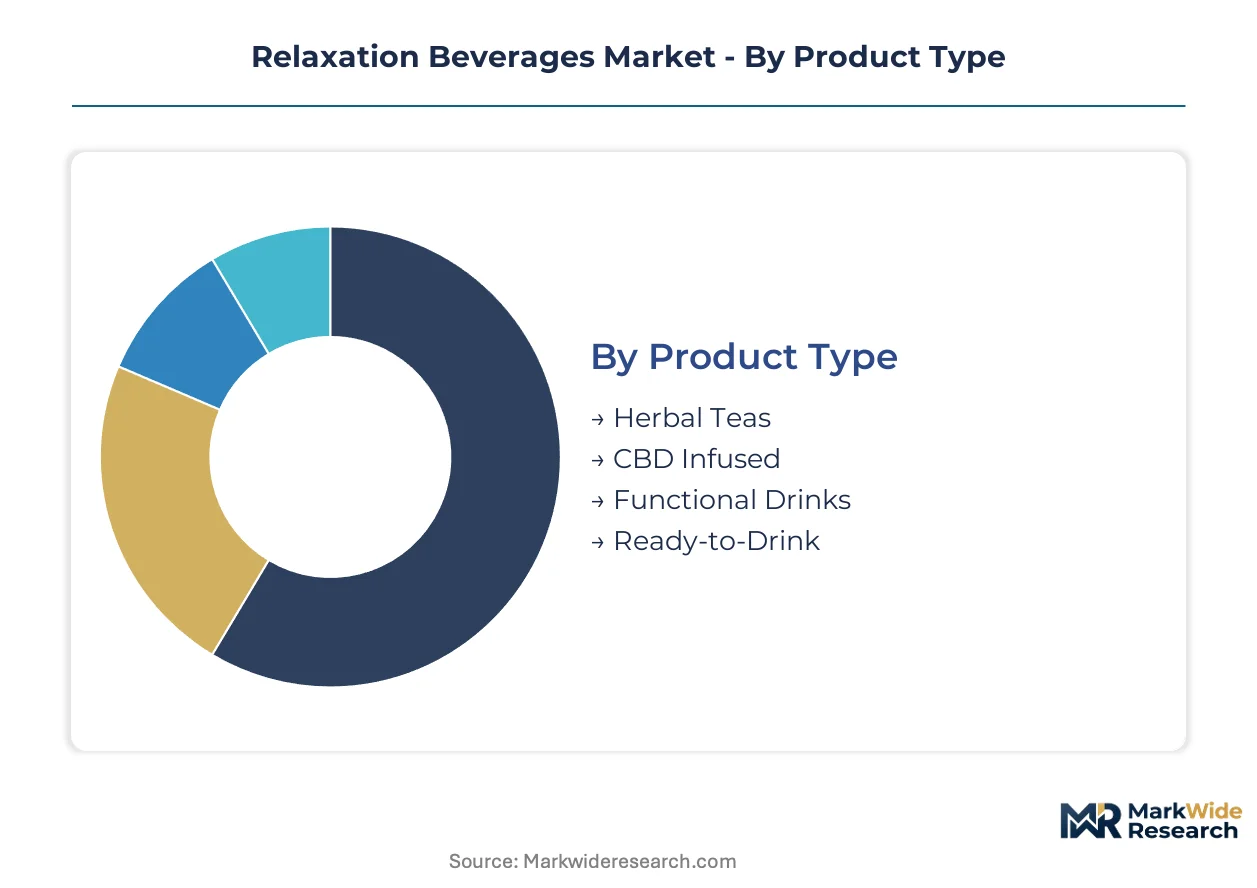
Relaxation beverages fragment across four distinct category axes, each commanding different margin profiles and channel strategies. Product type and consumer segmentation drive formulation priorities, while distribution and format choices determine capital intensity and geographic reach.
Product Type:
Mature formats coexist with emerging entrants across the maturity spectrum, creating tiered pricing architecture from commodity herbal infusions to premium functional positioning.
- Herbal Teas:Camomile, valerian root, and passionflower formulations steeped at sub-boiling temperatures to preserve volatile terpenes. Demand concentrates in German pharmacy networks where Apotheke partnerships confer clinical credibility and margin premiums unavailable in mass retail.
- CBD Infused:Hemp-derived cannabinoid beverages face scheduling fragmentation across US state jurisdictions and EFSA novel food dossier requirements in Europe. California and Colorado anchor North American volume despite federal ambiguity, while Dutch regulators apply strictest interpretive standards for cross-border distribution.
- Functional Drinks:Adaptogen-forward formulations with ashwagandha, L-theanine, or GABA target stress-resilience positioning. Corporate wellness programs in US metropolitan markets drive institutional procurement.
- Ready-to-Drink:Single-serve convenience formats dominate refrigerator case allocation in specialty retailers and urban convenience channels.
Ready-to-Drink retains volume leadership; CBD Infused holds the steepest expansion curve.
Consumer Type:
Cost tier stratification separates premium wellness seekers from price-sensitive mass market entrants, with employer subsidy programs blurring traditional sensitivity boundaries.
- Health-Conscious:Ingredient transparency demands drive organic certification requirements and clean-label formulation. E-commerce subscription retention rates run highest among this cohort.
- Millennials:Lifestyle-oriented branding and social media discovery patterns concentrate trial generation. Urban coastal markets show lowest churn sensitivity to price adjustments.
- Working Professionals:Employer wellness subsidies convert this segment into institutional demand anchor. US corporations now classify relaxation beverages as reimbursable wellness expenses.
- Fitness Enthusiasts:Powder concentrates attract portable dosing preferences. Sports nutrition brands adopt microencapsulation technology fastest, compressing supplement-to-beverage adoption cycles.
Working Professionals command institutional procurement volume; Fitness Enthusiasts generate the highest subscription renewal velocity.
Distribution Channel:
Channel selection determines margin capture versus reach tradeoffs, with pharmacy and specialty retail conferring endorsement credibility that mass retail cannot replicate.
- Supermarkets:Mainstream shelf space competition with conventional soft drinks and non-alcoholic craft alternatives. Slotting fees and promotional spending requirements exclude capital-constrained entrants.
- Health Stores:Staff recommendation authority and educated consumer base support premium pricing. GNC and Vitamin Shoppe equivalents concentrate fitness-oriented SKUs.
- E-commerce:Direct-to-consumer replenishment models capture consumption data enabling predictive personalization. Neurobrands LLC leverages subscription infrastructure to sustain repeat purchase rates.
- Specialty Shops:Curated assortment and lifestyle positioning occupy premium shelf space. Recess anchors presence through aesthetic differentiation and urban retail density.
E-commerce expands most quickly; Health Stores defend the highest margin structure.
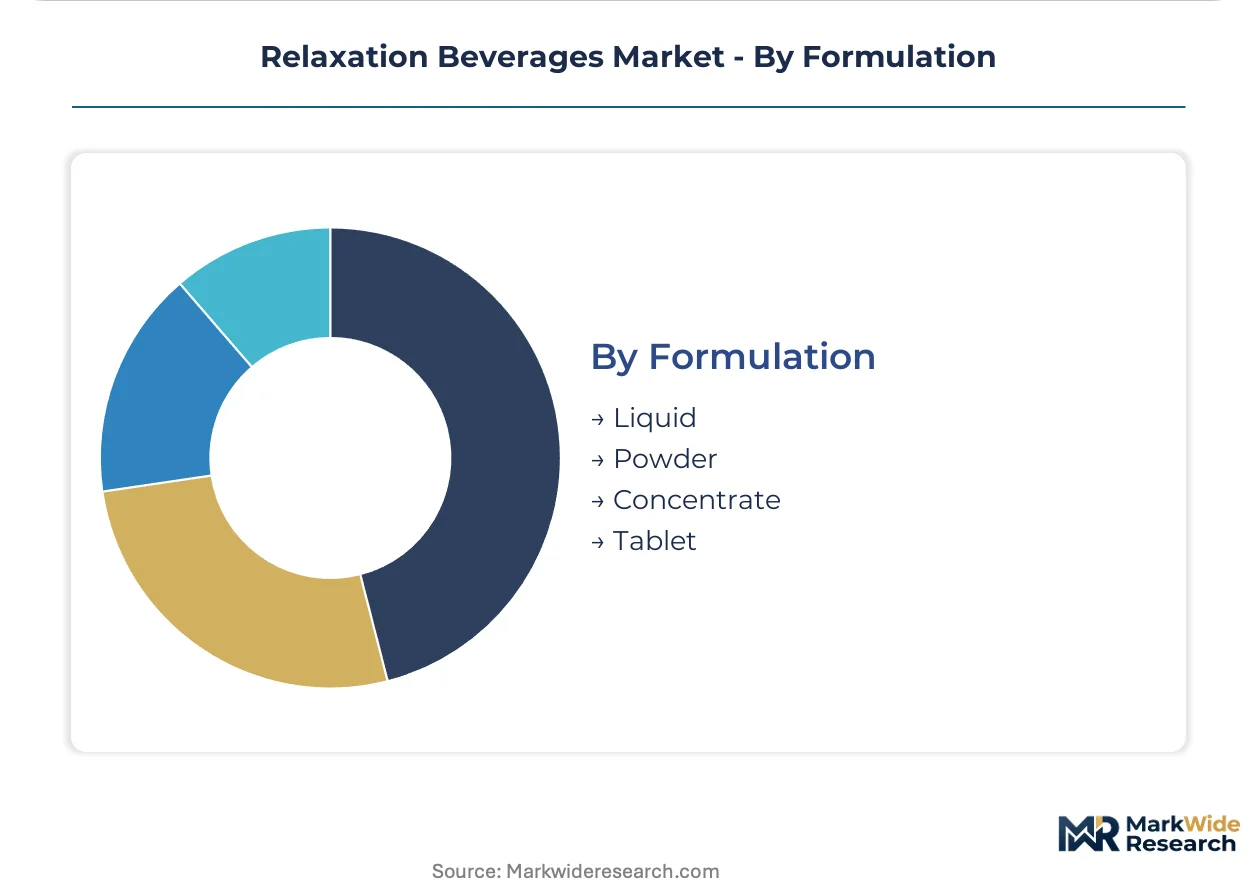
Formulation:
Volume and portability requirements segment manufacturing capital intensity, with liquid formats demanding cold-chain infrastructure that powder alternatives circumvent.
- Liquid:Ready-to-consume aqueous matrices requiring emulsion stability for lipid-soluble actives. Cold-brew extraction protocols preserve bioactive integrity superior to heat processing.
- Powder:Portable dosing control attracts fitness and remote worker segments. Microencapsulation enables stable dispersion of ashwagandha and CBD without separation.
- Concentrate:Dilution-flexible formats reduce shipping weight and storage footprint. Foodservice and workplace dispensing applications concentrate demand.
- Tablet:Supplement-adjacent positioning bridges beverage and nutraceutical categories. Pharmacy channel placement aligns with clinician endorsement strategies.
Liquid dominates absolute volume; Powder gains share fastest through fitness channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employer wellness subsidies in the United States render buyers least price-sensitive, while mass-market consumers in emerging markets exhibit highest elasticity to premium positioning. European pharmacy channels sustain margin premiums through clinical endorsement credibility. Asian markets fragment between traditional herbal consumption patterns and Western functional drink adoption.
United States
Corporate wellness programs drive institutional procurement volume across metropolitan coastal markets. FDA DSHEA notification pathways clarify entry requirements for adaptogen formulations. Austin and Los Angeles anchor startup brand density, with direct-to-consumer subscription infrastructure concentrated in these urban clusters.
Germany
Apotheke channel partnerships confer reimbursement discussions and clinician endorsement credibility unavailable in mass retail. EFSA novel food dossier requirements apply strictest interpretive standards for botanical extract approvals. Bavaria and North Rhine-Westphalia concentrate manufacturing capacity for cold-brew extraction protocols.
Netherlands
Cross-border distribution hubs serve EFSA-approved hemp-derived compounds throughout the European Union. Dutch regulators apply stringent safety substantiation requirements that exclude capital-constrained entrants. Amsterdam anchors logistics infrastructure for pharmacy channel penetration into adjacent markets.
United Kingdom
Health-conscious consumers drive organic certification requirements and clean-label formulation demand. Post-Brexit regulatory divergence from EFSA frameworks creates parallel compliance obligations for botanical extracts. London concentrates specialty retail presence and subscription platform headquarters.
Canada
Federal cannabis framework permits CBD-infused beverage distribution through provincial liquor boards. Health Canada and PMRA oversight applies to novel ingredient safety assessments. British Columbia and Ontario anchor production capacity for hemp-derived formulation variants.
Relaxation Beverages Market Competitive Landscape
Capability concentration sits with specialized adaptogen formulators; scale advantage sits with diversified beverage conglomerates. The market structures around three tiers: multinational soft drink portfolios, dedicated functional wellness brands, and emerging direct-to-consumer specialists. Strategic moves center on pharmacy channel partnerships and subscription infrastructure acquisition. Cold-brew extraction technology licensing and European novel food dossier capabilities represent contested capability domains.
Within the direct-to-consumer specialist tier, Neurobrands LLC exemplifies subscription replenishment model execution, while Recess occupies lifestyle-oriented positioning in premium specialty retail. TranQuini anchors European pharmacy channel penetration. These three represent distinct archetypes: technology-enabled recurring revenue, aesthetic-driven urban retail presence, and clinical endorsement credibility through Apotheke partnerships.
| Leading Market Players |
|---|
| The Coca-Cola Company |
| Neurobrands LLC |
| CENTR Brands Corp. |
| Herbalife International of America Inc. |
| TranQuini |
| Chillbev |
| Slow Cow |
| Som Sleep |
| Recess |
| Others |
Pricing and Supply Chain Analysis
Madhya Pradesh and Karnataka anchor global organic ashwagandha supply, with monsoon-dependent harvest cycles transmitting volatility directly into formulation costs for adaptogen-forward SKUs. Cold-brew extraction facilities in Bavaria and North Rhine-Westphalia command premium contract pricing due to limited GABA-preservation capacity, while employer wellness subsidies in US metropolitan markets insulate branded producers from consumer discretionary compression.
Pricing Analysis
Aftermarket subscription revenue drives lifetime value, with direct-to-consumer replenishment models capturing consumption data that enables predictive personalization. Three-tier pricing structure across premium, standard, and economy levels separates pharmacy-endorsed functional drinks from mass-market herbal teas and private-label concentrates. Pricing pressure stems from non-alcoholic craft alternatives fragmenting shelf space and marketing attention in premium retail. Working professionals receiving employer wellness subsidies exhibit lowest price sensitivity; fitness enthusiasts purchasing powder concentrates show highest elasticity to premium positioning.
Supply Chain Analysis
Supplier-financing facilities extended by German and Dutch logistics hubs enable cross-border distribution of EFSA-approved hemp-derived compounds. Raw material sourcing concentrates in India for organic ashwagandha, the Netherlands for hemp-derived CBD, and Germany for cold-brew extraction equipment. Formulation rests on L-theanine from Chinese suppliers, GABA precursors from Japanese fermentation specialists, and microencapsulation technology licensed from pharmaceutical applications. Single-source vulnerability in Madhya Pradesh monsoon exposure creates harvest quality inconsistency. Distribution runs through pharmacy channel partnerships in Germany, direct-to-consumer platforms in US coastal markets, and specialty retail networks in London and Amsterdam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation science capabilities sit in scarce supply relative to brand proliferation, with cold-brew extraction protocols and EFSA novel food dossier expertise concentrated among specialized consultancies rather than scaled beverage conglomerates.
For Market Incumbents: Pre-empt subscription infrastructure acquisition before direct-to-consumer platforms consolidate consumption data advantages. Secure backward integration into organic ashwagandha cultivation in Karnataka to defend against harvest volatility and quality inconsistency. Acquire cold-brew GABA extraction licensing to preserve bioactive integrity claims against heat-processed competitors. For New Entrants and Emerging Players: Establish a beachhead in German Apotheke channel partnerships where clinician endorsement credibility commands margin premiums unavailable in mass retail. Target fitness enthusiasts seeking portable powder concentrates with microencapsulation-enabled stable dispersion. Pursue direct-to-clinic sampling programs that convert prescriptive authority into trial generation while bypassing advertising restrictions on anxiety-related claims. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because subscription replenishment models are displacing conventional retail trial-and-repeat cycles across urban coastal markets. Acquisition target archetype: direct-to-consumer platforms with predictive personalization engines and lowest churn sensitivity to price adjustments. Watch DEA and state-level hemp derivative scheduling decisions as the primary inflection indicator for formulation flexibility and geographic SKU fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacy Channel Partnership | Apotheke placement in Germany confers clinician endorsement credibility and reimbursement discussions. |
| Subscription Infrastructure Acquisition | Direct-to-consumer platforms capture consumption data enabling predictive flavor and efficacy personalization. |
| Cold-Brew Extraction Licensing | Sub-boiling temperature protocols preserve bioactive integrity superior to conventional heat processing. |
| Backward Integration into Cultivation | In-house organic ashwagandha production in Karnataka reduces monsoon-dependent harvest volatility exposure. |
| EFSA Novel Food Dossier Investment | Safety substantiation capabilities unlock cross-border distribution of hemp-derived compounds throughout the European Union. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with formulation scientists, pharmacy channel buyers, corporate wellness program managers, and direct-to-consumer platform operators; and secondary validation through FDA DSHEA notification records, EFSA novel food safety dossiers, customs trade data for adaptogen imports, and Nielsen retail audit data for functional beverage shelf allocations. Bottom-up SKU-level volume builds were triangulated against top-down category expenditure estimates.
Forecast inputs across the analysis window incorporated product type segmentation by maturity spectrum, consumer type stratification by cost tier, distribution channel margin capture tradeoffs, and formulation capital intensity requirements. CAGRs were derived from segment-level growth trajectory modeling. Industry-specific inputs included employer wellness subsidy expansion rates, EFSA novel food approval timelines, and cannabinoid scheduling decision probabilities.
Stress conditions across monsoon harvest variability, DEA hemp derivative reclassification, and EFSA interpretive standard tightening were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions documented in segmentation and regional frameworks. Macroeconomic recession compressing employer wellness budgets, abrupt cannabinoid scheduling shifts, or adaptogen GRAS status revocation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
North America Kombucha Market
Beverages
Recovery Drinks Market
Beverages
China Soy Beverages Market
Beverages
Yerba Mate Market
Beverages
Europe Yerba Mate Market
Beverages
Semillon Market
Beverages
Japan Kombucha Market
Beverages
Aloe Vera-Based Drink Market
Beverages
Birch Water Market
Beverages
United Kingdom Energy Drink Market
Beverages
Caffeinated Beverage Market
Beverages
Ready to Drink Premixes Market
Beverages
Asia Pacific Soy Beverages Market
Beverages
Soy Drinks Market
Beverages
South America Mate Market
Beverages
Chocolate Malt Drink Market