
 China Orange Juice Market | 2026-2036
China Orange Juice Market Size, Share, and Industry Trends Forecast 2026-2036
China Orange Juice Market Analysis
Young urban professionals are reorganizing demand within the China orange juice category, displacing traditional household bulk purchasing with premium single-serve formats. China Huiyuan Juice Group Limited leverages its established cold-chain infrastructure to dominate modern trade channels. Cofco Tunhe Co., Ltd. anchors industrial concentrate supply to downstream beverage manufacturers. Hunan Sanhe Food Co., Ltd. differentiates through citrus sourcing partnerships in Xiangxi growing belts.
China orange juice comprises the expressed and processed liquid extract of Citrus sinensis, typically standardized to Brix levels between 11.3 and 12.5 degrees for single-strength retail products and preserved through pasteurization or aseptic processing to maintain shelf stability for commercial distribution. Not-from-concentrate products command widening margin pools as consumers trade up from reconstituted alternatives, while organic certification remains structurally constrained by limited domestic citrus acreage meeting conversion standards. Online retailers represent the fastest-growing distribution vector, though supermarkets still control the majority of volume throughput in lower-tier cities.
SAMR nutrition labeling enforcement and GB standards for fruit juice content thresholds shape product formulation decisions, with the national food safety regulator tightening purity requirements that disadvantage diluted or compound beverages. MEE environmental compliance obligations for processing wastewater and citrus peel waste disposal add operational cost layers concentrated in Guangxi and Jiangxi production zones. Stakeholders must monitor evolving organic certification pathways under revised national standards and assess whether cold-pressed processing investments align with emerging channel preferences.
Market Dynamics
SAMR nutrition labeling enforcement is compressing formulation margins for diluted beverage producers while accelerating premium not-from-concentrate adoption among label-conscious urban buyers in the Yangtze River Delta corridor.
Growth Catalysts
- GB Standards Purity Thresholds:SAMR's tightened fruit juice content requirements under revised national food safety standards are disqualifying compound beverages from shelf positioning, clearing channel space for single-strength products.
- Cold-Chain Infrastructure Maturation:Temperature-controlled logistics networks extending into lower-tier cities are enabling pasteurized not-from-concentrate distribution beyond traditional metropolitan cores.
- Urban Professional Consumption Clustering:Young professionals in Shanghai and Beijing are consolidating purchasing power around premium single-serve formats, displacing household bulk buying patterns.
Market Restraints
- Organic Certification Scarcity:Limited domestic citrus acreage meeting national organic conversion standards constrains supply expansion for certified premium positioning.
- Guangxi-Jiangxi Production Concentration:MEE environmental compliance obligations for wastewater and peel waste disposal are concentrated in these processing zones, creating regional cost asymmetries.
- Concentrate Price Volatility:Industrial orange concentrate input costs fluctuate with Brazilian and Florida crop cycles, pressuring margin stability for reconstituted product lines.
Strategic Opportunities
- Xiangxi Sourcing Partnerships:Citrus belt alliances in Hunan's western growing regions offer traceability narratives for premium brand differentiation.
- Online Retail Channel Expansion:E-commerce platforms represent underexploited penetration vectors in tier-three and tier-four cities where supermarket coverage remains thin.
- Cold-Pressed Processing Investment:Aseptic cold-press technology convergence with extended shelf-life packaging is opening chilled distribution pathways previously reserved for heat-pasteurized alternatives.
Industry Challenges
- Dual Carbon Goal Compliance:MEE carbon intensity benchmarks for food processing operations are forcing capital-intensive retrofitting of thermal pasteurization lines.
- Revised Organic Certification Pathways:Transition timelines under updated national organic standards are extending supplier qualification periods, constraining new product launch velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Orange Juice Market |
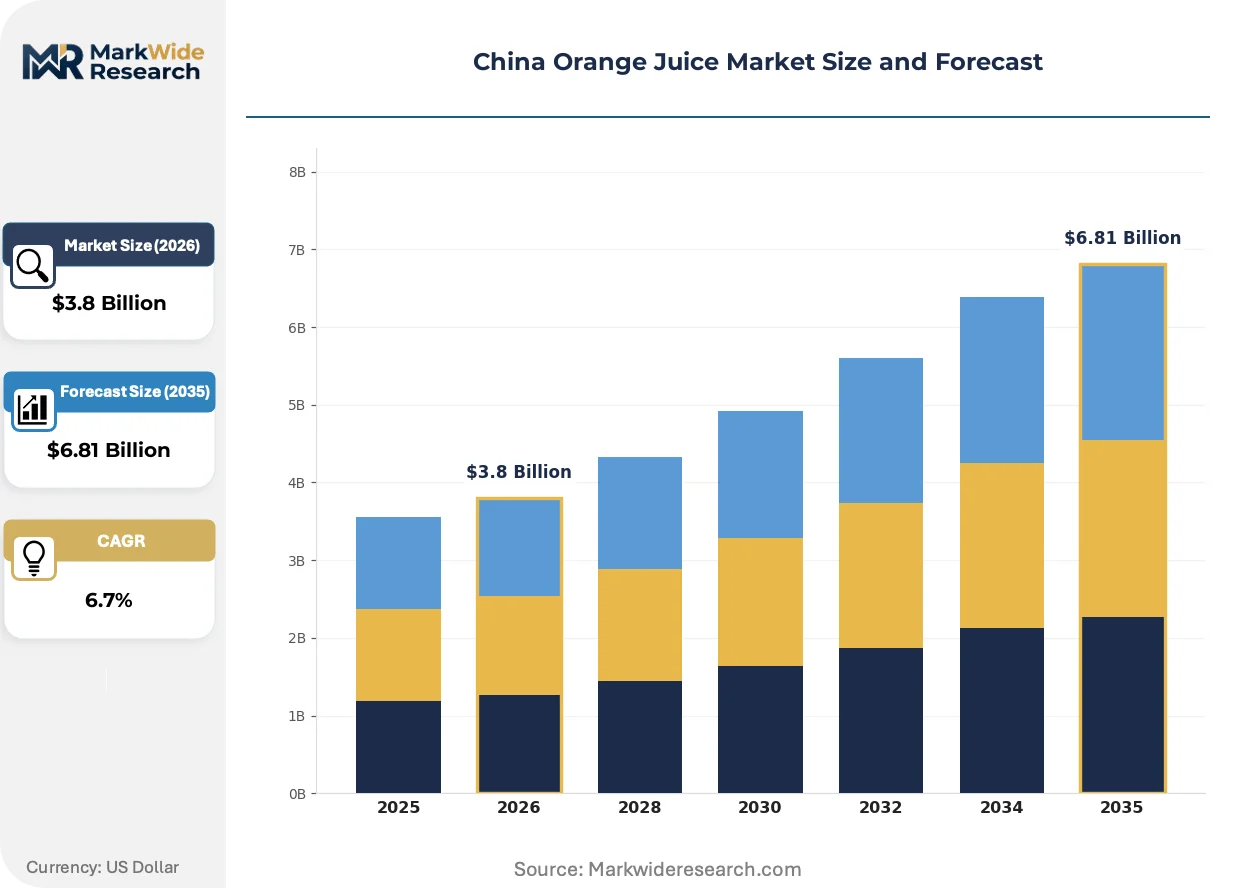
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Not From Concentrate, Organic, Frozen Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Direct Sales Packaging Type: Bottles, Cartons, Cans, Pouches End User: Households, Restaurants, Cafes, Hotels |
| Companies Covered | Hunan Sanhe Food Co., Ltd., Chongqing Tianrun Cifu Co., Ltd., China Haisheng Juice Holdings Co., Ltd., Jiangxi Tianyu Fruit & Vegetable Juice Co., Ltd., Guangxi State Farms Mingyang Biochemical Group, Zhongke Health Industry Group Co., Ltd., Sichuan Guodong Food Co., Ltd., China Huiyuan Juice Group Limited, Cofco Tunhe Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Orange Juice Market Emerging Trajectories
Processing technology and regulatory disclosure requirements are compressing traditional product hierarchies while channel fragmentation creates new entry points for specialized formats.
Aseptic cold-press systems are miniaturizing. Equipment manufacturers are deploying compact modular units that reduce facility footprint requirements for mid-scale processors. Regional bottlers in Jiangsu and Zhejiang are adopting these systems at accelerating rates. The technology is miniaturizing capital barriers that previously concentrated premium processing capacity among national-scale players.
SAMR refined nutrition labeling standards are mandating ingredient disclosure granularity that exposes dilution ratios and additive content. Domestic packaged beverage producers face reformulation costs or shelf repositioning. Premium not-from-concentrate lines are capturing displaced volume as compound beverages lose label credibility.
Urban professional buyers are consolidating purchasing around traceability-verified single-serve formats. Supermarket bulk channels in lower-tier cities are losing volume share to subscription-based online delivery models. Shanghai and Beijing demonstrate the sharpest channel pivot, with cold-chain-enabled direct-to-consumer platforms displacing traditional retail intermediation.
China Orange Juice Market Segmentation
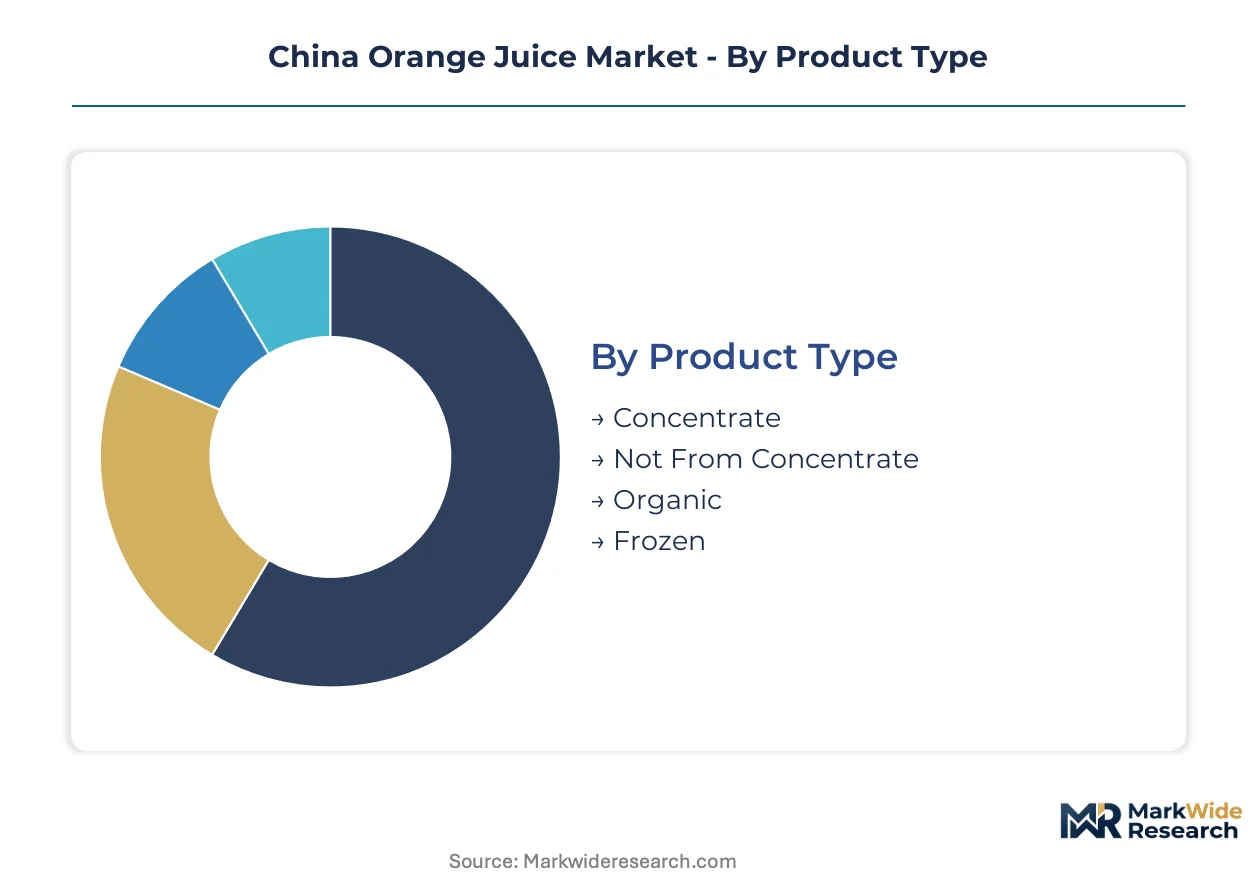
China orange juice segmentation reveals divergent growth vectors across processing methods and channel formats. Domestic consumption patterns concentrate around premium single-serve offerings in coastal metros, while industrial concentrate supply chains serve export-oriented beverage manufacturers.
Product Type:
Domestic demand clusters around not-from-concentrate and organic variants in Shanghai and Beijing, whereas concentrate output feeds industrial buyers and export channels concentrated in Guangxi processing zones.
- Concentrate:Industrial-grade orange concentrate standardized to 65-66 degrees Brix serves downstream beverage manufacturers and export markets. Demand concentrates in Guangxi and Jiangxi production corridors where MEE environmental compliance obligations create regional cost asymmetries. Concentrate commands the established base.
- Not From Concentrate:Single-strength juice preserved through pasteurization or aseptic processing, standardized to 11.3-12.5 degrees Brix. Young urban professionals in the Yangtze River Delta corridor are consolidating purchasing power around premium single-serve formats, displacing household bulk buying patterns. The steepest expansion runs through not-from-concentrate.
- Organic:Certified organic juice constrained by limited domestic citrus acreage meeting national conversion standards under revised organic certification pathways. Hunan Sanhe Food leverages Xiangxi sourcing partnerships for traceability differentiation.
- Frozen:Blast-frozen single-strength juice for foodservice and industrial blending applications, distributed through cold-chain networks extending into lower-tier cities.
Not-from-concentrate commands the established base. The steepest expansion runs through organic, constrained by certification scarcity.
Distribution Channel:
Channel fragmentation creates divergent margin profiles, with modern trade and e-commerce capturing premium pricing while traditional formats serve volume in lower-tier markets.
- Supermarkets:Modern trade channels dominate volume throughput in lower-tier cities where cold-chain infrastructure remains underdeveloped. China Huiyuan Juice leverages established distribution networks to anchor shelf positioning.
- Convenience Stores:Premium single-serve formats target urban professional consumption clustering in Shanghai and Beijing, with 24-hour outlets capturing impulse purchases.
- Online Retailers:E-commerce platforms represent underexploited penetration vectors in tier-three and tier-four cities. Subscription-based delivery models are displacing traditional retail intermediation in metropolitan cores.
- Direct Sales:Cold-chain-enabled direct-to-consumer platforms serve traceability-conscious buyers seeking verified sourcing narratives from Xiangxi citrus belts.
Supermarkets command the established base. The steepest expansion runs through online retailers.
Packaging Type:
Packaging selection tracks channel requirements and shelf-life specifications, with aseptic formats enabling extended distribution reach.
- Bottles:PET and glass bottles dominate premium not-from-concentrate positioning in modern trade, with lightweight aseptic PET enabling ambient distribution.
- Cartons:Laminated aseptic cartons anchor bulk household purchasing in lower-tier supermarket channels, offering cost-efficient ambient shelf stability.
- Cans:Metal cans serve foodservice and vending applications, with standard fill volumes targeting restaurant and cafe procurement patterns.
- Pouches:Flexible pouch formats emerge in online retail and direct-to-consumer channels, reducing shipping weight and enabling subscription model economics.
Cartons command the established base. The steepest expansion runs through pouches.
End User:
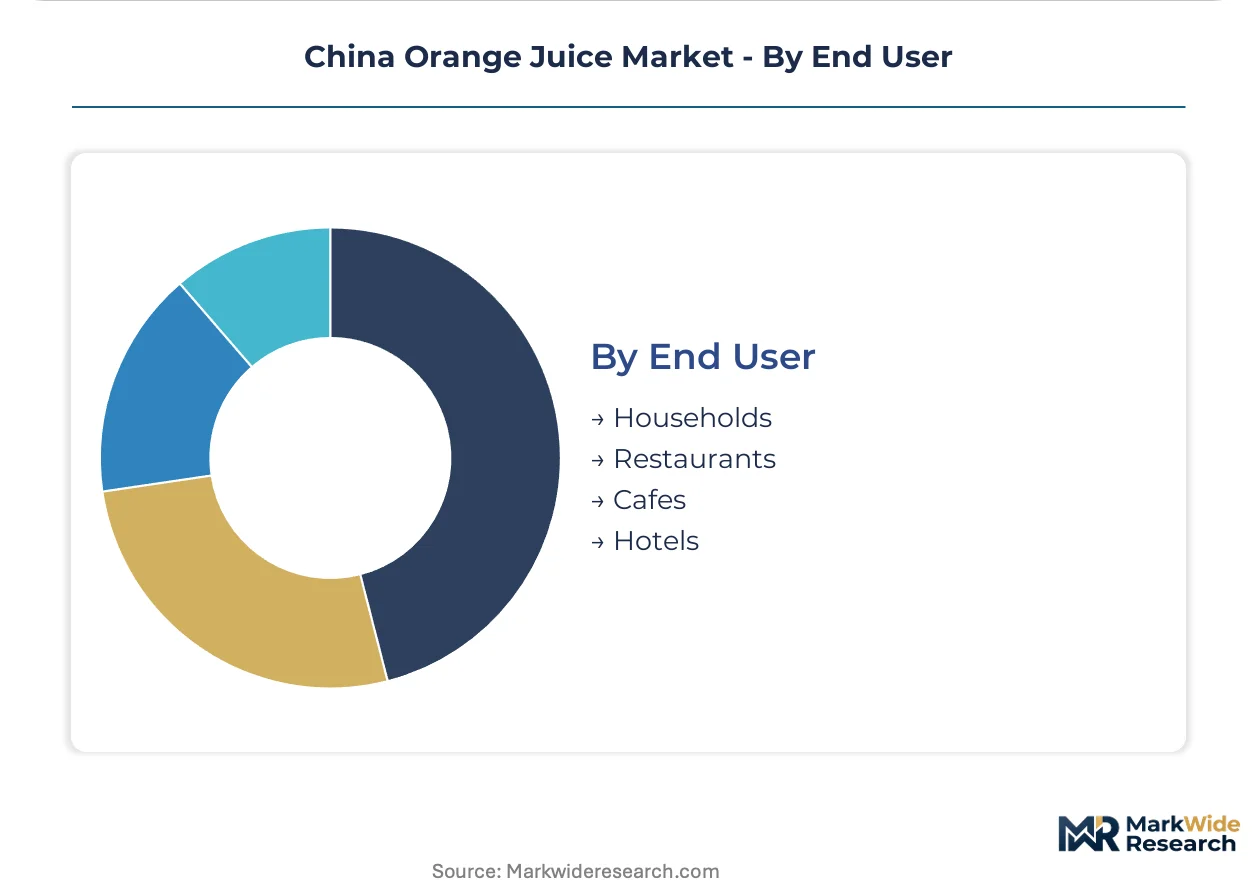
End-use segmentation reflects bifurcated demand between household consumption upgrading to premium formats and foodservice procurement seeking cost-efficient concentrate inputs.
- Households:Traditional bulk purchasing patterns persist in lower-tier cities, while young urban professionals in Shanghai and Beijing trade up to premium single-serve not-from-concentrate formats.
- Restaurants:Foodservice operators procure reconstituted concentrate for fountain and batch applications, with SAMR nutrition labeling enforcement compressing formulation margins for diluted beverage producers.
- Cafes:Specialty coffee chains and independent cafes drive demand for traceability-verified single-serve formats, sourcing through direct sales channels with cold-chain guarantees.
- Hotels:Hospitality procurement concentrates in international chain properties seeking premium not-from-concentrate for breakfast service and in-room amenities.
Households command the established base. The steepest expansion runs through cafes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan Deep Water Port anchors cold-chain import capacity for premium not-from-concentrate products entering the Yangtze River Delta corridor. Temperature-controlled rail links extending westward from this hub enable pasteurized juice distribution into Sichuan-Chongqing consumption clusters.
Yangtze River Delta
Young urban professionals in Shanghai and Hangzhou are consolidating purchasing power around premium single-serve formats. SAMR nutrition labeling enforcement compresses margins for diluted beverage producers in this corridor. Cold-chain infrastructure maturation enables pasteurized not-from-concentrate distribution beyond traditional metropolitan cores into Suzhou and Ningbo satellite cities.
Beijing-Tianjin-Hebei
Household bulk purchasing patterns persist in lower-tier Hebei cities while Beijing buyers trade up to traceability-verified formats. GB standards purity thresholds disqualify compound beverages from modern trade shelf positioning. Cofco Tunhe anchors industrial concentrate supply to downstream beverage manufacturers through Tianjin port logistics.
Guangxi Processing Belt
Industrial concentrate output feeds export-oriented beverage manufacturers concentrated in Nanning processing zones. MEE environmental compliance obligations for wastewater and peel waste disposal create regional cost asymmetries. China Haisheng Juice Holdings exemplifies scale-driven processing capacity in this citrus production corridor.
Sichuan-Chongqing
Western consumption clusters demonstrate accelerating demand for cold-pressed single-serve formats through subscription-based online delivery models. Dual carbon goal compliance forces capital-intensive retrofitting of thermal pasteurization lines in Chongqing bottling facilities. Direct-to-consumer platforms are displacing traditional retail intermediation in Chengdu metropolitan cores.
Hunan Citrus Belt
Xiangxi growing regions supply traceability-verified citrus for premium brand differentiation. Hunan Sanhe Food leverages these sourcing partnerships to anchor organic certification narratives. Limited domestic acreage meeting national organic conversion standards constrains supply expansion for certified premium positioning in this western Hunan production zone.
China Orange Juice Market Vendor Landscape
Listed leaders compete with private specialists across cold-chain infrastructure access and citrus sourcing control. The vendor base concentrates around three tiers: national-scale processors with integrated concentrate-to-retail operations, regional bottlers exploiting modular aseptic technology, and specialty organic players constrained by certification scarcity. Strategic archetypes include cold-chain dominant modern trade suppliers, Xiangxi-sourcing traceability specialists, and industrial concentrate exporters. Competitive moves center on backward integration into citrus growing belts and geographic expansion through temperature-controlled logistics partnerships.
Among state-affiliated and private fabricators, China Huiyuan Juice Group Limited and Cofco Tunhe Co., Ltd. occupy positions as scale-driven national processors, while Hunan Sanhe Food Co., Ltd. exemplifies the specialty organic archetype constrained by certification timelines. These three entities represent divergent strategic postures: cold-chain infrastructure leverage, industrial concentrate export orientation, and premium traceability differentiation respectively. Their positioning reflects the market's bifurcation between volume-driven commodity supply and premium single-serve segmentation.
| Leading Market Players |
|---|
| Hunan Sanhe Food Co., Ltd. |
| Chongqing Tianrun Cifu Co., Ltd. |
| China Haisheng Juice Holdings Co., Ltd. |
| Jiangxi Tianyu Fruit & Vegetable Juice Co., Ltd. |
| Guangxi State Farms Mingyang Biochemical Group |
| Zhongke Health Industry Group Co., Ltd. |
| Sichuan Guodong Food Co., Ltd. |
| China Huiyuan Juice Group Limited |
| Cofco Tunhe Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Single-serve premium formats displacing household bulk purchasing simultaneously concentrate sourcing control in Xiangxi citrus belts and compress margin pools for reconstituted concentrate processors unable to command traceability premiums. This substitution dynamic rewards cold-chain infrastructure holders while penalizing commodity-grade suppliers.
Pricing Analysis
Volume-discount tiering structures stratify across premium not-from-concentrate, standard reconstituted, and economy compound beverage levels. Price differentiation hinges on organic certification status under SAMR's revised national standards and cold-chain delivery guarantees to urban professional buyers. Pricing pressure stems from MEE environmental compliance obligations concentrated in Guangxi and Jiangxi processing zones, forcing cost absorption or facility retrofitting. Household bulk purchasers in lower-tier cities demonstrate highest price sensitivity, while traceability-verified single-serve buyers in Shanghai and Beijing show lowest elasticity.
Supply Chain Analysis
Inbound logistics costs through Shanghai Yangshan Deep Water Port fluctuate with container availability on Brazil-China and Florida-China trade lanes, compressing landed cost predictability for imported concentrate inputs. Geographic supply concentration centers on Guangxi and Jiangxi industrial processing corridors, with Xiangxi growing belts feeding premium organic lines. Raw material dependencies include Brazilian orange concentrate, domestic citrus from Hunan, and aseptic packaging materials. Single-source vulnerability runs through concentrated cold-chain infrastructure access. Distribution feeds through modern trade supermarkets in lower-tier cities and subscription-based online platforms in metropolitan cores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China orange juice sits in early-cycle expansion as young urban professionals accelerate premium not-from-concentrate adoption faster than supply-side organic certification can match.
For Market Incumbents: Shield market position by deepening backward integration into Xiangxi citrus growing belts to secure traceability narratives, and accelerate cold-pressed processing investments before modular aseptic technology democratizes premium capacity. SAMR's tightened GB standards purity thresholds threaten compound beverage shelf positioning, making certification infrastructure the critical defensive lever. For New Entrants and Emerging Players: Anchor in tier-three and tier-four online retail channels where supermarket coverage remains thin and cold-chain infrastructure maturation enables pasteurized distribution. Subscription-based delivery models targeting Sichuan-Chongqing consumption clusters offer the most penetrable white space, with direct-to-consumer traceability storytelling as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward regional bottlers exploiting modular aseptic technology and established cold-chain partnerships rather than industrial concentrate exporters facing Brazilian crop cycle volatility. Long-term viability across the analysis window favors upstream citrus sourcing control and certification pipeline depth. The signal to watch is SAMR organic conversion standard revision timelines, which would accelerate premium supply expansion or prolong scarcity pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Partnership | China Huiyuan Juice leverages temperature-controlled networks to dominate modern trade shelf positioning. |
| Xiangxi Sourcing Alliance | Hunan Sanhe Food secures traceability-verified citrus for organic certification differentiation. |
| Modular Aseptic Technology Adoption | Jiangsu and Zhejiang regional bottlers reduce capital barriers for premium not-from-concentrate processing. |
| Online Retail Channel Expansion | E-commerce platforms penetrate tier-three and tier-four cities where supermarket coverage remains underdeveloped. |
| MEE Environmental Compliance Retrofit | Guangxi processing facilities absorb carbon intensity benchmark costs to maintain concentrate export capacity. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade records, GB standards documentation, and cold-chain logistics disclosures. Primary interviews engaged juice category managers at modern trade retailers, procurement leads at downstream beverage manufacturers, citrus cooperative directors in Xiangxi growing belts, and cold-chain logistics operators. Secondary validation drew from SAMR regulatory filings, MEE environmental compliance databases, and Nielsen retail audit data. Bottom-up volume triangulation against top-down value estimates ensures cross-verified outputs.
Segmentation dimensions modeled span product type, distribution channel, packaging format, and end user across the projection horizon. Analytical framework applies category growth rates derived from urban professional consumption clustering patterns and cold-chain infrastructure penetration curves. Forecast inputs incorporate SAMR nutrition labeling enforcement trajectories and organic certification conversion timelines under revised national standards.
Underlying assumptions cover sustained urban professional income growth and cold-chain logistics maturation into lower-tier cities, with deviation risk concentrated in Brazilian concentrate input cost volatility and MEE carbon intensity benchmark acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Health Drinks Market
Beverages
Hot Beverages Market
Beverages
Saudi Arabia Retail Bubble Tea Kits Market
Beverages
North America Fruit Juice Market
Beverages
Canned Beverages Market
Beverages
Tonic Water Market
Beverages
Middle East and Africa Fruits and Vegetable Juice Market
Beverages
US Bubble Tea Market
Beverages
Bottled Air Market
Beverages
Drinking Water Market
Beverages
Soft Serves Market
Beverages
North America Yerba Mate Market
Beverages
Orange Juice Market
Beverages
Germany Probiotic Drinks Market
Beverages
Fruit Beverages Market
Beverages
Aloe Vera Drinks Market