
 Premium Water Market | 2026-2036
Premium Water Market Size, Share, and Industry Trends Forecast 2026-2036
Premium Water Market Analysis
Recycled aluminum is consolidating share against virgin PET in premium water packaging economics. Nestlé leverages its European bottling network to sustain glass and aluminum format transitions across multiple source locations. Danone anchors its competitive position through specialized mineral composition sourcing in France and Italy. Fiji Water differentiates via remote Pacific aquifer control and ocean freight logistics mastery.
Premium water denotes bottled water sourced from protected underground reservoirs or springs, distinguished by specific mineral content measured in total dissolved solids and verified geographic origin, serving both hydration and sensory experience purposes in commercial and retail channels. Spring water and mineral water categories dominate volume, while alkaline water captures expanding shelf space in health-focused retail. Glass bottles and aluminum cans command margin premiums over plastic, though supermarkets remain the primary volume channel against faster-growing specialty stores and online retailers.
The FDA enforces bottled water quality standards under 21 CFR 165.110, while the EU's Drinking Water Directive and F-Gas Regulation shape refrigerant choices for cold-chain distribution across member states. EFSA mineral content labeling requirements influence how brands communicate health claims on European packaging. Stakeholders must monitor whether emerging packaging regulations in major markets will mandate recycled content thresholds that reshape sourcing economics for bottle and can suppliers.
Market Dynamics
The EU's Single-Use Plastics Directive is compressing virgin PET demand while aluminum and glass formats capture margin premiums across European retail channels, forcing bottlers to reconfigure filling lines and source contracts.
Growth Catalysts
- Mineral Provenance Verification:German and Italian regulatory frameworks for PDO-certified springs enable brands to command shelf space premiums in fine-dining channels.
- Aluminum Recycling Infrastructure:European smelter networks now supply food-grade recycled sheet at scale, cutting packaging carbon intensity for brands targeting CSRD disclosure compliance.
- Hotel Water Program Expansion:Luxury hospitality procurement teams in Paris, Milan, and Dubai are standardizing multi-source premium water menus as ancillary revenue streams.
Market Restraints
- Remote Source Logistics:Pacific and Alpine aquifer access requires dedicated cold-chain fleets that concentrate cost exposure with specialized refrigerated haulers.
- Glass Weight Penalties:EU road freight regulations impose axle-load limits that inflate per-unit transport costs for heavy packaging formats versus aluminum alternatives.
- Groundwater Extraction Permits:French and German state-level water rights adjudication creates multi-year licensing delays for new spring development.
Strategic Opportunities
- India Urban Premiumization:Mumbai and Delhi five-star hotel construction pipelines outpace installed premium water supply, creating white space for imported source partnerships.
- Direct-to-Consumer Subscription:Chilled last-mile delivery networks in London and New York enable recurring revenue models bypassing supermarket slotting fees.
- EFSA Health Claim Pathways:Emerging mineral-specific hydration efficacy approvals allow brands to differentiate beyond taste claims in pharmacy retail.
Industry Challenges
- Sensory Panel Calibration:Maintaining consistent TDS perception across seasonal aquifer fluctuation requires trained in-house tasting teams that command specialized compensation.
- Multi-Format Line Conversion:Legacy PET-optimized filling equipment demands seven-figure retrofit investments to handle aluminum can carbonation profiles without contamination risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Premium Water Market |
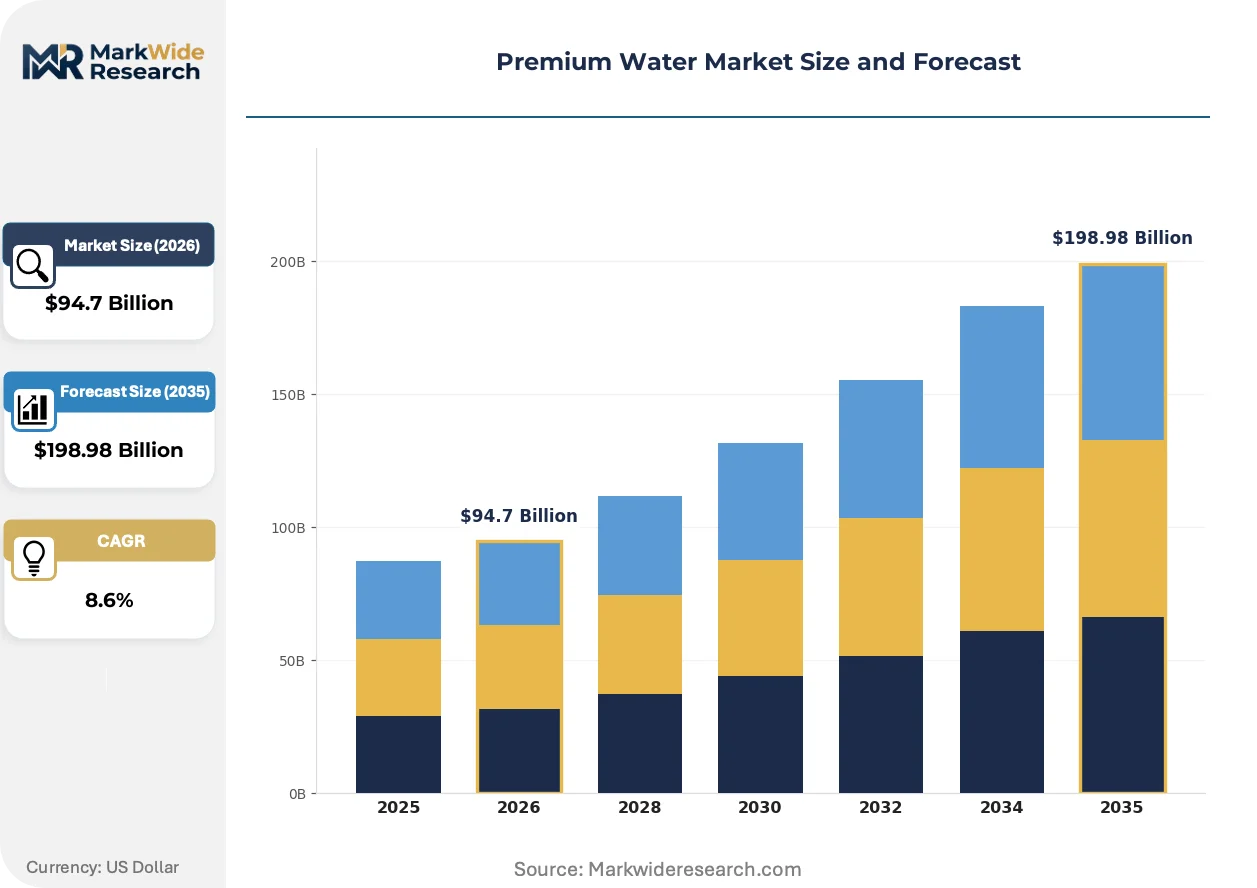
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $198.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spring Water, Mineral Water, Alkaline Water, Sparkling Water Packaging Type: Bottles, Cans, Pouches, Tetra Packs Distribution Channel: Supermarkets, Specialty Stores, Online Retailers, Health Clubs End User: Restaurants, Hotels, Health-conscious Consumers, Events |
| Companies Covered | Nestlé, Danone, The Coca-Cola Company, PepsiCo, Gerolsteiner Brunnen GmbH & Co., Fiji Water, The Wonderful Company, Highland Spring Group, Icelandic Water Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Premium Water Market Emerging Trajectories
Packaging material science and digital traceability systems are compressing traditional sourcing advantages while creating new differentiation vectors around carbon accountability and origin storytelling.
Blockchain-enabled provenance tracking is unifying source documentation with consumer-facing QR verification. High-end restaurants in Copenhagen and Tokyo now scan batch records tableside. This transparency architecture is compressing trust premiums previously captured by legacy brands with established name recognition.
REACH-compliant PFAS restrictions in EU packaging substrates are forcing liner and sealant reformulation across glass and aluminum closure systems. German canning equipment manufacturers report eighteen-month qualification timelines for new barrier coatings. Smaller bottlers without dedicated regulatory affairs functions face compliance delays that concentrate volume with integrated multinationals.
Curated water pairing menus are displacing static bottled lists in Michelin-starred dining rooms. Sommelier-led selection in Barcelona and Singapore now matches mineral profiles to dish salinity and wine progression. This service model rotation compresses standard retail margins while capturing ancillary revenue through guided tasting experiences.
Premium Water Market Segmentation
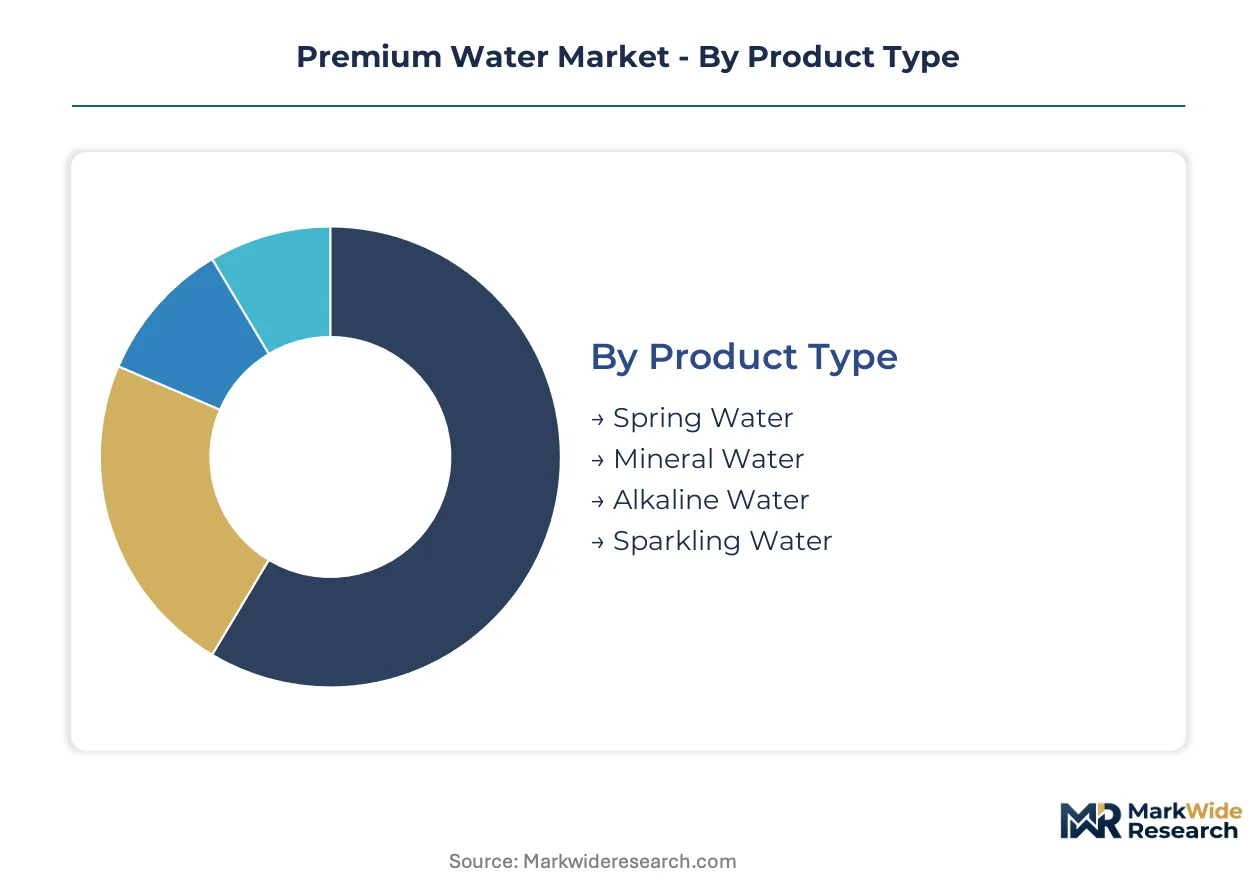
Premium water segmentation separates commodity hydration from experiential consumption through mineral composition verification and packaging material signaling. Each category reflects distinct procurement logic across hospitality procurement teams versus individual retail selection.
Product Type:
Standardization dominates spring and mineral categories with PDO-certified source documentation, while alkaline and sparkling variants permit formulation customization that commands shelf space premiums.
- Spring Water:Sourced from protected underground formations with natural flow to the surface, verified by hydrological survey documentation. German and Italian state-level water rights frameworks anchor per-capita consumption leadership through tradition-bound procurement in fine-dining channels.
- Mineral Water:Contains consistent mineral content from geologically stable aquifers, with TDS levels measured and labeled per EFSA requirements. Hotels across Paris, Milan, and Dubai standardize multi-source mineral water menus as ancillary revenue streams, matching provenance to guest origin preferences.
- Alkaline Water:pH-adjusted through electrolysis or natural mineral infusion, targeting health-focused retail placement.
- Sparkling Water:Carbonated naturally at source or injected, capturing margin premiums in restaurant beverage programs.
Leading the category by volume: Spring Water. Expanding most quickly: Alkaline Water.
Packaging Type:
Cost tiers separate mass retail from hospitality channels, with material weight and recyclability driving logistics economics and regulatory compliance.
- Bottles:Glass commands margin premiums in European hospitality while recycled PET retains supermarket volume dominance. EU Single-Use Plastics Directive compression of virgin PET demand is accelerating format transitions toward aluminum and glass in member states.
- Cans:Food-grade recycled aluminum sheet from European smelter networks cuts carbon intensity for CSRD disclosure compliance. Copenhagen and Tokyo restaurants now scan batch records tableside through QR-enabled provenance tracking.
- Pouches:Flexible format targeting on-the-go consumption with reduced transport weight versus rigid alternatives.
- Tetra Packs:Aseptic carton technology enabling ambient distribution with extended shelf stability.
Glass bottles lead hospitality procurement by margin contribution. Aluminum cans gain share fastest in retail format transitions.
Distribution Channel:
Volume concentration versus customer acquisition cost defines channel strategy, with slotting fees and cold-chain requirements creating divergent economics.
- Supermarkets:Primary volume channel with established refrigerated shelf infrastructure and standardized slotting fee structures. Chilled last-mile delivery networks in London and New York enable recurring revenue models bypassing these fees.
- Specialty Stores:Curated selection targeting health-conscious consumers with premium positioning and trained staff recommendation.
- Online Retailers:Subscription mechanics capturing direct customer relationships with delivery scheduling flexibility.
- Health Clubs:Post-exercise hydration placement with impulse purchase dynamics and member loyalty integration.
Supermarkets retain volume leadership. Online retailers climb the fastest on subscription model expansion.
End User:
Procurement sophistication varies from institutional tender processes to individual taste preference, with mineral provenance verification requirements scaling accordingly.
- Restaurants:Sommelier-led water pairing menus in Barcelona and Singapore match mineral profiles to dish salinity, compressing standard retail margins while capturing ancillary revenue.
- Hotels:Luxury hospitality procurement teams standardize multi-source premium water programs, with Mumbai and Delhi five-star construction pipelines outpacing installed supply.
- Health-conscious Consumers:Individual purchasers prioritizing mineral content labeling and EFSA health claim pathways for hydration efficacy differentiation.
- Events:Temporary demand concentration requiring scalable logistics and branded packaging for sponsorship visibility.
Hotels lead institutional procurement by program standardization. Health-conscious consumers gain share fastest on pharmacy retail placement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hotels and fine-dining restaurants in Germany, France, and Italy anchor institutional demand for verified mineral provenance, while regulatory pressure on single-use plastics accelerates packaging format transitions across European retail channels.
Germany
PDO-certified spring traditions sustain per-capita consumption leadership through state-level water rights frameworks. The EU's Single-Use Plastics Directive compresses virgin PET demand while aluminum and glass capture margin premiums. Gerolsteiner's Rhineland-Palatinate operations exemplify mineral composition verification standards that fine-dining procurement teams demand.
France
Luxury hospitality in Paris and Lyon standardizes multi-source premium water programs as ancillary revenue streams. EFSA mineral content labeling requirements shape how brands communicate hydration efficacy claims. The Auvergne-Rhône-Alpes cluster anchors specialized mineral sourcing for pharmacy retail placement.
United States
FDA enforcement under 21 CFR 165.110 governs bottled water quality standards while health-conscious consumers drive alkaline water expansion. Chilled last-mile delivery networks in New York enable direct-to-consumer subscription models bypassing supermarket slotting fees. California's Pacific Coast aquifer access supports remote-source differentiation strategies.
Italy
Sommelier-led water pairing menus in Milan and Rome match mineral profiles to dish salinity, compressing standard retail margins. REACH-compliant PFAS restrictions force liner reformulation across glass closure systems. The Lombardy-Veneto corridor concentrates carbonated natural mineral water production for European export.
India
Mumbai and Delhi five-star hotel construction pipelines outpace installed premium water supply, creating white space for imported source partnerships. FSSAI labeling standards govern mineral content disclosure for health-focused retail placement. The Maharashtra-Gujarat industrial corridor enables aluminum can manufacturing scale for domestic format transitions.
Premium Water Market Vendor Landscape
Portfolio diversification dominates the current landscape as multinationals reconfigure filling lines for aluminum and glass transitions. The vendor base concentrates around integrated beverage conglomerates with European bottling networks, mid-sized specialists with protected aquifer control, and regional players leveraging PDO-certified source documentation. Three archetypes define positioning: scale-driven format transition specialists, provenance-focused source controllers, and hospitality-channel direct suppliers. M&A activity targets aluminum packaging capabilities, while strategic partnerships secure recycled sheet supply from European smelter networks.
Among integrated multinationals, Nestlé and Danone exemplify scale-driven format transition capabilities, leveraging European bottling infrastructure to sustain glass and aluminum migrations across multiple source locations. Fiji Water occupies a position as a provenance-focused source controller, with remote Pacific aquifer access and ocean freight logistics mastery differentiating its market presence. Gerolsteiner Brunnen GmbH & Co. anchors the specialist tier, representing PDO-certified mineral water traditions that command shelf space premiums in German fine-dining channels.
| Leading Market Players |
|---|
| Nestlé |
| Danone |
| The Coca-Cola Company |
| PepsiCo |
| Gerolsteiner Brunnen GmbH & Co. |
| Fiji Water |
| The Wonderful Company |
| Highland Spring Group |
| Icelandic Water Holdings |
| Others |
Supply Flow & Price Mechanics
Luxury hospitality procurement teams in Paris, Milan, and Dubai anchor volume concentration for premium water, locking in contract-based long-term offtake pricing that shields established suppliers from spot-market volatility. This buyer concentration enables incumbent bottlers to command margin premiums through multi-source menu standardization while compressing price negotiation leverage for smaller entrants.
Pricing Analysis
Volume concentrates in supermarket retail at standard tiers while hospitality channels capture margin premiums through provenance-verified sourcing. Three-tier pricing structure across premium, standard, and economy levels differentiates by mineral certification grade and packaging material weight, with glass and aluminum formats commanding shelf space premiums over recycled PET. Cost compression in standard tiers intensifies because EU Single-Use Plastics Directive compliance investments inflate per-unit production economics. Individual health-conscious consumers exhibit highest price sensitivity, while fine-dining procurement teams prioritize provenance verification over per-bottle cost.
Supply Chain Analysis
Regional distribution centers in Germany, France, and Italy operate hub-and-spoke patterns feeding European retail and hospitality channels. Source concentration draws from protected Alpine and Rhineland-Palatinate aquifers, with Pacific remote sourcing for differentiated provenance positioning. Food-grade recycled aluminum sheet and glass closure systems constitute critical input dependencies. Single-source vulnerability runs through specialized refrigerated hauler networks for cold-chain integrity. Distribution runs through integrated bottler networks with direct-to-hotel delivery capabilities bypassing wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
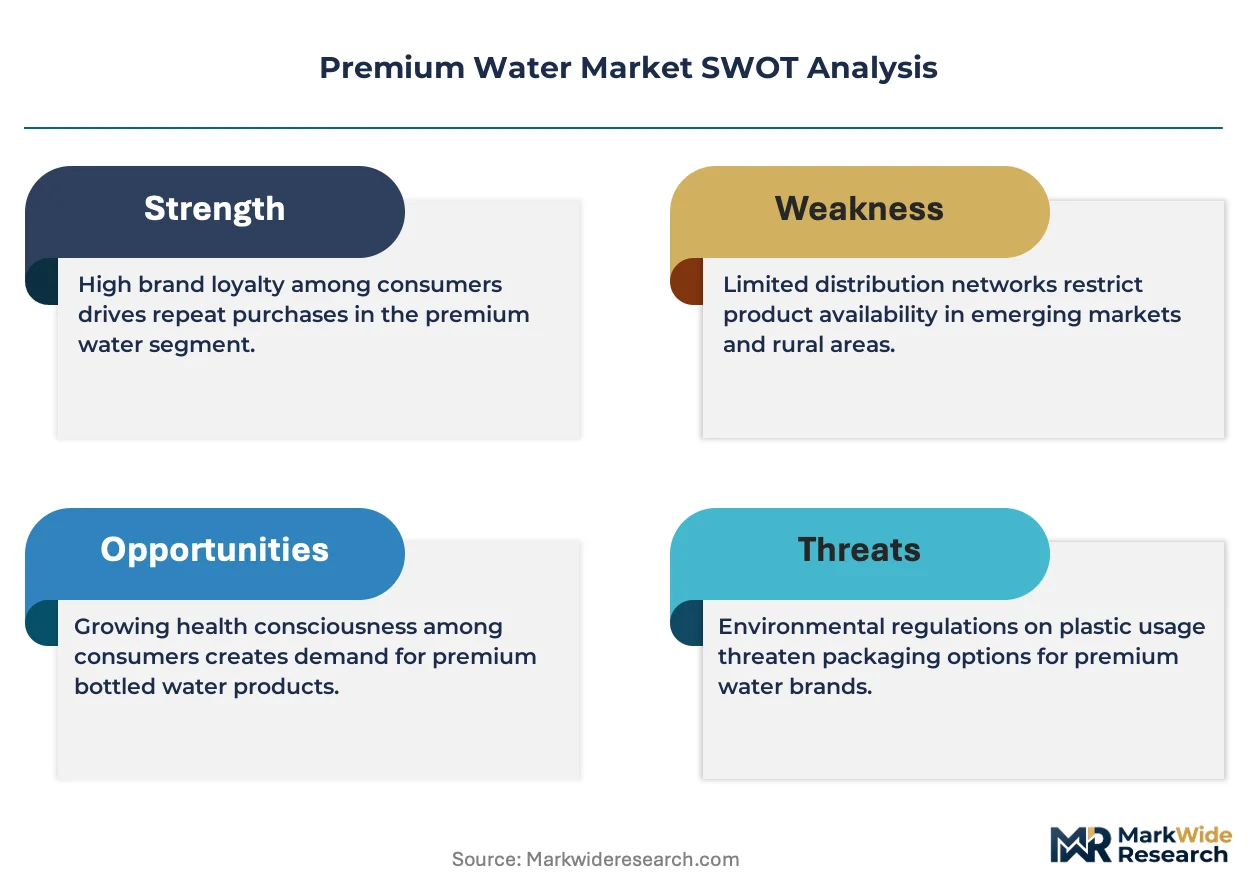
The EU's Single-Use Plastics Directive erects a cost-of-compliance barrier that favors integrated multinationals with dedicated regulatory affairs functions and capital reserves for filling line retrofits, squeezing smaller bottlers into acquisition targets or market exit.
For Market Incumbents: Deepen aluminum packaging capabilities through European smelter network partnerships and captive recycling infrastructure investments. Acquire mid-sized PDO-certified specialists in Italy and Germany before REACH-compliant PFAS restriction deadlines concentrate volume further. Threat substitution from blockchain-enabled provenance tracking compresses legacy brand trust premiums, demanding rapid digital traceability deployment. For New Entrants and Emerging Players: Capture white space in Mumbai and Delhi five-star hotel construction pipelines through imported source partnerships with established European PDO-certified brands. Target direct-to-consumer subscription mechanics in London and New York chilled last-mile delivery corridors. Go-to-market positioning centers on EFSA health claim pathway navigation for pharmacy retail placement. For Investors and Strategic Acquirers: The window for entry favors aluminum packaging capability specialists and PDO-certified source controllers with German or Italian water rights adjudication progress. Long-term viability rests on CSRD disclosure compliance infrastructure and carbon intensity reduction trajectories. Signal to monitor: EU recycled content threshold mandates that would reshape sourcing economics for bottle and can suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Format Transition | European smelter partnerships cut carbon intensity for CSRD compliance disclosure requirements. |
| PDO Source Certification | German and Italian regulatory frameworks enable shelf space premiums in fine-dining channels. |
| Direct-to-Consumer Subscription | Chilled last-mile networks in London and New York bypass supermarket slotting fee structures. |
| Blockchain Provenance Tracking | Copenhagen and Tokyo restaurants scan batch records tableside, compressing legacy brand advantages. |
| Hotel Program Standardization | Luxury hospitality procurement in Dubai and Paris captures ancillary revenue through multi-source menus. |
Methodological Framework
Document review covered customs and trade data, SEC filings from integrated beverage conglomerates, and EFSA regulatory guidance documents, complemented by interviews with luxury hospitality procurement directors, European bottling plant managers, aluminum packaging procurement leads, and specialty retail category buyers. Secondary validation drew from EU Single-Use Plastics Directive implementation reports, REACH compliance databases, and CSRD disclosure frameworks. Bottom-up volume triangulation against top-down market sizing anchored forecast integrity.
Model outputs span value and volume trajectories across the projection horizon, with segmentation dimensions covering product type, packaging material, distribution channel, and end-user procurement sophistication. CAGRs derived from historical consumption elasticity analysis and regulatory-driven format shift assumptions. Industry-specific inputs incorporated cold-chain logistics cost curves and groundwater extraction permit adjudication timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU recycled content mandate timing, Alpine aquifer climate fluctuation patterns, and hospitality construction pipeline completion rates. Outputs reflect documented assumptions around regulatory implementation schedules and consumer willingness-to-pay evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Europe Sugar Free Energy Drinks Market
Beverages
Ready-To-Drink (RTD) Beverages Market
Beverages
Hot Cocoa Mix Market
Beverages
Citrus Water Market
Beverages
Peanut Oil Market
Beverages
Milk Tea Powder Market
Beverages
Fiber Fortified Beverages Market
Beverages
Europe Yerba Mate Market
Beverages
Global Soft Drinks Concentrate Market
Beverages
Yerba Mate Market
Beverages
Water Bottle Market
Beverages
India Cafes & Bars Market
Beverages
Enzyme-Enabled Cold-Brew Concentrates Market
Beverages
Probiotic Beverage Market
Beverages
North America Fruit Juice Market
Beverages
Coconut Milk Beverages Market