
 Saudi Arabia Bottled Water Market | 2026-2036
Saudi Arabia Bottled Water Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Bottled Water Market Outlook
Premium mineral specifications are redrawing competitive boundaries in Saudi Arabia. Nestlé Waters leverages its European technical heritage to sustain credibility among discerning hospitality buyers. Agthia Group anchors Gulf distribution density through backward integration into captive supply chains. Almarai competes by extending dairy-era cold-chain expertise into temperature-controlled bottled water logistics.
Bottled water in Saudi Arabia comprises treated, packaged drinking water—typically sourced from desalinated seawater, deep aquifers, or municipal supplies—then filtered, mineral-balanced, and sealed under SFDA hygiene protocols for safe consumption in arid climates where potable surface water is absent. Purified water dominates volume through supermarket and convenience store channels serving residential consumers, while mineral water commands margin premiums in hospitality and restaurant end uses. Plastic bottles occupy the mass-market tier, though regulatory pressure on single-use polymers is accelerating pouch and glass bottle trials among Riyadh-based distributors.
SFDA mandates mineral content disclosure and facility licensing, while SASO technical regulations enforce packaging integrity standards that shape product differentiation and import eligibility. The Saudi Water Partnership Company coordinates desalination capacity allocation, indirectly constraining feedstock availability for private bottlers. Stakeholders must monitor desalination tariff revisions and packaging material restrictions to calibrate sourcing and format strategies.
Market Dynamics
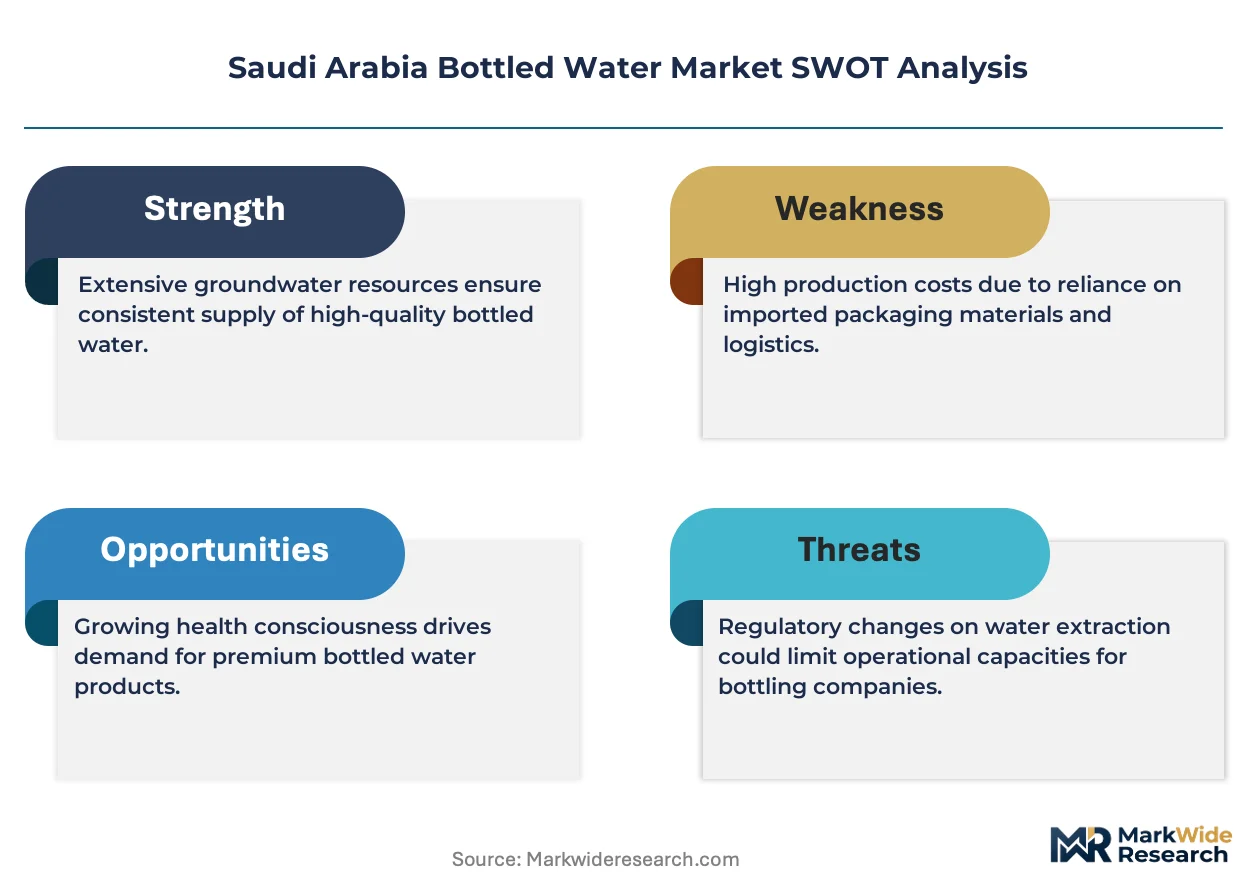
SFDA mineral disclosure mandates and Saudi Water Partnership Company feedstock allocation rules are compressing bottler margins while forcing capital redeployment toward certified purification infrastructure.
Growth Catalysts
- Pilgrimage tourism diversification:Hospitality venues in Jeddah and Riyadh are expanding premium water procurement to serve non-religious leisure segments.
- SFDA facility licensing:Stricter hygiene protocols are consolidating production among compliant bottlers, reducing informal competition.
- Desalination capacity expansion:Saudi Water Partnership Company infrastructure investments are stabilizing feedstock availability for private bottlers.
Market Restraints
- Single-use polymer cost volatility:Petrochemical feedstock fluctuations compress packaging margins for mass-market plastic bottles.
- Central Region demand concentration:Riyadh and surrounding provinces absorb disproportionate volume, leaving peripheral distributors exposed to logistics inefficiencies.
- Municipal supply substitution:Improving tap water infrastructure in urban cores threatens entry-tier bottled water demand.
Strategic Opportunities
- Eastern Province underpenetration:Dammam and Khobar hospitality corridors remain underserved by premium mineral water distribution.
- Glass bottle channel innovation:High-end restaurants in Riyadh are trialing returnable glass formats as regulatory pressure on plastics intensifies.
- PLI-adjacent packaging incentives:Saudi Industrial Development Fund support for domestic manufacturing equipment is lowering barrier costs for local bottlers.
Industry Challenges
- Cold-chain technician scarcity:Temperature-controlled logistics expansion outpaces trained workforce availability in secondary cities.
- SFDA certification timelines:Mineral content validation protocols extend product launch cycles by four to six months.
- Legacy distributor integration:Family-owned wholesale networks resist ERP system adoption, fragmenting demand visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Bottled Water Market |
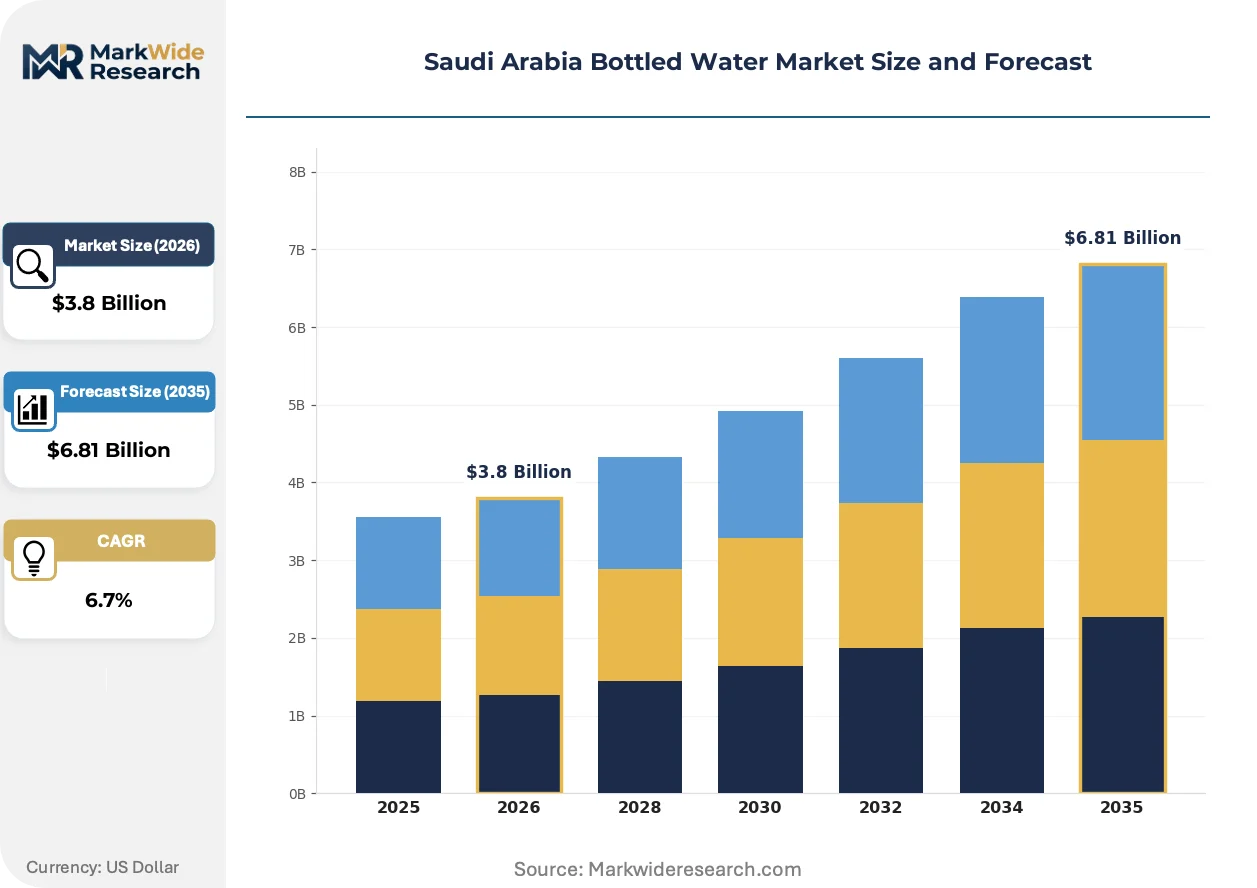
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spring Water, Mineral Water, Purified Water, Sparkling Water Packaging Type: Plastic Bottles, Glass Bottles, Pouches, Tetra Packs Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Vending Machines End User: Residential Consumers, Office Use, Hospitality, Restaurants |
| Companies Covered | Agthia Group, Coca-Cola Bottling Co., Almarai, Aloyoun Water Factory Inc., Nestlé Waters, Health Water Bottling Co., PepsiCo, Naqi Water Company, Hana Food Industries Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Bottled Water Market Strategic Shifts
Packaging material innovation and mineral specification transparency are redrawing competitive boundaries. Producers now face simultaneous pressure to reduce polymer dependence and validate provenance claims.
Advanced membrane filtration is bifurcating the purified water segment. Large-scale bottlers in Riyadh are deploying reverse osmosis with remineralization to achieve consistent TDS profiles. This technology is compressing price premiums for basic purified grades while enabling certified mineral water positioning at higher tiers.
SFDA labeling requirements are tightening disclosure standards for mineral content and source origin. Bottlers must now submit third-party laboratory validation for calcium, magnesium, and sodium levels. Premium hospitality channels in Jeddah are responding by demanding batch-specific certificates to satisfy international guest expectations.
Direct procurement from bottlers is displacing traditional wholesale intermediaries in the Central Region. Large hotel groups and restaurant chains are negotiating annual volume contracts with guaranteed cold-chain service levels. This pattern is most visible in Riyadh, where consolidated buyers now capture fifteen to twenty percent price advantages over fragmented retail channels.
Saudi Arabia Bottled Water Market Segmentation
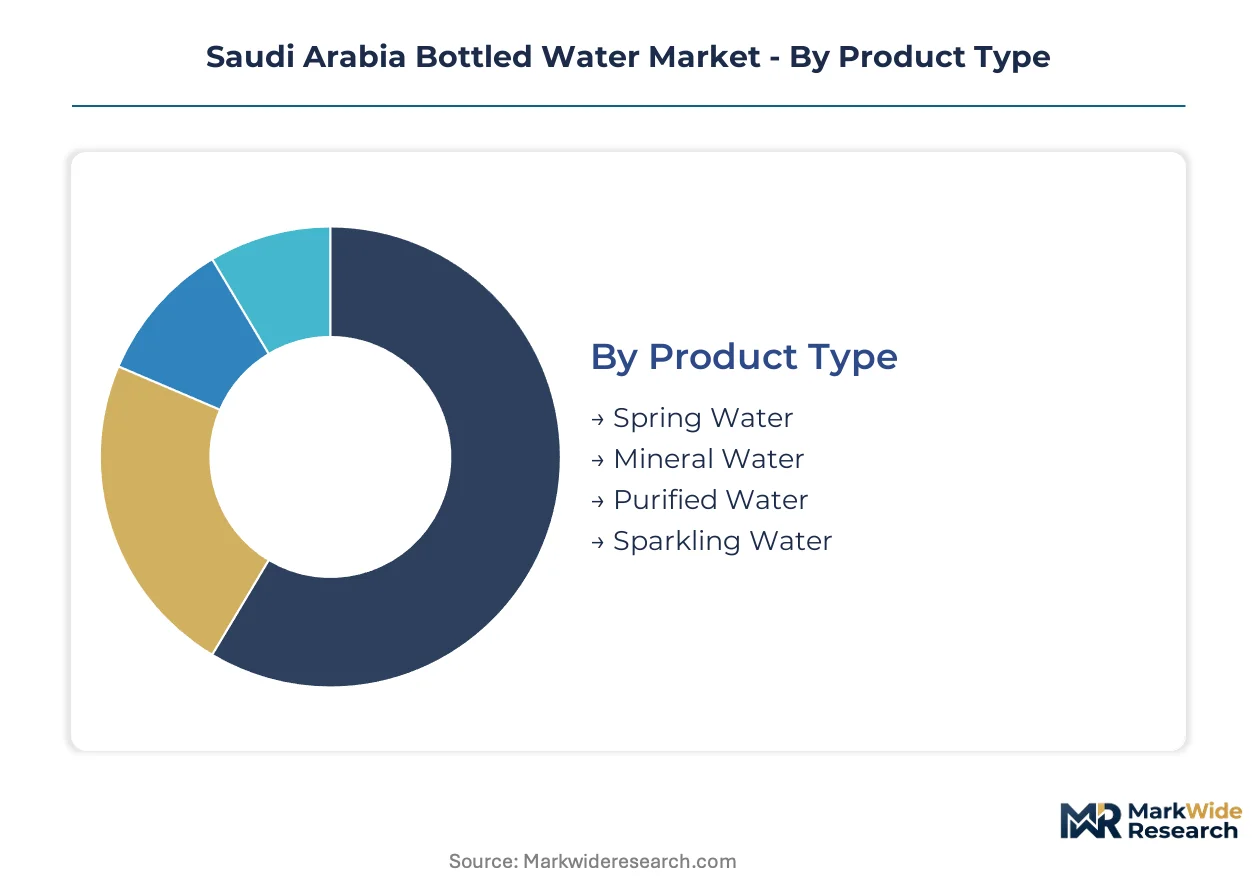
Saudi Arabia's bottled water market segments reflect divergent vulnerability to municipal tap water substitution and pilgrimage tourism demand cycles. Understanding these fault lines clarifies where producers must defend volume versus pursue premium repositioning.
Product Type:
Substitution pressure from improving municipal infrastructure falls unevenly across water grades, with basic purification facing the steepest threat while certified mineral origins command defensive premiums.
- Purified Water:Desalinated seawater or municipal feedstock undergoes reverse osmosis and carbon filtration to achieve low TDS profiles. Residential demand concentrates in Riyadh's supermarket channels where family bulk purchasing dominates, though per-unit margins compress under petrochemical feedstock volatility.
- Mineral Water:Naturally sourced or artificially remineralized water maintains specified calcium, magnesium, and sodium levels validated under SFDA protocols. Hospitality procurement in Jeddah's pilgrimage corridor drives premium positioning as international guests demand provenance documentation.
- Spring Water:Deep aquifer extraction with minimal processing retains natural mineral signatures. Limited domestic spring availability constrains scale.
- Sparkling Water:Carbonated variants targeting restaurant and café channels. Riyadh's fine-dining expansion supports niche growth.
Purified water anchors the volume base while mineral water gains share at the steepest rate.
Packaging Type:
Cost tier stratification separates mass-market polymer dependence from emerging regulatory-driven format experimentation.
- Plastic Bottles:PET and HDPE formats dominate unit economics through lightweight logistics and scale manufacturing. Central Region retail penetration remains deepest, though SASO polymer restrictions threaten format viability.
- Glass Bottles:Returnable and single-use glass commands hospitality premiums in Riyadh's high-end restaurant trials. Cold-chain requirements limit distribution radius.
- Pouches:Flexible film formats reduce polymer mass per liter. Pilgrimage season vending applications drive seasonal demand.
- Tetra Packs:Aseptic carton technology suits ambient distribution in peripheral provinces. Shelf-stable logistics appeal to Eastern Province distributors.
Plastic bottles retain volume dominance while glass formats climb fastest on regulatory pressure.
Distribution Channel:
Customer type fragmentation splits between consolidated institutional procurement and fragmented retail replenishment patterns.
- Supermarkets:Hypermarket and grocery chains aggregate family-scale purchasing with promotional price sensitivity. Riyadh's retail density supports category management investments.
- Convenience Stores:Small-format urban outlets capture impulse and replenishment trips. Extended hours match Saudi consumption patterns.
- Online Retail:E-commerce platforms aggregate subscription and bulk delivery demand. Younger demographic adoption accelerates in metropolitan clusters.
- Vending Machines:Automated point-of-need distribution serves pilgrimage infrastructure and office corridors. Seasonal utilization spikes around Hajj periods.
Supermarkets anchor the volume base while online retail expands most quickly on delivery infrastructure maturation.
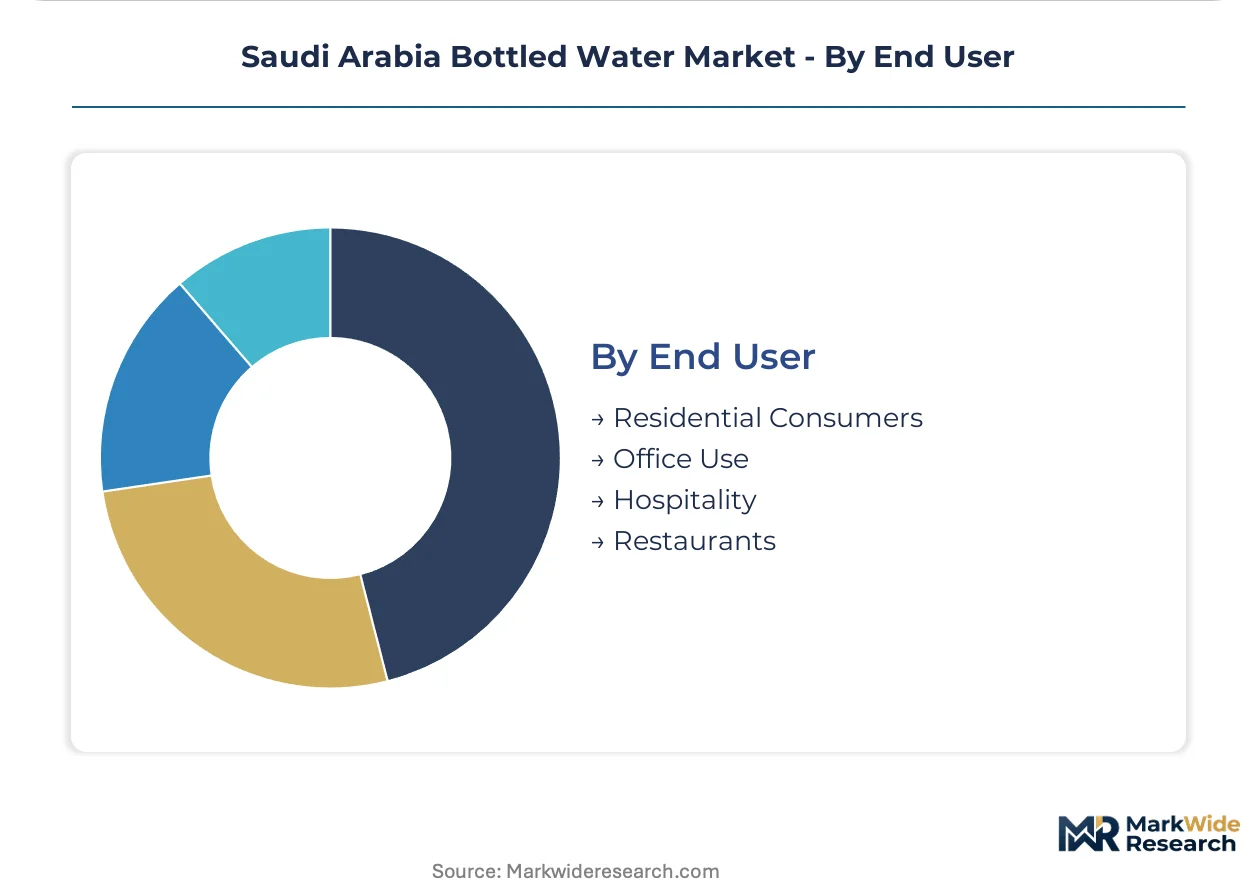
End User:
Application maturity separates saturated residential replacement demand from hospitality growth corridors tied to tourism diversification.
- Hospitality:Hotels and serviced apartments procure premium grades with batch certification requirements. Jeddah's non-religious leisure segment expansion drives specification tightening.
- Restaurants:Foodservice channels negotiate direct bottler contracts with guaranteed cold-chain service levels. Riyadh's consolidated buyer groups capture procurement leverage.
- Residential Consumers:Household replenishment of bulk formats for drinking and cooking. Municipal supply quality improvements threaten entry-tier substitution.
- Office Use:Corporate water cooler and meeting room provisioning. Hybrid work patterns compress per-employee consumption.
Residential consumers anchor the volume base while hospitality gains share fastest on pilgrimage tourism diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's bottled water trade flows reflect a net import position in premium mineral grades while domestic desalination capacity anchors purified water self-sufficiency. Regional demand patterns concentrate around pilgrimage corridors and metropolitan consumption clusters.
Riyadh
Central Region households drive the kingdom's highest per-capita consumption rates through bulk supermarket purchasing. SFDA facility licensing protocols have consolidated production among compliant bottlers, squeezing informal suppliers. The Riyadh industrial zone hosts reverse osmosis facilities serving both retail chains and direct hospitality procurement.
Jeddah
Pilgrimage tourism diversification is expanding premium water procurement beyond religious travel into leisure hospitality. Western Region distributors face seasonal demand spikes around Hajj periods that strain cold-chain logistics capacity. King Abdullah Economic City logistics hubs are emerging as consolidation points for Red Sea coastal distribution.
Eastern Province
Dammam and Khobar hospitality corridors remain underserved by premium mineral water distribution relative to their commercial density. Saudi Water Partnership Company desalination infrastructure in the region stabilizes feedstock costs for local bottlers. Jubail industrial clusters supply PET resin to packaging converters serving Eastern Province distributors.
NEOM Northwest
The giga-project zone is piloting sustainable packaging trials including returnable glass and biodegradable film formats. Regulatory pressure on single-use plastics is accelerating format experimentation ahead of nationwide SASO restrictions. NEOM's logistics isolation currently limits bottled water distribution radius to project-bound construction and hospitality sites.
Saudi Arabia Bottled Water Market Competitive Environment
Listed leaders compete with private specialists across capital access and operational agility dimensions, producing a tiered structure where scale advantages meet niche responsiveness. The vendor base spans multinational beverage conglomerates, Gulf-based food conglomerates, and Saudi family-owned bottlers with legacy distribution networks. Two strategic archetypes dominate: diversified food-and-beverage groups leveraging backward integration into captive supply chains, and dedicated water specialists optimizing single-category purification technology. Competitive moves concentrate on direct procurement contracts with hospitality buyers and cold-chain service level guarantees.
Within the diversified conglomerate tier, Agthia Group and Almarai exemplify players extending Gulf distribution density and dairy-era cold-chain expertise into temperature-controlled bottled water logistics. Nestlé Waters occupies a distinct position representing European technical heritage in mineral specification validation. Among Saudi specialists, Naqi Water Company and Health Water Bottling Co. anchor the mid-market segment with regional production footprints focused on purified water grades for retail channels.
| Leading Market Players |
|---|
| Agthia Group |
| Coca-Cola Bottling Co. |
| Almarai |
| Aloyoun Water Factory Inc. |
| Nestlé Waters |
| Health Water Bottling Co. |
| PepsiCo |
| Naqi Water Company |
| Hana Food Industries Company |
| Others |
Value Chain & Pricing Dynamics
Municipal tap water infrastructure upgrades across Riyadh and Jeddah are displacing entry-tier purified water demand while simultaneously compressing bottler margins and forcing premium repositioning toward mineral-certified grades. This substitution dynamic redistributes supply geography toward Eastern Province desalination clusters and reshapes pricing economics around cold-chain service guarantees rather than volume scale.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with hospitality procurement groups negotiating annual volume agreements that embed guaranteed cold-chain service levels. Price differentiation rests on certification grade under SFDA protocols and geographic delivery cost to peripheral provinces. Pricing pressure stems from petrochemical feedstock volatility in plastic bottle formats. Residential consumers in Riyadh's supermarket channels exhibit highest price sensitivity, while Jeddah's international hospitality buyers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Red Sea port congestion and container availability constraints on Asia-Saudi trade lanes intermittently disrupt PET resin and filtration membrane inbound flows. Supply concentrates in Saudi Arabia's domestic desalination infrastructure, with supplemental equipment sourcing from Germany, South Korea, and China. Raw material dependencies include PET resin, reverse osmosis membranes, and mineral additives for remineralization. Single-source vulnerability in membrane technology creates structural risk. Distribution runs through family-owned wholesale networks resisting ERP integration, fragmenting demand visibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's bottled water sector sits in early-cycle expansion, with pilgrimage tourism diversification and premium hospitality procurement creating penetration tailwinds that outpace mature-market substitution dynamics.
For Market Incumbents: Compound defensive positioning through backward integration into captive desalination feedstock agreements with Saudi Water Partnership Company, while accelerating SFDA certification investments to raise compliance barriers against informal competitors. Threats from municipal supply substitution in Riyadh's residential tier demand channel control reinforcement in hospitality direct procurement.
For New Entrants and Emerging Players: SFDA certification fast-track programs unlock white-space capture in Eastern Province hospitality corridors, where Dammam and Khobar commercial density exceeds premium mineral water distribution penetration. Target glass bottle trials in Riyadh's fine-dining segment as regulatory pressure on plastics intensifies. Go-to-market leverage rests on cold-chain technician training partnerships with Saudi Industrial Development Fund initiatives.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-market bottlers with established SFDA compliance and underutilized Eastern Province production capacity. Long-term viability across the projection horizon hinges on format diversification beyond polymer dependence. Watch NEOM sustainable packaging trial outcomes as inflection indicator for nationwide SASO restriction timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Temperature-controlled logistics guarantees secure hospitality procurement contracts in Jeddah's pilgrimage corridor. |
| SFDA Certification Investment | Third-party laboratory validation protocols extend product launch cycles but consolidate market share among compliant producers. |
| Glass Bottle Channel Trials | Returnable format experimentation in Riyadh restaurants anticipates SASO polymer restrictions ahead of regulatory enforcement. |
| Eastern Province Distribution Buildout | Dammam and Khobar hospitality corridors remain underserved relative to commercial density, creating geographic expansion opportunity. |
| Desalination Feedstock Partnership | Saudi Water Partnership Company allocation agreements stabilize input costs and secure capacity for scaled production. |
Study Parameters
Initial hypotheses were tested against primary input from bottler operations directors, hospitality procurement managers, cold-chain logistics coordinators, and SFDA compliance officers and refined through secondary validation. Secondary sources included SFDA facility licensing databases, Saudi Water Partnership Company desalination capacity disclosures, SASO technical regulation filings, and customs trade records for PET resin imports. Bottom-up volume modeling triangulated against top-down macroeconomic consumption benchmarks.
Variance decomposition across the projection horizon isolates segment-specific growth contributions from product type, packaging format, distribution channel, and end-user application dimensions. CAGRs were derived through exponential smoothing of annualized growth trajectories. Industry-specific forecast inputs incorporated desalination tariff revision schedules and pilgrimage tourism volume elasticity assumptions.
Decision-makers should treat outputs as directional under stable SFDA regulatory enforcement and continued Saudi Water Partnership Company feedstock allocation continuity; material deviation would warrant model refresh. Specific risk factors include accelerated municipal tap water quality improvements and unilateral polymer packaging restrictions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
CBD-Infused Beverages Market
Beverages
Herb Infused Water Market
Beverages
Morocco Bottled Water Market
Beverages
Alternative Waters (Plant Based Waters) Market
Beverages
Europe Smoothies Market
Beverages
Whole Grain Drinks Market
Beverages
GCC Bottled Water Market
Beverages
Ginger Ale Market
Beverages
United States and Australia Coconut Water Market
Beverages
Powdered Soft Drinks Market
Beverages
Ready to Drink Margarita Market
Beverages
Pineapple Juice Market
Beverages
Spring Water Market
Beverages
Birch Water Market
Beverages
Bottled Water Processing Market
Beverages
Oat Based Beverages Market