
 Maple Water Market | 2026-2036
Maple Water Market Size, Share, and Industry Trends Forecast 2026-2036
Maple Water Market Intelligence
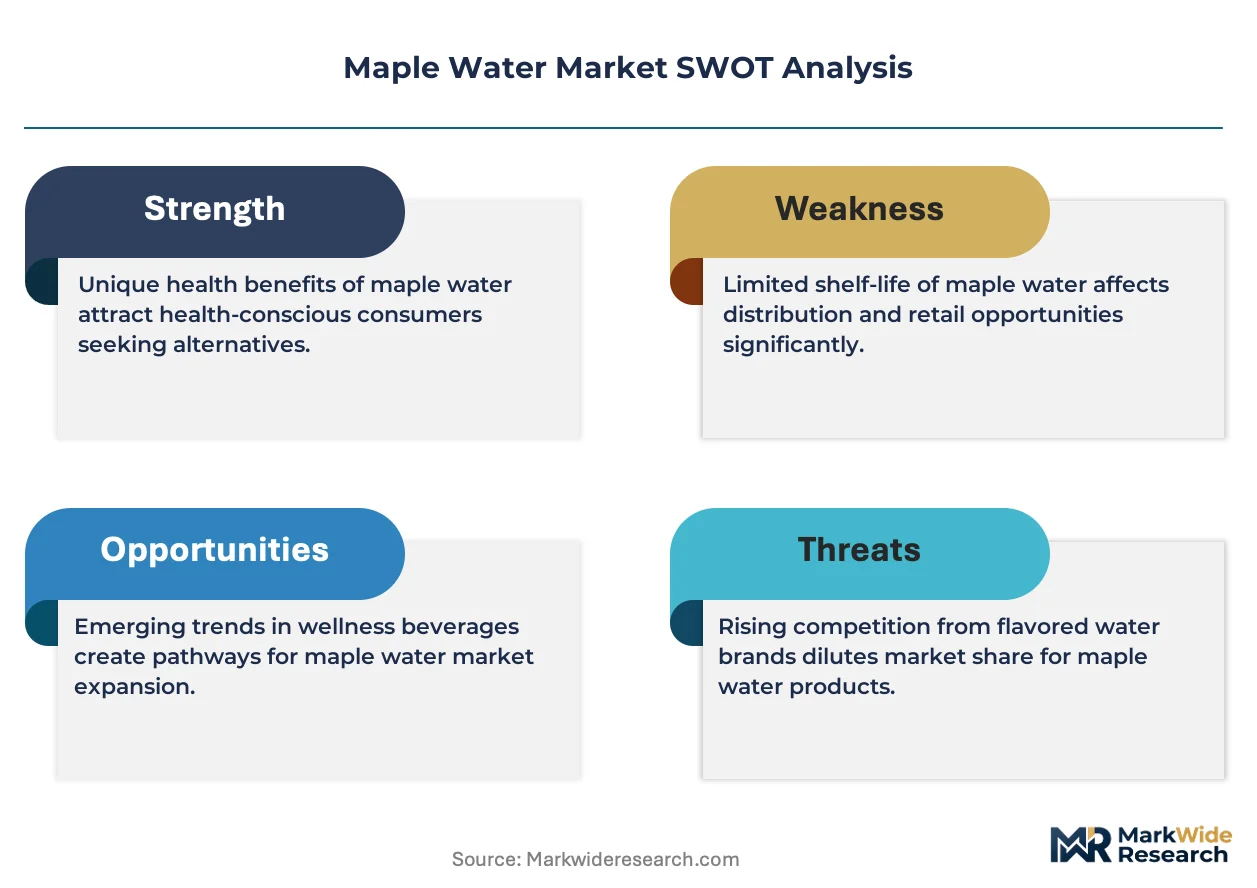
The gap between artisanal single-origin maple water and mass-market blended offerings is recalibrating how producers allocate capital and brand investment. Drink Simple leverages its Northeast supply partnerships to sustain premium positioning across specialty grocers. Lower Valley Beverage Company anchors its operations in Vermont's sugaring corridor, competing on terroir transparency rather than price. Maple 3 differentiates through organic certification and Quebecois provenance, dominating Francophone European channels.
Maple water denotes the sterile sap collected from Acer saccharum trees during early spring thaw, containing approximately 98% water with naturally occurring minerals, organic acids, and trace sugars below 4 Brix; it serves as a functional hydration base for direct consumption and as an ingredient in clean-label beverage formulations. Pure maple water occupies the highest margin tier due to minimal processing requirements and single-origin storytelling, while sparkling maple water represents the fastest-growing format as carbonation extends consumption occasions beyond seasonal peaks. Health food stores and online retail collectively control the most profitable distribution pathways, whereas supermarkets impose slotting fees that compress returns for smaller bottlers.
The US Food and Drug Administration scrutinizes plant water health claims under existing beverage labeling frameworks, while Canada's Canadian Food Inspection Agency enforces bilingual packaging and maple product identity standards that restrict dilution thresholds. The European Food Safety Authority evaluates novel food status for non-traditional EU-sourced waters, creating divergent market access timelines. Stakeholders must monitor how evolving organic certification harmonization between USDA and Canadian Organic Regime affects cross-border raw sap trade and finished goods positioning.
Market Dynamics
The FDA's evolving plant water labeling guidance is forcing importers to restructure compliance workflows while Quebec's sugaring corridor concentrates raw sap supply, creating asymmetric power dynamics between bottlers and forest leaseholders.
Growth Catalysts
- Clean-label beverage substitution:Functional hydration seekers in specialty retail channels are displacing conventional sports drinks with mineral-rich plant waters. Health food stores report sustained basket attachment rates for single-origin offerings.
- REACH-compliant packaging innovation:European bottlers adopting recyclable PET alternatives gain preferential shelf placement in EU Green Deal-aligned retail networks. EFSA novel food pathways for non-traditional waters are streamlining market entry timelines.
- Montérégie sugaring infrastructure:Quebec's year-round processing capabilities support consistent raw material flows to Francophone export markets. Vacuum tubing systems reduce labor intensity during narrow harvest windows.
Market Restraints
- Seasonal sap concentration risk:Northeast Kingdom and Montérégie harvests compress 80% of annual volume into 4-6 week windows, creating inventory financing stress for small bottlers.
- FDA labeling friction:Plant water health claim scrutiny under existing beverage frameworks forces reformulation or claim abandonment, delaying product launches.
- Sparkling water substitution:Flavored carbonated mineral waters from established European brands capture shelf space in premium grocery, compressing maple water trial rates.
Strategic Opportunities
- Organic certification harmonization:USDA-Canadian Organic Regime alignment creates cross-border raw sap trade efficiencies. Stakeholders can reposition finished goods in dual-certified channels.
- Carbonation format expansion:Sparkling maple water extends consumption occasions beyond spring harvest peaks. Specialty coffee shops and mixology channels represent underpenetrated trial venues.
- Direct-to-subscription channels:E-commerce platforms bypass supermarket slotting fee structures that currently compress margins for artisanal bottlers.
Industry Challenges
- Sugaring technician scarcity:Vacuum system operation and reverse osmosis calibration require specialized skills concentrated among aging Quebecois and Vermont operators.
- Bilingual packaging compliance:Canadian Food Inspection Agency enforcement of French-English labeling adds production line complexity for US-based bottlers serving cross-border markets.
- Raw sap quality standardization:Brix variability across forest stands complicates consistent finished product formulation, requiring real-time monitoring investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maple Water Market |
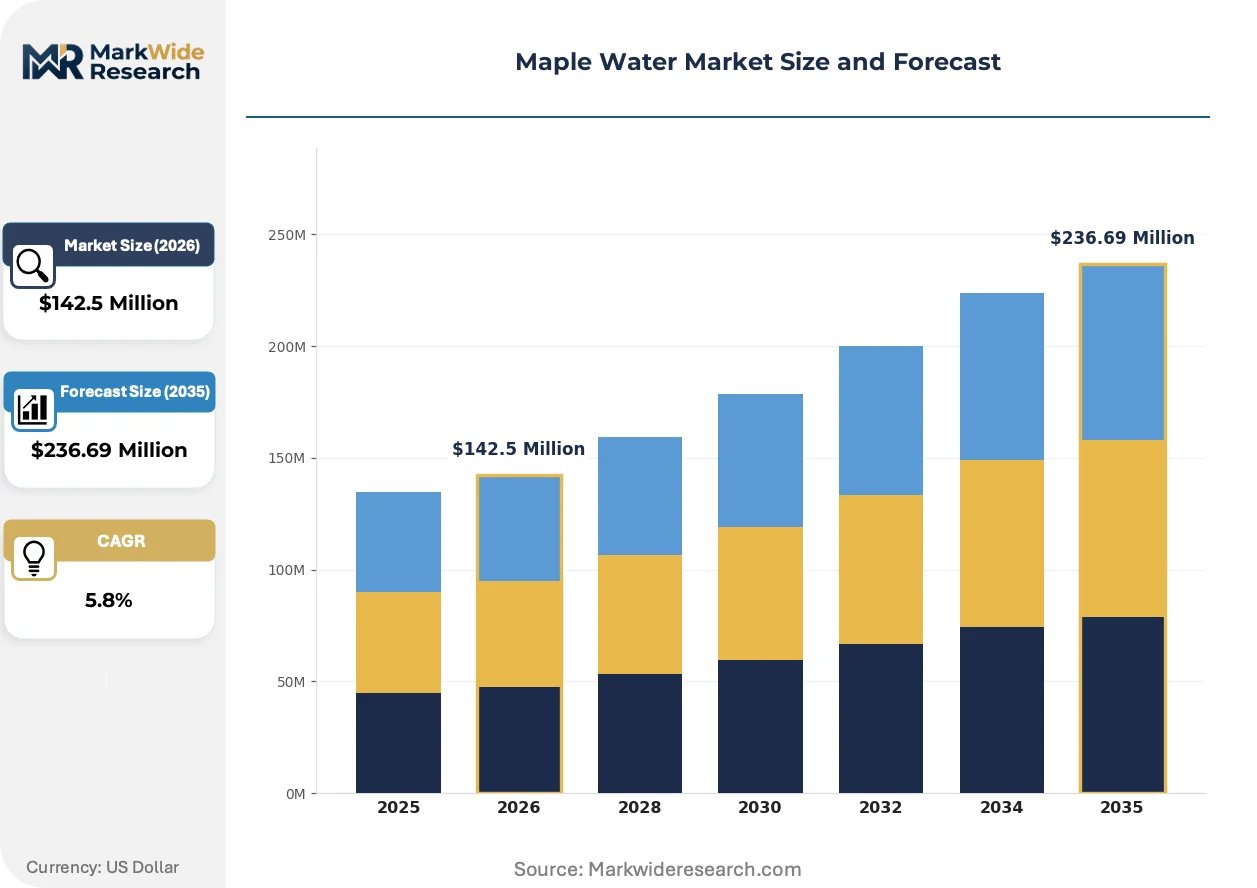
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $236.69 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pure Maple Water, Flavored Maple Water, Concentrated Maple Water, Sparkling Maple Water Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Health Food Stores End User: Consumers, Food Service, Beverage Manufacturers, Health Enthusiasts Package Type: Bottles, Tetra Packs, Cans, Pouches |
| Companies Covered | Drink Simple, Lower Valley Beverage Company, Maple 3, MapleMama Beverages, Kiki Maple Water, Feronia Forests, SEVA Maple Water, Drink HappyTree, Oviva Eau D’Erable Pure, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maple Water Market Strategic Shifts & Innovations
Processing technology and distribution architecture are restructuring competitive boundaries in plant waters. Three developments warrant particular attention.
Reverse osmosis concentration systems are reducing energy inputs in maple water processing. Mid-scale bottlers in Vermont's sugaring corridor are adopting membrane filtration at accelerating rates. This technology is converging with aseptic cold-fill lines to extend shelf life without thermal degradation of heat-sensitive organic acids.
EFSA's novel food status evaluations for non-EU sourced waters are creating divergent market access timelines. European bottlers face extended safety assessment periods for maple water imports. Specialty retailers in Germany and France are responding by prioritizing domestic birch and birch-blended offerings while awaiting regulatory clarity.
Health food store buyers are consolidating supplier relationships around certified organic provenance. Single-origin storytelling now dominates procurement criteria, displacing price-based vendor rotation. This pattern concentrates most visibly in Pacific Northwest co-op networks where terroir transparency commands premium positioning.
Maple Water Market Segmentation
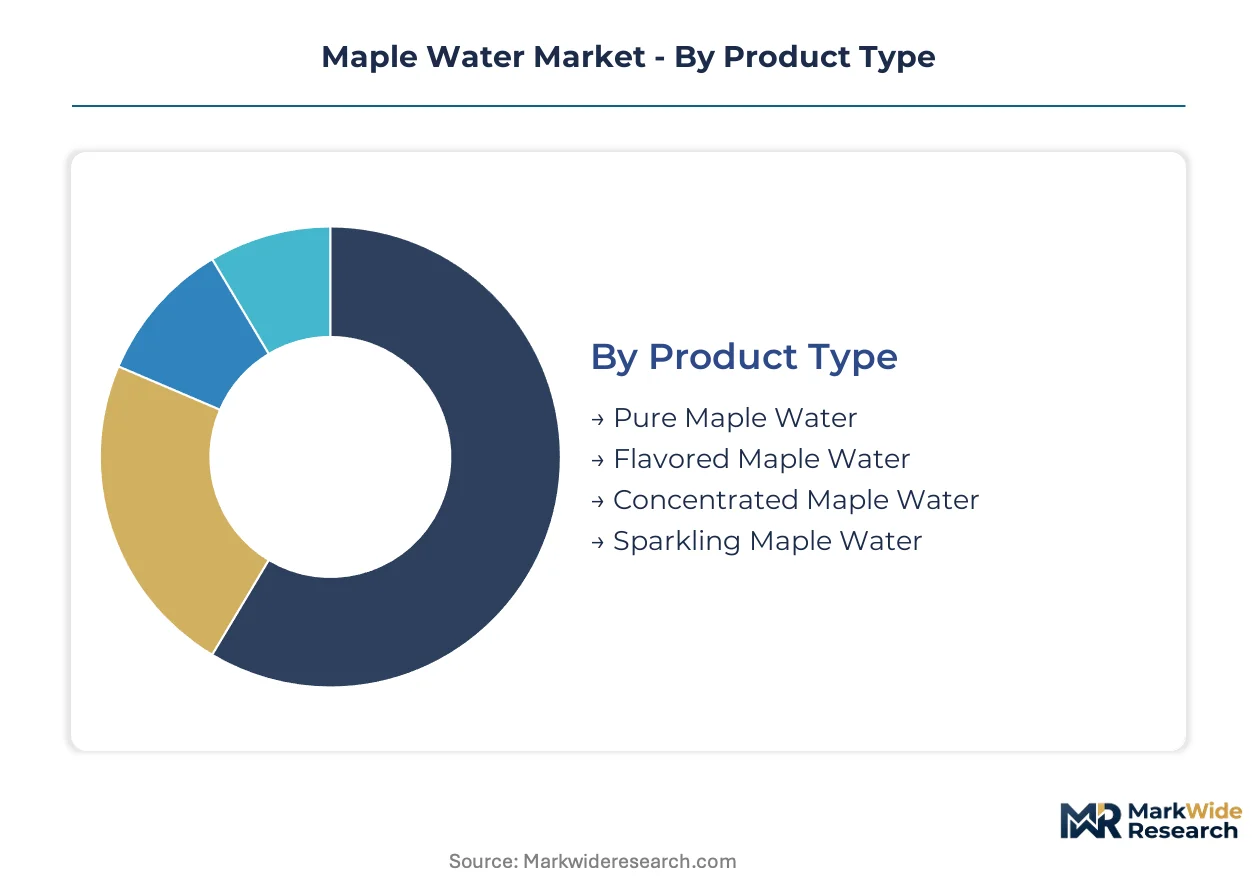
Maple water producers face divergent margin profiles across product formats and channel structures. Segmentation reveals where capital efficiency concentrates and where emerging formats threaten incumbent positioning.
Product Type:
Supply concentration in Quebec's Montérégie and Vermont's Northeast Kingdom directly shapes which product tiers command premium extraction versus commodity compression.
- Pure Maple Water:Unprocessed sterile sap from Acer saccharum with sub-4 Brix sugar content and intact mineral profiles. Demand concentrates in Pacific Northwest co-op networks and Francophone European specialty retail where single-origin storytelling commands shelf price premiums. FDA plant water labeling scrutiny forces claim restraint that paradoxically reinforces clean-label positioning.
- Sparkling Maple Water:Carbonated format extending consumption occasions beyond spring harvest windows. Specialty coffee shops and mixology channels in Germany and France drive trial adoption while EFSA novel food assessments delay full EU market penetration. This segment gains share fastest as carbonation equipment costs decline for mid-scale Vermont bottlers.
- Flavored Maple Water:Botanical or fruit-infused variants targeting flavored water migration. Health food stores in urban US markets report basket attachment rates comparable to coconut water.
- Concentrated Maple Water:Reverse osmosis reduced sap for ingredient applications. Beverage manufacturers in clean-label formulation channels absorb contracted volumes.
Today's leader: Pure Maple Water. Tomorrow's challenger: Sparkling Maple Water.
Distribution Channel:
Channel cost structures determine whether artisanal bottlers survive or surrender to consolidated retail gatekeepers.
- Health Food Stores:Pacific Northwest co-ops and Northeast specialty grocers consolidate supplier relationships around organic certification and terroir transparency. Slotting fee absence preserves margin for small Quebecois bottlers while procurement criteria now favor single-origin vendors over price-based rotation.
- Online Retail:Direct-to-subscription platforms bypass supermarket fee structures that compress returns for artisanal producers. E-commerce penetration climbs fastest in urban Canadian markets where bilingual packaging requirements add friction to cross-border supermarket placement.
- Supermarkets:Slotting fees and planogram competition favor volume-scaled producers with national distribution infrastructure.
- Convenience Stores:Impulse purchase positioning competes with established coconut and birch water SKUs for cooler space.
Health Food Stores extract premium positioning. Online Retail expands most quickly.
End User:
End-use fragmentation creates divergent specification requirements that reshape processing investments.
- Consumers:Direct consumption demand clusters in health-conscious demographics seeking sports drink alternatives. North American and European functional hydration seekers drive category volume.
- Beverage Manufacturers:Ingredient buyers require consistent Brix standardization for formulation stability. Real-time sap monitoring investments concentrate among suppliers serving this segment.
- Food Service:Specialty coffee and cocktail program adoption remains underpenetrated relative to retail channels.
- Health Enthusiasts:Early adopter cohort with highest willingness to pay for organic certification and provenance verification.
Consumers dominate volume. Beverage Manufacturers concentrate value.
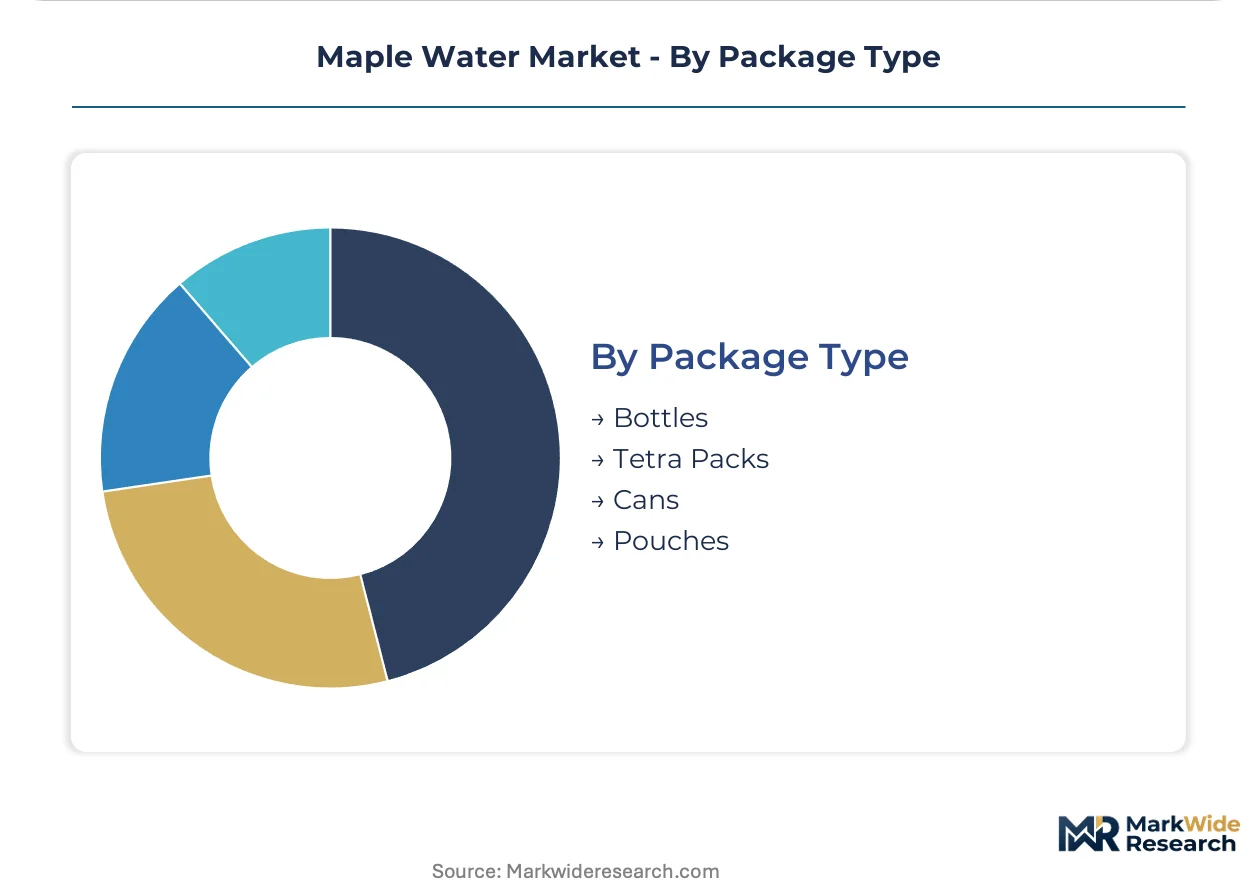
Package Type:
Packaging technology choices intersect with shelf-life requirements and EU Green Deal compliance trajectories.
- Bottles:Recyclable PET dominates North American retail placement. REACH-compliant alternatives gain preferential positioning in EU-aligned retail networks.
- Tetra Packs:Aseptic cold-fill compatibility extends distribution reach for ambient-stable products. European bottlers prioritize this format pending EFSA novel food clarity.
- Cans:Aluminum formats suit sparkling variants and on-premise consumption occasions. Mixology channel adoption drives niche demand.
- Pouches:Flexible packaging for concentrated and single-serve applications. Logistics efficiency appeals to direct-to-consumer subscription models.
Bottles anchor current placement. Tetra Packs offer expansion leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quebecois and Vermont sugaring technicians anchor the industry's geographic footprint, concentrating specialized vacuum system operation and reverse osmosis calibration skills in narrow harvest corridors.
United States
Health-conscious consumers in Pacific Northwest co-op networks and Northeast specialty grocers drive premium-tier demand for single-origin offerings. The FDA's evolving plant water labeling guidance forces importers to restructure compliance workflows around health claim restraint. Vermont's Northeast Kingdom hosts Lower Valley Beverage Company operations competing on terroir transparency.
Canada
Francophone European export channels absorb consistent raw material flows from year-round processing capabilities. The Canadian Food Inspection Agency enforces bilingual packaging and maple product identity standards that restrict dilution thresholds. Quebec's Montérégie cluster concentrates vacuum tubing systems reducing labor intensity during narrow harvest windows.
Germany
Specialty retailers prioritize domestic birch and birch-blended offerings while awaiting EFSA novel food clarity for maple water imports. REACH-compliant packaging innovation governs recyclable PET alternatives gaining preferential shelf placement in EU Green Deal-aligned retail networks. Berlin and Hamburg distribution hubs face extended safety assessment periods for non-traditional waters.
France
Mixology channels in Paris and Lyon drive trial adoption of sparkling formats extending consumption beyond spring harvest peaks. EFSA novel food status evaluations create divergent market access timelines for non-EU sourced waters. Maple 3 dominates Francophone European channels through organic certification and Quebecois provenance positioning.
United Kingdom
London health food stores consolidate supplier relationships around certified organic provenance and single-origin storytelling. GDPR compliance overlays beverage labeling requirements for direct-to-subscription e-commerce platforms. Greater Manchester and Birmingham logistics nodes handle cross-border raw sap trade awaiting USDA-Canadian Organic Regime harmonization.
Maple Water Market Key Industry Players
Top-tier vendors anchor premium positioning through Northeast supply partnerships, while mid-scale bottlers compete on terroir transparency and organic certification. The vendor base stratifies across three archetypes: terroir-focused single-origin specialists, carbonation-format innovators, and clean-label ingredient suppliers serving beverage manufacturers. Dominant competitive moves include direct-to-subscription channel expansion bypassing supermarket slotting fees, and backward integration into sugaring infrastructure securing captive raw sap supply.
Within the terroir-specialist tier, Drink Simple and Lower Valley Beverage Company exemplify divergent geographic anchoring strategies. Drink Simple leverages Northeast supply partnerships to sustain premium positioning across specialty grocers. Lower Valley Beverage Company anchors operations in Vermont's sugaring corridor, competing on transparency rather than price. Maple 3 occupies a distinct position bridging Quebecois provenance with Francophone European channel dominance through organic certification credentials.
| Leading Market Players |
|---|
| Drink Simple |
| Lower Valley Beverage Company |
| Maple 3 |
| MapleMama Beverages |
| Kiki Maple Water |
| Feronia Forests |
| SEVA Maple Water |
| Drink HappyTree |
| Oviva Eau D'Erable Pure |
| Others |
Cost & Logistics Intelligence
Health food store procurement consolidation in Pacific Northwest co-op networks and Northeast specialty grocers anchors premium extraction through terroir transparency rather than volume discounts, creating a bifurcated pricing architecture where single-origin storytelling commands shelf price premiums while mass-market blended offerings compete on cost efficiency.
Pricing Analysis
Raw maple sap and finished maple water trade on fundamentally unbundled terms, with forest leaseholders capturing value upstream and bottlers extracting margin through processing and brand positioning. Three-tier pricing structure across premium single-origin, standard organic-certified, and economy blended tiers separates producers by certification grade and provenance documentation. Cost compression in the economy tier is intensifying because supermarket slotting fees force smaller bottlers toward direct-to-subscription channels. Beverage manufacturers serving as ingredient buyers exhibit lowest price sensitivity due to formulation stability requirements, whereas convenience store impulse purchasers drive hardest bargain negotiations.
Supply Chain Analysis
Canadian Food Inspection Agency bilingual packaging mandates and maple product identity standards reshape sourcing calculus for US-based bottlers serving cross-border markets, forcing production line investments or third-party Quebecois co-packing arrangements. Raw sap supply concentrates in Quebec's Montérégie cluster and Vermont's Northeast Kingdom, with vacuum tubing systems and reverse osmosis concentration technology drawing from sugaring infrastructure investments made over decades. Single-source vulnerability runs through the narrow 4-6 week harvest window that compresses 80% of annual volume. Distribution runs through health food store networks and direct-to-subscription platforms that bypass supermarket gatekeeper fees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's evolving plant water labeling guidance operates as a regulatory compounder, with health claim scrutiny paradoxically reinforcing clean-label positioning that drives premium-tier demand among functional hydration seekers.
For Market Incumbents: Lock in captive raw sap supply through long-term forest leasehold arrangements in Vermont's Northeast Kingdom before sugaring technician scarcity intensifies. Secure dual USDA-Canadian Organic Regime certification to capture cross-border trade efficiencies as harmonization proceeds. Carbonation format expansion represents the priority defensive move against sparkling mineral water substitution in European premium grocery. For New Entrants and Emerging Players: EFSA novel food status evaluations for non-EU sourced waters in Germany and France open a window for white-space entry through domestic birch-blended positioning while regulatory clarity for maple water imports remains pending. Target underpenetrated specialty coffee shop and mixology channels in Paris and Lyon where sparkling format trial adoption outpaces retail shelf competition. Lead with organic certification and Quebecois provenance credentials to satisfy consolidated procurement criteria in Pacific Northwest co-op networks. For Investors and Strategic Acquirers: Beverage conglomerates seeking clean-label portfolio expansion are the most active acquirer in this space, with terroir-focused single-origin specialists commanding premium multiples over commodity-blended operations. Vertically integrated mid-scale bottlers with captive sugaring infrastructure and established direct-to-subscription channels present the most defensible acquisition profile across a 5-10 year viability window. Monitor EFSA novel food pathway resolution timelines as the critical inflection signal for European market entry capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sugaring Infrastructure | Captive raw sap supply secures margin control against forest leaseholder power asymmetry. |
| Carbonation Format Line Extension | Sparkling variants capture mixology channel trial adoption beyond seasonal harvest peaks. |
| Dual Organic Certification Investment | USDA-Canadian Organic Regime alignment unlocks cross-border raw sap trade efficiencies. |
| Direct-to-Subscription Channel Launch | E-commerce platforms bypass supermarket slotting fees that compress artisanal bottler returns. |
| EFSA Novel Food Regulatory Pathway Navigation | Early compliance positioning accelerates market access timelines for German and French retail entry. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary field engagement with sugaring technicians, health food store category buyers, beverage manufacturer procurement leads, and regulatory affairs specialists at FDA and CFIA with secondary validation from customs trade records, organic certification databases, and retail audit data. Bottom-up volume modeling across product formats and distribution channels triangulated against top-down category sizing derived from trade association disclosures and import-export documentation.
Segment-weighting approaches applied differential growth assumptions across pure, sparkling, flavored, and concentrated product tiers, with channel-specific CAGRs derived from health food store, online retail, supermarket, and convenience store penetration trajectories over the projection horizon. Raw sap Brix variability, seasonal harvest concentration, and EFSA novel food assessment timelines served as industry-specific forecast inputs alongside packaging format adoption curves and organic certification harmonization progress.
Revisions become necessary when FDA labeling guidance finalization, EFSA novel food determinations, or sugaring technician labor availability constraints materialize differently than modeled assumptions anticipate. Forecasts reflect documented expectations regarding regulatory pathway resolution, harvest yield stability, and premium-channel procurement consolidation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Beverage Dispenser Market
Beverages
Africa Dairy Based Beverages Market
Beverages
Plant Based Protein Beverages Market
Beverages
North America Fruits and Vegetables Juice Market
Beverages
Middle East and Africa Ready to Drink Beverages Market
Beverages
Bottled Beverages Market
Beverages
South East Asia Bottled Water Market
Beverages
Soft Serve Premix Market
Beverages
Europe Ready-To-Drink Beverages Market
Beverages
Saudi Arabia Food & Beverage Market
Beverages
Citrus Water Market
Beverages
Growlers Market
Beverages
Saudi Arabia Bottled Water Market
Beverages
Asia Pacific Fermented Drinks Market
Beverages
Hydrogen Water Bottle Market
Beverages
Low Calorie RTD Beverages Market