
 Rose Floral Water Market | 2026-2036
Rose Floral Water Market Size, Share, and Industry Trends Forecast 2026-2036
Rose Floral Water Market Analytics
EU Green Deal sustainability criteria is restructuring procurement standards across European cosmetics supply chains. Alteya Inc. leverages its Bulgarian rose valley sourcing to sustain organic certification premiums in personal care formulations. Dabur India Ltd. anchors its Ayurvedic heritage positioning in domestic and Middle Eastern markets. Iran Golab Co. competes through geographic specialization in Kashan rose cultivation, controlling traditional distillation output for food-grade and cosmetic applications.
Rose floral water denotes the aqueous co-product of steam distillation from Rosa damascena or Rosa centifolia petals, typically containing trace essential oil components below 0.1 percent concentration and used as a functional ingredient in skincare, flavoring, and therapeutic applications. Hydrosol formulations lead volume consumption in cosmetics manufacturing due to their milder sensory profile and broader formulation compatibility compared to concentrated essential oils. Aromatic water segments command premium positioning in Middle Eastern food and beverage applications, where traditional rose water flavoring carries cultural certification value.
REACH compliance in Europe governs cosmetic ingredient registration and restricts residual solvent thresholds, while FDA oversight in the United States classifies food-grade rose water under flavoring substance regulations with specific purity benchmarks. BIS standards in India mandate microbial load limits for hydrosols sold in domestic retail channels. Stakeholders must monitor evolving organic certification reciprocity between EU and non-European producing regions to secure uninterrupted market access for premium distilled water exports.
Market Dynamics
EU Green Deal ingredient traceability mandates are compressing supply chains toward certified organic hydrosol producers with verifiable Rose Valley sourcing, forcing reformulation investments across European personal care manufacturers.
Growth Catalysts
- EU Green Deal compliance requirements:REACH and CSRD disclosure rules compel cosmetics formulators to document hydrosol origin and carbon footprint, accelerating procurement from Bulgarian cooperatives with established organic certification chains.
- Steam-distillation cooperatives in Bulgaria's Rose Valley:Traditional artisanal producers command premium positioning through geographic indication recognition and controlled cultivation of Rosa damascena cultivars.
- Ayurvedic personal care expansion:Middle Eastern and South Asian wellness markets elevate rose water from flavoring ingredient to therapeutic positioning, creating parallel demand channels beyond European cosmetics.
Market Restraints
- Input cost volatility in organic rose cultivation:Climate variability in Bulgaria and Iran affects petal yield consistency, compressing margins for distillers locked into fixed-price annual contracts.
- Supply concentration in Kashan and Kazanlak corridors:Over 60 percent of food-grade and cosmetic hydrosol output originates from two narrow geographic bands, exposing buyers to localized harvest failures or geopolitical friction.
- Substitution pressure from synthetic fragrance compounds:Biotechnology-derived rose odorants from Givaudan and Firmenich laboratories achieve cost parity below premium natural hydrosol thresholds.
Strategic Opportunities
- Underpenetrated North American therapeutic applications:FDA flavoring substance classification permits wellness positioning expansion beyond ethnic food retail into spa and clinical aromatherapy channels.
- CSRD-aligned supply chain transparency tools:Blockchain-enabled provenance tracking allows Bulgarian producers to monetize full traceability premiums previously captured by European brand intermediaries.
- Convergence of hydrosol extraction with supercritical CO2 processing:Hybrid facilities capture both aromatic water and essential oil fractions, improving petal utilization economics for mid-scale distillers.
Industry Challenges
- Organic certification reciprocity gaps:EU recognition of Iranian and Moroccan organic standards remains inconsistent, blocking market access for otherwise compliant Kashan producers.
- Capex requirements for distillation modernization:Traditional copper alembic cooperatives face capital constraints to install stainless steel column systems meeting BIS microbial load specifications for export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rose Floral Water Market |
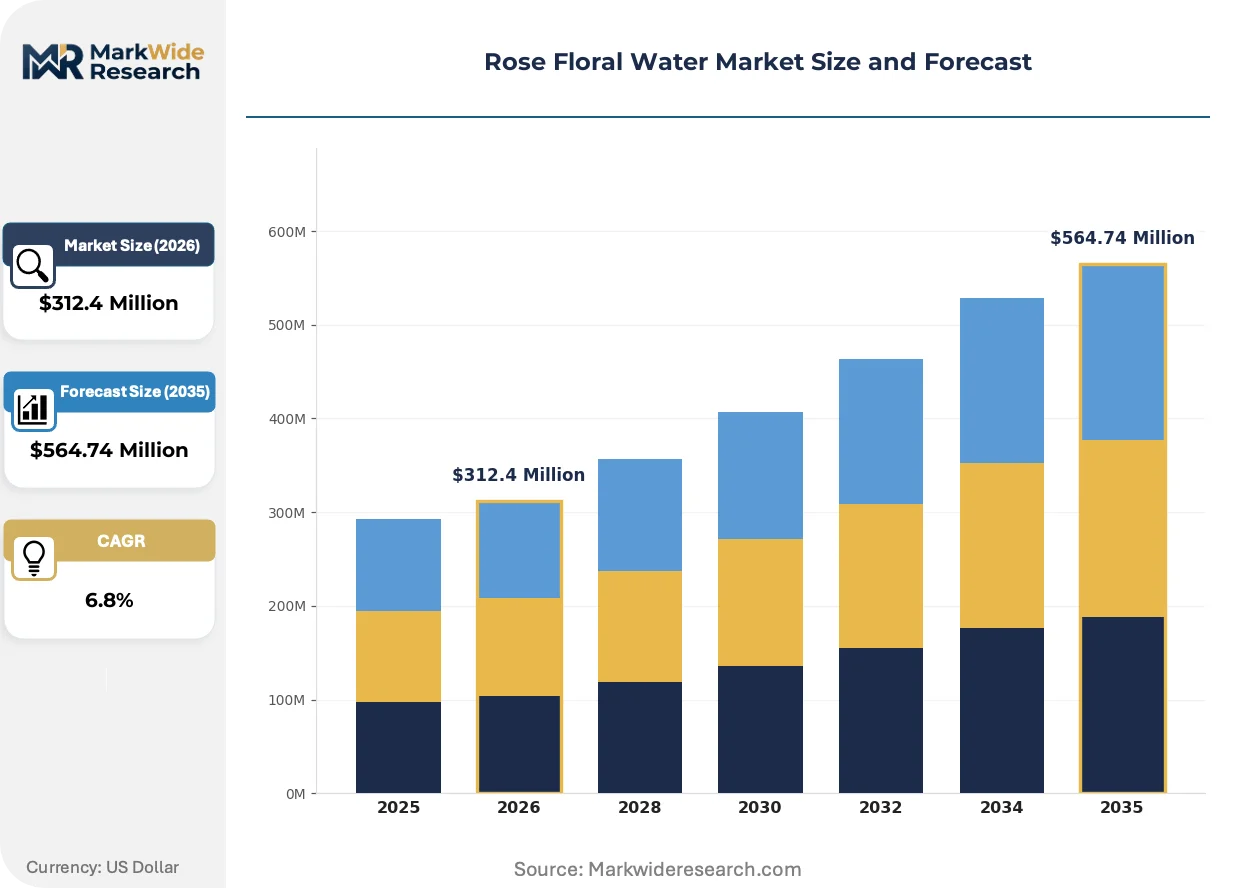
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Distilled Water, Aromatic Water, Hydrosol, Essential Oil Application: Cosmetics, Food & Beverage, Aromatherapy, Personal Care Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales End User: Pharmaceuticals, Cosmetics Manufacturers, Restaurants, Home Users |
| Companies Covered | SVA Naturals, Taj Agro International, Bioprocess LLC, Alteya Inc., Dabur India Ltd., MEENA PERFUMERY, Iran Golab Co., Eve Hansen, Poppy Austin Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rose Floral Water Market Evolving Landscape
Steam-distillation infrastructure is fragmenting into scalable, decentralized units while regulatory disclosure requirements force digitization of provenance records across the value chain.
Membrane filtration technology for hydrosol stabilization is modularizing quality control across small-batch producers. Bulgarian and Iranian distillers now deploy ceramic microfiltration units previously restricted to pharmaceutical-grade facilities. This modularization enables cooperatives to achieve shelf-life extension without centralized processing investments, compressing the quality gap between artisanal and industrial outputs.
REACH substance registration deadlines are tightening residual solvent thresholds for cosmetic-grade hydrosols. ECHA documentation requirements now mandate full supply chain disclosure from petal harvest through final formulation. European personal care manufacturers are responding by consolidating supplier bases to three certified organic sources with pre-validated registration dossiers.
Direct-to-brand contracting is displacing layered trader intermediaries in hydrosol procurement. French and German cosmetics formulators now source aromatic water through annual offtake agreements with named Rose Valley cooperatives rather than regional distributors. This pattern concentrates most visibly in premium skincare segments where origin storytelling commands measurable price premiums.
Rose Floral Water Market Segmentation
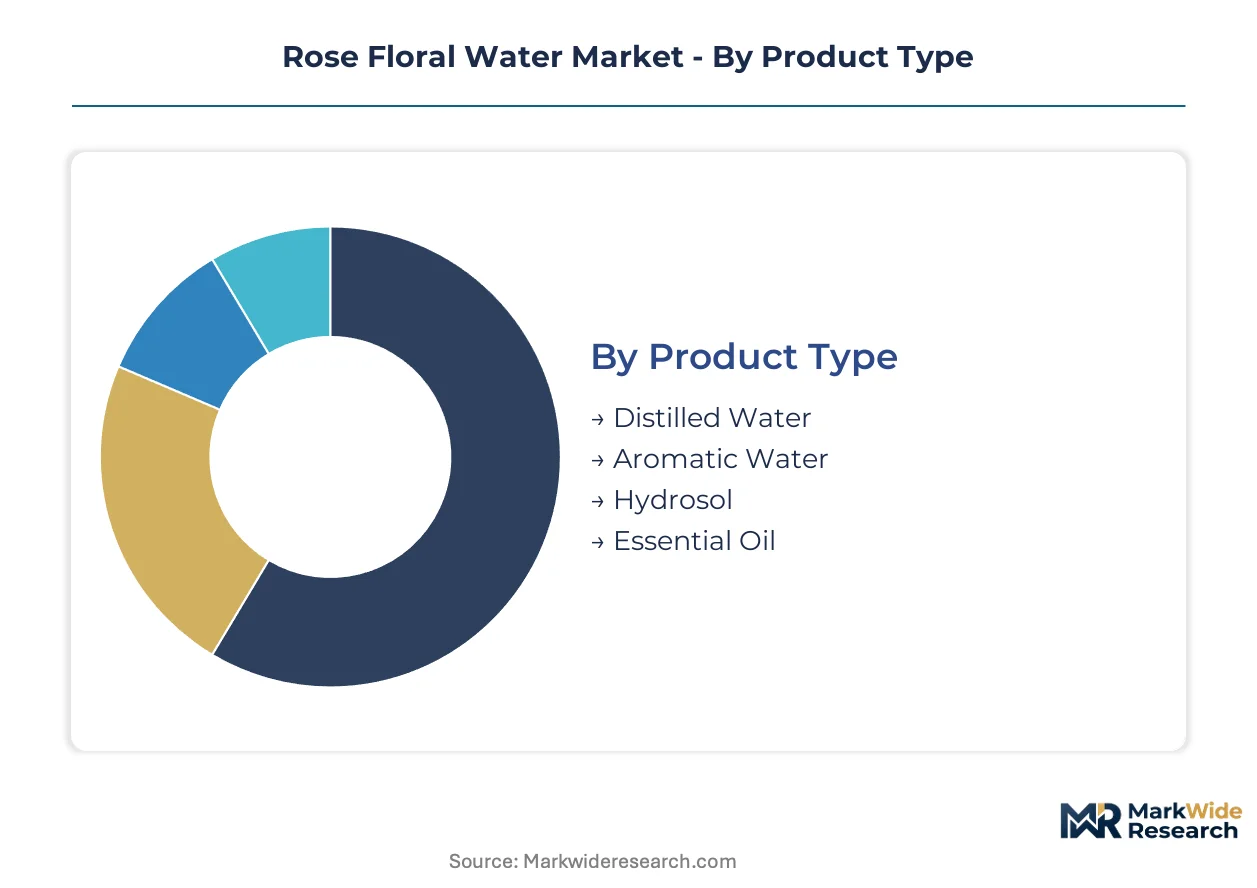
Rose floral water procurement decisions hinge on certification grade, formulation compatibility, and provenance documentation. Manufacturers segment offerings across extraction method, purity tier, and end-use specification to capture divergent buyer requirements spanning European cosmetics, Middle Eastern food traditions, and therapeutic applications.
Product Type:
Buyers prioritize extraction method and residual oil concentration when selecting product type, with formulation requirements dictating specification choice.
- Hydrosol:Aqueous co-product of steam distillation containing trace essential oil components below 0.1 percent concentration. Demand concentrates in European cosmetics manufacturing where REACH-compliant hydrosols with verified Rose Valley sourcing command procurement premiums from French and German personal care formulators facing EU Green Deal traceability mandates.
- Aromatic Water:Traditional distillation output with higher volatile oil content, typically 0.02-0.05 percent. Middle Eastern food and beverage applications in Iran, Saudi Arabia, and UAE elevate this grade through cultural certification value, with Kashan-sourced material retaining preference for authenticity positioning in premium retail channels.
- Distilled Water:Lower concentration variant produced through repeated fractional distillation. Bulgarian cooperatives supply this grade for industrial cosmetic formulations where cost efficiency outweighs aromatic intensity requirements.
- Essential Oil:Concentrated lipophilic extract requiring dilution before application. Limited direct consumption as floral water substitute; instead functions as upstream input for hydrosol blending in mass-market personal care products.
Hydrosol leads on scale; aromatic water leads on momentum.
Application:
End-use specification intensity varies sharply across segments, with regulatory compliance thresholds creating divergent procurement patterns.
- Cosmetics:Skin toners, serums, and moisturizers incorporating hydrosol as functional base ingredient. ECHA registration requirements and CSRD disclosure rules compel formulators to document carbon footprint and origin, consolidating procurement toward Bulgarian cooperatives with pre-validated organic certification chains.
- Personal Care:Hair treatments, body mists, and hygiene products emphasizing milder sensory profiles. India's Ayurvedic heritage positioning drives domestic demand expansion, with Dabur and similar houses sourcing certified organic material for Middle Eastern export markets.
- Food & Beverage:Traditional flavoring in Middle Eastern sweets, beverages, and confectionery. Iranian Kashan producers dominate this segment through geographic indication recognition, though EU organic certification reciprocity gaps restrict market access for otherwise compliant distillers.
- Aromatherapy:Therapeutic and spa applications requiring pharmaceutical-grade purity. Underpenetrated in North American clinical channels despite FDA flavoring substance classification permitting wellness positioning expansion.
Cosmetics dominates current procurement volumes; personal care shows steepest expansion trajectory.
Distribution Channel:
Channel selection reflects buyer scale, certification verification requirements, and geographic proximity to production clusters.
- Direct Sales:Annual offtake agreements between named Rose Valley cooperatives and European cosmetics manufacturers. French and German formulators now bypass regional distributors to secure pre-validated REACH dossiers and origin storytelling for premium skincare positioning.
- Specialty Stores:Premium retail channels emphasizing organic certification and geographic indication. Concentrated in urban centers with established wellness consumer bases.
- Online Retail:E-commerce platforms serving home users and small-scale cosmetics producers. Blockchain-enabled provenance tracking allows Bulgarian producers to monetize full traceability premiums previously captured by brand intermediaries.
- Supermarkets:Mass-market distribution for food-grade aromatic water in Middle Eastern markets. Volume concentration in Saudi Arabia and UAE retail chains.
Direct sales commands the highest value capture; online retail is expanding most quickly.
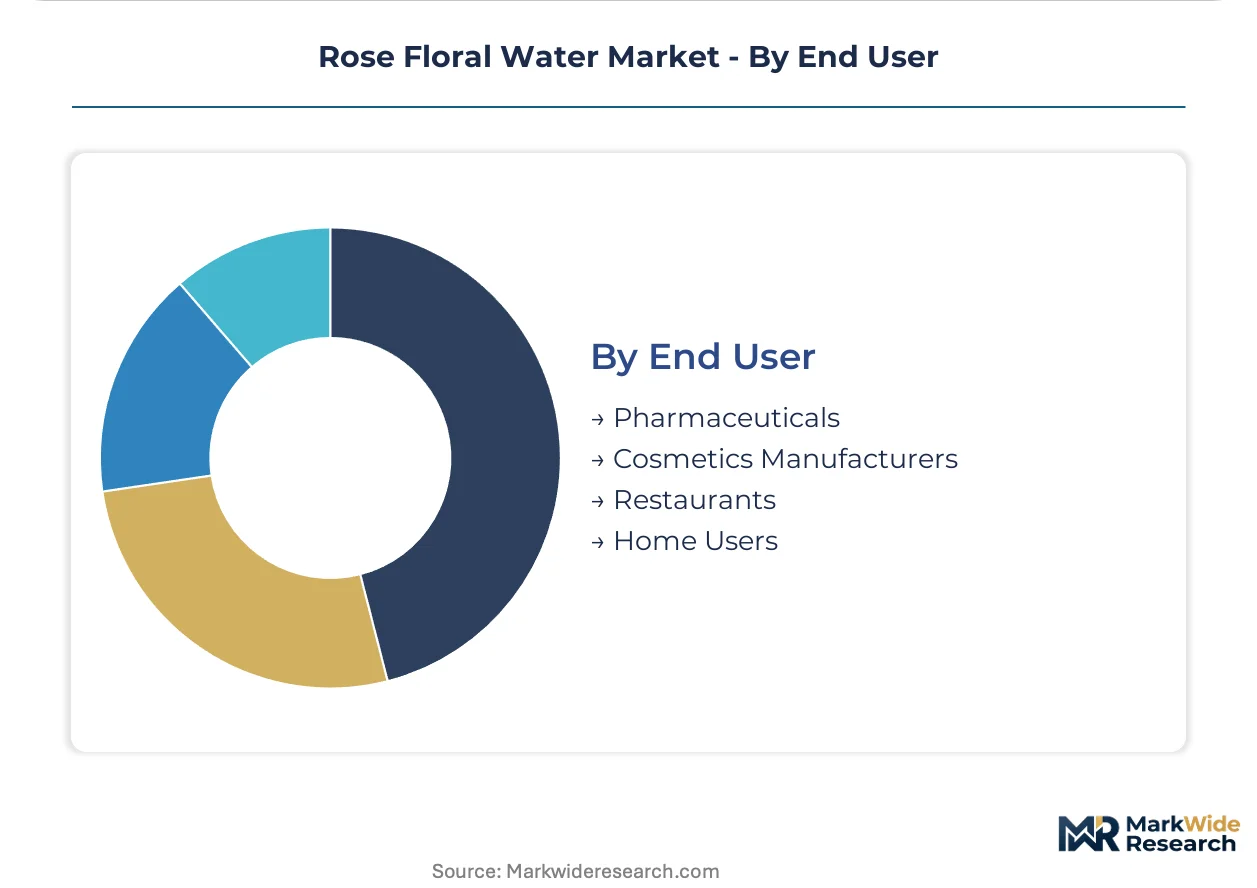
End User:
User scale and regulatory exposure determine specification intensity, with pharmaceutical and cosmetics manufacturers facing the most stringent compliance requirements.
- Cosmetics Manufacturers:Large-scale formulators requiring documented organic certification and REACH registration. Procurement consolidation toward three certified sources with validated supply chain disclosure from petal harvest through final formulation.
- Pharmaceuticals:Clinical and therapeutic applications demanding BIS microbial load compliance in India, with similar purity benchmarks enforced by national pharmaceutical regulators in other producing regions.
- Restaurants:Food service procurement of food-grade aromatic water for traditional cuisine preparation. Concentrated in Middle Eastern and South Asian metropolitan markets.
- Home Users:Direct consumption for skincare, culinary, and wellness applications. Price-sensitive segment with limited certification verification capacity.
Cosmetics manufacturers anchor procurement volume; pharmaceuticals offers the highest margin capture potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bulgarian distillers anchor the skilled artisan workforce concentrated in Kazanlak, where generational expertise in copper alembic operation sustains premium hydrosol output for European cosmetics formulators.
Bulgaria
Rose Valley cooperatives supply certified organic hydrosol to French and German personal care manufacturers facing EU Green Deal traceability mandates. ECHA registration requirements compel documented carbon footprint disclosure from petal harvest through final formulation. Kazanlak-based distillers deploy blockchain-enabled provenance tracking to capture premiums previously absorbed by brand intermediaries.
Iran
Kashan cultivation corridors dominate food-grade aromatic water production for Middle Eastern confectionery and beverage applications. Organic certification reciprocity gaps with EU standards restrict market access for otherwise compliant distillers. Traditional distillation households in the Kashan-Isfahan axis maintain geographic indication recognition for authentic rose water positioning in premium retail channels.
India
Ayurvedic heritage positioning drives domestic demand expansion for therapeutic-grade hydrosol in personal care formulations. BIS microbial load limits govern retail distribution of hydrosols sold through domestic channels. Kannauj-based perfumery clusters supply both food-grade and cosmetic material to Middle Eastern export markets through established trade relationships.
Germany
Cosmetics manufacturers consolidate procurement toward three certified organic sources with pre-validated REACH dossiers. CSRD disclosure rules accelerate supplier base rationalization to reduce compliance documentation burden. Hamburg and Munich-based formulators now execute annual offtake agreements directly with named Bulgarian cooperatives rather than regional distributors.
France
Prestige skincare houses leverage Rose Valley origin storytelling to command measurable price premiums in global distribution. ANSM cosmetic ingredient oversight aligns with REACH substance registration deadlines. Grasse and Paris-based manufacturers bypass layered trader intermediaries to secure direct contracting with steam-distillation cooperatives for provenance verification.
Rose Floral Water Market Competitive Landscape
Capital-heavy producers compete with asset-light designers as copper alembic cooperatives face capital constraints while digital-native brands monetize origin storytelling without distillation assets. The vendor base clusters around three strategic archetypes: geographic specialists controlling traditional cultivation corridors, vertically integrated Ayurvedic houses with captive supply chains, and asset-light wellness brands sourcing through contract manufacturing. Consolidation pressure concentrates in European procurement channels where REACH compliance costs favor suppliers with pre-validated registration dossiers. Dominant competitive moves include direct-to-brand contracting displacing regional distributors and hybrid facility investments capturing both hydrosol and essential oil fractions.
Within the geographic specialist tier, Alteya Inc. and Iran Golab Co. exemplify provenance-anchored positioning through Bulgarian and Kashan cultivation control respectively. Dabur India Ltd. occupies a distinctive position as an Ayurvedic heritage house with backward integration into domestic hydrosol sourcing for Middle Eastern export markets. These three entities represent divergent competitive vectors: European regulatory compliance, traditional geographic indication, and wellness heritage expansion.
| Leading Market Players |
|---|
| SVA Naturals |
| Taj Agro International |
| Bioprocess LLC |
| Alteya Inc. |
| Dabur India Ltd. |
| MEENA PERFUMERY |
| Iran Golab Co. |
| Eve Hansen |
| Poppy Austin Ltd |
| Others |
Value Network & Pricing Analysis
Skilled copper alembic operators concentrated in Kazanlak, Bulgaria, command wage premiums that widen spreads between artisanal hydrosol tiers and industrial distilled water grades. Labor-cost differentials between traditional cooperatives and mechanized facilities in Iran and India create three distinct pricing bands across the procurement landscape.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified organic hydrosols from conventional aromatic water and industrial distilled grades. Price differentiation rests on organic certification tier and Rose Valley geographic indication, with EU Green Deal compliance adding documentation premiums. Cost compression in the economy tier is intensifying because synthetic biotechnology substitutes from fragrance houses achieve cost parity below natural thresholds. Home users in direct retail channels exhibit highest price sensitivity; prestige skincare houses show least sensitivity due to origin storytelling requirements.
Supply Chain Analysis
EU Green Deal local-content mandates are reshaping sourcing toward Bulgarian cooperatives with verifiable organic certification chains. Supply concentrates in Bulgaria, Iran, and India, with raw material dependencies on Rosa damascena petal harvests, copper alembic equipment, and stainless steel column systems for export-grade microbial compliance. Single-source vulnerability runs through the Kashan-Kazanlak corridor concentration, where localized climate events or geopolitical friction disrupt annual offtake agreements. Distribution runs through direct annual contracts between named cooperatives and European cosmetics manufacturers, displacing layered trader intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
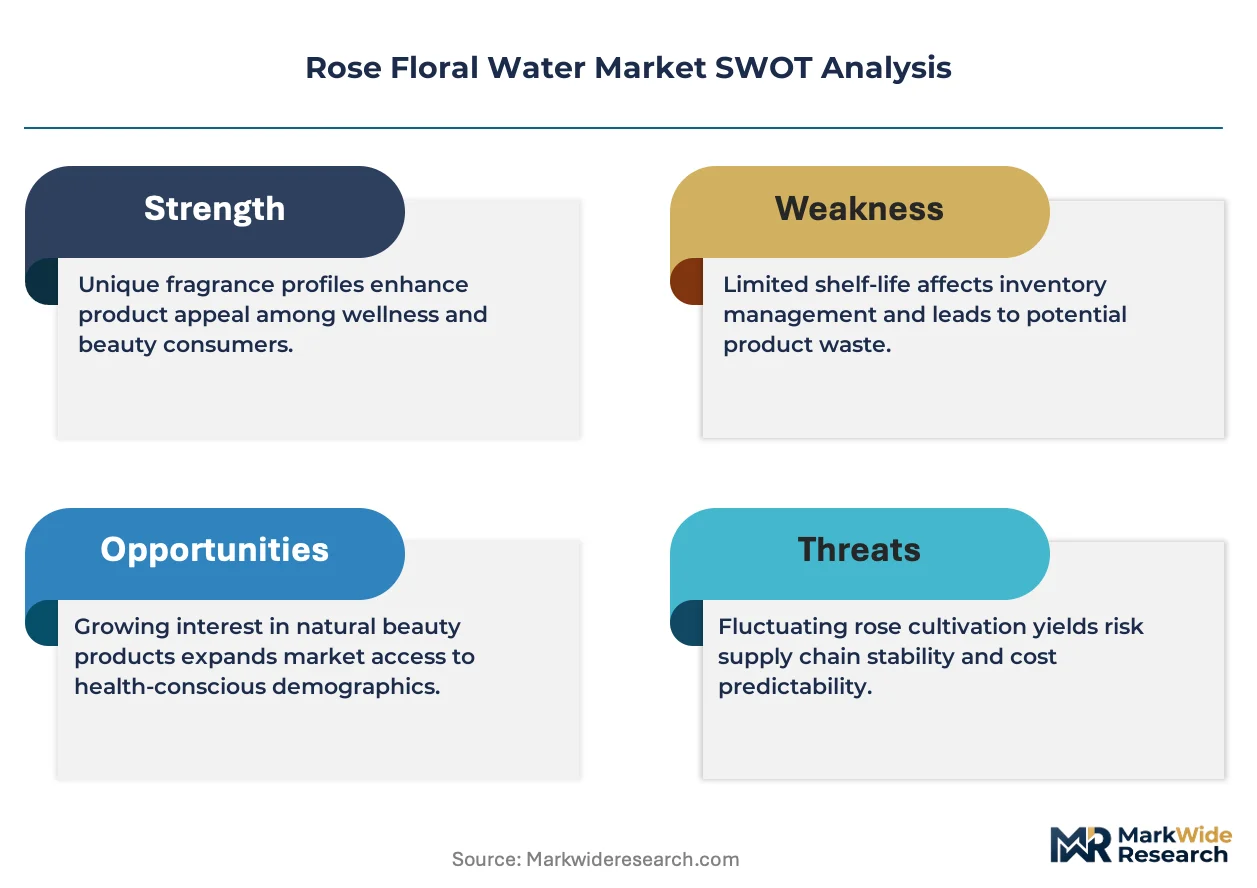
Rose floral water offers margin-expansion potential as blockchain-enabled provenance tracking allows producers to capture premiums previously absorbed by brand intermediaries. Cost compression in synthetic substitutes is forcing natural producers toward certification-grade differentiation.
For Market Incumbents: Anchor procurement consolidation through pre-validated REACH dossiers and CSRD-aligned supply chain transparency tools. Defend against synthetic biotechnology substitutes from Givaudan and Firmenich by deepening backward integration into Rose Valley cultivation control. Prioritize hybrid facility investments capturing both hydrosol and essential oil fractions to improve petal utilization economics. For New Entrants and Emerging Players: Wellness spas and clinical aromatherapy channels in North America represent the most penetrable white-space target given FDA flavoring substance classification permitting therapeutic positioning expansion. Ayurvedic personal care in Middle Eastern export markets offers secondary entry through heritage positioning partnerships. Pursue contract manufacturing relationships with asset-light digital-native brands seeking provenance storytelling without distillation capital. For Investors and Strategic Acquirers: European cosmetics manufacturers with CSRD disclosure burdens are the most active acquirer in this space, seeking captive supply to rationalize compliance documentation. Long-term viability hinges on organic certification reciprocity resolution between EU and non-European producing regions. Monitor blockchain provenance adoption rates as inflection indicator for traceability premium capture shifting from intermediaries to origin producers.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Brand Contracting | Bypasses regional distributors to secure REACH-compliant provenance documentation for French and German formulators. |
| Hybrid Extraction Facility Investment | Captures both hydrosol and essential oil fractions, improving economics for mid-scale Bulgarian and Iranian distillers. |
| Blockchain Provenance Implementation | Monetizes full traceability premiums through ECHA-aligned carbon footprint disclosure from petal harvest forward. |
| Organic Certification Reciprocity Advocacy | Unlocks EU market access for Kashan producers currently blocked by inconsistent recognition of Iranian standards. |
| North American Therapeutic Channel Expansion | Leverages FDA flavoring classification to position aromatic water in spa and clinical aromatherapy beyond ethnic retail. |
Research Methodology
Bottom-up cosmetics formulation modeling reconciled against top-down hydrosol production tracking forms the analytical core of this study. Primary interviews with Rose Valley cooperative managers, French and German procurement directors, regulatory affairs leads at ECHA, and Ayurvedic brand supply planners combined with secondary validation from EU customs records, BIS microbial load filings, FSSAI food-grade registrations, and ECHA substance registration databases. Top-down trade flow analysis triangulates against bottom-up capacity assessments across Bulgarian, Iranian, and Indian distillation clusters.
Historical trendline analysis of certified organic hydrosol premiums against conventional grades established baseline price elasticity patterns across the projection horizon. Segmentation modeling spans extraction method, certification tier, end-use application, and geographic production hub. CAGRs derive from fitted growth curves adjusted for EU Green Deal implementation pace and organic certification reciprocity negotiation timelines. Forecast inputs include climate variability indices for Bulgarian and Iranian petal yields and biotechnology substitute cost curves from fragrance house R&D disclosures.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU-Iran organic certification reciprocity resolution and synthetic biotechnology cost parity achievement. Assumptions reflect current regulatory trajectories and climate patterns without anticipating geopolitical ruptures or breakthrough fermentation technologies. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
North America Energy Drink Market
Beverages
Europe Beverage Market
Beverages
Ready to Drink Premixes Market
Beverages
Carbonated Beverages Market
Beverages
Global Bottled Water Market
Beverages
Saudi Arabia Retail Bubble Tea Kits Market
Beverages
Plant Based Protein Beverages Market
Beverages
Drinking Water Market
Beverages
Mixers Market
Beverages
Beverage Dispenser Market
Beverages
Hot Chocolate Market
Beverages
Semillon Market
Beverages
Bottled Air Market
Beverages
Europe Bottled Water Processing Market
Beverages
Italy Bottled Water Market
Beverages
United States Beverage Contract Bottling and Filling Market