
 CBD-Infused Beverages Market | 2026-2036
CBD-Infused Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
CBD-Infused Beverages Market Insights
Buyer concentration across the CBD-Infused Beverages Market is rebalancing as specialty wellness retailers consolidate shelf-space negotiations while direct-to-consumer subscriptions fragment purchasing patterns. Tilray Brands leverages its beverage infrastructure from craft alcohol partnerships to control distribution depth in regulated channels. Canopy Growth Corporation anchors North American supply through its Constellation Brands alliance, sustaining bulk ingredient access. Charlotte's Web Holdings differentiates via vertical control over hemp cultivation, occupying the premium traceability tier.
CBD-infused beverages constitute non-alcoholic drinks containing cannabidiol extract, typically formulated at 10–25 mg per serving using nanoemulsion technology to enhance bioavailability and shelf stability; these products target functional relaxation, recovery, and stress modulation for health-oriented consumers. Sodas lead current volume due to familiar consumption rituals and carbonation masking hemp-derived terpene notes, while sports drinks represent the fastest-expanding margin pool as athletes seek alternatives to traditional recovery formulations. Cans dominate packaging economics at scale, though pouches are gaining traction in fitness-channel trials where portability commands price premiums.
The FDA's ongoing evaluation of CBD under the Food, Drug, and Cosmetic Act constrains interstate commerce and labeling claims, compelling producers to navigate a patchwork of state hemp authorities and agricultural department rulings. The 2018 Farm Bill's hemp descheduling created the foundational legal space, yet the absence of GRAS affirmation leaves brands exposed to warning-letter risk and reformulation costs. Stakeholders must monitor federal rulemaking velocity against state enforcement divergence to calibrate geographic rollout sequencing and inventory commitments.
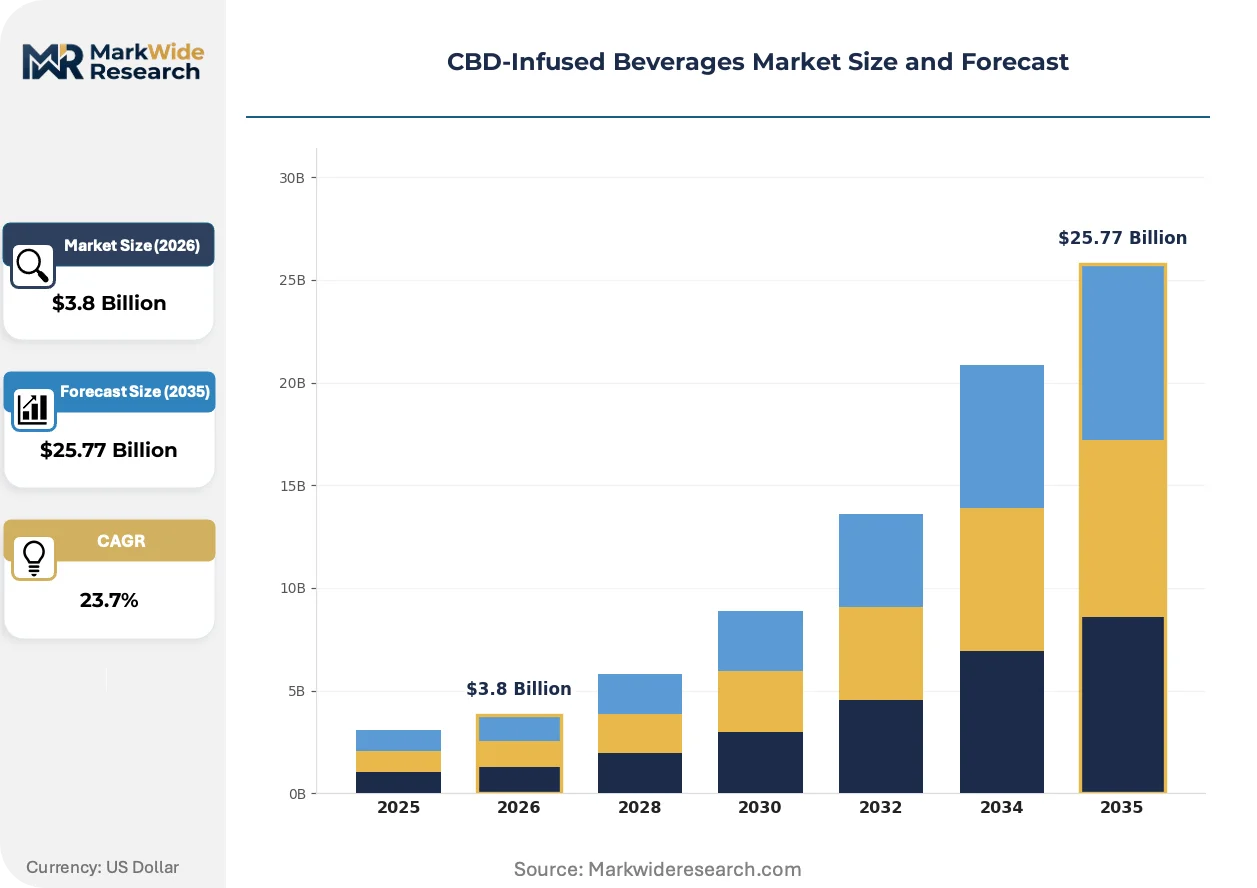
Market Dynamics
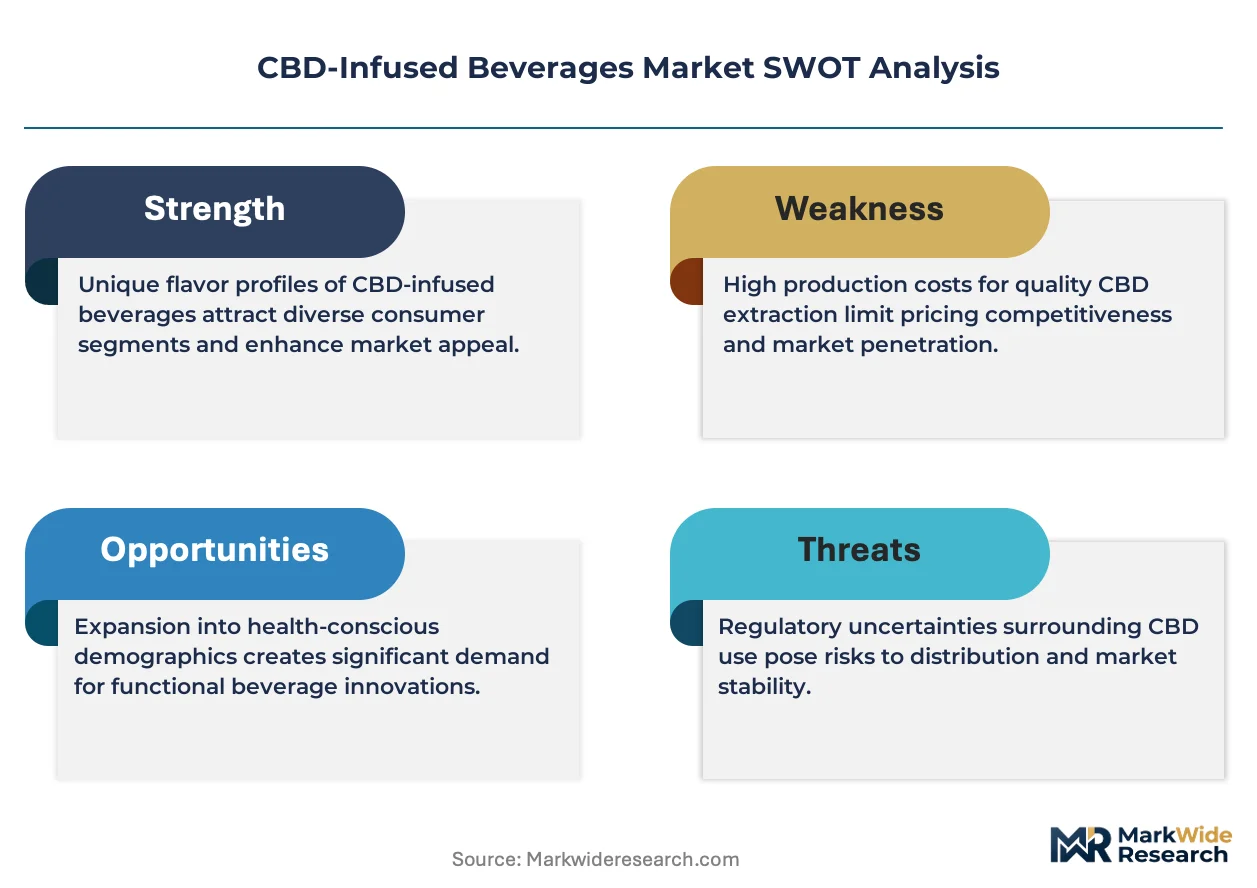
Nanoemulsion technology is compressing formulation timelines while the FDA's GRAS evaluation paralysis forces brands to maintain dual-state compliance infrastructures, creating a structural drag on capital deployment velocity.
Growth Catalysts
- State hemp legislation:Colorado, California, and Oregon have enacted comprehensive hemp beverage frameworks that exceed federal clarity, enabling compliant interstate distribution networks to emerge.
- Nanoemulsion processing:This oil-in-water dispersion technique achieves particle sizes below 100 nanometers, dramatically improving CBD bioavailability and shelf stability for ready-to-drink formats.
- Wellness retail channel expansion:Specialty grocers and fitness boutiques are dedicating refrigerated shelf space to functional beverages, creating dedicated merchandising real estate previously reserved for kombucha and cold-press juices.
Market Restraints
- GRAS affirmation absence:The FDA's refusal to designate CBD as Generally Recognized As Safe under the Food, Drug, and Cosmetic Act exposes producers to warning-letter enforcement and interstate commerce injunctions.
- Hemp biomass price volatility:Raw extract costs fluctuate with agricultural harvest cycles and extraction capacity bottlenecks, compressing gross margins for non-vertically integrated formulators.
- Terpenoid stability limitations:Light and oxygen degradation of hemp-derived aromatic compounds necessitates opaque packaging and nitrogen flushing, adding per-unit cost burdens.
Strategic Opportunities
- On-premise hospitality channels:Hotels, spas, and wellness retreats represent unsaturated venues where CBD beverages command premium pricing as amenity offerings rather than commodity retail.
- Sports recovery applications:Electrolyte-enhanced formulations targeting post-workout inflammation modulation are capturing trial among amateur endurance athletes seeking alternatives to NSAID recovery protocols.
- EU novel foods authorization pathway:EFSA's evolving stance on hemp-derived ingredients may unlock harmonized access across 27 member states for compliant producers willing to navigate 18-month safety dossier requirements.
Industry Challenges
- Formulation chemistry expertise scarcity:Food scientists capable of stabilizing lipophilic cannabinoids in aqueous matrices command compensation premiums that strain mid-cap R&D budgets.
- Co-manufacturing qualification timelines:Beverage packagers require 12-18 month vendor validation cycles for controlled-substance adjacent ingredients, delaying product launches.
- Label claim substantiation burden:Brands must navigate FTC enforcement against structure-function claims while avoiding FDA drug-claim triggers, requiring specialized regulatory counsel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CBD-Infused Beverages Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $25.77 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodas, Tea, Coffee, Sports Drinks Flavor Profile: Citrus, Berry, Herbal, Tropical Packaging Type: Cans, Bottles, Pouches, Tetra Packs Target Audience: Health Enthusiasts, Millennials, Athletes, Casual Drinkers |
| Companies Covered | Canopy Growth Corporation, Tilray Brands, Inc., Aurora Cannabis Inc., Charlotte's Web Holdings, Inc., Curaleaf, Cronos Group, Alkaline Water Company, Trulieve, Green Thumb Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CBD-Infused Beverages Market Trends and Innovations
Formulation science and distribution infrastructure are converging to reshape competitive positioning, with bioavailability engineering and channel fragmentation operating as simultaneous accelerants and complexity multipliers.
Nanoemulsion encapsulation systems are rewriting the technical foundation of CBD beverage manufacturing. These particle-size reduction platforms enable clear, shelf-stable formulations that dissolve uniformly in carbonated matrices. Beverage formulators at mid-scale production facilities are adopting ultrasonic homogenization equipment at accelerating rates. The technology is compressing the competitive moat previously held by pharmaceutical-grade extraction houses, enabling craft-scale entrants to achieve comparable bioavailability metrics.
REACH registration requirements for novel food contact materials are reshaping packaging supply strategies for European market aspirants. ECHA's substance evaluation protocols now encompass hemp-derived residuals in laminated can linings, forcing reformulation of interior coatings. German and Dutch importers are responding by qualifying aluminum bottle alternatives with epoxy-phenolic barriers that predate novel substance classifications.
Subscription-direct fulfillment is displacing traditional distributor-reliant restocking for repeat-purchase consumers. Wellness-oriented buyers in urban coastal markets are consolidating monthly beverage procurement into auto-ship portals that bypass retail markups. This pattern is most pronounced in California and New York metro corridors, where same-day delivery infrastructure supports chilled product integrity without intermediary warehousing.
CBD-Infused Beverages Market Segmentation
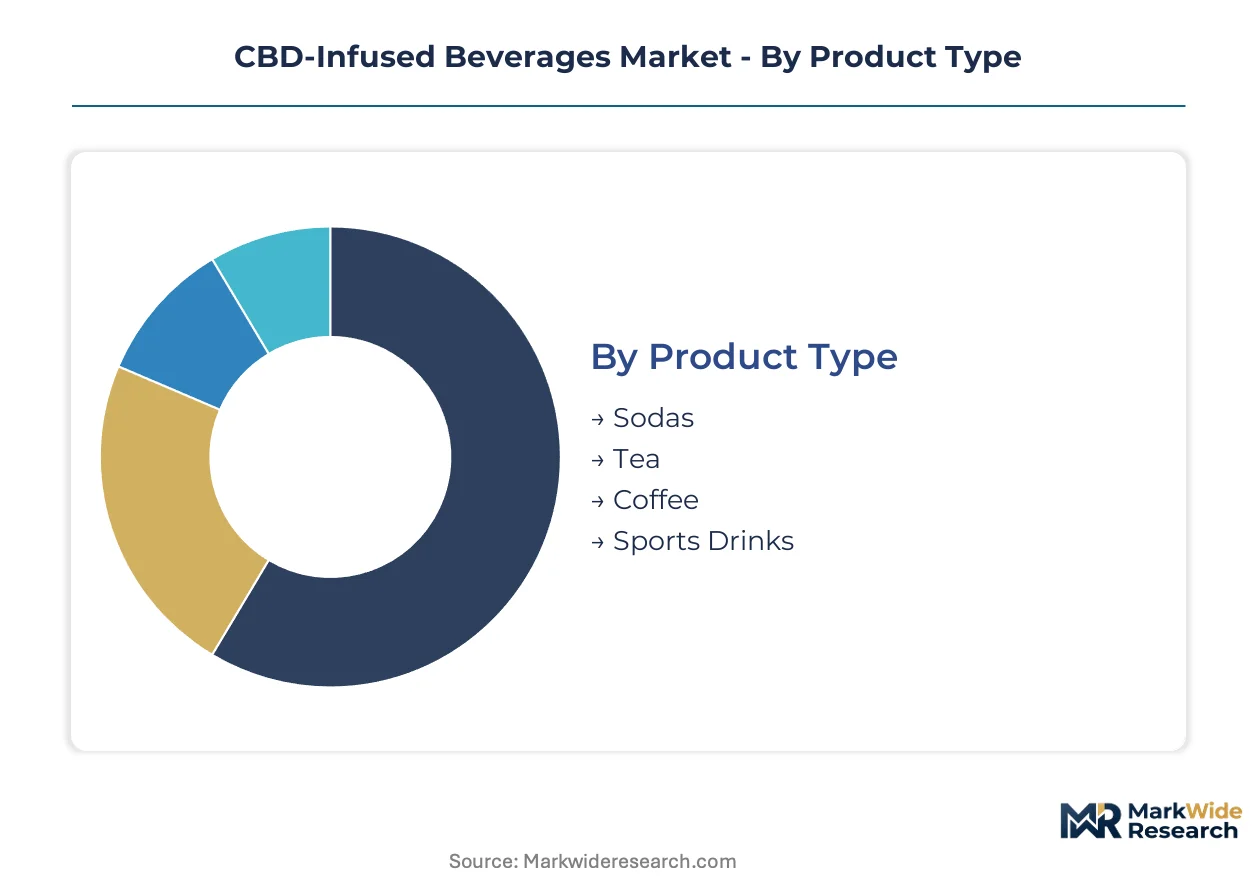
Segmentation in the CBD-Infused Beverages Market reveals how formulation chemistry, consumption ritual, and channel economics fragment addressable demand. Distinct product architectures command divergent margin profiles and regulatory exposure, forcing brands to calibrate R&D allocation against channel-specific compliance burdens.
Product Type:
Volume concentration clusters in familiar consumption formats where hemp terpene masking is technically solved, while premium pricing accrues to functional recovery applications with bioavailability claims.
- Sodas:Carbonated matrices at 10-25 mg CBD per serving leverage familiar refreshment rituals to drive trial among casual consumers. Colorado and California retailers dedicate prime refrigerated placement to these formats, though state-level THC cross-contamination testing adds per-batch compliance costs.
- Sports Drinks:Electrolyte-enhanced formulations with nanoemulsion CBD target post-workout inflammation modulation among amateur endurance athletes. Demand concentrates in fitness boutiques and specialty grocers where portability commands price premiums over traditional retail.
- Tea:Ready-to-drink botanical blends position CBD within established wellness consumption patterns, appealing to health enthusiasts seeking alternatives to caffeinated energy drinks.
- Coffee:Cold-brew and nitro formats combine CBD with caffeine for functional alertness-with-calm positioning, capturing morning ritual substitution in urban coastal markets.
Mature deployment sits with sodas. Newer deployment is concentrated in sports drinks.
Flavor Profile:
Formulation choices here determine terpene compatibility and shelf stability, with natural flavor systems requiring distinct emulsifier packages versus artificial masking agents.
- Citrus:Limonene and terpinene profiles in lemon-lime and grapefruit variants naturally complement hemp-derived terpenes, reducing the need for synthetic masking and supporting clean-label positioning in specialty channels.
- Berry:Anthocyanin-rich formulations in acai and mixed berry profiles target antioxidant-conscious consumers, though natural color stability requires nitrogen-flushed packaging that adds per-unit cost.
- Herbal:Lavender, chamomile, and adaptogenic botanical blends occupy the premium relaxation tier, appealing to spa and hospitality channel procurement.
- Tropical:Mango and passionfruit profiles leverage established functional beverage acceptance in fitness and convenience retail, with flavor intensity sufficient to mask residual hemp notes without artificial additives.
Herbal formats anchor premium positioning. Tropical profiles are gaining share fastest in mainstream retail expansion.
Packaging Type:
Material selection directly shapes distribution radius, chilled integrity requirements, and recycling compliance costs across state and municipal jurisdictions.
- Cans:Aluminum formats with epoxy-phenolic interior barriers dominate scale economics, enabling nitrogen flushing and light protection critical for terpenoid stability. German and Dutch importers are qualifying these for EU novel foods pathways.
- Pouches:Flexible laminated formats command fitness-channel price premiums where single-serve portability drives trial, though multi-layer material complexity complicates recycling compliance in jurisdictions with extended producer responsibility laws.
- Bottles:PET and glass variants support premium visual differentiation in hospitality and direct-to-consumer channels, with opaque and amber options addressing light degradation concerns.
- Tetra Packs:Aseptic carton formats enable ambient distribution economics for mass retail penetration, though laminated barrier qualification timelines extend vendor validation cycles.
Cans anchor volume scale. Pouch deployment is expanding most quickly in subscription-direct fulfillment models.
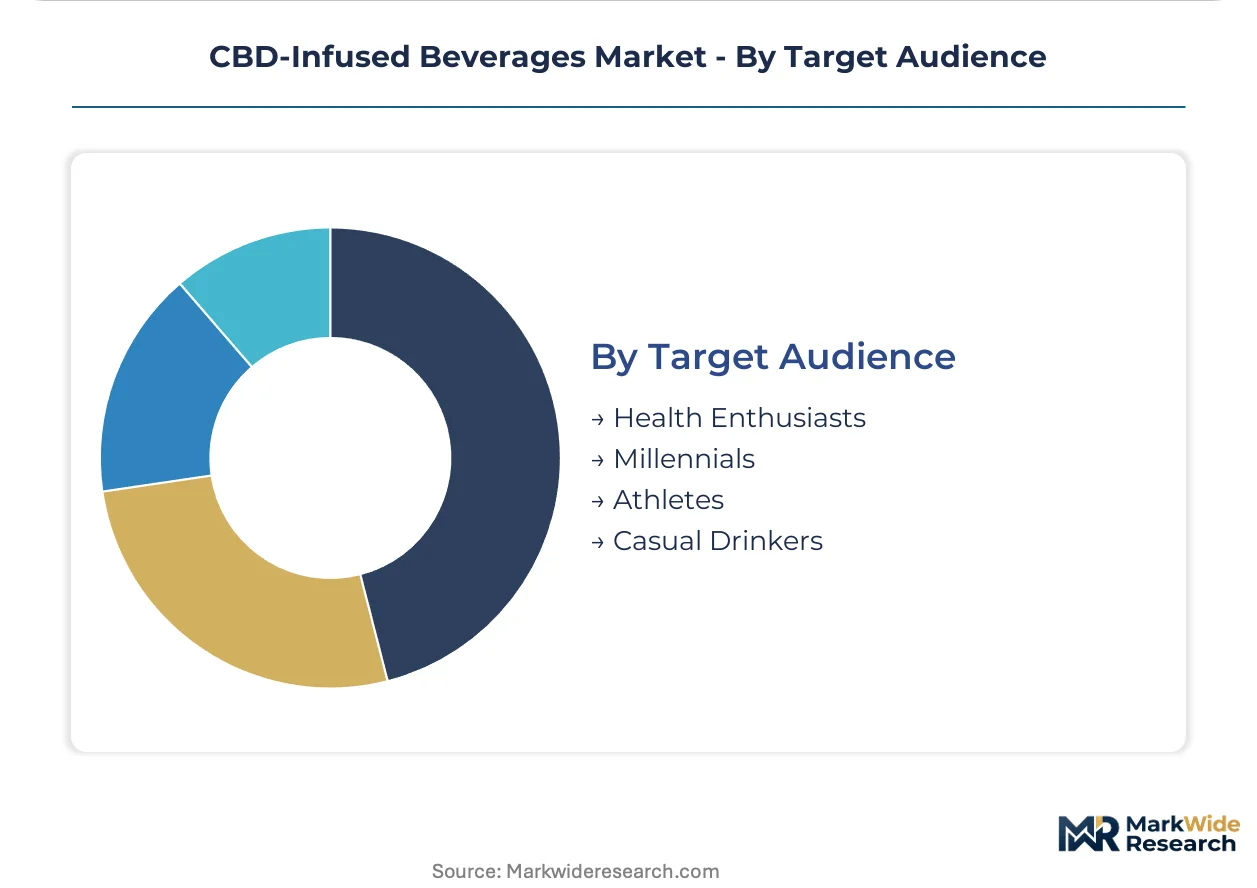
Target Audience:
Demographic concentration determines channel strategy, with wellness-oriented millennials driving trial rates while athlete segments sustain premium pricing through performance-linked claims.
- Millennials:Urban coastal consumers aged 25-40 consolidate monthly procurement through auto-ship portals, bypassing retail markups in California and New York metro corridors where same-day delivery infrastructure supports chilled integrity.
- Athletes:Amateur endurance and CrossFit practitioners seek NSAID alternatives for recovery, driving electrolyte-enhanced formulation demand in specialty fitness retail with price insensitivity to bioavailability premiums.
- Health Enthusiasts:Kombucha and cold-press juice adjacent consumers respond to traceability claims, rewarding vertical integration into hemp cultivation with shelf space access.
- Casual Drinkers:Occasional refreshment seekers respond to familiar brand extensions and trial-size availability in conventional grocery, though purchase frequency remains below wellness-motivated segments.
Health enthusiasts anchor established channel presence. Athlete targeting is climbing the fastest as sports recovery claims proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for CBD-infused beverages concentrates in the United States, where state-level hemp legislation has outpaced federal clarity and wellness-oriented millennials drive trial rates through specialty retail channels.
United States
Colorado, California, and Oregon have enacted comprehensive hemp beverage frameworks that exceed federal standards, enabling compliant interstate distribution networks to emerge. The FDA's ongoing GRAS evaluation under the Food, Drug, and Cosmetic Act constrains labeling claims and interstate commerce, exposing producers to warning-letter enforcement. Denver and Los Angeles anchor formulation R&D clusters where nanoemulsion technology providers co-locate with craft-scale beverage innovators.
Canada
Health Canada's Cannabis Act framework provides federal clarity absent in neighboring jurisdictions, enabling licensed producers to distribute CBD beverages through provincial liquor boards and private retailers. The PMRA regulates hemp-derived inputs for non-prescription products, creating a distinct compliance pathway from pharmaceutical cannabinoid oversight. Ontario and British Columbia concentrate manufacturing capacity where Tilray Brands leverages legacy beverage infrastructure from craft alcohol partnerships.
Germany
EFSA's evolving stance on hemp-derived novel foods drives producer investment in 18-month safety dossier preparation for EU harmonized access. The BfR evaluates CBD food contact materials under REACH protocols, forcing reformulation of laminated can linings to exclude hemp-derived residuals. Cologne and Hamburg host import qualification facilities where aluminum bottle alternatives with epoxy-phenolic barriers undergo ECHA substance evaluation.
United Kingdom
The FSA's novel foods authorization requirement for CBD extracts has compressed market entry timelines, with validated applications numbering in the hundreds awaiting safety assessment completion. UK Trading Standards enforce THC threshold compliance at 0.01% for finished beverages, stricter than EU baseline standards. London anchors subscription-direct fulfillment innovation where same-day delivery infrastructure supports chilled product integrity for wellness-oriented urban consumers.
Australia
The TGA's down-scheduling of low-dose CBD to pharmacist-only medicine status has opened distinct regulatory space separate from food-grade beverage pathways, creating dual-track market development. State food authorities in New South Wales and Victoria administer hemp food licensing with varying THC testing protocols. Sydney and Melbourne concentrate fitness-channel trial activity where electrolyte-enhanced formulations target amateur endurance athletes seeking NSAID alternatives.
CBD-Infused Beverages Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue hospitality and subscription-direct channels where regulatory arbitrage and consumer intimacy command price premiums. The vendor base stratifies across three maturity tiers: licensed cannabis incumbents with beverage infrastructure, wellness-focused hemp specialists with vertical cultivation control, and functional beverage crossovers from adjacent categories. Consolidation pressure operates through M&A activity targeting nanoemulsion technology assets and state-level distribution licenses.
Within the licensed cannabis incumbent tier, Canopy Growth Corporation and Tilray Brands exemplify scale-driven positioning through beverage infrastructure leverage and Constellation Brands alliance structures. Charlotte's Web Holdings occupies the premium traceability tier via backward integration into hemp cultivation. These three entities anchor competitive dynamics across North American regulated channels, with each representing distinct strategic archetypes: beverage infrastructure deployment, alcohol partnership monetization, and vertical supply control.
| Leading Market Players |
|---|
| Canopy Growth Corporation |
| Tilray Brands, Inc. |
| Aurora Cannabis Inc. |
| Charlotte's Web Holdings, Inc. |
| Curaleaf |
| Cronos Group |
| Alkaline Water Company |
| Trulieve |
| Green Thumb Industries |
| Others |
Pricing and Supply Chain Analysis
Backward integration into hemp cultivation anchors supply security and pricing power for premium-tier producers navigating volatile biomass costs. Captive supply of CBD isolate insulates vertically integrated formulators from raw extract price swings while commanding shelf-space premiums through traceability claims.
Pricing Analysis
Volume concentration in sodas compresses per-unit margins to commodity levels while sports drinks capture premium pricing through bioavailability claims and fitness-channel positioning. Three-tier pricing structure across premium, standard, and economy levels separates nanoemulsion-enhanced formulations from basic oil-in-water suspensions and private-label alternatives. Pricing pressure stems from hemp biomass oversupply cycles and extraction capacity expansions that depress input costs for non-integrated competitors. Casual drinkers exhibit highest price sensitivity, while amateur athletes accept bioavailability premiums for post-workout recovery positioning.
Supply Chain Analysis
Single-source vulnerability sits with Colorado and Oregon hemp biomass processors that dominate North American CBD isolate production. Raw material flows draw from Kentucky, Oregon, and Colorado hemp cultivation regions, with extraction capacity concentrated in Denver and Portland metro clusters. Supply chain risk centers on FDA enforcement actions that could trigger interstate commerce injunctions and inventory seizures. Distribution runs through state-licensed beverage distributors in compliant jurisdictions, supplemented by direct-to-consumer subscription fulfillment in California and New York corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as GRAS affirmation delays force smaller formulators to absorb dual-state compliance costs that erode already-thin margins. Weaker players lacking nanoemulsion capabilities or beverage infrastructure face forced exit or acquisition.
For Market Incumbents: Lock in nanoemulsion technology partnerships to defend formulation moats against craft-scale entrants adopting ultrasonic homogenization equipment. Secure multi-year hemp biomass offtake agreements before agricultural harvest cycles compress input costs for competitors. Prioritize state-level distribution licenses in Colorado, California, and Oregon where compliant interstate networks are crystallizing.
For New Entrants and Emerging Players: Enter via hospitality and wellness retreat channels where CBD beverages command amenity pricing without retail margin compression. Target on-premise venues in spa and hotel segments where procurement decisions favor premium traceability over volume scale. Deploy subscription-direct fulfillment models in urban coastal markets where same-day delivery infrastructure supports chilled product integrity.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by licensed cannabis incumbents seeking beverage infrastructure and state distribution licenses. Long-term viability favors targets with captive hemp supply and validated nanoemulsion formulations over brand-dependent marketing plays. Watch FDA GRAS rulemaking velocity as the critical inflection signal for interstate commerce expansion and valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Nanoemulsion Technology Acquisition | Secures bioavailability advantages as ultrasonic homogenization democratizes particle-size reduction capabilities. |
| State Distribution License Expansion | Unlocks compliant interstate networks in Colorado, California, and Oregon ahead of federal clarity. |
| Captive Hemp Cultivation Investment | Insulates margin structure from biomass price volatility and supports premium traceability claims. |
| Hospitality Channel Partnership | Captures amenity pricing in spa and hotel segments with lower regulatory exposure than retail. |
| Subscription-Direct Fulfillment Buildout | Bypasses distributor markups in California and New York metro corridors with same-day delivery infrastructure. |
Research Methodology
SEC filings, state hemp authority regulatory databases, and trade customs records formed the secondary backbone for supply-side and compliance infrastructure mapping. Primary interviews with beverage formulators, regulatory counsel specializing in FDA enforcement, specialty retailer category buyers, and hemp cultivation operations managers validated secondary findings. Bottom-up modeling of nanoemulsion equipment deployment and top-down triangulation against state-level hemp beverage framework adoption cross-checked volume assumptions.
Historical trendline analysis of hemp biomass pricing and extraction capacity expansion informed input cost trajectories across the projection horizon. Segmentation modeling incorporated product type, packaging format, distribution channel, and target audience dimensions with bioavailability tier as a CBD-specific stratifier. CAGRs derived from fitted growth curves adjusted for regulatory scenario probabilities and state-level framework maturation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA enforcement acceleration or GRAS affirmation delays. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Dairy Based Beverages Market
Beverages
Spring Water Market
Beverages
BBQ Charcoal Market
Beverages
Packaged Coconut Water Market
Beverages
Relaxation Beverages Market
Beverages
Still Drinks Market
Beverages
South America Energy Drink Market
Beverages
Sparkling Water Market
Beverages
Tonic Water Market
Beverages
Water Flavor Market
Beverages
Apple Cider Vinegar Market
Beverages
Herb Infused Water Market
Beverages
Soft Serves Market
Beverages
Saudi Arabia Drinking Water Market
Beverages
Caffeine Mint Market
Beverages
Maple Water Market